
 Veterinary Stereotactic Radiosurgery System Market | 2026-2036
Veterinary Stereotactic Radiosurgery System Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Stereotactic Radiosurgery System Market Analysis
Carbon fiber patient positioning arrays are restructuring cost structures in stereotactic veterinary radiotherapy, replacing heavier metal gantry components that constrained clinic throughput. Accuray Incorporated leverages its human-radiotherapy supply chain to sustain cost advantages in veterinary-adapted platforms. Elekta AB anchors European installations through established service networks. Varian Medical Systems, Inc. competes on software integration, while PetCure Oncology dominates the United States through its dedicated veterinary radiation center model.
Veterinary stereotactic radiosurgery systems deliver high-dose, precisely targeted ionizing radiation to tumors in companion animals using stereotactic coordinates, typically achieving sub-millimeter accuracy through image-guided beam delivery with dose rates exceeding 600 monitor units per minute. The primary purpose is to ablate neoplastic tissue while sparing adjacent healthy structures in non-surgical candidates. Linear Accelerators occupy the largest installed base due to versatility across tumor sites, while CyberKnife Systems capture premium positioning through robotic tracking that accommodates respiratory motion in anesthetized patients. Image-Guided Radiation Therapy leads technology adoption, yet Motion Management represents the fastest-expanding capability as clinics treat thoracic and abdominal lesions.
FDA Center for Veterinary Medicine oversight intersects with FCC equipment authorization for integrated imaging components, creating dual-compliance requirements for manufacturers entering the United States market. The EU Medical Device Regulation, through delegated acts on active implantable devices, shapes conformity pathways for systems with implantable fiducial compatibility. Stakeholders must monitor whether veterinary-specific reimbursement codes emerge from private pet insurance negotiations, as this will determine capital recovery timelines for clinic investors weighing system procurement against outsourced referral models.
Market Dynamics
Carbon fiber positioning arrays are compressing equipment footprints and enabling same-day treatment protocols that previously required multi-day scheduling blocks. This material substitution is redistributing capital efficiency across referral networks and reshaping clinic throughput economics.
Growth Catalysts
- FDA Center for Veterinary Medicine streamlining:Expedited 510(k) pathways for human-equipment crossovers accelerate platform commercialization timelines for veterinary-adapted linear accelerators.
- Pet insurance reimbursement expansion:Rising policy penetration in the United States converts out-of-pocket radiotherapy costs into reimbursable procedures, expanding addressable patient populations.
- Image-guided beam delivery:Sub-millimeter accuracy protocols enable thoracic and abdominal lesion treatment in anesthetized companion animals previously deemed non-candidates.
Market Restraints
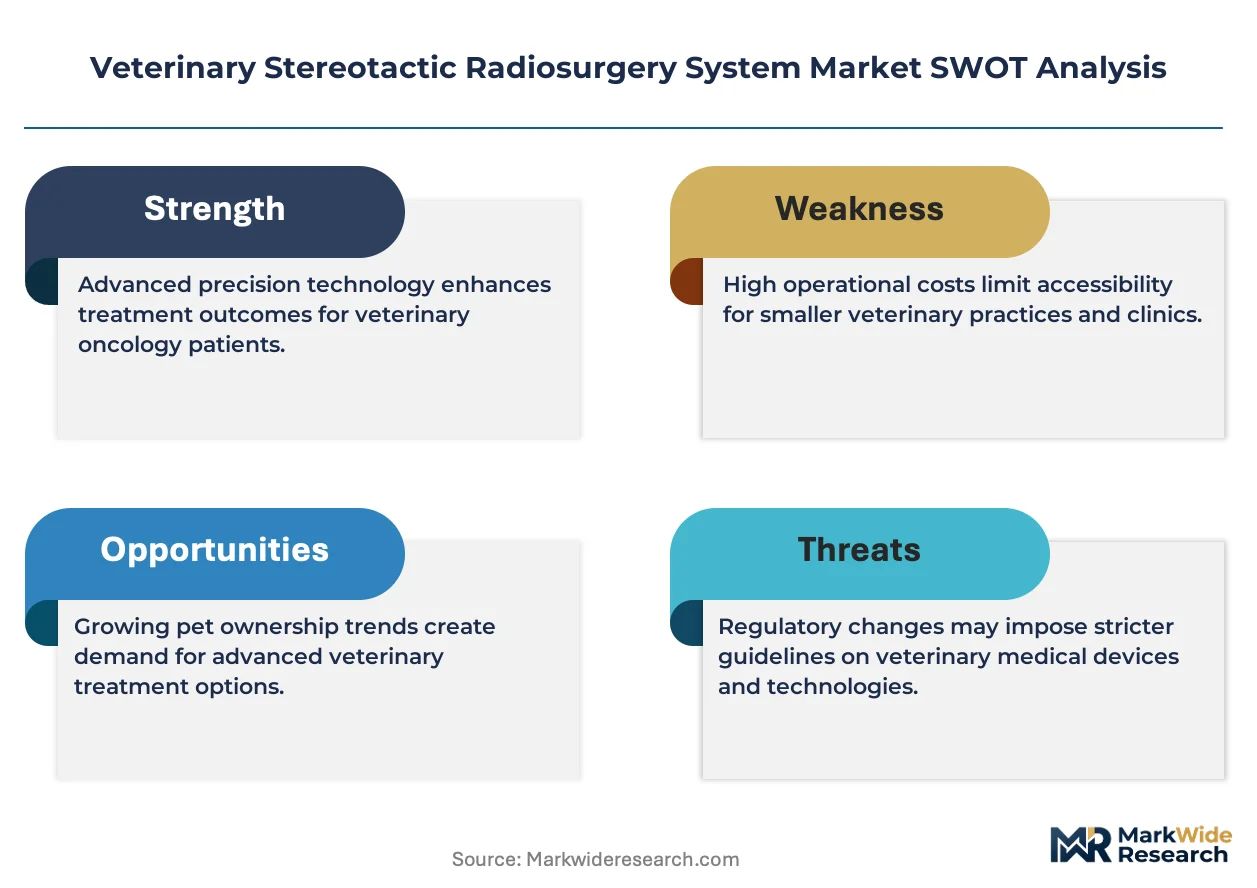
- Capital intensity of linear accelerator procurement:Multi-million dollar system costs constrain independent veterinary practice participation, concentrating adoption within specialty oncology networks.
- Implantable fiducial supply concentration:Compatibility requirements with active implantable device regulations create dependency on limited European component suppliers.
- Anesthesia protocol complexity:Extended immobilization requirements for respiratory motion management limit daily case volumes and compress per-procedure margins.
Strategic Opportunities
- Underpenetrated Japanese companion animal market:Aging pet demographics and METI-supported veterinary infrastructure investments create whitespace for precision radiotherapy platform deployment.
- Motion management capability expansion:Robotic tracking systems originally developed for human CyberKnife applications transfer to veterinary thoracic oncology, enabling real-time respiratory compensation.
- Telemedicine-integrated treatment planning:Remote dosimetry review and teleradiology partnerships allow regional clinics to access specialist expertise without on-site physicist staffing.
Industry Challenges
- Veterinary radiation oncologist scarcity:Board-certified specialist training programs produce insufficient graduates to staff expanding specialty center networks.
- Dual-compliance complexity:FCC equipment authorization for integrated imaging components intersects with FDA veterinary device oversight, extending pre-market preparation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Stereotactic Radiosurgery System Market |
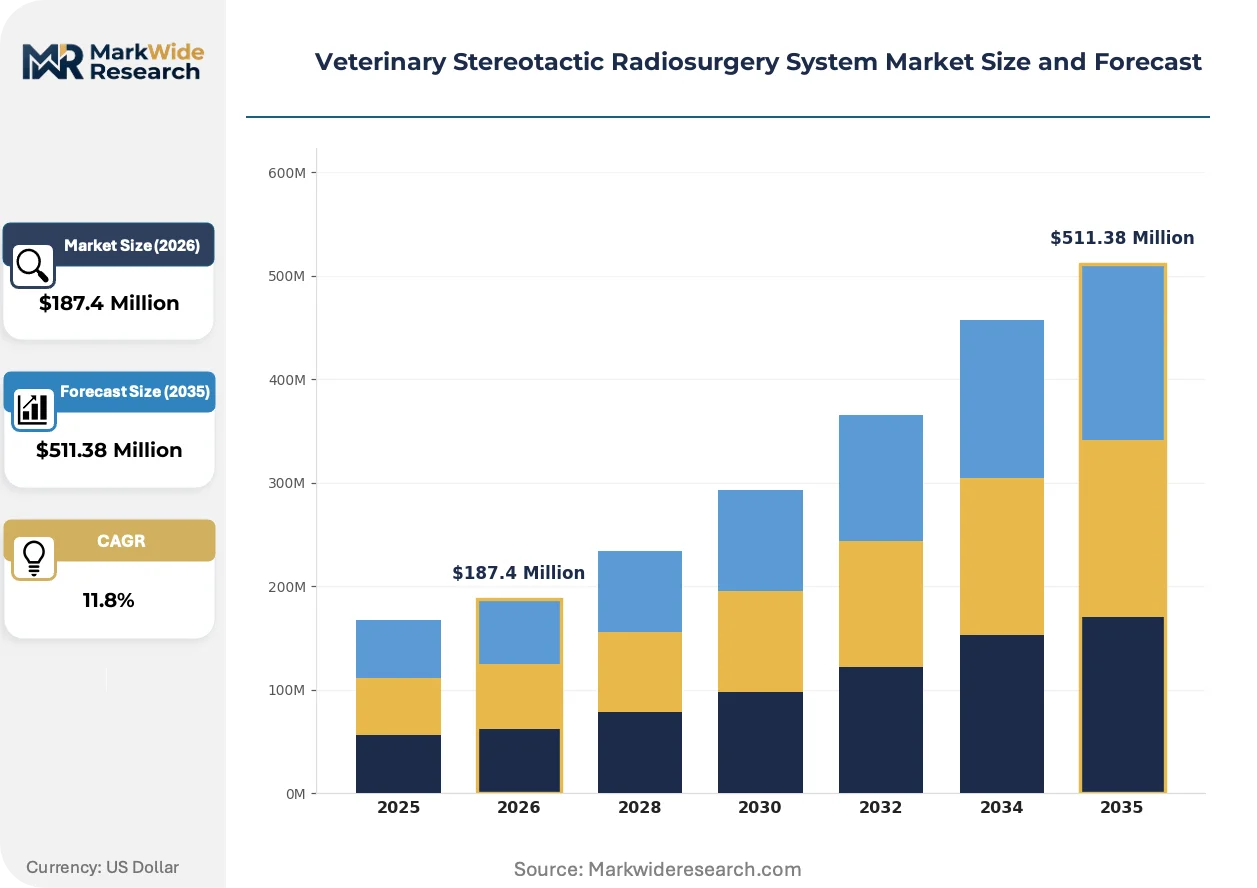
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $511.38 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Accelerators, CyberKnife Systems, Gamma Knife Systems, Cone Beam CT Systems End User: Animal Hospitals, Veterinary Clinics, Research Institutions, Academic Institutions Technology: 3D Planning, Image-Guided Radiation Therapy, Motion Management, Remote Monitoring Application: Oncology, Neurology, Orthopedics, Cardiology |
| Companies Covered | PetCure Oncology, Accuray Incorporated, Elekta AB, Varian Medical Systems, Inc., Xstrahl Ltd., Brainlab AG, Mevion Medical Systems Inc., ZAP Surgical Systems Inc., ViewRay Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Stereotactic Radiosurgery System Market Emerging Trajectories
Robotic beam delivery architectures are compressing the gap between human and veterinary radiotherapy capabilities, enabling motion-compensated treatments that were previously restricted to research institutions.
Carbon fiber patient positioning arrays are decentralizing stereotactic radiotherapy access by reducing shielding requirements and enabling retrofit installation in existing veterinary facilities with limited structural load capacity. Community specialty practices in the United States are adopting these lightweight systems at accelerated pace. This material transition is compressing the capital barrier between academic referral centers and independent oncology practices.
EU Medical Device Regulation delegated acts on active implantable devices are reshaping conformity assessment pathways for systems with fiducial marker compatibility. Manufacturers must demonstrate biocompatibility and electromagnetic interference resilience under notified body supervision. European installations face extended certification timelines compared to United States 510(k) routes, creating competitive divergence in regional platform availability.
Pet owner payment behavior is fragmenting across insurance reimbursement, third-party veterinary financing platforms, and direct out-of-pocket expenditure. Specialty oncology centers in the United States are unbundling treatment planning from delivery to align with insurance pre-authorization workflows. This financial intermediation is most visible in metropolitan markets with high policy penetration and established referral networks.
Veterinary Stereotactic Radiosurgery System Market Segmentation
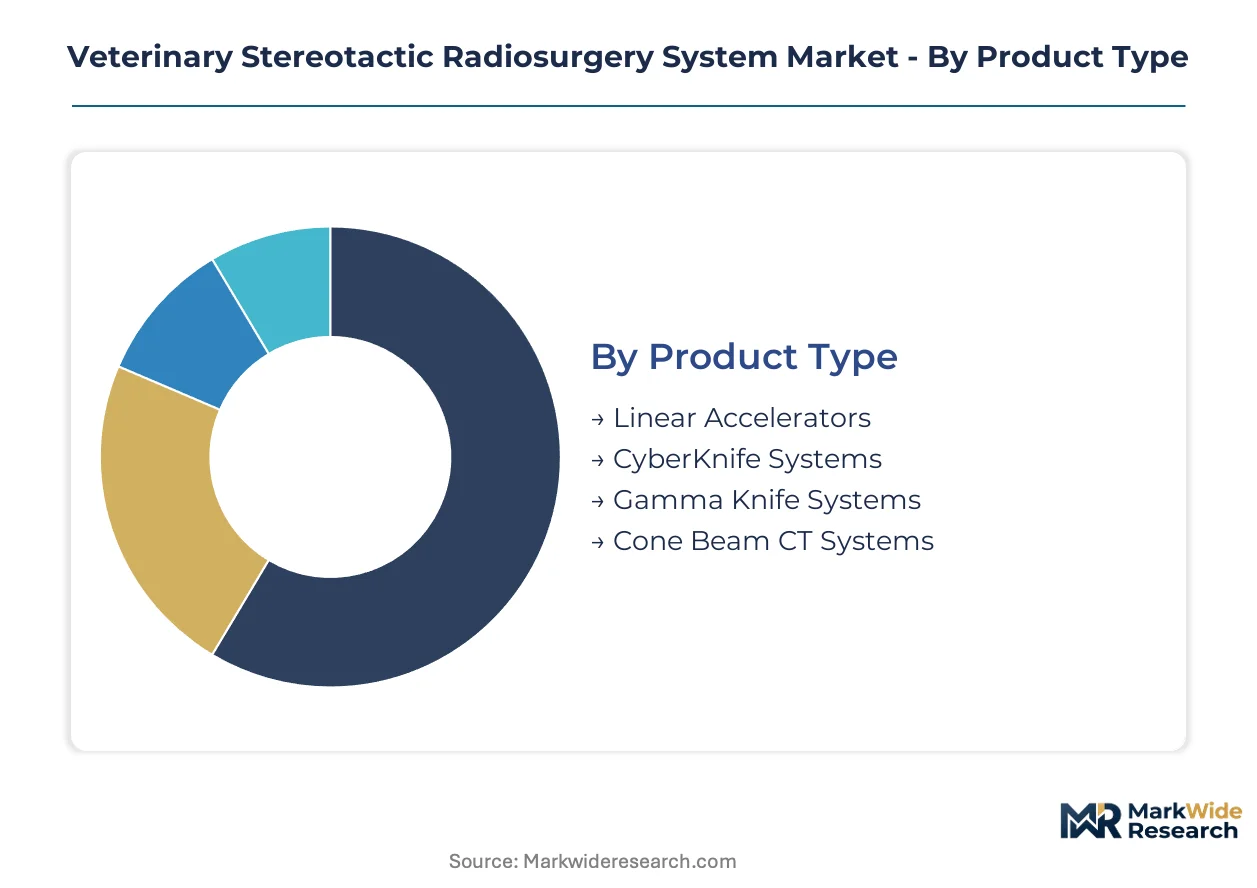
Capital allocation patterns across product configurations determine which veterinary practices can enter stereotactic radiotherapy. Segmentation reveals where procurement concentrates and which technology investments yield viable patient throughput.
Product Type:
Linear accelerators demand the heaviest upfront capital commitment, while compact robotic systems reconfigure facility requirements and shielding economics.
- Linear Accelerators:Versatile beam delivery platforms accommodate multiple tumor sites through adjustable gantry angles and multi-leaf collimator configurations. Specialty oncology networks in the United States concentrate procurement here, driven by patient volume thresholds that justify multi-million dollar installations and dedicated vault construction.
- CyberKnife Systems:Robotic tracking architectures compensate for respiratory motion in anesthetized companion animals without rigid head frames. Demand clusters in metropolitan referral centers treating thoracic and abdominal lesions where real-time motion management commands premium reimbursement.
- Gamma Knife Systems:Cobalt-60 based platforms deliver focused radiation to intracranial targets with steep dose gradients. Limited veterinary adoption outside academic neurosurgery collaborations.
- Cone Beam CT Systems:Integrated imaging modules enable same-day simulation and treatment planning. Community practices deploy these for workflow compression without physicist-heavy infrastructure.
Most installed capacity flows through Linear Accelerators. Expansion is steepest in CyberKnife Systems.
End User:
Facility scale dictates technology tier, with academic centers absorbing experimental platforms and community hospitals prioritizing proven throughput economics.
- Animal Hospitals:Multi-specialty institutions with dedicated oncology departments house the majority of stereotactic radiotherapy suites. These facilities command sufficient case volume to amortize capital costs across diversified service lines.
- Veterinary Clinics:General practice settings rarely host linear accelerators directly; instead they refer to networked specialty centers or participate in hub-and-spoke telemedicine arrangements for treatment planning.
- Research Institutions:Experimental protocols and comparative oncology trials drive adoption of emerging motion compensation algorithms and novel fractionation schedules.
- Academic Institutions:Veterinary teaching hospitals integrate stereotactic platforms into residency training programs, producing the specialist workforce that staffs commercial installations.
Animal Hospitals absorb the dominant share of current installations. Research Institutions are climbing the fastest as comparative oncology funding expands.
Technology:
Software sophistication separates premium-tier platforms from baseline configurations, with planning algorithms and real-time tracking commanding disproportionate margin capture.
- 3D Planning:Dose calculation engines construct volumetric tumor models from CT and MRI fusion datasets. Standard equipment across all installed base tiers.
- Image-Guided Radiation Therapy:KV imaging prior to each fraction enables millimeter-level patient repositioning. Now baseline expectation in specialty center procurement specifications.
- Motion Management:Respiratory gating and robotic tracking expand treatable anatomy to thoracic and abdominal sites previously excluded from curative protocols. Fastest capability expansion as clinics compete for complex oncology referrals.
- Remote Monitoring:Cloud-connected platforms enable vendor technical support and treatment data aggregation without on-site physicist presence. Emerging adoption in underserved geographic markets.
Image-Guided Radiation Therapy constitutes the standard capability layer. Motion Management is gaining share fastest as thoracic oncology referrals expand.
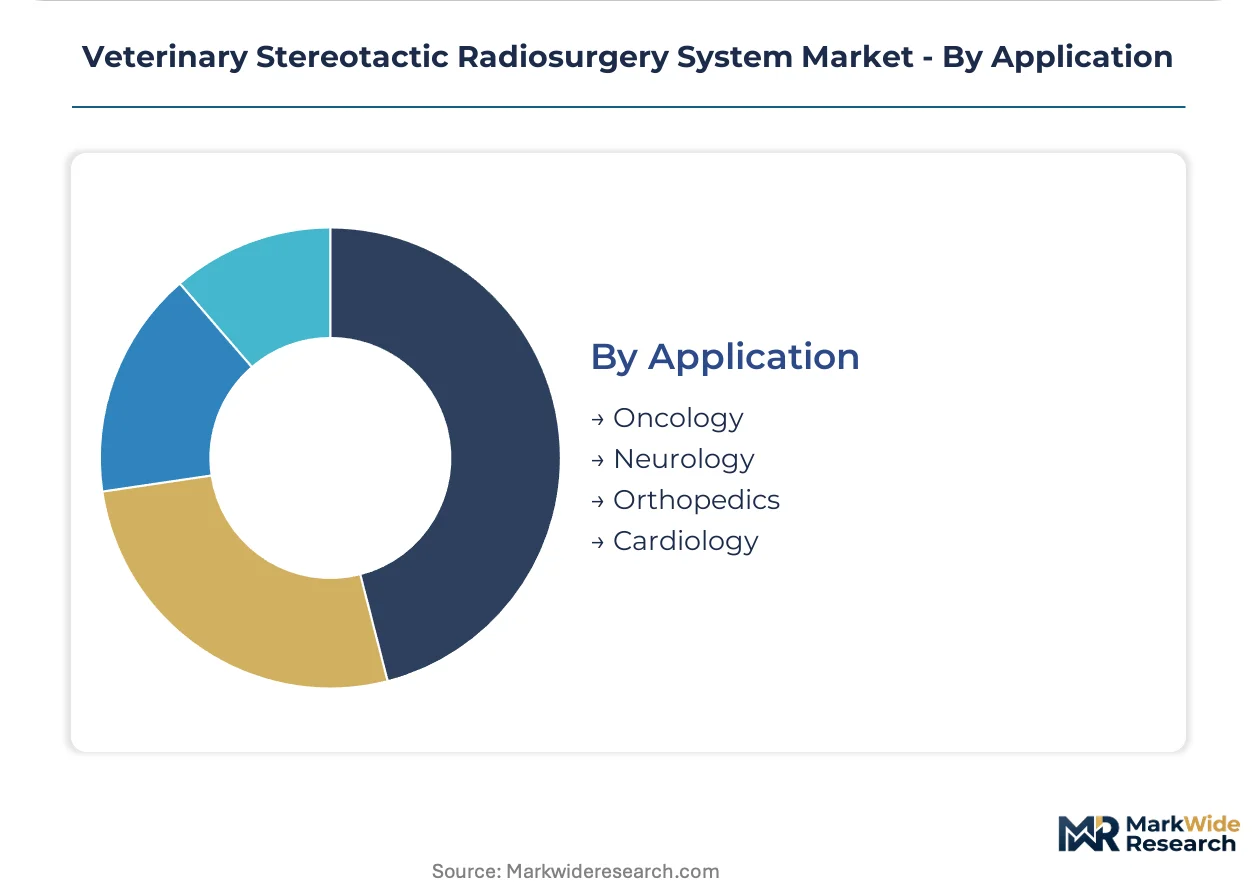
Application:
Oncology dominance reflects companion animal cancer incidence patterns, while adjacent specialties remain experimental or reimbursement-constrained.
- Oncology:Curative and palliative protocols for solid tumors in dogs and cats represent the commercial core. Mast cell tumors, osteosarcoma, and nasal carcinoma drive procedure volume in United States specialty networks.
- Neurology:Intracranial meningioma and pituitary macroadenoma protocols demonstrate clinical efficacy but remain limited by anesthesia risk in compromised patients and specialist neurosurgical collaboration requirements.
- Orthopedics:Adjuvant radiotherapy for incompletely resected soft tissue sarcomas and palliative bone pain management. Secondary application with fragmented reimbursement pathways.
- Cardiology:Experimental arrhythmia ablation and cardiac tumor protocols in research settings. No commercial scale.
Oncology commands the overwhelming procedure volume. Neurology shows the steepest expansion trajectory as imaging resolution and anesthesia protocols improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty veterinary oncology centers in the United States concentrate the highest installed capacity of stereotactic radiosurgery platforms, driven by pet insurance penetration and metropolitan referral network density.
United States
Pet insurance reimbursement expansion converts out-of-pocket radiotherapy costs into reimbursable procedures, broadening addressable patient populations for specialty centers. FDA Center for Veterinary Medicine 510(k) pathways streamline human-equipment crossovers for veterinary-adapted linear accelerators. The Dallas-Fort Worth metroplex anchors the highest concentration of PetCure Oncology installations, with same-day treatment protocols compressing scheduling blocks.
Germany
Established service networks from Elekta AB sustain European platform adoption through localized technical support and maintenance infrastructure. EU Medical Device Regulation delegated acts on active implantable devices reshape conformity assessment for fiducial-compatible systems. The Munich-Stuttgart corridor hosts the densest cluster of university veterinary teaching hospitals integrating stereotactic platforms into residency training programs.
Japan
Aging companion animal demographics and METI-supported veterinary infrastructure investments create whitespace for precision radiotherapy deployment. PMDA consultation pathways for veterinary medical devices accelerate pre-market preparation for manufacturers with human-equipment portfolios. The Tokyo-Osaka corridor concentrates emerging specialty oncology center formation, with robotic tracking systems gaining traction for thoracic lesion protocols.
United Kingdom
Referral network consolidation around academic veterinary hospitals concentrates stereotactic capability in the southeast and midlands regions. MHRA alignment with EU MDR transitional provisions maintains continuity for CE-marked platform imports. The Cambridge-Oxford-London triangle leads comparative oncology trial enrollment, linking research institutions to commercial installation expansion.
Australia
Geographic dispersion of veterinary specialists drives telemedicine-integrated treatment planning adoption for regional clinic access to dosimetry expertise. TGA inclusion of veterinary radiotherapy devices under therapeutic goods frameworks clarifies import pathways for linear accelerator systems. The Sydney-Melbourne corridor concentrates private equity investment in specialty oncology center rollups, with shielding-reduced carbon fiber arrays enabling retrofit installation.
Veterinary Stereotactic Radiosurgery System Market Vendor Landscape
Global majors compete with regional champions across technology licensing and service network coverage, creating tiered competitive dynamics. The vendor base stratifies between diversified human-radiotherapy conglomerates with veterinary-adapted portfolios and dedicated veterinary radiation center operators. Three archetypes dominate: human-equipment crossover specialists, veterinary-exclusive platform deployers, and robotic tracking technology licensors. M&A activity concentrates on specialty center network consolidation, while strategic partnerships link academic research protocols to commercial installation expansion.
Within the human-equipment crossover tier, Accuray Incorporated and Elekta AB exemplify diversified conglomerates leveraging human-radiotherapy supply chains for veterinary cost advantages. Varian Medical Systems, Inc. occupies a position emphasizing software integration capabilities. PetCure Oncology anchors the veterinary-exclusive archetype through its dedicated radiation center operating model concentrated in United States metropolitan markets. These three company groupings represent distinct strategic postures without implying specific market share claims.
| Leading Market Players |
|---|
| PetCure Oncology |
| Accuray Incorporated |
| Elekta AB |
| Varian Medical Systems, Inc. |
| Xstrahl Ltd. |
| Brainlab AG |
| Mevion Medical Systems Inc. |
| ZAP Surgical Systems Inc. |
| ViewRay Inc. |
| Others |
Supply Flow & Price Mechanics
Backward integration into carbon fiber positioning array manufacturing anchors supply security for veterinary radiotherapy OEMs while compressing procurement costs for downstream specialty oncology networks. This captive production of lightweight patient positioning components simultaneously insulates vendors from European implantable fiducial supply bottlenecks and enables premium pricing for motion-capable system configurations.
Pricing Analysis
Input-cost pass-through from cobalt-60 source replenishment and linear accelerator tube replacement cycles anchors maintenance contract pricing for installed base systems. Three-tier pricing structure across premium robotic tracking, standard image-guided, and economy fixed-beam configurations reflects software sophistication and real-time motion compensation capabilities. Cost compression in the economy tier intensifies as refurbished human-radiotherapy platforms enter veterinary adaptation pipelines. Independent veterinary practices exhibit highest price sensitivity, while academic teaching hospitals absorb premium configurations with bundled training and residency program integration.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Japan consolidate spare parts logistics for linear accelerator service networks serving veterinary installations. Manufacturing draws from specialized cobalt-60 suppliers in Canada and Russia, precision robotics components from Japan, and carbon fiber composites from Taiwan. Single-source vulnerability in implantable fiducial biocompatibility certification creates regulatory chokepoints for EU market entry. Distribution runs through manufacturer-direct service engineers for high-value systems, with third-party veterinary equipment distributors handling consumables and accessories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where pet insurance reimbursement expansion shifts demand toward motion-managed thoracic protocols requiring premium platform specifications.
For Market Incumbents: Hedge against margin erosion in linear accelerator configurations by deepening software subscription revenue streams and securing exclusive service contracts for robotic tracking architectures. Accelerate CE marking timelines for fiducial-compatible systems to preempt European competitor entry. Channel control through direct service engineer deployment protects installed base pricing power.
For New Entrants and Emerging Players: Community specialty practices in secondary United States metropolitan markets represent the most penetrable buyer archetype, underserved by current academic center concentration. Telemedicine-integrated treatment planning partnerships offer a de novo entry angle without capital-intensive physicist staffing. Target shielding-reduced carbon fiber retrofit installations to bypass vault construction barriers.
For Investors and Strategic Acquirers: Roll-up economics work for regional specialty oncology center networks because fragmented independent practice ownership creates consolidation arbitrage against rising capital equipment procurement costs. Five-to-ten year viability hinges on veterinary radiation oncologist training pipeline expansion matching center network growth. Watch private pet insurance policy penetration rates in metropolitan markets as the inflection signal for addressable patient population expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Motion Management Software Licensing | Enables thoracic lesion treatment expansion beyond cranial applications in anesthetized companion animals. |
| Telemedicine-Integrated Treatment Planning | Connects regional clinics to specialist dosimetry expertise without on-site physicist infrastructure requirements. |
| Carbon Fiber Positioning Array Manufacturing Scale-Up | Reduces shielding footprints and enables retrofit installation in existing veterinary facilities with load constraints. |
| Veterinary Radiation Oncologist Training Program Expansion | Addresses specialist scarcity constraining commercial installation utilization and referral network throughput. |
| Pet Insurance Reimbursement Strategy Development | Aligns treatment planning workflows with pre-authorization requirements in high-penetration metropolitan markets. |
Methodological Framework
Bottom-up specialty oncology center installation modeling reconciled against top-down veterinary radiotherapy equipment import tracking forms the analytical core of this study. Primary interviews with veterinary radiation oncologists, biomedical physicists, specialty hospital procurement directors, pet insurance reimbursement specialists, and FDA Center for Veterinary Medicine regulatory consultants combined with secondary validation against FDA 510(k) filings, EU MDR notified body certification databases, American College of Veterinary Radiology residency program directories, and pet insurance policy penetration surveys from North American Pet Health Insurance Association.
Historical trendline analysis of linear accelerator and CyberKnife system deployment trajectories informed projection frameworks across the analysis window. Segmentation dimensions modeled include product configuration, end-user facility type, technology capability tier, and application specialty. CAGRs derived from equipment procurement cycle analysis, replacement demand patterns, and referral network expansion timelines. Forecast inputs incorporated pet insurance reimbursement policy evolution and veterinary specialist training program graduation rates.
Inputs from regulatory filing databases and specialty center operational surveys were available through the study window; gaps in real-time installed base utilization metrics introduce uncertainty bands around capacity expansion assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Electrocautery Devices Market
Medical Devices
Eye Massage Device Market
Medical Devices
Pharmaceutical Filtration Devices Market
Medical Devices
Electrosurgery Accessories Market
Medical Devices
Peak Flow Meters Market
Medical Devices
Eye Examination Equipment Market
Medical Devices
Europe Sperm Separation Devices Market
Medical Devices
Middle Ear Implants Market
Medical Devices
Eye Sphere Implants Market
Medical Devices
Global Cerebrospinal Fluid Management Devices Market
Medical Devices
Condylar Plate Fixation System Market
Medical Devices
Intrauterine Devices (IUD) Market
Medical Devices
Urinary Collection Device Market
Medical Devices
Mexico Respiratory Devices Market
Medical Devices
Global Intraoral Cameras Market
Medical Devices
Cranial Implants Treatment Market