
 Global Body Contouring Devices Market | 2026-2036
Global Body Contouring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Body Contouring Devices Market Foresight
Software-defined treatment protocols is recalibrating how body contouring platforms generate recurring revenue beyond hardware sales. AbbVie Inc. leverages its Allergan Aesthetics arm to sustain premium positioning across cryolipolysis and injectable portfolios. InMode Ltd anchors its competitive stance through radiofrequency technology leadership and direct-to-physician channel control. Alma Lasers differentiates by dominating mid-market laser and ultrasound platforms across Asia-Pacific and Latin American markets.
Body contouring devices are electromechanical or energy-based systems that apply controlled thermal, acoustic, or electromagnetic energy to adipose tissue and dermal layers, typically operating at frequencies between 1 MHz and 40 MHz for radiofrequency modalities and wavelengths of 650–1064 nm for laser-based systems, with primary commercial purpose being non-invasive or minimally invasive reduction of subcutaneous fat and improvement of skin laxity. Radiofrequency devices command the deepest installed base due to versatility across skin tightening and fat reduction applications, while cryolipolysis machines represent the fastest-expanding category as patient preference shifts toward single-session, no-downtime procedures. Medical spas and dermatology clinics concentrate margin pools through bundled treatment packages that lock in repeat patient visits across multiple body areas.
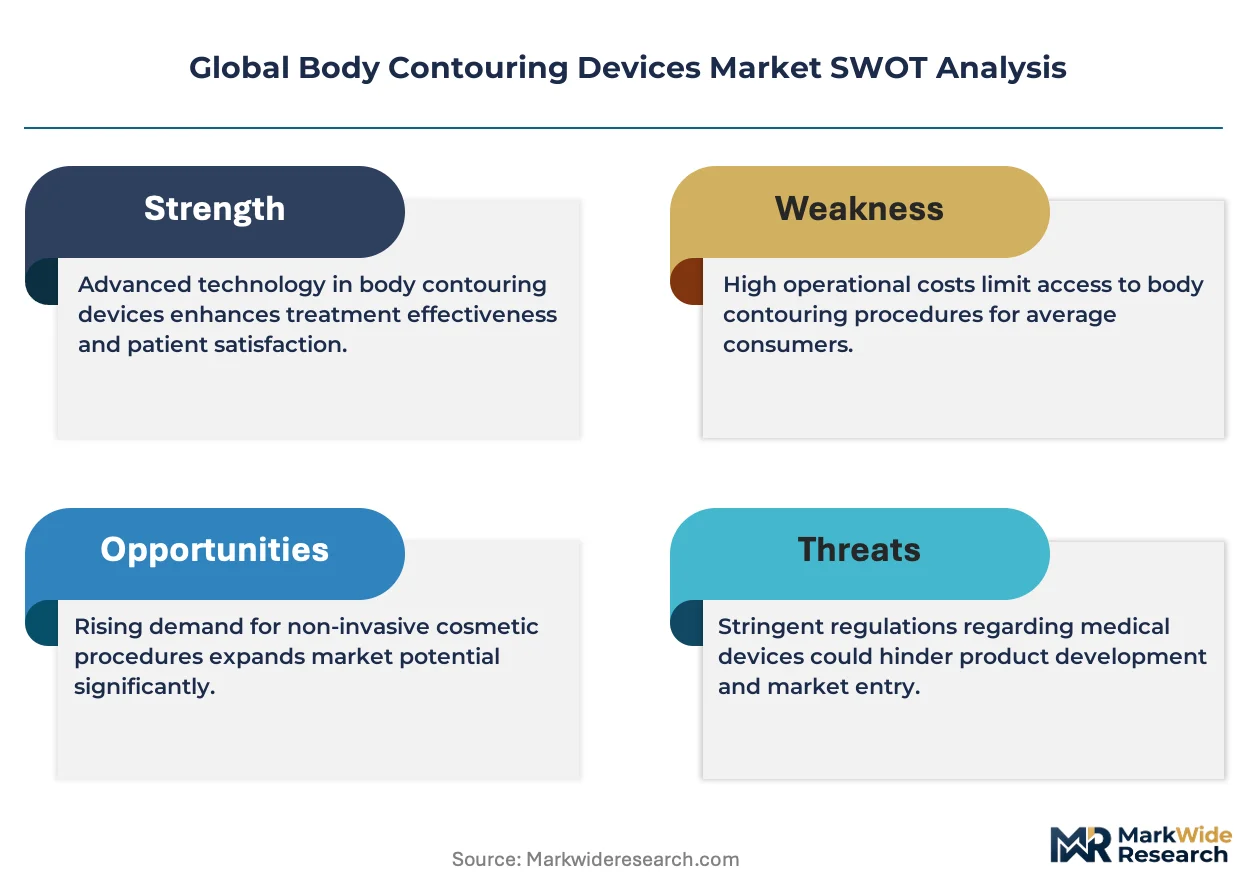
The FDA's 510(k) premarket notification framework governs device safety and efficacy claims in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements and post-market surveillance obligations for CE-marked products sold across Europe. Brazil's national health surveillance agency, ANVISA, maintains separate registration pathways that delay market entry but reward early movers with protected positioning in the world's second-largest aesthetic procedure market. Stakeholders must monitor how divergent clinical evidence standards between the FDA and European notified bodies reshape global product development resource allocation and launch sequencing.
Market Dynamics
Software-defined treatment protocols are compressing hardware replacement cycles while locking clinics into recurring software licensing streams that reshape vendor-customer economics.
Growth Catalysts
- ANVISA registration pathways:Brazil's national health surveillance agency rewards early movers with protected positioning in the world's second-largest aesthetic procedure market, accelerating fleet expansion among dermatology clinics.
- Radiofrequency versatility:Multi-application platforms covering skin tightening and fat reduction reduce capital burden per treatment room, driving adoption across mid-market medical spas.
- Cryolipolysis patient preference:Single-session, no-downtime protocols concentrate demand in premium urban clinics across São Paulo, Dubai, and Seoul.
Market Restraints
- EU MDR clinical evidence requirements:Stricter post-market surveillance obligations for CE-marked products extend development timelines and inflate regulatory compliance costs.
- Supply concentration in semiconductor components:RF generator chips and laser diodes concentrate among East Asian foundries, exposing device manufacturers to input volatility.
- Technical limitation in deep adipose targeting:Energy-based systems face efficacy ceilings at depths beyond 3 centimeters, restricting treatable patient profiles.
Strategic Opportunities
- Underpenetrated India:Rising disposable income and medical tourism infrastructure in Mumbai and Delhi create whitespace for mid-tier ultrasound platforms.
- Technology convergence:Combined radiofrequency-electromagnetic muscle stimulation devices capture bundled body sculpting demand previously split across separate capital purchases.
- Direct-to-physician channel innovation:Subscription-based equipment leasing models reduce upfront capital barriers for independent dermatology practices.
Industry Challenges
- Clinical training certification timelines:Energy-based device operation requires physician credentialing that extends sales-to-revenue cycles.
- IP disputes in cooling technology:Cryolipolysis patent thickets complicate new market entry and inflate licensing costs for emerging vendors.
- Integration complexity with electronic medical records:Treatment protocol documentation systems lack standardized APIs, forcing custom integration work at clinic sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Body Contouring Devices Market |
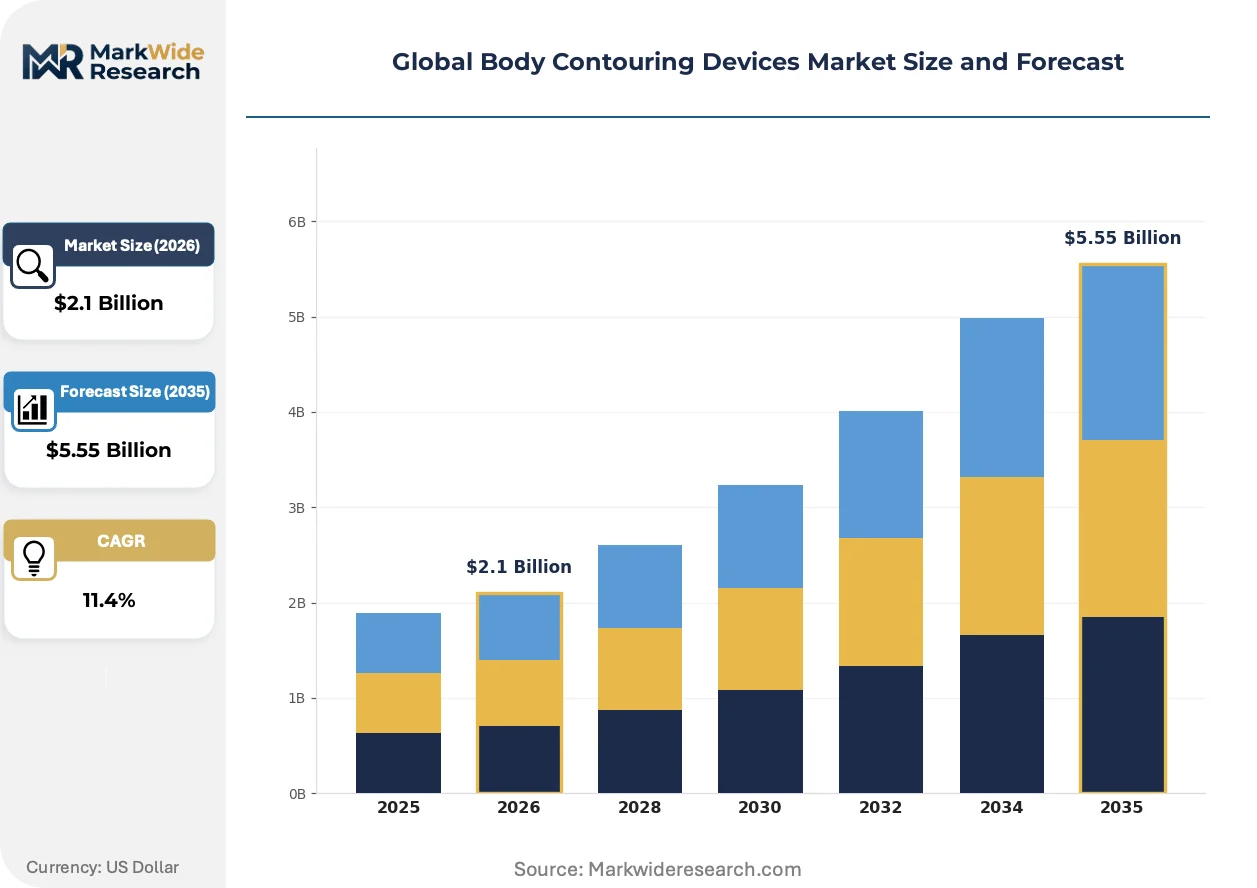
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Laser Therapy Devices, Ultrasound Cavitation Devices, Radiofrequency Devices, Cryolipolysis Machines, Infrared Devices Technology: Cryolipolysis, Ultrasonic, Radiofrequency, Laser Lipolysis, Vacuum Therapy Application: Fat Reduction, Cellulite Treatment, Skin Tightening, Body Sculpting End User: Medical Spas, Dermatology Clinics, Cosmetic Surgery Centers, Wellness Centers, Fitness Studios |
| Companies Covered | AbbVie Inc., Cutera, Inc., Cynosure, Inc., Alma Lasers, Bausch Health Companies Inc., InMode Ltd, Candela Medical Ltd., Lumenis Be Ltd., Venus Concept, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Body Contouring Devices Market Shifts & Advancements
Energy delivery modalities are fragmenting as vendors pursue differentiation through proprietary wavelength combinations and AI-guided treatment mapping that automates physician decision-making.
Multi-polar radiofrequency systems with real-time impedance feedback are expanding into dermatology chains seeking standardized outcomes across geographically dispersed locations. Large clinic groups in Texas and Florida deploy these platforms to reduce physician-to-physician variability. The technology is expanding into subscription revenue models where hardware margins compress while software licensing fees accumulate.
The FDA's evolving 510(k) clearance pathways for energy-based aesthetic devices are compressing product development timelines for established manufacturers while raising evidentiary barriers for novel modalities. Premarket notification frameworks now demand comparative effectiveness data against predicate devices. Cryolipolysis and laser-based fat reduction systems face the steepest documentation requirements.
After-sales service unbundling is disrupting traditional capital equipment purchasing in medical spas. Buyers now procure maintenance, software updates, and consumables through separate contracts rather than bundled warranties. This pattern concentrates margin capture among vendors with captive service networks in California, New York, and Illinois aesthetic corridors.
Global Body Contouring Devices Market Segmentation
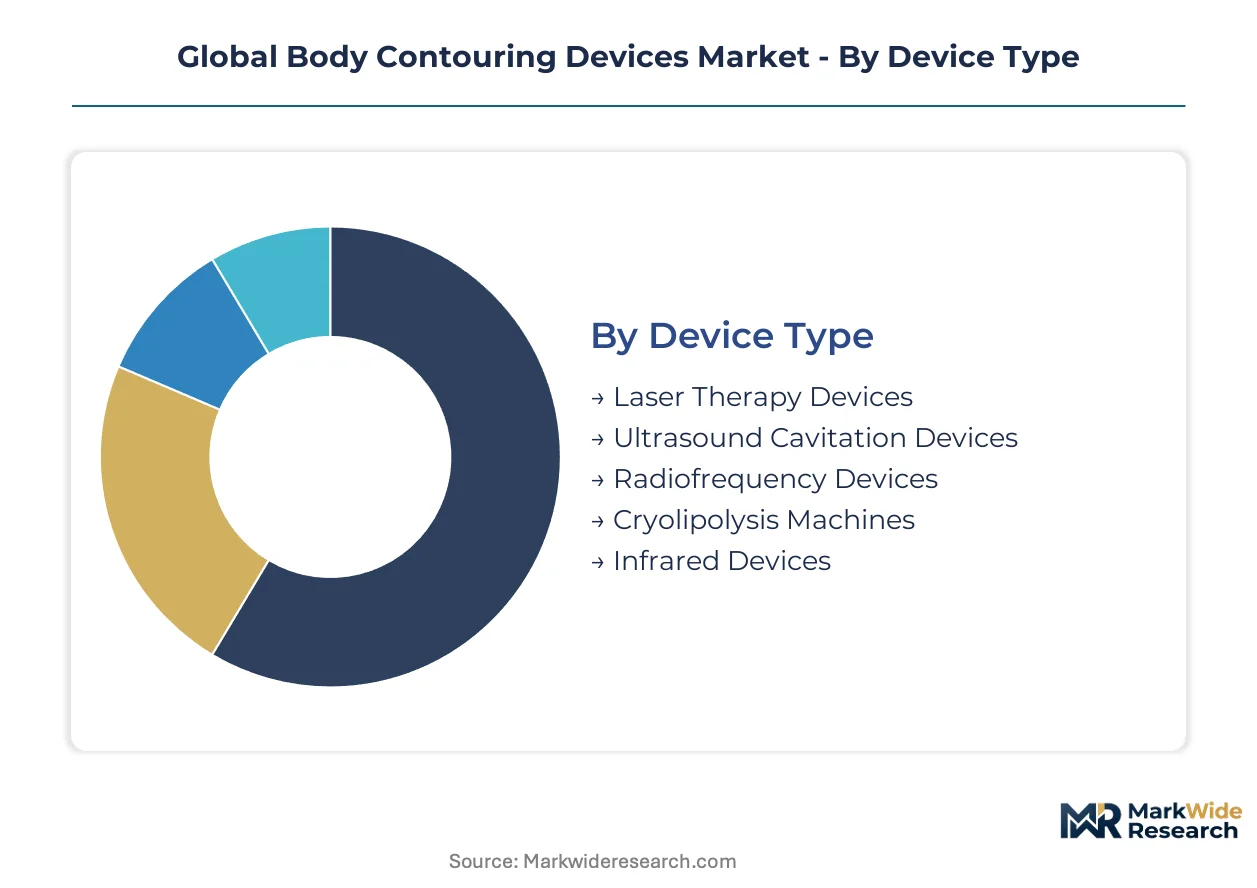
Device heterogeneity in body contouring creates distinct margin profiles and replacement cycles across the installed base. Procurement decisions split between capital-intensive multi-modal platforms and single-purpose devices, with software licensing economics reshaping total cost of ownership calculations.
Device Type:
Capital allocation intensity drives buyer segmentation, with treatment room throughput and reimbursement profiles determining hardware selection.
- Radiofrequency Devices:Multi-polar systems with real-time impedance feedback dominate dermatology chains seeking standardized outcomes. Texas and Florida clinic groups deploy these platforms to reduce physician-to-physician variability across locations. Volume concentrates in mid-market medical spas bundling skin tightening with fat reduction protocols.
- Cryolipolysis Machines:Controlled cooling systems operating at temperatures between -11°C and -1°C selectively crystallize adipocytes without dermal damage. Premium urban clinics in São Paulo and Seoul concentrate demand for single-session, no-downtime protocols. Patent thickets around cooling technology inflate licensing costs for new entrants.
- Laser Therapy Devices:Diode and Nd:YAG wavelengths target superficial fat layers with photothermal energy conversion.
- Ultrasound Cavitation Devices:Low-frequency acoustic waves disrupt adipocyte membranes through cavitation bubble formation.
- Infrared Devices:Near-infrared wavelengths penetrate 5-10 millimeters to stimulate collagen remodeling and mild lipolysis.
Volume sits with Radiofrequency Devices; growth tilts toward Cryolipolysis Machines.
Technology:
Energy delivery modality determines clinical indication breadth and regulatory pathway complexity for manufacturers.
- Radiofrequency:Alternating current at 1-40 MHz generates dermal heating through tissue resistance, with monopolar configurations reaching deeper subcutaneous layers. Dermatology clinics in California and New York aesthetic corridors favor these systems for versatility across skin laxity and fat reduction applications.
- Cryolipolysis:Apoptosis induction via controlled cooling requires precise temperature monitoring and suction applicators. The FDA's evolving 510(k) pathways demand comparative effectiveness data against predicate devices, compressing development timelines for established manufacturers while raising evidentiary barriers for novel modalities.
- Ultrasonic:High-intensity focused ultrasound creates thermal coagulation points at specified tissue depths.
- Laser Lipolysis:650-1064 nm wavelengths target chromophores in adipose tissue with photoselective thermolysis.
- Vacuum Therapy:Mechanical massage combined with suction mobilizes lymphatic drainage and temporarily improves cellulite appearance.
Installed base concentrates in Radiofrequency; steepest expansion trajectory belongs to Cryolipolysis.
Application:
Patient demand fragmentation across aesthetic concerns determines device utilization rates and pricing power.
- Fat Reduction:Non-invasive adipocyte destruction or removal commands premium pricing in medical spas and cosmetic surgery centers. Brazil's ANVISA registration pathways reward early movers with protected positioning in the world's second-largest aesthetic procedure market, accelerating fleet expansion among São Paulo dermatology clinics.
- Skin Tightening:Collagen neogenesis through controlled thermal injury addresses post-weight loss laxity and aging dermis. Radiofrequency platforms capture this demand through multi-application configurations that reduce capital burden per treatment room.
- Cellulite Treatment:Subdermal fibrous septae release and adipose redistribution target connective tissue irregularities.
- Body Sculpting:Muscle definition enhancement through electromagnetic stimulation represents the fastest-climbing application segment.
Revenue concentration favors Fat Reduction; patient visit frequency peaks in Skin Tightening.
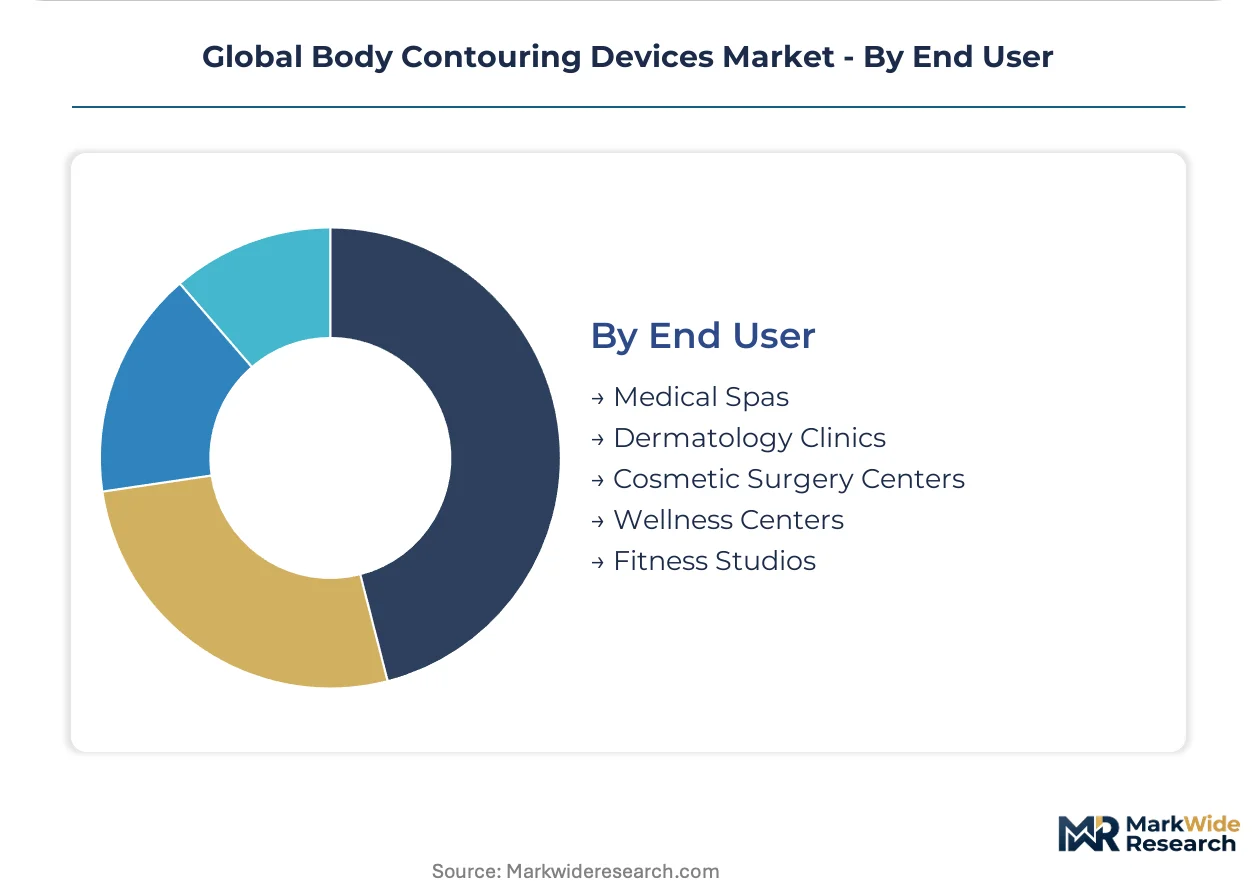
End User:
Channel structure determines service bundling capabilities and software subscription attach rates.
- Dermatology Clinics:Physician-supervised settings with credentialing requirements concentrate high-value procedures and complex case referrals. Large clinic groups deploy standardized platforms to enforce protocol consistency across Texas, Florida, and California locations, reducing outcome variability.
- Medical Spas:Non-physician operated facilities drive volume in maintenance treatments and package-based patient retention. After-sales service unbundling disrupts traditional capital equipment purchasing in California, New York, and Illinois aesthetic corridors, with maintenance and software updates procured through separate contracts.
- Cosmetic Surgery Centers:Hybrid surgical-non-surgical settings capture pre- and post-operative body contouring demand.
- Wellness Centers:Lifestyle-oriented facilities integrate body contouring with nutrition and fitness programming.
- Fitness Studios:Gym-affiliated treatment rooms represent emerging channel experimentation with lower price points.
Margin pools concentrate in Dermatology Clinics; fleet expansion rates peak in Medical Spas.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing clusters concentrate in Israel and the United States, while Brazil and South Korea absorb disproportionate procedure volumes relative to their production bases.
United States
Dermatology chains in Texas and Florida deploy standardized radiofrequency platforms to reduce outcome variability across locations. The FDA's evolving 510(k) clearance pathways compress development timelines for established manufacturers while raising evidentiary barriers for novel modalities. California and New York aesthetic corridors concentrate premium cryolipolysis demand and drive after-sales service unbundling trends.
Brazil
ANVISA registration pathways reward early movers with protected positioning in the world's second-largest aesthetic procedure market. São Paulo dermatology clinics accelerate fleet expansion to capture medical tourism flows and domestic aesthetic culture demand. Rio de Janeiro and Minas Gerais secondary markets show rising penetration of mid-tier ultrasound platforms.
Germany
The EU Medical Device Regulation imposes stricter clinical evidence requirements and post-market surveillance obligations that extend development timelines for CE-marked products. Bavaria and Baden-Württemberg manufacturing clusters supply precision RF generator components to global device assemblers. Berlin aesthetic practices favor multi-application platforms that reduce capital burden per treatment room.
South Korea
Seoul premium urban clinics concentrate demand for single-session, no-downtime cryolipolysis protocols. The MFDS maintains registration pathways that parallel FDA timelines while demanding localized clinical trial data for energy-based devices. Busan medical tourism infrastructure channels regional patient flows into body sculpting procedure packages.
India
Rising disposable income and medical tourism infrastructure in Mumbai and Delhi create whitespace for mid-tier ultrasound platforms. CDSCO device registration timelines lag FDA and EU pathways, delaying market entry but protecting early movers from rapid competitive erosion. Maharashtra and Karnataka clinic networks experiment with subscription-based equipment leasing models.
Global Body Contouring Devices Market Competitive Landscape
Top-tier vendors anchor premium cryolipolysis and radiofrequency portfolios, while mid-market specialists compete on multi-modal platform versatility and regional channel control. The vendor base spans three strategic archetypes: diversified pharmaceutical-aesthetic conglomerates, pure-play energy-based device manufacturers, and regional laser platform specialists. Competitive moves concentrate on technology convergence for bundled body sculpting demand and direct-to-physician channel innovation through subscription leasing models.
Within the diversified conglomerate tier, AbbVie Inc. occupies a position exemplifying premium portfolio breadth across cryolipolysis and injectable categories. Among pure-play energy-based specialists, InMode Ltd and Alma Lasers represent contrasting geographic anchoring strategies—Israeli technology leadership versus Asia-Pacific and Latin American market penetration. These three entities illustrate how competitive positioning fragments across technology specialization, channel control, and regional footprint depth rather than consolidating around scale alone.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Cutera, Inc. |
| Cynosure, Inc. |
| Alma Lasers |
| Bausch Health Companies Inc. |
| InMode Ltd |
| Candela Medical Ltd. |
| Lumenis Be Ltd. |
| Venus Concept |
| Others |
Supply & Pricing Matrix
Israeli RF engineering talent clusters in Yokneam Illit and Caesarea drive labor-cost differentials that separate premium-tier device pricing from mid-market alternatives. These specialized workforce concentrations compress margins for manufacturers lacking captive engineering depth while rewarding vendors with in-house generator design capabilities.
Pricing Analysis
Cost-down pressure on mid-tier ultrasound platforms accelerates because Indian and Brazilian clinics demand subscription-based leasing models that shift revenue to recurring streams. Three-tier pricing structure across premium, standard, and economy levels separates cryolipolysis machines with full FDA 510(k) clearance from CE-marked alternatives and non-regulated imports. Certification grade and after-sales service bundling drive price differentiation. Independent dermatology practices in Texas and Florida exhibit highest price sensitivity; premium urban clinics in Seoul and São Paulo show lowest.
Supply Chain Analysis
Direct-to-physician channels handle fleet expansion demand from large dermatology chains, bypassing traditional distributor markups. RF generator chips and laser diodes concentrate among South Korean and Taiwanese foundries. Device assembly draws from Israeli precision manufacturing and German component engineering. Single-source vulnerability in semiconductor inputs exposes manufacturers to foundry allocation constraints. Distribution runs through captive service networks in California, New York, and Illinois aesthetic corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around vendors with integrated software-hardware stacks, as EU MDR compliance costs force sub-scale players toward exit or acquisition.
For Market Incumbents: Deploy subscription-based equipment leasing to lock in recurring revenue and raise switching costs for clinic customers. Deepen backward integration into RF generator chip design to reduce exposure to East Asian foundry allocation cycles. Patent thickets around cryolipolysis cooling technology threaten margin compression for licensors; accelerate proprietary wavelength development to escape royalty burdens. For New Entrants and Emerging Players: Independent dermatology practices in secondary Indian cities represent underserved buyer archetype with whitespace for mid-tier ultrasound platforms. ANVISA registration pathways in Brazil reward first movers with protected positioning against later entrants. Target CDSCO registration timelines to capture Maharashtra and Karnataka clinic networks before multinational vendors establish service infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with pure-play energy-based device manufacturers given technology convergence toward bundled body sculpting platforms. Five-to-ten year viability favors vendors with direct-to-physician channel control and software subscription attach rates above hardware replacement cycles. Watch FDA 510(k) clearance velocity for novel modalities as inflection indicator for competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | AI-guided treatment mapping automates physician decision-making and locks clinics into recurring licensing. |
| CE Marking Pathway Investment | EU MDR clinical evidence requirements extend timelines but protect early movers from rapid competitive erosion. |
| Hospital System Partnership | Dermatology chains in Texas and Florida deploy standardized platforms to reduce outcome variability across locations. |
| Backward Integration into RF Components | In-house generator design reduces foundry dependency and compresses bill-of-materials for multi-polar systems. |
| ANVISA Early Registration | Brazil's protected positioning rewards accelerate fleet expansion in São Paulo's medical tourism corridor. |
Research Methodology
Multi-period observation of device procurement patterns, regulatory submission timelines, and clinic fleet expansion rates anchored the trend analysis, supplemented by interviews with biomedical engineers, dermatology clinic operators, GPO contracts managers, and ANVISA registration specialists. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body decisions, CDSCO device registration records, and hospital procurement databases. Bottom-up clinic-by-clinic demand estimation triangulated against top-down manufacturer shipment data.
Input-output matrices mapped energy delivery modality adoption to end-user channel structure across the projection horizon. Segmentation dimensions modeled include device type, technology platform, clinical application, and geographic regulatory cluster. CAGRs derived from logistic diffusion curves fitted to installed base replacement cycles and first-time adoption rates. Software licensing attach rates and subscription conversion ratios informed recurring revenue projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA evidentiary requirement shifts, semiconductor supply allocation disruptions, and ANVISA pathway modifications. Forecasts reflect documented assumptions regarding clinic capital expenditure cycles and patient visit frequency elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Pulse Oximeters Market
Medical Devices
Europe Spinal Fusion Devices Market
Medical Devices
Software As a Medical Device Market
Medical Devices
Indonesia Devices Market
Medical Devices
Artificial Cartilage Implant Market
Medical Devices
Ultrasound Probe Market
Medical Devices
Global Medical Device Contract Manufacturing Market
Medical Devices
Blood Collection Vacuum Devices Market
Medical Devices
Global Cardiac Holter Monitor Market
Medical Devices
Argentina Aesthetic Devices Market
Medical Devices
PDA Closure Devices Market
Medical Devices
Global Bone Screw System Market
Medical Devices
Global Surgical Polypropylene Mesh Market
Medical Devices
Anesthesia Circuits Market
Medical Devices
Global Prosthetic Heart Valve Market
Medical Devices
Global Photomedicine Market