
 Apoptosis Testing Market | 2026-2036
Apoptosis Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Apoptosis Testing Market Outlook
North American reagent manufacturing is hardening as suppliers scale GMP-compliant production lines for clinical-grade apoptosis detection materials. Thermo Fisher Scientific leverages its end-to-end life sciences platform to control distribution channels across academic and pharmaceutical accounts. Bio-Rad Laboratories sustains competitive positioning through specialized flow cytometry instrumentation that anchors its apoptosis workflow offerings. Promega Corporation differentiates via luminescence-based assay architectures that dominate high-throughput drug screening applications.
Apoptosis testing encompasses laboratory methods that detect programmed cell death through biochemical, morphological, or molecular markers, typically measuring caspase activity, DNA fragmentation, or phosphatidylserine externalization with detection thresholds reaching picogram sensitivity. These techniques serve pharmaceutical development, toxicology safety assessment, and fundamental cancer biology research by quantifying cell viability pathways and therapeutic cytotoxicity. Reagents and kits capture the largest revenue share due to recurring consumable demand across multi-year research programs, while flow cytometry technology leads instrument investment as researchers prioritize multiplexed single-cell resolution. Drug development applications represent the fastest-expanding segment as FDA and EMA both intensify requirements for mechanistic cell death data in oncology trial submissions.
FDA biomarker qualification programs and EMA's ICH S9 oncology guidelines jointly reshape apoptosis assay validation standards for regulatory submission packages. ISO 13485 and CLSI EP17-A2 frameworks govern analytical performance claims for in vitro diagnostic applications of cell death detection methods. Stakeholders must monitor evolving harmonization between FDA's biomarker initiative and EMA's scientific advice procedures to anticipate future data package requirements.
Market Dynamics
Pharmaceutical pipeline complexity is driving assay standardization as oncology developers consolidate around multiplexed cell death detection platforms to satisfy mechanistic data requirements for regulatory submissions.
Growth Catalysts
- FDA Biomarker Qualification Programs:The agency's structured pathways for cell death marker validation accelerate assay adoption into Phase II and III oncology trials.
- Flow cytometry instrumentation:Single-cell resolution capabilities enable researchers to quantify apoptotic subpopulations within heterogeneous tumor samples.
- Germany's biotech clusters:Concentrated pharmaceutical R&D in Munich and Heidelberg generates sustained demand for clinical-grade apoptosis detection reagents.
Market Restraints
- Specialized fluorophore supply:Limited manufacturers of Annexin V conjugates create input cost volatility and procurement bottlenecks for assay kit producers.
- ICH S9 analytical validation:EMA's stringent oncology safety guidelines extend development timelines and raise compliance expenditures for diagnostic developers.
- Primary cell sourcing:Human tissue acquisition constraints limit assay standardization across pharmaceutical contract research organizations.
Strategic Opportunities
- Japan's regenerative medicine sector:PMDA's accelerated approval pathways for cell therapies create demand for apoptosis monitoring in stem cell quality control workflows.
- Luminescence-cytometry convergence:Integration of high-sensitivity detection with single-cell analysis enables new multiparametric screening architectures.
- ISO 13485 certification expansion:In vitro diagnostic framework harmonization opens pathway for apoptosis assays to migrate from research-only to clinical diagnostic use.
Industry Challenges
- Multiplex assay development expertise:Shortage of scientists proficient in panel design for simultaneous caspase, DNA fragmentation, and membrane marker detection constrains product pipeline velocity.
- Legacy fluorescence microscope integration:Academic laboratories face capital friction when upgrading to automated imaging platforms compatible with high-content apoptosis screening.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apoptosis Testing Market |
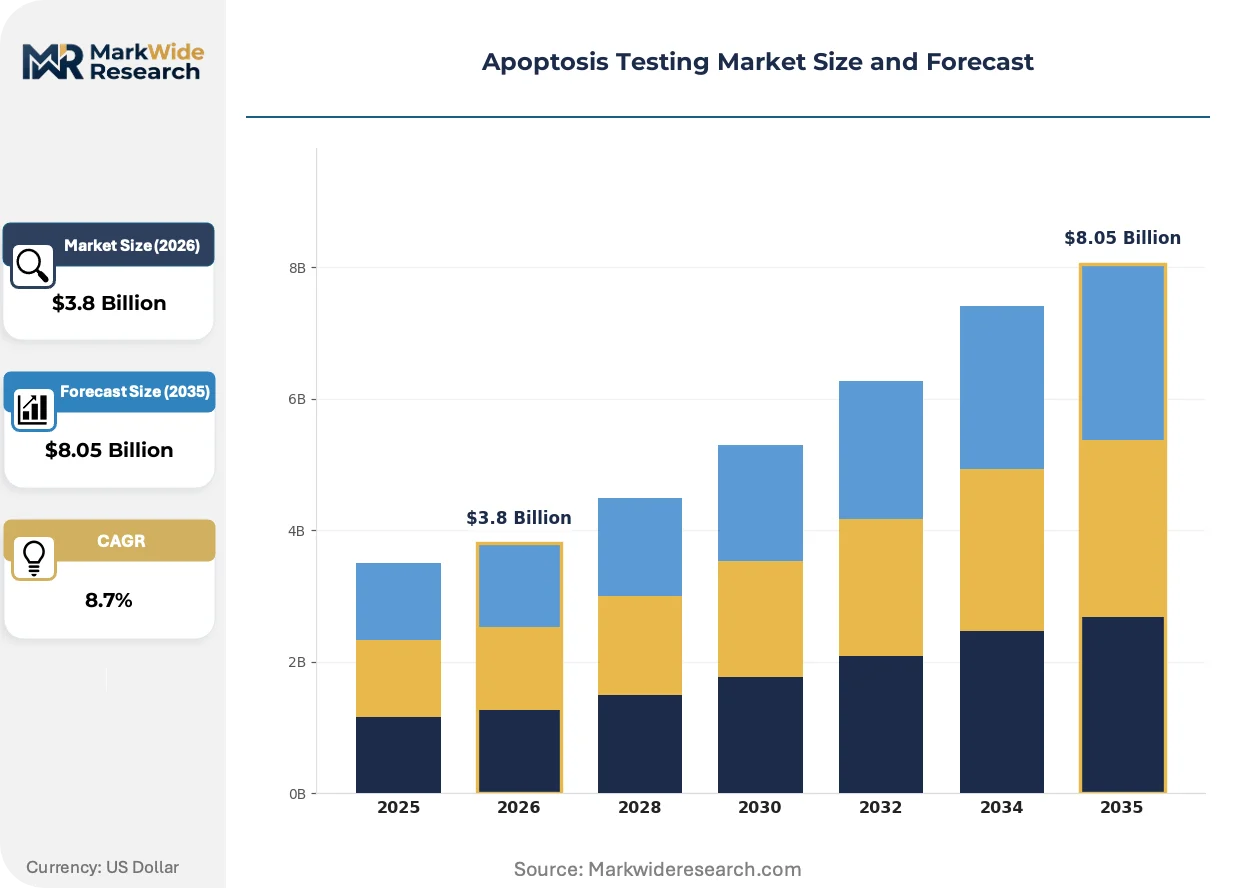
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Instruments, Assays Technology: Flow Cytometry, ELISA, Microscopy, PCR End User: Pharmaceuticals, Biotechnology Companies, Research Institutions, Hospitals Application: Drug Development, Cancer Research, Toxicology Testing, Basic Research |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, Bio-Rad Laboratories, Inc., Promega Corporation, Abcam plc, Becton, Dickinson and Company, Danaher Corporation, PerkinElmer, Bio-Techne, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apoptosis Testing Market Strategic Shifts
Detection modality diversification is compressing traditional workflow boundaries as researchers demand quantitative precision alongside morphological context. Instrument manufacturers are responding with hybrid platforms that merge biochemical sensitivity with spatial resolution.
Real-time luminescence readouts are overtaking endpoint fluorescence assays in pharmaceutical high-throughput screening. Caspase-Glo architectures deliver picogram-level sensitivity without wash steps. Major contract research organizations in the United States have standardized on these platforms for cytotoxicity profiling. The shift compresses assay timelines from hours to minutes while reducing technician handling variables.
EMA's ICH S9 oncology guidelines are tightening mechanistic cell death documentation requirements for investigational new drug submissions. Developers must now distinguish apoptotic from necrotic cell death in safety pharmacology packages. European pharmaceutical sponsors are investing in validated assay panels that satisfy both FDA and EMA biomarker standards simultaneously. This regulatory convergence is elevating multiplexed flow cytometry to default status for oncology toxicology studies.
Consolidated procurement through centralized core facilities is displacing departmental instrument purchasing at research universities. Shared access models spread capital costs across multiple principal investigator groups. Germany's Max Planck Institutes and Japan's RIKEN centers exemplify this operational shift. The model favors vendors offering service contracts and reagent subscription programs over discrete equipment sales.
Apoptosis Testing Market Segmentation
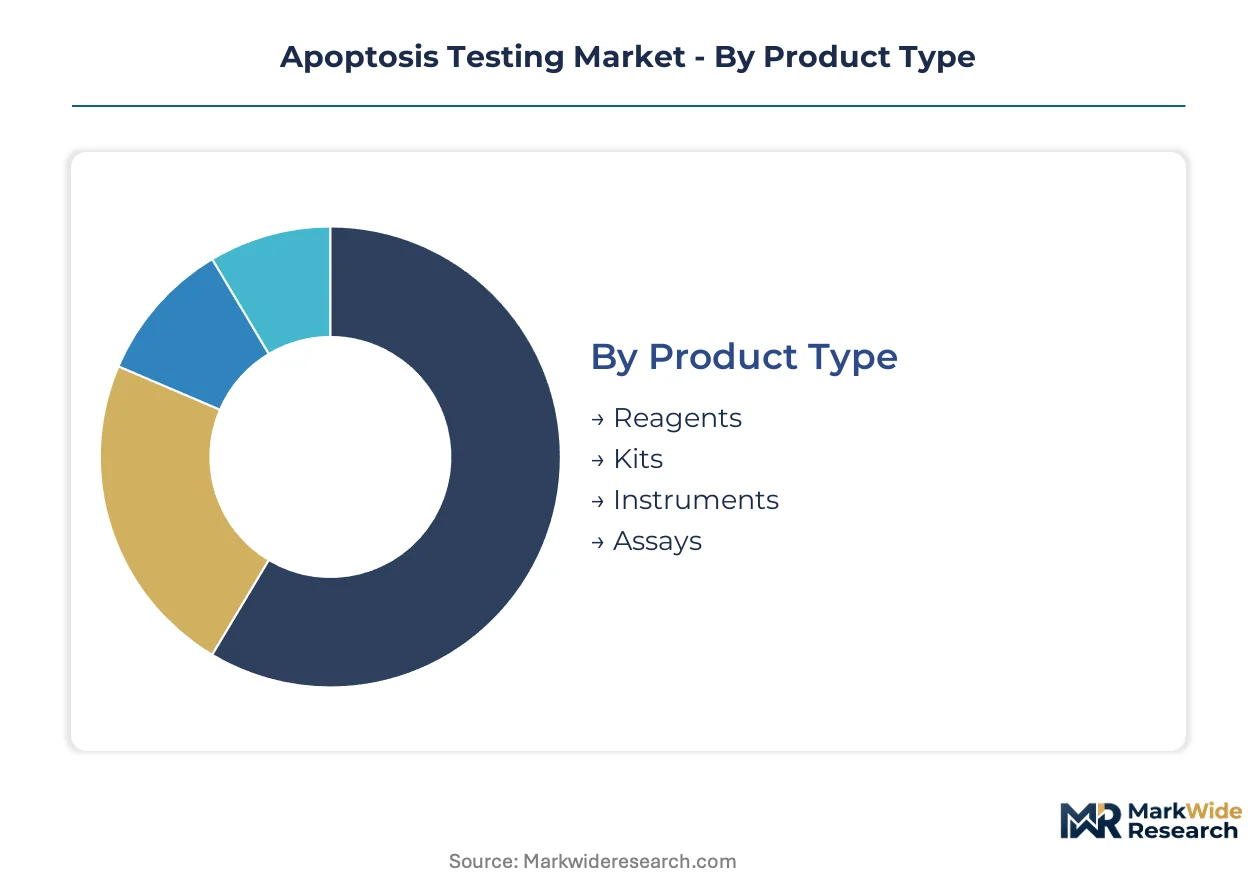
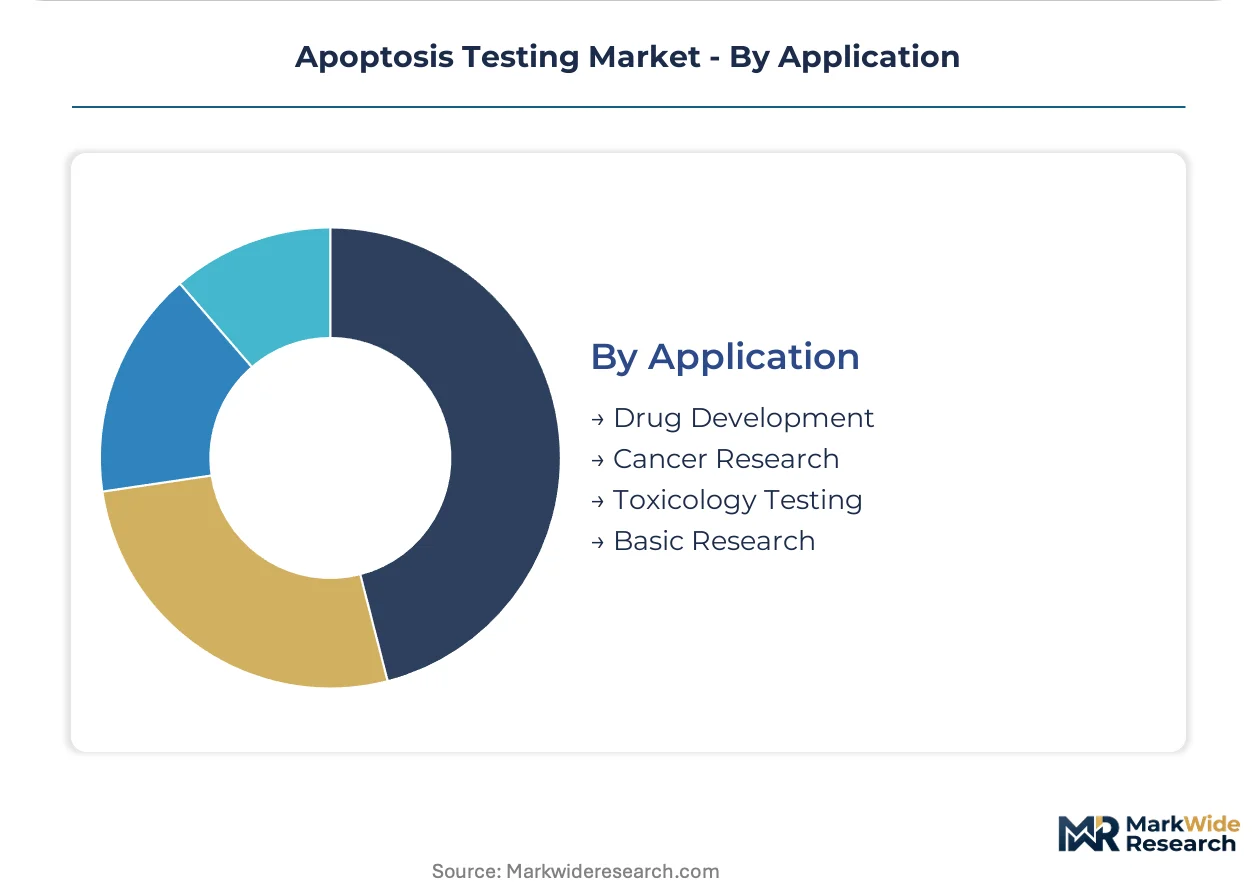
Apoptosis testing markets fragment across multiple dimensions that determine procurement patterns and margin structures. Product refresh cycles, technology obsolescence, and regulatory validation requirements create distinct upgrade dynamics within each category. Understanding these segmentation boundaries enables precise targeting of R&D investment and distribution capacity.
Product Type:
Replacement cycles vary sharply across product categories, with consumable reagents demanding continuous replenishment while instruments trigger capital committee reviews.
- Reagents:Clinical-grade detection reagents require GMP-compliant manufacturing and cold-chain logistics. Pharmaceutical contract manufacturers in Germany and Japan sustain the heaviest procurement volumes as they scale oncology drug screening operations.
- Kits:Pre-formulated assay kits compress setup time for multi-site clinical trials. FDA biomarker qualification programs are accelerating kit standardization among United States-based pharmaceutical sponsors seeking regulatory submission efficiency.
- Instruments:Flow cytometers and automated imaging platforms carry five-to-seven-year depreciation schedules.
- Assays:Custom assay development services address specialized mechanistic cell death questions.
Volume placements concentrate in Reagents; the faster expansion belongs to Kits.
Technology:
Technology selection hinges on the resolution-throughput tradeoff, with single-cell analysis commanding premium positioning against bulk biochemical readouts.
- Flow Cytometry:Multiparametric single-cell resolution enables apoptotic subpopulation quantification within heterogeneous tumor samples. Academic medical centers in the United States and Germany prioritize this modality for immuno-oncology translational research.
- ELISA:Plate-based enzyme assays deliver cost-efficient bulk population measurements for high-throughput cytotoxicity screening.
- Microscopy:Morphological confirmation of apoptotic bodies requires trained pathologist interpretation.
- PCR:DNA fragmentation detection via laddering assays provides molecular specificity for late-stage apoptosis confirmation.
Capital deployment favors Flow Cytometry; PCR is climbing the fastest as companion diagnostic applications mature.
End User:
Customer procurement authority differs dramatically between centralized pharmaceutical sourcing and distributed academic purchasing.
- Pharmaceuticals:Integrated drug developers mandate validated apoptosis data packages for FDA and EMA oncology submissions. Mechanistic cell death documentation requirements under ICH S9 guidelines are expanding assay panel procurement across Phase I-III trial portfolios.
- Biotechnology Companies:Venture-funded biotechs prioritize flexible assay architectures that scale from discovery through IND-enabling studies. United States coastal clusters in Boston and San Francisco generate concentrated demand for luminescence-based screening platforms.
- Research Institutions:University core facilities spread instrument costs across multiple principal investigator groups.
- Hospitals:Clinical pathology laboratories represent nascent demand as apoptosis assays migrate toward diagnostic applications.
Contract values peak with Pharmaceuticals; Biotechnology Companies are expanding most quickly.
Application:
Application segmentation tracks the regulatory intensity gradient from exploratory research through formal safety pharmacology.
- Drug Development:Oncology pipeline sponsors require multiplexed cell death detection to satisfy mechanistic data requirements. EMA's ICH S9 guidelines and FDA biomarker qualification programs jointly elevate assay validation standards for investigational new drug packages.
- Cancer Research:Fundamental tumor biology studies probe apoptotic pathway modulation by novel therapeutic modalities. German Max Planck Institutes and Japan's RIKEN centers anchor sustained reagent demand through centralized core facility procurement.
- Toxicology Testing:Safety pharmacology departments distinguish apoptotic from necrotic cell death in preclinical candidate profiling.
- Basic Research:Exploratory cell biology investigations employ lower-stringency assay formats.
Validation requirements are stiffest in Drug Development; Cancer Research maintains the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized fluorophore manufacturing concentrates in southern Germany and the Massachusetts corridor, anchoring reagent supply chains for clinical-grade apoptosis detection materials. Pharmaceutical R&D clustering in three distinct biotech corridors drives regional procurement intensity.
United States
FDA biomarker qualification programs accelerate assay adoption into Phase II and III oncology trials. The agency's structured validation pathways reshape product development requirements for domestic sponsors. Greater Boston and San Francisco Bay Area biotech clusters generate concentrated demand for luminescence-based screening platforms.
Germany
EMA's ICH S9 oncology guidelines extend development timelines and raise compliance expenditures for diagnostic developers. ISO 13485 certification requirements govern analytical performance claims for in vitro diagnostic applications. Munich and Heidelberg pharmaceutical R&D centers sustain heavy procurement volumes for clinical-grade detection reagents.
Japan
PMDA's accelerated approval pathways for cell therapies create demand for apoptosis monitoring in stem cell quality control workflows. METI industrial standards support regenerative medicine sector expansion. RIKEN research centers exemplify consolidated procurement through centralized core facilities spreading capital costs across investigator groups.
United Kingdom
MHRA post-Brexit regulatory autonomy enables tailored pathways for novel cell death biomarker validation. Academic medical centers prioritize flow cytometry instrumentation for immuno-oncology translational research. Cambridge and Oxford life science clusters anchor sustained reagent demand through shared access service contracts.
China
NMPA medical device classification reforms streamline in vitro diagnostic registration for apoptosis detection methods. Domestic pharmaceutical pipeline expansion drives assay standardization for mechanistic cell death documentation. Shanghai and Suzhou biotech parks concentrate contract research organization procurement for multi-site clinical trial support.
Apoptosis Testing Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue luminescence-cytometry convergence architectures. The vendor base stratifies across three maturity levels: diversified life sciences conglomerates controlling distribution channels, specialized assay developers dominating high-throughput applications, and regional reagent fabricators serving localized academic accounts. Strategic differentiation centers on GMP-compliant manufacturing scale, multiplexed detection panel breadth, and regulatory submission support capabilities. Consolidation pressure intensifies as pharmaceutical sponsors demand end-to-end workflow solutions spanning reagents through data analysis.
Among diversified platform providers, Thermo Fisher Scientific and Danaher Corporation represent integrated life sciences conglomerates leveraging end-to-end capabilities. Bio-Rad Laboratories occupies a position within the specialized instrumentation tier, while Promega Corporation exemplifies assay architecture specialists. These three anchors demonstrate how competitive positioning depends on controlling distinct value chain segments rather than horizontal coverage alone.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Bio-Rad Laboratories, Inc. |
| Promega Corporation |
| Abcam plc |
| Becton, Dickinson and Company |
| Danaher Corporation |
| PerkinElmer |
| Bio-Techne |
| Others |
Value Chain & Pricing Dynamics
ISO 13485 certification compliance gates both qualified supply and premium-tier pricing access for clinical-grade apoptosis detection reagents, as pharmaceutical sponsors demand validated assay packages for FDA and EMA oncology submissions. GMP-compliant manufacturing scale separates premium-tier suppliers from standard research-grade vendors, with cold-chain logistics capabilities further stratifying procurement tiers across United States, German, and Japanese biotech clusters.
Pricing Analysis
Service bundling separates instrument-reagent subscription models from unbundled transactional kit sales, with Thermo Fisher Scientific and Danaher Corporation leveraging multi-year service contracts to lock pharmaceutical accounts. Three-tier pricing structure across premium, standard, and economy levels reflects GMP certification status, multiplex panel breadth, and regulatory submission support depth. Cost compression in standard research-grade reagents is intensifying because contract research organizations consolidate procurement through centralized core facilities. Academic laboratories exhibit highest price sensitivity due to capital committee approval friction, while integrated pharmaceutical developers prioritize validation documentation over unit cost.
Supply Chain Analysis
Direct-to-pharmaceutical channels handle hyperscale buyer demand for validated assay panels, while distributor networks serve fragmented academic accounts across regional clusters. Manufacturing concentrates in southern Germany, Massachusetts, and Japan where specialized fluorophore synthesis capabilities anchor Annexin V conjugate supply. Raw material dependencies include high-purity fluorophores, recombinant caspase enzymes, and clinical-grade Annexin V proteins. Single-source vulnerability in Annexin V conjugate manufacturing creates procurement bottlenecks when specialized suppliers face capacity constraints. Distribution runs through life sciences platform providers controlling end-to-end workflow solutions rather than discrete component vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where controlling GMP-compliant reagent manufacturing represents the decisive upstream lever separating premium-tier suppliers from commoditized competitors.
For Market Incumbents: Deploy regulatory submission support capabilities as defensive moats against emerging luminescence-cytometry convergence specialists. Incumbents should deepen backward integration into fluorophore synthesis to secure Annexin V conjugate supply chains, while expanding ISO 13485-certified manufacturing capacity in Germany and Japan to capture regenerative medicine quality control demand. Capacity addition in PMDA-aligned production facilities addresses stem cell therapy monitoring workflows. For New Entrants and Emerging Players: Digital channel partnerships with contract research organization procurement platforms offer lower-friction market entry than direct pharmaceutical sales cycles. New entrants should target biotechnology companies in Boston and San Francisco coastal clusters seeking flexible assay architectures scaling from discovery through IND-enabling studies. White-space opportunity concentrates in luminescence-based high-throughput screening platforms where Promega Corporation's dominance leaves room for specialized panel developers. For Investors and Strategic Acquirers: FDA biomarker qualification program approvals for specific cell death markers are the leading indicator that assay validation standards have hardened sufficiently to justify premium multiples. Long-term viability hinges on regulatory convergence between FDA and EMA mechanistic cell death documentation requirements. Acquisition targets should display multiplex assay development expertise combining caspase, DNA fragmentation, and membrane marker detection capabilities. Practitioners should monitor ICH S9 guideline harmonization progress for early signals of validation standard elevation.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Manufacturing Scale-Up | ISO 13485 certification unlocks clinical diagnostic migration pathways beyond research-only applications. |
| Multiplex Panel Expansion | Simultaneous caspase, DNA fragmentation, and phosphatidylserine detection satisfies ICH S9 mechanistic documentation requirements. |
| Regulatory Submission Support | FDA biomarker qualification program navigation accelerates pharmaceutical sponsor assay adoption into Phase II-III trials. |
| Luminescence-Cytometry Convergence | Integration of picogram-sensitivity detection with single-cell analysis enables new high-content screening architectures. |
| Core Facility Service Contracts | Shared access models at Max Planck Institutes and RIKEN centers spread capital costs across investigator groups. |
Study Parameters
Document review covered FDA biomarker qualification program filings, EMA ICH S9 guideline documentation, and ClinicalTrials.gov mechanistic cell death data requirements, complemented by interviews with oncology drug development executives, regulatory affairs leads at pharmaceutical sponsors, flow cytometry core facility directors, and reagent procurement managers at contract research organizations. Secondary validation drew from SEC 10-K life sciences segment disclosures, ISO 13485 certification databases, and German and Japanese industrial standards publications. Bottom-up demand modeling across reagent, kit, instrument, and assay categories was triangulated against top-down pharmaceutical R&D expenditure allocations.
Historical instrument placement data was cross-referenced against panel input from academic medical center procurement committees and biotechnology company screening platform directors. Segmentation dimensions modeled include product type, detection technology, end-user category, and application intensity across drug development, cancer research, toxicology testing, and basic research. CAGRs were derived from regression analysis of replacement cycle dynamics and regulatory validation timeline compression. Industry-specific forecast inputs incorporated PMDA accelerated approval pathway expansion for cell therapies and EMA scientific advice procedure evolution for biomarker packages.
The model holds under continued regulatory convergence between FDA and EMA mechanistic cell death documentation standards; deviation in ICH S9 guideline implementation timelines or fluorophore supply disruptions would shift instrument procurement priorities and reagent pricing trajectories. Practitioners should monitor Annexin V conjugate manufacturer capacity utilization and biomarker qualification program approval velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Biologics Safety Testing Market
Testing Services
Pharmaceutical Sterility Testing Market
Testing Services
Global Diagnostic Testing Market
Testing Services
Radiographic Testing Market
Testing Services
Global CA 125 Test Market
Testing Services
Global Drug Abuse Testing Market
Testing Services
Global Rapid Test Market
Testing Services
Nanoparticle Drug Delivery Size and Zeta Potential Measurement Instruments Market
Testing Services
Pharmaceutical Dissolution Testing Services Market
Testing Services
Platelet Function Testing Market
Testing Services
Blood Testing Market
Testing Services
Apolipoprotein Testing Market
Testing Services
Rapid Antigen Testing Market
Testing Services
Nucleic Acid Testing Market
Testing Services
Asia Pacific Pregnancy and Ovulation Testing Market
Testing Services
Blood Pressure Test Market