
 Bluetooth Smart Plugs Market | 2026-2036
Bluetooth Smart Plugs Market Size, Share, and Industry Trends Forecast 2026-2036
Bluetooth Smart Plugs Market Analysis
Polycarbonate housings replacing ABS enclosures is broadening thermal tolerance margins for high-amperage Bluetooth smart plugs operating near circuit limits. TP-Link Technologies Co. Ltd. leverages vertically integrated semiconductor sourcing to control chipset costs across its Kasa product line. Belkin International Inc. anchors its Wemo brand through deep retail partnerships with home improvement chains in North America. Etekcity Corporation specializes in budget-tier USB-integrated models that compete aggressively on e-commerce platforms.
Bluetooth smart plugs are self-contained electrical adapters that embed Bluetooth Low Energy or dual-mode chipsets to enable smartphone-based on-off scheduling, energy monitoring, and voice-assistant relay without dedicated hub hardware; typical units carry 10-15A load ratings, incorporate relay switches rated for 100,000+ cycles, and communicate via BLE 5.0 or 5.3 protocols with sub-30ms latency for real-time responsiveness. Indoor plugs dominate unit volume as consumers prioritize lamp and appliance automation, while outdoor plugs command premium positioning due to weatherproofing requirements and GFCI integration that extends usable margin pools. The hospitality end-user segment shows structural acceleration as hotel chains deploy property-wide energy management systems that treat plug-level control as a retrofit alternative to rewiring.
FCC Part 15 emissions rules in the United States, CE marking under the EU Radio Equipment Directive, and China's SRRC certification collectively shape product development timelines and test-budget allocation for multi-region suppliers. The EU's Ecodesign and Energy Labelling frameworks now mandate maximum standby power draw thresholds that directly influence relay selection and Bluetooth module sleep-state engineering. Stakeholders must monitor evolving cybersecurity labeling requirements from regulators in multiple jurisdictions, as firmware update mechanisms and local data storage become compliance battlegrounds rather than optional features.
Market Dynamics
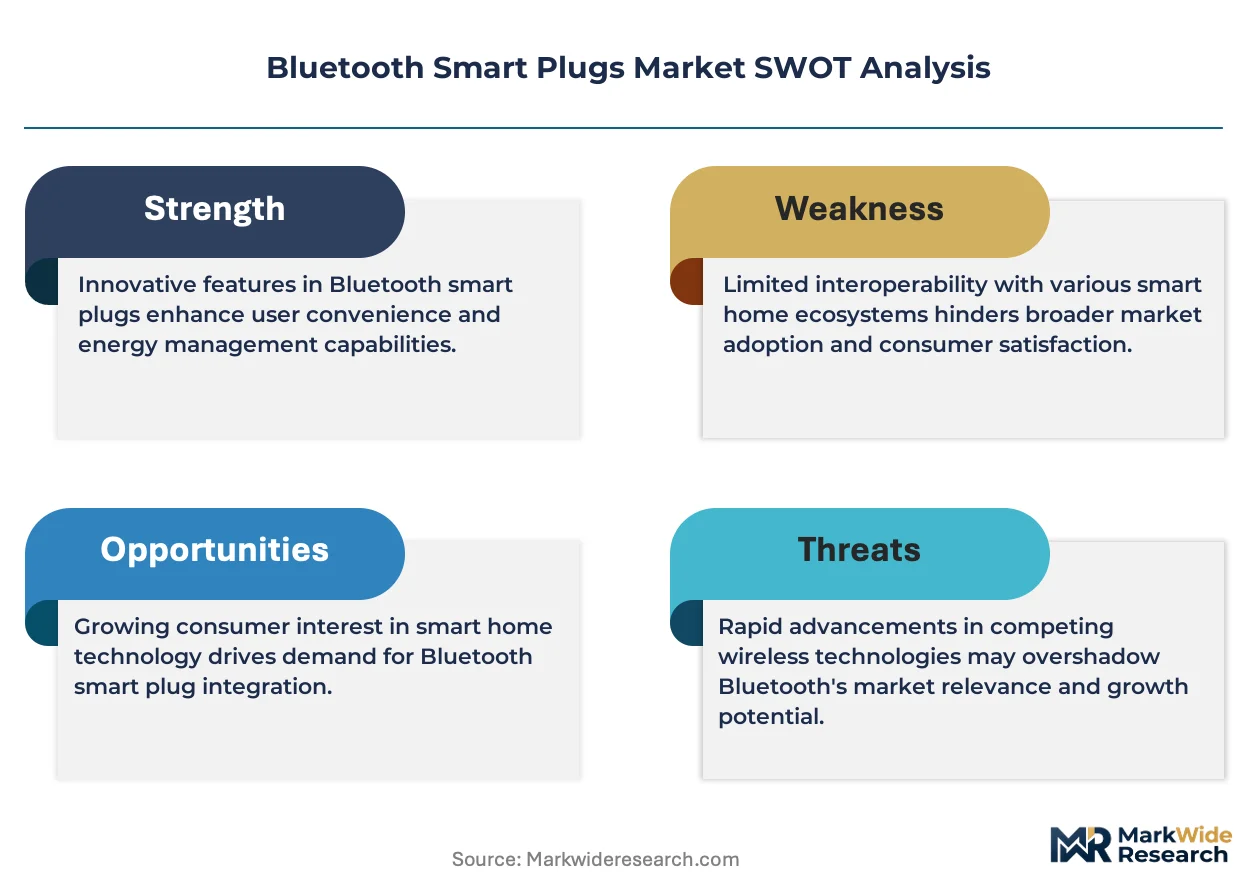
The EU Green Deal's standby power mandates are forcing relay redesigns and sleep-state engineering changes across the Bluetooth smart plug supply base, compressing margins for manufacturers unable to absorb certification costs.
Growth Catalysts
- Utility Rebate Programs:Subsidized connected home energy management in Germany, China, and the United States accelerates residential retrofit adoption.
- Ecodesign Regulation:The EU's tightening idle-state power limits compel manufacturers to invest in efficient Bluetooth module engineering, creating technical differentiation.
- Hospitality Energy Retrofits:Hotel chains deploy plug-level control systems as alternatives to property-wide rewiring, opening a structural demand vertical.
Market Restraints
- Relay Component Concentration:Specialty electromechanical relay supply clusters in East Asian manufacturing hubs, exposing procurement to single-source risk.
- Polycarbonate Input Volatility:Engineering resin price swings directly impact housing cost structures for high-amperage rated units.
- Wi-Fi Mesh Substitution:Lower-latency Wi-Fi 6E smart plugs threaten Bluetooth's hub-free positioning in whole-home automation deployments.
Strategic Opportunities
- Outdoor Weatherproofing Premium:GFCI-integrated exterior models command expanded margin pools in North American residential construction.
- Matter Protocol Convergence:Thread-over-BLE interoperability is converging with existing chipset architectures to unlock cross-platform retail placement.
- India Smart City Mandates:Municipal energy monitoring requirements in tier-1 Indian cities create bulk procurement channels for connected plug infrastructure.
Industry Challenges
- Firmware Security Certification:Evolving cybersecurity labeling requirements from FCC, CE marking authorities, and China's SRRC extend test-budget allocation timelines.
- Legacy Electrical Infrastructure Integration:Retrofit compatibility with aging residential wiring standards in established housing stocks complicates installation support costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bluetooth Smart Plugs Market |
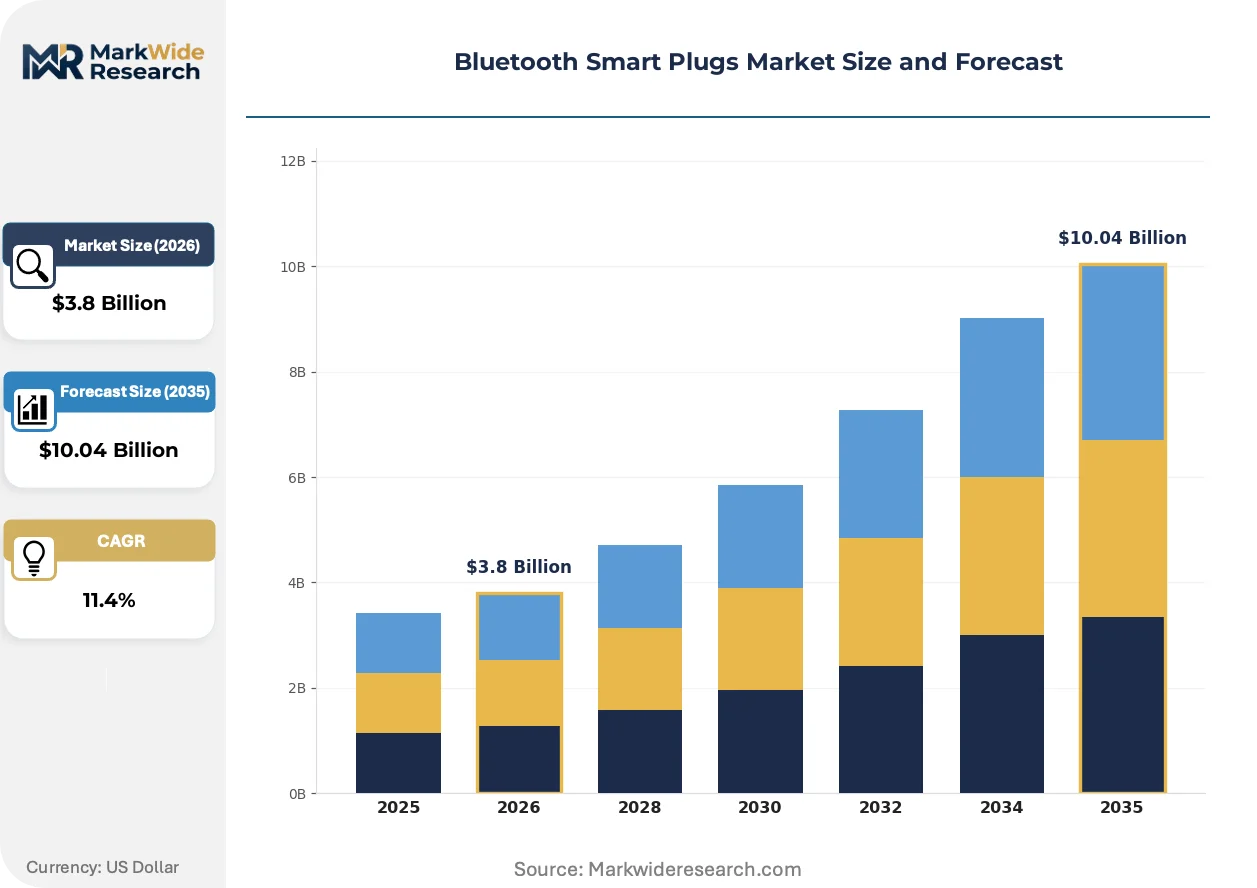
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Plugs, Outdoor Plugs, USB Plugs, Smart Power Strips End User: Residential, Commercial, Industrial, Hospitality Connectivity: Wi-Fi, Zigbee, Z-Wave, Others Installation Type: Smart Home Integration, Standalone, Retrofit, Panel-Mounted |
| Companies Covered | Belkin International Inc., TP-Link Technologies Co. Ltd., D-Link Corp., Leviton Manufacturing Co. Inc., Etekcity Corporation, EDIMAX Technology Co. Ltd., Panasonic Corporation, Insteon, SDI Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bluetooth Smart Plugs Market Emerging Trajectories
Active engineering focus centers on protocol interoperability, materials thermal performance, and regulatory-driven power efficiency as the three vectors reshaping competitive positioning in connected plug hardware.
Matter-over-Thread implementation is converging with existing BLE 5.3 silicon to enable cross-ecosystem compatibility without dedicated bridge hardware. Smart home integrators and retail buyers are prioritizing multi-platform certification as a procurement filter. This convergence is compressing market share for single-protocol legacy architectures that lack interoperability credentials.
CE marking under the EU Radio Equipment Directive now mandates explicit cybersecurity documentation for firmware update mechanisms. Manufacturers must engineer local data storage and over-the-air patch pipelines as compliance features rather than optional add-ons. German and French national regulators are advancing the strictest implementation timelines, forcing earliest design lock for products targeting EU27 distribution.
Channel disintermediation through direct-to-consumer e-commerce platforms is displacing traditional home improvement retail for budget-tier USB-integrated models. E-commerce analytics enable rapid feature iteration based on review sentiment, compressing traditional product development cycles. This shift is most pronounced in North American and Chinese consumer segments where platform logistics infrastructure supports same-day fulfillment expectations.
Bluetooth Smart Plugs Market Segmentation
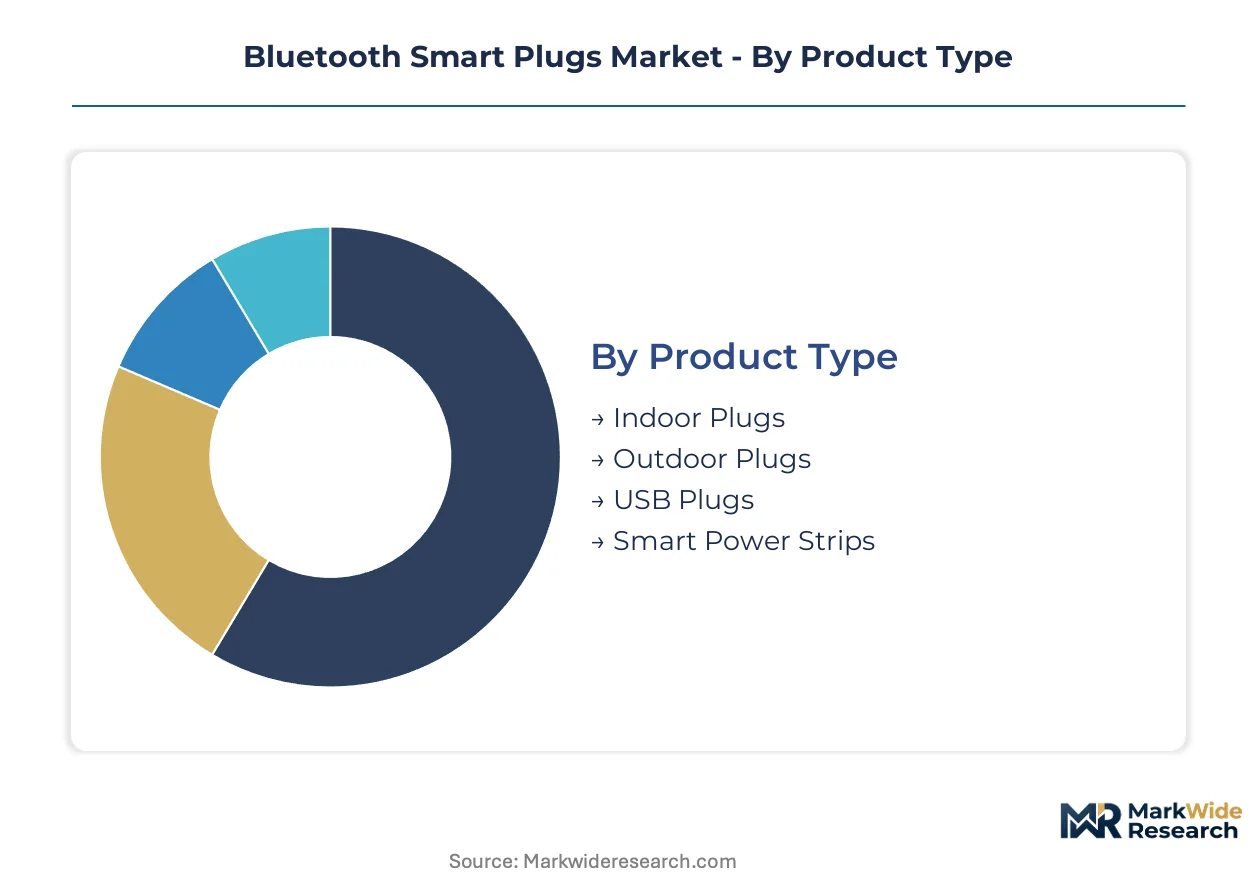
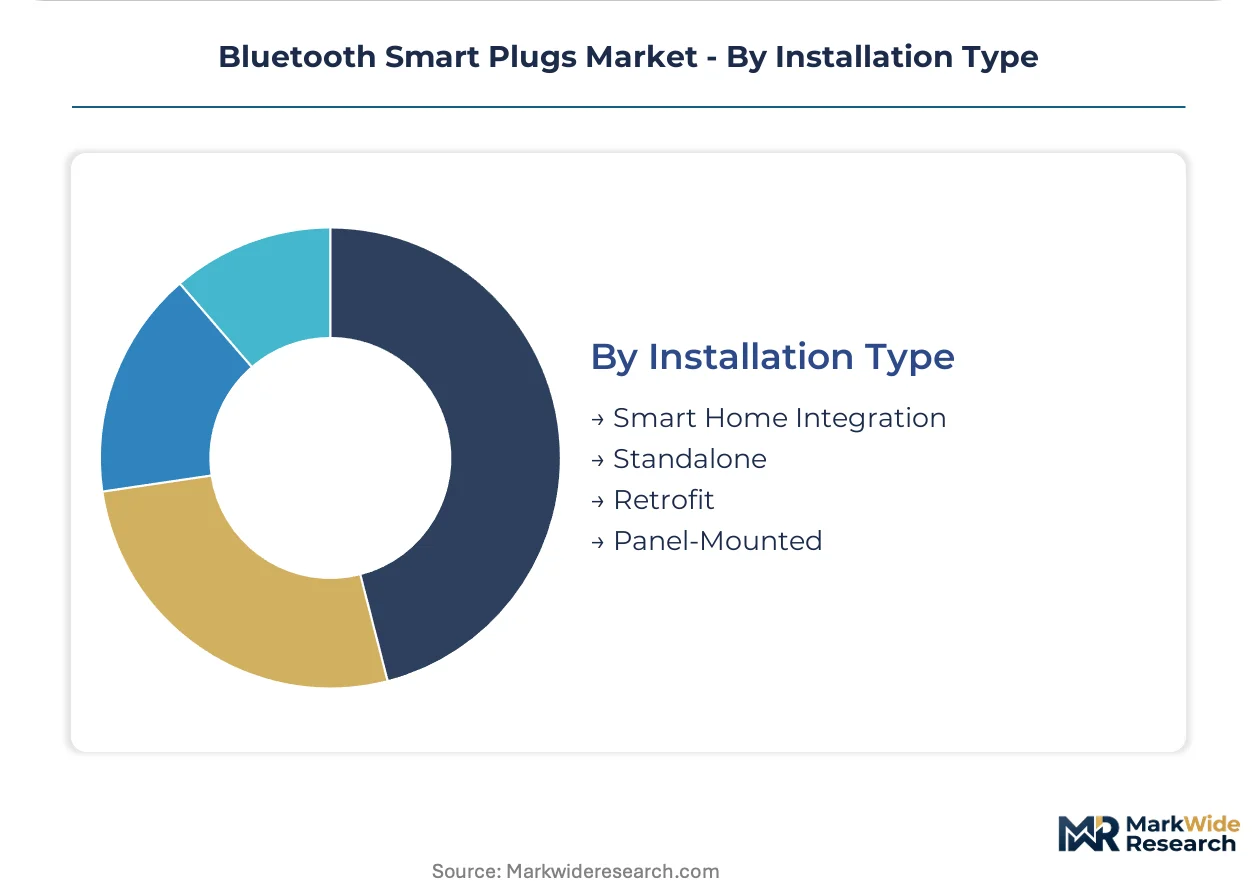
Bluetooth smart plug manufacturers configure product portfolios across four structural dimensions that determine pricing power, certification burden, and channel access. Each segmentation axis carries distinct margin profiles and technical requirements that shape supplier positioning.
Product Type:
Standardization dominates at the low end while weatherproofing and multi-outlet density drive customization premiums.
- Indoor Plugs:ABS or polycarbonate housings with 10-15A relay ratings constitute the volume base. Demand concentrates in Germany and the United States where utility rebate programs subsidize residential energy monitoring retrofits, though Wi-Fi mesh substitution threatens Bluetooth's hub-free positioning.
- Outdoor Plugs:GFCI-integrated weatherproof enclosures with IP65+ ratings command expanded margin pools in North American residential construction. The segment benefits from NEC 2023 outdoor receptacle mandates that accelerate replacement cycles.
- USB Plugs:Integrated 5V/2.4A charging ports with Type-A or Type-C outputs target bedside and desk applications.
- Smart Power Strips:Multi-outlet density with individual socket control via BLE mesh networking serves entertainment centers and home offices.
Most installed capacity flows through Indoor Plugs. Expansion is steepest in Outdoor Plugs.
End User:
Margin architecture inverts across this category: low-unit-value residential volume subsidizes high-contract-value hospitality and industrial deployments.
- Residential:Smartphone-scheduled lamp and appliance automation drives unit economics through e-commerce direct-to-consumer channels. FCC Part 15 emissions compliance and standby power engineering under EU Ecodesign dominate product development costs.
- Hospitality:Hotel chains deploy plug-level control as retrofit alternatives to property-wide rewiring, with property management system integration requirements. The segment shows structural acceleration as energy-as-a-service contracts proliferate.
- Commercial:Office building sub-metering and after-hours equipment scheduling demand enterprise-grade firmware security certification.
- Industrial:Heavy-duty 20A+ ratings with industrial relay specifications serve manufacturing floor equipment monitoring.
Residential channels move the highest unit volumes. Hospitality contracts deliver the steepest expansion trajectory.
Connectivity:
Protocol selection determines hub dependency, latency tolerance, and retail shelf positioning against Wi-Fi native alternatives.
- Wi-Fi:Direct router connectivity eliminates hub hardware but increases standby power draw and complicates FCC Part 15 certification scope.
- Zigbee:Mesh networking with sub-50ms latency supports whole-home automation through compatible hubs.
- Z-Wave:Sub-GHz frequency operation reduces interference in dense RF environments for security-focused installations.
- Others:Thread-over-BLE and proprietary protocols serve Matter convergence roadmaps and white-label OEM arrangements.
BLE-native architectures retain cost advantage in standalone deployments. Matter protocol convergence is gaining share fastest.
Installation Type:
Channel economics bifurcate between consumer self-install and professional integration with recurring service revenue potential.
- Smart Home Integration:Pre-wired new construction with centralized panel coordination and whole-home automation programming.
- Standalone:Hub-free BLE operation with out-of-box smartphone pairing dominates e-commerce fulfillment.
- Retrofit:Compatibility with aging residential wiring standards in established housing stocks complicates installation support costs but opens the largest addressable base.
- Panel-Mounted:DIN-rail or breaker-box integration for whole-circuit monitoring in commercial and industrial electrical infrastructure.
Retrofit installations represent the dominant deployment mode. Smart Home Integration contracts are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics manufacturing corridor anchors Bluetooth smart plug production capacity, with component ecosystems extending through Dongguan and Guangzhou. Distribution networks radiate from this cluster to serve residential retrofit demand across Germany, the United States, and India.
United States
Utility rebate programs in California and Texas accelerate residential energy management adoption. FCC Part 15 emissions certification shapes product development timelines for multi-region suppliers. The Pacific Northwest corridor hosts firmware engineering clusters serving hospitality energy retrofit contracts.
Germany
EU Green Deal standby power mandates drive relay redesign investments among exporters targeting EU27 distribution. CE marking under the Radio Equipment Directive now mandates explicit cybersecurity documentation. Bavaria's industrial automation sector supplies precision electromechanical components for high-amperage rated units.
China
SRRC certification requirements and domestic smart city mandates in Shenzhen and Shanghai create dual-track regulatory compliance. MIIT oversees dual-mode chipset integration standards. The Pearl River Delta concentrates polycarbonate housing fabrication and BLE module assembly operations.
India
Municipal energy monitoring requirements in Mumbai and Delhi generate bulk procurement channels for connected plug infrastructure. BIS certification timelines extend market entry planning for foreign suppliers. Karnataka's electronics manufacturing zone attracts assembly investments targeting Middle East re-export.
Japan
METI efficiency standards for standby power influence BLE module sleep-state engineering specifications. Tokyo and Osaka metropolitan areas drive premium-tier demand for Matter protocol convergence. Chubu region semiconductor fabricators supply low-latency chipsets for sub-30ms responsiveness requirements.
Bluetooth Smart Plugs Market Vendor Landscape
Vertical integration into semiconductor sourcing dominates the current landscape as manufacturers seek cost control over BLE chipsets. The vendor base clusters into three tiers: diversified electronics conglomerates with captive component supply, networking specialists leveraging retail channel density, and budget-tier e-commerce natives competing on USB-integrated feature sets. Strategic archetypes include hub-free positioning specialists, Matter protocol early adopters, and hospitality energy-as-a-service contractors. Capacity expansion in polycarbonate housing fabrication and M&A activity targeting firmware security capabilities represent the dominant competitive vectors.
Among diversified networking equipment manufacturers, TP-Link Technologies Co. Ltd. and D-Link Corp. exemplify scale-driven archetypes with integrated supply chain control. Etekcity Corporation occupies a position within the direct-to-consumer tier, representing budget-focused specialists competing through e-commerce platform optimization. Belkin International Inc. anchors the retail-channel-dependent segment, exemplifying brand equity built through home improvement chain partnerships.
| Leading Market Players |
|---|
| Belkin International Inc. |
| TP-Link Technologies Co. Ltd. |
| D-Link Corp. |
| Leviton Manufacturing Co. Inc. |
| Etekcity Corporation |
| EDIMAX Technology Co. Ltd. |
| Panasonic Corporation |
| Insteon |
| SDI Technologies Inc. |
| Others |
Supply Flow & Price Mechanics
Firmware engineering talent concentration in Shenzhen and Dongguan creates labor-cost differentials that widen pricing-tier spreads between premium Matter-certified units and budget-tier standalone BLE models. Polycarbonate housing fabrication clusters in the Pearl River Delta feed directly into tiered cost structures, with high-amperage rated units absorbing resin price volatility while economy SKUs compress margin to maintain e-commerce positioning.
Pricing Analysis
Input-cost pass-through from polycarbonate resin and BLE chipset sourcing determines tier boundaries across the product portfolio. Three-tier pricing structure across premium, standard, and economy levels separates GFCI-integrated outdoor models with IP65+ ratings from basic indoor units and USB-integrated budget SKUs. Price differentiation hinges on certification grade—CE marking with cybersecurity documentation commands measurable premiums over baseline FCC Part 15 compliance—and volume scale, with hospitality energy-as-a-service contracts securing preferential unit economics. Pricing pressure stems from Wi-Fi 6E substitution threats in whole-home automation deployments. Residential e-commerce buyers exhibit highest price sensitivity, while hospitality procurement teams prioritize firmware security certification and property management system integration over per-unit cost.
Supply Chain Analysis
Freight cost escalation from Pearl River Delta ports to North American distribution centers compresses landed margins for bulky polycarbonate housings, incentivizing regional assembly investments. Manufacturing concentrates in China, with component ecosystems extending through Vietnam for lower-complexity assembly and Mexico for tariff-advantaged North American fulfillment. Raw material dependencies encompass polycarbonate engineering resin from petrochemical complexes, electromechanical relays from Japanese and German specialty suppliers, and BLE 5.3 chipsets from Taiwan semiconductor fabricators. Single-source vulnerability concentrates in relay component supply from East Asian electromechanical specialists. Distribution runs through direct-to-consumer e-commerce platforms for residential volumes and specialized B2B channels for hospitality energy-as-a-service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Bluetooth smart plugs market functions as a regulatory compounder, with EU Ecodesign standby power mandates and cybersecurity labeling requirements creating sustained demand for engineering-intensive retrofit solutions.
For Market Incumbents: Cement hub-free BLE positioning through Matter protocol convergence before Wi-Fi 6E mesh substitution accelerates in whole-home automation deployments. Deepen captive supply of BLE chipsets via backward integration into semiconductor sourcing partnerships, insulating margin from Taiwan foundry capacity constraints. Prioritize firmware security certification investments ahead of German and French national regulator implementation timelines, converting compliance burden into technical differentiation against budget-tier entrants lacking documentation capabilities. For New Entrants and Emerging Players: EU Green Deal standby power mandates in Germany open a window for specialized relay engineering firms to capture hospitality retrofit contracts as energy-as-a-service proliferates. White-space targets include outdoor GFCI-integrated models for North American residential construction under NEC 2023 mandates, and bulk procurement channels for municipal energy monitoring in tier-1 Indian cities. The most penetrable segment is budget-tier USB-integrated models through platform-native e-commerce optimization, leveraging rapid feature iteration based on review sentiment analytics. For Investors and Strategic Acquirers: Diversified networking equipment manufacturers are the most active acquirer in this space, seeking firmware security capabilities and Matter certification expertise to complete smart home portfolios. Long-term viability favors suppliers with demonstrated compliance engineering depth across FCC, CE marking, and SRRC jurisdictions, as regulatory fragmentation intensifies. Acquisition target archetype: mid-cap specialists with hospitality energy-as-a-service contract pipelines and captive polycarbonate housing fabrication. The signal to watch is BIS certification timeline compression in India, which would accelerate market entry planning for foreign suppliers and reward early compliance investments.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | CE marking authorities now mandate explicit cybersecurity documentation for firmware update mechanisms. |
| Backward Integration into Chipset Sourcing | Taiwan foundry capacity constraints reward captive BLE silicon supply through integrated partnerships. |
| Hospitality Energy-as-a-Service Contracting | Hotel chains deploy plug-level control as retrofit alternatives to property-wide rewiring investments. |
| Outdoor Weatherproofing Premium Capture | NEC 2023 outdoor receptacle mandates accelerate replacement cycles for GFCI-integrated IP65+ models. |
| Direct-to-Consumer Platform Optimization | E-commerce analytics enable rapid feature iteration based on review sentiment in North American markets. |
Methodological Framework
Coverage spans Germany, the United States, China, and India, with primary inputs from each regional cluster combining executive interviews with product managers at networking equipment manufacturers, procurement leads at hospitality energy service companies, regulatory affairs specialists navigating CE marking and FCC Part 15 processes, and channel partners in home improvement retail. Secondary validation draws from SEC filings of listed networking equipment suppliers, Ecodesign directive implementation documents, SRRC certification databases, and utility rebate program disclosures in California and Texas. Bottom-up unit shipment estimates triangulate against top-down market value reconstructions across the analysis window.
Rate-of-change decomposition separates volume expansion from pricing trajectory across product type, end user, connectivity protocol, and installation mode dimensions. The analytical framework models standalone BLE adoption against Matter-over-Thread convergence, hospitality retrofit penetration against residential e-commerce velocity, and indoor volume concentration against outdoor premium capture throughout the forecast period. CAGRs derive from regression analysis of historical utility rebate program correlation with shipment data, polycarbonate input cost elasticity, and regulatory milestone timing.
Revisions become necessary when standby power threshold tightening accelerates beyond current Ecodesign trajectories, when Wi-Fi 6E mesh cost curves intersect Bluetooth's hub-free positioning, or when cybersecurity labeling requirements fragment across national implementations. Forecasts reflect assumptions about relay component supply stability and polycarbonate resin price normalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Europe Cellular IoT Market
Internet of Things (IoT)
IoT in Energy Market
Internet of Things (IoT)
IoT Gateway Devices Market
Internet of Things (IoT)
North America Narrowband-Internet of Things (NB-IoT) Market
Internet of Things (IoT)
Wireless Smart Plug Market
Internet of Things (IoT)
Global Narrowband IoT Market
Internet of Things (IoT)
Qatar Internet of Things (IoT) Market
Internet of Things (IoT)
Marine Internet of Things Market
Internet of Things (IoT)
Enterprise IoT Market
Internet of Things (IoT)
Internet of Things (IoT) in Healthcare Market
Internet of Things (IoT)
Smart Tracker Market
Internet of Things (IoT)
IoT in Manufacturing Market
Internet of Things (IoT)
Europe IoT Market
Internet of Things (IoT)
IoT Communication Protocol Market
Internet of Things (IoT)
Smart Connected Device Market
Internet of Things (IoT)
IoT Application Development Services Market