
 Smart Tracker Market | 2026-2036
Smart Tracker Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Tracker Market Intelligence
Platform licensing revenue is rewriting profitability expectations across the smart tracker value chain. Apple leverages its ecosystem control to sustain premium positioning in wearable trackers. Garmin anchors its position through specialized GPS device technology for outdoor and aviation segments. Samsung competes across multiple connectivity standards, extending its reach from consumer health monitoring to enterprise logistics applications.
A smart tracker is an electronic device that integrates radio frequency modules, motion sensors, and power management circuits to capture and transmit location, activity, or environmental data to connected systems. These devices typically operate on coin-cell or rechargeable lithium-polymer batteries with power budgets optimized for months-long standby cycles, serving industrial inventory control, personal safety assurance, and preventive health management. Wearable trackers and fitness monitors currently occupy the largest revenue pools as consumer health consciousness drives replacement cycles. GPS devices represent the fastest-expanding category as precision agriculture, fleet management, and lone-worker safety mandates broaden addressable demand. Bluetooth-enabled smart tags are maturing into a cost-driven segment where manufacturing scale determines supplier viability.
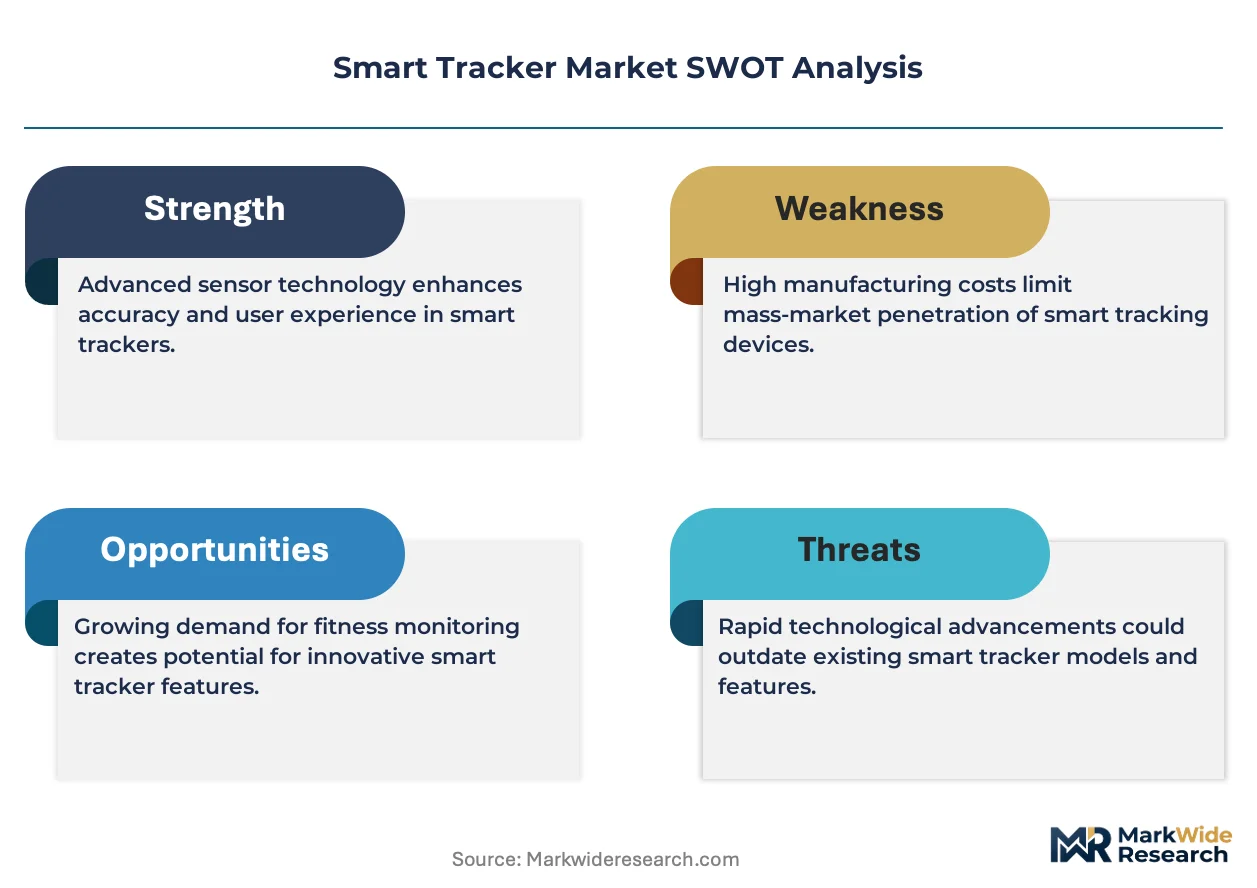
FCC Part 15 regulations in the United States govern unlicensed radio transmission for Bluetooth and Wi-Fi trackers, while CE marking under the EU Radio Equipment Directive shapes market access across European member states. REACH compliance for battery materials and RoHS restrictions on hazardous substances further constrain component sourcing and end-of-life disposal pathways. Stakeholders must monitor evolving cybersecurity certification requirements for connected health devices as FDA and EMA frameworks increasingly intersect with consumer-grade biometric monitoring.
Market Dynamics
Supply chain digitization mandates are compressing procurement cycles for enterprise-grade trackers, forcing manufacturers to integrate FCC Part 15 pre-certification into product development workflows rather than treating regulatory compliance as a terminal gate.
Growth Catalysts
- CE marking under EU Radio Equipment Directive:Harmonized standards accelerate cross-border deployment for logistics operators managing multi-country fleets. Device manufacturers gain scale economies through unified testing protocols.
- Precision agriculture adoption:GPS-enabled livestock and equipment trackers reduce field loss rates for large-scale farming operations across the United States, Australia, and Brazil. Soil monitoring integration expands sensor payload requirements.
- Lone-worker safety mandates:OSHA-aligned regulations in construction and energy sectors mandate real-time location monitoring for hazardous site personnel. This creates pull-through demand for ruggedized wearable form factors.
Market Restraints
- Lithium-polymer cell cost volatility:Raw material concentration in Chinese processing facilities exposes battery bill-of-materials to geopolitical supply disruptions. Alternative chemistries remain uncompetitive for coin-cell footprints.
- RoHS substance restrictions:Lead-free solder and restricted cadmium content complicate miniaturization of RF shielding components. REACH compliance adds documentation burden for European market entry.
- Mesh network substitution:Low-power wide-area protocols such as LoRa and Sigfox displace Bluetooth in warehouse-scale deployments where cellular backhaul costs prove prohibitive.
Strategic Opportunities
- Preventive health convergence:FDA-cleared biometric algorithms paired with consumer-grade hardware create hybrid reimbursement pathways. Insurers in Germany and Japan pilot subscription models for chronic condition monitoring.
- Aviation ground support equipment tracking:IATA operational efficiency targets drive adoption of BLE-GPS hybrid tags for baggage cart and cargo loader positioning. This vertical remains underpenetrated relative to maritime and road logistics.
- India PLI scheme for electronics manufacturing:Component assembly incentives attract module suppliers to Gujarat and Tamil Nadu clusters. Local value-add requirements favor joint ventures with domestic system integrators.
Industry Challenges
- RF engineering talent scarcity:Specialized antenna design and power optimization skills concentrate in Shenzhen, Shenzhen-adjacent Taiwanese firms, and select German automotive suppliers. Recruitment friction delays product iteration cycles.
- Multi-certification timeline compression:Simultaneous FCC, CE, and MIC Japan approvals require parallel testing workflows. Third-party laboratory capacity constraints extend time-to-revenue by two to four quarters for new entrants.
- Legacy enterprise system integration:SAP and Oracle warehouse management platforms demand custom API development for tracker data ingestion. Middleware vendors extract margin through perpetual licensing structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Tracker Market |
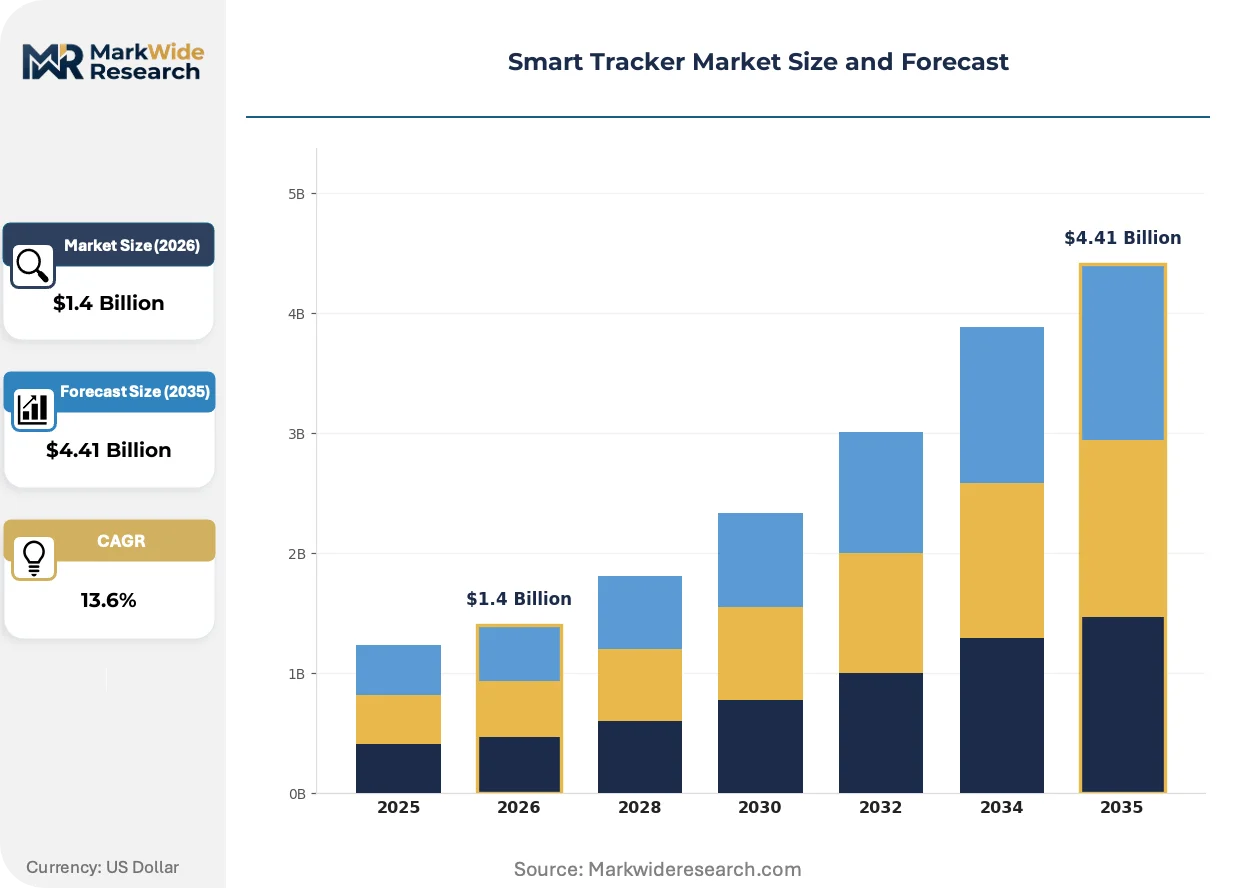
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Trackers, Fitness Monitors, Smart Tags, GPS Devices Technology: Bluetooth, Wi-Fi, NFC, GPS Application: Health Monitoring, Asset Tracking, Personal Safety, Pet Tracking End User: Consumers, Enterprises, Healthcare Providers, Logistic Firms |
| Companies Covered | Whoop, Amazfit, Garmin, Huawei, Xiaomi, Apple, Oura, Samsung, Fitbit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Tracker Market Strategic Shifts & Innovations
Hardware-software decoupling is redrawing competitive boundaries as platform licensing revenue displaces unit economics in vendor financial models. Three interconnected developments merit attention.
UWB positioning technology is migrating from smartphone accessory applications into industrial asset tracking deployments. Automotive manufacturers in Germany and South Korea adopt UWB for assembly line tool location and finished vehicle yard management. Centimeter-grade precision enables use cases where Bluetooth RSSI accuracy proves insufficient, compressing addressable market scope for legacy beacon suppliers.
EU Cybersecurity Act certification requirements are tightening for connected health devices that process biometric data. EMA framework alignment with consumer-grade monitoring creates dual jurisdiction compliance obligations for wearable tracker vendors. Manufacturers serving European markets now embed hardware security modules and encrypted firmware update channels as baseline architectural requirements.
Enterprise buyers are consolidating vendor relationships through multi-year platform subscriptions that bundle hardware, connectivity, and analytics. Industrial distributors in the United States and Germany lose attach-rate revenue as manufacturers sell direct to fleet operators and facility managers. This channel compression concentrates pricing power with ecosystem owners capable of delivering end-to-end solutions.
Smart Tracker Market Segmentation
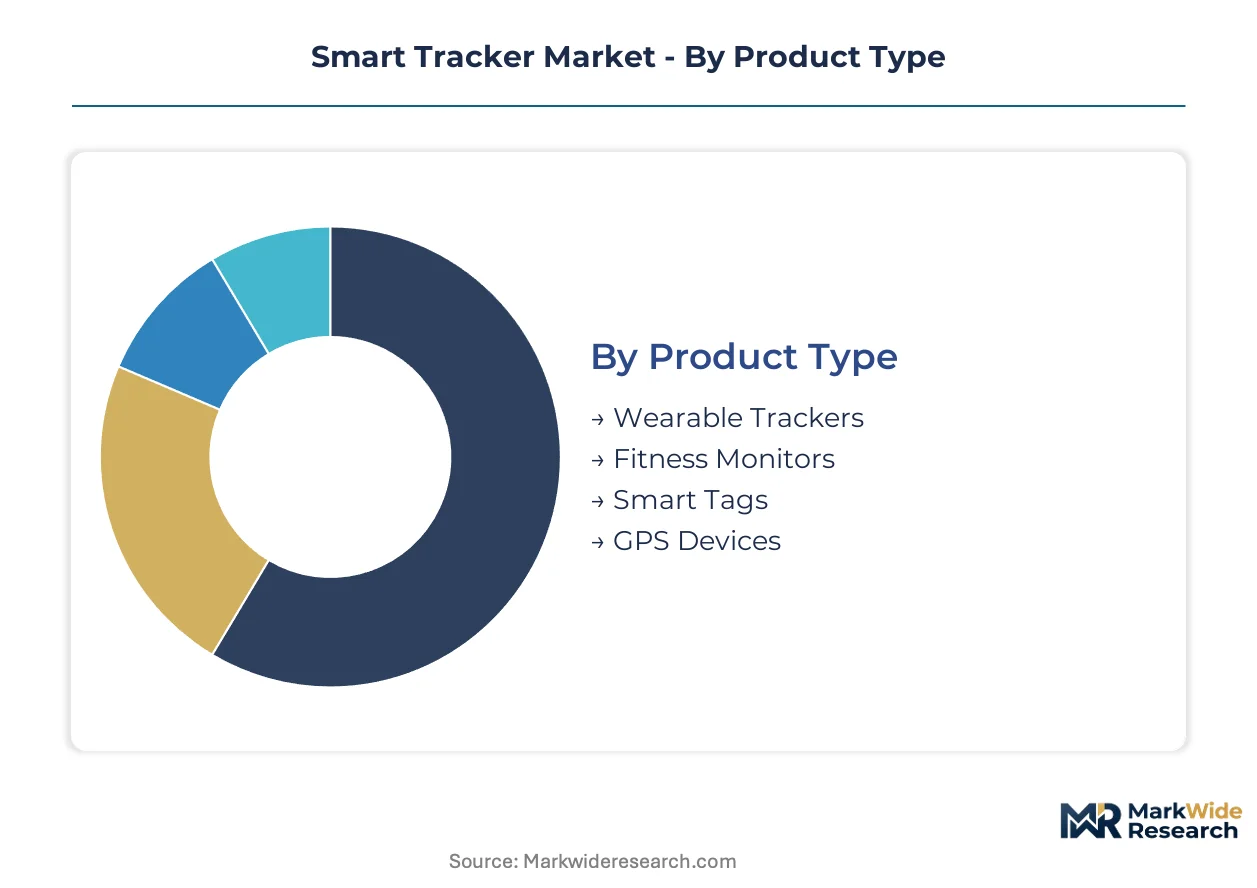
Segmentation in smart trackers reveals divergent replacement rhythms and margin structures across form factors and connectivity protocols. Procurement cycles compress in consumer wearables while enterprise asset tags extend deployment horizons through multi-year platform subscriptions.
Product Type:
Wearable trackers and fitness monitors turn inventory fastest through annual consumer upgrade cycles, whereas GPS-enabled industrial tags operate on three-to-five-year replacement schedules tied to fleet refresh timelines.
- Wearable Trackers:Wrist-worn devices integrate photoplethysmography sensors, accelerometers, and Bluetooth Low Energy modules for continuous biometric streaming. Demand concentrates in the United States and Germany where employer wellness subsidies offset consumer out-of-pocket costs. Battery life limitations and aesthetic obsolescence drive eighteen-month average replacement.
- GPS Devices:Ruggedized units combine multi-constellation satellite receivers with cellular modems for real-time position reporting in remote environments. Precision agriculture operations across Australia and Brazil deploy livestock and equipment variants to reduce field loss rates. Lone-worker safety mandates in energy and construction sectors accelerate enterprise procurement.
- Fitness Monitors:Chest straps and clip-on podometers prioritize heart rate accuracy over full-featured smartwatch functionality. Gym chains and corporate wellness programs in Japan purchase bulk quantities for member engagement initiatives.
- Smart Tags:Coin-cell powered BLE beacons enable proximity-based item location through smartphone mesh networks. Manufacturing scale in Shenzhen and Ho Chi Minh City determines supplier viability in this cost-driven segment.
Wearable trackers anchor the volume base while GPS devices gain share at the steepest rate.
Technology:
Cost tiers separate licensed spectrum protocols from unlicensed alternatives, with cellular GPS modules commanding five-to-ten-fold premiums over Bluetooth silicon at equivalent production volumes.
- Bluetooth:BLE 5.3 chipsets enable direction-finding and mesh networking at sub-dollar bill-of-materials for consumer tags. FCC Part 15 pre-certification requirements compress development timelines for vendors targeting United States retail channels.
- GPS:Multi-band receivers incorporating Galileo and BeiDou constellations deliver meter-grade accuracy for agricultural and aviation ground support applications. German automotive manufacturers adopt UWB-GPS hybrids for assembly line tool tracking.
- Wi-Fi:802.11ax-enabled trackers leverage existing enterprise infrastructure for indoor positioning without dedicated beacon deployment. Hospital systems in the United States prioritize Wi-Fi for patient and equipment location where cellular dead zones persist.
- NFC:Passive 13.56MHz tags require no onboard power, limiting functionality to tap-to-identify use cases. Pharmaceutical cold chain verification in the European Union drives batch-level authentication demand.
Bluetooth silicon dominates unit shipments while GPS modules capture the highest average selling prices.
Application:
Customer type splits the market between reimbursed healthcare endpoints and self-funded consumer purchases, with divergent regulatory pathways shaping product development priorities.
- Health Monitoring:FDA-cleared biometric algorithms enable hybrid reimbursement models when paired with consumer-grade hardware. German and Japanese insurers pilot subscription frameworks for chronic condition management.
- Asset Tracking:Enterprise mandates for supply chain digitization compress procurement cycles for fleet and warehouse deployments. SAP and Oracle integration requirements favor vendors with pre-built middleware connectors.
- Personal Safety:Ruggedized wearables with panic buttons and fall detection address OSHA-aligned lone-worker regulations. Construction and energy sector procurement concentrates in the United States and Gulf state infrastructure projects.
- Pet Tracking:GPS-LTE collars with geofencing capabilities target companion animal owners in suburban United States markets. Subscription revenue models offset hardware margin compression.
Health monitoring commands premium pricing while asset tracking scales through enterprise platform consolidation.
End User:
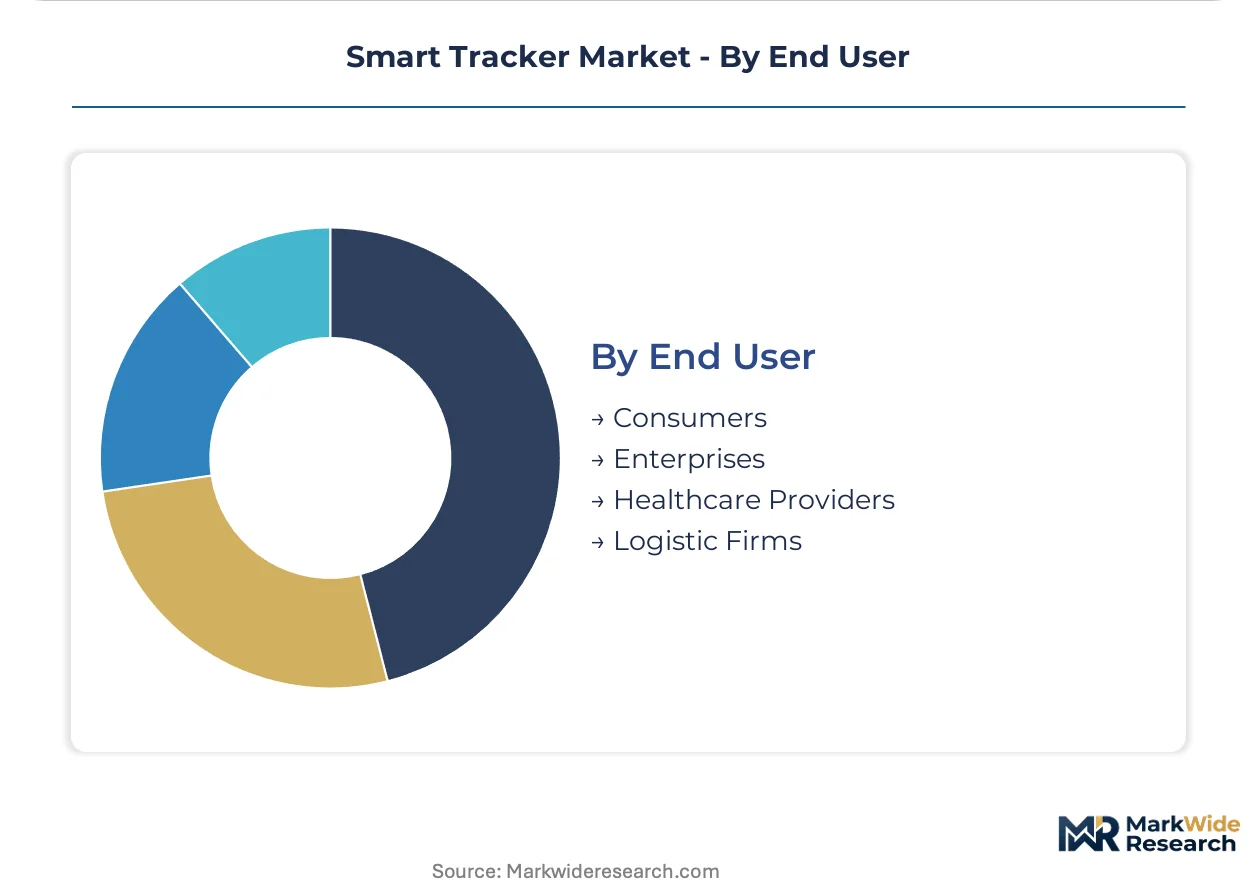
Volume concentration versus margin extraction varies sharply across buyer categories, with direct-to-consumer channels ceding ground to institutional procurement.
- Consumers:Individual purchasers drive replacement cycles through aesthetic and feature upgrades. Amazon and direct-to-consumer brands capture attach-rate revenue lost by traditional electronics retailers.
- Enterprises:Fleet operators and facility managers consolidate vendor relationships through multi-year platform subscriptions. Industrial distributors in Germany and the United States lose margin to manufacturer-direct sales motions.
- Healthcare Providers:Hospitals and clinics demand FDA-cleared devices with encrypted data transmission for patient monitoring. EMA cybersecurity certification requirements add compliance burden for European market entry.
- Logistic Firms:Third-party logistics operators deploy hybrid BLE-GPS tags for cross-dock visibility and last-mile proof-of-delivery. IATA operational efficiency targets drive aviation ground support equipment tracking adoption.
Consumer volumes remain largest in unit terms while healthcare providers and logistic firms expand fastest through institutional procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in Germany and the United States absorb premium pricing for certified industrial trackers, while consumers in India and Brazil drive volume through cost-optimized wearable segments. This elasticity divide shapes regional deployment strategies and certification priorities.
United States
Employer wellness subsidies accelerate wearable tracker replacement cycles, with corporate procurement offsetting consumer out-of-pocket costs. FCC Part 15 regulations govern Bluetooth and Wi-Fi device certification, compressing development timelines for retail-bound vendors. Silicon Valley and Austin clusters concentrate RF engineering talent for antenna optimization and power management circuits.
Germany
Precision agriculture operations deploy GPS-enabled livestock and equipment trackers to reduce field loss rates across large-scale farming cooperatives. CE marking under the EU Radio Equipment Directive harmonizes cross-border deployment standards for logistics operators managing multi-country fleets. Bavarian automotive manufacturers adopt UWB-GPS hybrid tags for assembly line tool location and finished vehicle yard management.
China
Shenzhen manufacturing ecosystems determine supplier viability in cost-driven Bluetooth beacon segments through production scale advantages. MIIT radio transmission licensing and GB standards compliance shape domestic market access requirements for cellular-enabled trackers. Pearl River Delta clusters concentrate specialized antenna design capabilities and lithium-polymer battery assembly capacity.
Japan
Corporate wellness programs and insurer pilot subscription models drive demand for chronic condition monitoring devices with biometric accuracy prioritization. METI industrial standards and PMDA framework alignment create dual jurisdiction compliance obligations for connected health devices. Tokyo and Osaka metropolitan areas anchor distribution infrastructure for enterprise fleet deployments.
India
PLI scheme incentives for electronics manufacturing attract module suppliers to Gujarat and Tamil Nadu assembly clusters with local value-add requirements favoring joint ventures. TRAI spectrum allocation for IoT protocols shapes connectivity cost structures for asset tracking deployments. Bangalore and Hyderabad technology corridors concentrate system integration capabilities for SAP and Oracle warehouse management platform connectors.
Smart Tracker Market Key Industry Players
Ecosystem-anchored technology conglomerates and specialized positioning equipment manufacturers split the market between platform licensing revenue models and hardware-centric profitability. The vendor base concentrates around three strategic archetypes: consumer electronics ecosystems leveraging cross-device integration, industrial GPS specialists serving precision agriculture and aviation verticals, and component-scale suppliers competing on manufacturing efficiency. Dominant competitive moves include direct-to-enterprise sales motions that bypass industrial distributors, and hardware-software decoupling through multi-year platform subscription bundling.
Within the ecosystem-anchored tier, Apple and Samsung exemplify platform control strategies that extend from consumer health monitoring into enterprise logistics applications. Garmin occupies a specialized position serving outdoor recreation and aviation segments through purpose-built GPS device technology. These three companies represent divergent approaches to connectivity standard competition, ecosystem lock-in, and vertical market depth.
| Leading Market Players |
|---|
| Whoop |
| Amazfit |
| Garmin |
| Huawei |
| Xiaomi |
| Apple |
| Oura |
| Samsung |
| Fitbit |
| Others |
Cost & Logistics Intelligence
Shenzhen lithium-polymer battery assembly clusters anchor upstream cost structures, concentrating margin extraction in platform licensing tiers where subscription bundling displaces unit economics. Component-scale suppliers in the Pearl River Delta feed manufacturing ecosystems that determine viability in cost-driven Bluetooth beacon segments.
Pricing Analysis
Platform subscription revenue streams now drive lifetime value capture across the smart tracker value chain. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared biometric devices from consumer-grade wearables and unbranded commodity tags. Certification grade under FCC Part 15 and CE marking directives creates price differentiation between pre-certified industrial units and retail-bound consumer hardware. Cost compression in economy-tier Bluetooth tags is intensifying because manufacturing scale in Ho Chi Minh City and Shenzhen erodes hardware margins. Fleet operators and facility managers show least price sensitivity, while individual consumers drive replacement cycles through aesthetic upgrades.
Supply Chain Analysis
Supply-chain finance facilities extended by Shenzhen module suppliers compress working capital cycles for downstream device assemblers. China, Taiwan, and Germany concentrate RF engineering talent and specialized antenna design capabilities. Raw material dependencies center on lithium carbonate processing, rare earth magnet supply, and multi-layer ceramic capacitor feedstock. Single-source vulnerability in Chinese lithium-polymer cell production exposes bill-of-materials to geopolitical disruption. Distribution runs through direct-to-enterprise sales motions that bypass industrial distributors in the United States and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform licensing revenue layers expand faster than hardware unit sales, transforming vendor financial models toward recurring-revenue architectures. This service-attach opportunity concentrates with ecosystem owners capable of delivering end-to-end connectivity and analytics bundles.
For Market Incumbents: Pre-empt UWB-GPS hybrid displacement by accelerating certification investment under EU Cybersecurity Act frameworks. Vertical integration into antenna design capabilities in Bavarian automotive clusters defends margin position against Shenzhen-adjacent Taiwanese specialists. Capacity addition in Gujarat and Tamil Nadu under India's PLI scheme secures supply chain optionality. For New Entrants and Emerging Players: Aviation ground support equipment tracking represents the most penetrable entry point, with IATA operational efficiency targets driving BLE-GPS hybrid adoption below saturation levels. Precision agriculture operations in Brazil and Australia offer second-tier white space where livestock and equipment variants reduce field loss rates. Direct-to-fleet-operator sales motions bypass entrenched industrial distributor relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial GPS specialists serving precision agriculture and lone-worker safety verticals. Five-to-ten year viability hinges on platform subscription attach rates outpacing hardware commoditization. Watch FDA-EMA framework convergence for connected health devices as inflection indicator for reimbursement pathway expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Subscription Bundling | Multi-year enterprise contracts with SAP and Oracle middleware connectors consolidate vendor relationships. |
| UWB-GPS Hybrid Certification | Centimeter-grade precision under EU Cybersecurity Act requirements displaces legacy Bluetooth beacon suppliers. |
| India PLI Joint Ventures | Local value-add requirements in Gujarat and Tamil Nadu favor partnerships with domestic system integrators. |
| FDA-EMA Dual Jurisdiction | Hardware security modules and encrypted firmware channels become baseline for biometric data processing. |
| Aviation Ground Support Tracking | IATA operational efficiency targets drive BLE-GPS adoption for baggage cart and cargo loader positioning. |
Research Approach
Cross-validation between FCC certification databases and EMA cybersecurity filings anchors the qualitative findings on regulatory pathway complexity. Primary interviews with RF engineering directors, enterprise fleet procurement managers, platform licensing executives, and third-party laboratory testing leads combine with secondary validation from SEC 10-K hardware revenue disclosures, MIIT radio transmission registries, and EU Radio Equipment Directive harmonized standards databases. Bottom-up triangulation across connectivity protocol shipment estimates and top-down reconciliation against platform subscription revenue pools ensures dimensional consistency.
Calibration against historical replacement cycle data and enterprise procurement compression patterns shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product form factor, connectivity protocol, certification tier, end-use application, and buyer category. CAGRs derive from fitted growth curves against observed adoption inflections in precision agriculture and lone-worker safety mandates. Forecast inputs incorporate lithium-polymer cell cost trajectories and parallel FCC-CE-MIC Japan approval timeline compression.
Macroeconomic conditions sit as an overlay; deviation in lithium raw material pricing, IoT spectrum allocation decisions, or cybersecurity certification timeline expansion would shift the trajectory. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT in Energy Market
Internet of Things (IoT)
Smart Home M2M Market
Internet of Things (IoT)
North America Internet of Things Devices Market
Internet of Things (IoT)
IoT in BFSI Market
Internet of Things (IoT)
Global IoT Managed Services Market
Internet of Things (IoT)
IoT Connected Machines Market
Internet of Things (IoT)
Location of Things Market
Internet of Things (IoT)
IoT Application Development Services Market
Internet of Things (IoT)
Global IOT Connectivity Management Platform (CMP) Market
Internet of Things (IoT)
IoT Software Engineering Market
Internet of Things (IoT)
Asia-Pacific Massive IoT Market
Internet of Things (IoT)
IoT Data Management Market
Internet of Things (IoT)
GCC Indoor LBS Market
Internet of Things (IoT)
IoT Cellular Market
Internet of Things (IoT)
Middle East and Africa IoT Node and Gateway Market
Internet of Things (IoT)
IoT Lpwans Market