
 IoT in Energy Market | 2026-2036
IoT in Energy Market Size, Share, and Industry Trends Forecast 2026-2036
IoT in Energy Market Intelligence
Edge-to-cloud orchestration is rewriting how energy IoT platforms deliver real-time analytics to grid operators. GE Vernova leverages its turbine heritage to anchor industrial IoT deployments across power generation assets. Siemens Energy differentiates through integrated digital twins that span offshore platforms and onshore facilities. Schneider Electric controls the building-to-grid interface with energy management systems that compete on protocol interoperability.
IoT in Energy encompasses sensor networks, communication protocols, and analytics platforms that monitor, control, and optimize energy production, transmission, and consumption infrastructure. These systems typically operate across sub-second latency thresholds for grid stability applications while integrating SCADA, AMI, and DERMS layers into unified architectures. Predictive maintenance and demand response solutions capture expanding margin pools as asset-intensive operators prioritize uptime over capital replacement cycles. Smart metering dominates installed base volumes, though renewable integration applications are accelerating fastest as inverter-connected solar and wind assets proliferate across distribution networks.
FERC Order 2222 in the United States, the EU Cybersecurity Act with CE marking requirements, and GB standards from China's SAMR collectively shape product certification pathways and data governance obligations for cross-border platform vendors. These frameworks force architecture decisions around data residency, encryption standards, and interoperability protocols before market access becomes viable. Stakeholders must monitor how divergent cybersecurity mandates across jurisdictions fragment platform development roadmaps and inflate compliance costs for unified product strategies.
Market Dynamics
Grid modernization mandates are forcing utilities to replace legacy SCADA architectures with edge-native IoT stacks that can process telemetry at sub-second latency thresholds. This infrastructure turnover is redistributing value capture toward software-defined control layers.
Growth Catalysts
- FERC Order 2222:US wholesale market rules now compensate aggregated distributed energy resources for grid services, creating revenue streams for IoT-enabled virtual power plants.
- Industrial predictive maintenance:German manufacturing facility managers are prioritizing vibration-monitoring sensor networks to reduce unplanned turbine downtime.
- AMI 2.0 deployments:North American utility providers are expanding smart metering infrastructure to support time-of-use pricing and demand response orchestration.
Market Restraints
- Silicon carbide supply concentration:Power electronics for grid-tied inverters depend on substrates from limited foundry capacity in East Asia.
- EU F-Gas Regulation compliance costs:Tightened emissions standards for switchgear sensors are inflating certification timelines for connected infrastructure vendors.
- Legacy protocol fragmentation:Interoperability gaps between DNP3, IEC 61850, and proprietary building automation protocols delay unified platform rollouts.
Strategic Opportunities
- Offshore wind digital twins:North Sea operators need integrated asset performance management for floating turbine platforms.
- EU Green Deal funding windows:National recovery plans in France and Italy are subsidizing building-to-grid energy management retrofits.
- LPWAN-5G convergence:Low-power wide-area networks are hybridizing with cellular slices to serve remote pipeline monitoring applications.
Industry Challenges
- Cybersecurity certification bottlenecks:CE marking under the EU Cybersecurity Act requires third-party audits that extend product launch timelines.
- OT-IT integration complexity:Utility control centers struggle to reconcile millisecond-critical operational technology stacks with cloud-native analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT in Energy Market |
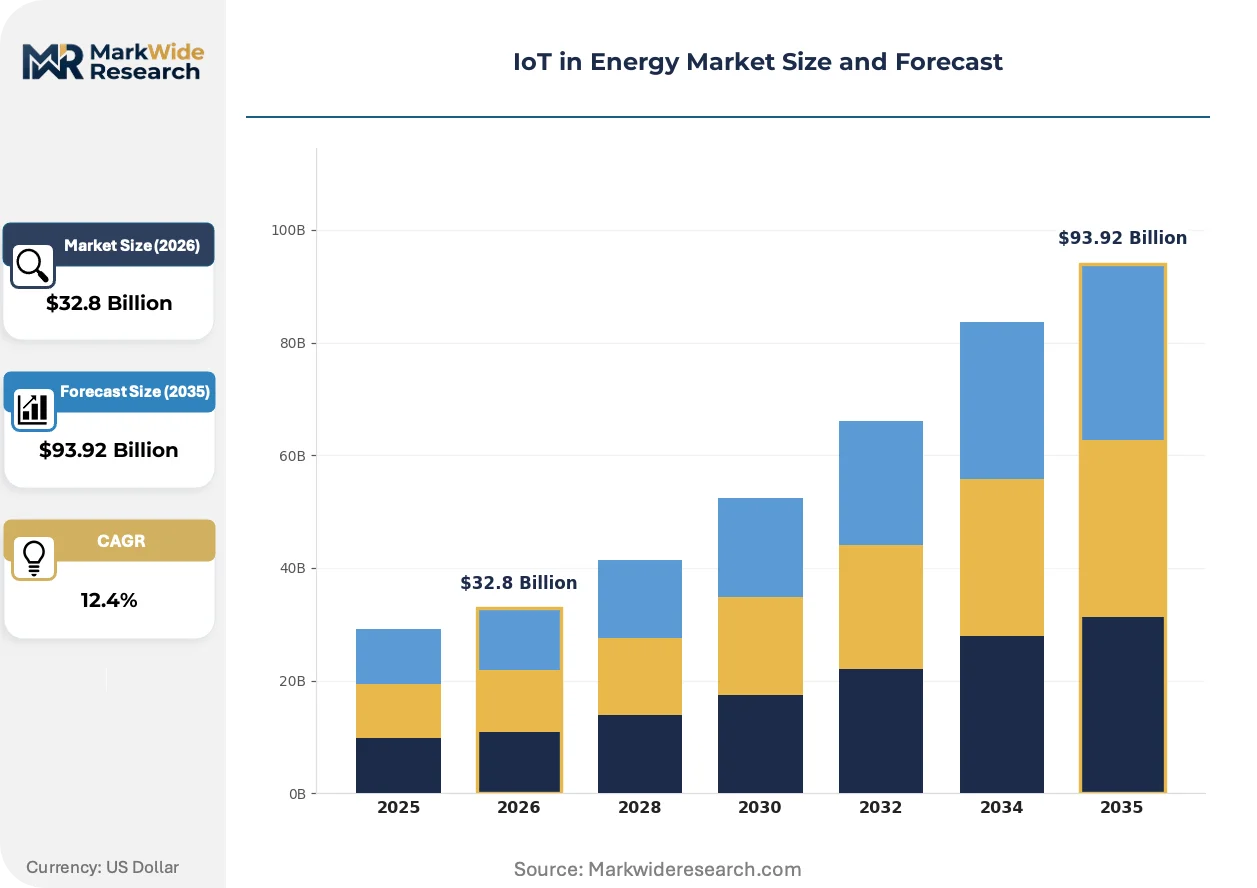
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $93.92 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Smart Metering, Asset Tracking, Remote Monitoring, Predictive Maintenance, Demand Response, Energy Management Application: Grid Automation, Load Forecasting, Renewable Integration, Fault Detection, Consumption Analytics, Power Quality Monitoring Installation: Onshore Facilities, Offshore Platforms, Substation Equipment, Transmission Lines, Distribution Networks, Microgrids End User: Utility Providers, Independent Power Producers, Equipment Manufacturers, Regulatory Bodies, Energy Traders, Facility Managers |
| Companies Covered | GE Vernova, Transition Technologies MS, GE Digital, Siemens Energy, Toshiba, Siemens, IBM, Cognizant, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT in Energy Market Strategic Shifts & Innovations
Edge-to-cloud orchestration is compressing decision loops for grid operators while regulatory fragmentation forces architecture bets on data residency and encryption standards. Three developments are reshaping competitive positioning.
Digital twin platforms are hybridizing physics-based simulation with real-time sensor feeds to optimize power generation asset performance. Offshore wind operators in the North Sea are deploying these systems at scale to reduce turbine maintenance vessel dispatches. The technology is compressing operating expenditure margins for asset-intensive operators while creating new service revenue pools for platform vendors.
The EU Cybersecurity Act's CE marking requirements are mandating third-party conformity assessments for connected energy infrastructure before market access. Industrial IoT vendors must now document secure-by-design development processes and encryption key management protocols. German and French grid operators are prioritizing certified platforms in procurement specifications, displacing uncertified alternatives from tender shortlists.
Utility procurement patterns are favoring outcome-based service contracts over capital equipment purchases for grid monitoring systems. North American municipal utilities are contracting for guaranteed uptime and predictive accuracy rather than owning sensor hardware. This shift is visible most acutely in California and Texas markets where wildfire and storm resilience mandates accelerate infrastructure refresh cycles.
IoT in Energy Market Segmentation
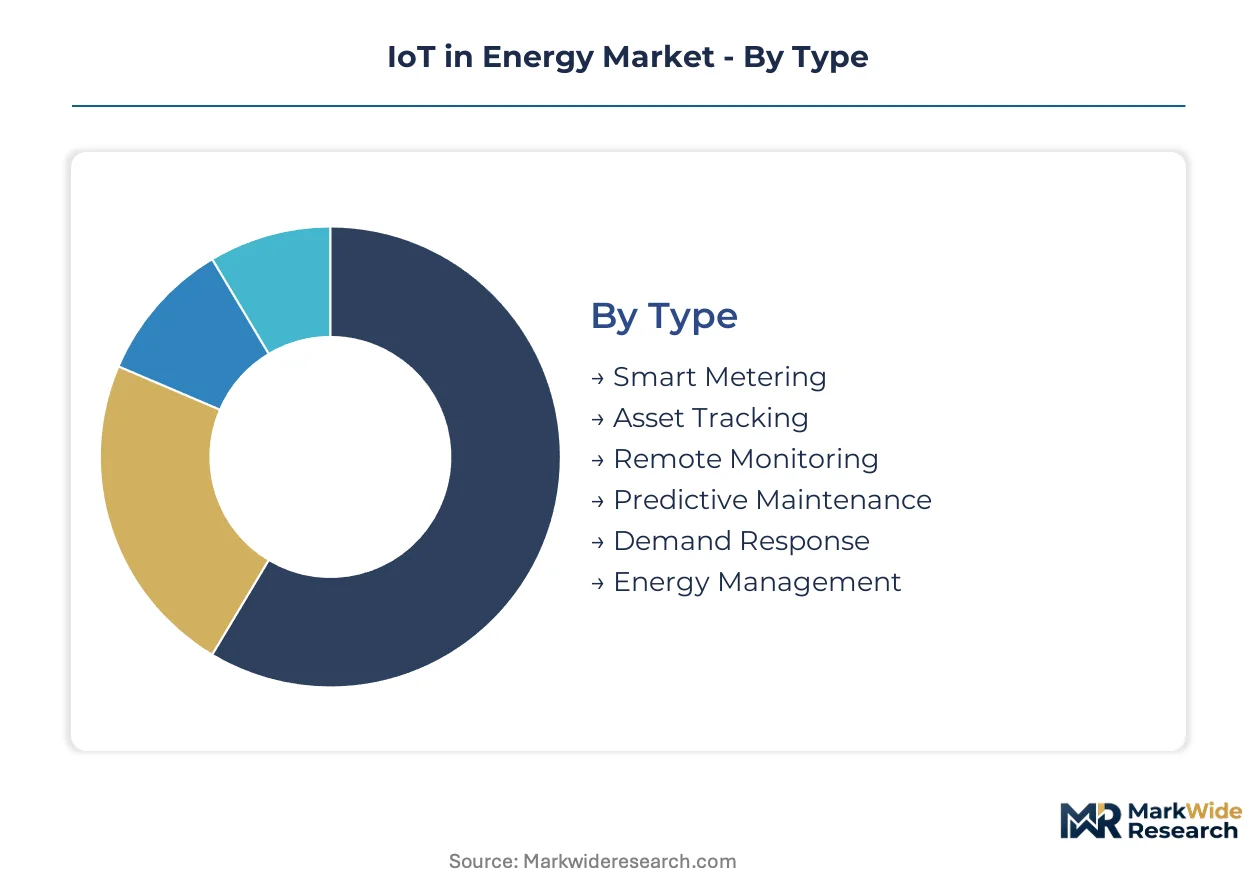
Segmentation in the IoT in Energy market reveals distinct technology maturity curves and divergent deployment economics across infrastructure layers. Understanding these partitions helps vendors align R&D roadmaps with procurement cycles that vary dramatically between regulated utilities and competitive independent power producers.
Type:
The maturity spectrum spans decades-old metering infrastructure to emerging AI-driven maintenance platforms that remain in pilot phases across most geographies.
- Smart Metering:Advanced metering infrastructure with two-way communication protocols and time-of-use billing capabilities. Demand concentrates in North American municipal utilities replacing first-generation AMR systems under grid modernization mandates; FERC Order 2222 compliance timelines accelerate procurement cycles.
- Predictive Maintenance:Vibration, thermal, and acoustic sensor networks feeding machine learning models for failure anticipation. German industrial facility managers prioritize turbine monitoring to reduce unplanned downtime in combined-cycle power plants; EU F-Gas Regulation tightens sensor certification requirements.
- Asset Tracking:GPS and RFID-enabled location monitoring for mobile generation equipment and spare parts inventory.
- Remote Monitoring:Telemetry systems for unmanned substations and pipeline compressor stations.
- Demand Response:Load curtailment orchestration platforms enabling virtual power plant aggregation.
- Energy Management:Building-to-grid optimization systems controlling HVAC and storage assets.
Smart Metering retains volume leadership; Predictive Maintenance holds the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive grid automation deployments from lightweight analytics subscriptions targeting energy traders.
- Grid Automation:SCADA replacement and feeder reconfiguration systems operating at sub-second latency thresholds. Chinese grid operators under SAMR GB standards deploy wide-area measurement systems; state-owned utility procurement favors domestic protocol stacks.
- Renewable Integration:Inverter control and forecasting platforms for solar and wind asset dispatch. North Sea offshore wind operators require floating platform telemetry; EU Green Deal recovery funding subsidizes deployment costs.
- Load Forecasting:Statistical and machine learning models predicting demand curves for generation scheduling.
- Fault Detection:Real-time disturbance identification and sectionalizing for outage isolation.
- Consumption Analytics:End-user disaggregation and efficiency benchmarking for commercial buildings.
- Power Quality Monitoring:Harmonic and sag-swell detection for industrial voltage-sensitive loads.
Grid Automation dominates capital deployment; Renewable Integration is climbing the fastest as inverter-connected assets proliferate.
Installation:
Geographic dispersion creates divergent connectivity constraints, from fiber-rich substations to satellite-dependent offshore environments.
- Offshore Platforms:Harsh-environment sensor networks for floating wind and oil-gas electrification assets. North Sea operators deploy digital twin-integrated monitoring; salt spray and vibration specifications exceed onshore equivalents.
- Distribution Networks:Pole-mounted sensors and recloser controllers spanning low-voltage feeders. US rural electric cooperatives prioritize wildfire ignition detection; California IOUs face strict vegetation contact mitigation rules.
- Onshore Facilities:Power plant and industrial site instrumentation with established maintenance access.
- Substation Equipment:Transformer and switchgear monitoring for condition-based asset replacement.
- Transmission Lines:Sag, temperature, and ice-loading sensors for dynamic line rating.
- Microgrids:Islanding detection and synchronization controls for campus and military installations.
Distribution Networks retain volume leadership; Offshore Platforms hold the steepest expansion curve.
End User:
Customer type fragmentation splits procurement between regulated rate-base recovery and competitive merchant revenue streams.
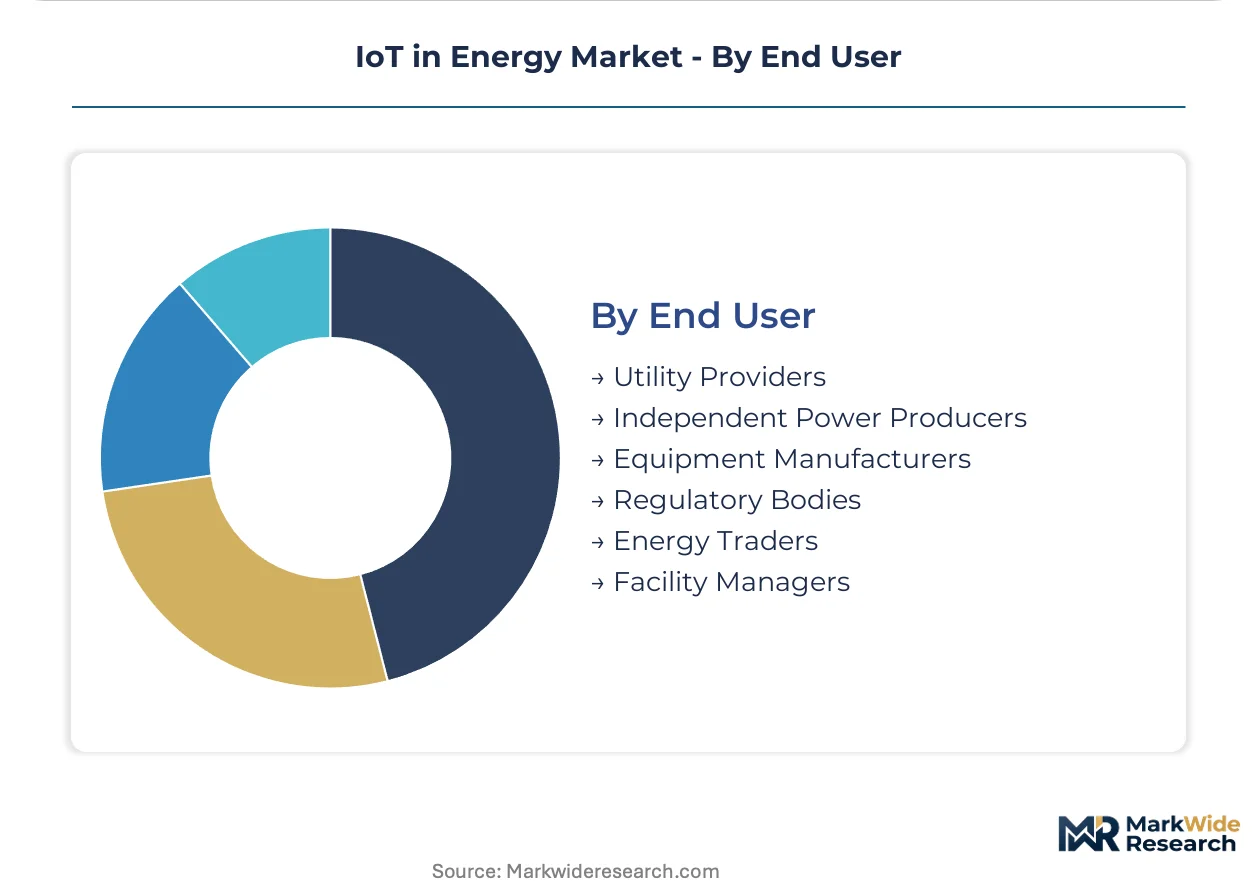
- Utility Providers:Vertically integrated and distribution-only entities with rate-case-driven technology adoption. US investor-owned utilities amortize AMI 2.0 through regulatory asset mechanisms; cybersecurity audit requirements extend procurement timelines.
- Independent Power Producers:Competitive generators optimizing merchant margins through asset performance management. Texas ERCOT market participants deploy fast-frequency response IoT to capture ancillary service revenues; real-time price exposure drives automation investment.
- Equipment Manufacturers:OEMs embedding connectivity into turbines, inverters, and switchgear.
- Regulatory Bodies:Grid operators and market monitors acquiring visibility platforms for compliance enforcement.
- Energy Traders:Speculative and hedging entities requiring demand signal intelligence.
- Facility Managers:Commercial and industrial building operators procuring behind-the-meter optimization.
Utility Providers retain volume leadership; Independent Power Producers are expanding most quickly as merchant markets deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a significant trade surplus in energy IoT platforms, exporting edge-native grid software to European and Asian utilities while importing specialized sensor hardware from East Asian foundries. Germany and China represent the largest import markets for US-origin virtual power plant orchestration systems. Cross-border data governance requirements under the EU Cybersecurity Act and China's SAMR GB standards increasingly determine where vendors localize platform development.
United States
Texas ERCOT market participants deploy fast-frequency response IoT to capture ancillary service revenues from wholesale price volatility. FERC Order 2222 mandates compensation for aggregated distributed energy resources, accelerating virtual power plant procurement timelines. California investor-owned utilities prioritize wildfire ignition detection sensors under strict vegetation contact mitigation rules from state regulators.
Germany
Industrial facility managers in the Ruhr and Bavaria prioritize vibration-monitoring sensor networks to reduce unplanned turbine downtime in combined-cycle power plants. The EU F-Gas Regulation tightens emissions standards for switchgear sensors, extending certification timelines for connected infrastructure vendors. North Sea offshore wind operators around Hamburg and Bremen deploy digital twin-integrated monitoring for floating turbine platforms.
China
State-owned grid operators under SAMR GB standards deploy wide-area measurement systems with domestic protocol stack preferences. Provincial utilities in Jiangsu and Guangdong prioritize AMI 2.0 infrastructure to support time-of-use pricing and demand response orchestration. The country's dual carbon goals accelerate renewable integration investments across inverter-connected solar and wind assets.
United Kingdom
Distribution network operators in London and the Southeast prioritize OT-IT integration for substation automation under Ofgem's RIIO price control framework. The UK regulator mandates cybersecurity resilience standards that align with EU CE marking requirements post-Brexit. Scottish offshore wind clusters around Aberdeen require harsh-environment sensor specifications for floating platform telemetry.
India
State electricity boards in Maharashtra and Gujarat expand smart metering deployments under the national Smart Meter National Programme. The Central Electricity Authority mandates communication protocol interoperability between legacy SCADA and new IoT layers. Industrial zones around Pune and Ahmedabad prioritize energy management systems for manufacturing facility optimization.
IoT in Energy Market Key Industry Players
On the supply side, the industry is consolidating around three distinct capability clusters: industrial conglomerates with turbine heritage, pure-play software vendors with cloud-native architectures, and building automation specialists with protocol interoperability expertise. Strategic archetypes include asset-heavy OEMs embedding connectivity into generation equipment, IT services firms delivering utility transformation programs, and energy management pure-plays controlling the building-to-grid interface. Dominant competitive moves include vertical integration into silicon carbide power electronics and strategic partnerships between software platforms and hardware sensor manufacturers.
Within the industrial conglomerate tier, GE Vernova and Siemens Energy occupy positions anchored by power generation equipment heritage. Schneider Electric exemplifies the building-to-grid interface specialist archetype. IBM and Cognizant represent IT services firms delivering utility digital transformation programs. Toshiba sits within the diversified industrial electronics segment with cross-sector IoT platform capabilities.
| Leading Market Players |
|---|
| GE Vernova |
| Transition Technologies MS |
| GE Digital |
| Siemens Energy |
| Toshiba |
| Siemens |
| IBM |
| Cognizant |
| Schneider Electric |
| Others |
Cost & Logistics Intelligence
Jiangsu province's silicon carbide foundry cluster anchors power electronics supply for grid-tied inverters, concentrating upstream pricing leverage among East Asian substrate manufacturers while downstream platform vendors absorb margin compression through software value-adds.
Pricing Analysis
AMI 2.0 smart metering platforms command premium positioning over first-generation AMR systems, while predictive maintenance software subscriptions undercut capital-equipment pricing models. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales service bundling. Pricing pressure stems from EU F-Gas Regulation compliance costs inflating sensor certification timelines. Municipal utilities exhibit highest price sensitivity; offshore wind operators demonstrate lowest sensitivity due to vessel dispatch cost avoidance.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for IoT gateway hardware. Manufacturing concentrates in China, Taiwan, and Vietnam for sensor assemblies and communication modules. Silicon carbide substrates, MEMS accelerometers, and LPWAN chipsets constitute critical input dependencies. Single-source vulnerability persists for wide-bandgap semiconductor foundry capacity. Distribution runs through systems integrators and EPC contractors rather than direct vendor-to-utility channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across protocol standards and regulatory jurisdictions creates niche entry points for specialized vendors as utility procurement shifts from capital equipment to outcome-based service contracts.
For Market Incumbents: Pre-empt pure-play software vendors by embedding edge-native analytics into existing turbine and switchgear installed bases. Threatened by cloud-native platforms unencumbered by legacy SCADA integration burdens, incumbents should prioritize CE marking investment under EU Cybersecurity Act to maintain tender eligibility. Channel control through certified systems integrator networks represents the priority defensive lever. For New Entrants and Emerging Players: Build out virtual power plant orchestration capabilities targeting Texas ERCOT market participants capturing ancillary service revenues from FERC Order 2222 compliance. North American rural electric cooperatives present the most penetrable utility segment given wildfire resilience mandates accelerating procurement cycles. Go-to-market execution should emphasize guaranteed uptime contracting rather than hardware ownership transfer. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-defined control layer vendors with utility outcome-based contracts. Long-term viability favors platforms with demonstrated interoperability across DNP3, IEC 61850, and building automation protocols. Acquisition target archetype: mid-scale predictive maintenance pure-plays with North Sea offshore wind reference installations. Signal to watch: procurement specification language shifting from equipment specifications to guaranteed predictive accuracy metrics.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies SCADA, AMI, and DERMS layers for FERC Order 2222 compliance. |
| CE Marking Investment | Secures tender eligibility under EU Cybersecurity Act for connected infrastructure. |
| Outcome-Based Contracting | Aligns revenue streams with utility uptime guarantees rather than hardware sales. |
| Silicon Carbide Supply Agreement | Captures substrate allocation from Jiangsu foundry capacity for inverter production. |
| Digital Twin Development | Reduces North Sea offshore wind maintenance vessel dispatches through physics-based simulation. |
Research Approach
The analysis maps smart metering infrastructure, predictive maintenance platforms, grid automation systems, and renewable integration software, each validated through utility planning officers, IPP project developers, EPC contractors, and grid operators. Primary fieldwork combined structured interviews with secondary validation against EIA data, IEA reports, FERC filings, and project development databases. Bottom-up segment sizing triangulated with top-down market reconstruction.
Assumptions held fixed include regulatory enforcement timelines for EU F-Gas Regulation and SAMR GB standards, while technology adoption curves and merchant market depth were varied across scenarios. The analytical framework models deployment by fuel source, generation capacity tier, project scale, and regional grid type across the analysis window. CAGRs derive from segment-level growth trajectory synthesis incorporating AMI 2.0 replacement cycles and offshore wind capacity additions.
The forecast holds incumbent behavior within observed patterns; aggressive platform integration moves by industrial conglomerates or pure-play software vendors would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Global IoT Devices Market
Internet of Things (IoT)
US Smart Thermostat Market
Internet of Things (IoT)
Qatar Internet of Things (IoT) Market
Internet of Things (IoT)
Global 5G Industrial IOT Market
Internet of Things (IoT)
Airport Internet of Things Market
Internet of Things (IoT)
Smart Pool Systems Market
Internet of Things (IoT)
Global IoT in Warehouse Market
Internet of Things (IoT)
IoT for Cold Chain Monitoring Market
Internet of Things (IoT)
North America Internet of Things Devices Market
Internet of Things (IoT)
Massive Machine Type Communication Market
Internet of Things (IoT)
Global Pervasive Computing Technology Market
Internet of Things (IoT)
Global Agile IoT Market
Internet of Things (IoT)
Europe IoT in Smart Cities Market
Internet of Things (IoT)
Global Internet of Things (IoT) Defence Market
Internet of Things (IoT)
UK IoT Software Market
Internet of Things (IoT)
Consumer IoT Market