
 IoT in Manufacturing Market | 2026-2036
IoT in Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
IoT in Manufacturing Market Analysis
Germany's industrial corridor is fragmenting as new IoT capacity spreads across Eastern European manufacturing zones. Siemens leverages deep vertical integration in digital twin platforms to sustain engineering margins. Rockwell Automation competes through tight channel control across North American automotive assembly lines. IBM differentiates via AI-driven predictive maintenance software layered atop legacy SCADA infrastructure.
IoT in Manufacturing denotes networked sensor arrays, edge computing nodes, and cloud analytics platforms that extract real-time operational intelligence from production equipment, typically communicating over protocols such as MQTT or OPC UA with sub-100-millisecond latency requirements. The architecture serves to minimize unplanned downtime, optimize throughput, and enforce traceability across multi-tier supply chains. Predictive maintenance applications capture the deepest margin pools as aerospace and heavy machinery operators pay premiums for failure-avoidance algorithms. Edge computing deployments are accelerating fastest where cloud latency threatens safety-critical control loops. Sensor networks remain the most mature layer, with commodity pressure eroding hardware margins.
The EU AI Act imposes conformity assessments on autonomous manufacturing decisions, while the Machinery Directive mandates functional safety validation for networked control systems. Germany's national regulator aligns BSI cybersecurity standards with IEC 62443 frameworks for industrial communication security. FDA scrutiny of software-as-a-medical-device is spilling into pharmaceutical manufacturing IoT deployments in the United States. Stakeholders must monitor whether emerging carbon-border adjustment mechanisms will embed IoT traceability as a compliance prerequisite for exported manufactured goods.
Market Dynamics
The EU AI Act's conformity assessment mandates for autonomous manufacturing decisions are restructuring competitive advantage around algorithmic auditability and documented safety validation, forcing vendors to rebuild engineering workflows around explainable AI architectures.
Growth Catalysts
- EU AI Act compliance mandates:The regulation's risk-based classification system for industrial AI systems is compelling manufacturers to upgrade control architectures, creating pull for validated IoT platforms with embedded audit trails.
- Predictive maintenance in aerospace:Fleet operators facing unplanned downtime penalties are deploying sensor arrays with failure-avoidance algorithms that command premium pricing over conventional scheduled maintenance.
- Ruhr industrial cluster concentration:Germany's dense ecosystem of systems integrators and component suppliers accelerates proof-of-concept cycles for smart factory deployments.
Market Restraints
- Semiconductor input volatility:Discrete sensor and edge processor supply remains concentrated among Taiwanese foundries, exposing hardware margins to foundry allocation disruptions.
- IEC 62443 implementation costs:Industrial cybersecurity certification for networked control systems demands specialized engineering labor that mid-tier manufacturers struggle to source.
- Cloud latency limitations:Safety-critical control loops in metal forming and chemical processing cannot tolerate round-trip delays above 50 milliseconds, constraining pure-cloud architectures.
Strategic Opportunities
- Eastern European manufacturing zones:Greenfield plants in Poland and the Czech Republic are skipping legacy SCADA generations entirely, adopting native IoT architectures without retrofit constraints.
- Digital twin convergence with physics simulation:Coupling real-time sensor feeds with finite element analysis enables virtual commissioning that compresses production ramp timelines.
- Carbon-border adjustment mechanisms:Emerging EU CBAM requirements for embedded emissions documentation will mandate IoT traceability as a compliance prerequisite for exported manufactured goods.
Industry Challenges
- OT-IT integration expertise scarcity:Control engineers fluent in both IEC 61131-3 ladder logic and containerized microservices architectures command compensation premiums that inflate project delivery costs.
- FDA software-as-medical-device spillover:Pharmaceutical manufacturers deploying IoT for continuous process verification face validation timelines that extend 18-24 months for systems touching regulated drug production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT in Manufacturing Market |
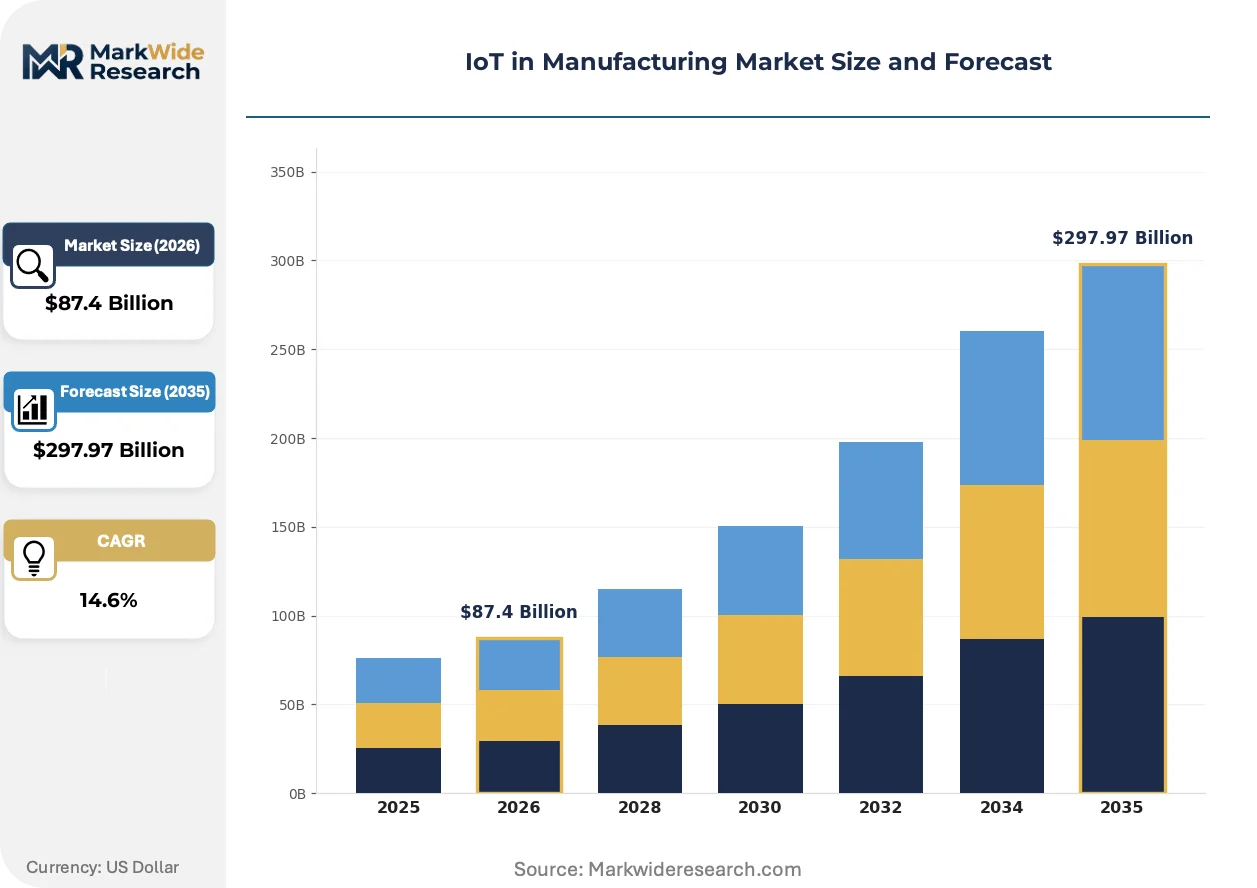
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $297.97 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Sensor Networks, Cloud Computing, Edge Computing, AI Integration Application: Predictive Maintenance, Asset Tracking, Quality Control, Supply Chain Management End User: Aerospace, Automotive Components, Electronics Assembly, Heavy Machinery Deployment: On-premises, Cloud-based, Hybrid, Distributed Systems |
| Companies Covered | Siemens, Cisco Systems, Rockwell Automation, IBM, Microsoft, SAP SE, ABB, General Electric, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT in Manufacturing Market Emerging Trajectories
Edge intelligence architectures are displacing cloud-dependent analytics in latency-sensitive control applications, while regulatory pressure on algorithmic transparency accelerates investment in explainable AI tooling for industrial automation.
Time-sensitive networking over standard Ethernet is migrating from proprietary fieldbus replacement to deterministic control backbone in automotive assembly lines. Tier-one suppliers in Stuttgart and Wolfsburg are piloting TSN-enabled sensor networks for synchronized motion control. The technology is migrating from niche aerospace applications to mainstream discrete manufacturing, compressing vendor margins on legacy DeviceNet and PROFIBUS hardware.
The EU Machinery Directive's 2023 update tightens functional safety validation for networked control systems with embedded AI decision modules. Industrial automation vendors must now submit updated technical files demonstrating systematic capability for safety-related software. German machinery builders exporting into regulated end-uses are front-loading conformity assessment costs, passing premiums to buyers in pharmaceutical and nuclear component sectors.
Buyer procurement for IoT platforms is consolidating around outcome-based performance contracts rather than capital equipment purchases. Automotive OEMs in Bavaria and Baden-Württemberg now specify uptime guarantees and throughput improvement targets as contract terms, shifting vendor revenue to recurring service streams. This model is most visible in battery cell manufacturing, where gigafactory operators demand guaranteed line efficiency rather than discrete sensor hardware.
IoT in Manufacturing Market Segmentation
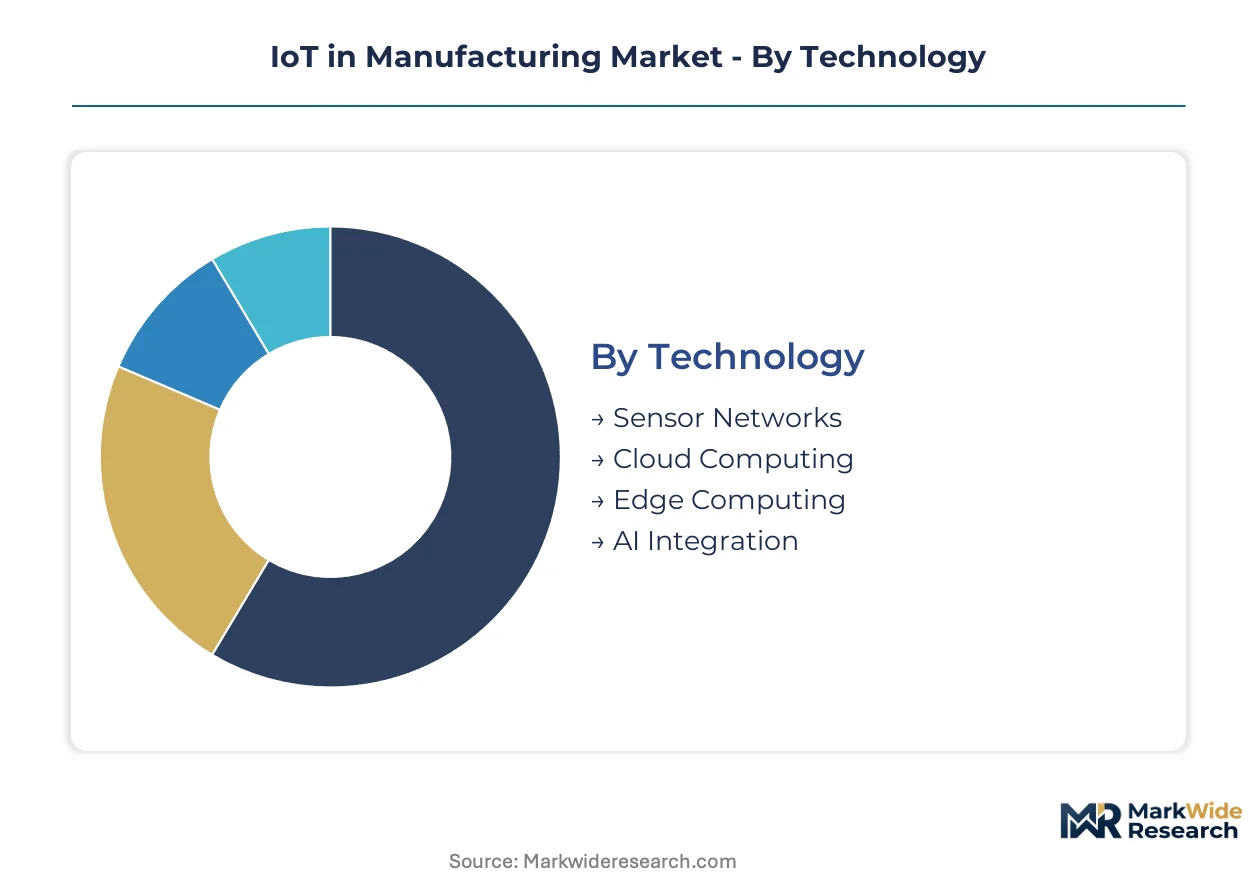
IoT deployments in manufacturing fragment sharply across technology layers and operational use-cases, with each segment demanding distinct latency tolerances, integration complexity, and regulatory compliance postures. Understanding these divides reveals where margin pools concentrate and which architectures face commoditization pressure.
Technology:
Use-case spectrum spans latency-insensitive cloud analytics to sub-10-millisecond safety-critical edge control, with each technology layer commanding different engineering premiums and hardware margins.
- Sensor Networks:Arrays of pressure, vibration, and temperature transducers communicating over MQTT or OPC UA protocols. Automotive component makers in Stuttgart and Wolfsburg deploy dense sensor grids for synchronized motion control, though commoditization erodes hardware margins fastest here.
- Edge Computing:Distributed processing nodes executing inference locally to meet sub-50-millisecond control loop requirements. Aerospace manufacturers pay premiums for failure-avoidance algorithms that cannot tolerate cloud round-trip delays during critical forming operations.
- Cloud Computing:Centralized analytics platforms aggregating historical operational data for long-term optimization. Heavy machinery operators leverage cloud reservoirs for fleet-wide pattern recognition where latency tolerance permits.
- AI Integration:Embedded machine learning modules for autonomous decision-making in production workflows. EU AI Act conformity assessments now mandate explainable architectures, inflating engineering costs for vendors serving regulated pharmaceutical and nuclear component sectors.
The dominant share belongs to Sensor Networks, while Edge Computing is closing the gap fastest.
Application:
Cost tier differentiation separates premium failure-avoidance systems from standard monitoring tools, with aerospace and pharmaceutical buyers absorbing the steepest premiums for predictive capabilities.
- Predictive Maintenance:Algorithm-driven failure forecasting using vibration spectral analysis and thermal imaging. Fleet operators in commercial aviation face contractual downtime penalties that justify six-figure sensor deployments per production line.
- Quality Control:Machine vision systems with real-time defect classification. Electronics assembly plants in Bavaria integrate high-speed camera arrays with edge inference to catch micron-level soldering faults before downstream value destruction.
- Asset Tracking:Location and condition monitoring for work-in-progress inventory across multi-tier supply chains. Automotive OEMs use RFID and UWB triangulation to eliminate search time in sprawling component warehouses.
- Supply Chain Management:End-to-end traceability platforms documenting material provenance and carbon intensity. Emerging EU CBAM requirements for embedded emissions documentation are pulling demand for IoT-enabled compliance architectures.
Predictive Maintenance commands the deepest margins, though Quality Control is expanding most quickly as vision system costs decline.
End User:
Customer type determines integration complexity, with aerospace and pharmaceutical manufacturers demanding 18-24 month validation timelines that exclude agile vendors lacking regulatory expertise.
- Aerospace:Safety-critical manufacturing of turbine blades, structural components, and avionics assemblies. Tier-one suppliers absorb premiums for predictive maintenance systems that prevent unplanned downtime during narrow production windows.
- Automotive Components:High-volume production of powertrain, chassis, and battery systems. Stuttgart-based suppliers pilot time-sensitive networking for deterministic control in electric vehicle battery cell manufacturing.
- Heavy Machinery:Capital equipment production with extended operational lifecycles. German manufacturers leverage digital twin convergence to compress commissioning timelines for custom-engineered mining and construction equipment.
- Electronics Assembly:Surface-mount technology lines and semiconductor packaging operations. Cleanroom environments demand specialized sensor enclosures and contamination-resistant edge computing form factors.
Aerospace dominates procurement value, while Automotive Components is gaining share fastest as battery gigafactory construction accelerates.
Deployment:
Architecture maturity correlates with legacy infrastructure burden, with greenfield Eastern European plants skipping generations of SCADA evolution entirely.
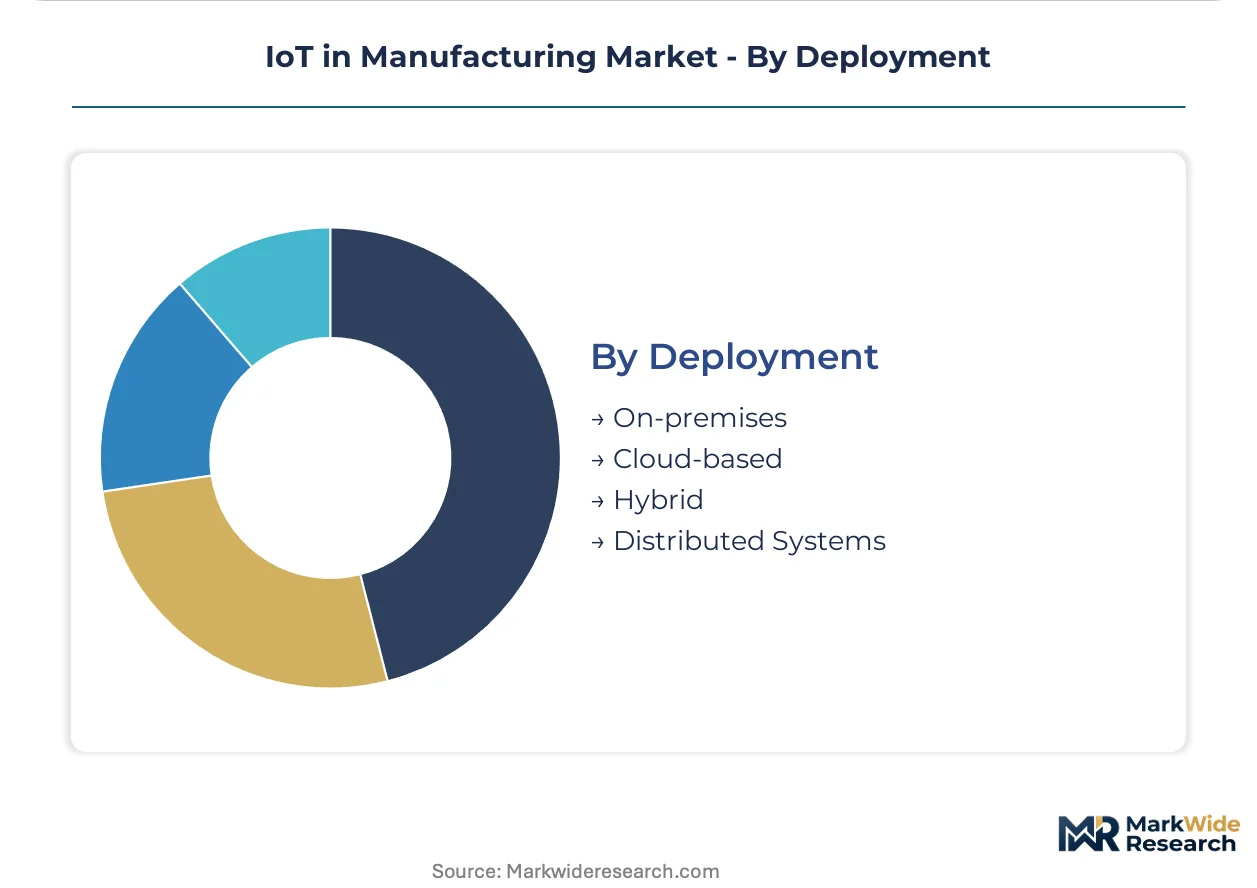
- Hybrid:Split architectures processing safety-critical loops locally while feeding historical data to cloud reservoirs. This configuration satisfies IEC 62443 cybersecurity segmentation requirements while preserving analytics depth.
- On-premises:Fully air-gapped systems for nuclear component, defense, and classified pharmaceutical manufacturing. Air-gap mandates from national security regulators exclude cloud connectivity regardless of latency tolerance.
- Cloud-based:Pure SaaS platforms for non-critical asset monitoring and energy optimization. Mid-tier manufacturers without OT security expertise default here to outsource cybersecurity liability.
- Distributed Systems:Mesh architectures with peer-to-peer node communication for resilient operation during network partition events. Mining equipment manufacturers deploy these for autonomous haul truck coordination in connectivity-constrained pit environments.
Hybrid architectures hold the installed base majority, though Distributed Systems are climbing the fastest as resilience requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Discrete sensor and edge processor supply concentrates among Taiwanese foundries, exposing hardware margins to allocation disruptions. Demand clusters in Germany's Ruhr industrial corridor, where dense ecosystems of systems integrators accelerate smart factory proof-of-concept cycles. Regulatory divergence across jurisdictions fragments vendor engineering workflows.
United States
FDA scrutiny of software-as-a-medical-device spills into pharmaceutical manufacturing IoT deployments, extending validation timelines. The Inflation Reduction Act's domestic content incentives pull battery gigafactory construction toward Michigan and Georgia. Automotive OEMs in Detroit specify uptime guarantees as contract terms, shifting vendor revenue to recurring service streams.
Germany
The EU AI Act's conformity assessments for autonomous manufacturing decisions force algorithmic auditability investments. BSI cybersecurity standards align with IEC 62443 frameworks for industrial communication security. Siemens and SAP SE anchor smart factory ecosystems in the Ruhr cluster, where dense supplier networks compress deployment cycles.
China
MIIT's dual carbon goals mandate IoT traceability for emissions monitoring in heavy industry. GB standards for industrial internet platforms tighten interoperability requirements for state-owned steel and chemical enterprises. Yangtze River Delta manufacturers deploy native IoT architectures in greenfield semiconductor fabs without legacy SCADA retrofit burdens.
Japan
METI's Society 5.0 roadmap funds edge computing deployments in precision machining and robotics assembly. JIS standards for industrial IoT security create compliance moats against foreign platform vendors. Nagoya-based automotive component makers pilot time-sensitive networking for synchronized battery cell manufacturing.
Poland
EU structural funds finance greenfield manufacturing plants skipping legacy automation generations entirely. CE marking requirements for machinery exports align with Machinery Directive functional safety mandates. Wrocław and Kraków industrial zones attract German automotive suppliers seeking lower-cost IoT deployment environments.
IoT in Manufacturing Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with eroding hardware margins. The vendor base separates into three strata: diversified industrial conglomerates with captive software stacks, pure-play automation vendors defending channel control, and cloud-native entrants attacking analytics layers. Consolidation pressure concentrates in the middle tier as scale advantages harden. Dominant competitive moves include M&A for AI talent acquisition and strategic partnerships bridging OT-IT integration gaps.
Among diversified industrial technology groups, Siemens and ABB exemplify vertical integration strategies spanning hardware through software layers. Rockwell Automation occupies a position within the North American channel-controlled tier, while IBM represents the services-led archetype layering AI capabilities atop legacy infrastructure. These anchors illustrate how competitive positioning fragments across integration depth, geographic footprint, and regulatory compliance expertise rather than converging on a single dominant model.
| Leading Market Players |
|---|
| Siemens |
| Cisco Systems |
| Rockwell Automation |
| IBM |
| Microsoft |
| SAP SE |
| ABB |
| General Electric |
| Schneider Electric |
| Others |
Supply Flow & Price Mechanics
Taiwanese foundry allocation disruptions for discrete sensor and edge processor supply determine both tiered pricing spreads across validated versus commodity IoT platforms and the geographic shape of manufacturing footprints as buyers seek supply security.
Pricing Analysis
The EU AI Act dictates the pricing tier structure by mandating conformity assessment costs that inflate engineering premiums for explainable AI architectures serving pharmaceutical and nuclear component sectors. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated predictive maintenance systems from CE-marked industrial monitoring tools and unvalidated commodity sensor arrays. Cost compression in the sensor network tier is intensifying because automotive component makers in Stuttgart and Wolfsburg negotiate volume scale discounts for dense deployment grids. Mid-tier manufacturers without OT security expertise exhibit the highest price sensitivity, defaulting to pure-cloud SaaS platforms to outsource cybersecurity liability, while aerospace fleet operators absorb the steepest premiums for failure-avoidance algorithms.
Supply Chain Analysis
Silicon feedstock for edge processors and MEMS sensor substrates draws from Taiwanese foundries, South Korean memory fabricators, and German precision component specialists. Raw material dependencies span 300mm silicon wafers, rare earth elements for magnetic sensors, and specialized ceramics for high-temperature transducers. Single-source vulnerability concentrates in Taiwanese foundry allocation decisions that expose hardware margins to geopolitical disruption. Distribution runs through systems integrator networks anchored in Germany's Ruhr cluster, where dense supplier ecosystems compress deployment cycle timelines for smart factory rollouts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Outcome-based performance contracts for uptime guarantees and throughput improvement targets are expanding faster than discrete sensor hardware sales, transforming vendor economics toward recurring service streams.
For Market Incumbents: Insulate engineering margins by deepening captive software stack integration around digital twin platforms and AI-driven predictive maintenance modules. Accelerate IEC 62443 cybersecurity certification investments to exclude mid-tier competitors lacking specialized engineering labor pools. Channel control across North American automotive assembly lines remains defensible against cloud-native entrants attacking analytics layers. For New Entrants and Emerging Players: Pursue greenfield Eastern European manufacturing zones in Poland and the Czech Republic where plants skip legacy SCADA generations entirely. Target battery gigafactory operators demanding guaranteed line efficiency rather than capital equipment purchases. Lead with edge computing deployments for safety-critical control loops where cloud latency constraints exclude pure-cloud incumbents. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diversified industrial conglomerates with captive AI talent and regulatory compliance expertise. Long-term viability hinges on service-attach revenue ratios exceeding hardware transaction values. Watch for carbon-border adjustment mechanism implementation timelines as the inflection signal that will mandate IoT traceability as a compliance prerequisite for exported manufactured goods.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Coupling real-time sensor feeds with finite element analysis compresses production ramp timelines for German heavy machinery manufacturers. |
| Regulatory Compliance Investment | Front-loading EU AI Act conformity assessment costs creates pricing power in pharmaceutical and nuclear component sectors. |
| Geographic Expansion | Greenfield plants in Poland and the Czech Republic adopt native IoT architectures without retrofit constraints. |
| Strategic Partnership | Bridging OT-IT integration gaps through alliances with systems integrators accelerates proof-of-concept cycles. |
| Acquisition of Specialist Firm | AI talent acquisition targets explainable AI tooling vendors serving EU Machinery Directive functional safety mandates. |
Methodological Framework
A spread of perspectives from plant engineers, OEM procurement teams, aftermarket service heads, and systems integrators converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, IEC standards documentation, and customs trade data for industrial automation equipment. Bottom-up deployment volume estimates triangulated against top-down market size assessments from hyperscaler capex disclosures and automotive OEM production databases.
Demand-supply balance modeling across the analysis window integrated technology layer segmentation with end-use industry adoption curves, deployment architecture migration patterns, and regional regulatory cluster differentiation. CAGRs derived from historical trajectory analysis adjusted for EU AI Act implementation timelines and carbon-border adjustment mechanism phased rollouts. Forecast inputs incorporated foundry capacity allocation forecasts and battery gigafactory construction pipelines.
Sensitivities concentrate around Taiwanese semiconductor supply disruptions, EU regulatory enforcement intensity, and Eastern European manufacturing investment flows. Forecasts reflect documented assumptions regarding interoperability standard adoption rates and OT-IT integration labor availability. Cross-checking against IEC 62443 certification timeline benchmarks and automotive OEM service contract disclosure patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IIOT Gateway for Utility Market
Internet of Things (IoT)
IoT Gateway Hardware and Software Market
Internet of Things (IoT)
North America Industrial IoT Market
Internet of Things (IoT)
Global Internet of Behaviors Market
Internet of Things (IoT)
Smart Sprinkler Controller Market
Internet of Things (IoT)
IoT Development Kit Market
Internet of Things (IoT)
IoT Integration Market
Internet of Things (IoT)
Smart Tracker Market
Internet of Things (IoT)
Wi-Fi Smart Scale Market
Internet of Things (IoT)
IoT Device Management Platform Market
Internet of Things (IoT)
IoT Device Management Market
Internet of Things (IoT)
Global IOT Gateway Market
Internet of Things (IoT)
Satellite IoT Communication Market
Internet of Things (IoT)
Bluetooth Smart Plugs Market
Internet of Things (IoT)
Narrow Band IoT Tracker Market
Internet of Things (IoT)
Telecom Internet of Things (IoT) Market