
 Smart Shelf Market | 2026-2036
Smart Shelf Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Shelf Market Analytics
RFID systems engineering talent is rotating from logistics into retail shelf automation, narrowing the deployment bottleneck that slowed early pilots. Samsung Electronics leverages its semiconductor fabrication scale to produce low-latency edge processors for vision-enabled shelves. Zebra Technologies dominates handheld and fixed reader ecosystems, extending its installed base into shelf-level infrastructure. Pricer AB specializes in electronic shelf label integration, anchoring its position in European grocery modernization programs.
A smart shelf integrates load cells, optical sensors, RFID antennas, or electronic ink displays with edge computing gateways to track product presence, weight change, or price updates in real time. These systems transmit telemetry through Bluetooth mesh, NFC tap points, or cloud-connected RFID backbones to trigger replenishment alerts, dynamic pricing, or planogram compliance audits. IoT-enabled Shelf configurations lead current deployments because they retrofit existing fixtures without full replacement, while Automated Inventory Shelf segments capture the fastest growth as warehouses adopt robotic picking coordination. RFID technology sustains the largest installed base, though Cloud Computing backends now determine margin pools by enabling subscription revenue models that offset hardware commoditization.
The EU Green Deal and REACH substance restrictions shape hardware material choices and modular disassembly requirements for shelf systems sold across Europe. CE marking and the EU AI Act impose conformity obligations on computer-vision shelves that perform automated customer analytics, filtering market access for non-compliant vendors. Stakeholders must monitor whether national data protection regulators interpret shelf-mounted cameras as biometric collection points, as this classification would trigger GDPR Article 9 consent architectures and reshape system design priorities.
Market Dynamics
Edge-computing shelf networks are compressing data latency requirements below 50 milliseconds, forcing hardware vendors to redesign sensor-to-gateway architectures around localized inference rather than cloud dependency.
Growth Catalysts
- EU Green Deal:Modular hardware mandates accelerate component standardization across German, French, and Italian retail chains, reducing replacement cycle costs and e-waste liability.
- Weight-sensing systems:Supermarkets deploy load-cell arrays to automate replenishment triggers, cutting stockout incidents and labor reallocation costs in high-SKU environments.
- RFID engineering migration:Talent rotation from logistics into retail shelf automation narrows deployment bottlenecks that stalled early vision-based pilots.
Market Restraints
- Semiconductor supply concentration:Edge processor fabrication clusters in Taiwan and South Korea expose shelf system lead times to geopolitical disruption and foundry allocation constraints.
- GDPR Article 9 friction:National data protection regulators in Germany and France debate whether shelf-mounted cameras constitute biometric collection, chilling computer-vision rollout timelines.
- Lithium-ion cell volatility:Electronic shelf label battery costs fluctuate with raw material spot markets, compressing hardware margin pools for mid-tier vendors.
Strategic Opportunities
- Urban micro-fulfillment:Dense German city-center formats pilot edge-computing shelf networks that coordinate robotic picking, opening warehouse-adjacent revenue streams.
- REACH substance compliance:Modular disassembly requirements create aftermarket service contracts for component replacement and recycling, shifting revenue toward recurring models.
- Bluetooth mesh-NFC convergence:Hybrid connectivity architectures enable tap-to-verify authentication alongside continuous telemetry, appealing to pharmacy and cosmetics verticals.
Industry Challenges
- Computer-vision calibration:SKU proliferation demands continuous retraining of edge inference models, straining ML operations teams and deployment velocity.
- CE marking complexity:EU AI Act conformity assessments for customer-analytics shelves extend certification timelines, filtering vendor participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Shelf Market |
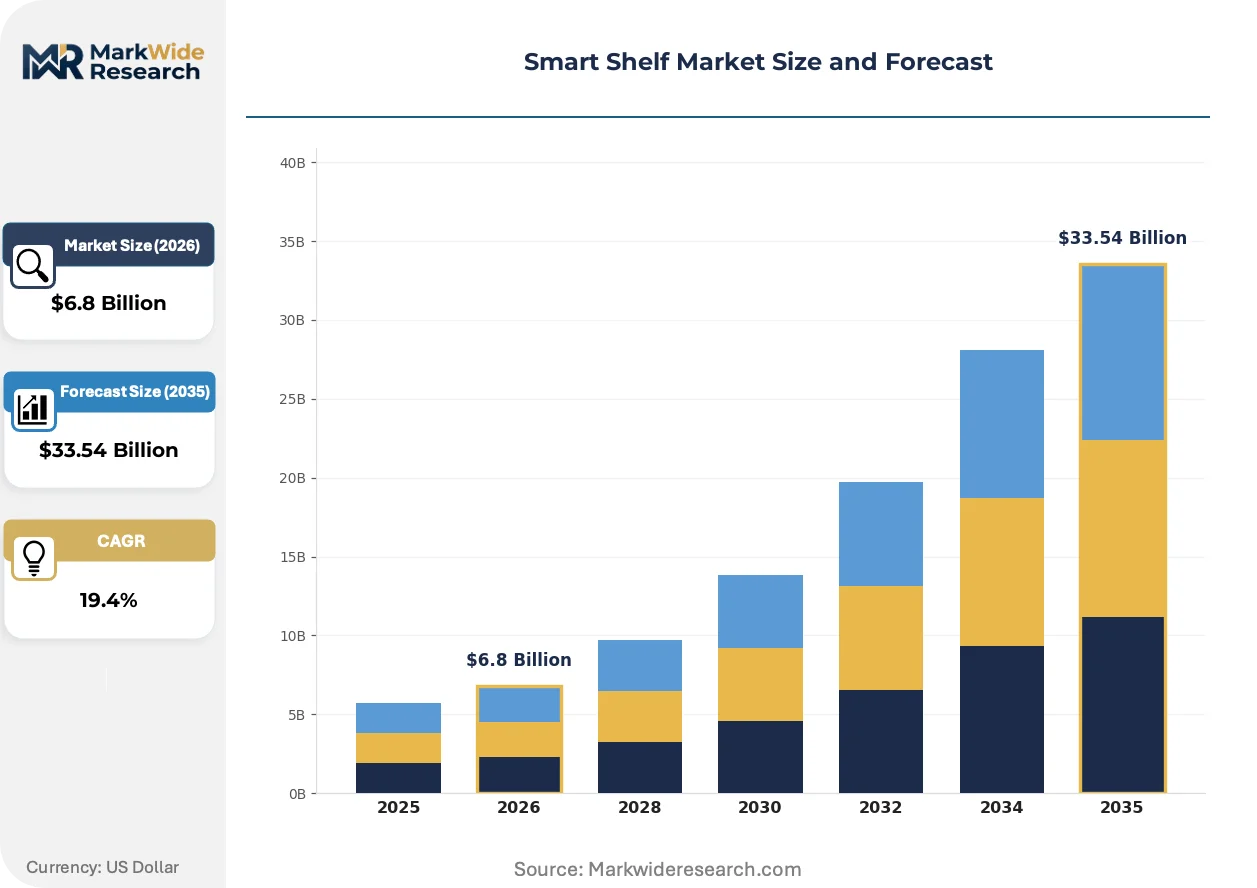
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $33.54 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Shelf, IoT-enabled Shelf, Automated Inventory Shelf, Smart Display Shelf Technology: RFID, NFC, Bluetooth, Cloud Computing End User: Retail Stores, Warehouses, Supermarkets, Distribution Centers Installation: Wall-mounted, Freestanding, Modular, Custom-built |
| Companies Covered | Honeywell International, Samsung Electronics, Intel Corporation, Avery Dennison Corporation, Pricer AB, Huawei Technologies, Zebra Technologies, Trax Technology Solutions, E Ink Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Shelf Market Evolving Landscape
Vision-based shelf monitoring is migrating inference workloads from cloud backends to localized edge processors, compressing response latency and enabling real-time replenishment coordination.
Computer-vision edge processors are supplanting RFID backbones as the dominant intelligence layer in high-SKU grocery environments. German retail chains lead adoption, deploying localized inference to trigger sub-second replenishment alerts. This migration compresses cloud dependency and shifts margin capture toward semiconductor and software subscription layers.
REACH substance restrictions and EU AI Act conformity obligations are reshaping hardware material selection and computer-vision system design across European deployments. Vendors must document modular disassembly protocols and algorithmic transparency to maintain market access. German regulators interpret shelf-mounted analytics most stringently, forcing design prioritization toward privacy-preserving edge architectures.
Buyer procurement patterns are fragmenting between retrofit IoT-enabled Shelf configurations and full Automated Inventory Shelf replacements, with warehouse operators favoring robotic coordination capabilities while supermarkets prioritize minimal fixture disruption. Channel intermediaries face margin compression as direct vendor relationships expand. This bifurcation is most pronounced in German dense urban formats, where space constraints dictate hardware selection.
Smart Shelf Market Segmentation
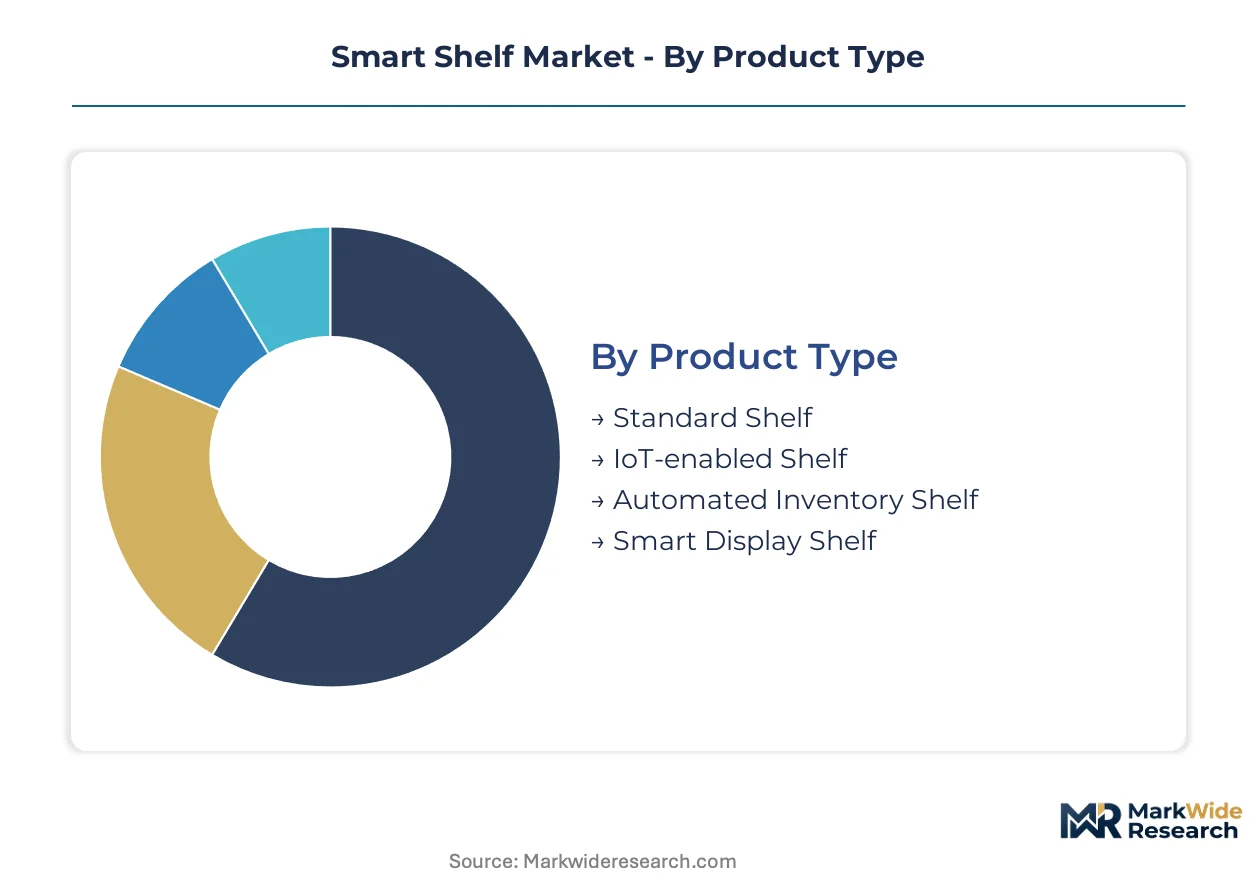
Smart shelf procurement fragments across retrofit compatibility, connectivity protocols, and operational intensity requirements. Buyers prioritize segments that minimize fixture replacement while satisfying regulatory mandates for modularity and data governance.
Product Type:
REACH substance restrictions and EU AI Act conformity obligations differentiate hardware categories by disassembly complexity and embedded intelligence.
- IoT-enabled Shelf:Retrofit sensor arrays attach to existing fixtures through load cells, optical modules, or RFID antennas without structural replacement. German supermarket chains favor this configuration for dense urban formats where fixture removal disrupts operations.
- Automated Inventory Shelf:Integrated robotic coordination interfaces enable real-time picking synchronization in warehouse environments. Distribution centers in automated fulfillment networks deploy these systems to compress replenishment latency below 50 milliseconds.
- Standard Shelf:Non-instrumented storage infrastructure serves baseline inventory needs without telemetry integration.
- Smart Display Shelf:Electronic ink or LED-integrated surfaces enable dynamic pricing and promotional content delivery at the point of decision.
Established volume favors IoT-enabled Shelf configurations; emerging adoption favors Automated Inventory Shelf systems.
Technology:
Margin capture concentrates at semiconductor layers as intelligence migrates toward localized inference.
- RFID:Ultra-high frequency and NFC antenna arrays sustain the largest installed base through proven inventory tracking reliability. Logistics engineering talent rotation into retail applications narrows deployment bottlenecks that stalled early implementations.
- Cloud Computing:Backend subscription architectures determine recurring revenue pools by enabling predictive analytics and cross-store benchmarking. European grocery modernization programs prioritize vendors with GDPR-compliant data residency guarantees.
- NFC:Tap-to-verify authentication supports pharmacy and cosmetics verticals requiring item-level pedigree confirmation.
- Bluetooth:Mesh networking protocols enable continuous telemetry transmission without dedicated infrastructure backbones.
RFID anchors current procurement volumes; Cloud Computing backends are expanding most quickly as subscription models displace hardware-only transactions.
End User:
Labor cost pressures and SKU proliferation intensity segment selection across operational environments.
- Supermarkets:Weight-sensing and vision-based systems automate replenishment triggers in high-SKU environments. French and Italian retail chains pilot edge-computing networks to reduce stockout incidents and optimize associate deployment.
- Warehouses:Robotic picking coordination demands sub-second latency from shelf-to-gateway architectures. Automated Inventory Shelf configurations dominate this segment through direct integration with warehouse management systems.
- Retail Stores:General merchandise and specialty retailers prioritize minimal-disruption retrofit solutions.
- Distribution Centers:High-velocity fulfillment operations require modular hardware designs that simplify component replacement under REACH e-waste directives.
Supermarkets concentrate current deployment value; warehouses are gaining share fastest through robotic automation adoption.
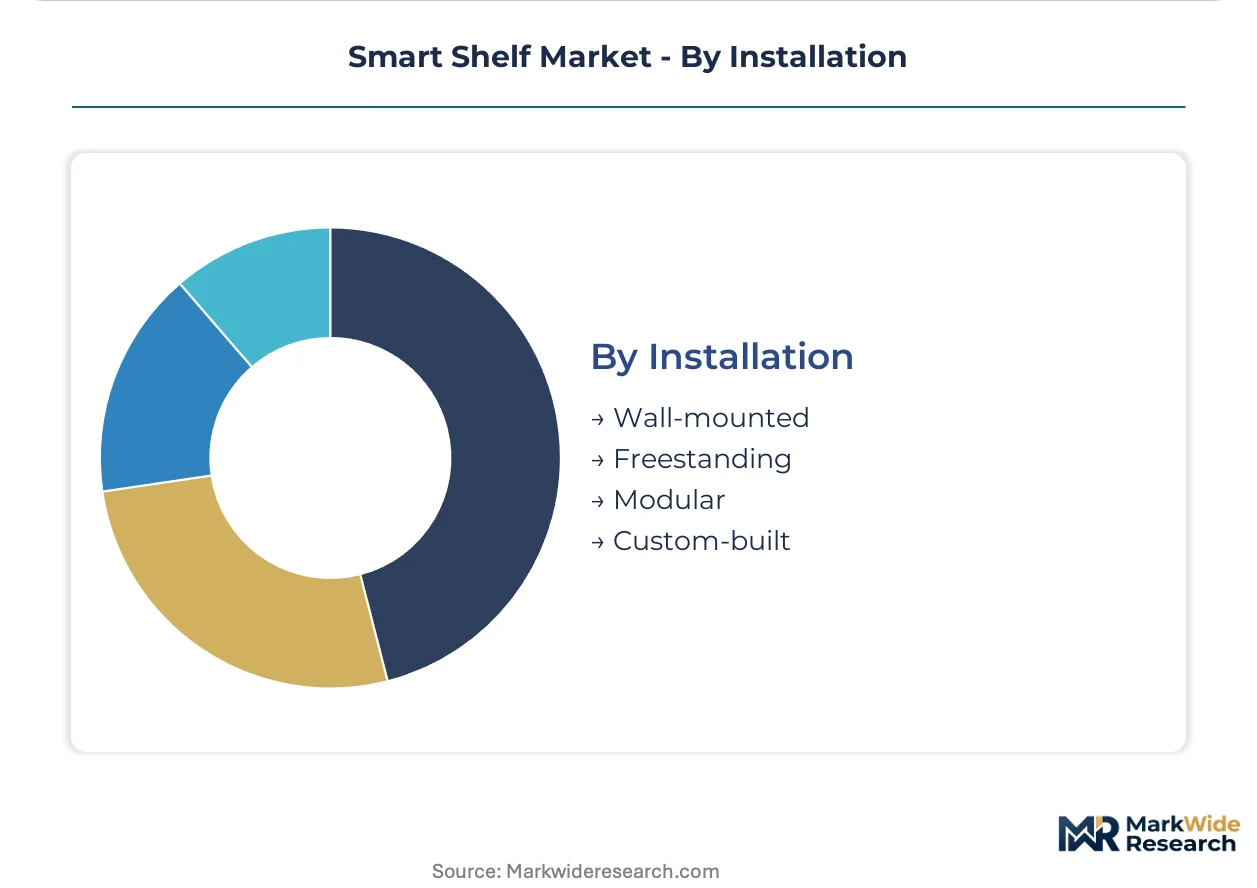
Installation:
Space constraints and fixture lifecycle management shape hardware mounting decisions.
- Modular:Component-level disassembly satisfies EU Green Deal mandates for simplified recycling and field replacement. German regulators interpret modular design requirements most stringently, forcing vendor prioritization of standardized interfaces.
- Freestanding:Self-supporting units enable rapid reconfiguration in temporary retail and pop-up formats without structural anchoring.
- Wall-mounted:Permanent fixture integration maximizes floor space efficiency in constrained urban store formats.
- Custom-built:Bespoke dimensions accommodate non-standard product categories or architectural constraints.
Modular installation dominates European procurement specifications; freestanding configurations are climbing the fastest in experimental retail formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail chains in Germany deploy weight-sensing and vision-based systems for labor optimization, while warehouses in the United States prioritize robotic picking coordination. This consumption-mix differential reflects divergent operational pressures across geographies.
Germany
Dense urban supermarket formats drive edge-computing shelf network pilots in Berlin and Hamburg. The EU Green Deal and national e-waste directives enforce modular hardware mandates, accelerating component standardization. The Rhine-Ruhr metropolitan region concentrates retail automation engineering talent migrating from logistics applications.
United States
Distribution centers demand sub-50 millisecond latency for robotic fulfillment coordination. OSHA workplace safety guidelines intersect with state-level data privacy frameworks in California and Illinois, complicating vision-based customer analytics deployment. The Dallas-Fort Worth logistics corridor anchors automated inventory shelf adoption for e-commerce fulfillment.
France
Supermarket chains pilot computer-vision shelves to reduce stockout incidents in high-SKU environments. CNIL interpretations of GDPR Article 9 scrutinize shelf-mounted cameras for biometric classification, chilling rollout timelines. The Île-de-France region concentrates grocery modernization procurement decisions.
China
Urban retail formats integrate electronic shelf labels with dynamic pricing capabilities. SAMR standards and dual carbon goals shape hardware material selection and energy efficiency requirements. The Yangtze River Delta manufacturing cluster supplies edge processors and sensor modules for domestic and export markets.
Japan
Convenience store operators deploy compact IoT-enabled shelf retrofits to optimize limited floor space. METI guidelines on IoT security and JIS standards for electronic equipment influence procurement specifications. The Kanto region around Tokyo hosts pilot programs for Bluetooth mesh-NFC hybrid connectivity in pharmacy verticals.
Smart Shelf Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the smart shelf market. Semiconductor fabricators and industrial electronics conglomerates occupy the upper tier through captive edge processor production and scale advantages. Mid-tier specialists concentrate on electronic shelf label integration, RFID antenna design, or vision software stacks. Competitive moves center on backward integration into sensor manufacturing and geographic expansion through direct retail chain relationships.
Among Asia-Pacific-based electronics conglomerates, Samsung Electronics and Huawei Technologies exemplify integrated leaders leveraging semiconductor fabrication scale. Zebra Technologies represents the specialist tier with established reader ecosystem expertise extending into shelf-level infrastructure. These anchors illustrate divergent strategic positions: captive silicon supply versus installed base extension.
| Leading Market Players |
|---|
| Honeywell International |
| Samsung Electronics |
| Intel Corporation |
| Avery Dennison Corporation |
| Pricer AB |
| Huawei Technologies |
| Zebra Technologies |
| Trax Technology Solutions |
| E Ink Holdings |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety day edge processor lead times from Taiwan and South Korea foundries compress hardware margin pools and force buyers toward subscription-heavy contract structures that lock in component allocation priority.
Pricing Analysis
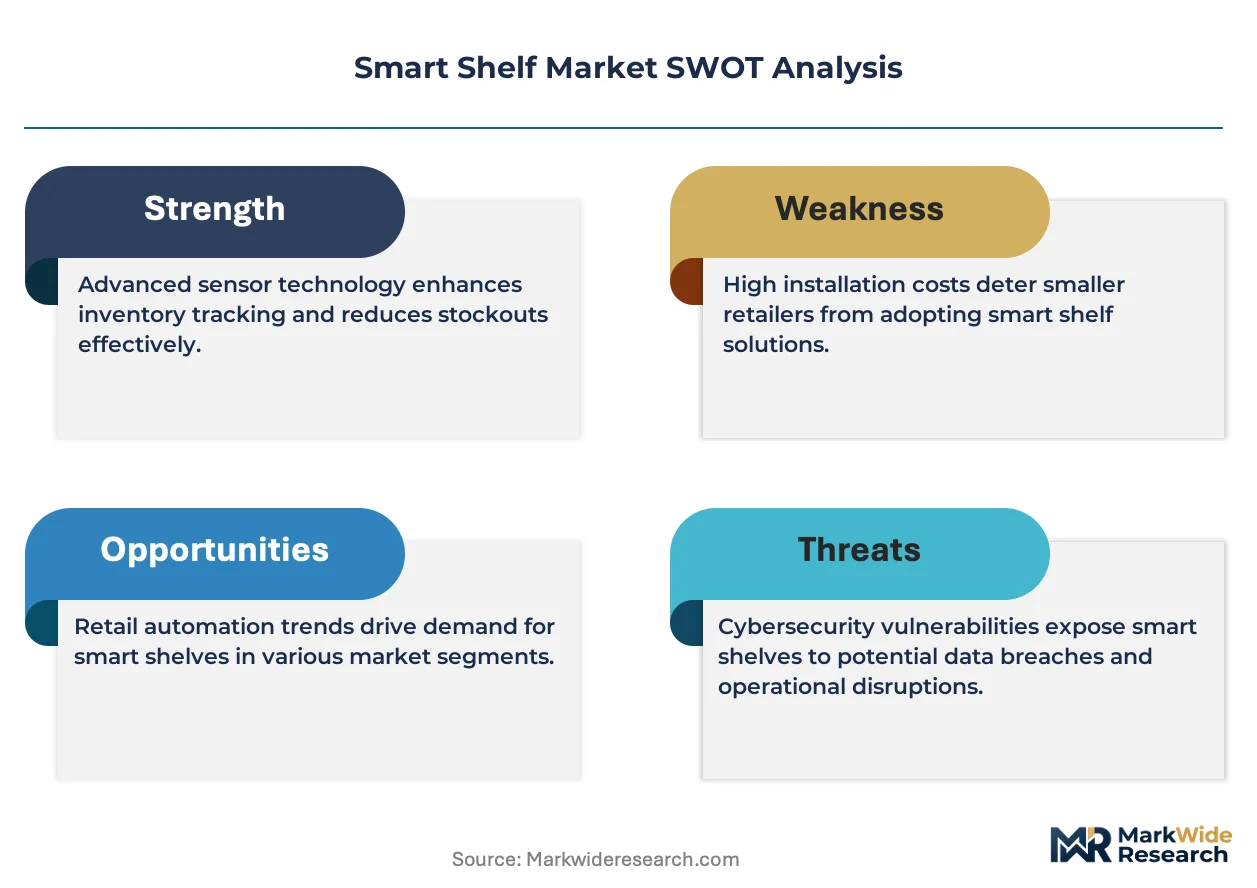
Long-term offtake agreements dominate procurement between retail chains and semiconductor vendors, though spot purchases persist for electronic shelf label batteries and optical sensor modules. Three-tier pricing structure across premium, standard, and economy levels separates GDPR-compliant edge-computing systems from basic RFID retrofit kits. Cost compression in mid-tier hardware is intensifying because lithium-ion cell volatility feeds through to label production costs. Warehouse operators exhibit lowest price sensitivity due to robotic coordination latency requirements, while independent supermarket chains face acute margin pressure.
Supply Chain Analysis
Taiwan and South Korea anchor edge processor fabrication for vision-enabled shelf systems, with China supplying electronic ink displays and load-cell sensor arrays. The supply chain draws from rare earth processing for magnet components, silicon wafer supply for inference chips, and cobalt-lithium chemistry for ESL power cells. Single-source vulnerability in advanced node semiconductor fabrication exposes shelf system availability to geopolitical disruption. Distribution runs through direct vendor-retailer relationships that displace traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud computing backend subscriptions and REACH-compliant modular refurbishment services are expanding faster than hardware unit sales, creating durable revenue attach opportunities across installation lifecycles.
For Market Incumbents: Consolidate backward integration into sensor manufacturing to defend against commoditization of RFID antenna hardware. Acquire edge-computing software stacks in German-speaking markets to deepen subscription revenue pools and preempt regulatory-driven vendor consolidation. For New Entrants and Emerging Players: Anchor in French supermarket pilot programs where CNIL regulatory friction has chilled computer-vision rollout timelines for established vendors. Target Bluetooth mesh-NFC hybrid connectivity architectures for pharmacy verticals seeking tap-to-verify authentication without cloud dependency. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial electronics conglomerates seeking to divest non-core shelf automation divisions amid semiconductor cycle volatility. Mid-cap specialists with captive ESL battery recycling capabilities and GDPR-certified edge architectures represent priority acquisition profiles. Watch for German KBA interpretations of shelf-mounted cameras as biometric collection points as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive load-cell production insulates margin pools from lithium price volatility. |
| GDPR-Certified Edge Architecture Development | Privacy-preserving inference enables German market access under Article 9 scrutiny. |
| Modular Refurbishment Service Launch | REACH-compliant component replacement shifts revenue toward recurring aftermarket models. |
| Robotic Picking Interface Standardization | Sub-50 millisecond latency protocols secure warehouse automation procurement decisions. |
| Bluetooth Mesh-NFC Hybrid Platform | Dual connectivity captures pharmacy and cosmetics pedigree verification requirements. |
Research Methodology
Operator-level perspectives from retail automation engineers, supermarket category managers, warehouse systems integrators, and semiconductor procurement leads anchored the qualitative base. These primary inputs combined with secondary validation from EU AI Act conformity assessment databases, REACH substance restriction filings, SEC 10-K hardware segment disclosures, and German e-waste directive implementation reports. Bottom-up unit deployment estimates triangulated against top-down retail modernization budget allocations.
Sensitivity analysis tested forecast outputs across edge processor yield scenarios, lithium carbonate price bands, and regulatory interpretation variance between German KBA and French CNIL authorities. Segmentation dimensions modeled include product type, connectivity protocol, installation format, and end-user operational intensity. CAGRs derived from logistic diffusion curves fitted to early-adopter deployment trajectories and scaled by retail square footage automation potential. Industry-specific inputs incorporated robotic picking coordination latency requirements and modular disassembly compliance cost curves.
Material uncertainties — geopolitical disruption to Taiwan semiconductor foundries, GDPR Article 9 reclassification of shelf-mounted cameras, and raw material spot market volatility — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and component supply continuity that could require revision. Recalibration cycles align with material shifts in EU AI Act enforcement patterns and edge processor allocation announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
Retail Inventory Software Market
Retail Technology
Enterprise Mobility in Retail Market
Retail Technology
Data-Driven Retail Solution Market
Retail Technology
Smart Grocery Cart Market
Retail Technology
United States Grocery and Pharmacy Point of Sale (POS) Terminal Market
Retail Technology
AR in Retail Market
Retail Technology
Internet of Things (IoT) in Retail Market
Retail Technology
North America Automation in Retail Market
Retail Technology
Global Advanced Shopping Technology Market
Retail Technology
Global Kiosk Market
Retail Technology
Self-Checkout in Retail Market
Retail Technology
Retail-As-A-Service (Raas) Market
Retail Technology
Customer-Facing Technology Market
Retail Technology
US Self-Checkout Systems Market
Retail Technology
Cash Register Machines Market
Retail Technology
Selfservice Technologies Market