
 IoT Application Development Services Market | 2026-2036
IoT Application Development Services Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Application Development Services Market Outlook
Systems integrator channels serving mid-market industrial clients is fragmenting as cloud hyperscalers build direct embedded-software practices and boutique firmware shops cultivate vertical expertise. Intellectsoft leverages its healthcare and logistics specialization to sustain premium project economics. Kanda Software anchors North American delivery through dedicated IoT labs in Austin and Boston. Softeq competes on hardware-software co-design capabilities for wearable and medical device makers.
IoT application development services encompass the full-cycle engineering of embedded firmware, edge analytics modules, cloud-native device management platforms, and API integration layers that connect physical sensors to enterprise systems. These services typically involve protocol translation between constrained devices using MQTT or CoAP and cloud infrastructures running on Kubernetes orchestration, with latency budgets under 100 milliseconds for real-time control loops. Consulting and development service types capture the largest revenue pools, while edge deployment models represent the fastest-growing structural segment as manufacturers push inference workloads closer to production lines. Healthcare and manufacturing end-user verticals concentrate margin-rich projects requiring FDA or ISO 13485 compliance, whereas smart home applications commoditize toward platform-agnostic subscription models.
FDA's software-as-medical-device guidance and the EU Cyber Resilience Act impose pre-market validation and post-market monitoring obligations that inflate development timelines and certification costs. Germany's BSI technical guidelines for IoT baseline security, Japan's METI data governance framework for connected industries, and China's GB/T standards for IoT interoperability collectively segment vendor qualification requirements by jurisdiction. Stakeholders must monitor which regulatory frameworks their target customers face, as compliance capability becomes the primary bid qualifier before technical evaluation even begins.
Market Dynamics
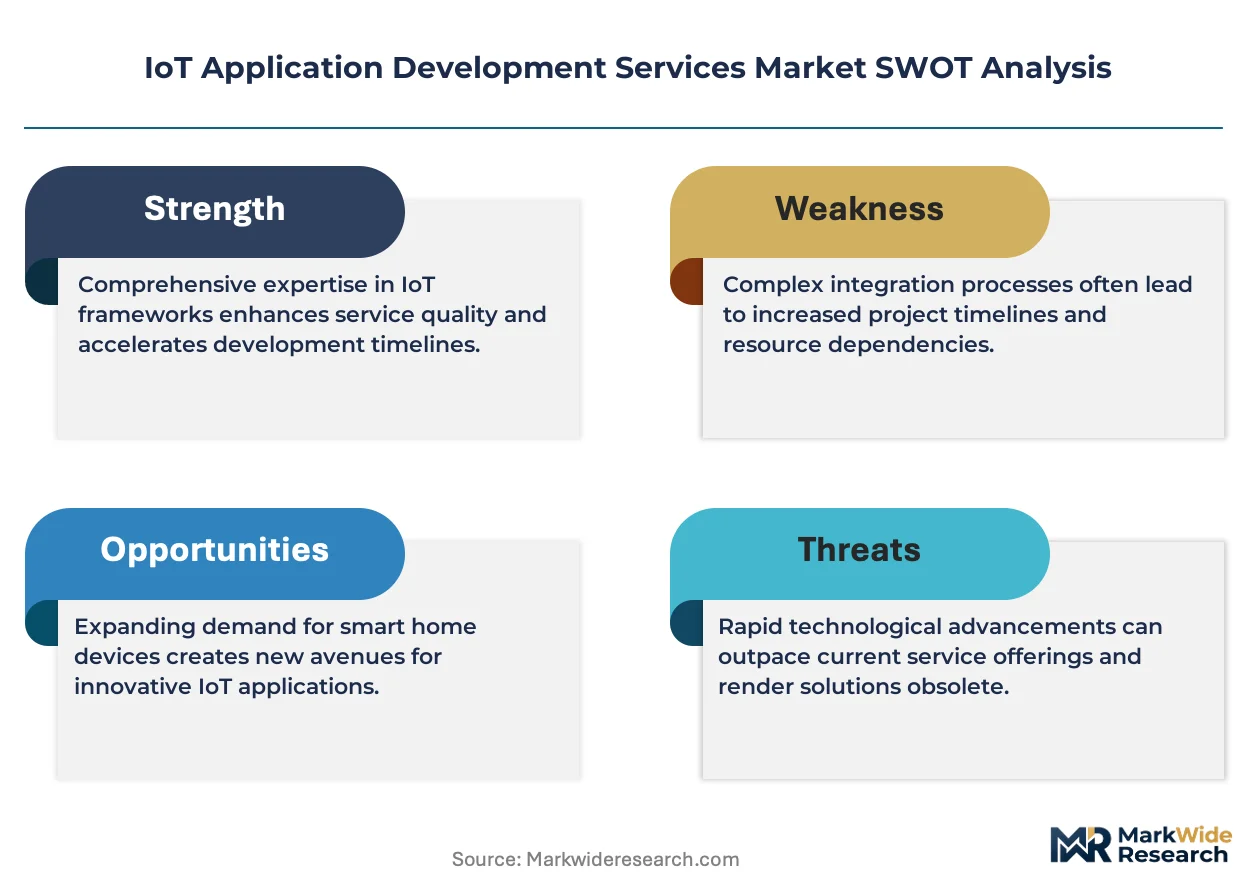
Cloud hyperscalers are embedding firmware development capabilities directly into their platform stacks, collapsing the traditional systems integrator channel that historically connected mid-market manufacturers to specialized engineering talent. This vertical compression is redistributing margin pools from independent service providers toward platform-native development ecosystems.
Growth Catalysts
- FDA Software-as-Medical-Device Guidance:Pre-market validation requirements for connected diagnostics and remote patient monitoring devices are expanding the addressable engineering services pool for healthcare IoT specialists. Compliance mandates create captive demand for validated development partners.
- Industrial IoT in German Automotive:Machinery OEMs in Baden-Württemberg and Bavaria are commissioning edge analytics modules for predictive maintenance, driving procurement of co-design services that bridge operational technology and cloud infrastructure.
- EU Cyber Resilience Act:Mandatory security-by-design obligations for connected products entering European markets are forcing hardware manufacturers to outsource firmware hardening and post-market monitoring capabilities.
Market Restraints
- Semiconductor Supply Concentration:Foundry capacity constraints in Taiwan and South Korea create 26-40 week lead times for specialized microcontrollers, delaying client project milestones and inflating buffer inventory costs for development shops.
- Certification Cost Escalation:ISO 13485 quality management system audits and FDA 510(k) submission preparation now consume 15-22% of total program budgets for medical device IoT projects, compressing service provider margins.
- Protocol Fragmentation:Coexistence of MQTT, CoAP, LwM2M, and proprietary industrial protocols forces engineering teams to maintain multiple stack implementations, diluting specialization economies.
Strategic Opportunities
- Edge AI Convergence:TensorFlow Lite and ONNX Runtime deployment on ARM Cortex-M55 microcontrollers enables millisecond-latency inference for vibration analysis and acoustic monitoring, opening new service categories for industrial predictive maintenance.
- Japan METI Data Governance Framework:Cross-border data flow restrictions for connected industries are creating localized development demand, favoring regional engineering partners with domestic data residency capabilities.
- Smart Building Retrofit:Commercial real estate operators in Singapore and South Korea are replacing legacy BACnet systems with IP-native sensor networks, generating greenfield commissioning projects for wireless mesh specialists.
Industry Challenges
- Firmware Security Engineering Talent Gap:Secure boot implementation, side-channel attack mitigation, and cryptographic key provisioning expertise remains concentrated among a narrow cohort of semiconductor veterans, constraining team scaling.
- Interoperability Testing Complexity:Multi-vendor sensor ecosystems require exhaustive validation against 50+ cloud platform variants, extending quality assurance cycles without commensurate revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Application Development Services Market |
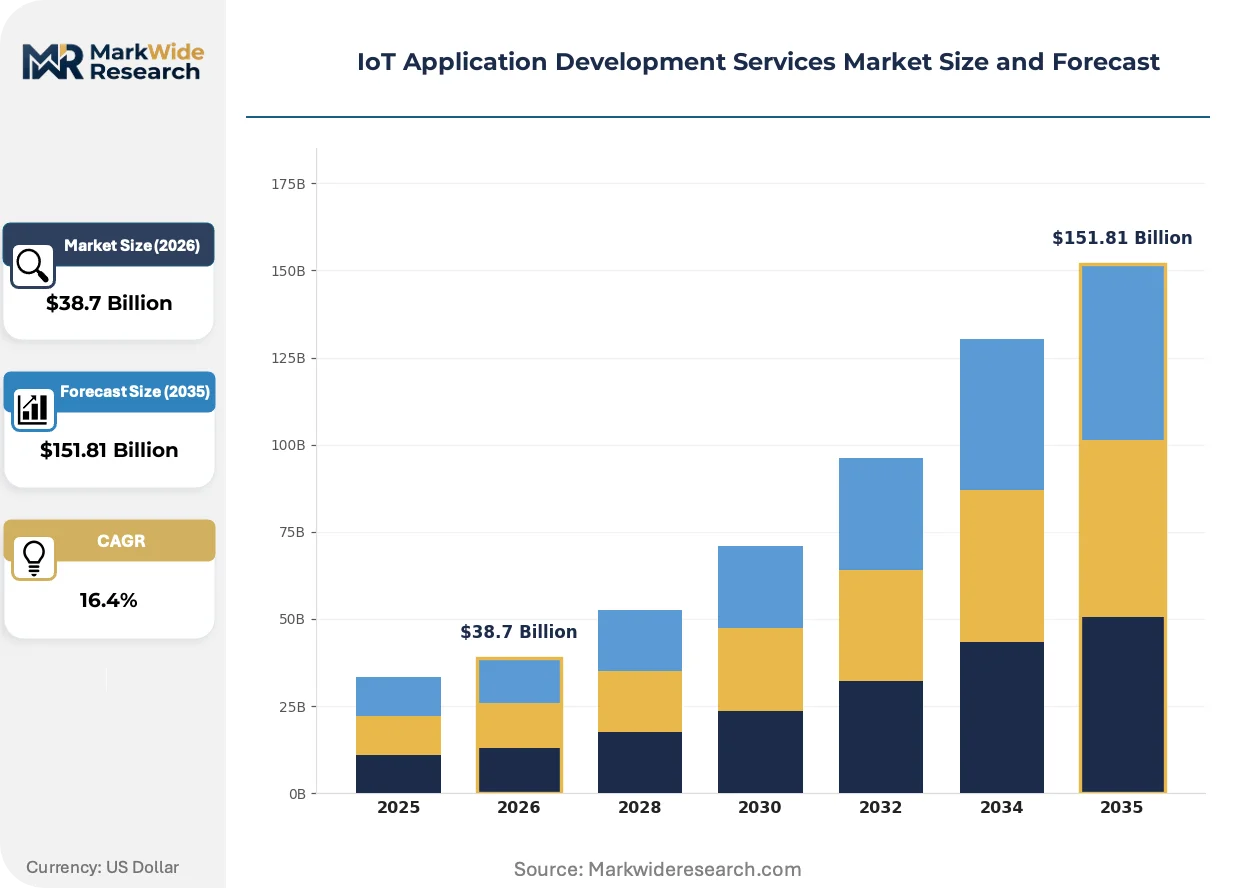
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Development, Implementation, Maintenance Deployment Model: Cloud, On-Premises, Hybrid, Edge End User: Smart Home, Healthcare, Manufacturing, Retail Technology: Bluetooth, Zigbee, LoRaWAN, Cellular |
| Companies Covered | Agicent Technologies, Matellio, Orangesoft, Softeq, Overcode, Intellectsoft, Computools, Intetics, Kanda Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Application Development Services Market Strategic Shifts
Digital twin architectures are migrating from design-phase simulation tools to runtime operational layers, requiring development services to integrate physics-based modeling with live telemetry pipelines. This shift is redefining the boundary between embedded engineering and enterprise software integration.
Digital thread implementations are digitizing the full product lifecycle from CAD geometry through field performance telemetry, enabling automotive and aerospace manufacturers to trace design decisions to operational outcomes. Engineering service providers are embedding PLM connectors into their delivery stacks to capture this workflow integration revenue. Tier-1 suppliers in Germany and Japan are prioritizing vendors with Siemens Teamcenter or Dassault ENOVia certification.
The EU AI Act's risk classification framework for machine learning in safety-critical applications is forcing medical device and industrial automation developers to implement explainability layers and human oversight mechanisms. High-risk system providers must now document training data provenance and model validation protocols before CE marking. This regulatory architecture favors European development shops with established notified body relationships over offshore competitors.
Asset-as-a-service commercial models are compressing hardware procurement cycles and expanding recurring revenue attachments for remote monitoring and predictive maintenance software. German machine tool builders and Japanese robotics OEMs are leading this transition, outsourcing the full stack development of usage-based billing platforms and customer-facing performance dashboards to specialized service partners.
IoT Application Development Services Market Segmentation
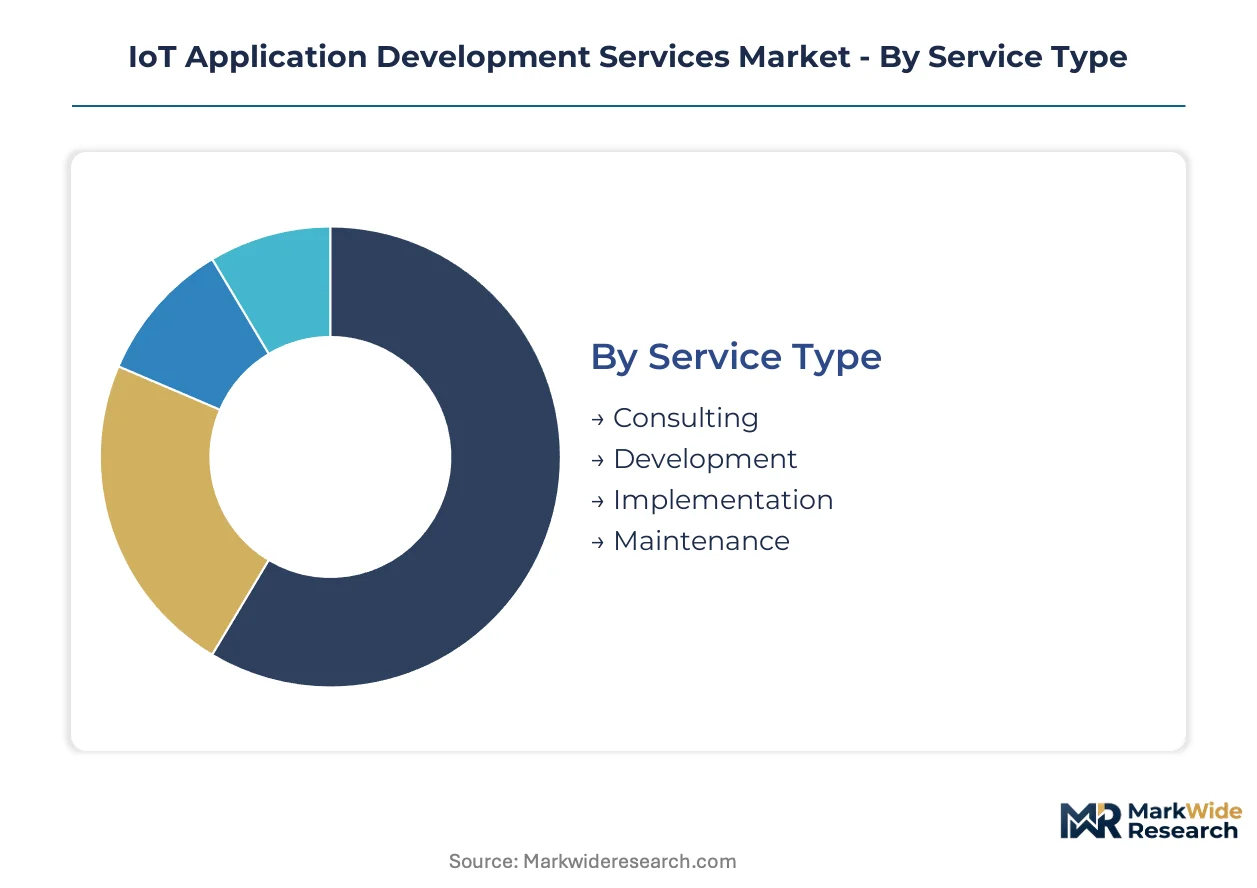
IoT application development services fragment across service delivery modes, infrastructure architectures, and connectivity protocols. Each segmentation axis carries distinct margin profiles and compliance burdens that reshape vendor qualification criteria.
Service Type:
Consulting engagements anchor early-phase customer relationships through regulatory roadmapping and architecture validation.
- Consulting:Pre-engagement assessments cover FDA 510(k) pathway planning, EU Cyber Resilience Act gap analysis, and edge-to-cloud topology design. German automotive suppliers commission these services to align predictive maintenance architectures with BSI baseline security guidelines.
- Development:Full-cycle engineering spans embedded firmware, protocol translation layers, and Kubernetes-native device management platforms. Healthcare providers in North America and Europe concentrate procurement here to satisfy FDA software-as-medical-device validation requirements.
- Implementation:Field deployment and systems integration for production environments.
- Maintenance:Post-market monitoring, security patch management, and firmware update orchestration.
Established volume favors Development; emerging adoption favors Maintenance.
Deployment Model:
Latency budgets and data sovereignty requirements partition infrastructure choices across manufacturing floors and regulated facilities.
- Edge:TensorFlow Lite and ONNX Runtime deployment on ARM Cortex-M55 microcontrollers enables sub-100 millisecond inference for vibration analysis. Japanese machinery OEMs under METI data governance constraints favor this model for acoustic monitoring workloads.
- Cloud:Hyperscaler-native device management with serverless telemetry ingestion and auto-scaling API gateways.
- Hybrid:Split architectures retaining sensitive preprocessing on-premises while pushing aggregated analytics to public infrastructure.
- On-Premises:Air-gapped installations for defense, critical infrastructure, and high-assurance medical environments.
Edge deployment gains share fastest in industrial predictive maintenance; Cloud retains scale advantage in smart home and retail.
End User:
Regulatory intensity and hardware-software integration depth separate margin-rich verticals from subscription-commoditized segments.
- Healthcare:Connected diagnostics and remote patient monitoring demand ISO 13485 quality systems and FDA pre-market validation. EU AI Act risk classifications impose explainability layers and human oversight mechanisms on machine learning components.
- Manufacturing:Predictive maintenance and digital twin implementations in German automotive and machinery sectors drive co-design services bridging operational technology with cloud infrastructure.
- Smart Home:Platform-agnostic subscription models commoditize development toward mass-market hardware integration.
- Retail:Inventory tracking and cold chain monitoring using wireless mesh networks.
Healthcare commands premium pricing through compliance captivity; Manufacturing shows steepest expansion trajectory via digital thread investments.
Technology:
Protocol selection constrains power budgets, range requirements, and interoperability testing scope.
- Cellular:LTE-M and NB-IoT modules provide wide-area coverage for asset tracking and fleet management without gateway infrastructure. Singapore and South Korean smart building retrofits favor this for replacing legacy BACnet systems.
- LoRaWAN:Ultra-low-power wide-area networking for agricultural sensors and utility metering across extended geographies.
- Bluetooth:Short-range personal area networking dominates wearable and medical device peripherals.
- Zigbee:Mesh topology for residential and commercial building automation with self-healing network properties.
Cellular scales through carrier ecosystem partnerships; LoRaWAN penetrates most aggressively in utility and agriculture telemetry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-Cologne rail corridor and Rhine-Ruhr industrial belt underpin Europe's densest concentration of IoT engineering talent, while the Dallas-Fort Worth logistics hub anchors North American device management platform development.
Germany
Automotive OEMs in Stuttgart and Munich commission edge analytics modules for predictive maintenance, driving specialized procurement of operational technology-cloud integration services. The BSI technical guidelines for IoT baseline security reshape vendor qualification criteria. Baden-Württemberg machinery builders outsource firmware hardening to meet EU Cyber Resilience Act obligations.
United States
FDA software-as-medical-device guidance expands the engineering services pool for connected diagnostics and remote patient monitoring. HIPAA compliance requirements and FDA 510(k) pathways concentrate validated development partnerships in Minneapolis medical device corridors and Boston healthcare technology clusters. Texas-based IoT labs anchor North American delivery for industrial clients.
Japan
METI's data governance framework for connected industries creates localized development demand with strict cross-border data flow restrictions. Machinery OEMs under these constraints favor edge deployment models for acoustic monitoring and vibration analysis workloads. Nagoya automotive suppliers and Osaka industrial equipment makers drive co-design service procurement.
China
GB/T standards for IoT interoperability segment vendor qualification requirements for domestic and export-facing manufacturers. The Yangtze River Delta electronics manufacturing belt generates firmware development demand for smart home and wearable device exporters. Shanghai and Shenzhen clusters concentrate hardware-software co-design capabilities.
Singapore
Smart building retrofit programs replacing legacy BACnet systems with IP-native sensor networks generate greenfield commissioning projects. Commercial real estate operators deploy wireless mesh specialists for inventory tracking and cold chain monitoring. The port-city's data residency capabilities attract regional headquarters for Asia-Pacific IoT platform operators.
IoT Application Development Services Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream capturing firmware and edge module economics. The vendor map compresses vertically as cloud hyperscalers embed development capabilities directly into platform stacks, redistributing margin pools from independent service providers. Three archetypes dominate: healthcare compliance specialists, industrial co-design engineers, and hardware-software integration boutiques. Competitive moves concentrate on vertical capability acquisition and geographic delivery hub expansion.
Among North American engineering services providers, Kanda Software and Intellectsoft occupy positions reflecting divergent specialization vectors. Kanda Software anchors delivery through dedicated IoT labs in Austin and Boston, exemplifying the geographic concentration archetype. Intellectsoft represents the vertical specialization model, with positioning shaped by healthcare and logistics sector focus. Softeq competes from the hardware-software co-design tier, serving wearable and medical device makers with integrated firmware and industrial design capabilities. These three patterns—geographic anchoring, vertical deepening, and integration breadth—structure competitive differentiation.
| Leading Market Players |
|---|
| Agicent Technologies |
| Matellio |
| Orangesoft |
| Softeq |
| Overcode |
| Intellectsoft |
| Computools |
| Intetics |
| Kanda Software |
| Others |
Value Chain & Pricing Dynamics
Taiwanese foundry concentration for ARM Cortex-M series microcontrollers anchors margin capture at the semiconductor tier, forcing development services providers to absorb buffer inventory costs or extend project timelines. This upstream bottleneck redistributes pricing power toward chip vendors while compressing service provider margins on fixed-bid firmware engagements.
Pricing Analysis
Volume-discount tiering structures separate enterprise healthcare contracts requiring FDA 510(k) validation support from mid-market industrial projects and commodity smart home integrations. Certification grade and customization depth drive price differentiation, with ISO 13485-audited development commands substantial premiums over standard commercial firmware. Pricing pressure stems from cloud hyperscalers embedding development capabilities into platform subscriptions. Healthcare providers show lowest price sensitivity due to compliance captivity, while smart home OEMs concentrate procurement on lowest-bid hardware integration.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for IoT module sourcing. Component sourcing draws from Taiwan for semiconductors, China for PCB assemblies and sensor modules, and South Korea for memory components. Single-source vulnerability concentrates in specialized secure microcontrollers for medical device applications. Distribution runs through direct OEM relationships for tier-1 automotive and healthcare accounts, with systems integrator channels fragmenting for mid-market industrial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IoT application development services market sits in early-cycle expansion as EU Cyber Resilience Act compliance deadlines force hardware manufacturers to outsource firmware hardening capabilities.
For Market Incumbents: Entrench compliance differentiation by deepening FDA and EU notified body relationships before offshore competitors establish certification credibility. Acquire boutique firmware security shops in Germany and Japan to capture localized regulatory expertise. Cloud hyperscaler embedded-software practices threaten traditional systems integrator margins, making vertical capability acquisition the priority defensive lever.
For New Entrants and Emerging Players: Build out edge AI deployment capabilities for industrial predictive maintenance, where TensorFlow Lite optimization on ARM Cortex-M55 microcontrollers creates specialist white space. Target Japanese machinery OEMs under METI data governance constraints, as cross-border data flow restrictions favor regional engineering partners with domestic data residency. Lead with acoustic monitoring and vibration analysis case studies to establish technical credibility.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed healthcare compliance specialists that have built ISO 13485 quality systems and FDA validation track records. The five-to-ten year viability window favors vendors with established notified body relationships over pure technical capability plays. Monitor EU AI Act enforcement patterns as the inflection signal for explainability-layer development demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | Deepens FDA 510(k) and EU Cyber Resilience Act compliance capabilities for healthcare and industrial clients. |
| Edge AI Capability Acquisition | Captures TensorFlow Lite and ONNX Runtime deployment demand for millisecond-latency industrial inference workloads. |
| Geographic Delivery Hub Expansion | Establishes localized engineering presence in Germany and Japan for data sovereignty-sensitive manufacturing clients. |
| Firmware Security Specialist Acquisition | Addresses secure boot implementation and side-channel attack mitigation talent scarcity constraining team scaling. |
| Digital Thread Platform Integration | Embeds PLM connectors into delivery stacks to capture automotive and aerospace workflow integration revenue. |
Study Parameters
Cross-validation between primary interviews and secondary data sources anchors the qualitative findings in this study. Engineering directors at healthcare device manufacturers, procurement leads at German automotive OEMs, firmware architects at industrial machinery builders, and regulatory affairs specialists at notified bodies provided operational perspective. Secondary validation drew from FDA 510(k) submission databases, EU Cyber Resilience Act implementation guidance, METI policy documents, and hyperscaler IoT platform documentation. Bottom-up project pipeline analysis and top-down market sizing triangulate volume estimates.
Calibration against historical contract values and disclosed project scopes refines the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, deployment architecture, end-user vertical, and connectivity protocol. CAGRs derive from weighted average growth across these segments, with regulatory deadline schedules and semiconductor supply constraints as primary forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by cloud hyperscalers would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Global IoT Routers Market
Internet of Things (IoT)
Global IoT Managed Services Market
Internet of Things (IoT)
North America Industrial IoT Market
Internet of Things (IoT)
Europe IoT Market
Internet of Things (IoT)
Wi-Fi Smart Scale Market
Internet of Things (IoT)
Qatar Internet of Things (IoT) Market
Internet of Things (IoT)
Internet of Everything Market
Internet of Things (IoT)
Industrial IoT Market
Internet of Things (IoT)
Wifi IoT Market
Internet of Things (IoT)
Non-Terrestrial IoT Gateway Hardware and Software Market
Internet of Things (IoT)
Cellular Internet of Things (IoT) Devices Market
Internet of Things (IoT)
IoT Cloud Platform Market
Internet of Things (IoT)
Internet of Things (IoT) in Healthcare Market
Internet of Things (IoT)
IoT in BFSI Market
Internet of Things (IoT)
Private Narrowband IoT Market
Internet of Things (IoT)
Internet of Things in BFSI Market