
 Internet of Things (IoT) in Healthcare Market | 2026-2036
Internet of Things (IoT) in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Internet of Things (IoT) in Healthcare Market Intelligence
The center of care delivery is shifting from traditional hospitals towards home healthcare settings, altering the demand for IoT solutions. Medtronic plc specializes in smart implants and remote monitoring devices for chronic disease management. Koninklijke Philips N.V. competes with integrated platforms that bridge hospital and home care data streams, while Cisco Systems Inc. provides the secure network infrastructure essential for reliable data transmission.
Internet of Things (IoT) in healthcare comprises a network of interconnected medical devices, sensors, and software platforms. These systems collect, transmit, and analyze real-time patient data, often utilizing low-power wide-area networks (LPWAN) for connectivity. Wearable devices and remote patient monitoring systems lead product segment growth. The chronic disease management application commands the largest share, driven by the need for continuous physiological tracking.
Regulatory frameworks like HIPAA in the United States set stringent rules for patient data security. In Europe, the GDPR and Medical Device Regulation (MDR) impose strict consent and interoperability standards on device manufacturers. Navigating these disparate compliance landscapes is a primary challenge. Stakeholders must therefore balance feature innovation against the escalating costs of regulatory adherence and cybersecurity.
Market Dynamics
The fundamental dynamic shaping the IoT in healthcare market is the decentralization of care delivery. This shift from centralized hospital settings to continuous home-based monitoring for chronic conditions directly influences demand for connected, user-friendly medical devices and integrated data platforms.
Growth Catalysts
- Regulatory Standardization:The European Union's Medical Device Regulation (MDR) creates a clear framework for device approval, standardizing data security and interoperability requirements, which clarifies product development pathways for manufacturers.
- LPWAN Connectivity:The expansion of low-power wide-area networks provides reliable, energy-efficient connectivity for remote patient monitoring devices, enabling long-term data collection without frequent battery changes or complex network setups.
- Chronic Disease Management:A higher prevalence of chronic illnesses necessitates continuous physiological monitoring outside of clinical environments, driving patient and provider adoption of wearable sensors and remote tracking systems.
Market Restraints
- High Compliance Costs:The escalating costs of adhering to disparate data security regulations, such as HIPAA in the United States and GDPR in Europe, act as a significant financial barrier for device manufacturers.
- Interoperability Deficits:A lack of universal communication standards between IoT devices from different vendors creates data silos, hindering the creation of a unified patient view for healthcare providers and limiting system-wide value.
- Cybersecurity Vulnerabilities:The proliferation of connected devices expands the potential attack surface for cyber threats, with the risk of data breaches or device manipulation acting as a major deterrent to adoption for risk-averse healthcare organizations.
Strategic Opportunities
- Predictive Analytics Integration:Embedding artificial intelligence and machine learning algorithms into IoT platforms offers the opportunity to move from reactive data collection to predictive analytics for early disease detection and intervention.
- Preventative Wellness Applications:There is a significant opportunity to expand IoT solutions beyond chronic disease into preventative health and wellness monitoring, targeting consumer markets and corporate wellness programs with non-clinical devices.
- Platform-as-a-Service Models:Developing scalable, cloud-based Platform-as-a-Service (PaaS) offerings can address the needs of smaller clinics and independent practices that lack the IT resources to build custom IoT infrastructures.
Industry Challenges
- Legacy System Integration:A primary operational hurdle is the complex and costly process of integrating new IoT data streams with existing and often outdated hospital IT systems, particularly legacy electronic health record (EHR) platforms.
- Data Governance Complexity:Stakeholders face significant challenges in establishing clear data governance policies that manage patient consent, data ownership, and usage rights across a fragmented ecosystem of devices, apps, and cloud services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internet of Things (IoT) in Healthcare Market |
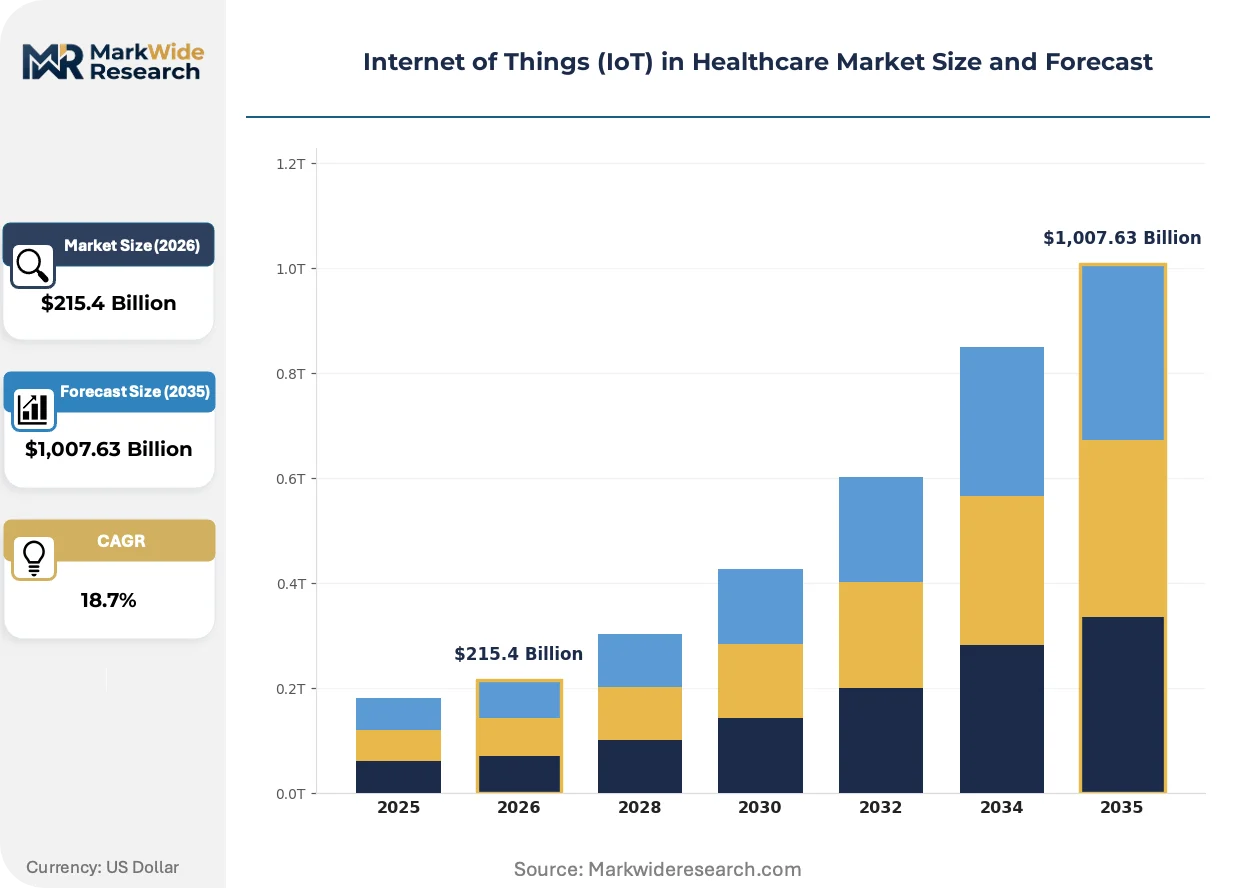
| Market Size in 2026 | $215.4 Billion |
| Market Size in 2035 | $1,007.63 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Connected Medical Devices, Remote Patient Monitoring, Smart Implants, Ambient Assisted Living Devices Application: Chronic Disease Management, Elder Care, Medication Adherence, Fitness & Wellness, Emergency Response End User: Hospitals, Ambulatory Centers, Home Healthcare Providers, Diagnostic Labs, Rehabilitation Clinics Deployment: Cloud-Based Platforms, On-Premises Systems, Hybrid Solutions, Edge Computing |
| Companies Covered | Medtronic plc, Koninklijke Philips N.V., GE Healthcare, Cisco Systems Inc., IBM Corporation, Microsoft Corporation, Siemens Healthineers AG, SAP SE, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internet of Things (IoT) in Healthcare Market Strategic Shifts & Innovations
The industrialization of healthcare data streams is reshaping the market. This evolution moves beyond isolated device deployments toward the creation of scalable, interconnected ecosystems that bridge disparate points of care, from the hospital intensive care unit to the patient's home.
Edge computing represents a significant technological evolution within healthcare IoT. This technology processes sensor data directly on or near the medical device, reducing latency and dependence on centralized cloud infrastructure. Medical device manufacturers are adopting edge capabilities for smart implants and real-time monitors. This trend is modularizing device architecture, separating hardware from software analytics and enabling more rapid, independent innovation cycles for each layer.
Europe's Medical Device Regulation (MDR) establishes a more stringent regulatory environment for connected medical products. Its implementation is forcing manufacturers to generate more extensive clinical evidence and improve post-market surveillance systems. The software-as-a-medical-device (SaMD) and remote monitoring segments are most affected, prompting redesigns to comply with stricter cybersecurity and data management protocols required for CE marking.
Procurement models are evolving as large hospital networks consolidate their purchasing power. These organizations increasingly favor integrated, end-to-end IoT platforms over acquiring standalone point solutions from multiple vendors. This shift disrupts the market for niche device makers while benefiting suppliers who offer comprehensive data aggregation and analytics capabilities. This demand pattern for unified platforms is most visible in the United States healthcare system.
Internet of Things (IoT) in Healthcare Market Segmentation
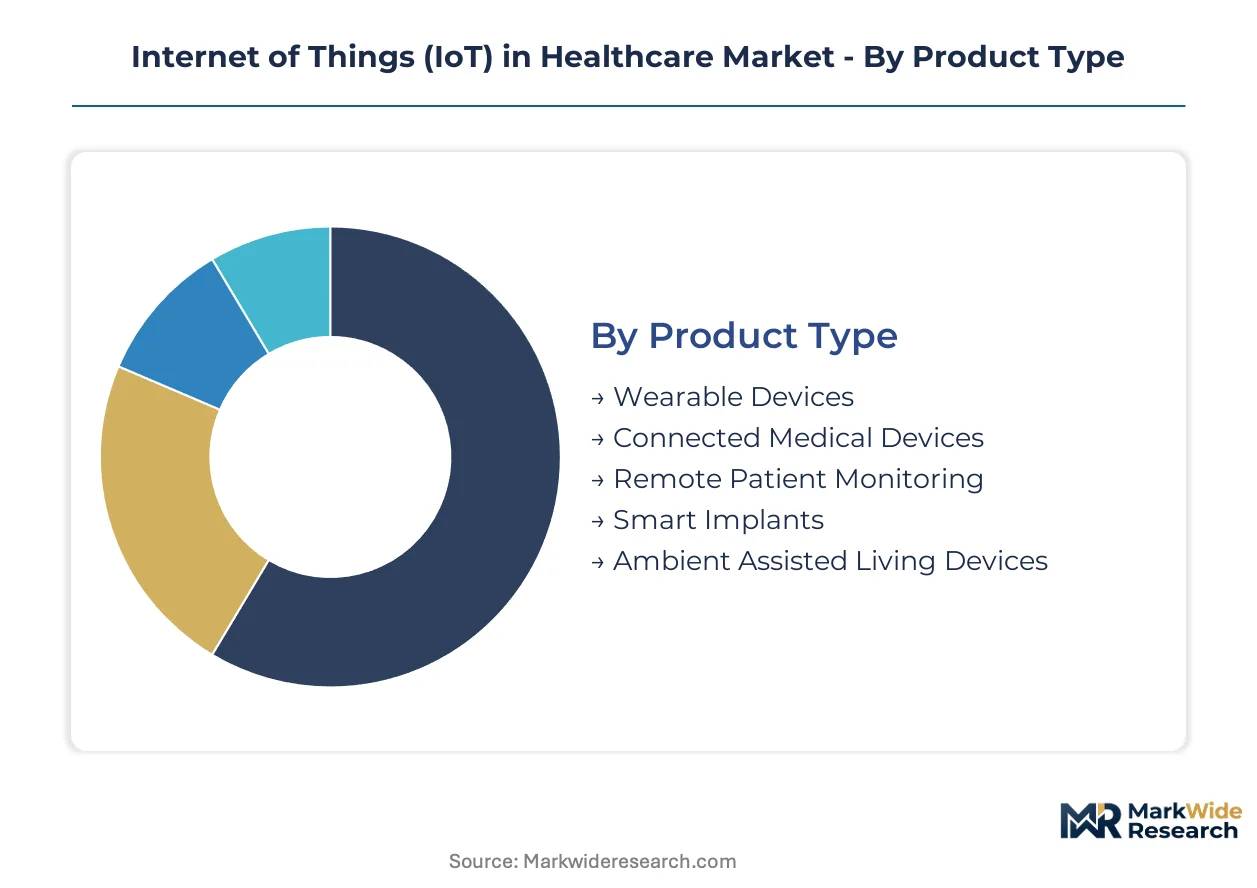
The Internet of Things (IoT) in healthcare market segments across various dimensions, reflecting distinct technological approaches and application areas. Understanding these classifications is crucial for stakeholders to identify specific demand patterns and areas for strategic investment. Each segment addresses particular patient needs or operational challenges within the healthcare ecosystem.
Product Type:
Device selection in IoT healthcare often prioritizes patient comfort and continuous data capture capabilities.
- Wearable Devices:These non-invasive sensors attach to the body, continuously collecting physiological data like heart rate, activity levels, and sleep patterns. Demand concentrates in consumer health and preventative wellness programs, driven by user-friendly interfaces and direct patient engagement.
- Remote Patient Monitoring:These systems track patient health data from outside traditional clinical settings, transmitting information to providers for review. Adoption accelerates in chronic disease management, enabling continuous oversight of conditions like diabetes and hypertension.
- Connected Medical Devices:These are traditional medical instruments equipped with network capabilities for data transmission, enhancing data accuracy and accessibility.
- Smart Implants:These surgically placed devices integrate sensors and communication for long-term physiological monitoring or therapeutic delivery within the body.
- Ambient Assisted Living Devices:These systems use environmental sensors to support elderly or disabled individuals, enhancing safety and independence within their homes.
Volume sits with Wearable Devices; growth tilts toward Remote Patient Monitoring.
Application:
The specific health outcome desired shapes the deployment of IoT solutions across various healthcare applications.
- Chronic Disease Management:This application focuses on continuous physiological tracking and intervention for long-term conditions such as diabetes, heart disease, and COPD. This segment commands the largest market share, driven by the need for proactive care and reduced hospital readmissions.
- Fitness & Wellness:This category includes devices and platforms that monitor general health metrics, exercise, and nutrition for preventative purposes. There is significant opportunity to expand IoT solutions into this consumer market, targeting proactive health maintenance.
- Elder Care:IoT solutions in elder care provide monitoring, fall detection, and communication tools to support independent living for seniors.
- Medication Adherence:These applications use smart dispensers or reminders to ensure patients take prescribed medications on schedule, improving treatment efficacy.
- Emergency Response:IoT devices in this segment can detect critical events like falls or sudden health changes, automatically alerting emergency services or caregivers.
Chronic disease management represents the largest application segment, while preventative wellness applications show steep expansion.
End User:
Healthcare providers adopt IoT based on their operational models and patient interaction frequency, influencing technology procurement.
- Home Healthcare Providers:These organizations deliver medical services directly to patients' residences, leveraging IoT for remote monitoring and virtual consultations. The shift from centralized hospitals to home settings directly influences demand for connected, user-friendly medical devices in this segment.
- Hospitals:Traditional inpatient facilities deploy IoT for asset tracking, patient monitoring within wards, and integrating data from various medical devices. Large hospital networks increasingly favor integrated, end-to-end IoT platforms to streamline operations and enhance patient care.
- Ambulatory Centers:These outpatient facilities use IoT for efficient patient flow management and localized data collection from diagnostic equipment.
- Diagnostic Labs:IoT in diagnostic labs supports automated sample tracking and real-time equipment monitoring, improving operational efficiency.
- Rehabilitation Clinics:These centers utilize IoT wearables and sensors for tracking patient progress during physical therapy and recovery programs.
Home healthcare providers drive significant IoT adoption, with hospitals also investing in integrated platforms.
Deployment:
The technical architecture supporting IoT solutions reflects evolving data processing and security demands from healthcare organizations.
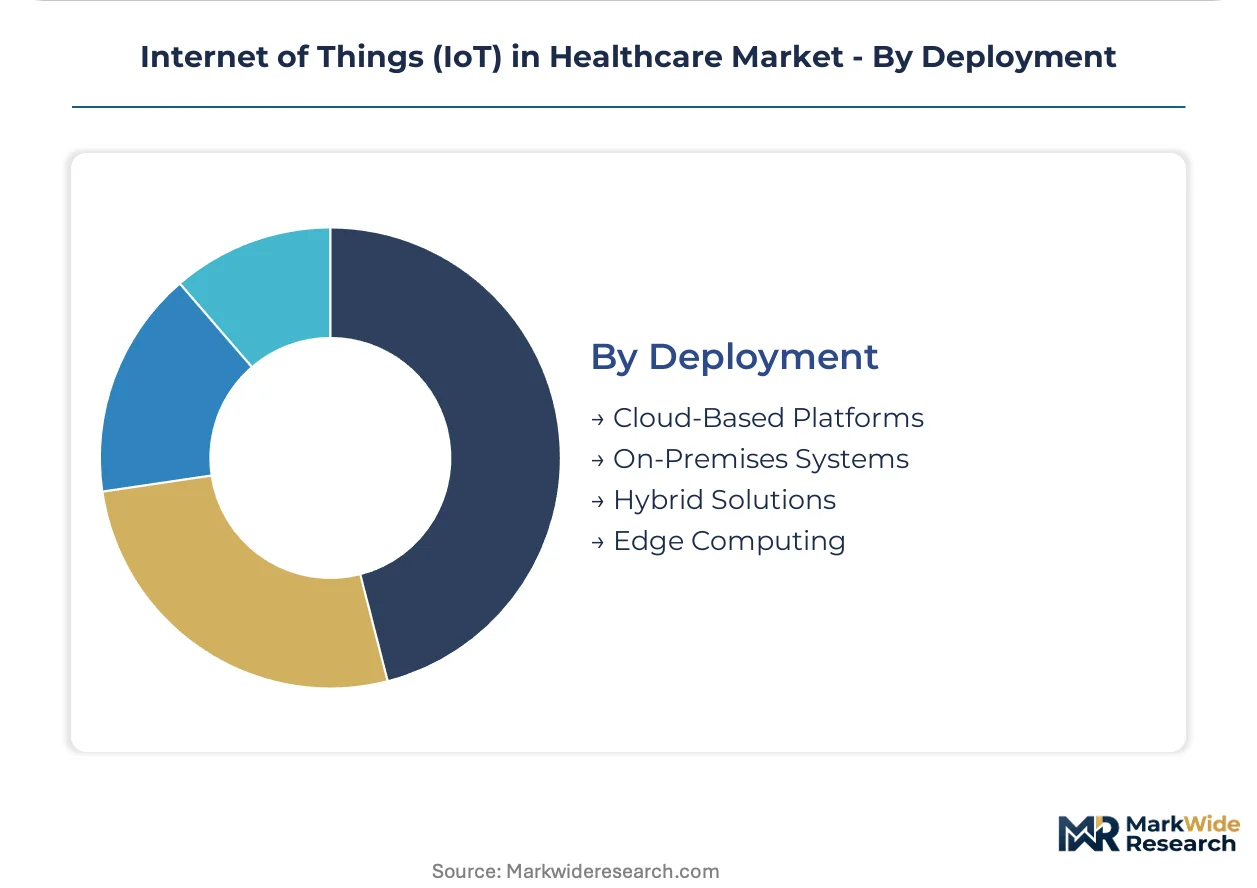
- Cloud-Based Platforms:These solutions host IoT data and analytics on remote servers, offering scalability, accessibility, and reduced infrastructure costs for users. Developing scalable Platform-as-a-Service (PaaS) offerings addresses the needs of smaller clinics lacking extensive IT resources.
- Edge Computing:This technology processes sensor data directly on or near the medical device, reducing latency and dependence on centralized cloud infrastructure. Medical device manufacturers are adopting edge capabilities for smart implants and real-time monitors, enabling faster insights.
- On-Premises Systems:These deployments involve hardware and software hosted within the end-user's physical location, providing maximum control and security over sensitive patient data.
- Hybrid Solutions:These models combine elements of both cloud and on-premises deployment, balancing flexibility with data residency and regulatory compliance requirements.
Cloud-based platforms underpin many IoT deployments, and edge computing solutions are gaining share rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's innovation ecosystem drives significant concentration for IoT in healthcare, fostering new device development and platform integration. This dynamic environment attracts substantial investment into connected medical technologies. The United States healthcare system actively procures integrated IoT platforms from large hospital networks.
United States
Demand for remote patient monitoring and smart implants drives IoT adoption across US healthcare providers. HIPAA sets stringent rules for patient data security, influencing device design and software architecture. Boston's medical technology cluster actively develops AI-powered diagnostic tools for chronic disease management.
Germany
Germany's aging population necessitates advanced elder care solutions and preventative wellness applications. The European Union's Medical Device Regulation (MDR) standardizes data and security requirements for connected devices. Munich's digital health sector focuses on integrating IoT data streams with existing hospital IT systems.
China
A vast patient population and government initiatives for digital health propel the expansion of IoT in healthcare. The NMPA regulates medical devices, including connected health solutions, ensuring product safety and efficacy. Shenzhen's technology hub produces a high volume of wearable health devices for both consumer and clinical use.
Japan
Japan's focus on longevity and home healthcare solutions accelerates demand for ambient assisted living devices. METI supports research and development in medical device technology, including IoT-enabled systems. Tokyo's research institutions are at the forefront of smart implant development for long-term physiological monitoring.
India
Expanding digital infrastructure and a growing middle class increase the accessibility of IoT healthcare solutions in India. The CDSCO regulates medical devices, with new guidelines emerging for digital health products. Bengaluru's tech industry develops scalable cloud-based platforms for remote patient monitoring in rural areas.
Internet of Things (IoT) in Healthcare Market Key Industry Players
Top-tier vendors anchor the integrated platform segment, while niche device makers focus on specialized sensor technologies. The market structure exhibits a tiered consolidation, with established medical technology firms competing alongside technology giants. Strategic archetypes include comprehensive platform providers, specialized device manufacturers, and network infrastructure specialists. Dominant competitive moves involve strategic partnerships for data integration and portfolio diversification into preventative wellness applications.
Within the comprehensive platform providers archetype, Medtronic plc exemplifies leadership in smart implants and remote monitoring devices for chronic disease management. Koninklijke Philips N.V., a Netherlands-based enterprise, further represents integrated platforms bridging hospital and home care data streams, offering solutions that span various care settings. Cisco Systems Inc., a prominent US-based technology firm, occupies a position as a secure network infrastructure specialist, providing the essential backbone for reliable data transmission and cybersecurity across the IoT healthcare ecosystem. These entities collectively shape the industry's strategic direction through their distinct technological contributions.
| Leading Market Players |
|---|
| Medtronic plc |
| Koninklijke Philips N.V. |
| GE Healthcare |
| Cisco Systems Inc. |
| IBM Corporation |
| Microsoft Corporation |
| Siemens Healthineers AG |
| SAP SE |
| Honeywell International |
| Others |
Cost & Logistics Intelligence
Large hospital networks’ preference for integrated, end-to-end IoT platforms over point solutions forces manufacturers to bundle offerings, influencing overall solution pricing. This consolidation of purchasing power shifts negotiation dynamics and emphasizes value-based pricing models.
Pricing Analysis
Premium pricing for short lead times on specialized medical IoT components reflects constrained manufacturing capacity and regulatory hurdles. Subscription-based SaaS models dominate software platforms, offering scalability and continuous updates. Quality grade, particularly FDA or CE marking certification, and after-sales service bundles drive price differentiation. Pricing pressure stems from the high compliance costs associated with disparate regulations like HIPAA and GDPR. Home healthcare providers exhibit the highest price sensitivity for basic monitoring solutions, while large hospital systems prioritize comprehensive platform value.
Supply Chain Analysis
Specialized sensor components supply rests heavily on manufacturers in Germany and Japan, countries known for precision engineering and medical device innovation. Key raw material dependencies include microcontrollers from Taiwan and advanced battery chemistries. Single-source vulnerability for specialized chipsets presents a structural risk to device production timelines. Distribution runs through a tiered model, with global medical technology firms managing direct sales to large hospital networks and regional distributors serving smaller clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Internet of Things in healthcare is undergoing a technology-transition phase, with advanced edge computing solutions increasingly displacing traditional cloud-dependent data processing. This shift enables faster, more secure real-time patient monitoring and analytics.
For Market Incumbents: Extend existing product portfolios through strategic acquisitions of specialized AI and analytics firms to enhance predictive capabilities. Consolidate market position by investing in comprehensive platform integration, addressing the interoperability deficits that hinder broader adoption. The increasing threat from tech giants entering the health space necessitates robust cybersecurity investments to protect patient data. Controlling key intellectual property in smart implant technology remains a critical lever for long-term differentiation.
For New Entrants and Emerging Players: Direct-to-consumer digital channels offer a viable route for introducing preventative wellness applications to a broader user base. Target the underpenetrated preventative health and wellness segment with user-friendly wearable devices focused on non-clinical data. Focus on developing niche SaMD solutions that integrate seamlessly with existing EHR systems, providing value to smaller clinics. A freemium model with premium features for advanced analytics can serve as an effective go-to-market angle.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking to build integrated platforms rather than fragmented device portfolios. Long-term viability hinges on companies that can navigate complex regulatory landscapes like MDR and HIPAA while delivering scalable solutions. Target specialized software-as-a-medical-device (SaMD) firms with strong intellectual property in AI-driven diagnostics. Consistent compliance with evolving data security protocols across multiple geographies serves as a critical signal to watch for sustained growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidating disparate data streams enhances interoperability across hospital and home care settings. |
| CE Marking Pathway | Ensuring compliance with Europe's Medical Device Regulation unlocks access to a significant regional market. |
| AI-Powered Diagnostics Development | Embedding predictive analytics into IoT devices transitions care from reactive to proactive intervention. |
| Cybersecurity Enhancement | Strengthening data protection measures builds trust and mitigates risks for risk-averse healthcare organizations. |
| Home Healthcare Partnership | Collaborating with home care providers expands reach into the growing decentralized care delivery model. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a broad market overview. Primary research involved in-depth interviews with medical device engineers, hospital procurement officers, home healthcare administrators, and regulatory compliance specialists. This approach combined bottom-up market sizing with top-down validation against industry reports. Triangulation across these diverse sources ensured data consistency and reliability.
Market volume and value were modeled at a granular level across product type, application, end-user, and deployment, with specific attention to regional regulatory environments. The analytical framework projected growth across the analysis window by assessing technology adoption curves and competitive intensity. Compound annual growth rates were derived from historical trends and forward-looking market drivers. Key forecast inputs included chronic disease prevalence rates and digital health infrastructure investment.
The model holds under current regulatory stability and projected technological advancements; deviation in cybersecurity threats or major policy shifts would shift market trajectories. Forecasts reflect assumptions documented through extensive primary and secondary research. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Global IoT Solutions and Services Market
Internet of Things (IoT)
Global IOT Connectivity Management Platform (CMP) Market
Internet of Things (IoT)
Europe IoT in Smart Cities Market
Internet of Things (IoT)
Massive IoT Market
Internet of Things (IoT)
IoT for Cold Chain Monitoring Market
Internet of Things (IoT)
Europe Cellular IoT Market
Internet of Things (IoT)
Global IoT Routers Market
Internet of Things (IoT)
North America IoT Software Market
Internet of Things (IoT)
IoT in Energy Market
Internet of Things (IoT)
Solar Based Internet of Things (IoT) Market
Internet of Things (IoT)
Bluetooth Smart Plugs Market
Internet of Things (IoT)
LPWAN in the Consumer IoT Market
Internet of Things (IoT)
Global IoT Battery Market
Internet of Things (IoT)
Smart Home M2M Market
Internet of Things (IoT)
IoT Smart Poles Market
Internet of Things (IoT)
Global IoT in Warehouse Market