
 North America Narrowband-Internet of Things (NB-IoT) Market | 2026-2036
North America Narrowband-Internet of Things (NB-IoT) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Narrowband-Internet of Things (NB-IoT) Market Analytics
The LPWAN technology stack is fragmenting as NB-IoT, LTE-M, and unlicensed alternatives diverge across power-budget and latency requirements. Verizon Communications Inc. leverages its nationwide LTE infrastructure to anchor NB-IoT coverage in dense urban corridors. AT&T Inc. competes through integrated platform services that bundle connectivity with device management portals. Qualcomm Technologies, Inc. specializes in modem silicon that sustains multi-mode operation across NB-IoT and Cat-M1 standards.
North America Narrowband-Internet of Things (NB-IoT) denotes a 3GPP-standardized cellular technology operating in licensed spectrum below one megahertz channel bandwidth, optimized for intermittent data transmission from battery-constrained endpoints with receive sensitivity reaching minus one hundred thirty decibel-milliwatts. Its primary commercial purpose centers on enabling decade-long sensor deployments without maintenance cycles across meter reading, asset tracking, and environmental monitoring applications. The smart cities end-user segment leads current deployment volumes as municipalities retrofit streetlighting and waste management infrastructure with connected nodes. Deployment type preferences increasingly favor hybrid architectures that combine public carrier coverage with private campus networks for industrial automation sites requiring localized control.
The FCC governs spectrum licensing and device certification under Part fifteen and Part twenty-seven rules that determine which frequency bands NB-IoT modules may occupy across the United States. Industry Canada and Mexico's IFT coordinate parallel allocations that enable cross-border roaming and harmonized equipment approval throughout North America. The NIST cybersecurity framework shapes enterprise procurement criteria for connected infrastructure, particularly in healthcare and utility verticals where data integrity carries operational risk. Stakeholders must monitor 3GPP Release eighteen specifications and corresponding carrier certification timelines to align product roadmaps with evolving power-saving and positioning capabilities.
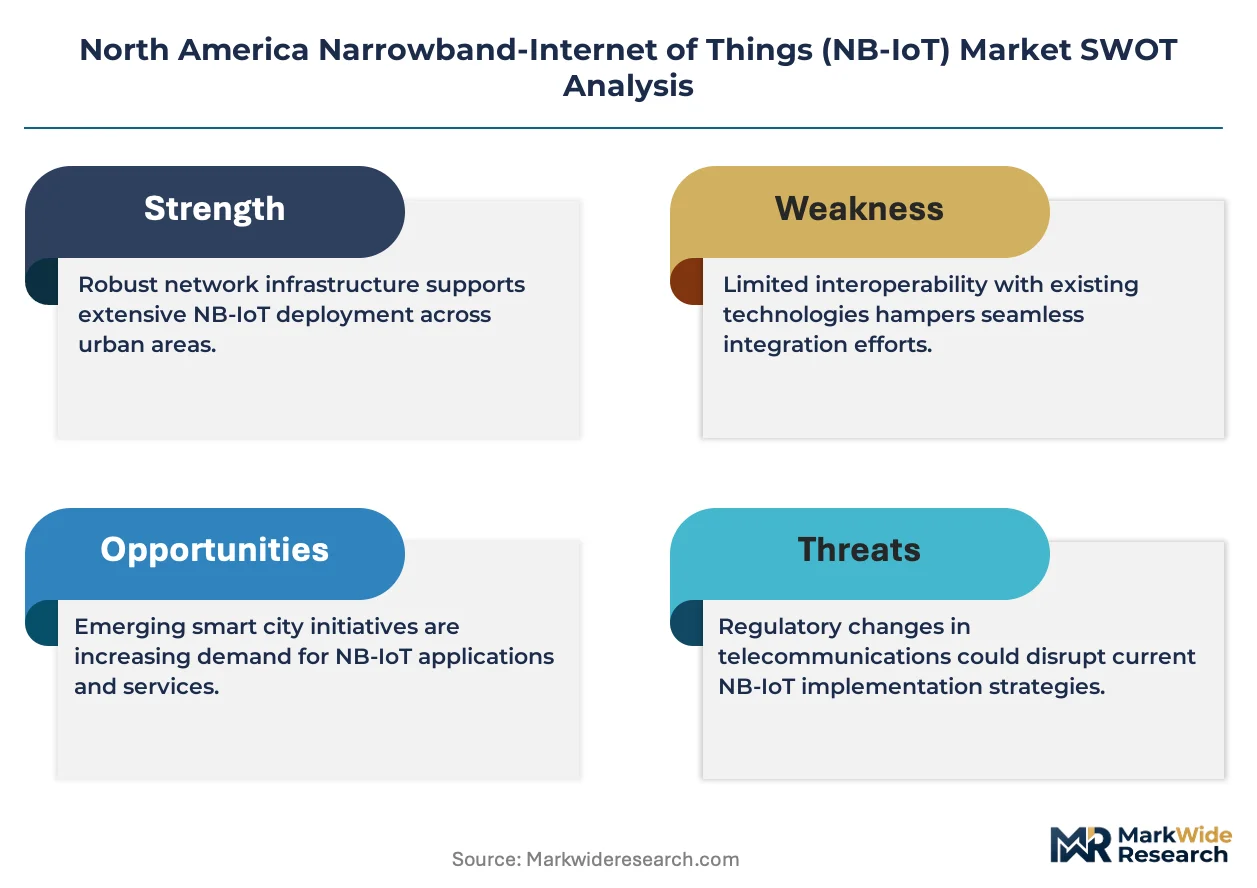
Market Dynamics
The FCC's spectrum reallocation for low-power wide-area networks is compressing carrier deployment timelines and forcing equipment vendors to recertify modules for newly opened guard bands, accelerating a technology transition that favors multi-mode silicon over single-standard designs.
Growth Catalysts
- Smart Agriculture Expansion:Soil moisture and livestock tracking deployments across the Midwest are scaling sensor density per acre, creating sustained module demand from precision farming operations.
- FCC Part 27 Harmonization:Unified device certification rules across the United States, Canada, and Mexico enable cross-border roaming and reduce manufacturer compliance costs for North American product lines.
- Industrial Automation Retrofit:Factory floors in Texas and Illinois are replacing wired sensor infrastructure with battery-operated NB-IoT nodes to eliminate conduit installation and enable rapid line reconfiguration.
Market Restraints
- Licensed Spectrum Cost Structure:Annual carrier subscription fees per endpoint exceed total hardware cost over a ten-year deployment, compressing project ROI for high-density municipal sensor networks.
- Module Supply Concentration:Qualcomm and MediaTek control substantially all cellular IoT baseband silicon, creating single-source risk for North American equipment vendors during fab allocation cycles.
- LTE-M Substitution Threat:AT&T and Verizon prioritize Cat-M1 for voice-capable and mobility-use cases, diverting R&D investment from NB-IoT-specific feature development.
Strategic Opportunities
- Private Campus Networks:Industrial sites in California's Central Valley are deploying hybrid architectures combining carrier coverage with localized 3GPP Release 17 private cells for sub-ten-millisecond control loops.
- Healthcare Asset Tracking:NIST cybersecurity framework compliance is opening hospital procurement channels for patient-worn monitors and infusion pump locators requiring encrypted licensed spectrum.
- 3GPP Release 18 Positioning:Sub-meter accuracy without GNSS power draw is enabling new theft-recovery and yard-management applications for construction and logistics equipment.
Industry Challenges
- RF Engineering Talent Scarcity:Design of efficient antenna matching networks for sub-gigahertz licensed bands requires specialized expertise concentrated among a shrinking pool of cellular modem architects.
- PTCRB Certification Bottlenecks:Queue times for North American carrier acceptance testing extend hardware release schedules by four to six months, delaying revenue recognition for seasonal deployment windows.
- Legacy SCADA Integration:Utility metering projects require protocol translation between Modbus and CoAP stacks, adding software complexity and field commissioning cost to brownfield installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Narrowband-Internet of Things (NB-IoT) Market |
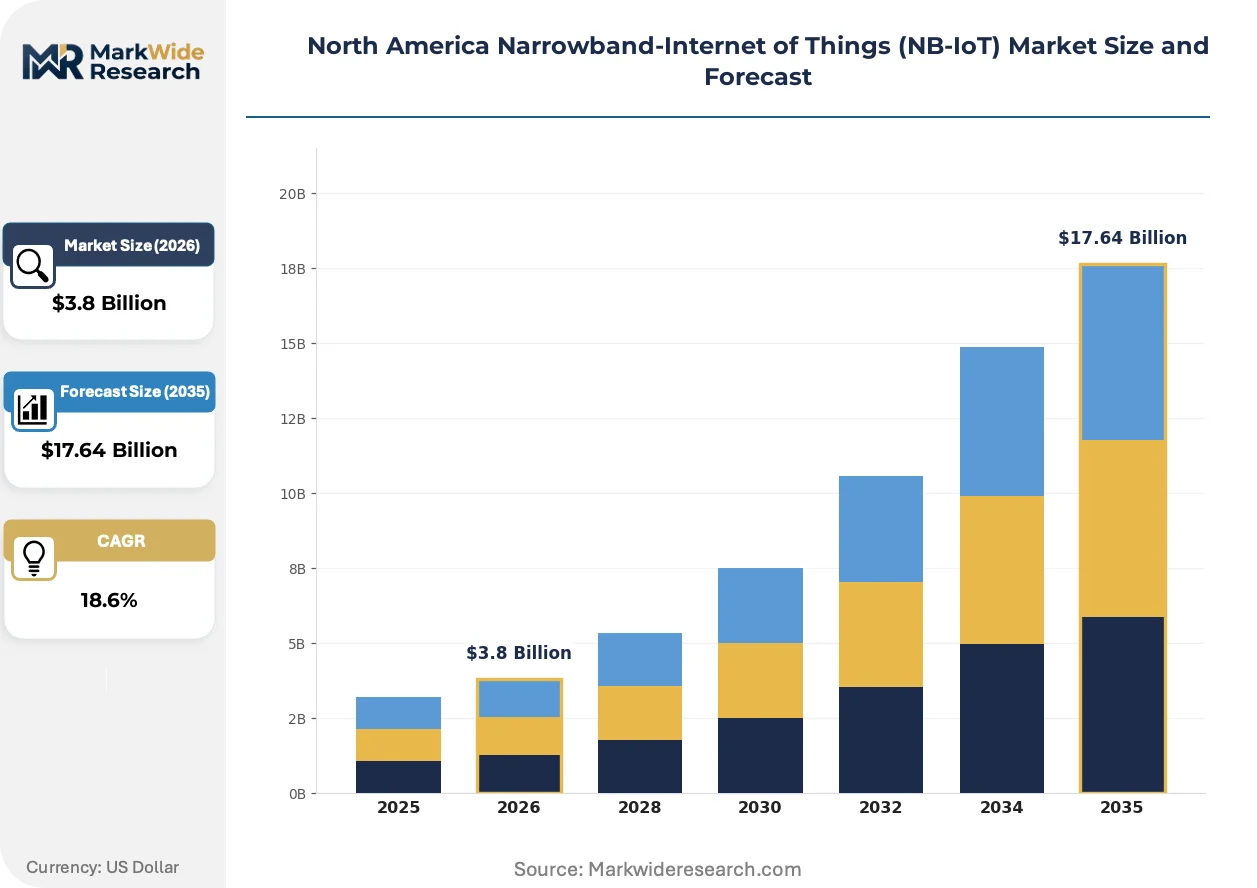
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: 3GPP Releases, LTE-M, NB-IoT, Cat-M1 End User: Smart Agriculture, Smart Cities, Healthcare, Industrial Automation Deployment Type: Public Network, Private Network, Hybrid Network, Managed Network Service Type: Connectivity Services, Platform Services, Device Management, Security Services |
| Companies Covered | Verizon Communications Inc., AT&T Inc., Cisco Systems, Inc., Sierra Wireless, Nokia Corporation, Qualcomm Technologies, Inc., Intel Corporation, Telefonaktiebolaget LM Ericsson, MediaTek Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Narrowband-Internet of Things (NB-IoT) Market Evolving Landscape
NB-IoT module architecture is hybridizing with adjacent connectivity standards, creating multi-mode silicon that adapts to regional spectrum availability and application latency requirements without hardware swaps.
Multi-mode modem silicon is hybridizing NB-IoT and LTE-M baseband processing onto single-chip designs with dynamic protocol selection. Agricultural OEMs in the Midwest are specifying these modules to simplify SKU management across carrier coverage footprints. This convergence is compressing pure-play NB-IoT silicon margins while expanding addressable endpoint volume for flexible hardware platforms.
FCC Part 15 and Part 27 rulemakings are expanding available guard band spectrum below one gigahertz for unlicensed adjacent operation. Equipment manufacturers must redesign front-end filtering to prevent adjacent-channel interference in these newly opened allocations. Smart city vendors in Texas municipalities are piloting dual-use modules that sense spectrum occupancy before transmission.
Buyer preference is rotating toward connectivity-as-a-service contracts that bundle hardware, carrier subscription, and cloud platform access into per-endpoint monthly fees. Municipal procurement departments in Illinois are displacing capital-expense sensor purchases with operational-expense service agreements. This shift transfers technology obsolescence risk from city IT departments to system integrators and compresses hardware vendor direct sales cycles.
North America Narrowband-Internet of Things (NB-IoT) Market Segmentation
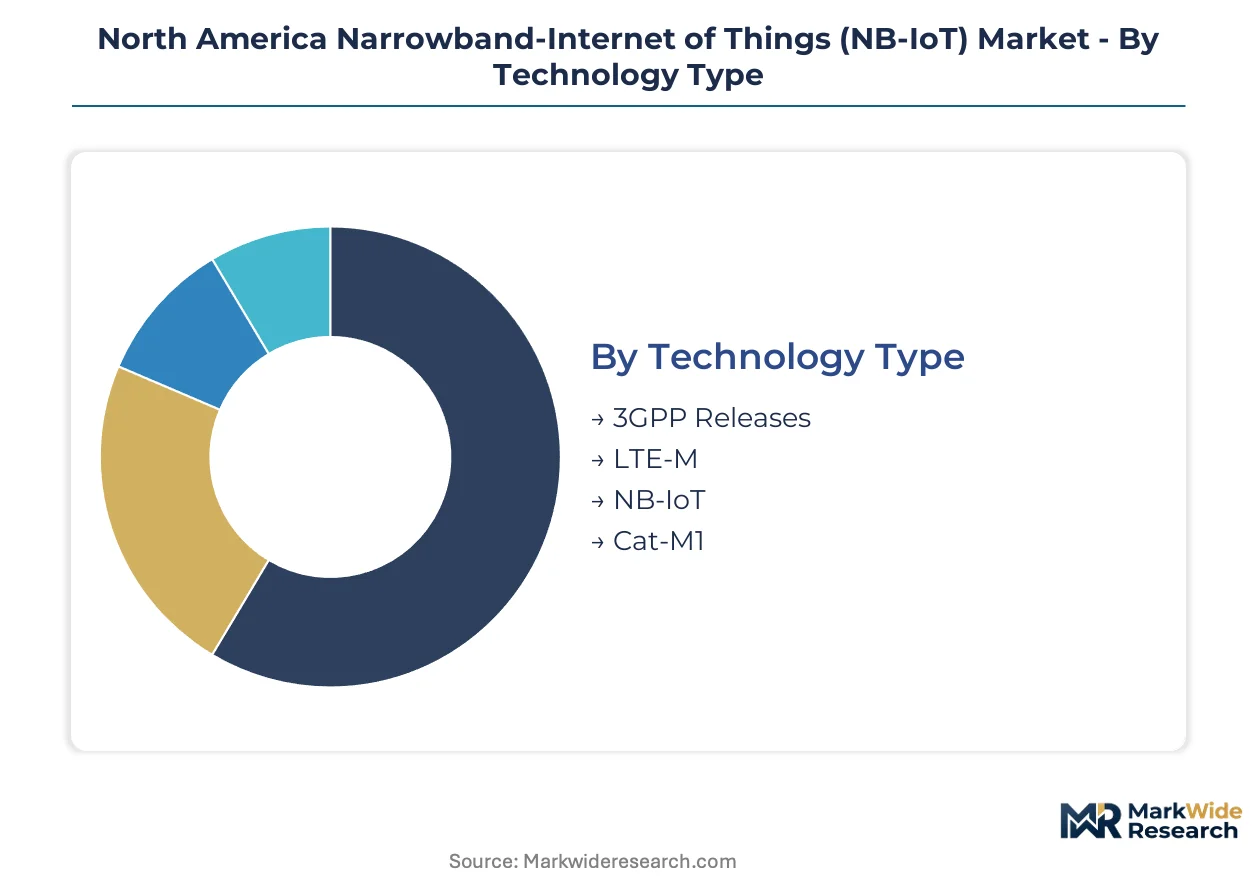
NB-IoT market segmentation reveals distinct service intensity patterns across technology generations and deployment architectures. Procurement patterns diverge sharply between municipal buyers seeking long-term operational contracts and industrial purchasers prioritizing private campus control.
Technology Type:
After-sales service intensity varies dramatically across protocol generations, with newer 3GPP releases demanding firmware update subscriptions and legacy Cat-M1 requiring minimal ongoing vendor engagement.
- 3GPP Releases:Successive 3GPP specifications introduce power-saving mode enhancements and positioning accuracy improvements that require carrier-coordinated firmware deployment. Agricultural OEMs in the Midwest prioritize Release 17 modules for their reduced sleep-mode current draw during extended field deployments.
- NB-IoT:The narrowband standard operates in 180 kHz channels with peak data rates below 250 kbps, optimized for sensor payloads under 200 bytes. Texas utility metering projects specify NB-IoT for its superior building-penetration loss characteristics compared to higher-bandwidth alternatives.
- LTE-M:Cat-M1 delivers mobility support and voice capability through 1.4 MHz channels, expanding addressable use cases beyond static sensor applications.
- Cat-M1:This mid-rate standard enables firmware-over-the-air updates and TCP/IP socket connections that pure NB-IoT cannot support.
NB-IoT holds the largest share; momentum sits with 3GPP Releases as carrier certification timelines align with agricultural deployment windows.
End User:
Volume concentration and margin profiles diverge across verticals, with healthcare procurement cycles extending 18-24 months while agricultural purchases follow seasonal planting schedules.
- Smart Agriculture:Soil moisture probes and livestock collar deployments across Illinois and Iowa corn belts drive module demand with extreme temperature tolerance requirements. Midwest cooperatives specify IP67-rated hardware for field longevity without maintenance access.
- Smart Cities:Municipal streetlighting retrofits and waste bin fill-level monitoring concentrate deployment volume in California and Texas urban corridors. Chicago's smart streetlight program exemplifies the shift from capital procurement to connectivity-as-a-service contracting.
- Healthcare:Patient-worn monitors and infusion pump locators require NIST cybersecurity framework compliance and encrypted licensed spectrum.
- Industrial Automation:Factory floors in Detroit and Houston replace wired sensor infrastructure with battery-operated nodes for rapid line reconfiguration.
Smart Cities holds the largest share; momentum sits with Smart Agriculture as precision farming operations scale sensor density per acre.
Deployment Type:
Customer type and control requirements shape architecture selection, with municipal buyers accepting public carrier dependency while industrial sites demand localized network sovereignty.
- Public Network:Carrier-operated infrastructure eliminates upfront capital expenditure and transfers spectrum licensing burden to Verizon or AT&T. Illinois municipalities favor this model for its predictable operational budgeting and zero RF engineering staffing requirements.
- Private Network:Localized 3GPP Release 17 cells deliver sub-ten-millisecond latency for industrial control loops that public networks cannot guarantee. California Central Valley food processing plants deploy private cells to isolate critical sensor traffic from carrier congestion.
- Hybrid Network:Dual-mode architectures combine wide-area carrier coverage with campus-local private cells for seamless indoor-outdoor asset tracking.
- Managed Network:System integrators assume operational responsibility for private infrastructure, bridging the expertise gap for mid-sized industrial facilities.
Public Network holds the largest share; momentum sits with Hybrid Network as industrial sites seek coverage continuity without full private infrastructure investment.
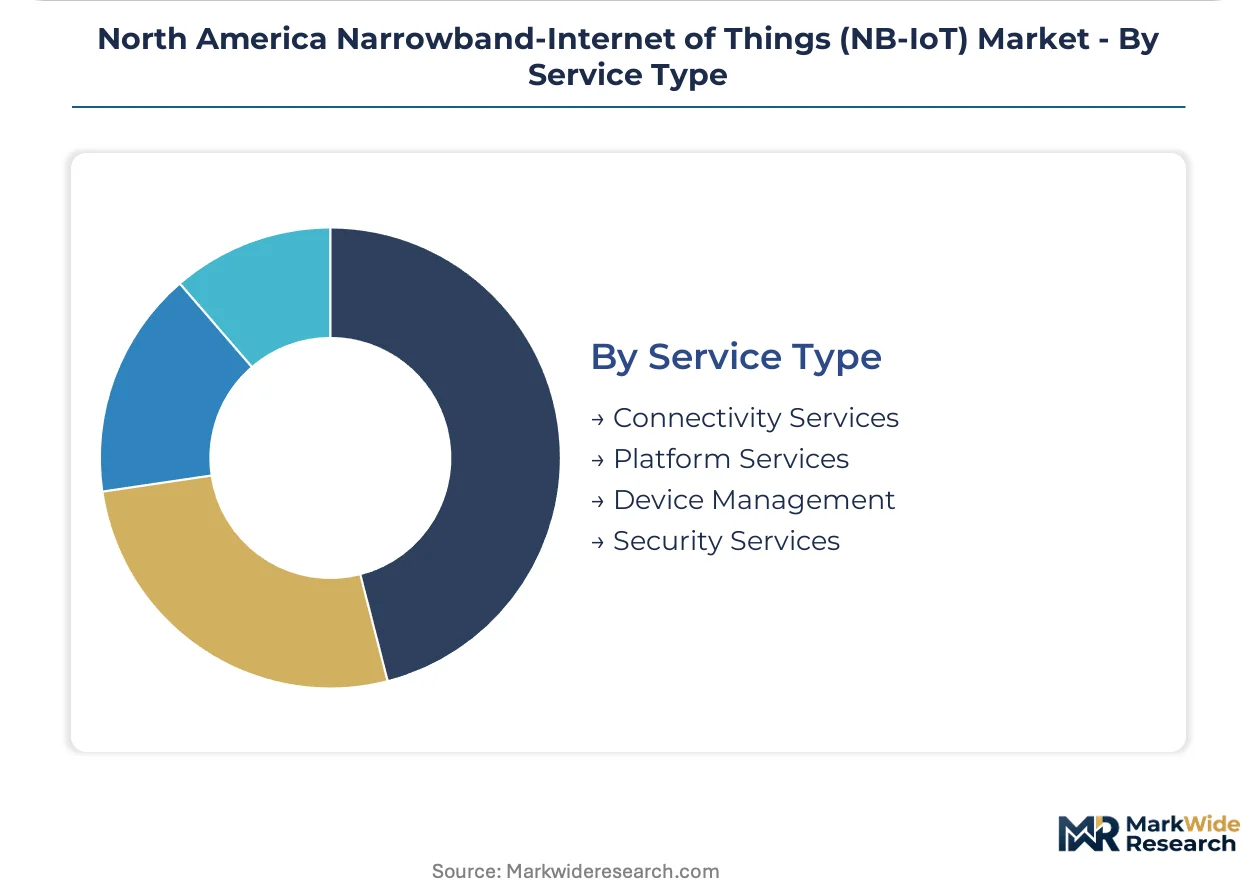
Service Type:
Supply concentration and margin capture shift across the value stack, with hardware vendors ceding recurring revenue to platform providers and managed security services.
- Connectivity Services:Carrier subscription fees per endpoint dominate ten-year total cost of ownership and compress hardware vendor margins. AT&T's bundled platform services capture recurring revenue streams that pure module sales cannot match.
- Platform Services:Device management portals and cloud analytics layers aggregate sensor data for municipal dashboard visualization. Texas smart city vendors specify platform-agnostic APIs to prevent carrier lock-in during contract renewal cycles.
- Device Management:Firmware lifecycle management and remote diagnostics reduce truck-roll costs for dispersed agricultural deployments.
- Security Services:Encrypted transport and certificate lifecycle management address NIST framework requirements for healthcare and utility verticals.
Connectivity Services holds the largest share; momentum sits with Platform Services as buyers prioritize operational expenditure models over capital hardware purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal procurement departments and industrial automation buyers concentrate NB-IoT demand across three North American jurisdictions, with deployment preferences diverging between public carrier dependency and private campus sovereignty.
United States
Texas utility metering projects and California smart city retrofits drive module volume, with Chicago's streetlight program exemplifying connectivity-as-a-service contracting. FCC Part 15 and Part 27 spectrum rulemakings expand guard band availability below one gigahertz. Illinois municipalities favor public network architectures for predictable operational budgeting without RF engineering staffing.
Canada
Prairie province agricultural cooperatives specify IP67-rated hardware for extreme temperature field deployments across Saskatchewan and Manitoba corn belts. Industry Canada coordinates spectrum allocations with FCC harmonization to enable cross-border equipment certification. Toronto-area smart city vendors pilot dual-use modules sensing spectrum occupancy before transmission.
Mexico
Central Valley food processing plants deploy hybrid network architectures combining carrier coverage with localized private cells. IFT spectrum coordination with FCC and Industry Canada enables harmonized equipment approval throughout North America. Nuevo León industrial automation sites retrofit factory floors with battery-operated sensor nodes eliminating conduit installation.
North America Narrowband-Internet of Things (NB-IoT) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a structure where carrier-operated infrastructure and silicon module vendors capture divergent value chain positions. National wireless operators leverage licensed spectrum ownership to anchor recurring subscription revenue, while equipment manufacturers concentrate on multi-mode modem designs. Two strategic archetypes dominate: integrated platform providers bundling connectivity with device management, and component specialists supplying baseband silicon across carrier certification timelines. Competitive moves center on spectrum harmonization advocacy and multi-standard silicon roadmaps that reduce single-technology risk.
Within the carrier archetype, Verizon Communications Inc. and AT&T Inc. occupy positions defined by nationwide LTE infrastructure ownership and bundled service portfolios. Qualcomm Technologies, Inc. anchors the silicon tier, with its modem designs sustaining multi-mode operation across NB-IoT and Cat-M1 standards. These three entities exemplify how channel control and component supply concentrate influence over deployment timelines and certification requirements.
| Leading Market Players |
|---|
| Verizon Communications Inc. |
| AT&T Inc. |
| Cisco Systems, Inc. |
| Sierra Wireless |
| Nokia Corporation |
| Qualcomm Technologies, Inc. |
| Intel Corporation |
| Telefonaktiebolaget LM Ericsson |
| MediaTek Inc. |
| Others |
Value Network & Pricing Analysis
Qualcomm's near-monopoly on cellular IoT baseband silicon concentrates upstream margin capture in San Diego, forcing North American module vendors to accept thin hardware spreads while carriers extract recurring subscription rents downstream.
Pricing Analysis
Cost-plus contracts with semiconductor foundries index wafer starts to trailing twelve-month average utilization rates, compressing module vendor margins when fab capacity tightens. Pricing stratifies across premium, standard, and economy tiers based on carrier certification tier and firmware customization depth. Cost compression in economy-grade modules intensifies because MediaTek's entry-level silicon forces price matching. Municipal buyers exhibit highest price sensitivity due to connectivity-as-a-service contract structures, while healthcare procurement shows lowest sensitivity owing to NIST cybersecurity compliance requirements.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for NB-IoT module manufacturers assembling in Mexico or Southeast Asia. Taiwan and South Korea anchor front-end wafer processing, while Malaysia and Vietnam handle backend test and module integration. Raw material dependencies include gallium arsenide substrates, high-purity silicon wafers, and ceramic filter components. Single-source vulnerability concentrates in Qualcomm's baseband silicon during fab allocation cycles. Distribution runs through carrier-direct procurement channels for public network deployments and system integrator relationships for private campus installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against LTE-M's voice-capable mobility use cases, which threaten to divert carrier R&D investment and module vendor attention from pure NB-IoT feature development.
For Market Incumbents: Pre-empt LTE-M substitution by accelerating 3GPP Release 18 positioning feature certification through PTCRB queues before rival standards capture mobility-sensitive applications. Backward integration into antenna matching network design addresses RF engineering talent scarcity concentrated among retiring cellular modem architects. Carrier partnership depth remains the priority lever for securing firmware update subscription revenue streams.
For New Entrants and Emerging Players: Mexico's Central Valley food processing corridor offers underpenetrated demand for hybrid network architectures combining carrier coverage with localized private cells. Private campus network deployment expertise represents the most penetrable segment given industrial automation retrofit momentum across Nuevo León factory floors. A go-to-market angle anchored to managed network service bundling bypasses direct carrier competition and captures operational expenditure procurement preferences.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed system integrators holding connectivity-as-a-service contracts with Illinois municipalities and Texas smart city vendors. Long-term viability hinges on multi-mode silicon roadmap execution across the five-to-ten year technology transition window. The signal to watch is 3GPP Release 18 carrier certification timeline acceleration as an inflection indicator for positioning-enabled application expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Mode Silicon Roadmap Execution | Qualcomm's dual-protocol designs reduce single-technology obsolescence risk for agricultural OEMs. |
| Private Campus Network Deployment | California Central Valley food processors demand sub-ten-millisecond latency for critical control loops. |
| Carrier Certification Acceleration | PTCRB queue compression secures seasonal agricultural deployment windows before planting cycles. |
| Platform Services Bundling | AT&T's integrated portals capture recurring revenue streams pure module vendors cannot match. |
| Spectrum Harmonization Advocacy | FCC Part 27 alignment with Industry Canada and IFT reduces cross-border equipment compliance costs. |
Research Methodology
A standing panel of carrier network planning executives, agricultural OEM procurement directors, municipal IT managers, and PTCRB certification engineers provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against FCC rulemaking dockets, 3GPP specification releases, carrier capex disclosures, and NIST cybersecurity framework updates. Bottom-up module shipment estimates triangulated against top-down carrier subscription revenue models.
Scenario-bracketing framed demand projections across conservative, baseline, and aggressive technology adoption paths throughout the analysis window. Segmentation dimensions modeled include technology type, end-user vertical, deployment architecture, and service tier. CAGRs derived from logistic diffusion curves fitted to historical cellular IoT adoption patterns. Industry-specific forecast inputs incorporated seasonal agricultural planting schedules and municipal budget cycle phasing.
The forecast holds incumbent behavior within observed patterns; aggressive moves by unlicensed LPWAN technology providers or satellite IoT entrants would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
North America IoT Device Market
Internet of Things (IoT)
IoT Communication Protocol Market
Internet of Things (IoT)
North America IoT Node and Gateway Market
Internet of Things (IoT)
IoT Market
Internet of Things (IoT)
South Africa IoT Market
Internet of Things (IoT)
Industrial Internet of Things (Iiot) Market
Internet of Things (IoT)
Airport Internet of Things Market
Internet of Things (IoT)
Connected IoT Devices Market
Internet of Things (IoT)
Smart Remote Market
Internet of Things (IoT)
Smart Pool Systems Market
Internet of Things (IoT)
Healthcare M2M Market
Internet of Things (IoT)
Internet of Things (IoT) Market
Internet of Things (IoT)
LTE IoT Market
Internet of Things (IoT)
Europe IoT Services Market
Internet of Things (IoT)
Smart Sound and Gateway Market
Internet of Things (IoT)
UK IoT Software Market