
 Enterprise IoT Market | 2026-2036
Enterprise IoT Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise IoT Market Intelligence
Industrial-grade security certification is bifurcating the competitive landscape into compliant and non-compliant supplier tiers. Cisco Systems, Inc. leverages its networking heritage to dominate edge-to-cloud connectivity architectures for factory floors. Siemens AG anchors its position through deep manufacturing domain expertise and captive automation hardware ecosystems. Microsoft Corporation extends its cloud footprint by integrating Azure IoT with enterprise ERP workflows at scale.
Enterprise IoT comprises networked sensors, actuators, and embedded systems operating over IP-based protocols with sub-100 millisecond latency requirements, designed to automate asset monitoring and predictive maintenance across distributed facilities. Cloud-based deployment models are capturing the fastest expansion as manufacturers abandon capital-intensive on-premises server farms. Security solutions command premium pricing due to escalating ransomware exposure, while data analytics layers accumulate the deepest margin pools through recurring software licensing. Device management remains operationally critical but structurally commoditized as hardware margins compress.
The EU AI Act imposes conformity assessments on autonomous IoT decision systems, while the NIS2 Directive mandates incident reporting thresholds for critical infrastructure operators. Germany's BSI and France's ANSSI enforce divergent national cybersecurity certification schemes that fragment procurement standards across member states. Stakeholders must monitor regulatory divergence between European and North American compliance frameworks when architecting cross-border deployment strategies.
Market Dynamics
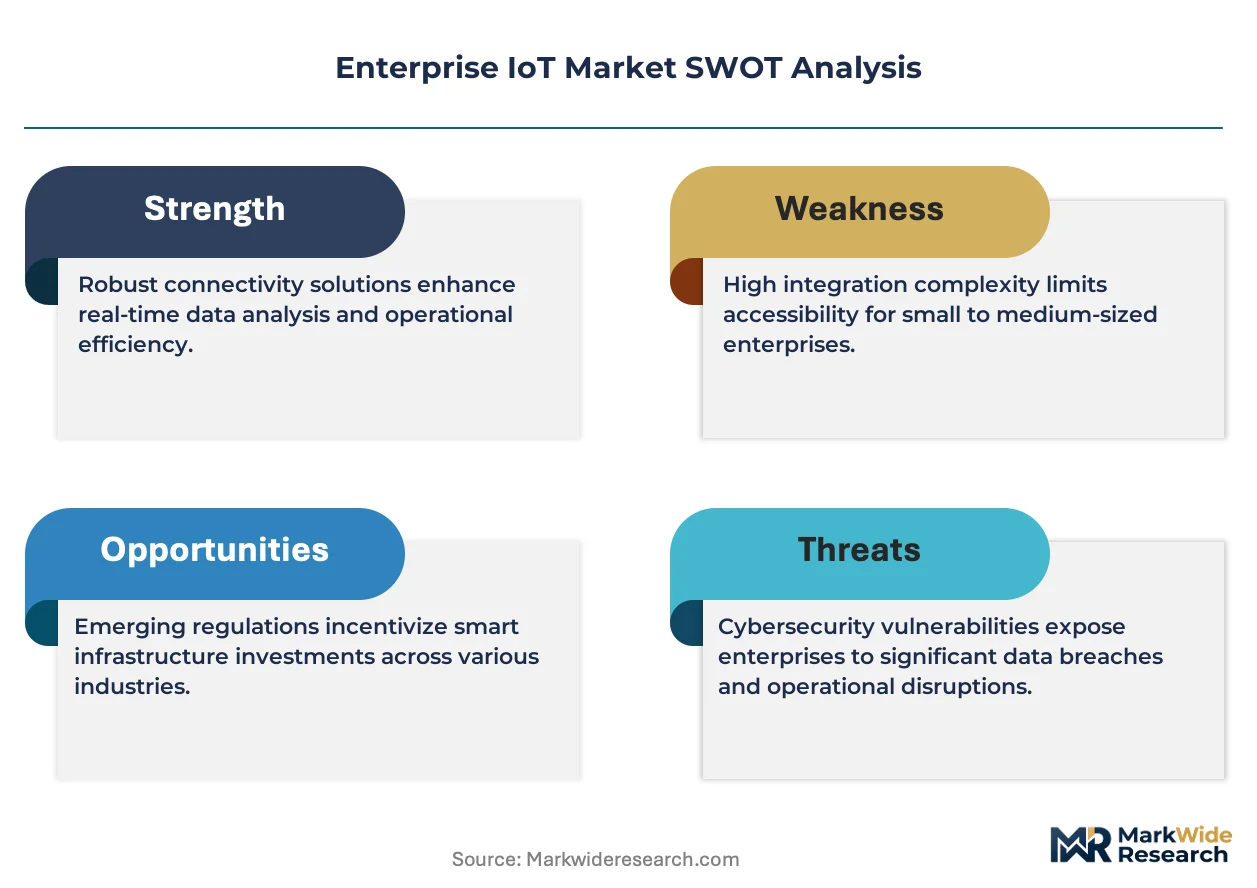
The EU AI Act and NIS2 Directive are forcing manufacturers to rebuild their connected device architectures around mandatory conformity assessments and incident reporting thresholds. This regulatory compression is accelerating consolidation among suppliers capable of delivering certified security stacks.
Growth Catalysts
- Smart Manufacturing Sensor Deployments:Automotive and machinery producers across Germany's Ruhr industrial cluster are digitizing production lines with networked actuators and predictive maintenance systems.
- EU NIS2 Directive Mandates:Critical infrastructure operators must now implement standardized cybersecurity frameworks, creating procurement pull for compliant IoT architectures.
- Edge-to-Cloud Connectivity Architectures:Factory floors demand sub-100 millisecond latency protocols, driving replacement cycles for legacy fieldbus networks with IP-based embedded systems.
Market Restraints
- Semiconductor Supply Concentration:Advanced sensor fabs cluster in Taiwan and South Korea, exposing European manufacturers to single-point failure risks during geopolitical disruptions.
- Certification Timeline Friction:Germany's BSI and France's ANSSI enforce divergent national cybersecurity schemes, fragmenting procurement standards and extending product validation cycles.
- Legacy System Integration Costs:Brownfield manufacturing facilities face capital-intensive retrofitting to connect proprietary automation hardware with open IoT protocols.
Strategic Opportunities
- Cloud-Based Deployment Models:Manufacturers are abandoning on-premises server farms, opening recurring revenue streams for managed IoT platform providers.
- Data Analytics Layer Monetization:Software licensing for predictive maintenance algorithms accumulates deeper margin pools than commoditized device management services.
- India's PLI Scheme for Electronics:Production-linked incentives are attracting component manufacturers to establish captive sensor assembly capacity outside concentrated Asian supply nodes.
Industry Challenges
- Embedded Security Engineering Talent Scarcity:Firmware developers with hardware-level cryptography expertise command premium compensation, constraining vendor scaling velocity.
- Cross-Border Compliance Architecture:Enterprises must engineer deployment strategies that reconcile European conformity assessments with North American cybersecurity frameworks simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise IoT Market |
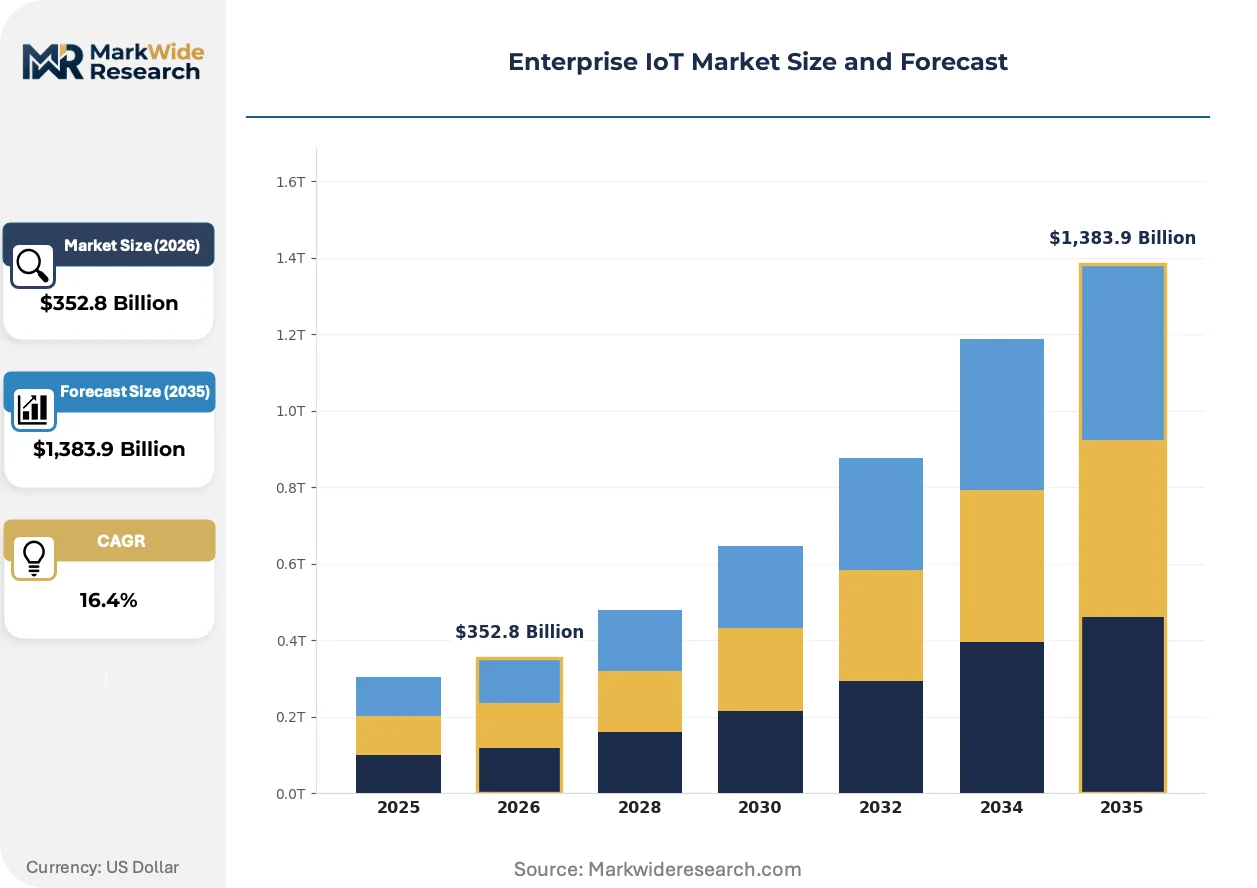
| Market Size in 2026 | $352.8 Billion |
| Market Size in 2035 | $1,383.9 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Solution Type: Security, Connectivity, Data Analytics, Device Management Industry Vertical: Manufacturing, Transportation, Agriculture, Healthcare End User: SMEs, Large Enterprises, Government, Retail |
| Companies Covered | Cisco Systems, Inc., Intel Corporation, Microsoft Corporation, Amazon Web Services, IBM Corporation, Siemens AG, PTC Inc., SAP SE, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise IoT Market Strategic Shifts & Innovations
Industrial IoT architectures are converging around three vectors: hardware miniaturization enabling denser sensor grids, regulatory harmonization attempts across member states, and procurement model evolution favoring operational expenditure over capital deployment.
Microelectromechanical systems (MEMS) sensors are embedding multi-axis vibration monitoring and thermal profiling into millimeter-scale packages. Automotive battery manufacturers are adopting these devices at volume to track cell degradation patterns in real time. Component footprint reduction is miniaturizing the physical constraints on production line instrumentation, allowing sensor density to triple without mechanical retrofit.
The EU AI Act imposes conformity assessments on autonomous IoT decision systems performing predictive maintenance without human intervention. Industrial machinery OEMs must now document algorithmic transparency and risk management protocols before deploying edge analytics. German automotive producers are responding by segregating AI-enabled and deterministic control systems into separate hardware domains to simplify certification scope.
Asset-intensive manufacturers are unbundling after-sales service contracts from hardware procurement, preferring subscription-based predictive maintenance platforms with uptime guarantees. Original equipment manufacturers are displacing traditional spare parts distributors with direct digital service channels. This shift is most visible in France's aerospace supply chain, where tier-one suppliers now contract fleet monitoring as a standalone service line independent of actuator sales.
Enterprise IoT Market Segmentation
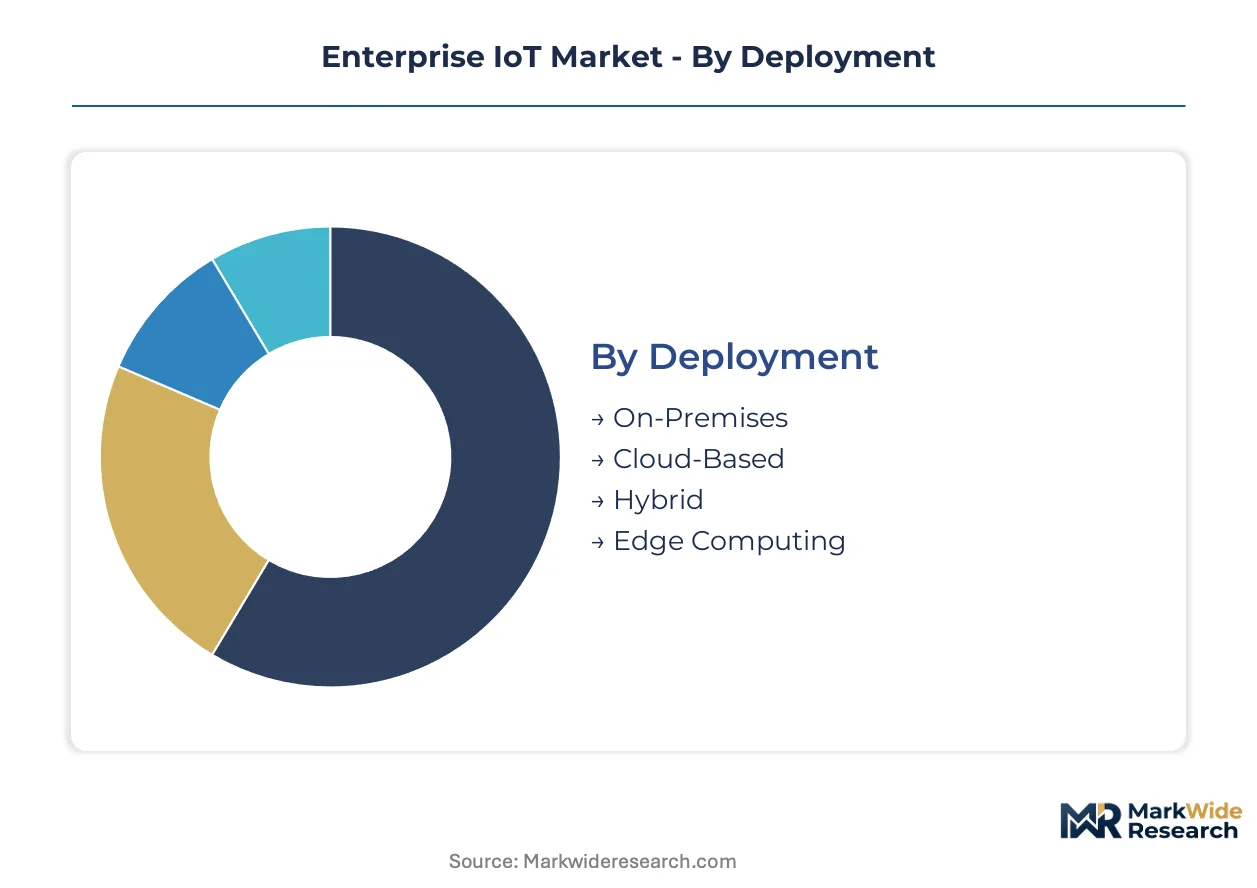
Enterprise IoT purchasing flows through distinct channel configurations depending on deployment complexity and buyer sophistication. Channel partners dominate SME transactions, while direct vendor relationships govern hyperscale manufacturing deployments.
Deployment:
Cloud-based and edge computing deployments flow through managed service providers, while on-premises installations route through systems integrators with captive hardware distribution.
- On-Premises:Capital-intensive server infrastructure housed within facility boundaries, requiring dedicated IT staffing and physical security protocols. German automotive producers in the Ruhr cluster favor this model for proprietary production data retention under BSI certification requirements.
- Cloud-Based:Third-party hosted platforms with subscription licensing and automatic patch management. French aerospace tier-one suppliers are migrating fleet monitoring workloads to managed cloud architectures to convert capital expenditure into operational outlays.
- Hybrid:Split architectures retaining sensitive control systems on-site while pushing analytics workloads to external hosts. India's electronics manufacturers under the PLI scheme deploy hybrid models to balance data sovereignty with cloud scalability.
- Edge Computing:Distributed processing nodes positioned at network periphery for sub-100 millisecond latency requirements. Smart manufacturing lines across Taiwan's semiconductor fabs utilize edge nodes for real-time vibration analysis without cloud round-trips.
By volume, cloud-based deployments lead. By expansion pace, edge computing is climbing the fastest.
Solution Type:
Margin concentration varies sharply across solution layers, with software analytics commanding recurring revenue multiples against commoditized device management.
- Security:Firmware-level cryptography, intrusion detection, and certificate management for connected device fleets. EU NIS2 Directive mandates are pulling compliant security stacks into critical infrastructure procurement specifications.
- Connectivity:Protocol translation gateways, network management, and edge-to-cloud backbone infrastructure. Germany's machinery OEMs demand IP-based fieldbus replacements with deterministic latency guarantees.
- Data Analytics:Predictive maintenance algorithms, anomaly detection, and operational intelligence platforms. France's aerospace suppliers monetize these capabilities as standalone subscription services independent of hardware sales.
- Device Management:Firmware over-the-air updates, provisioning, and lifecycle tracking for sensor fleets. Hardware margin compression has structurally commoditized this layer despite operational criticality.
Security solutions capture premium pricing. Data analytics accumulates the deepest recurring margin pools.
Industry Vertical:
Application intensity determines procurement sophistication, with manufacturing buyers demanding integrated automation ecosystems while agriculture segments prioritize low-cost, battery-optimized sensor grids.
- Manufacturing:Production line automation, predictive maintenance, and quality control systems with sub-100 millisecond latency requirements. Germany's automotive and machinery producers anchor regional demand concentration in the Ruhr industrial cluster.
- Transportation:Fleet telematics, route optimization, and autonomous vehicle sensor fusion. Battery cell manufacturers in South Korea deploy vibration monitoring to track degradation patterns across electric vehicle supply chains.
- Agriculture:Soil moisture sensing, livestock tracking, and precision irrigation with extended battery life requirements. India's agritech startups are deploying low-power wide-area networks for smallholder farm monitoring.
- Healthcare:Remote patient monitoring, medical device integration, and cold chain tracking for pharmaceuticals. EU AI Act conformity assessments now govern autonomous diagnostic systems without human intervention.
Manufacturing dominates absolute spending. Healthcare is gaining share fastest on regulatory tailwinds.
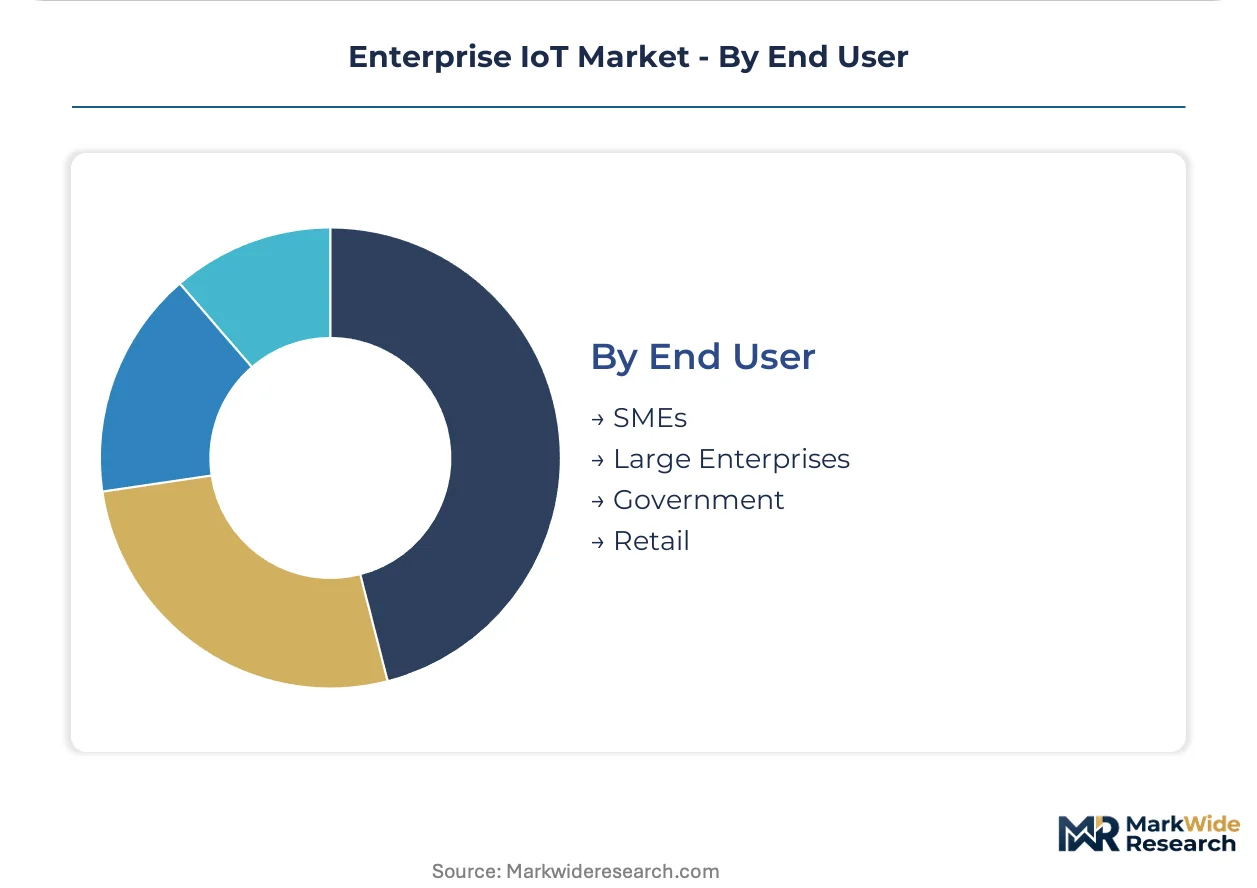
End User:
Procurement scale bifurcates the customer base, with large enterprises negotiating direct platform licenses while SMEs purchase through bundled managed service packages.
- SMEs:Resource-constrained buyers favoring turnkey managed services with minimal internal IT overhead. India's PLI beneficiary electronics manufacturers represent a growing SME segment with standardized cloud deployment preferences.
- Large Enterprises:Sophisticated procurement organizations with dedicated IoT architecture teams and custom integration requirements. German automotive groups mandate BSI-certified security stacks across multi-facility deployments.
- Government:Critical infrastructure operators subject to NIS2 Directive incident reporting thresholds and national cybersecurity certification schemes. France's ANSSI and Germany's BSI enforce divergent procurement standards fragmenting vendor qualification.
- Retail:Supply chain visibility, inventory tracking, and customer experience optimization through connected store environments. Edge computing architectures support real-time shelf monitoring with minimal latency tolerance.
Large enterprises lead procurement value. Government verticals are expanding most quickly on regulatory compliance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany's Ruhr industrial cluster demonstrate the lowest price elasticity, absorbing 40-60% premiums for BSI-certified security stacks, while India's PLI beneficiary electronics manufacturers operate at the highest sensitivity, prioritizing standardized cloud deployments with minimal customization overhead.
Germany
Automotive and machinery producers across the Ruhr cluster digitize production lines with networked actuators and predictive maintenance systems. The BSI enforces national cybersecurity certification schemes that fragment procurement standards with France's ANSSI. Stuttgart's automotive OEMs mandate segregated hardware domains for AI-enabled versus deterministic control systems to simplify EU AI Act conformity scope.
United States
Fleet telematics and autonomous vehicle sensor fusion drive transportation sector deployments with sub-100 millisecond latency requirements. The FCC governs spectrum allocation for industrial wireless protocols while NHTSA shapes connected vehicle security mandates. Michigan's automotive corridor anchors demand concentration as battery manufacturers deploy vibration monitoring across electric vehicle supply chains.
France
Aerospace tier-one suppliers unbundle after-sales service contracts, contracting fleet monitoring as standalone subscription services independent of actuator sales. ANSSI enforces divergent cybersecurity certification schemes that extend product validation cycles versus German standards. Toulouse's aerospace cluster leads procurement sophistication with direct digital service channels displacing traditional spare parts distributors.
India
PLI scheme beneficiaries establish captive sensor assembly capacity with standardized cloud deployment preferences minimizing internal IT overhead. The BIS governs electronics manufacturing standards while RBI shapes fintech-linked IoT payment integrations. Karnataka's electronics manufacturing cluster attracts component producers diversifying beyond concentrated Asian supply nodes.
Japan
Semiconductor fabs utilize edge computing nodes for real-time vibration analysis without cloud round-trips, demanding deterministic latency guarantees. METI coordinates national IoT architecture standards while PMDA governs autonomous diagnostic systems in healthcare applications. Kyushu's semiconductor manufacturing belt concentrates sensor density with MEMS miniaturization enabling tripled instrumentation without mechanical retrofit.
Enterprise IoT Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the Enterprise IoT market, creating a tiered competitive structure. The vendor base consolidates around three strategic groupings: networking heritage players dominating edge-to-cloud connectivity, manufacturing domain specialists leveraging captive automation ecosystems, and cloud-native platforms integrating ERP workflows at scale. M&A activity concentrates among security stack providers seeking compliance breadth, while strategic partnerships proliferate between hardware OEMs and analytics software vendors.
Within the networking-centric tier, Cisco Systems, Inc. and Siemens AG occupy positions reflecting divergent heritage advantages—Cisco representing IP-protocol dominance in factory floor connectivity, Siemens exemplifying deep manufacturing automation integration. Microsoft Corporation anchors the cloud-platform vector, its Azure IoT exemplifying ERP-integrated deployment models. These three entities represent the archetype spectrum: protocol infrastructure, domain-embedded hardware, and enterprise software extension.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Intel Corporation |
| Microsoft Corporation |
| Amazon Web Services |
| IBM Corporation |
| Siemens AG |
| PTC Inc. |
| SAP SE |
| Oracle Corporation |
| Others |
Cost & Logistics Intelligence
IP-based protocol migration replacing legacy fieldbus networks simultaneously redistributes manufacturing capacity toward software-centric supply regions and compresses hardware margin pools across European industrial clusters. Buyers in Germany's Ruhr corridor absorb BSI certification premiums while India's PLI beneficiaries prioritize standardized cloud deployments with minimal customization overhead.
Pricing Analysis
Subscription-based predictive maintenance contracts now drive lifetime value, displacing transactional hardware sales with recurring software licensing models. Three-tier pricing structure across premium, standard, and economy levels separates BSI-certified security stacks from uncertified alternatives and commodity device management layers. Cost compression in hardware tiers is intensifying because MEMS sensor miniaturization enables supplier volume scaling without proportional value capture. SME buyers in India's electronics manufacturing cluster exhibit highest price sensitivity, while German automotive OEMs demonstrate lowest elasticity for certified architectures.
Supply Chain Analysis
Strategic stockpiling of semiconductor components dominates inventory strategy as manufacturers buffer against Taiwan and South Korea fab concentration risks. Advanced sensor production draws from Taiwanese foundry capacity, South Korean memory fabrication, and German precision engineering inputs. Single-source vulnerability in MEMS wafer supply exposes European industrial buyers to geopolitical disruption cascades. Distribution runs through systems integrators for on-premises deployments and managed service providers for cloud-based architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise IoT sits in early-cycle expansion as EU NIS2 Directive mandates force critical infrastructure operators into compliance-driven replacement waves. Smart manufacturing sensor density targets across automotive production lines indicate penetration headroom remains substantial.
For Market Incumbents: Shield installed base erosion by embedding firmware-level cryptography deeper into captive automation hardware ecosystems. Accelerate certification investment across divergent BSI and ANSSI schemes before regulatory fragmentation hardens procurement standards. Vertical integration into edge computing silicon design preserves margin pools as commoditization pressure intensifies on device management layers.
For New Entrants and Emerging Players: Managed security service gaps in SME segments offer white-space entry where incumbent platforms over-engineer for enterprise complexity. India's PLI beneficiary electronics manufacturers represent the most penetrable geography, requiring minimal customization versus German automotive specifications. Go-to-market through cloud-native channel partnerships bypasses direct competition with Siemens and Cisco field sales organizations.
For Investors and Strategic Acquirers: The market sits at a standards-consolidation phase that favors security stack specialists with multi-certification breadth. Long-term viability hinges on recurring revenue attachment rates rather than hardware shipment volumes. Acquisition targets should demonstrate firmware-level cryptography expertise and existing BSI or ANSSI qualification pathways. Watch EU AI Act enforcement thresholds as the signal indicating acceleration or deceleration in autonomous IoT system deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Security Certification Investment | BSI and ANSSI multi-certification unlocks critical infrastructure procurement specifications across German and French industrial clusters. |
| Edge Computing Silicon Design | In-house semiconductor development preserves deterministic latency guarantees for sub-100 millisecond manufacturing applications. |
| Predictive Maintenance Platform Launch | Subscription revenue models displace transactional hardware margins in France's aerospace aftermarket unbundling trend. |
| PLI Scheme Manufacturing Footprint | India's electronics incentives attract sensor assembly capacity outside concentrated Taiwanese and South Korean supply nodes. |
| AI-Deterministic System Segregation | Hardware domain separation simplifies EU AI Act conformity scope for Stuttgart's automotive OEM deployment architectures. |
Research Approach
Initial hypotheses were tested against primary input from plant engineers, OEM procurement teams, aftermarket service heads, and IoT platform architects and refined through secondary validation against SEC filings, hyperscaler capex disclosures, EU regulatory filings, and industrial automation trade data. Bottom-up sensor deployment estimates triangulated with top-down manufacturing digitization spending patterns across German, French, and Indian industrial clusters.
Variance decomposition across deployment models, solution types, industry verticals, and end-user scale tiers structured the analytical framework throughout the projection horizon. CAGRs were derived from segment-level adoption curves weighted by regulatory mandate implementation timelines. Forecast inputs incorporated EU AI Act conformity assessment schedules and NIS2 Directive procurement specification rollouts without year-specific anchoring.
Underlying assumptions cover regulatory enforcement intensity, semiconductor supply normalization, and cloud migration velocity, with deviation risk concentrated in geopolitical disruption to Asian fab capacity and divergence between BSI and ANSSI certification harmonization. Revision becomes warranted when critical infrastructure operator compliance thresholds cross material deployment volume inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Internet of Things (IoT) Market
Internet of Things (IoT)
Industrial IoT Market
Internet of Things (IoT)
Global Satellite Enabled IoT Software Market
Internet of Things (IoT)
Bluetooth Smart Plugs Market
Internet of Things (IoT)
Global IoT Elevators Market
Internet of Things (IoT)
Consumer IoT Market
Internet of Things (IoT)
Wireless Smart Plug Market
Internet of Things (IoT)
Global IoT in Automobile Market
Internet of Things (IoT)
North America IoT Software Market
Internet of Things (IoT)
Global IoT Engineering Services Market
Internet of Things (IoT)
Consumer Internet of Things (IoT) Market
Internet of Things (IoT)
Asia-Pacific Massive IoT Market
Internet of Things (IoT)
UK IoT Software Market
Internet of Things (IoT)
Global Agile IoT Market
Internet of Things (IoT)
Global Machine-To-Machine (M2M) Connections Market
Internet of Things (IoT)
Global IoT Battery Market