
 IoT Communication Protocol Market | 2026-2036
IoT Communication Protocol Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Communication Protocol Market Analysis
The EU Green Deal is broadening the addressable market for low-power, interoperable IoT protocols across energy-intensive industries. Cisco Systems leverages its networking infrastructure dominance to anchor enterprise-grade protocol deployments in industrial settings. Silicon Labs specializes in multi-protocol wireless silicon that sustains design wins across Zigbee and Thread ecosystems. Sierra Wireless competes through embedded cellular modules that extend IoT connectivity into remote asset-tracking applications.
IoT communication protocols govern data exchange rules, message formats, and device handshaking procedures that enable heterogeneous sensors and actuators to interoperate across constrained networks. These protocols typically operate below the application layer, handling packet fragmentation, quality-of-service levels, and sleep-wake scheduling to preserve battery life in edge devices. MQTT retains leadership in bandwidth-constrained telemetry due to its publish-subscribe architecture and minimal overhead, while LoRa connectivity technology captures margin pools in wide-area, low-bit-rate deployments for agriculture and utilities. Smart metering as a use case exhibits the fastest expansion trajectory as utilities mandate two-way communication infrastructure for grid modernization.
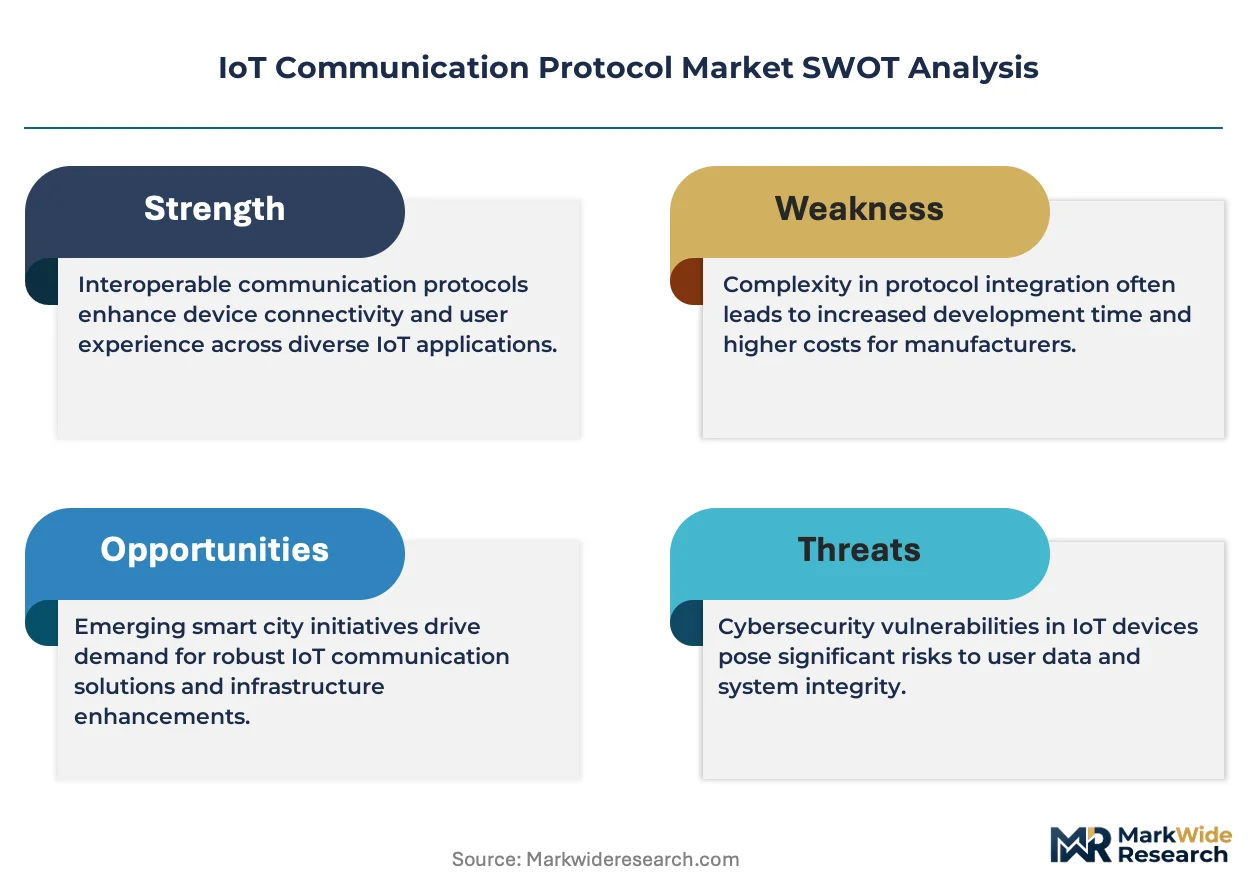
FCC certification requirements in the United States constrain radio-frequency emissions and spectrum allocation for unlicensed IoT bands, directly shaping hardware-protocol pairing decisions. ETSI standards in Europe mandate cybersecurity baselines and interoperability testing that filter which protocols gain market access in member states. China's MIIT enforces domestic encryption standards and type-approval processes that favor localized protocol implementations. Stakeholders must monitor evolving national cybersecurity mandates that increasingly prescribe minimum encryption grades and firmware update mechanisms as preconditions for device certification.
Market Dynamics
The EU AI Act and cybersecurity certification frameworks are forcing protocol vendors to embed encryption and firmware update capabilities at the hardware layer, fundamentally restructuring development roadmaps and certification timelines.
Growth Catalysts
- Industrial digitization mandates:Germany's Industry 4.0 program and China's MIIT smart manufacturing directives are accelerating deployment of time-sensitive networking protocols in automotive and precision machinery plants.
- EU Green Deal energy efficiency requirements:The framework mandates two-way smart metering infrastructure across member states, directly expanding addressable demand for low-power wide-area protocols in utility applications.
- Smart home ecosystem consolidation:Matter protocol standardization is eliminating fragmentation between Zigbee, Thread, and Wi-Fi devices, reducing integration friction for residential IoT deployments.
Market Restraints
- Silicon supply concentration:Advanced wireless SoC fabrication concentrates among Taiwan-based foundries, exposing protocol hardware vendors to geopolitical disruption and allocation constraints.
- Radio-frequency licensing costs:FCC Part 15 and ETSI EN 300 328 certification expenses for unlicensed spectrum devices impose fixed cost barriers for low-volume protocol implementations.
- Cellular module substitution:Embedded LTE-M and NB-IoT modules from Sierra Wireless and Quectel are displacing proprietary mesh protocols in asset-tracking applications where coverage uniformity matters.
Strategic Opportunities
- Agricultural sensor networks:Brazil's expanding precision agriculture sector presents underpenetrated demand for LoRa-based soil monitoring and irrigation control systems.
- Healthcare device interoperability:FDA's guidance on cybersecurity in medical devices creates regulatory tailwind for protocols supporting end-to-end encryption and secure boot processes.
- Edge-AI convergence:Integration of TinyML inference engines with Bluetooth Low Energy 5.3 is enabling on-device pattern recognition without cloud dependency, opening new application categories.
Industry Challenges
- Firmware security engineering talent scarcity:Protocol vendors face acute shortages of embedded systems engineers with cryptographic implementation expertise, extending development cycles.
- Multi-certification complexity:Simultaneous compliance with FCC, CE marking, and China's SRRC type-approval processes creates timeline friction for product launches.
- Legacy SCADA integration:Industrial protocol gateways must bridge Modbus and Profinet installations without disrupting operational continuity, complicating deployment architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Communication Protocol Market |
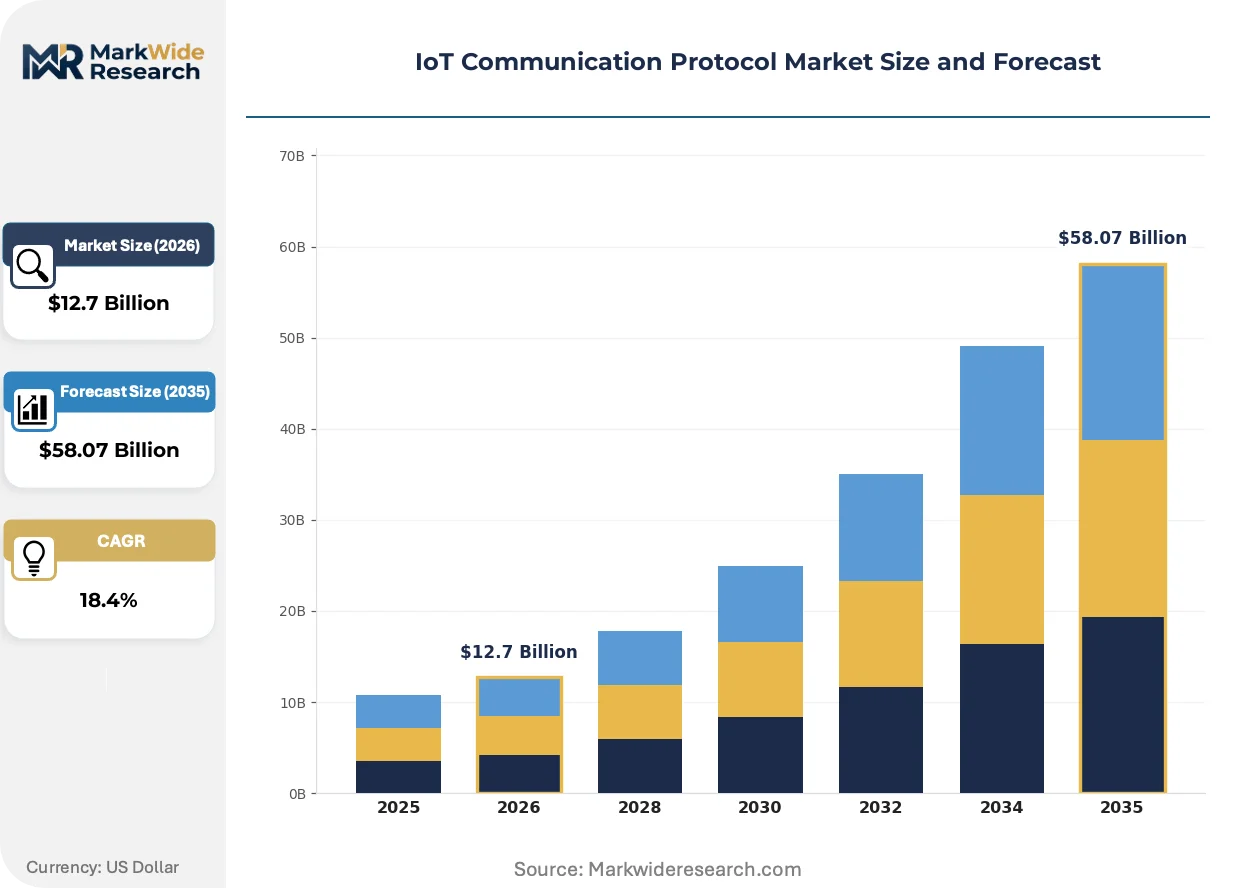
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $58.07 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Protocol Type: MQTT, CoAP, AMQP, DDS Connectivity Technology: Wi-Fi, Zigbee, LoRa, Bluetooth End User: Smart Home, Industrial Automation, Healthcare, Agriculture Use Case: Remote Monitoring, Asset Tracking, Smart Metering, Environmental Monitoring |
| Companies Covered | Connectivity Standards Alliance, Thread Group, Cisco Systems, GSMA Intelligence, Zigbee Alliance, Sierra Wireless, Bluetooth SIG, Silicon Labs, Telit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Communication Protocol Market Emerging Trajectories
Protocol standardization bodies and silicon vendors are converging on unified security architectures that embed hardware root-of-trust capabilities, compressing differentiation timelines for proprietary implementations.
Thread 1.3 with built-in border routing and IPv6 mesh capabilities is rewriting competitive positioning in smart home and commercial building automation. Multi-dwelling unit developers in the United States are specifying Thread-native infrastructure to reduce gateway hardware costs. The protocol's deterministic latency characteristics are compressing market space for Zigbee in lighting control applications.
ETSI's Cyber Security for Consumer Internet of Things standard and the EU AI Act's risk-based classification system are mandating vulnerability disclosure programs and secure update mechanisms for connected devices. Protocol stacks must now incorporate signed firmware verification and rollback protection to achieve CE marking. Medical device manufacturers in Germany and the Netherlands are prioritizing protocols with pre-certified security libraries to accelerate their own regulatory submissions.
Utility procurement departments are consolidating vendor relationships around integrated platform offerings rather than discrete protocol components. European distribution system operators are bundling AMI head-end systems with mandated communication modules, displacing standalone protocol licensing. This concentration is most visible in France and Italy, where Enel and EDF have established single-source frameworks for smart meter deployment through 2030.
IoT Communication Protocol Market Segmentation
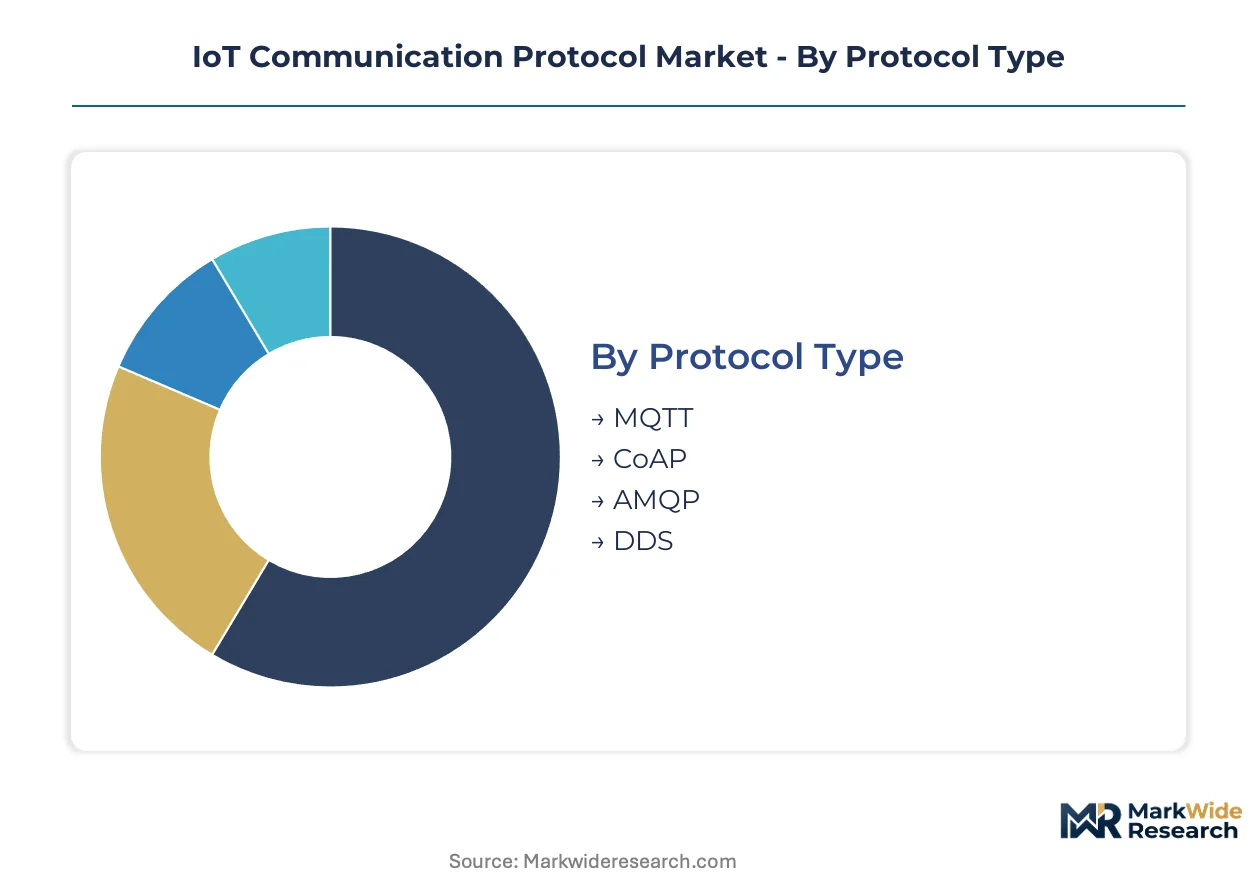
IoT communication protocol segmentation reveals how certification burdens, power constraints, and interoperability requirements fragment addressable markets across hardware-software pairings. Understanding these divisions exposes where procurement power concentrates and which protocol stacks command premium positioning.
Protocol Type:
MQTT carries FCC Part 15 and CE marking obligations for broker implementations handling telemetry streams, while DDS faces stricter ETSI cybersecurity baselines for industrial real-time deployments. CoAP and AMQP navigate lighter certification loads in constrained device and enterprise messaging contexts respectively.
- MQTT:Publish-subscribe architecture minimizes packet overhead for bandwidth-starved sensor networks. Demand clusters in German smart manufacturing facilities where Industry 4.0 mandates lightweight telemetry ingestion. FCC unlicensed spectrum rules shape hardware pairing decisions for US deployments.
- DDS:Real-time publish-subscribe middleware guarantees deterministic latency for autonomous vehicle and robotics control loops. China's MIIT smart manufacturing directives accelerate adoption in automotive foundries and precision machinery plants. ETSI industrial cybersecurity standards filter market access across European member states.
- CoAP:RESTful constrained application protocol optimized for UDP transport in battery-powered edge devices.
- AMQP:Enterprise message queuing standard for reliable business-critical data exchange between cloud platforms and backend systems.
MQTT sits at the top of the volume ranking, with DDS climbing the fastest.
Connectivity Technology:
Cost tiers separate silicon-integrated solutions from module-based alternatives, with discrete RF components commanding premium positioning in certified industrial hardware.
- LoRa:Chirp spread spectrum modulation enables kilometer-range transmission at sub-gigahertz frequencies with minimal power draw. Brazilian precision agriculture operations deploy soil moisture and irrigation sensors across expansive farmland where cellular coverage proves uneconomical. FCC Part 15 certification costs constrain low-volume hardware entrants.
- Wi-Fi:High-throughput protocol dominates smart home gateway and video streaming applications where bandwidth exceeds power constraints. US multi-dwelling unit developers specify Wi-Fi 6E infrastructure to reduce cabling costs in residential construction. ETSI EN 300 328 radio compliance adds fixed cost barriers for European market entry.
- Zigbee:Mesh networking stack for low-power home automation with proven interoperability across lighting and climate control ecosystems.
- Bluetooth:Short-range protocol capturing wearable and proximity sensing applications with integrated PHY/MAC silicon cost advantages.
Wi-Fi commands the largest installed base, with LoRa gaining share fastest in utility and agricultural verticals.
End User:
Application maturity determines margin structure, with regulated healthcare and industrial segments sustaining premium pricing against commoditized residential deployments.
- Industrial Automation:Time-sensitive networking requirements prioritize deterministic latency over power efficiency in automotive and precision machinery plants. Germany's Industry 4.0 program mandates protocol interoperability that filters vendor selection toward certified implementations. FDA cybersecurity guidance for connected manufacturing equipment adds compliance layers for US market participants.
- Smart Home:Matter protocol standardization eliminates fragmentation between Zigbee, Thread, and Wi-Fi device ecosystems. US residential construction specifies unified infrastructure to reduce gateway hardware proliferation. EU Green Deal energy efficiency labeling shapes consumer procurement toward certified low-power implementations.
- Healthcare:FDA medical device cybersecurity rules mandate end-to-end encryption and secure boot processes for patient-connected monitors.
- Agriculture:Brazil's expanding precision farming sector drives sensor network deployment for soil and climate monitoring.
Industrial Automation generates the highest average revenue per endpoint, with Healthcare expanding most quickly under regulatory tailwinds.
Use Case:
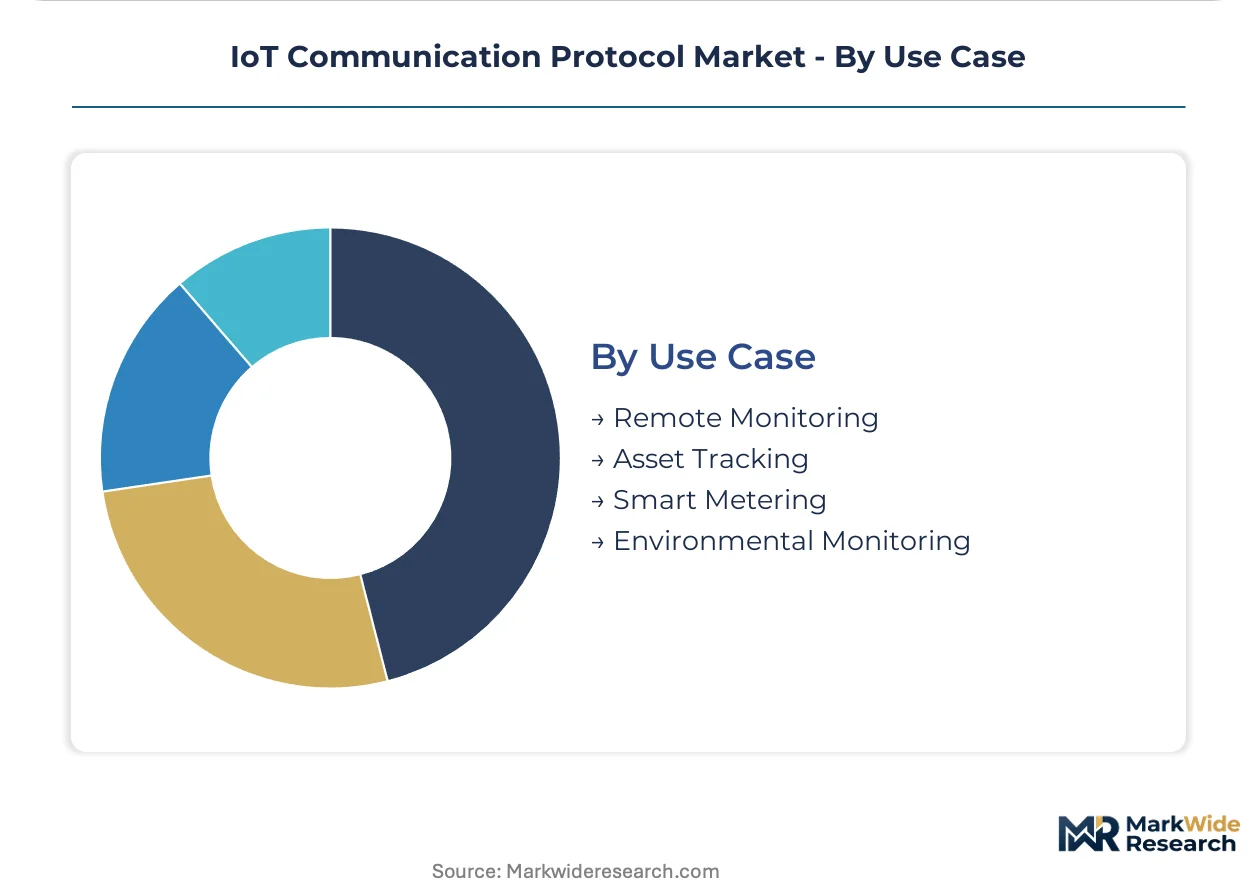
Customer procurement patterns bifurcate between utility-scale integrated platforms and discrete component sourcing for specialized monitoring applications.
- Smart Metering:Two-way communication infrastructure mandates low-power wide-area protocols for grid modernization across EU member states. France's EDF and Italy's Enel bundle AMI head-end systems with mandated communication modules through 2030. China's MIIT enforces domestic encryption standards that favor localized protocol implementations.
- Asset Tracking:Embedded cellular modules from specialized vendors displace proprietary mesh protocols where coverage uniformity matters. German logistics operators prioritize LTE-M and NB-IoT for fleet visibility across transcontinental routes. FCC certification timelines constrain rapid hardware iteration for US market entrants.
- Remote Monitoring:Telemetry applications for industrial equipment and environmental sensors requiring intermittent burst transmission.
- Environmental Monitoring:Air quality and water quality sensor networks deployed by municipal agencies and regulatory bodies.
Smart Metering dominates procurement volume, with Asset Tracking showing the steepest expansion trajectory as cellular module costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The IoT communication protocol industry traces its commercial origins to Silicon Valley's wireless networking pioneers and European industrial automation clusters, with subsequent scale-up concentrated in German precision manufacturing corridors and Chinese electronics manufacturing hubs.
United States
Smart home ecosystem consolidation and multi-dwelling unit construction drive protocol demand across residential and commercial verticals. FCC Part 15 certification requirements constrain radio-frequency emissions for unlicensed IoT bands, directly shaping hardware-protocol pairing decisions. Silicon Valley anchors enterprise-grade deployments, while Austin and Boston clusters specialize in industrial IoT gateway development.
Germany
Industry 4.0 digitization mandates accelerate time-sensitive networking protocol adoption in automotive foundries and precision machinery plants. ETSI cybersecurity baselines and interoperability testing filter which protocols gain market access across European member states. The Stuttgart-Munich corridor concentrates automotive protocol integration, with Berlin emerging as a hub for healthcare device interoperability certification.
China
MIIT smart manufacturing directives and domestic encryption standards favor localized protocol implementations in industrial and utility applications. Type-approval processes enforce GB standards that shape hardware design decisions for connected devices. Shenzhen's electronics manufacturing ecosystem supplies wireless SoC fabrication, while Shanghai clusters focus on smart metering infrastructure deployment.
Brazil
Expanding precision agriculture operations deploy LoRa-based soil monitoring and irrigation sensors across expansive farmland where cellular coverage proves uneconomical. ANVISA regulatory frameworks for connected medical devices create compliance layers for healthcare protocol implementations. São Paulo's industrial corridor anchors manufacturing automation deployments, with Minas Gerais emerging as a center for agricultural sensor network integration.
France
EU Green Deal energy efficiency requirements mandate two-way smart metering infrastructure across utility networks. EDF's bundled AMI head-end systems with mandated communication modules through 2030 concentrate procurement around integrated platform offerings. The Île-de-France region hosts smart city protocol deployments, while Lyon-Grenoble clusters specialize in industrial cybersecurity certification.
IoT Communication Protocol Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the protocol stack, with semiconductor foundries anchoring silicon-integrated solutions while module vendors specialize in certified hardware combinations. The market structure fragments across standards bodies, silicon vendors, and systems integrators with limited vertical consolidation. Three archetypes dominate: networking infrastructure incumbents extending enterprise protocols into industrial settings; wireless silicon specialists capturing design wins across multi-protocol ecosystems; and embedded cellular module providers extending connectivity into remote asset-tracking applications. Dominant competitive moves include strategic partnerships between standards bodies and silicon vendors, plus geographic expansion through localized certification partnerships.
Within the networking infrastructure tier, Cisco Systems represents enterprise-grade protocol deployment archetypes, anchoring industrial settings through existing customer relationships. Silicon Labs exemplifies the wireless silicon specialist model, with its multi-protocol portfolio sustaining design wins across Zigbee and Thread ecosystems. Sierra Wireless occupies a position among embedded cellular module providers, extending IoT connectivity into remote applications where coverage uniformity determines procurement decisions.
| Leading Market Players |
|---|
| Connectivity Standards Alliance |
| Thread Group |
| Cisco Systems |
| GSMA Intelligence |
| Zigbee Alliance |
| Sierra Wireless |
| Bluetooth SIG |
| Silicon Labs |
| Telit |
| Others |
Supply Flow & Price Mechanics
Embedded systems engineers with cryptographic implementation expertise concentrate in Germany's Stuttgart-Munich corridor and Shenzhen's electronics manufacturing ecosystem, creating labor-cost differentials that widen pricing-tier spreads between certified industrial-grade protocol stacks and commodity residential implementations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the protocol stack market. Premium tiers command spreads based on FCC Part 15 and ETSI EN 300 328 certification completeness plus hardware root-of-trust integration. Cost compression in economy tiers intensifies because Taiwanese foundry allocation constraints squeeze silicon margins. Residential smart home deployments exhibit highest price sensitivity; regulated healthcare and industrial automation segments show lowest.
Supply Chain Analysis
Refurbishment flows for certified industrial gateways create secondary supply channels that compete with new module sales in price-sensitive segments. Advanced wireless SoC fabrication concentrates in Taiwan, with South Korea and the United States anchoring specialty foundry capacity. Supply chains draw from silicon wafers, RF front-end components, and cryptographic security IP cores. Single-source vulnerability around Taiwan-based fabrication exposes vendors to geopolitical disruption. Distribution runs through direct OEM partnerships for industrial volumes and electronics distributors for developer kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the IoT communication protocol market rests on Matter protocol standardization compressing certification costs for residential tiers and embedded cellular module cost curves steepening in asset-tracking applications.
For Market Incumbents: Extend platform integration roadmaps to capture utility-scale AMI bundling opportunities as EDF and Enel consolidate vendor relationships through 2030. Deepen backward integration into multi-protocol wireless silicon to defend against Sierra Wireless and Quectel cellular substitution in remote monitoring. Prioritize Thread 1.3 border routing certifications to maintain positioning in multi-dwelling unit specifications. For New Entrants and Emerging Players: Launch via precision agriculture sensor networks in Brazil's Minas Gerais region where LoRa coverage gaps persist and cellular economics fail. Target FDA pre-certified security libraries for German and Dutch medical device manufacturers accelerating regulatory submissions. Pursue white-label protocol gateway partnerships with industrial SCADA integrators bridging Modbus and Profinet legacy installations. For Investors and Strategic Acquirers: Valuations sit cheapest among embedded firmware security engineering boutiques with cryptographic implementation expertise and existing ETSI certification track records. Long-term viability hinges on protocol stack portability across RISC-V and ARM architecture transitions. Watch for inflection when EU AI Act enforcement triggers mandatory firmware update capability retrofits in installed device bases.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Silicon Integration | Silicon Labs captures design wins across Zigbee and Thread ecosystems through unified radio architectures. |
| Cellular Module Cost Reduction | Quectel and Sierra Wireless displace proprietary mesh protocols in German logistics fleet visibility applications. |
| Hardware Root-of-Trust Certification | ETSI cybersecurity baselines filter market access for protocol stacks with signed firmware verification. |
| Utility AMI Platform Bundling | EDF and Enel single-source frameworks through 2030 concentrate procurement around integrated offerings. |
| Edge-AI Protocol Convergence | TinyML inference engines integrated with Bluetooth Low Energy 5.3 enable on-device pattern recognition without cloud dependency. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement covered protocol engineering directors at wireless silicon vendors, certification managers at standards bodies, and procurement leads at European distribution system operators. Secondary validation drew from FCC equipment authorization databases, ETSI technical specification releases, MIIT type-approval registries, and SEC filings from semiconductor suppliers. Bottom-up protocol deployment estimates triangulated against top-down connectivity module shipment aggregates.
Segment-weighting across protocol type, connectivity technology, end user, and use case dimensions structured the analytical framework. Modeled variables included industrial digitization program spending trajectories, smart meter deployment pipelines under EU Green Deal mandates, and cellular module cost curves across the projection horizon. CAGR derivation incorporated technology substitution elasticities and regulatory compliance timeline compressions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Taiwan semiconductor foundry allocation disruptions or accelerated EU AI Act enforcement timelines. Forecasts reflect assumptions about Matter protocol adoption velocity and Thread ecosystem consolidation rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Airline IoT Market
Internet of Things (IoT)
IoT Software Market
Internet of Things (IoT)
M2M Communication Market
Internet of Things (IoT)
IoT in Warehouse Management Market
Internet of Things (IoT)
Massive IoT Market
Internet of Things (IoT)
Airport Internet of Things Market
Internet of Things (IoT)
Consumer IoT Market
Internet of Things (IoT)
Internet of Things in BFSI Market
Internet of Things (IoT)
Wireless Smart Plug Market
Internet of Things (IoT)
Automotive Internet of Things (IoT) Market
Internet of Things (IoT)
IoT Utilities Market
Internet of Things (IoT)
IoT Gateway Devices Market
Internet of Things (IoT)
IoT in Energy Market
Internet of Things (IoT)
Wireless Connected Devices Market
Internet of Things (IoT)
Smart Sprinkler Controller Market
Internet of Things (IoT)
Solar Based Internet of Things (IoT) Market