
 Ovulation Microscope Market | 2026-2036
Ovulation Microscope Market Size, Share, and Industry Trends Forecast 2026-2036
Ovulation Microscope Market Analytics
Direct-to-consumer online channels is tilting toward specialized fertility platforms and telehealth-integrated storefronts. Fairhaven Health leverages its established brand presence in natural fertility products to sustain repeat purchase rates. Clearblue anchors premium positioning through advanced digital imaging integration. OvuSense competes on subscription-linked hardware models that extend customer lifetime value beyond initial device sales.
An ovulation microscope is a compact optical or digital imaging device designed to detect estrogen surge patterns through saliva crystallization or cervical mucus observation, typically operating at 20x to 40x magnification with LED illumination for home or clinical fertility monitoring. The handheld product category dominates unit volumes due to lower price points and discretion, while digital imaging technology captures expanding margin pools as consumers prioritize automated result interpretation. Fertility centers represent the fastest-growing end-user segment as clinics integrate patient-managed monitoring into assisted reproduction protocols.
FDA device classification rules determine whether ovulation microscopes enter the market as wellness products or regulated medical devices, directly affecting labeling claims and distribution access. The EU Medical Device Regulation and CE marking requirements impose additional conformity assessment burdens on manufacturers targeting European markets. Stakeholders must monitor evolving digital health software regulations that could reclassify app-connected devices and reshape competitive barriers to entry.
Market Dynamics
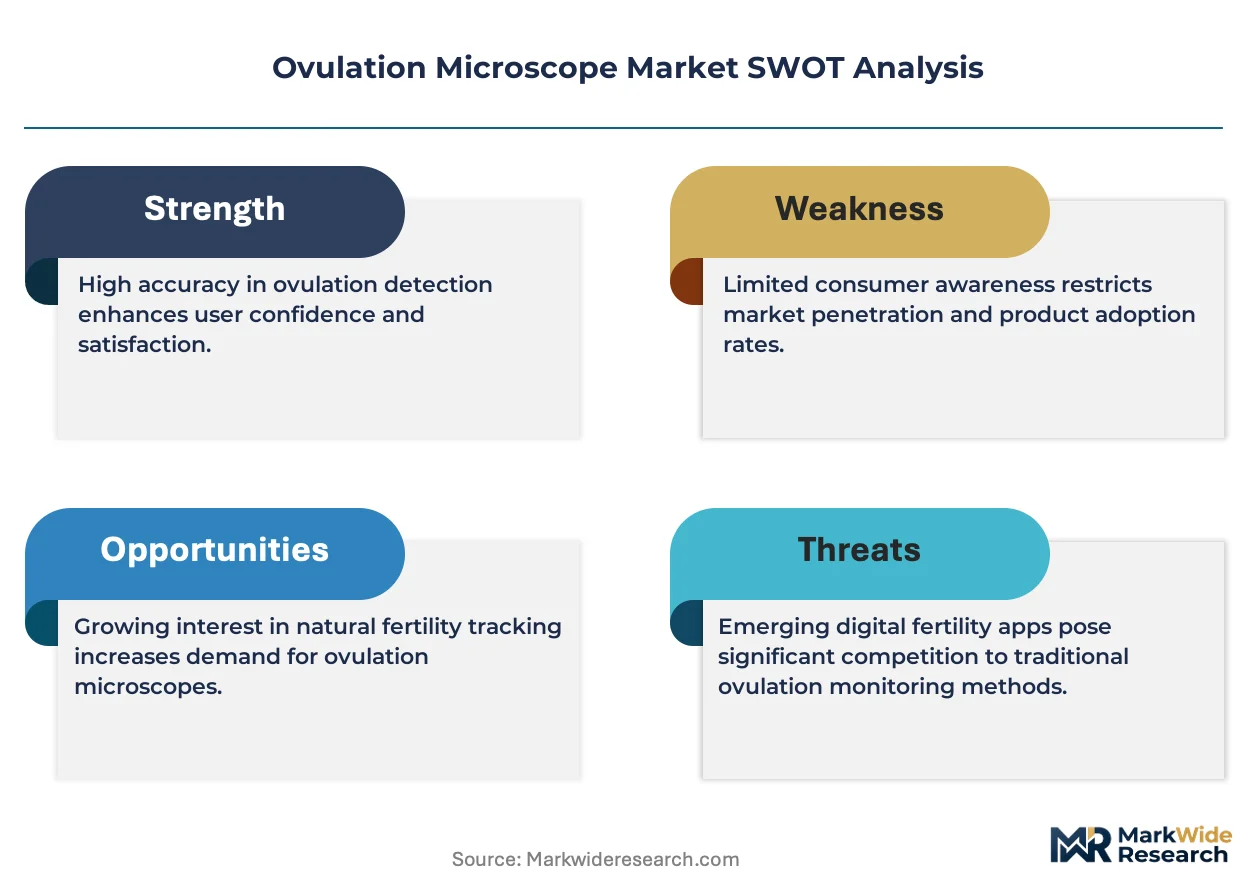
The convergence of smartphone-connected optics and FDA 510(k) clearance pathways is restructuring how ovulation microscopes transition from wellness gadgets to reimbursable medical devices, compressing development timelines while elevating compliance costs.
Growth Catalysts
- Telehealth integration:Fertility clinics in the United States now embed patient-managed salivary ferning data into IVF protocols, creating pull-through demand for connected devices that sync with electronic health records.
- CE marking under EU MDR:The 2021 Medical Device Regulation harmonizes conformity assessment across 27 member states, enabling manufacturers to leverage single-notified-body approvals for multi-country market access.
- Saliva crystallization algorithms:Machine learning pattern recognition is automating estrogen surge detection, reducing user interpretation error and expanding addressable segments beyond sympto-thermal method adherents.
Market Restraints
- Optical component concentration:German and Japanese lens suppliers control high-precision 40x magnification assemblies, exposing manufacturers to lead-time volatility and currency fluctuation risk.
- FDA dual-classification ambiguity:The agency's wellness-to-medical-device boundary shifts unpredictably, forcing firms to maintain parallel labeling strategies and delaying commercialization by 12-18 months.
- Urinary LH test substitution:Dipstick ovulation predictors at mass retail price points capture price-sensitive consumers who prioritize cost over multi-cycle reusability.
Strategic Opportunities
- India's underserved tier-2 cities:Rising female labor force participation and delayed first pregnancy are creating first-time demand for discreet home fertility tracking outside metro hospital networks.
- Subscription hardware models:Recurring revenue from app-linked analytics and personalized cycle coaching extends customer lifetime value beyond one-time device margins.
- ISO 13485 certification acceleration:Quality management system adoption opens institutional procurement channels in NHS England and France's Assurance Maladie reimbursement frameworks.
Industry Challenges
- Biomedical optics talent scarcity:Miniaturized LED illumination engineering requires specialized skill sets concentrated in Swiss and German precision manufacturing clusters.
- Software-as-medical-device reclassification:Connected app updates trigger new FDA premarket review cycles, complicating agile development workflows and version control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ovulation Microscope Market |
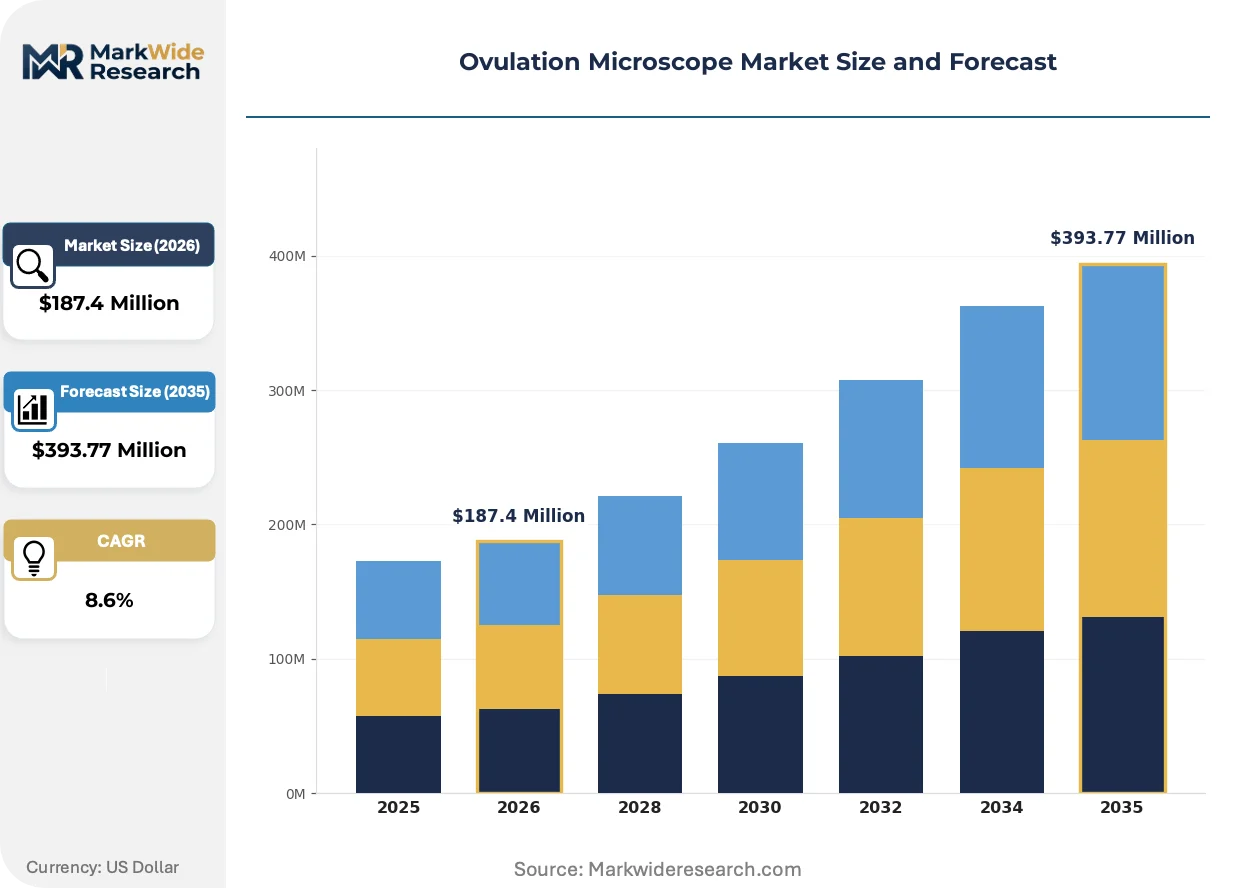
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Tabletop, Digital, Portable Technology: Optical, Digital Imaging, Microfluidic, Fluorescence End User: Home Users, Clinics, Fertility Centers, Research Laboratories Distribution Channel: Online, Retail, Direct Sales, Wholesale |
| Companies Covered | Fairhaven Health, Clearblue, OvuScope, Knowhen, Fertile Focus, Gemc Technology Group, Salignostics, Femometer, OvuSense, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ovulation Microscope Market Evolving Landscape
Salivary biosensing and cloud-based cycle analytics are displacing analog microscopy as the dominant technical paradigm, while regulatory frameworks scramble to catch up with software-enabled diagnostic claims.
Digital imaging arrays with automated ferning pattern recognition are digitizing the core detection mechanism that previously required manual visual interpretation. Fertility centers in Denmark and the Netherlands are piloting these systems for remote patient monitoring between clinic visits. The technology is digitizing result consistency and reducing inter-user variability that plagued traditional lens-based devices.
The EU Artificial Intelligence Act's risk classification system is reshaping how algorithm-driven ovulation prediction tools enter European markets. High-risk AI systems face mandatory conformity assessment and post-market monitoring obligations. Connected microscope manufacturers targeting Germany and France must now embed explainability features and human oversight protocols into their software architectures.
Direct-to-consumer subscription models are fragmenting traditional pharmacy and clinic distribution channels. Specialized fertility platforms and telehealth-integrated storefronts capture growing share of initial device purchases in the United States and United Kingdom. This channel shift concentrates marketing spend on digital customer acquisition rather than wholesale relationships, favoring brands with strong content and community infrastructure.
Ovulation Microscope Market Segmentation
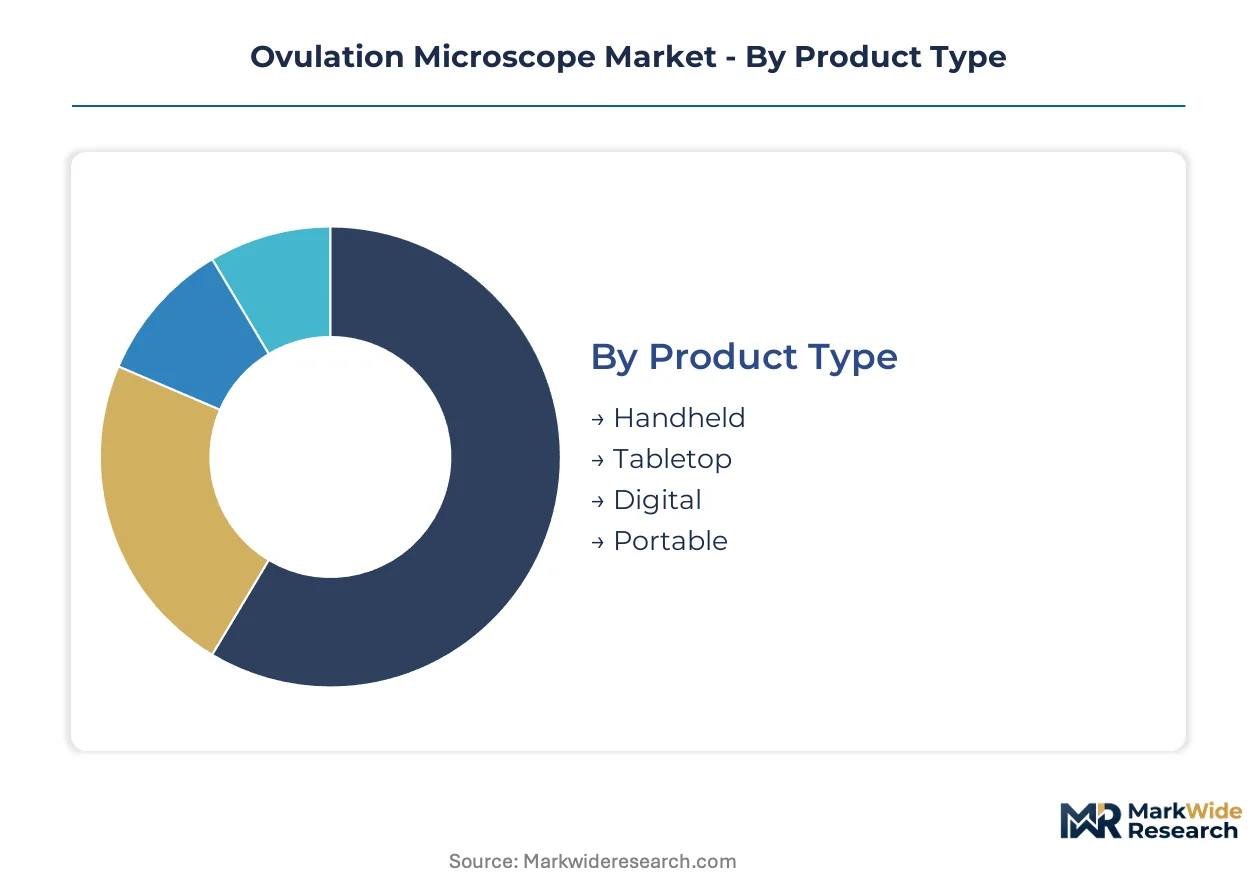
Ovulation microscopes fragment across four critical dimensions that determine pricing power, regulatory pathway, and customer acquisition cost. Product form factor and imaging technology define hardware margins, while end-user setting and distribution channel shape commercialization strategy and lifetime value capture.
Product Type:
After-sales intensity varies sharply by product form, with digital and tabletop units requiring firmware updates and calibration services that extend revenue per customer.
- Handheld:Compact battery-operated devices with 20x to 40x optical magnification dominate unit volumes through pharmacy and online channels. Home users in the United States and Germany drive replacement cycles every 18 to 24 months as LED illumination degrades.
- Digital:Smartphone-connected optics with automated pattern recognition command premium pricing and recurring app subscription revenue. Fertility clinics in Denmark and the Netherlands embed these into remote patient monitoring protocols, creating institutional pull-through demand.
- Tabletop:Laboratory-grade precision optics serve clinical settings requiring documented calibration trails for ISO 13485 compliance.
- Portable:Mid-size rechargeable units bridge home and clinical use cases with hybrid positioning.
Handheld devices hold the largest share; momentum sits with digital as telehealth integration accelerates.
Technology:
Cost tier stratification runs from basic optical systems to algorithm-enhanced platforms, with R&D intensity and regulatory burden climbing across the spectrum.
- Digital Imaging:CMOS sensor arrays with machine learning ferning pattern detection eliminate user interpretation error. FDA 510(k) clearance pathways and CE marking under EU MDR impose 12 to 18 month development timelines that filter out undercapitalized entrants.
- Optical:Traditional lens-and-LED assemblies from German and Japanese suppliers anchor budget price tiers. Price-sensitive consumers in India and Southeast Asia sustain volume demand despite substitution pressure from urinary LH tests.
- Microfluidic:Saliva sample processing chips enable quantitative hormone measurement beyond qualitative crystallization observation.
- Fluorescence:High-sensitivity detection methods serve research laboratories and specialized fertility centers requiring biomarker quantification.
Optical technology retains volume leadership; digital imaging gains share fastest through automated result interpretation and subscription monetization.
End User:
Application context dictates performance requirements, with clinical settings demanding traceability and home use prioritizing discretion and ease of operation.
- Fertility Centers:Assisted reproduction clinics in the United States and United Kingdom integrate patient-managed salivary monitoring into IVF protocols. Connected devices that sync with electronic health records reduce in-person visit frequency while maintaining treatment oversight.
- Home Users:Direct-to-consumer purchasers favor discreet, reusable alternatives to disposable ovulation test strips. Delayed first pregnancy trends among professional women in tier-2 Indian cities and Western European metros expand addressable segments.
- Clinics:General practice and gynecology offices use mid-tier devices for preliminary fertility assessments before specialist referral.
- Research Laboratories:Academic and pharmaceutical research settings drive demand for fluorescence and microfluidic platforms with publication-grade data output.
Home users represent the largest installed base; fertility centers climb the fastest as clinics embed remote monitoring into standard care pathways.
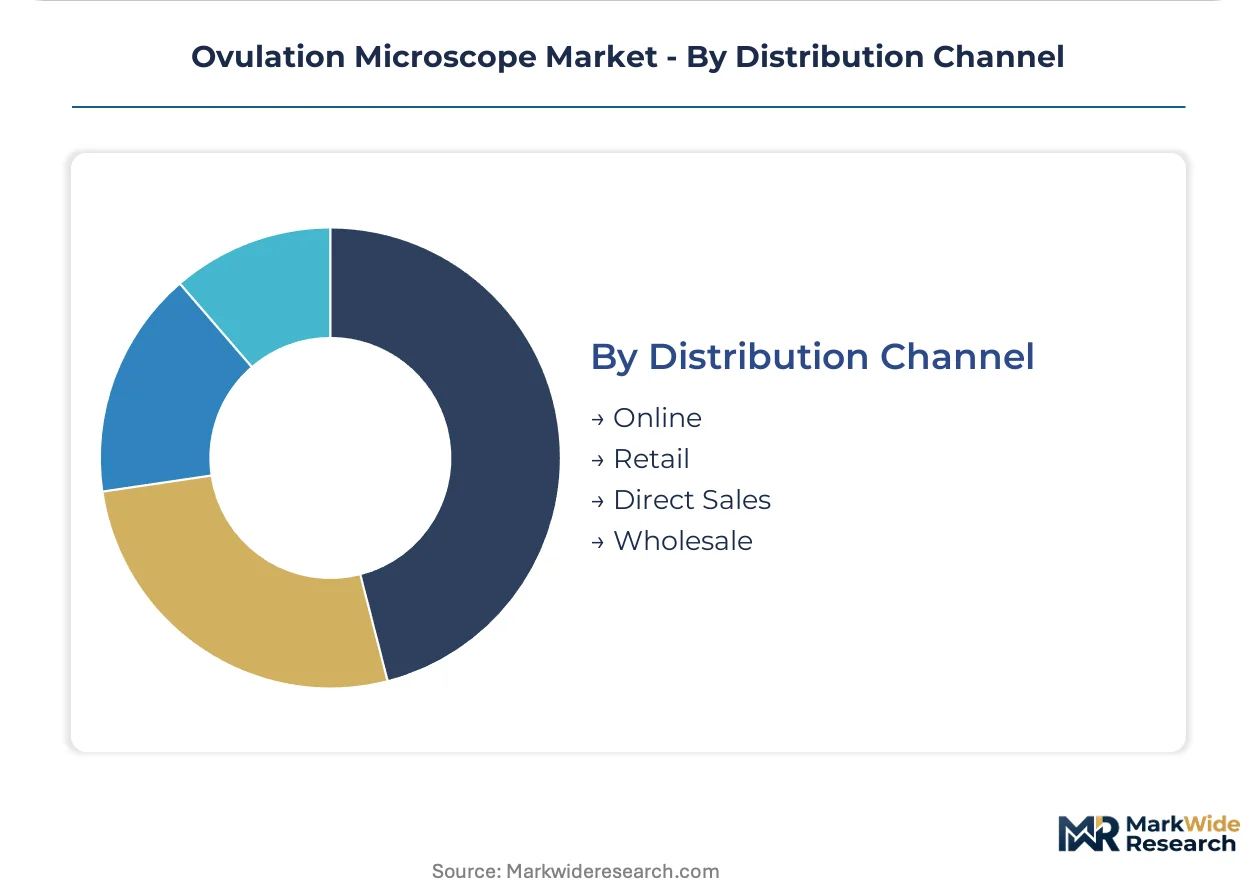
Distribution Channel:
Customer type concentration shapes channel economics, with direct digital acquisition displacing wholesale relationships for subscription-capable products.
- Online:Specialized fertility platforms and telehealth-integrated storefronts capture growing share of initial device purchases. Digital customer acquisition through content and community infrastructure favors established brands with repeat purchase ecosystems.
- Retail:Pharmacy and mass merchant channels serve price-sensitive consumers seeking immediate availability without app dependency.
- Direct Sales:Institutional procurement through fertility center and hospital supply agreements requires ISO 13485 certification and dedicated clinical support teams.
- Wholesale:Distributor networks penetrate geographic markets lacking direct brand presence, particularly in Latin America and Middle East regions.
Online channels hold the largest revenue share; direct sales expand most quickly as institutional procurement standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics infrastructure underwrites Western Europe's role as the primary distribution hub for fertility monitoring devices entering the EU single market.
United States
Telehealth-integrated fertility clinics in Massachusetts and California drive institutional procurement of connected ovulation microscopes. FDA 510(k) clearance pathways determine whether devices enter as wellness products or reimbursable medical equipment. Boston's medical device cluster hosts specialized regulatory consulting firms that guide manufacturers through premarket notification processes.
Germany
Delayed first pregnancy trends among professional women in Berlin and Munich expand direct-to-consumer demand for discreet home fertility tracking. CE marking under EU MDR imposes conformity assessment requirements that filter out undercapitalized market entrants. The precision optics manufacturing corridor in Baden-Württemberg supplies high-magnification lens assemblies to device manufacturers worldwide.
United Kingdom
NHS England's reimbursement frameworks for fertility diagnostics create institutional pull-through demand for ISO 13485-certified devices. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while introducing separate UKCA marking requirements. London's digital health venture ecosystem incubates subscription-linked hardware startups targeting remote patient monitoring protocols.
India
Rising female labor force participation in Bangalore and Hyderabad generates first-time demand for home-based fertility tracking outside metro hospital networks. CDSCO medical device rules classify ovulation microscopes based on intended use claims and risk profiles. Maharashtra's pharmaceutical distribution networks penetrate tier-2 cities where discreet e-commerce channels replace traditional pharmacy access.
Netherlands
Fertility centers in Amsterdam and Utrecht pilot smartphone-connected salivary monitoring for remote patient management between IVF clinic visits. EMA guidance on software-as-medical-device classification shapes how algorithm-driven prediction tools enter European markets. The Eindhoven photonics cluster develops miniaturized LED illumination components for next-generation handheld devices.
Ovulation Microscope Market Competitive Landscape
On the supply side, the industry is moderately concentrated with tiered positioning across premium digital imaging, established optical brands, and emerging subscription-hardware specialists. Strategic archetypes include telehealth-integrated platform builders, precision optics legacy manufacturers, and direct-to-consumer community brands. Dominant competitive moves center on FDA clearance acquisition for medical device reclassification and subscription model adoption to extend customer lifetime value beyond initial hardware margins.
Among North American platform specialists, Fairhaven Health and Clearblue exemplify divergent archetypes within the premium tier, while OvuSense represents the emerging subscription-linked hardware model. Fairhaven Health leverages established positioning in natural fertility products to sustain repeat purchase ecosystems. Clearblue anchors premium market positioning through advanced digital imaging integration. OvuSense competes on recurring revenue architectures that monetize app-linked analytics and personalized cycle coaching beyond one-time device sales.
| Leading Market Players |
|---|
| Fairhaven Health |
| Clearblue |
| OvuScope |
| Knowhen |
| Fertile Focus |
| Gemc Technology Group |
| Salignostics |
| Femometer |
| OvuSense |
| Others |
Value Network & Pricing Analysis
German and Japanese precision optics suppliers anchor upstream concentration for 40x magnification lens assemblies, feeding margin pools downstream toward algorithm-enhanced digital imaging tiers where automated ferning detection commands premium positioning.
Pricing Analysis
Volume-discount tiering structures separate subscription-linked hardware bundles from single-unit pharmacy sales, with fertility clinics capturing scale pricing through multi-device procurement contracts. Price differentiation hinges on FDA 510(k) medical device certification tier and bundled after-sales calibration services. Pricing pressure stems from urinary LH test substitution at mass retail price points, compressing margins in the optical segment. Home users in India and Southeast Asia exhibit highest price sensitivity, while institutional buyers in Denmark and the Netherlands prioritize connectivity over unit cost.
Supply Chain Analysis
Export-control regimes on precision optical components limit flows of high-magnification assemblies from Baden-Württemberg manufacturing corridors. Supply concentrates in Germany for lens systems, Japan for LED illumination engineering, and Switzerland for miniaturized photonics. Raw material dependencies include optical-grade glass, CMOS sensor arrays, and specialized LED substrates. Single-source vulnerability runs through the biomedical optics talent clusters concentrated in Swiss and German precision manufacturing regions. Distribution runs through specialized fertility platforms and telehealth-integrated storefronts for digital tiers, with pharmacy wholesale networks serving optical device volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against disposable urinary LH tests that capture price-sensitive consumers prioritizing immediate availability over multi-cycle reusability.
For Market Incumbents: Entrench market position through backward integration into precision optics manufacturing to reduce dependency on German and Japanese lens suppliers. Accelerate FDA 510(k) clearance acquisition for medical device reclassification, creating regulatory barriers against wellness-tier competitors. Counter urinary LH test substitution by emphasizing lifetime cost economics and telehealth integration value in fertility clinic channels.
For New Entrants and Emerging Players: Tier-2 Indian cities with rising female labor force participation and delayed first pregnancy trends represent the most penetrable entry point for discreet home fertility tracking outside established metro hospital networks. Subscription-linked hardware models with app-based cycle coaching offer recurring revenue architectures that extend customer lifetime value beyond one-time device margins. Target direct-to-consumer digital acquisition through specialized fertility content platforms rather than wholesale pharmacy relationships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision optics manufacturers seeking vertical integration into connected diagnostic device assembly. Long-term viability hinges on regulatory moat sustainability through FDA medical device classification and EU MDR CE marking compliance. Watch for CDSCO rule harmonization in India as an inflection indicator for geographic expansion opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Medical device reclassification unlocks reimbursement channels and blocks wellness-tier competitors. |
| CE Marking Under EU MDR | Harmonized conformity assessment enables single-notified-body entry across 27 member state markets. |
| Telehealth Platform Integration | Fertility clinics in Massachusetts and California embed patient-managed monitoring into IVF protocols. |
| Subscription Hardware Model | Recurring revenue from app-linked analytics extends customer lifetime value beyond initial device sales. |
| ISO 13485 Certification | Quality management system adoption opens NHS England and France Assurance Maladie procurement channels. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical engineers, fertility clinic directors, GPO contracts managers, and regulatory affairs specialists, then refined through secondary validation against FDA 510(k) filings, EMA guidance documents, hospital procurement databases, and customs trade records. Bottom-up demand modeling across handheld, digital, tabletop, and portable form factors was triangulated with top-down macroeconomic indicators.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, imaging technology, end-user setting, and distribution channel. CAGRs were derived from installed base growth rates and replacement cycle dynamics. Forecast inputs incorporated telehealth adoption curves in fertility clinics and regulatory pathway timelines for software-as-medical-device classification under EU AI Act risk tiers.
Practitioners should monitor FDA wellness-to-medical-device boundary shifts and EU MDR notified body capacity constraints for early signals of competitive barrier movement. Forecasts reflect assumptions about telehealth integration velocity and optical component supply stability. Material shifts in CDSCO medical device classification rules or German-Japanese lens supplier consolidation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Neurovascular Stent Market
Medical Devices
Latin America Biomedical Sensors Market
Medical Devices
Canada Aesthetic Devices Market
Medical Devices
Latin America Implantable Medical Devices Market
Medical Devices
Global Injectable Drug Delivery Devices Market
Medical Devices
Nerve Ablation Devices Market
Medical Devices
Global Micro Guide Catheters Market
Medical Devices
Asia-Pacific Medical Aesthetic Devices Market
Medical Devices
India Spinal Fusion Devices Market
Medical Devices
Lacrimal Devices Market
Medical Devices
North America IVD Regulatory Affairs Outsourcing Market
Medical Devices
Medical Bionic Implant Market
Medical Devices
Cryoballoon Ablation System Market
Medical Devices
North America Ultrasound Probe Disinfection Market
Medical Devices
Middle East and Africa Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Medical Smart Glasses Market