
 Polyether Ether Ketone (PEEK) Interbody Devices Market | 2026-2036
Polyether Ether Ketone (PEEK) Interbody Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Polyether Ether Ketone (PEEK) Interbody Devices Market Analytics
Aftermarket service revenue from implant revision monitoring is narrowing as manufacturers bundle predictive analytics with original device sales. Medtronic leverages its integrated spine platform to capture recurring clinical value beyond the initial implantation. Stryker Corporation sustains competitive pressure through specialized PEEK machining capabilities and surgeon training networks. Zimmer Biomet anchors its position in expandable interbody configurations that address intraoperative fit variability.
Polyether ether ketone interbody devices are high-performance thermoplastic spinal implants manufactured through precision machining or injection molding of polyaryletherketone polymer, exhibiting a flexural modulus closely matched to human cortical bone to reduce stress shielding and promote osseointegration. These devices function primarily to restore disc height and stabilize motion segments during anterior, lateral, or posterior spinal fusion procedures. Cylindrical and boxed devices occupy the mature core of the product portfolio, while expandable configurations capture accelerating demand as surgeons prioritize intraoperative adaptability over static sizing. Hospitals dominate end-user procurement through centralized orthopedic supply contracts, though ambulatory surgical centers represent the fastest-growing delivery setting as minimally invasive lateral interbody fusion techniques migrate to outpatient environments.
FDA 510(k) premarket notification requirements and EU MDR technical documentation standards govern biocompatibility validation and clinical evidence thresholds for PEEK interbody devices, directly shaping product development timelines and market access costs. ISO 10993 biological evaluation protocols and ASTM F2025 radiopacity standards further define material qualification benchmarks that manufacturers must satisfy across major commercial jurisdictions. Stakeholders must monitor evolving FDA guidance on 3D-printed patient-specific implants and corresponding EU notified body capacity constraints, as these regulatory developments will determine which technology pathways achieve scalable commercialization.
Market Dynamics
Surgeon demand for intraoperative adaptability is compressing static interbody device portfolios and elevating expandable configurations as the default procurement specification across hospital supply contracts.
Growth Catalysts
- EU MDR conformity pathways:Streamlined technical documentation standards for established PEEK formulations are accelerating market access timelines for second-generation expandable devices.
- Outpatient lateral interbody fusion:Migration of minimally invasive techniques to ambulatory surgical centers in the United States is expanding addressable procedure volumes beyond traditional inpatient settings.
- Titanium plasma-sprayed PEEK:Hybrid surface engineering combining osseoconductive coatings with polymer elasticity is broadening fusion rate confidence among spine surgeons.
Market Restraints
- High-purity PEEK resin concentration:Supply dependency on specialized polymer manufacturers in Germany and Switzerland creates input cost volatility and allocation risk during demand surges.
- FDA 510(k) clinical evidence thresholds:Expanding requirements for radiographic fusion data are extending development timelines and inflating premarket validation expenditures.
- 3D-printed titanium cages:Additive-manufactured alternatives with customizable porosity are capturing revision case volumes where bone ingrowth failure rates drive implant selection.
Strategic Opportunities
- Japan's aging surgical population:Underpenetrated demand for motion-preserving fusion alternatives in metropolitan Tokyo and Osaka hospital systems offers expansion potential for expandable device portfolios.
- Patient-specific 3D-printed PEEK:Convergence of computed tomography segmentation with selective laser sintering is enabling anatomically matched implants for complex deformity corrections.
- Bundled payment models:United States Center for Medicare and Medicaid Services procedural packaging is creating procurement incentives for devices with embedded predictive monitoring capabilities.
Industry Challenges
- Biomaterials engineering specialization:Scarce talent pools combining polymer science with orthopedic biomechanics are constraining R&D throughput at mid-scale manufacturers.
- EU notified body capacity:MDR certification queue congestion is delaying conformity assessment completion and compressing product launch windows against competitor timelines.
- Legacy inventory obsolescence:Rapid specification shifts toward expandable designs are stranding static device inventories and forcing write-downs across distributor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyether Ether Ketone (PEEK) Interbody Devices Market |
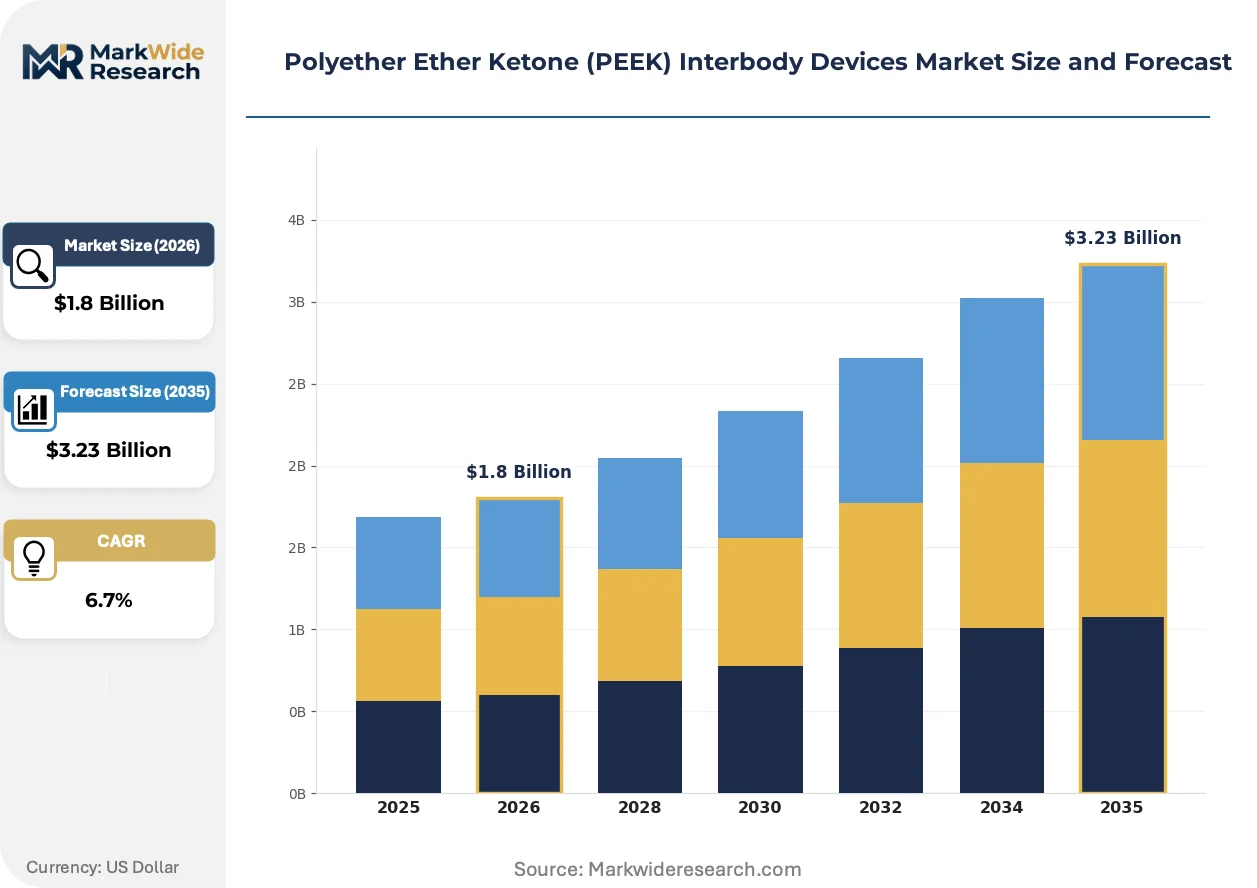
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cylindrical Devices, Boxed Devices, Expandable Devices, Customized Devices Application: Spinal Fusion, Anterior Interbody Fusion, Lateral Interbody Fusion, Posterior Interbody Fusion End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Rehabilitation Centers Technology: 3D Printing, Machining, Injection Molding, Surface Treatment |
| Companies Covered | Medtronic, Stryker Corporation, Zimmer Biomet, B. Braun Melsungen AG, SeaSpine Holdings Corporation, Shandong Weigao Group Medical Polymer Company Limited, Alphatec Holdings Inc, Xtant Medical Holdings Inc, Life Spine Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyether Ether Ketone (PEEK) Interbody Devices Market Evolving Landscape
Digital surgical planning and additive manufacturing are converging to collapse the traditional gap between anatomical assessment and implant delivery, reshaping how spine procedures are prepared and executed.
Expandable PEEK interbody devices with integrated mechanical height adjustment mechanisms are rendering obsolete the preoperative sizing uncertainty that previously required surgeons to maintain broad implant inventory. Leading academic medical centers in the United States and Germany are standardizing these configurations for degenerative disc disease procedures. Static cylindrical cages are retreating to emergency backup roles as hospitals consolidate SKU counts around adaptable platforms.
FDA draft guidance on 3D-printed medical devices is formalizing quality system requirements for point-of-care manufacturing while clarifying premarket submission expectations for patient-specific implants. Device sponsors must now demonstrate process validation across distributed production environments rather than centralized facilities. Small and mid-sized manufacturers are responding by partnering with specialized additive manufacturing service providers to access compliant production capacity without capital-intensive facility builds.
Surgeon training networks are displacing traditional distributor relationships as the primary channel for device selection influence in the United States. Hospital value analysis committees are increasingly deferring to institutional credentialing pathways that privilege platforms with embedded education infrastructure. This channel evolution concentrates procurement authority within integrated delivery networks that can mandate standardized implant portfolios across multiple surgical sites.
Polyether Ether Ketone (PEEK) Interbody Devices Market Segmentation
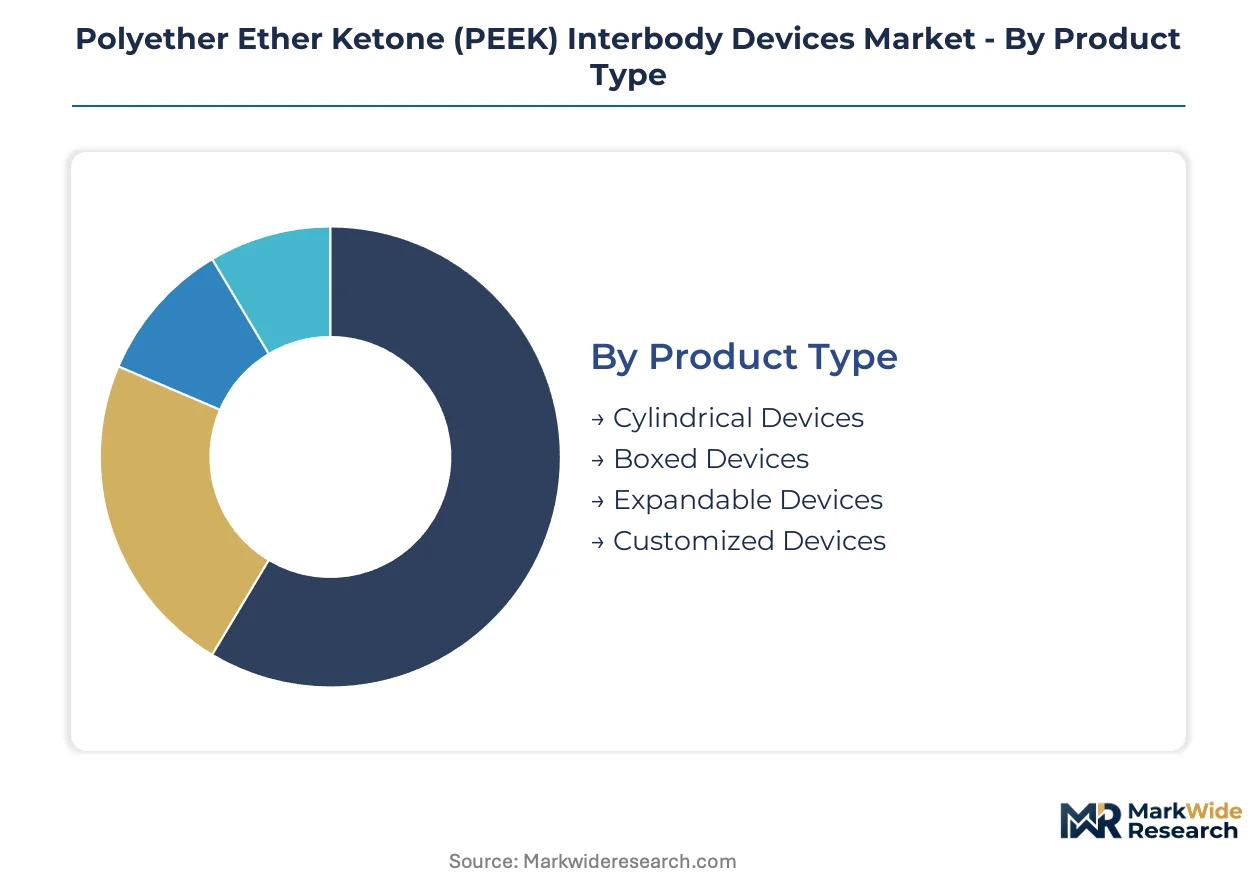
Segmentation in PEEK interbody devices reveals how surgeon workflow preferences and manufacturing capabilities partition commercial opportunity. Product architecture, procedural approach, and delivery setting each create distinct procurement pathways with unique margin profiles and regulatory requirements.
Product Type:
Mature geometries dominate hospital inventory while emerging configurations capture specification shifts in academic medical centers.
- Cylindrical Devices:Traditional threaded or smooth-walled implants machined from medical-grade PEEK resin. Demand concentrates in community hospitals across the United States where surgeon familiarity and established reimbursement codes sustain procurement volume despite limited intraoperative adjustability.
- Expandable Devices:Mechanically adjustable implants with integrated height expansion mechanisms enabling real-time fit optimization. Adoption accelerates in German and Japanese university hospitals where lateral interbody fusion procedures require precise endplate restoration under fluoroscopic guidance.
- Boxed Devices:Rectangular footprint implants with large graft windows for bone-to-bone contact.
- Customized Devices:Patient-matched geometries derived from preoperative imaging and produced via additive manufacturing or specialized machining.
Cylindrical devices retain volume leadership; expandable configurations hold the steepest expansion curve.
Application:
Procedural site selection drives device specification, with access corridor dictating footprint dimensions and mechanical loading requirements.
- Lateral Interbody Fusion:Transpsoas approaches through the retroperitoneal space. Demand concentrates in United States ambulatory surgical centers where minimally invasive technique migration enables same-day discharge protocols and expanded case scheduling capacity.
- Posterior Interbody Fusion:Transforaminal or posterior lumbar interbody approaches through the spinal canal. Volume localizes in German inpatient settings where complex deformity corrections and multilevel procedures require open posterior exposure for neural decompression concurrent with fusion.
- Anterior Interbody Fusion:Retroperitoneal or transperitoneal approaches to the lumbar spine.
- Spinal Fusion:General category encompassing all instrumented arthrodesis procedures without specified approach.
Posterior approaches sustain the highest procedure counts; lateral techniques are climbing the fastest.
End User:
Procurement authority concentrates in centralized supply chains while case volume migrates toward lower-acuity settings.
- Hospitals:Inpatient and outpatient departments within integrated delivery networks. Procurement runs through value analysis committees in United States health systems that standardize implant portfolios across multiple surgical sites to leverage volume-based pricing.
- Ambulatory Surgical Centers:Freestanding facilities specializing in same-day procedures. Volume expands in metropolitan Tokyo and Osaka where regulatory frameworks permit lateral interbody fusion outside traditional hospital settings and reimbursement incentives favor reduced length of stay.
- Specialty Clinics:Orthopedic-focused outpatient facilities without full surgical capabilities.
- Rehabilitation Centers:Post-acute care facilities managing recovery after implantation.
Hospitals retain procurement dominance; ambulatory surgical centers are gaining share fastest.
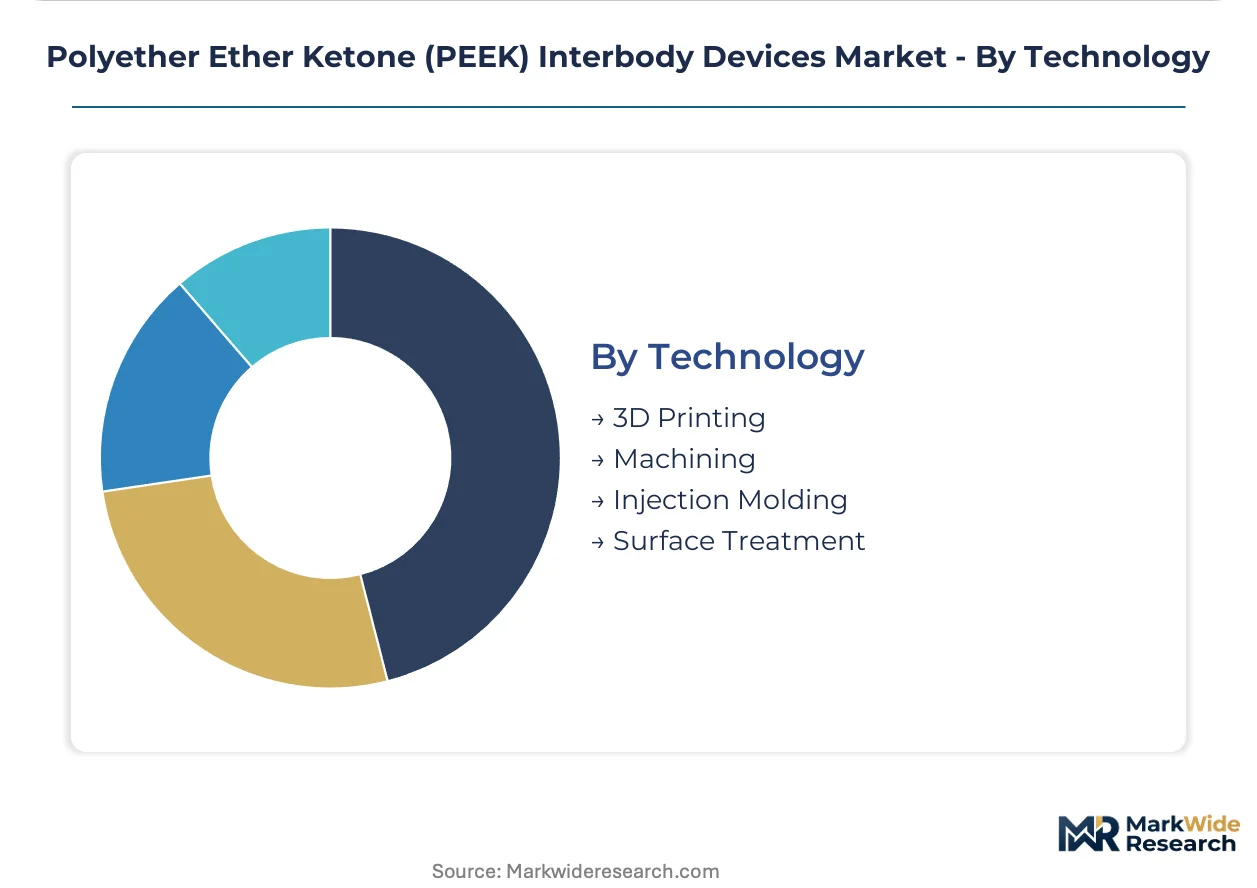
Technology:
Manufacturing method determines surface characteristics, geometric complexity, and production economics for device families.
- Machining:Subtractive manufacturing from extruded PEEK stock producing precise tolerances and smooth surfaces. Production concentrates in Swiss and German manufacturing clusters where medical device machining infrastructure supports tight radiopacity and dimensional specifications required by FDA 510(k) submissions.
- 3D Printing:Additive manufacturing via selective laser sintering enabling porous architectures and patient-specific geometries. Adoption accelerates in United States academic medical centers where point-of-care production models align with FDA draft guidance on distributed manufacturing quality systems.
- Injection Molding:High-volume production of standardized geometries with consistent material properties.
- Surface Treatment:Secondary processing including titanium plasma spraying or hydroxyapatite coating to enhance osseointegration.
Machining retains production volume leadership; 3D printing holds the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland exhibit low price elasticity due to specialized resin dependency, while United States procurement committees drive hard volume discounts through standardized implant portfolios.
United States
FDA 510(k) clearance pathways and CMS bundled payment models concentrate demand in integrated delivery networks across the Midwest and Southeast. Hospital value analysis committees in Cleveland Clinic and Mayo Clinic systems mandate expandable device specifications for lateral interbody fusion cases. Texas and Florida ambulatory surgical centers capture migrating outpatient volumes as minimally invasive techniques shift from inpatient settings.
Germany
EU MDR conformity assessments and statutory health insurance reimbursement frameworks sustain premium pricing for precision-machined implants. The Baden-Württemberg and Bavaria medical device clusters host specialized PEEK machining infrastructure serving European hospital procurement. University hospitals in Munich and Heidelberg standardize expandable configurations for complex deformity corrections requiring intraoperative adaptability.
Japan
PMDA regulatory frameworks and aging demographic surgical demand concentrate procurement in Tokyo and Osaka metropolitan hospital systems. The country's national health insurance program covers motion-preserving fusion alternatives with limited co-payment burden. Chiba and Kanagawa prefecture medical centers represent underpenetrated demand pockets for expandable device portfolios in lateral interbody fusion procedures.
Switzerland
Swissmedic certification requirements and high-purity PEEK resin manufacturing concentration create supply-side leverage for domestic producers. The Basel and Zurich orthopedic device clusters export precision-machined components to German and Austrian hospital supply chains. Cantonal hospital procurement cooperatives prioritize devices with embedded predictive monitoring capabilities under outcome-based contracting pilots.
China
NMPA registration pathways and provincial centralized procurement programs compress margins for imported implant portfolios. The Yangtze River Delta medical device manufacturing base in Jiangsu and Zhejiang provinces develops domestic PEEK machining capacity for local hospital procurement. Shanghai and Beijing tertiary hospitals drive demand for patient-specific 3D-printed configurations in complex spinal deformity cases.
Polyether Ether Ketone (PEEK) Interbody Devices Market Competitive Landscape
Capability concentration sits with integrated spine platform specialists; scale advantage sits with diversified orthopedic conglomerates. The market structure tiers across three archetypes: full-platform integrators capturing recurring clinical value, specialized PEEK machinists defending technical differentiation, and regional fabricators competing on localized service responsiveness. Dominant competitive moves include surgeon training network expansion and point-of-care manufacturing partnerships for distributed 3D printing capacity.
Within the full-platform integrator tier, Medtronic and Stryker Corporation exemplify archetypes combining implant portfolios with predictive analytics infrastructure. Among diversified orthopedic manufacturers, Zimmer Biomet occupies a position representing expandable configuration specialization. B. Braun Melsungen AG anchors the European precision manufacturing tier alongside SeaSpine Holdings Corporation representing mid-scale specialists in lateral interbody fusion platforms. These named entities represent competitive positioning patterns rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Medtronic |
| Stryker Corporation |
| Zimmer Biomet |
| B. Braun Melsungen AG |
| SeaSpine Holdings Corporation |
| Shandong Weigao Group Medical Polymer Company Limited |
| Alphatec Holdings Inc |
| Xtant Medical Holdings Inc |
| Life Spine Inc |
| Others |
Value Network & Pricing Analysis
Single-source dependency on high-purity PEEK resin manufacturers in Germany and Switzerland compresses margin flexibility across all pricing tiers while forcing hospital procurement committees toward volume-based contract structures that lock in supply allocation priority.
Pricing Analysis
Long-term offtake agreements between integrated delivery networks and device manufacturers dominate procurement, though spot purchasing persists for emergency revision cases. Pricing stratifies across premium, standard, and economy tiers based on surface treatment complexity and FDA 510(k) clearance vintage. Cost compression in the standard tier is intensifying because Chinese NMPA-registered competitors are penetrating provincial centralized procurement programs. Ambulatory surgical centers exhibit the highest price sensitivity due to bundled payment constraints, while German university hospitals show lowest elasticity given statutory insurance reimbursement stability.
Supply Chain Analysis
Extended payment terms from major hospital systems are forcing mid-scale manufacturers toward supply-chain finance facilities backed by specialized polymer distributors. Raw material production concentrates in Germany, Switzerland, and China's Yangtze River Delta. The supply chain rests on medical-grade PEEK resin, precision machining equipment, and titanium plasma-spray coating services. Single-source vulnerability sits with Victrex and Solvay resin allocation during demand surges. Distribution runs through orthopedic implant distributors with surgeon training network affiliations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is approaching a platform-economics inflection as predictive analytics bundling transforms device vendors into recurring-revenue service providers, with interoperability between implant portfolios and surgical planning software determining procurement lock-in.
For Market Incumbents: Build switching-cost moats through embedded predictive monitoring capabilities that tether revision surveillance to original device sales. Deepen backward integration into PEEK resin compounding to secure allocation priority during supply crunches. Capture surgeon training network density before 3D-printed patient-specific implants fragment specification authority.
For New Entrants and Emerging Players: Build out point-of-care manufacturing partnerships that leverage FDA draft guidance on distributed quality systems without capital-intensive facility builds. Target underpenetrated lateral interbody fusion demand in Japan's Chiba and Kanagawa prefectures where regulatory frameworks now permit ambulatory procedures. Lead with expandable device platforms that address intraoperative fit variability as the primary procurement specification.
For Investors and Strategic Acquirers: EU MDR notified body capacity constraints reshape the acquisition landscape by compressing product launch windows and privileging manufacturers with existing conformity assessments. Focus on mid-scale specialists with lateral interbody fusion platform concentration and established EU technical documentation. Watch FDA guidance finalization on 3D-printed devices as the inflection signal for patient-specific implant scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Surgeon Training Network Expansion | Hospital value analysis committees defer to institutional credentialing pathways privileging education-embedded platforms. |
| Point-of-Care Manufacturing Partnership | FDA draft guidance on distributed quality systems enables compliant production without centralized facility capital. |
| Expandable Device Portfolio Development | Static cylindrical cages are retreating to emergency backup roles as hospitals consolidate SKU counts. |
| Predictive Analytics Bundling | CMS procedural packaging creates procurement incentives for devices with embedded revision monitoring capabilities. |
| EU MDR Technical Documentation Investment | Notified body queue congestion compresses launch windows against competitors with existing conformity assessments. |
Research Methodology
A spread of perspectives from spine surgeons, hospital purchasing committee directors, biomedical engineers, GPO contracts managers, and orthopedic device R&D heads converged on the working assumptions underlying demand projections. Primary intelligence combined structured interviews with secondary validation against FDA 510(k) clearance databases, EU MDR notified body registration records, hospital procurement contract repositories, and CMS Medicare claims data. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue segmentation.
Demand-supply balance modeling across the projection horizon integrated expandable versus static device substitution rates, lateral interbody fusion migration to ambulatory settings, and 3D-printed titanium competitive displacement in revision cases. Segmentation dimensions included product architecture, procedural approach, delivery setting, and manufacturing technology. CAGRs derived from weighted average of historical procedure growth and penetration curve analysis for emerging configurations.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic manufacturers or accelerated FDA 510(k) clearance for patient-specific implants would shift outcomes. Macroeconomic contraction affecting elective procedure volumes, regulatory deviation in EU MDR implementation timelines, or breakthrough osseointegration coatings for titanium alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Penile Implants Market
Medical Devices
Asia-Pacific General Surgical Devices Market
Medical Devices
Adsorption Apheresis Devices Market
Medical Devices
Global Medical Tricorder Device Market
Medical Devices
Mobile Operating Rooms Market
Medical Devices
Cardiac Ablation Devices Market
Medical Devices
Urinary Incontinence Devices Market
Medical Devices
Breast Biopsy Localization Wire Market
Medical Devices
Inhaled Corticosteroid Device Market
Medical Devices
Australia General Surgical Devices Market
Medical Devices
Oral Appliance Market
Medical Devices
Urodynamic Devices Market
Medical Devices
Cranial Perforator Market
Medical Devices
Single-Lead ECG Monitors Market
Medical Devices
Global Cardiac Pacemakers Market
Medical Devices
Absorbable Antibacterial Envelope Market