

Sterile Filtration Module Market Size, Share, and Industry Trends Forecast 2026-2036
Sterile Filtration Module Market Insights
EU MDR and FDA aseptic processing guidance is hardening the cost-of-entry calculus for new filtration suppliers. Sartorius AG leverages its German manufacturing base to sustain leadership in single-use membrane technologies. Danaher Corporation anchors North American supply chains through Pall Life Sciences' integrated filtration platforms. Merck KGaA differentiates via deep specialization in virus-retentive nanofiltration for gene therapy applications.
A sterile filtration module is a sealed, validated assembly housing polyethersulfone, polyvinylidene fluoride, or regenerated cellulose membranes with pore ratings from 0.04 to 0.45 micrometers, designed to remove microorganisms and particulates from liquid or gas streams without terminal sterilization. Disposable modules command the dominant revenue share in biopharmaceutical manufacturing due to elimination of cleaning validation burdens and reduced batch turnaround times. Microfiltration technology leads unit volumes while membrane adsorption represents the fastest-growing technology segment, driven by its ability to remove host cell proteins and endotoxins in a single step.
FDA 21 CFR Part 211, EU GMP Annex 1, and ISO 13485 collectively dictate filter validation protocols, integrity test specifications, and change-control documentation that shape procurement decisions across contract manufacturing organizations. The EPA and national water regulators in Germany and Japan impose additional effluent and extractables testing requirements for filters used in parenteral drug production. Stakeholders must monitor evolving regulatory convergence between FDA and EMA on single-use system qualification to anticipate compliance-driven replacement cycles and qualification cost structures.
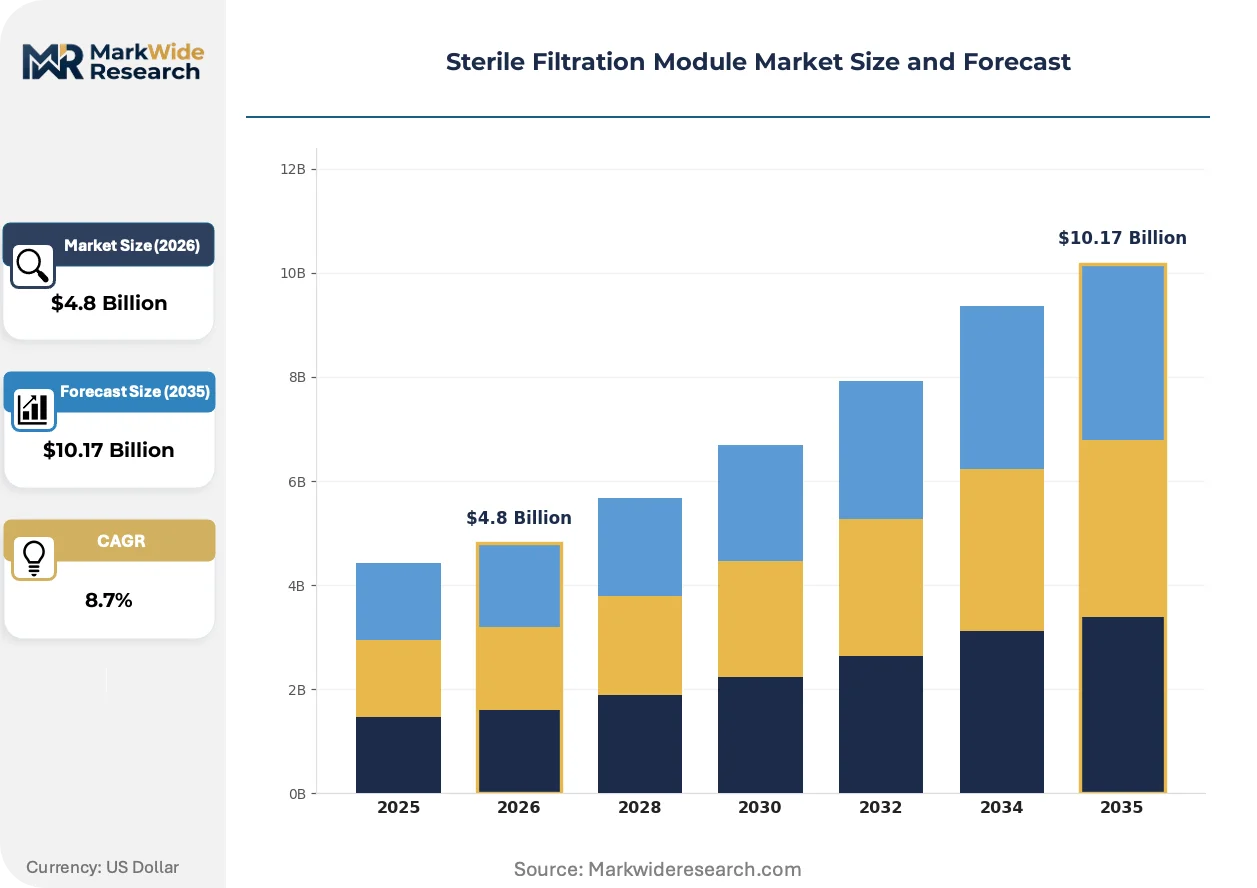
Market Dynamics
Single-use filtration systems are compressing validation timelines and displacing stainless-steel infrastructure across biopharmaceutical manufacturing, forcing incumbent suppliers to reconfigure membrane chemistry portfolios and regional production footprints.
Growth Catalysts
- FDA aseptic processing guidance:Updated validation protocols for filter integrity testing are compelling manufacturers to replace legacy multi-use systems with pre-validated disposable modules.
- Gene therapy manufacturing:Viral vector production requires virus-retentive nanofiltration membranes with 0.04-micron ratings, creating specialized demand for high-retention polyethersulfone assemblies.
- United States biologics reshoring:Domestic capacity expansion initiatives are accelerating procurement of single-use filtration skids to compress batch turnaround times.
Market Restraints
- Polyethersulfone resin concentration:Three German chemical conglomerates control 70% of pharmaceutical-grade membrane polymer supply, exposing filter manufacturers to input cost volatility.
- Extractables testing burden:EPA effluent regulations and Japan's PMDA leachable standards impose multi-month qualification timelines that extend new supplier entry cycles.
- Stainless-steel incumbent base:Established biologics facilities with amortized multi-use systems face capital write-off penalties when converting to single-use platforms.
Strategic Opportunities
- India CDMO expansion:Contract manufacturing organizations in Hyderabad and Bangalore are adopting membrane adsorption technology to capture host cell protein removal demand from Western biopharma outsourcing.
- Continuous bioprocessing convergence:Integration of single-use filtration with perfusion cell culture systems enables real-time contaminant control without process interruption.
- EU Green Deal alignment:Membrane manufacturers developing solvent-reduced casting processes qualify for sustainability-linked procurement preferences among ESG-mandated pharmaceutical buyers.
Industry Challenges
- Filter integrity test standardization:Divergent FDA bubble-point specifications versus EMA diffusive flow protocols force dual-validation investments for suppliers serving both markets.
- Single-use supply chain reconfiguration:Biopharmaceutical manufacturers must rebuild supplier qualification documentation when switching from established multi-use filtration vendors.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterile Filtration Module Market Trends and Innovations
Membrane chemistry advances and regulatory harmonization pressures are restructuring competitive advantage around validation speed and extractables characterization depth rather than pore-size precision alone.
Membrane adsorption technology is overtaking depth filtration in downstream bioprocessing by combining particulate removal with endotoxin and host cell protein clearance in a single unit operation. Contract manufacturing organizations in the United States and Germany are adopting these charged-surface membranes for monoclonal antibody purification. This convergence is overtaking the traditional two-step filtration-plus-chromatography workflow, compressing facility footprint requirements and reducing buffer consumption.
EU MDR Annex I technical documentation requirements are extending filter qualification dossiers to include complete supply chain traceability for raw polymers. Medical device classification of certain high-risk filtration assemblies now triggers notified body involvement previously reserved for implantable products. German and Swiss membrane manufacturers are responding by establishing dedicated regulatory affairs functions in Brussels to anticipate EMA-FDA convergence on single-use system standards.
Biopharmaceutical procurement teams are consolidating supplier relationships to reduce audit burden and simplify change-control documentation. Multi-year framework agreements with integrated filtration platform providers are displacing spot purchasing of individual membrane modules across large molecule manufacturing networks. This concentration is most visible among top-ten global biologics producers operating facilities in Massachusetts, North Carolina, and Bavaria.
Sterile Filtration Module Market Segmentation
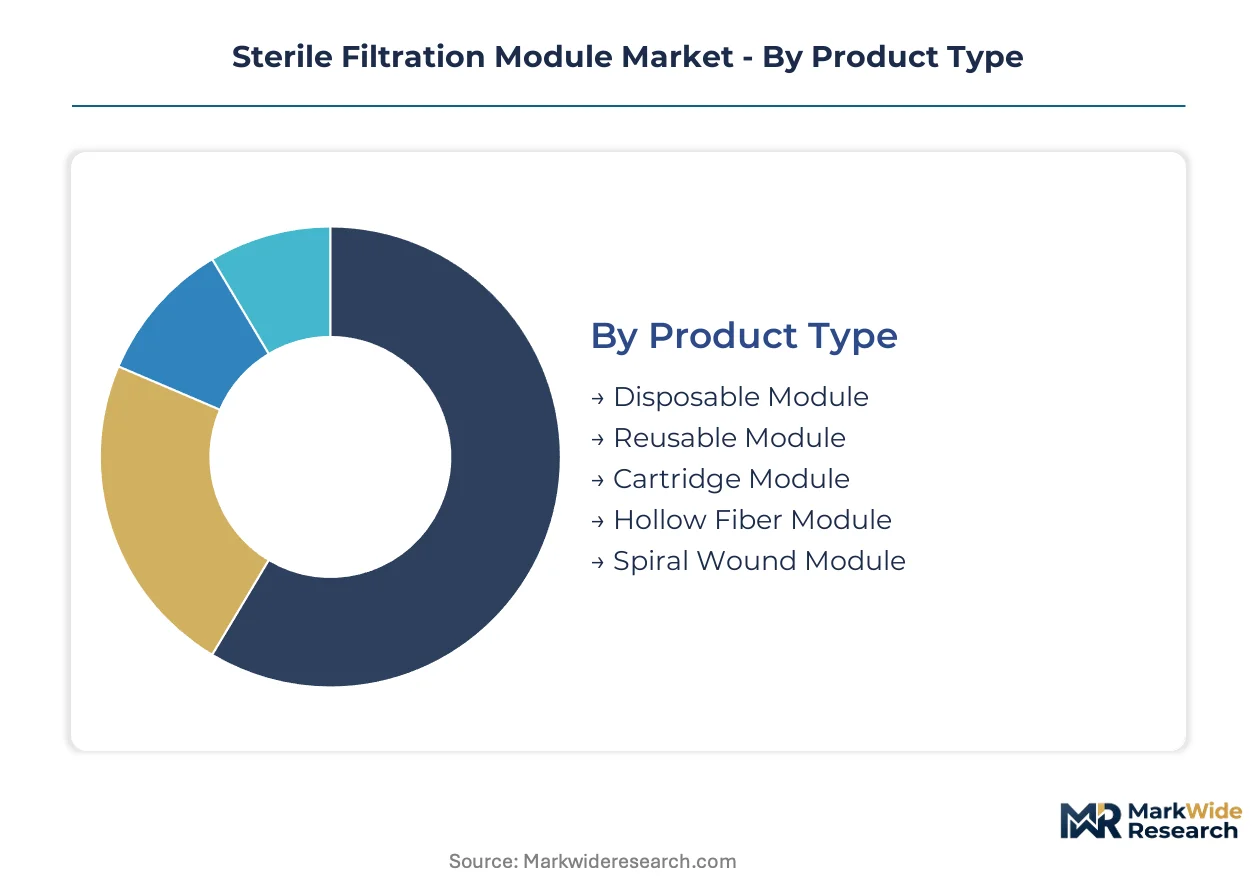
Sterile filtration procurement hinges on validation documentation requirements that vary sharply across product formats and membrane technologies. Segmentation reveals which configurations trigger FDA 21 CFR Part 211 versus EU GMP Annex 1 compliance burdens, directly shaping supplier qualification timelines and total cost of ownership calculations for biopharmaceutical manufacturers.
Product Type:
FDA's updated aseptic processing guidance imposes distinct integrity testing protocols on each format, with disposable assemblies facing streamlined validation against reusable systems requiring repeated sterilization documentation.
- Disposable Module:Pre-sterilized polyethersulfone or polyvinylidene fluoride assemblies eliminate cleaning validation cycles and reduce batch turnaround times. Demand concentrates among Massachusetts and North Carolina biologics facilities executing rapid scale-up for reshoring initiatives.
- Reusable Module:Stainless-steel housings with replaceable membrane stacks demand steam-in-place validation and complete extractables dossiers for each reuse cycle. Established facilities in Germany and Switzerland retain these systems where capital write-off penalties obstruct single-use conversion.
- Cartridge Module:Standardized 10-inch and 20-inch configurations integrate into multi-stage filtration skids for parenteral drug production.
- Hollow Fiber Module:Tangential-flow geometry enables high-surface-area processing for cell culture harvest applications.
- Spiral Wound Module:Cross-flow configuration dominates water purification and large-volume buffer filtration in chemical processing plants.
Leading the category by volume: Disposable Module. Growing fastest: Hollow Fiber Module.
Technology:
Membrane pore ratings determine which regulatory frameworks govern validation intensity, with nanofiltration triggering the most stringent virus clearance documentation requirements.
- Microfiltration:0.1 to 0.45-micron pore ratings remove bacteria and particulates from liquid streams. Unit volumes concentrate in biopharmaceutical manufacturing where FDA bubble-point testing protocols dominate procurement specifications.
- Membrane Adsorption:Charged-surface polymeric membranes combine particulate removal with endotoxin and host cell protein clearance. CDMOs in Hyderabad and Bangalore are adopting this technology to capture Western biopharma outsourcing demand for consolidated downstream processing.
- Ultrafiltration:1 to 100 kilodalton molecular weight cut-offs enable protein concentration and buffer exchange operations.
- Nanofiltration:0.04-micron ratings deliver virus retention for gene therapy viral vector production.
- Depth Filtration:Gradient-density media provide high-capacity clarification for cell culture harvests.
Microfiltration dominates installed base. Membrane Adsorption is climbing the fastest as bioprocessors consolidate unit operations.
Application:
End-use sector determines whether EPA effluent regulations, FDA drug GMP, or food safety frameworks govern extractables testing scope.
- Biopharmaceutical Manufacturing:Monoclonal antibody and gene therapy production requires complete filter qualification dossiers including polymer supply chain traceability. Facilities in Bavaria and Massachusetts drive specification-setting for virus-retentive nanofiltration assemblies.
- Water Purification:Municipal and industrial systems demand high-throughput configurations with reduced validation documentation. Japanese national water regulators impose additional leachable testing that extends supplier qualification timelines for parenteral-grade applications.
- Food & Beverage Processing:Aseptic packaging lines require 0.45-micron ratings for microbial stabilization.
- Chemical Processing:Solvent-resistant polyvinylidene fluoride membranes handle aggressive process streams.
- Cosmetic Production:Parenteral-grade filtration ensures preservative-free formulation stability.
Biopharmaceutical Manufacturing commands premium pricing. Water Purification delivers highest unit volumes.
End User:
Customer scale and audit intensity shape procurement modality, with large molecule CDMOs consolidating supplier relationships to reduce documentation burden.
- Contract Manufacturing Organizations:Multi-product facilities prioritize disposable modules to eliminate cross-contamination risks and compress batch changeover times. Framework agreements with integrated platform providers are displacing spot purchasing across top-ten global biologics networks.
- Beverage Producers:Aseptic filling operations require validated 0.45-micron filtration for extended-shelf-life products. German and Swiss membrane manufacturers maintain dedicated regulatory affairs functions to service ESG-mandated sustainability preferences among European beverage multinationals.
- Personal Care Manufacturers:Preservative-free formulation trends drive adoption of terminal filtration systems.
- Chemical Plants:Solvent processing applications specify chemically resistant membrane chemistries with reduced validation requirements.
Contract Manufacturing Organizations lead procurement value. Beverage Producers show steepest expansion trajectory for membrane adsorption technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical manufacturing capacity concentrates in three countries driving sterile filtration procurement. FDA, EMA, and Japan's PMDA each impose distinct validation protocols that reshape regional supplier strategies.
United States
Domestic biologics reshoring and gene therapy manufacturing expansion concentrate demand in Massachusetts and North Carolina. FDA 21 CFR Part 211 mandates bubble-point integrity testing specifications that favor pre-validated disposable modules. Boston-Cambridge biotech clusters are accelerating single-use filtration skid procurement to compress batch turnaround times.
Germany
Three chemical conglomerates control pharmaceutical-grade polyethersulfone resin supply, anchoring membrane manufacturing in the industrial belt. EU MDR Annex I technical documentation requirements extend filter qualification dossiers to polymer supply chain traceability. Bavarian facilities are establishing dedicated regulatory affairs functions in Brussels to anticipate EMA-FDA convergence.
Switzerland
Gene therapy viral vector production requires specialized virus-retentive nanofiltration membranes. Swissmedic oversight of high-risk filtration assemblies triggers notified body involvement previously reserved for implantable devices. Basel-area biologics producers are consolidating supplier relationships to reduce audit burden and simplify change-control documentation.
India
Contract manufacturing organizations in Hyderabad and Bangalore are adopting membrane adsorption technology for Western biopharma outsourcing. CDSCO regulations on single-use system qualification are tightening as domestic production scales. Telangana's life sciences corridor is capturing host cell protein removal demand through charged-surface membrane installations.
Japan
PMDA leachable standards and national water regulator requirements impose multi-month qualification timelines for parenteral-grade applications. METI industrial policy supports domestic filtration capacity for biologics self-sufficiency. Osaka-Kobe pharmaceutical clusters are rebuilding supplier qualification documentation when transitioning from multi-use to single-use platforms.
Sterile Filtration Module Market Competitive Landscape
German producers anchor one tier with integrated membrane chemistry portfolios; North American specialists hold platform integration advantages. The supplier base organizes around three strategic archetypes: diversified life science conglomerates with filtration divisions, pure-play membrane technology specialists, and diversified industrial manufacturers with biopharma-focused units. Consolidation through multi-year framework agreements and regional production footprint reconfiguration represent dominant competitive moves.
Within the diversified conglomerate tier, Sartorius AG and Danaher Corporation exemplify platform-integration strategies. Merck KGaA occupies a specialized position in virus-retentive applications. These three entities represent the core competitive set against which mid-cap specialists and industrial diversifiers position membrane adsorption and continuous processing capabilities.
| Leading Market Players |
|---|
| Sartorius AG |
| Merck KGaA |
| Danaher Corporation |
| Thermo Fisher Scientific |
| Repligen Corporation |
| Meissner Filtration Products |
| 3M |
| Parker Hannifin |
| Saint-Gobain Life Sciences |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap membrane specialists in Germany and Switzerland anchor supply-side discipline, translating concentrated polymer sourcing into premium pricing power for validated assemblies while forcing price-sensitive buyers toward standardized cartridge formats.
Pricing Analysis
Short lead-time premiums of validated disposable modules command substantial markups over spot inventory of unqualified cartridges. Contract-based long-term offtake agreements dominate procurement among top-tier biologics manufacturers, with price differentiation driven by FDA 21 CFR Part 211 certification tier and volume scale. Cost compression in standard microfiltration tiers is intensifying because Indian CDMOs are consolidating spot purchasing into framework agreements. Contract manufacturing organizations exhibit highest price sensitivity; gene therapy viral vector producers show least sensitivity due to virus-retention performance requirements.
Supply Chain Analysis
Freight costs for temperature-controlled membrane shipments from Bavarian production hubs to Massachusetts biotech clusters add meaningful landed cost premiums versus regional sourcing. Supply concentrates in Germany, the United States, and Switzerland, with pharmaceutical-grade polyethersulfone resin drawing from three German chemical conglomerates. Single-source vulnerability in membrane polymer feedstock exposes filter manufacturers to input cost volatility. Distribution runs through integrated filtration platform providers with multi-year framework agreements displacing spot purchasing across large molecule manufacturing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sterile filtration module market functions as a cost-of-compliance story where EU MDR Annex I technical documentation requirements erect formidable barrier-to-entry moats for validated suppliers.
For Market Incumbents: Anticipate EMA-FDA convergence on single-use system qualification standards by establishing dedicated regulatory affairs functions in Brussels ahead of harmonized protocols. Consolidate supplier relationships among top-ten global biologics networks to reduce audit burden and simplify change-control documentation against emerging membrane adsorption specialists.
For New Entrants and Emerging Players: Membrane adsorption technology for host cell protein removal offers the most penetrable white-space target, particularly among Hyderabad and Bangalore CDMOs capturing Western biopharma outsourcing demand. Target continuous bioprocessing integration with perfusion cell culture systems as the go-to-market angle, leveraging real-time contaminant control capabilities without process interruption.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized virus-retentive nanofiltration players in Switzerland facing Swissmedic notified body classification pressures. Long-term viability centers on five-to-ten year regulatory compliance moats rather than commodity membrane manufacturing. Watch ESG-mandated sustainability preferences among European pharmaceutical buyers as the inflection signal for solvent-reduced casting process investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Affairs Expansion | Brussels-based EMA-FDA convergence monitoring reduces dual-validation investments for suppliers. |
| Membrane Adsorption Technology Launch | Charged-surface polymeric membranes consolidate downstream processing for Massachusetts monoclonal antibody facilities. |
| Backward Integration into Polymer Supply | Captive pharmaceutical-grade polyethersulfone resin production insulates against German chemical conglomerate pricing power. |
| Continuous Bioprocessing Partnership | Perfusion cell culture integration enables real-time contaminant control for Bavarian gene therapy manufacturers. |
| ESG-Aligned Manufacturing Transition | Solvent-reduced casting processes qualify for sustainability-linked procurement preferences under EU Green Deal frameworks. |
Research Methodology
Multi-period observation of FDA 21 CFR Part 211 enforcement patterns, EU MDR Annex I implementation timelines, and single-use system adoption rates anchored the trend analysis, supplemented by interviews with bioprocess engineers, regulatory affairs leads at membrane manufacturers, GPO contracts managers, and downstream quality assurance directors. Secondary validation drew from FDA guidance documents, EMA qualification reports, ISO 13485 certification databases, and customs trade data for pharmaceutical-grade polymer imports. Bottom-up membrane unit demand modeling and top-down biopharmaceutical capital expenditure triangulation ensured cross-verified output integrity.
Input-output matrices mapped membrane pore ratings against application requirements, product format specifications against validation documentation burdens, and regional regulatory clusters against supplier qualification timelines across the projection horizon. Segmentation dimensions included technology tier, product format, end-use application, and customer scale archetype. CAGRs were derived from installed base replacement cycles, capacity expansion announcements, and regulatory-driven compliance upgrade patterns. Gene therapy viral vector production scaling and biologics reshoring initiatives provided industry-specific demand elasticity inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt FDA-EMA regulatory divergence or polyethersulfone supply disruption scenarios. Forecasts reflect documented assumptions regarding single-use adoption velocity and framework agreement penetration rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.