
 Multi Dose Drug Vial Adapters Market | 2026-2036
Multi Dose Drug Vial Adapters Market Size, Share, and Industry Trends Forecast 2026-2036
Multi Dose Drug Vial Adapters Market Foresight
Polypropylene is hardening its position over polycarbonate in multi-dose vial adapter housings as manufacturers chase lower extractables profiles and gamma sterilization compatibility. Baxter International leverages captive resin sourcing and in-house molding to protect margin structure across North American hospital contracts. Becton Dickinson and Company anchors its position through needle-free valve technology leadership, while West Pharmaceutical Services, Inc. specializes in elastomer formulation science for multi-puncture septa.
Multi dose drug vial adapters are sterile, single-patient-use interfaces that pierce a vial stopper to enable repeated withdrawal of medication without compromising closure integrity; they typically incorporate a luer-lock or spike connection, an elastomeric or thermoplastic septum, and a plastic body rated for 13mm to 20mm vial neck finishes. Plastic adapters dominate unit volume due to cost scalability in high-throughput injection molding, though combination adapters integrating metal reinforcement rings command premium positioning in oncology applications where dosing precision carries liability weight. Manual technology still occupies the bulk of installed base, yet smart systems with RFID dose tracking represent the fastest-expanding margin pool as health systems seek diversion control.
FDA 21 CFR Part 211 current good manufacturing practice requirements and EU MDR Class IIa device classifications shape material validation burdens and biocompatibility testing protocols for any adapter entering regulated channels. The country's national pharmaceutical regulator in Japan enforces JIS T 0320 standards for elastomeric closures, creating a parallel compliance track for suppliers targeting that market. Stakeholders must monitor how USP <797> and <800> sterile compounding revisions redirect purchasing criteria toward closed-system transfer devices that integrate vial adapters, as this regulatory vector will determine which product architectures survive formulary review.
Market Dynamics
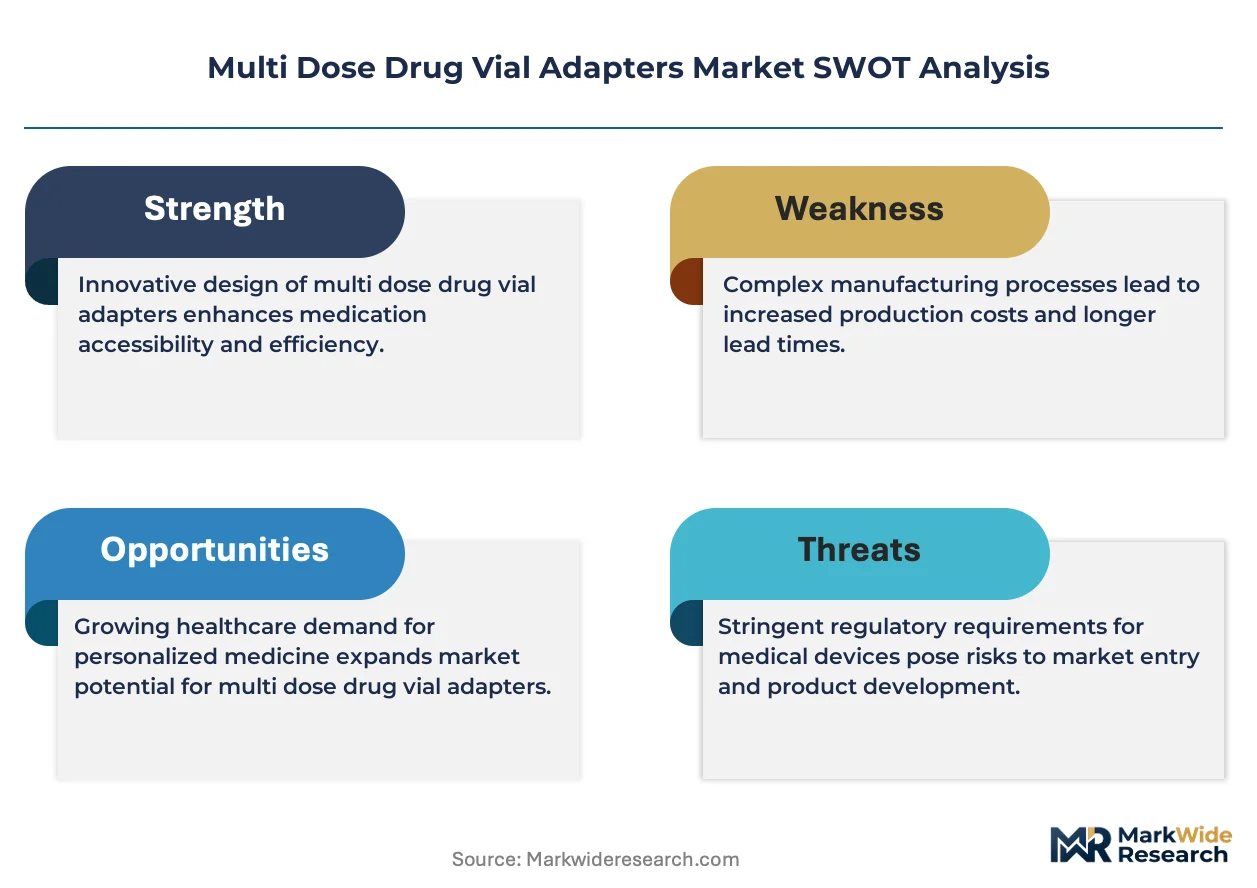
FDA 21 CFR Part 211 and EU MDR Class IIa classifications are hardening material validation burdens, forcing adapter manufacturers toward elastomer-coated interfaces and gamma-compatible resins that protect closure integrity across repeated puncture cycles.
Growth Catalysts
- Oncology compounding volumes:Hospital pharmacies in the United States, Germany, and Japan are expanding adapter procurement to support sterile preparation of cytotoxic therapies. This demand concentrates where compounding infrastructure is most mature.
- EU MDR device reclassification:Tightened vial closure integrity standards are accelerating material upgrades across European supply chains. Manufacturers must demonstrate biocompatibility and extractables profiles that exceed prior benchmarks.
- Closed-system transfer device integration:USP <797> and <800> revisions are redirecting purchasing criteria toward adapters that integrate with CSTD architectures. Health systems prioritize products that reduce hazardous drug exposure risk.
Market Restraints
- Medical-grade resin cost volatility:Polypropylene and thermoplastic elastomer feedstock prices fluctuate with petrochemical cycles. Converter margins compress when raw material spikes coincide with fixed hospital contract terms.
- Single-source sterilization dependency:Gamma irradiation capacity concentrates among contract providers in the United States and Western Europe. Bottlenecks emerge when demand surges exceed facility throughput.
- Metal-reinforced adapter substitution:Combination adapters with stainless steel rings command oncology premium positioning. Standard plastic variants face displacement in high-liability dosing applications.
Strategic Opportunities
- Japanese JIS T 0320 compliance track:Elastomeric closure standards enforced by the country's national pharmaceutical regulator create parallel certification requirements. First-mover suppliers capture formulary preference in this high-value market.
- RFID-enabled diversion control:Smart adapters with embedded dose-tracking chips are penetrating health systems seeking pharmaceutical security. Technology convergence between medical devices and inventory management platforms opens new margin pools.
- Ambulatory infusion center expansion:Outpatient oncology settings in Germany and the United States are adopting manual adapters for cost-controlled environments. Channel innovation toward non-hospital sites diversifies revenue concentration.
Industry Challenges
- Biocompatibility testing timeline compression:ISO 10993 cytotoxicity and sensitization protocols require 12-18 month validation cycles. Product development schedules strain against contract renewal windows.
- Legacy CSTD integration complexity:Adapter geometries must interface with proprietary closed-system platforms from established suppliers. Mechanical incompatibility risks formulary exclusion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi Dose Drug Vial Adapters Market |
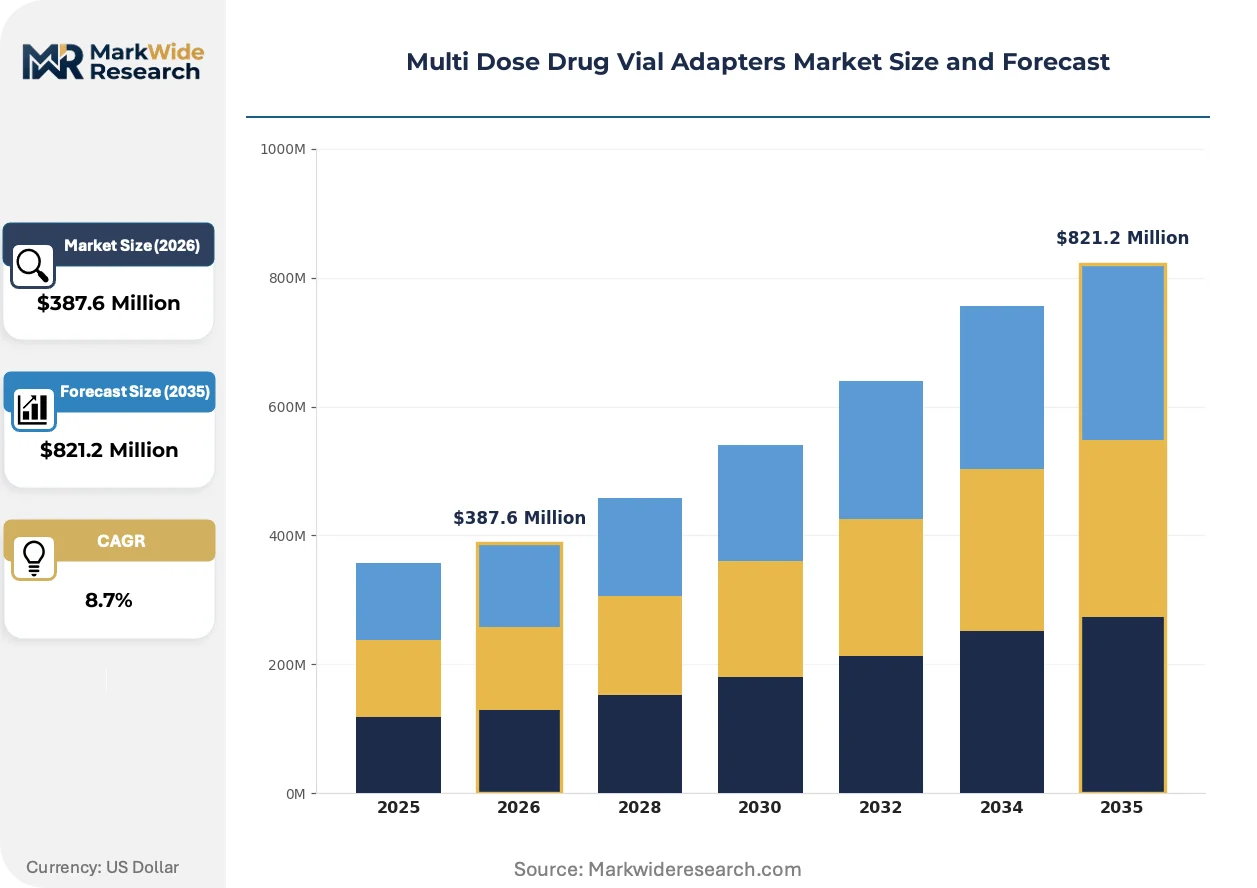
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Adapters, Metal Adapters, Rubber Adapters, Combination Adapters End User: Hospitals, Pharmacies, Research Laboratories, Home Healthcare Application: Oncology, Infectious Diseases, Pain Management, Anesthesia Technology: Manual, Automated, Hybrid, Smart Systems |
| Companies Covered | Baxter International Inc., Terumo Corporation, Becton Dickinson and Company, Gerresheimer AG, Nipro Corporation, West Pharmaceutical Services, Inc., Cardinal Health Inc., Ypsomed Holding AG, B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi Dose Drug Vial Adapters Market Shifts & Advancements
Active pharmaceutical ingredient complexity and hazardous drug handling protocols are reshaping how vial adapters incorporate materials, intelligence, and connectivity into sterile interfaces.
Needle-free valve technology is integrating RFID dose-tracking capabilities to enable real-time medication diversion monitoring. Hospital systems in the United States are piloting these smart adapters in oncology units where controlled substance accountability carries regulatory weight. The structural consequence is a bifurcation between commodity manual adapters and premium connected devices that command sustained margin premiums.
EU MDR technical documentation requirements are extending biocompatibility validation to every elastomer formulation variant. Manufacturers serving European markets must maintain design dossiers that trace material genealogy through molding, sterilization, and shelf-life testing. Smaller converters without dedicated regulatory affairs functions are ceding position to organizations with captive compliance infrastructure.
Health system consolidation is compressing supplier negotiation cycles and unbundling after-sales technical support from hardware pricing. Integrated delivery networks in Germany and Japan are standardizing on single-source adapter contracts that span multiple hospital sites. This behavioral shift favors manufacturers with direct field service presence over distributors unable to provide clinical education and complaint handling.
Multi Dose Drug Vial Adapters Market Segmentation
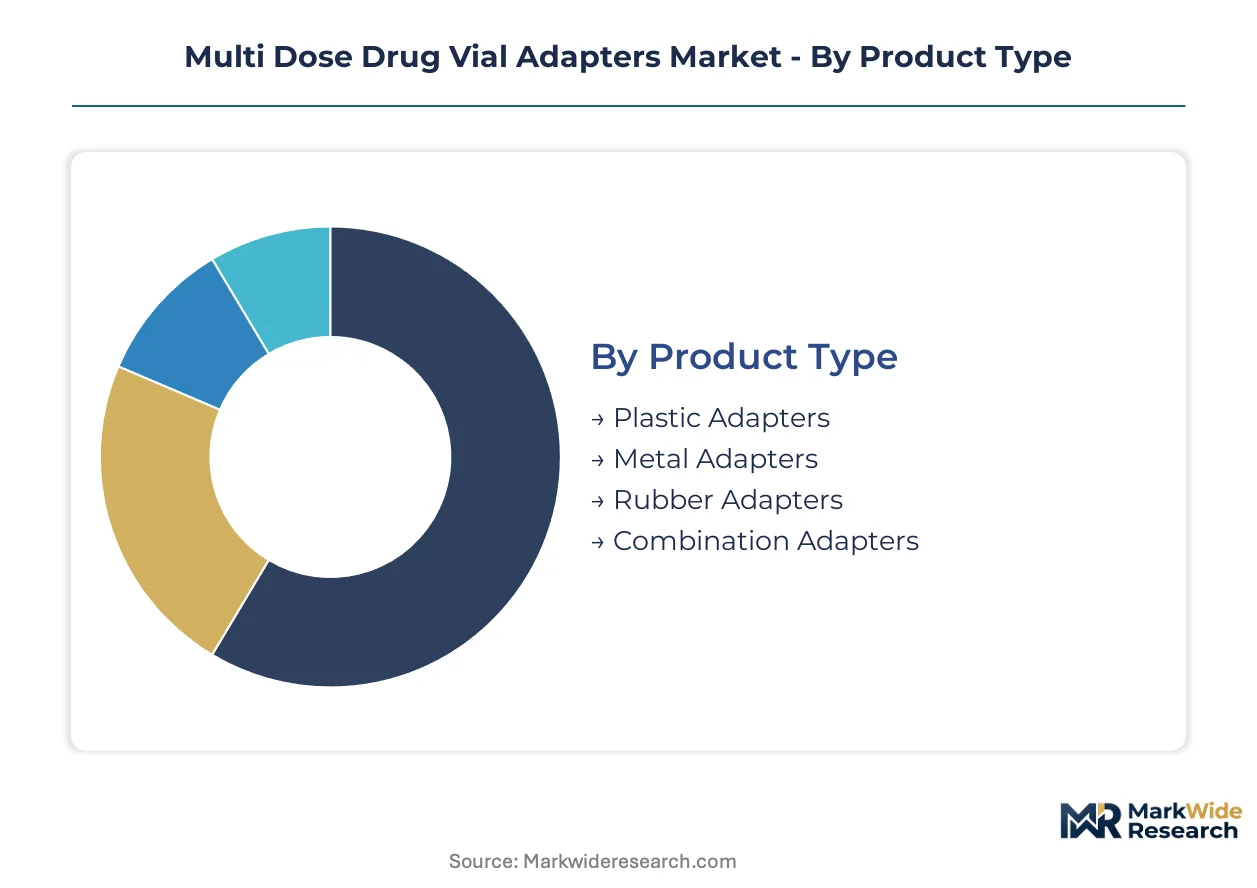
Multi dose drug vial adapters serve divergent clinical environments with distinct performance requirements, material constraints, and regulatory burdens. Segmentation reveals how procurement criteria fragment across acute care, compounding pharmacy, and ambulatory settings, each demanding specialized interface geometries and closure integrity specifications.
Product Type:
Cost tier and liability exposure separate buyers across material categories, with premium positioning commanding metal reinforcement and economy volumes concentrating in injection-molded plastics.
- Plastic Adapters:Polypropylene and polycarbonate housings dominate high-throughput hospital procurement due to gamma sterilization compatibility and scalable molding economics. Demand concentrates in United States ambulatory infusion centers where cost-controlled environments prioritize disposable unit economics over multi-puncture durability.
- Combination Adapters:Stainless steel reinforcement rings integrated with thermoplastic bodies capture oncology premium positioning where dosing precision carries malpractice exposure. German hospital pharmacies are expanding procurement of these hybrid architectures to meet EU MDR closure integrity standards for cytotoxic compounding.
- Metal Adapters:Machined aluminum or stainless steel variants serve specialized high-pressure applications requiring structural rigidity beyond thermoplastic limits.
- Rubber Adapters:Pure elastomeric constructions occupy niche positions in legacy vial systems requiring compliant septum interfaces.
Volume sits with plastic adapters; growth tilts toward combination architectures.
End User:
Volume scale and clinical liability create distinct purchasing behaviors across institutional settings, with centralized procurement favoring standardization and distributed sites demanding flexibility.
- Hospitals:Integrated delivery networks in Japan and Germany are consolidating adapter contracts across multiple sites, prioritizing suppliers with direct field service presence for clinical education and complaint handling. USP 797 and 800 compliance is redirecting formulary criteria toward closed-system transfer device compatibility.
- Pharmacies:Hospital-based and independent compounding operations represent the fastest-expanding demand pool as sterile preparation of hazardous drugs concentrates in regulated pharmacy environments. FDA 21 CFR Part 211 cGMP requirements are hardening material validation burdens for suppliers serving this channel.
- Research Laboratories:Preclinical and clinical trial operations require adapters with documented extractables profiles and batch-level material traceability.
- Home Healthcare:Patient-administered therapy settings in the United States are adopting simplified manual adapters for oncology and pain management regimens.
Procurement scale favors hospital systems; regulatory complexity is climbing fastest in pharmacy channels.
Application:
Drug hazard classification and dosing frequency determine adapter specification intensity, with cytotoxic therapies demanding the highest closure integrity and diversion control.
- Oncology:Cytotoxic and antineoplastic compounding drives premium adapter adoption where health systems prioritize needle-free valve technology and RFID-enabled dose tracking. United States oncology units are piloting smart adapters for controlled substance accountability under DEA and Joint Commission oversight.
- Infectious Diseases:Antibiotic and antiviral preparation in hospital pharmacies requires reliable multi-puncture septa for high-frequency vial access without compromising sterility.
- Pain Management:Opioid vial handling protocols are stimulating demand for diversion-resistant adapter designs in hospital and ambulatory settings.
- Anesthesia:Operating room environments favor rapid-connect adapters with secure luer-lock interfaces for time-critical medication access.
Revenue concentration rests with oncology; steepest expansion trajectory is emerging in pain management diversion control.
Technology:
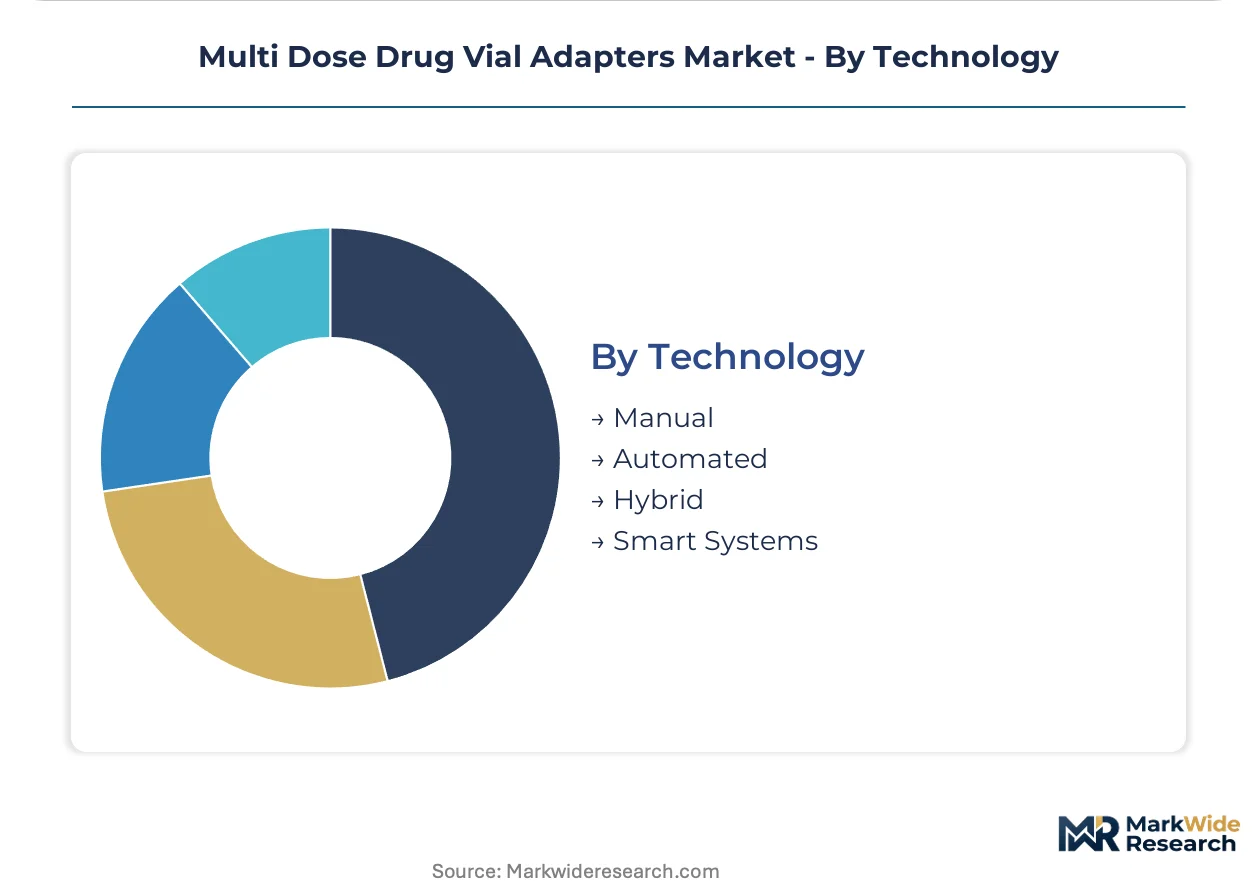
Automation maturity and connectivity integration separate legacy manual systems from emerging smart platforms, with capital availability and IT infrastructure determining adoption pace.
- Manual:Conventional spike and luer-lock adapters retain dominant installed base across cost-sensitive environments. German ambulatory infusion centers are expanding manual adapter procurement for outpatient oncology settings where capital constraints limit technology investment.
- Smart Systems:RFID-embedded adapters with real-time dose tracking are penetrating United States health systems seeking pharmaceutical security and inventory integration. Technology convergence between medical devices and enterprise resource planning platforms is opening new margin pools for connected device manufacturers.
- Automated:Robotic compounding systems with integrated adapter interfaces serve high-volume sterile preparation facilities in major academic medical centers.
- Hybrid:Semi-automated designs bridge manual flexibility with electronic verification for medication identification.
Installed base tilts toward manual systems; capability investment is concentrating in smart platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital pharmacies in the United States, Germany, and Japan concentrate adapter procurement where sterile compounding infrastructure for oncology therapies is most mature. Regulatory tightening across FDA, EU MDR, and Japan's PMDA is accelerating material upgrades toward elastomer-coated interfaces that protect closure integrity across repeated puncture cycles. Each geography presents distinct compliance tracks and channel structures that shape supplier positioning.
United States
Oncology compounding volumes and USP 797/800 hazardous drug handling protocols drive adapter demand through hospital pharmacies and ambulatory infusion centers. FDA 21 CFR Part 211 cGMP requirements harden material validation burdens for suppliers entering regulated channels. The Boston-Cambridge pharmaceutical corridor and New Jersey's sterile manufacturing cluster concentrate procurement decision-making among integrated delivery networks.
Germany
EU MDR Class IIa device reclassification is accelerating material upgrades across hospital pharmacy supply chains, with combination adapters commanding premium positioning. The country's national pharmaceutical regulator enforces closure integrity standards that exceed prior benchmarks for cytotoxic compounding. The Rhine-Main and Baden-Württemberg regions host concentrated pharmaceutical manufacturing infrastructure that shapes regional procurement criteria.
Japan
PMDA enforcement of JIS T 0320 elastomeric closure standards creates a parallel compliance track distinct from FDA and EU pathways. Hospital systems in Tokyo and Osaka are consolidating adapter contracts across multiple sites, prioritizing suppliers with direct field service presence. The Kanto region's pharmaceutical manufacturing density concentrates demand for high-integrity multi-puncture septa in oncology applications.
United Kingdom
Post-Brexit regulatory alignment with EU MDR technical documentation requirements extends biocompatibility validation burdens to adapter manufacturers serving NHS procurement channels. The MHRA maintains device classification frameworks that mirror EU Class IIa standards for closure integrity. London and the Southeast's health system consolidation is compressing supplier negotiation cycles toward single-source contracts.
India
CDSCO medical device rules and expanding hospital pharmacy infrastructure are creating new demand channels for cost-optimized plastic adapters in sterile compounding applications. The country's national pharmaceutical regulator is tightening import registration requirements for elastomeric closure components. Maharashtra and Gujarat's pharmaceutical manufacturing clusters are emerging as procurement decision centers for domestic health system networks.
Multi Dose Drug Vial Adapters Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers invest in gamma sterilization infrastructure and captive resin sourcing to protect margin structure across fixed hospital contracts. The supplier base organizes into three tiers: diversified medical device conglomerates with full regulatory affairs infrastructure, mid-scale converters specializing in elastomer formulation science, and regional fabricators serving cost-sensitive ambulatory channels. Strategic archetypes include integrated device-drug combination specialists, pure-play closure component suppliers, and health system service providers bundling clinical education with hardware. M&A activity and strategic partnerships concentrate around RFID-enabled smart adapter platforms and closed-system transfer device integration capabilities.
Among diversified medical device conglomerates, Baxter International Inc. and Becton Dickinson and Company occupy positions reflecting distinct strategic orientations toward hospital pharmacy contracting. Baxter's captive resin sourcing and in-house molding capabilities exemplify backward integration strategies that protect margin structures across North American integrated delivery networks. Becton Dickinson represents needle-free valve technology leadership within the premium adapter tier. West Pharmaceutical Services, Inc. anchors the elastomer formulation specialist archetype, with its positioning reflecting deep material science capabilities for multi-puncture septa applications. These three entities collectively illustrate how regulatory infrastructure scale and material specialization separate sustainable competitors from converters facing compliance-driven consolidation pressure.
| Leading Market Players |
|---|
| Baxter International Inc. |
| Terumo Corporation |
| Becton Dickinson and Company |
| Gerresheimer AG |
| Nipro Corporation |
| West Pharmaceutical Services, Inc. |
| Cardinal Health Inc. |
| Ypsomed Holding AG |
| B. Braun Melsungen AG |
| Others |
Supply & Pricing Matrix
Hospital pharmacy consolidation across United States integrated delivery networks is forcing adapter manufacturers toward multi-year contract structures with fixed unit pricing, compressing converter margins when medical-grade polypropylene and thermoplastic elastomer feedstock costs spike during petrochemical cycles.
Pricing Analysis
Volume sits with standard plastic adapters while margins concentrate in combination architectures with stainless steel reinforcement rings. Three-tier pricing structure across premium, standard, and economy levels separates oncology-grade metal-reinforced interfaces from gamma-compatible polypropylene housings and basic polycarbonate variants. Price differentiation stems from EU MDR Class IIa certification burden and after-sales clinical education bundling. Pricing pressure stems from health system procurement centralization demanding year-over-year unit cost reductions. Ambulatory infusion centers in Germany exhibit highest price sensitivity; United States oncology units show lowest sensitivity due to malpractice liability weight.
Supply Chain Analysis
FDA 21 CFR Part 211 and EU MDR technical documentation requirements gate supplier qualification, extending 12-18 month biocompatibility validation timelines that filter out converters lacking captive regulatory infrastructure. Manufacturing concentrates in United States, Germany, and Japan where gamma sterilization capacity and elastomer formulation expertise cluster. Raw material sourcing draws from medical-grade polypropylene resin, thermoplastic elastomer compounds, and 316L stainless steel rings. Single-source sterilization dependency among contract gamma providers in Western Europe creates bottleneck risk during demand surges. Distribution runs through direct hospital contracting and group purchasing organization channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RFID-enabled smart adapters are displacing conventional manual systems across United States oncology units, creating a technology-transition window where connected device capabilities determine formulary survival.
For Market Incumbents: Extend needle-free valve technology leadership into integrated closed-system transfer device platforms before emerging elastomer specialists capture EU MDR-compliant pharmacy contracts. Backward integration into captive resin sourcing protects margin structure against petrochemical volatility. Priority investment in gamma sterilization infrastructure reduces single-source dependency risk. For New Entrants and Emerging Players: Capture Japanese JIS T 0320 compliance track opportunities where first-mover suppliers secure formulary preference in Tokyo and Osaka hospital systems. Target ambulatory infusion center expansion in Germany with cost-optimized manual adapters for outpatient oncology settings. Go-to-market through direct field service presence rather than distributor intermediaries. For Investors and Strategic Acquirers: Re-rating potential sits with elastomer formulation specialists given EU MDR material upgrade acceleration and RFID technology convergence opening new margin pools. Long-term viability favors suppliers with dedicated regulatory affairs infrastructure and multi-puncture septa intellectual property. Watch for inflection in USP 797/800 enforcement intensity as signal for closed-system transfer device integration demand.| Strategic Initiative | Industry Significance |
|---|---|
| RFID-Enabled Smart Adapter Development | United States health systems pilot dose-tracking chips for DEA diversion control compliance. |
| EU MDR Technical Documentation Investment | German hospital pharmacies demand biocompatibility traceability exceeding prior closure integrity benchmarks. |
| Gamma Sterilization Capacity Expansion | Contract provider bottlenecks in Western Europe force captive facility investment. |
| Japanese JIS T 0320 Certification Track | PMDA enforcement creates parallel compliance pathway for elastomeric closure suppliers. |
| Closed-System Transfer Device Integration | USP 800 hazardous drug handling redirects formulary criteria toward adapter-CSTD compatibility. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with hospital pharmacy directors, GPO contracts managers, biomedical engineers, and regulatory affairs leads at adapter manufacturers. FDA 21 CFR Part 211 submission databases, EU MDR technical documentation repositories, and Japanese PMDA registration records provided material validation and biocompatibility testing timelines. Bottom-up demand modeling from hospital procurement databases triangulated against top-down market sizing from medical device trade flows.
Data-stream reconciliation across shipment volumes, sterilization capacity utilization, and raw material import patterns informed the analytical framework over the projection horizon. Segmentation dimensions included product material tier, end-user facility type, application hazard classification, and technology automation level. CAGRs derived from compound growth mechanics applied to base-year value and volume estimates. Industry-specific forecast inputs incorporated USP 797/800 revision implementation pace and EU MDR Class IIa reclassification transition timelines.
The model holds under steady regulatory enforcement intensity; deviation in FDA inspection frequency or EU MDR notified body capacity would shift adoption trajectories. Forecasts reflect assumptions regarding gamma sterilization throughput expansion and medical-grade resin supply continuity. A model refresh is warranted upon material change in USP hazardous drug handling protocol enforcement or JIS T 0320 standard revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
South Korea Aesthetic Devices Market
Medical Devices
Intravascular Warming Systems Market
Medical Devices
Manometry System Market
Medical Devices
Global Orthopedic Power Tools Market
Medical Devices
Craniomaxillofacial Implants Market
Medical Devices
Global Automated Dispensing Machines Market
Medical Devices
Europe Viscosupplementation Market
Medical Devices
Oxygen Conserving Devices Market
Medical Devices
Corneal Implants Market
Medical Devices
Disposable Needle Guides Market
Medical Devices
Rechargeable Medical Battery Market
Medical Devices
Global Surgical Visualization Products Market
Medical Devices
Microwave Ablation Devices Market
Medical Devices
Gastric Space-Occupying Devices Market
Medical Devices
Connected Drug Delivery Devices Market
Medical Devices
Germany Contraceptive Devices Market