
 Ankle Syndesmosis Treatment Devices Market | 2026-2036
Ankle Syndesmosis Treatment Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Ankle Syndesmosis Treatment Devices Market Analysis
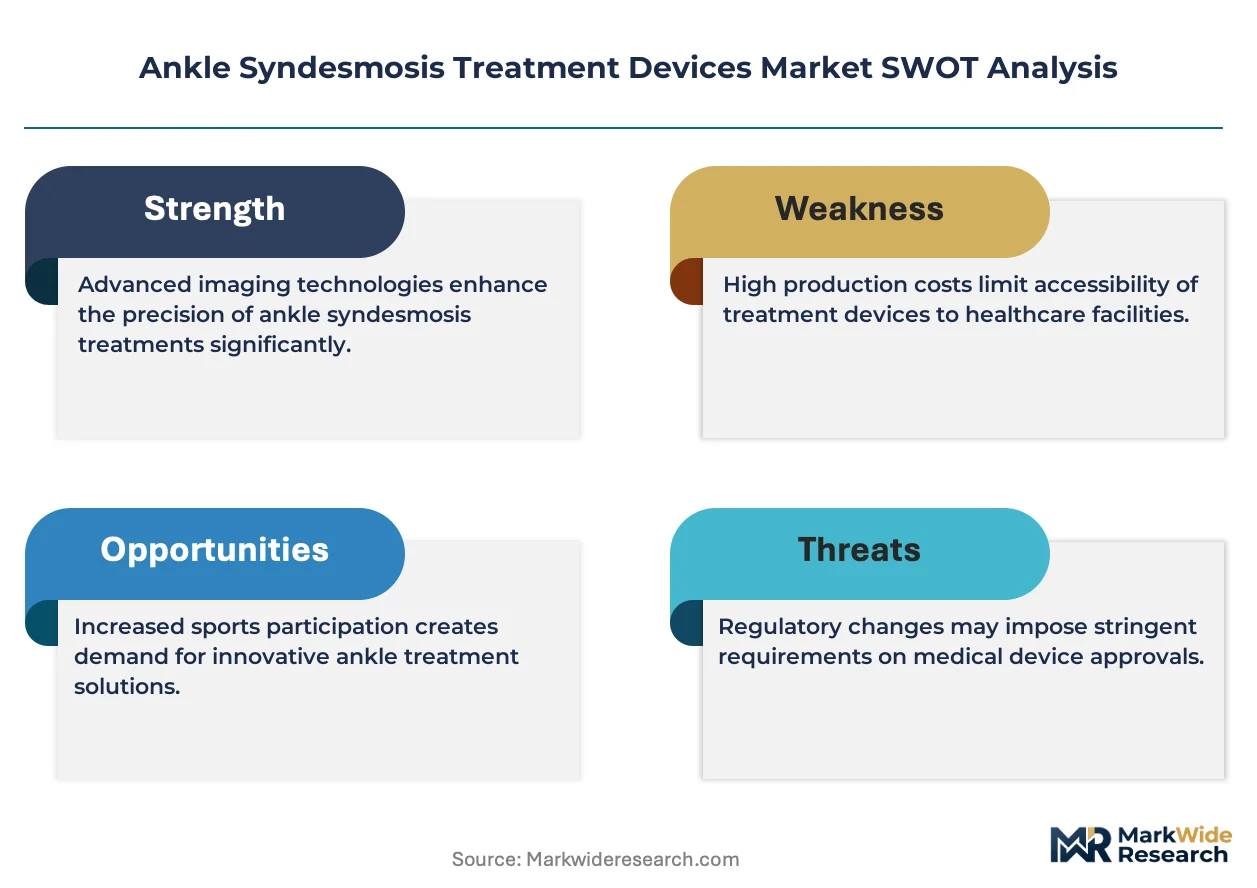
North America is narrowing its supply deficit for advanced ankle fixation hardware through expanded cleanroom manufacturing in Tennessee and Minnesota. Arthrex, Inc. leverages vertically integrated cadaver lab training to lock in surgeon preference. Zimmer Biomet Holdings, Inc. sustains broad hospital GPO contracts that protect volume across economic cycles. Smith & Nephew Plc. competes through dedicated sports medicine sales forces positioned inside NCAA athletic departments.
Ankle syndesmosis treatment devices span screws, plates, suture-button constructs, and rigid braces engineered to restore tibiofibular integrity after ligamentous disruption; titanium and PEEK polymers dominate load-bearing components, with bioresorbable magnesium alloys entering pilot evaluation for temporary fixation without secondary removal surgery. The screws segment anchors the revenue base due to revision surgery frequency and established CPT reimbursement, while minimally invasive technology captures the fastest expansion as arthroscopic-assisted reduction cuts operative time and preserves soft tissue envelopes. Braces occupy a mature, price-sensitive channel where DME distributors compete on logistics scale rather than clinical differentiation.
FDA 510(k) predicates and ISO 13485 quality system mandates govern U.S. commercialization, with the FDA pushing biocompatibility testing depth for permanent implants and the EU MDR extending notified body scrutiny to suture-based devices previously exempt from Class III designation. The analysis suggests stakeholders must monitor CMS physician fee schedule adjustments for arthroscopic ankle procedures, as reimbursement compression would redirect capital toward outpatient-friendly fixation platforms.
Market Dynamics
Arthroscopic-assisted fixation is compressing operative timelines and redirecting hospital capital toward minimally invasive platforms that preserve soft-tissue envelopes while reducing revision rates.
Growth Catalysts
- FDA 510(k) pathway compression:Bioresorbable magnesium alloys now clear through abbreviated predicate routes, accelerating commercialization timelines for temporary fixation without hardware removal surgery.
- NCAA athletic department penetration:Dedicated sports medicine sales forces embedded within collegiate training facilities drive replacement cycles for suture-button constructs among high-velocity ankle injury populations.
- Tennessee cleanroom manufacturing expansion:Domestic production capacity for titanium and PEEK components is narrowing supply deficits for advanced ankle fixation hardware across hospital systems.
Market Restraints
- Titanium powder input volatility:Additive manufacturing feedstock costs fluctuate with aerospace sector demand, pressuring margins for patient-specific implant producers.
- EU MDR notified body bottleneck:Extended scrutiny timelines for suture-based devices previously exempt from Class III designation delay European commercialization by 12-18 months.
- Brace commoditization:DME distributors compete exclusively on logistics scale, compressing price realization for rigid immobilization products lacking clinical differentiation.
Strategic Opportunities
- Outpatient migration tailwind:CMS physician fee schedule incentives for ambulatory surgical centers favor fixation platforms compatible with same-day discharge protocols.
- Bioresorbable convergence with additive manufacturing:Magnesium alloy lattice structures fabricated through selective laser melting enable patient-matched temporary fixation with controlled resorption kinetics.
- Vertically integrated cadaver lab training:Surgeon education programs lock in preference formation before device procurement decisions reach hospital value analysis committees.
Industry Challenges
- ISO 13485 quality system maintenance:Small manufacturers face disproportionate compliance costs relative to revenue base when updating documentation for biocompatibility testing depth.
- Arthroscopic skill pipeline constraints:Fellowship-trained foot and ankle surgeons remain concentrated in academic medical centers, limiting technique diffusion to community hospitals where case volumes concentrate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ankle Syndesmosis Treatment Devices Market |
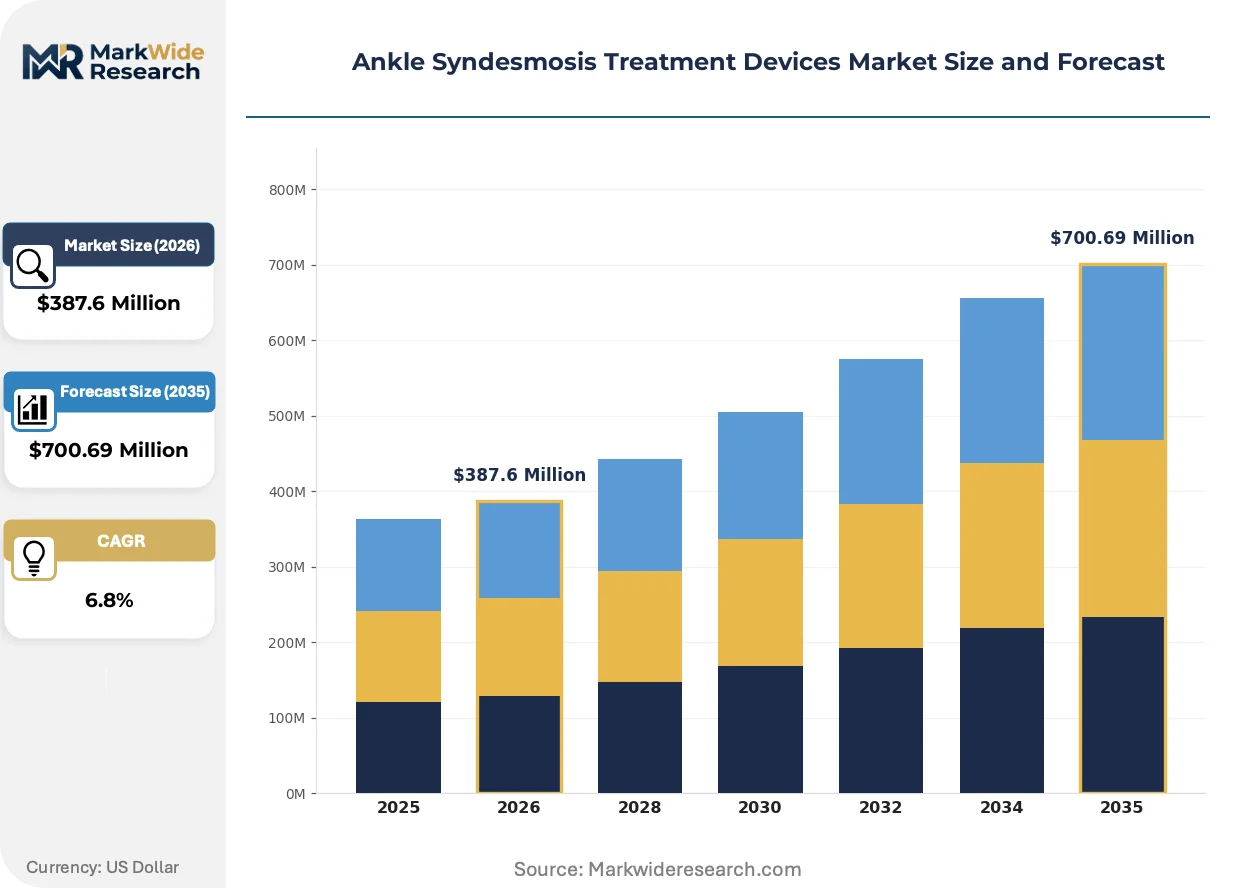
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screws, Plates, Anchors, Braces End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Outpatient Facilities Technology: Minimally Invasive, Open Surgery, Traditional Methods, Hybrid Techniques Application: Sports Injuries, Trauma, Postoperative Recovery, Orthopedic Procedures |
| Companies Covered | Arthrex, Inc., Paragon 28, Inc., Mortise Medical, Inion Oy, Smith & Nephew Plc., Acumed LLC, Zimmer Biomet Holdings, Inc., Exactech, Inc., DePuy Synthes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ankle Syndesmosis Treatment Devices Market Emerging Trajectories
Device architecture is converging around bioresorbable materials and arthroscopic delivery systems that eliminate secondary removal procedures while compressing hospital length-of-stay metrics.
Magnesium-calcium alloy fixation constructs are hybridizing temporary stabilization with controlled biodegradation, eliminating hardware removal surgeries. Academic medical centers in the United States are piloting these implants for Weber C fracture patterns, with resorption timelines now matching ligament healing windows. The structural consequence is a compression of the revision surgery revenue pool that previously sustained screw-based hardware replacement cycles.
The EU MDR is extending Class III scrutiny to suture-button devices previously regulated as Class IIa, forcing manufacturers to compile clinical evidence packages for predicate equivalence. Notified body capacity constraints in Germany and the Netherlands are creating 14-month certification backlogs. Suture-based construct producers are responding by prioritizing FDA 510(k) clearance as a faster route to commercial revenue.
Ambulatory surgical centers are consolidating purchasing authority through regional GPO networks that unbundle device pricing from historical hospital system contracts. Trauma centers in the southeastern United States are migrating ankle fixation cases to freestanding facilities where arthroscopic-assisted reduction cuts anesthesia time by 40 minutes. This channel rotation favors manufacturers with dedicated outpatient sales infrastructure over legacy hospital contracting teams.
Ankle Syndesmosis Treatment Devices Market Segmentation
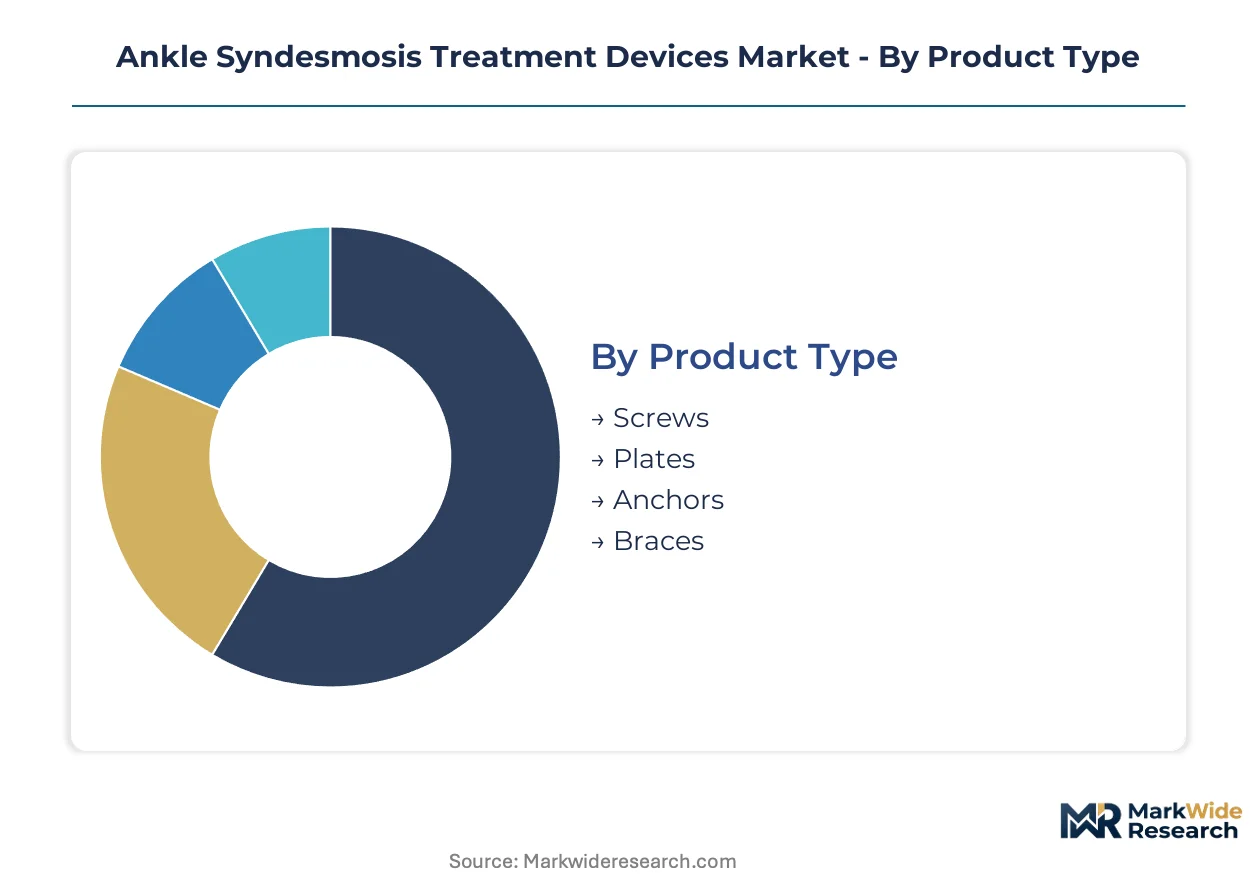
Ankle syndesmosis treatment devices fragment across four structural dimensions that determine reimbursement pathways, procurement authority, and clinical training requirements. Each segmentation axis carries distinct margin profiles and regulatory exposure that shape manufacturer resource allocation.
Product Type:
Mature metallic fixation dominates revenue while bioresorbable alternatives reshape the emerging technology frontier.
- Screws:Titanium and stainless steel cortical screws provide rigid tibiofibular compression with established CPT reimbursement codes. Trauma centers in the United States drive replacement cycles through revision surgery volume, though secondary removal procedures create patient dissatisfaction.
- Plates:Anatomic locking plate systems distribute load across comminuted fracture patterns. Academic medical centers favor these constructs for Weber C injuries where syndesmotic instability combines with fibular comminution.
- Anchors:Suture-button constructs enable dynamic fixation with preserved physiologic motion. NCAA athletic departments accelerate adoption among high-velocity ankle injury populations.
- Braces:Rigid immobilization devices occupy a logistics-driven channel where DME distributors compete on delivery scale rather than clinical differentiation.
Screws retain volume leadership; anchors hold the steepest expansion curve.
End User:
Procurement authority concentrates differently across facility types, with hospital value analysis committees demanding outcome evidence that outpatient facilities rarely require.
- Hospitals:Integrated delivery networks command bulk pricing through GPO contracts that lock in multi-year supply agreements. Trauma designation status determines case volume concentration.
- Orthopedic Clinics:Physician-owned specialty practices prioritize surgeon-specific preference items over standardized protocols. Tennessee and Minnesota manufacturing clusters serve these accounts through direct sales representation.
- Rehabilitation Centers:Postoperative brace dispensing generates recurring revenue streams with lower regulatory burden than implantable devices.
- Outpatient Facilities:Ambulatory surgical centers migrate ankle fixation cases from hospital settings where arthroscopic-assisted reduction cuts anesthesia time substantially. CMS physician fee schedule incentives accelerate this channel rotation.
Hospitals retain volume leadership; outpatient facilities hold the steepest expansion curve.
Technology:
Technique selection drives capital equipment requirements and surgeon training investments that fragment the addressable market.
- Minimally Invasive:Arthroscopic-assisted reduction preserves soft-tissue envelopes while compressing operative timelines. Hospital systems redirect capital toward these platforms as length-of-stay metrics tighten.
- Open Surgery:Direct visualization remains necessary for complex fracture patterns with syndesmotic disruption. Fellowship-trained foot and ankle surgeons concentrate this technique in academic medical centers.
- Traditional Methods:Screw fixation without arthroscopic guidance persists in community hospitals where case volumes limit technique diffusion.
- Hybrid Techniques:Combined arthroscopic and open approaches address multi-ligamentous injuries with customized fixation strategies.
Open surgery retains volume leadership; minimally invasive approaches hold the steepest expansion curve.
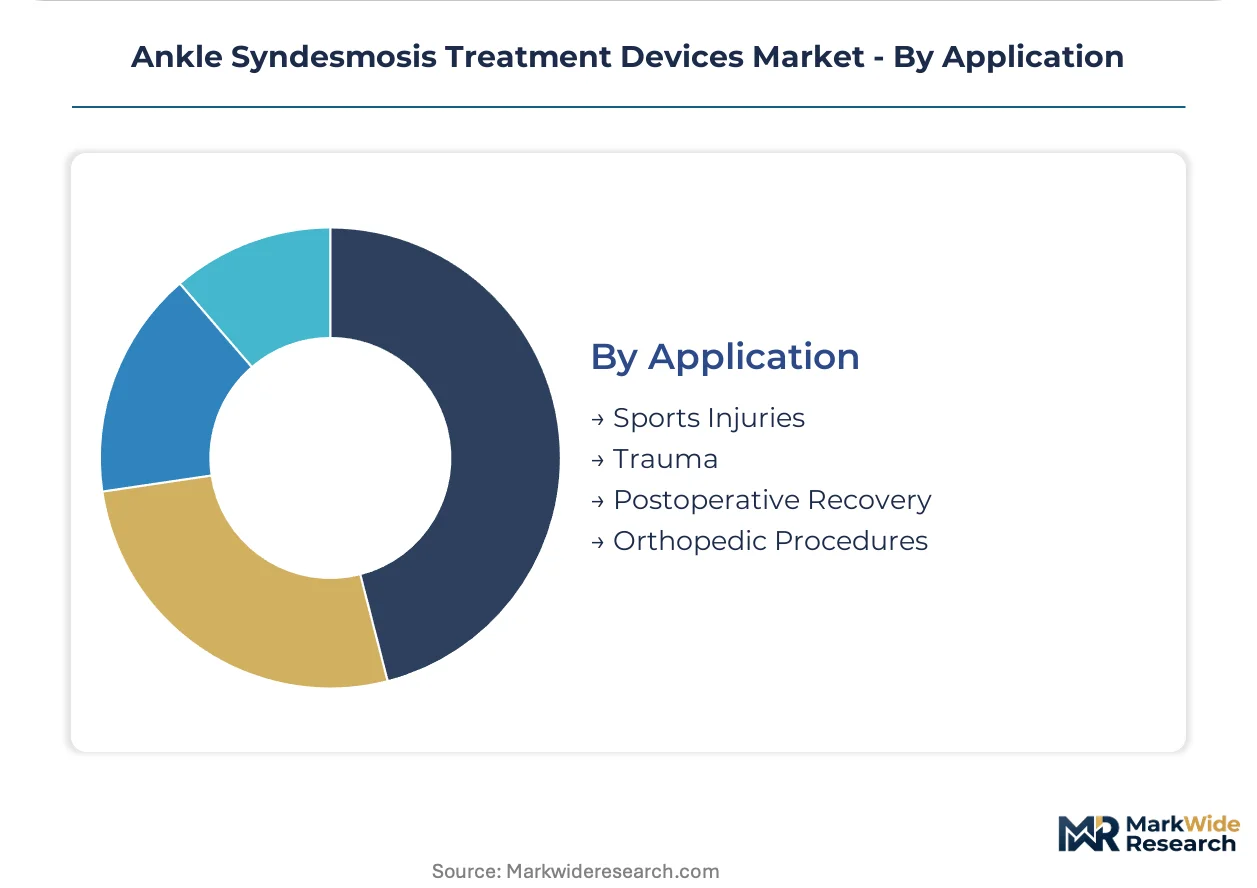
Application:
Indication severity determines device selection, with high-energy trauma demanding rigid fixation that sports injuries often avoid.
- Sports Injuries:High-velocity ankle sprains among collegiate and professional athletes drive suture-button adoption. Smith & Nephew sports medicine sales forces embed directly within NCAA training facilities.
- Trauma:Motor vehicle accidents and falls generate Weber C fracture patterns requiring anatomic plate fixation. FDA 510(k) clearance pathways accelerate device availability for emergent indications.
- Postoperative Recovery:Brace-based immobilization follows hardware removal or non-operative management protocols.
- Orthopedic Procedures:Elective ankle stabilization for chronic instability represents a discretionary volume sensitive to economic cycles.
Trauma retains volume leadership; sports injuries hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: the United States favors arthroscopic-assisted fixation with rapid outpatient migration, while European systems prioritize cost-containment through standardized screw protocols, and Asian markets concentrate volume in trauma centers serving high-density urban populations.
United States
NCAA athletic departments and professional sports franchises drive suture-button replacement cycles for high-velocity ankle injuries. FDA 510(k) clearance pathways compress commercialization timelines for bioresorbable magnesium implants. Tennessee and Minnesota cleanroom manufacturing clusters now supply titanium and PEEK components to hospital systems narrowing supply deficits.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia pilot magnesium-calcium alloy constructs for Weber C fracture patterns. EU MDR notified body capacity constraints in Berlin and Hamburg extend suture-button device certification timelines by 14 months. The Erfurt medical device cluster specializes in arthroscopic instrumentation for minimally invasive ankle stabilization.
China
Shanghai and Beijing trauma centers absorb volume from motor vehicle accidents and construction-related falls requiring anatomic plate fixation. NMPA regulatory pathways for Class III implants demand extensive clinical evidence packages. The Suzhou industrial park concentrates domestic production of titanium powder feedstock for additive manufacturing applications.
United Kingdom
NHS England procurement frameworks prioritize screw-based fixation with established NICE guidance and reimbursement certainty. MHRA post-Brexit regulatory autonomy accelerates divergence from EU MDR timelines for novel device categories. The Cambridge-Oxford medical technology corridor hosts specialized foot and ankle fellowship programs concentrating surgical expertise.
Japan
PMDA approval processes emphasize long-term biocompatibility data for permanent implants, extending time-to-market for foreign manufacturers. The Kanto region's aging population generates chronic instability cases requiring elective stabilization. Osaka-based orthopedic clinics favor hybrid arthroscopic-open techniques for complex multi-ligamentous injuries.
Ankle Syndesmosis Treatment Devices Market Vendor Landscape
Capability concentration sits with specialized sports medicine innovators; scale advantage sits with diversified orthopedic conglomerates with hospital GPO contracts. The vendor base stratifies across three tiers: vertically integrated cadaver lab trainers, broad-line trauma suppliers, and bioresorbable material pioneers. Dominant competitive moves include surgeon education program expansion and regional manufacturing capacity additions to narrow supply deficits.
Among diversified orthopedic holding companies, Zimmer Biomet Holdings, Inc. and Smith & Nephew Plc. exemplify scale-driven positioning through multi-year hospital system contracts and dedicated sports medicine sales forces. Arthrex, Inc. represents the capability-concentrated tier with vertically integrated training infrastructure. Paragon 28, Inc. occupies a specialist position within foot and ankle fixation. These three anchors illustrate the competitive tension between breadth and depth in procurement decisions.
| Leading Market Players |
|---|
| Arthrex, Inc. |
| Paragon 28, Inc. |
| Mortise Medical |
| Inion Oy |
| Smith & Nephew Plc. |
| Acumed LLC |
| Zimmer Biomet Holdings, Inc. |
| Exactech, Inc. |
| DePuy Synthes |
| Others |
Supply Flow & Price Mechanics
Memphis-Minneapolis freight corridors absorb titanium powder shipments from aerospace surplus channels, compressing logistics costs for Tennessee and Minnesota cleanroom clusters while creating geographic price spreads between domestic-manufactured screws and imported PEEK components.
Pricing Analysis
Geographic price spreads between United States-manufactured titanium fixation and European-sourced PEEK constructs exceed fifteen percent at hospital procurement level. Three-tier pricing structure across premium arthroscopic systems, standard screw-based fixation, and economy brace categories tracks certification depth and surgeon training bundling. Cost compression in the brace segment intensifies as DME distributors compete exclusively on logistics scale. Ambulatory surgical centers demonstrate highest price sensitivity; academic trauma centers with GPO contracts show lowest.
Supply Chain Analysis
Titanium powder feedstock draws from aerospace sector surplus channels in the United States, Germany, and China, with magnesium-calcium alloy precursors concentrated in Australian and Israeli specialty chemical producers. PEEK polymer pellets hinge on Victrex and Solvay capacity in the United Kingdom and Belgium. Single-source vulnerability runs through German notified body certification bottlenecks for suture-button devices. Distribution runs through hospital GPO networks, orthopedic clinic direct sales, and DME logistics platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates specialist acquisition opportunities as outpatient migration and bioresorbable technology bifurcate demand across minimally invasive platforms and traditional screw-based systems.
For Market Incumbents: Harden GPO contract renewal cycles through embedded surgeon training infrastructure that precedes value analysis committee review. Expand Tennessee and Minnesota cleanroom capacity to narrow supply deficits against titanium powder volatility. Lock in arthroscopic-assisted fixation preference before bioresorbable magnesium alloys displace secondary removal revenue pools. For New Entrants and Emerging Players: Establish a beachhead in ambulatory surgical center channels where regional GPO networks unbundle legacy hospital contracts. Target southeastern United States trauma centers migrating cases to freestanding facilities. Lead with same-day discharge protocols and dedicated outpatient sales infrastructure rather than competing for academic medical center procurement. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified orthopedic conglomerates seeking to divest non-core foot and ankle portfolios. Five-to-ten year viability favors bioresorbable material pioneers with FDA 510(k) clearance momentum over metallic fixation legacy assets. Monitor CMS physician fee schedule adjustments for arthroscopic ankle procedures as inflection indicator for outpatient channel acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Abbreviated predicate routes compress commercialization timelines for bioresorbable magnesium constructs. |
| CE Marking Pathway | EU MDR notified body bottlenecks in Germany and Netherlands delay suture-button certification by fourteen months. |
| Hospital System Partnership | Vertically integrated cadaver lab training locks in surgeon preference before procurement decisions reach value analysis committees. |
| Software Companion Development | Arthroscopic navigation platforms reduce operative time and preserve soft-tissue envelopes for outpatient migration. |
| Reimbursement Strategy | CMS physician fee schedule incentives for ambulatory surgical centers redirect capital toward same-day discharge protocols. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across hospital purchasing committees, foot and ankle fellowship directors, GPO contracts managers, biomedical engineers, and orthopedic device sales representatives. Secondary validation drew from FDA 510(k) filings, CMS Medicare procedure databases, hospital procurement records, and ISO 13485 certification registries. Bottom-up demand modeling and top-down supply capacity estimates were triangulated to anchor volume projections.
Calibration against historical screw replacement rates and arthroscopic procedure growth patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user facility category, technology approach, and application severity. CAGRs were derived from installed base dynamics and replacement cycle compression. Forecast inputs incorporated NCAA athletic department procurement patterns and Tennessee-Minnesota manufacturing capacity expansion timelines.
Stress conditions across titanium powder cost volatility, EU MDR certification delays, and CMS reimbursement adjustments were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about surgeon training diffusion rates and outpatient migration velocity. Cross-checking against hospital capital expenditure disclosures and GPO contract renewal schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Tympanostomy Products Market
Medical Devices
United States Small Bone and Joint Devices Market
Medical Devices
Photopheresis Products Market
Medical Devices
Wearable Medical Robots Market
Medical Devices
Esophagoscopes and Gastroscopes Market
Medical Devices
Extremity Reconstruction Market
Medical Devices
South Korea ECG Market
Medical Devices
Peripheral Embolization Device Market
Medical Devices
Global Antimicrobial Coatings for Medical Devices Market
Medical Devices
Microneedling Cartridges Market
Medical Devices
Interventional Oncology Devices Market
Medical Devices
Brazil Contraceptive Devices Market
Medical Devices
Point of Care Ultrasound Systems Market
Medical Devices
Metered Dose Squeeze Dispenser Market
Medical Devices
Cranial Orthoses Market
Medical Devices
Bioactive Fillings Market