
 Anemia Drugs Market | 2026-2036
Anemia Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Anemia Drugs Market Analysis
Multi-source procurement of active pharmaceutical ingredients is pivoting toward vertically integrated supply arrangements as manufacturers seek greater control over erythropoietin and iron-complex raw materials. Novartis leverages its captive biologics manufacturing network to secure consistent epoetin alfa supply across European and Asian markets. Amgen anchors the United States erythropoiesis-stimulating agent landscape through its long-standing dialysis clinic partnerships. Pfizer competes in the oral iron space with established hospital formulary positions that sustain recurring volume commitments.
Anemia drugs comprise therapeutic agents that modulate erythropoiesis, iron metabolism, or vitamin-dependent hematopoiesis, including recombinant erythropoietins, parenteral iron carbohydrate complexes, and cobalamin/folate derivatives formulated to specific pharmacokinetic profiles for bioavailability optimization. These agents restore oxygen-carrying capacity in populations with chronic disease, nutritional deficiency, or marrow suppression. Erythropoiesis-stimulating agents retain the highest revenue intensity per patient course despite biosimilar erosion, while intravenous iron formulations capture expanding share in hospital infusion centers where oral therapy fails. Home care administration routes represent the fastest-growing delivery channel as payors push cost avoidance through subcutaneous and oral alternatives.
The FDA, EMA, and WHO prequalification standards collectively govern anemia drug approval, manufacturing quality, and post-market surveillance, with FDA Risk Evaluation and Mitigation Strategies specifically constraining erythropoiesis-stimulating agent prescribing in oncology settings. REACH and EU MDR compliance requirements in Europe add material cost layers for iron complex and biologic manufacturers seeking continental market access. Stakeholders must monitor evolving biosimilar interchangeability designations and national reimbursement carve-outs that will determine competitive positioning in high-volume institutional accounts.
Market Dynamics
The FDA's Risk Evaluation and Mitigation Strategies for erythropoiesis-stimulating agents in oncology settings is compressing prescribing volumes while redirecting clinical demand toward intravenous iron formulations and biosimilar alternatives across hospital infusion networks.
Growth Catalysts
- Chronic kidney disease prevalence:Dialysis-dependent populations in the United States and Germany generate sustained demand for parenteral iron replacement protocols.
- EMA biosimilar pathways:Accelerated approval frameworks for epoetin alfa biosimilars expand therapeutic access across European hospital formularies.
- Subcutaneous administration technology:Prefilled pen delivery systems reduce infusion center burden and enable home-based anemia management.
Market Restraints
- Heparin sodium linkage:Erythropoiesis-stimulating agent production remains exposed to porcine-derived raw material supply volatility from Chinese agricultural sources.
- FDA black-box warnings:Oncology-related cardiovascular risk labeling constrains erythropoietin prescribing in solid tumor settings.
- Oral iron substitution:Ferrous sulfate and ferric maltol formulations capture stable ambulatory cases that previously required intravenous therapy.
Strategic Opportunities
- Japan's aging demographic:PMDA-approval pathways for long-acting erythropoiesis-stimulating agents address underpenetrated dialysis clinic segments.
- India's PLI scheme:Domestic biologics manufacturing incentives enable local production of iron sucrose complex for hospital tender markets.
- Home infusion nursing networks:Third-party specialty pharmacy channels bypass traditional hospital outpatient departments for maintenance iron dosing.
Industry Challenges
- Biosimilar interchangeability designation:FDA switching study requirements delay automatic substitution at the pharmacy level.
- EU MDR technical documentation:Iron complex device-drug combination products face extended conformity assessment timelines.
- Cold chain integrity:Epoetin alfa distribution requires validated temperature-controlled logistics across last-mile delivery to infusion centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anemia Drugs Market |
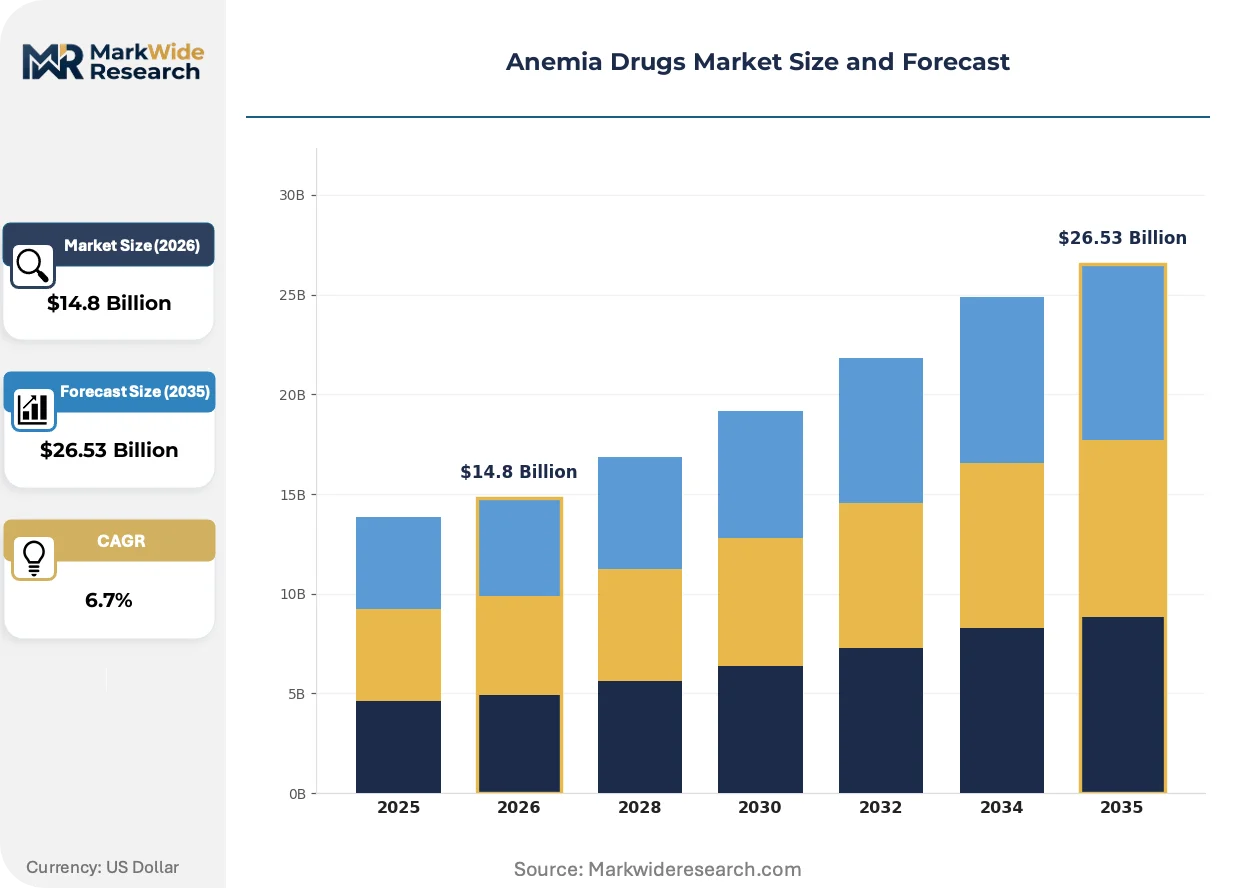
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iron Supplements, Vitamin B12, Erythropoiesis-Stimulating Agents, Folic Acid End User: Hospitals, Clinics, Ambulatory Surgical Centers, Home Care Administration Route: Oral, Intravenous, Subcutaneous, Intramuscular Formulation: Tablets, Injections, Liquids, Powders |
| Companies Covered | Novartis, Akebia Therapeutics, GSK plc, Sanofi, CSL Vifor, Pfizer, Takeda, Pharmacosmos Therapeutics, Amgen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anemia Drugs Market Emerging Trajectories
Formulation science and administration modality are converging to shift anemia treatment from facility-based infusion toward patient-managed therapy, with regulatory frameworks adapting to accommodate decentralized care models.
Long-acting erythropoiesis-stimulating agents incorporating hyaluronidase-facilitated subcutaneous absorption are unifying dosing intervals for dialysis patients. Nephrology clinics in Germany and Japan have adopted monthly administration schedules that compress treatment burden. The technology is unifying patient adherence metrics with payor cost-avoidance targets through reduced clinic visit frequency.
REACH authorization requirements for iron carbohydrate complex manufacturing are tightening impurity specifications for dextran and carboxymaltose derivatives. European contract manufacturers face capital outlays for upgraded purification suites. The hematology-oncology segment bears the steepest compliance cost absorption as hospitals demand batch-level documentation for infusion center liability protection.
Hospital purchasing consortia are consolidating anemia drug procurement under single-source agreements with rebate structures tied to volume thresholds. Integrated delivery networks in the United States displace independent dialysis clinic purchasing autonomy. The concentration is most visible in Medicare Advantage plan regions where risk-bearing entities negotiate direct manufacturer contracts for erythropoiesis-stimulating agent and iron bundle pricing.
Anemia Drugs Market Segmentation
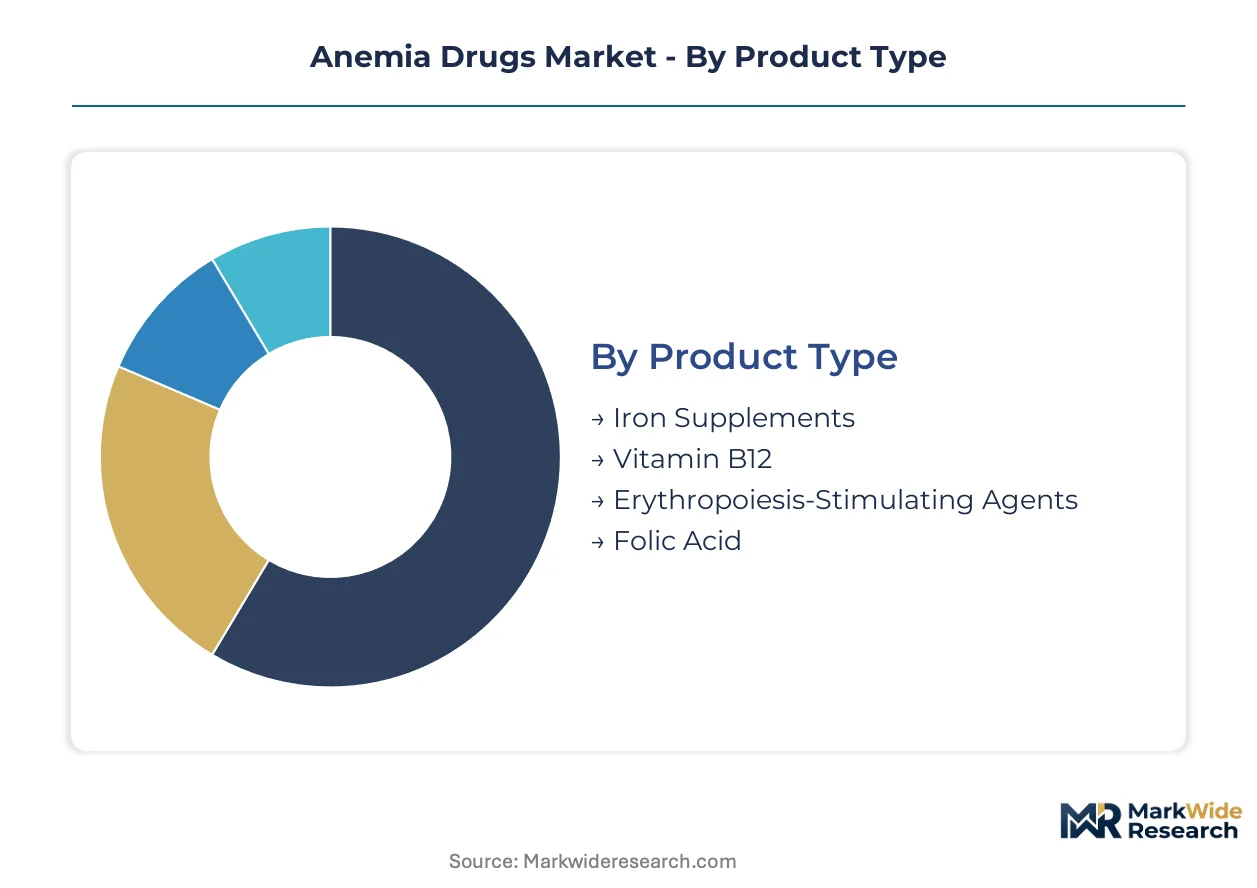
Anemia drug manufacturers navigate divergent regulatory pathways across product categories, with biologics requiring REMS compliance and iron complexes facing REACH impurity standards. Segmentation reveals where certification burdens concentrate and which delivery modalities capture shifting clinical preference.
Product Type:
FDA Risk Evaluation and Mitigation Strategies apply selectively within this category, with erythropoiesis-stimulating agents bearing the heaviest post-market surveillance obligations while iron supplements face lighter nutritional-supplement oversight.
- Erythropoiesis-Stimulating Agents:Recombinant epoetin alfa and darbepoetin alfa stimulate erythropoietin receptor signaling in bone marrow progenitor cells. Dialysis clinics in the United States generate concentrated demand under Medicare bundled payment structures, though FDA black-box warnings for cardiovascular risk constrain oncology prescribing.
- Iron Supplements:Parenteral iron carbohydrate complexes and oral ferrous salts restore ferritin stores and hemoglobin synthesis. Hospital infusion centers in Germany and the United States absorb expanding volumes as oral therapy fails in chronic kidney disease populations.
- Vitamin B12:Cyanocobalamin and hydroxocobalamin formulations address pernicious anemia and malabsorption syndromes through intramuscular or sublingual delivery.
- Folic Acid:Synthetic pteroylglutamic acid prevents megaloblastic anemia in pregnancy and antimetabolite chemotherapy settings.
Erythropoiesis-Stimulating Agents sit at the top of the volume ranking, with Iron Supplements climbing the fastest.
End User:
Procurement authority varies sharply across this category, with integrated delivery networks consolidating purchasing power in hospital systems while home care channels fragment across specialty pharmacy networks.
- Hospitals:Academic medical centers and community hospitals operate infusion centers for parenteral iron and erythropoiesis-stimulating agent administration. Medicare Advantage risk-bearing entities in the United States negotiate direct manufacturer contracts for bundled anemia management.
- Home Care:Subcutaneous epoetin alfa and oral iron formulations shift administration to patient-managed settings. Third-party specialty pharmacy channels in the United States bypass traditional hospital outpatient departments for maintenance dosing.
- Clinics:Nephrology and oncology practices administer erythropoiesis-stimulating agents under REMS protocols with documented cardiovascular risk counseling.
- Ambulatory Surgical Centers:Preoperative anemia correction protocols drive single-dose intravenous iron utilization ahead of orthopedic and cardiac procedures.
Hospitals command the largest procurement volumes, though Home Care is expanding most quickly as payors push cost avoidance through decentralized administration.
Administration Route:
Margin structures correlate with clinical supervision intensity, with intravenous delivery capturing facility fees while subcutaneous and oral routes enable lower-cost ambulatory management.
- Intravenous:Iron sucrose and ferric carboxymaltose infusions require hemodynamic monitoring in hospital infusion suites. REACH authorization requirements for carbohydrate complex manufacturing tighten impurity specifications in European markets.
- Subcutaneous:Prefilled pen delivery systems for epoetin alfa reduce clinic visit frequency. German and Japanese nephrology clinics have adopted monthly administration schedules that compress treatment burden for dialysis populations.
- Oral:Ferrous sulfate and ferric maltol tablets capture stable ambulatory cases with intact gastrointestinal absorption.
- Intramuscular:Vitamin B12 depot injections address pernicious anemia in patients with severe malabsorption.
Intravenous delivery retains the highest revenue intensity per course, with Subcutaneous routes gaining share fastest through home-based adoption.
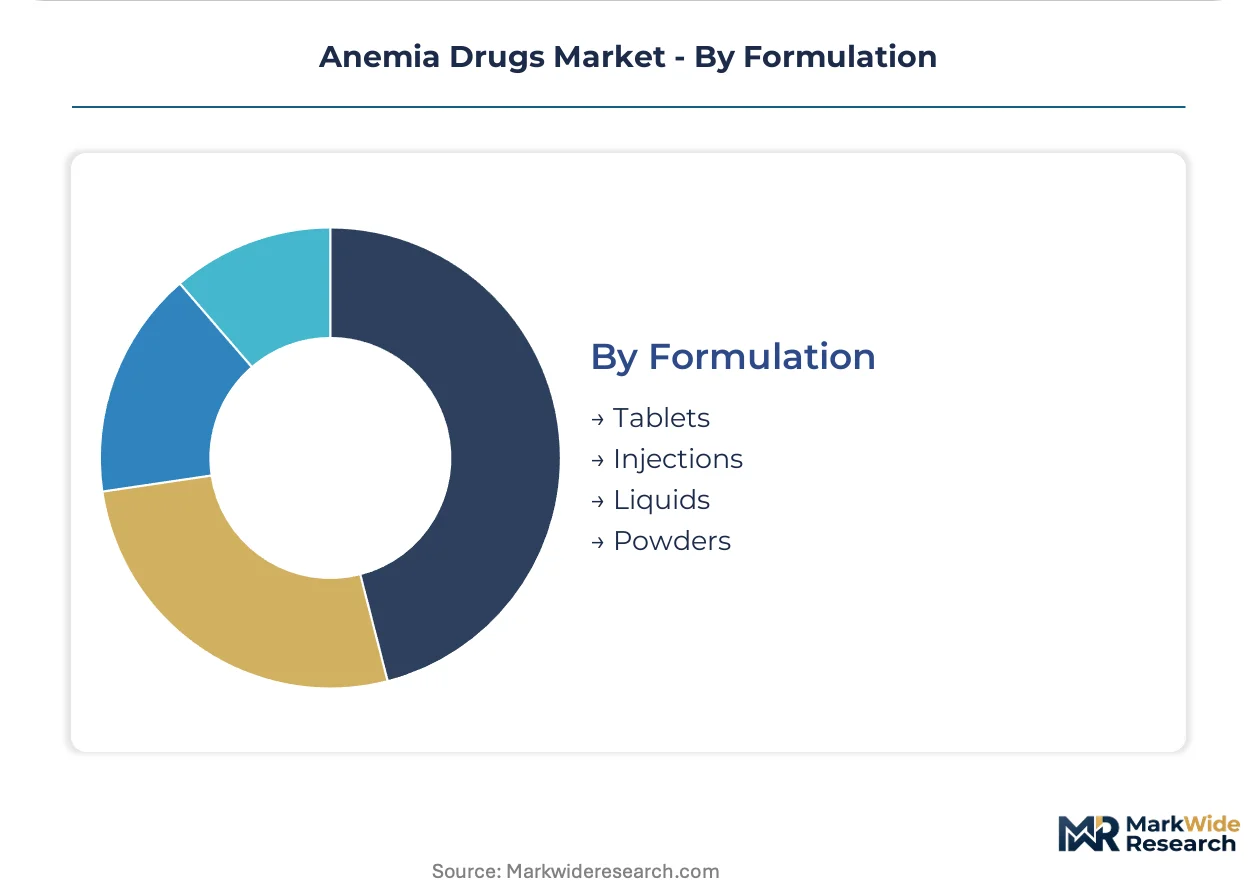
Formulation:
Stability requirements and cold chain demands differentiate manufacturing complexity, with liquid biologics requiring validated temperature-controlled logistics against solid oral dosage forms.
- Injections:Sterile parenteral preparations of erythropoietin and iron complexes demand aseptic fill-finish capacity with endotoxin control. Cold chain integrity requirements for epoetin alfa distribution extend through last-mile delivery to infusion centers.
- Tablets:Film-coated ferrous salts and folic acid enable stable ambient storage with extended shelf life. Hospital formularies in the United States sustain recurring volume commitments for oral iron through standardized order sets.
- Liquids:Pediatric and geriatric formulations improve palatability and dose titration flexibility.
- Powders:Reconstitutable lyophilized erythropoietin preserves stability during extended distribution intervals.
Injections dominate therapeutic value generation, with Tablets capturing stable ambulatory volumes through oral substitution trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biopharma corridor anchors erythropoiesis-stimulating agent development, with FDA REMS compliance shaping commercialization timelines. Dialysis clinic density and hospital infusion network expansion determine regional demand intensity.
United States
Medicare bundled payment structures concentrate erythropoiesis-stimulating agent procurement within dialysis chains. FDA black-box warnings for cardiovascular risk constrain oncology prescribing volumes. Integrated delivery networks in Texas and Florida negotiate direct manufacturer contracts for iron and erythropoietin bundle pricing.
Germany
Nephrology clinics in Bavaria and North Rhine-Westphalia adopt monthly subcutaneous administration schedules for dialysis populations. REACH authorization requirements tighten iron carbohydrate complex impurity specifications. Contract manufacturers in Baden-Württemberg upgrade purification suites to meet EU MDR compliance timelines.
Japan
PMDA approval pathways for long-acting erythropoiesis-stimulating agents address underpenetrated dialysis segments. Tokyo and Osaka medical centers pioneer hyaluronidase-facilitated subcutaneous absorption protocols. Prefilled pen delivery systems reduce clinic visit frequency for aging patient populations.
India
PLI scheme incentives enable domestic biologics manufacturing of iron sucrose complex for hospital tender markets. Maharashtra and Gujarat house expanding active pharmaceutical ingredient production. CDSCO regulatory pathways accelerate biosimilar epoetin alfa market entry.
China
NMPA biologics approval frameworks expand erythropoiesis-stimulating agent access for chronic kidney disease populations. Shanghai and Beijing hospital systems consolidate anemia drug procurement under volume-based purchasing agreements. Cold chain infrastructure investments support temperature-controlled distribution to regional infusion centers.
Anemia Drugs Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue biosimilar interchangeability and home administration technologies. The market structure reflects moderate consolidation around erythropoiesis-stimulating agents alongside fragmented iron supplement competition. Three archetypes dominate: integrated biopharmaceutical conglomerates with captive manufacturing networks, specialty iron complex manufacturers with hospital formulary positions, and biosimilar specialists leveraging accelerated approval pathways. Capacity expansion and strategic partnerships constitute the dominant competitive moves.
Among Swiss-based biopharmaceutical conglomerates, Novartis and Vifor occupy positions anchored by vertically integrated supply networks. Amgen exemplifies the established erythropoiesis-stimulating agent incumbent with long-standing dialysis clinic partnerships. Pfizer represents the diversified pharmaceutical archetype with hospital formulary presence across oral and parenteral iron categories.
| Leading Market Players |
|---|
| Novartis |
| Akebia Therapeutics |
| GSK plc |
| Sanofi |
| CSL Vifor |
| Pfizer |
| Takeda |
| Pharmacosmos Therapeutics |
| Amgen |
| Others |
Supply Flow & Price Mechanics
Prefilled pen delivery systems for subcutaneous erythropoiesis-stimulating agents are compressing cost economics for clinic administration while concentrating manufacturing scale among biologics specialists with validated cold chain infrastructure. This technology shift simultaneously reduces per-dose facility overhead and reinforces pricing power for producers with integrated fill-finish networks across European and North American markets.
Pricing Analysis
Input-cost pass-through from porcine-derived heparin sodium and recombinant cell culture media runs through erythropoiesis-stimulating agent list prices, with contract-based long-term offtake agreements dominating dialysis clinic procurement. Price differentiation centers on biosimilar interchangeability designation and REMS compliance tier, with FDA-approved interchangeable products commanding premium positioning over non-designated alternatives. Cost compression in the oral iron segment is intensifying because ferrous sulfate and ferric maltol substitution captures stable ambulatory cases. Hospital purchasing consortia exhibit highest price sensitivity through volume-threshold rebate negotiations, while nephrology clinics in bundled payment regions show lowest sensitivity due to pass-through reimbursement structures.
Supply Chain Analysis
Single-source vulnerability sits with Chinese agricultural heparin sodium suppliers and European contract manufacturers of iron carbohydrate complexes. Geographic supply concentration centers on Switzerland and Germany for biologics fill-finish, India for active pharmaceutical ingredient production of iron sucrose, and China for porcine-derived raw materials. Raw material dependencies encompass recombinant cell lines, dextran and carboxymaltose carbohydrate polymers, and parenteral-grade water for injection. Tariff exposure on Chinese-sourced heparin intermediates presents structural risk amid trade policy volatility. Distribution runs through hospital purchasing consortia and third-party specialty pharmacy channels for home-based administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between India's PLI-scheme manufacturing incentives and Western Europe's REACH compliance cost burdens, with production cost differentials exceeding regulatory certification expenses for iron complex manufacturers.
For Market Incumbents: Hedge biosimilar erosion in erythropoiesis-stimulating agents by deepening backward integration into recombinant cell culture media production and expanding captive biologics capacity in Singapore or Switzerland to diversify beyond single-source heparin dependencies. Prioritize REMS certification maintenance as a defensive moat against automatic pharmacy-level substitution.
For New Entrants and Emerging Players: Rural dialysis clinics in India's Maharashtra and Gujarat states represent the most penetrable buyer archetype, with underdeveloped iron sucrose tender markets and accelerating CDSCO biosimilar pathways. Target home infusion nursing networks in Medicare Advantage regions of Texas and Florida through third-party specialty pharmacy partnerships, bypassing consolidated hospital purchasing consortia.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap iron complex manufacturers with REACH-authorized European production and established hospital formulary positions but limited biosimilar pipeline exposure. Long-term viability over the coming decade hinges on successful navigation of EU MDR technical documentation requirements for device-drug combinations. Watch FDA interchangeability switching study completion rates as the critical inflection signal for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| REMS Compliance Investment | FDA Risk Evaluation and Mitigation Strategies certification blocks automatic biosimilar substitution in oncology settings. |
| REACH Authorization Upgrade | ECHA impurity specification tightening for iron carbohydrate complexes requires capital outlays for European market access. |
| Prefilled Pen Manufacturing Scale-Up | Subcutaneous delivery technology reduces clinic visit frequency and captures Medicare Advantage bundle pricing. |
| Indian PLI Scheme Manufacturing | Domestic biologics incentives enable cost-competitive iron sucrose production for hospital tender markets. |
| Specialty Pharmacy Channel Partnership | Third-party home infusion networks bypass traditional hospital outpatient departments for maintenance dosing. |
Methodological Framework
Coverage spans North America, Western Europe, Asia-Pacific, and India, with primary inputs from each region combining structured interviews with regulatory affairs leads, hospital formulary directors, dialysis clinic procurement managers, and payer access specialists alongside secondary validation. Secondary sources include FDA REMS documentation, EMA biosimilar assessment reports, ClinicalTrials.gov entries, and CMS Medicare bundled payment data. Bottom-up patient-volume modeling and top-down manufacturer revenue triangulation anchor market sizing.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions encompass product type, administration route, end-user setting, and regional regulatory cluster. CAGRs derive from patient population growth, therapy penetration rates, and biosimilar adoption curves. Forecast inputs incorporate dialysis clinic density projections, REACH authorization timelines, and FDA interchangeability designation pathways.
Underlying measurement precision varies by segment; erythropoiesis-stimulating agents carry tighter precision due to consolidated dialysis clinic reporting than fragmented oral iron ambulatory markets. Forecasts reflect documented assumptions regarding biosimilar substitution rates and regulatory approval timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Warm Autoimmune Hemolytic Anemia (WAIHA) Treatment Market
Hematology
Hemoglobinopathies Treatment Market
Hematology
Venous Blood Collection Market
Hematology
Thalassemia Treatment Market
Hematology
Alpha Thalassemia Market
Hematology
Chronic Immune Thrombocytopenia Treatment Market
Hematology
Burkitt Lymphoma Treatment Market
Hematology
Lymphopenia Therapeutics Market
Hematology
Myelodysplastic Syndrome (MDS) Treatment Market
Hematology
Haematocrit Centrifuge Market
Hematology
Malignant Lymphoma Market
Hematology
Global Hematopoietic Stem Cell Transplantation Market
Hematology
AL Amyloidosis Therapeutics Market
Hematology
Hematopoietic Agents Market
Hematology
Heparin-Induced Thrombocytopenia (HIT) Treatment Market
Hematology
Global Sickle Cell Disease Treatment Market