
 Warm Autoimmune Hemolytic Anemia (WAIHA) Treatment Market | 2026-2036
Warm Autoimmune Hemolytic Anemia (WAIHA) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Warm Autoimmune Hemolytic Anemia (WAIHA) Treatment Market Analytics
Second-line biologic efficacy thresholds is collapsing the historical dominance of corticosteroid monotherapy in WAIHA management. Sanofi leverages its immunology infrastructure to sustain development of complement-targeted modalities. Rigel Pharmaceuticals anchors commercial momentum through its established foothold in autoimmune hemolytic indications. F. Hoffmann-La Roche Ltd differentiates via integrated diagnostics-to-therapeutics positioning across hematology centers.
Warm Autoimmune Hemolytic Anemia constitutes an autoimmune disorder characterized by IgG-mediated erythrocyte destruction at body temperature, with primary therapeutic objectives centered on halting hemolysis, stabilizing hemoglobin levels above eight grams per deciliter, and preventing thromboembolic complications. The condition demands agents capable of modulating complement cascade activity or suppressing pathogenic autoantibody production. Monoclonal antibodies command the highest margin pools among product types, reflecting manufacturing complexity and targeted mechanism premiums. Hospitals retain dominant procedure volumes across end users, though specialty clinics capture the fastest-growing share as outpatient biologic administration protocols mature.
The FDA's orphan drug designation framework and the EMA's PRIME eligibility scheme jointly compress development timelines for novel WAIHA therapeutics while imposing stringent evidence standards for sustained hemoglobin response endpoints. Health Canada and the PMDA maintain aligned but jurisdiction-specific requirements for immunosuppressive agent labeling in autoimmune cytopenias. Stakeholders must monitor complement inhibitor reimbursement negotiations and evolving corticosteroid-sparing protocols to calibrate portfolio prioritization.
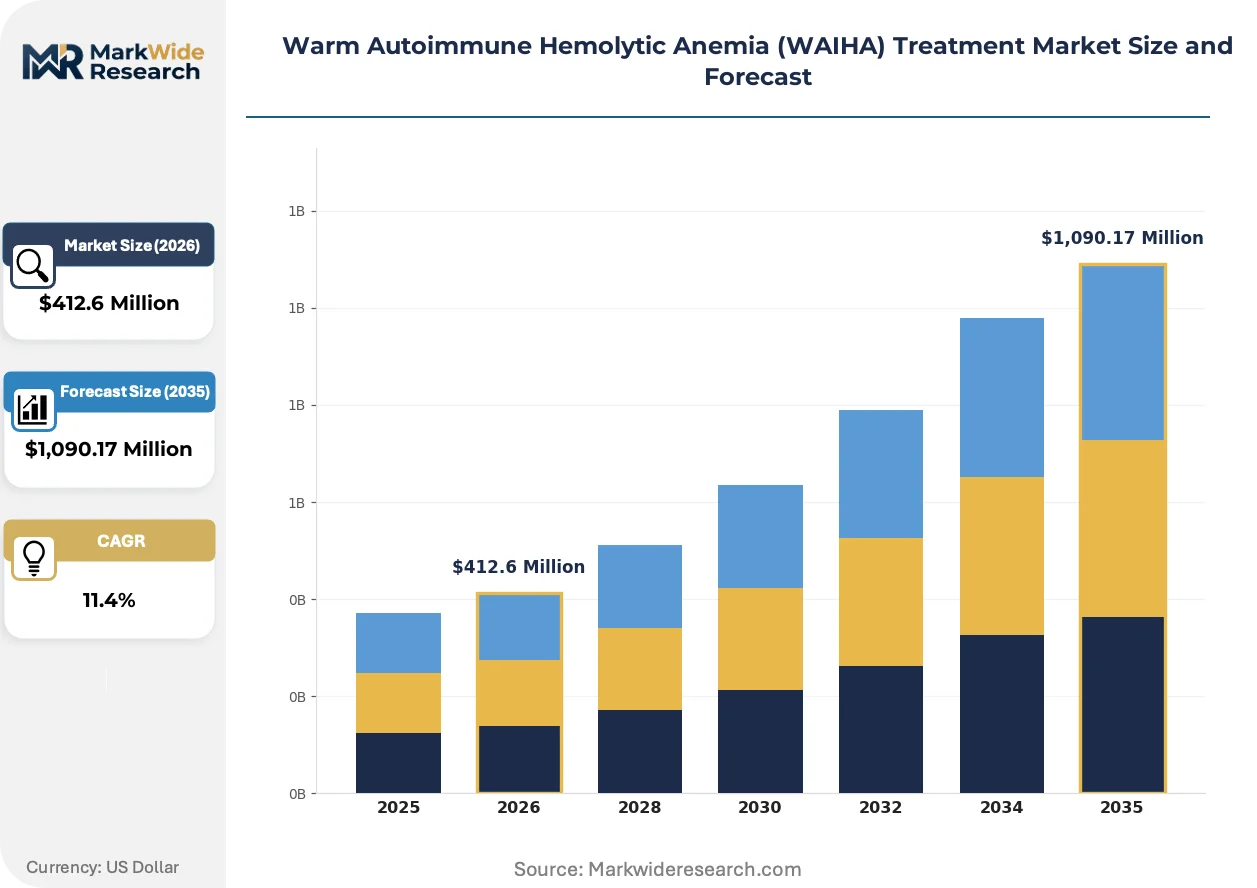
Market Dynamics
The FDA's accelerated approval pathway for orphan hematologic indications compresses commercialization timelines for complement-targeted therapies, while corticosteroid-sparing protocols in tertiary care centers pull patient volume toward biologic administration.
Growth Catalysts
- Orphan Drug Designation:The FDA's expedited review framework reduces development timelines for novel WAIHA therapeutics. EMA's PRIME eligibility scheme accelerates European market entry for agents demonstrating sustained hemoglobin response.
- Specialty Clinic Expansion:Outpatient biologic administration protocols mature across tertiary care networks. These facilities capture the fastest-growing share of procedure volumes as corticosteroid monotherapy retreats.
- Complement Cascade Modulation:Next-generation monoclonal antibodies targeting C1s and C3 convertase demonstrate efficacy in refractory cases. Manufacturing advances reduce production complexity for these high-margin modalities.
Market Restraints
- Biologic Manufacturing Concentration:Monoclonal antibody production concentrates among a limited supplier base. Single-source dependence for cell culture media and purification resins creates vulnerability.
- Reimbursement Negotiation Friction:Complement inhibitor pricing faces pressure from pharmacy benefit managers. Payers demand robust hemoglobin endpoint data before granting preferred formulary status.
- Corticosteroid Inertia:First-line prednisone protocols persist in community hematology settings despite guideline evolution. Physician familiarity with steroid tapering regimens slows biologic uptake.
Strategic Opportunities
- Diagnostic-Therapeutic Integration:Direct antiglobulin test automation converges with electronic health record decision support. Integrated platforms enable rapid identification of candidates for targeted therapy.
- Subcutaneous Formulation Development:Intravenous-to-subcutaneous conversion opens home administration channels. Patient preference for reduced infusion center visits drives formulation investment.
- Japan's PMDA Sakigake Pathway:Japan's priority review system offers expedited access for WAIHA agents with breakthrough potential. Early engagement with PMDA scientific advice accelerates dossier preparation.
Industry Challenges
- Immunogenicity Assessment Complexity:Anti-drug antibody detection requires specialized bioanalytical capabilities. Contract research organizations with validated assays command premium pricing and extended timelines.
- Cold Chain Integrity:Temperature excursions during biologic distribution compromise product stability. Last-mile logistics in emerging markets lack validated thermal packaging infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Warm Autoimmune Hemolytic Anemia (WAIHA) Treatment Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,090.17 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Steroids, Immunosuppressants, Intravenous Immunoglobulin End User: Hospitals, Specialty Clinics, Homecare Settings, Blood Transfusion Centers Delivery Mode: Intravenous, Subcutaneous, Oral, Intramuscular Application: Chronic Management, Acute Treatment, Supportive Care, Diagnostic Procedures |
| Companies Covered | Sanofi, Teva Pharmaceutical Industries Ltd, Rigel Pharmaceuticals, F. Hoffmann-La Roche Ltd, Novartis, Apellis Pharmaceuticals, Incyte Corporation, Immunovant, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Warm Autoimmune Hemolytic Anemia (WAIHA) Treatment Market Evolving Landscape
Mechanism-of-action diversification is fragmenting the historical corticosteroid-centric treatment paradigm, while regulatory innovation and care model evolution reshape how therapies reach refractory patient populations.
Complement-targeted modalities are fragmenting the second-line therapy landscape. FcRn inhibitors and neonatal Fc receptor blockers enter Phase III evaluation for steroid-refractory WAIHA. Tertiary hematology centers in the United States and Germany adopt these agents through expanded access programs, compressing the interval between regulatory approval and protocol integration.
EMA's PRIME eligibility scheme and FDA's breakthrough therapy designation create parallel regulatory tracks for WAIHA therapeutics. These frameworks mandate rolling review and accelerated assessment, reducing time-to-market for agents demonstrating hemoglobin stabilization above eight grams per deciliter. Sponsors must invest in natural history study infrastructure to satisfy evidentiary requirements, particularly for sustained response endpoints.
Patient registries and real-world evidence platforms displace traditional clinical trial exclusivity as the primary value demonstration vehicle. Payers in France and the United Kingdom increasingly condition reimbursement on post-authorization outcome data. Biopharmaceutical developers respond by embedding digital health technologies into commercial infrastructure, capturing treatment response metrics outside controlled trial settings.
Warm Autoimmune Hemolytic Anemia (WAIHA) Treatment Market Segmentation
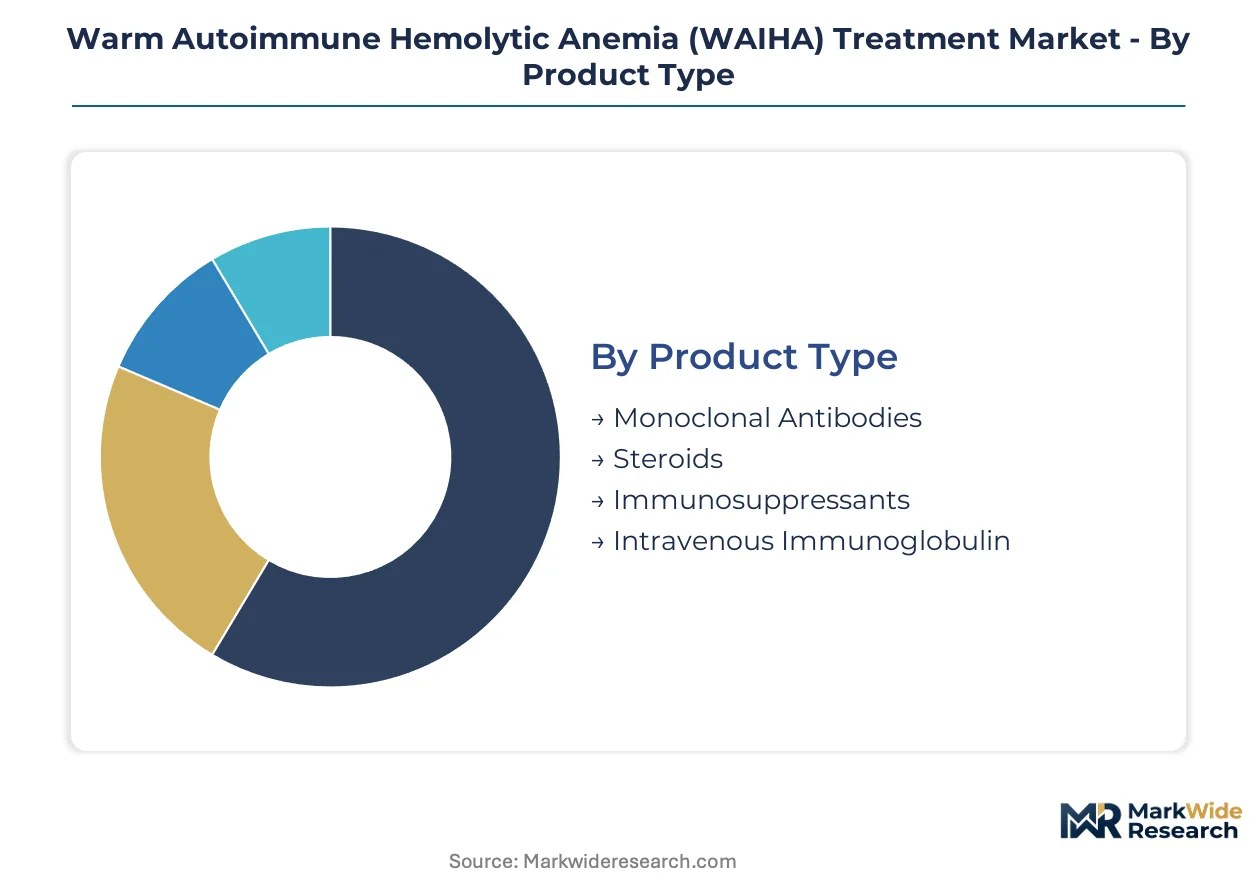
WAIHA treatment flows through distinct commercial channels shaped by therapy complexity, reimbursement structures, and patient acuity. Segment boundaries reflect how corticosteroid-sparing protocols redirect volume from inpatient infusion centers toward outpatient biologic administration.
Product Type:
Channel-mix dynamics vary sharply across therapeutic modalities, with high-complexity biologics concentrating in tertiary hospital pharmacies and oral agents dispersing through retail networks.
- Monoclonal Antibodies:Engineered immunoglobulins targeting C1s, C3 convertase, or FcRn demonstrate efficacy in steroid-refractory cases. Demand concentrates in United States tertiary hematology centers where complement inhibitor protocols have achieved protocol standardization.
- Steroids:Prednisone and methylprednisolone remain first-line despite retreating share. Community hematology settings in Germany and France sustain volume through physician familiarity with tapering regimens.
- Immunosuppressants:Azathioprine, cyclosporine, and mycophenolate mofetil serve as bridge therapies. Rheumatology-hematology crossover clinics in the United Kingdom drive prescription volume.
- Intravenous Immunoglobulin:Polyclonal antibody pools provide acute hemolysis control. Blood transfusion centers in Japan maintain dedicated IVIG infusion suites for cytopenia management.
By volume, Steroids leads. By growth pace, Monoclonal Antibodies is expanding most quickly.
End User:
Cost-tier stratification separates high-acuity inpatient management from routine outpatient monitoring, with reimbursement differentials determining site-of-care migration.
- Hospitals:Tertiary academic medical centers manage acute hemolytic crises, thrombotic complications, and protocol-induction biologic loading doses. United States centers of excellence anchor global procedure volume.
- Specialty Clinics:Outpatient hematology-focused facilities capture corticosteroid-sparing protocol expansion. German university-affiliated ambulatory centers lead European site-of-care shift.
- Homecare Settings:Subcutaneous formulation adoption enables patient-administered maintenance therapy. Home infusion nursing networks in France and the Netherlands mature rapidly.
- Blood Transfusion Centers:Cross-matched transfusion support and IVIG administration co-locate in centralized facilities. Japan's regional blood centers integrate diagnostic and therapeutic services.
By installed base, Hospitals dominates. By patient migration trends, Specialty Clinics gains share fastest.
Delivery Mode:
Application requirements dictate route selection, with acute hemolysis demanding immediate bioavailability and chronic maintenance favoring patient convenience.
- Intravenous:Rapid hemoglobin stabilization in acute crises. Hospital infusion centers in the United States and Germany retain volume for loading-dose protocols.
- Subcutaneous:Home administration potential reduces center visits. Formulation investment targets patient preference in France and the United Kingdom.
- Oral:Prednisone tapering and maintenance immunosuppression. Community pharmacy dispensing dominates in Japan.
- Intramuscular:Limited acute rescue applications. Emergency departments in select European centers retain for corticosteroid-refractory breakthrough.
By current volume, Intravenous leads. By pipeline investment, Subcutaneous shows the steepest expansion trajectory.
Application:
Patient acuity tiers separate emergency intervention from longitudinal disease modification, with diagnostic integration emerging as a distinct value node.
- Chronic Management:Long-term hemoglobin maintenance and thromboembolic prophylaxis. United States specialty clinics build dedicated WAIHA patient registries.
- Acute Treatment:Hemolytic crisis intervention and transfusion support. Tertiary hospital emergency departments in Germany manage highest case complexity.
- Supportive Care:Folate supplementation, iron management, and infection prophylaxis. Integrated care pathways in the United Kingdom embed these services.
- Diagnostic Procedures:Direct antiglobulin test automation and antibody specificity determination. Reference laboratories in Japan advance diagnostic-therapeutic platform integration.
By patient encounters, Chronic Management leads. By protocol innovation intensity, Diagnostic Procedures climbs fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologic therapies for WAIHA flow predominantly from United States and European development centers into tertiary care networks across Germany, Japan, and the United Kingdom, with regulatory harmonization accelerating cross-border protocol adoption.
United States
FDA's accelerated approval pathway for orphan hematologic indications compresses commercialization timelines for complement-targeted therapies. Tertiary academic medical centers in Boston and New York anchor global procedure volume for biologic loading-dose protocols. The country's pharmacy benefit managers now demand robust hemoglobin endpoint data before granting preferred formulary status for novel agents.
Germany
University-affiliated ambulatory centers in Berlin and Munich lead European site-of-care migration toward outpatient biologic administration. EMA's PRIME eligibility scheme accelerates market entry for agents demonstrating sustained hemoglobin response above eight grams per deciliter. German hematology societies actively disseminate corticosteroid-sparing protocols through regional continuing medical education networks.
Japan
PMDA's Sakigake priority review system offers expedited access for WAIHA agents with breakthrough potential. Regional blood centers in Tokyo and Osaka integrate diagnostic and therapeutic services through automated direct antiglobulin test platforms. The country's aging demographic intensifies demand for home-administered subcutaneous formulations.
United Kingdom
NICE technology appraisals increasingly condition reimbursement on post-authorization outcome data from patient registries. London and Manchester hematology centers embed digital health technologies into commercial infrastructure to capture treatment response metrics. Integrated care pathways in the National Health Service consolidate folate supplementation and thromboembolic prophylaxis within specialty clinic workflows.
France
ANSM maintains aligned but jurisdiction-specific requirements for immunosuppressive agent labeling in autoimmune cytopenias. Paris and Lyon specialty clinics build dedicated WAIHA patient registries to satisfy payer demands for real-world evidence. The country's hospital-at-home programs mature rapidly for subcutaneous biologic maintenance therapy.
Warm Autoimmune Hemolytic Anemia (WAIHA) Treatment Market Competitive Landscape
Listed leaders compete with private specialists across development-stage assets and commercial infrastructure. The WAIHA treatment market structures around three archetypes: diversified immunology majors with established hematology franchises, mid-cap biotechs with orphan disease focus, and emerging complement specialists advancing novel mechanisms. Competitive moves concentrate on strategic partnerships for diagnostic-therapeutic integration and geographic licensing to accelerate regulatory dossier preparation.
Within the diversified immunology tier, Sanofi and F. Hoffmann-La Roche Ltd occupy positions anchored by integrated diagnostics-to-therapeutics infrastructure across hematology centers. Rigel Pharmaceuticals exemplifies the orphan-focused mid-cap archetype, leveraging established footholds in autoimmune hemolytic indications to sustain commercial momentum. These three entities represent distinct strategic postures: platform breadth versus indication depth versus mechanism-specific concentration.
| Leading Market Players |
|---|
| Sanofi |
| Teva Pharmaceutical Industries Ltd |
| Rigel Pharmaceuticals |
| F. Hoffmann-La Roche Ltd |
| Novartis |
| Apellis Pharmaceuticals |
| Incyte Corporation |
| Immunovant |
| Johnson & Johnson |
| Others |
Value Network & Pricing Analysis
Cell culture media substitution from chemically defined formulations toward serum-free alternatives simultaneously concentrates biologic manufacturing in United States and German contract development sites and compresses per-batch production economics for monoclonal antibody therapies. This input transition elevates quality premiums for validated suppliers while eroding margin buffers for developers dependent on legacy serum-based protocols.
Pricing Analysis
Next-generation complement inhibitors command three-to-four-fold premiums over corticosteroid benchmarks, while established immunosuppressants occupy mid-tier positioning and prednisone generics anchor economy reference points. Three-tier pricing structure across premium, standard, and economy levels reflects manufacturing complexity gradients and orphan drug exclusivity windows. Cost compression in the steroid segment intensifies because pharmacy benefit managers deploy therapeutic interchange protocols. Community hematology practices exhibit highest price sensitivity; tertiary academic centers demonstrate lowest sensitivity due to protocol standardization and bundled reimbursement.
Supply Chain Analysis
Trans-Atlantic container availability constraints and Rotterdam port congestion elevate inbound logistics costs for temperature-sensitive biologic shipments from European manufacturing sites to United States distribution hubs. Biologic production concentrates in United States, Germany, and Switzerland, drawing from Chinese-sourced recombinant proteins, Japanese chromatography resins, and United States cell culture media. Single-source vulnerability pervades purification resin supply. Distribution runs through validated cold-chain logistics networks terminating in hospital pharmacy and specialty clinic infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA accelerated approval pathway compression for orphan hematologic indications constitutes a high-growth disruption, collapsing historical commercialization timelines from decade-long development cycles toward abbreviated regulatory trajectories.
For Market Incumbents: Consolidate manufacturing scale in United States and German CDMO networks to defend against emerging FcRn inhibitor developers eroding complement inhibitor market share. Deepen backward integration into cell culture media production to reduce single-source supplier exposure and capture margin compression relief. For New Entrants and Emerging Players: Anchor in Japanese PMDA Sakigake pathway engagement to exploit expedited review timelines for breakthrough-designated WAIHA assets. Target German university-affiliated ambulatory centers as the most penetrable site-of-care segment for outpatient biologic administration protocols. Deploy diagnostic-therapeutic integration partnerships as primary go-to-market mechanism. For Investors and Strategic Acquirers: FDA orphan drug exclusivity reshapes the acquisition landscape toward mid-cap biotechs with validated hemoglobin endpoint data and rolling review engagement. Five-to-ten year viability centers on sustained response durability rather than acute efficacy demonstration. Prioritize targets with integrated diagnostics infrastructure and real-world evidence platform deployment. Monitor EMA PRIME eligibility decisions as inflection indicator for European market access trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA accelerated designation compresses timelines for complement-targeted modalities. |
| Manufacturing Scale-Up | Serum-free cell culture transition anchors production economics in validated CDMO sites. |
| Diagnostic-Therapeutic Integration | Direct antiglobulin test automation converges with EHR decision support platforms. |
| Subcutaneous Formulation Development | Home administration channels capture patient preference in French and Dutch markets. |
| Pipeline Diversification | FcRn inhibitor advancement fragments second-line therapy concentration risk. |
Research Methodology
Cross-validation between hematologist prescribing data and payer formulary restriction records anchors the qualitative findings on biologic uptake velocity. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient volume modeling and top-down revenue reconciliation triangulate market size estimates.
Sensitivity analysis across hemoglobin response threshold assumptions, corticosteroid-sparing protocol penetration rates, and complement inhibitor pricing scenarios tests forecast robustness over the projection horizon. Segmentation dimensions modeled encompass treatment line, product type, end user facility tier, delivery mode, and regional regulatory cluster. CAGRs derive from log-linear trend fitting across annual volume and value estimates. Key inputs include tertiary care center procedure volumes, specialty clinic expansion trajectories, and orphan drug exclusivity expiration schedules.
Decision-makers should treat outputs as directional under sustained FDA accelerated approval pathway utilization and stable complement inhibitor reimbursement; material deviation in payer access policy or biosimilar entry timing would warrant model refresh. Recalibration cycles align with material shifts in regulatory designation decisions and formulary placement outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Allogeneic Stem Cell Therapy Market
Hematology
Peripheral T-Cell Lymphoma Treatment Market
Hematology
Global Hematologic Malignancies Treatment Market
Hematology
Neutropenia Treatment Market
Hematology
Hemoglobin Analyzer Market
Hematology
Sickle Cell Disease Market
Hematology
Global Hematology Diagnostics Market
Hematology
Patient Blood Management Market
Hematology
Apheresis Market
Hematology
Myelofibrosis Treatment Market
Hematology
Lymphoproliferative Disorder Treatment Market
Hematology
Graft vs Host Disease Market
Hematology
Bone Marrow Transplant Market
Hematology
Warm Autoimmune Hemolytic Anemia Market
Hematology
Hypereosinophilic Syndrome Market
Hematology
Polycythemia Vera Market