
 Paroxysmal Nocturnal Hemoglobinuria (PNH) Treatment Market | 2026-2036
Paroxysmal Nocturnal Hemoglobinuria (PNH) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Paroxysmal Nocturnal Hemoglobinuria (PNH) Treatment Market Outlook
Orphan drug exclusivity provisions are shifting the cost-of-entry calculus for PNH drug developers, extending market protection windows that reward targeted therapeutic innovation. AstraZeneca leverages its complement science infrastructure to sustain leadership in C5 inhibitor development. Apellis Pharmaceuticals anchors its competitive position through upstream control over pegcetacoplan manufacturing. Novartis differentiates via hematology portfolio breadth spanning transplant and complement-mediated disorders.
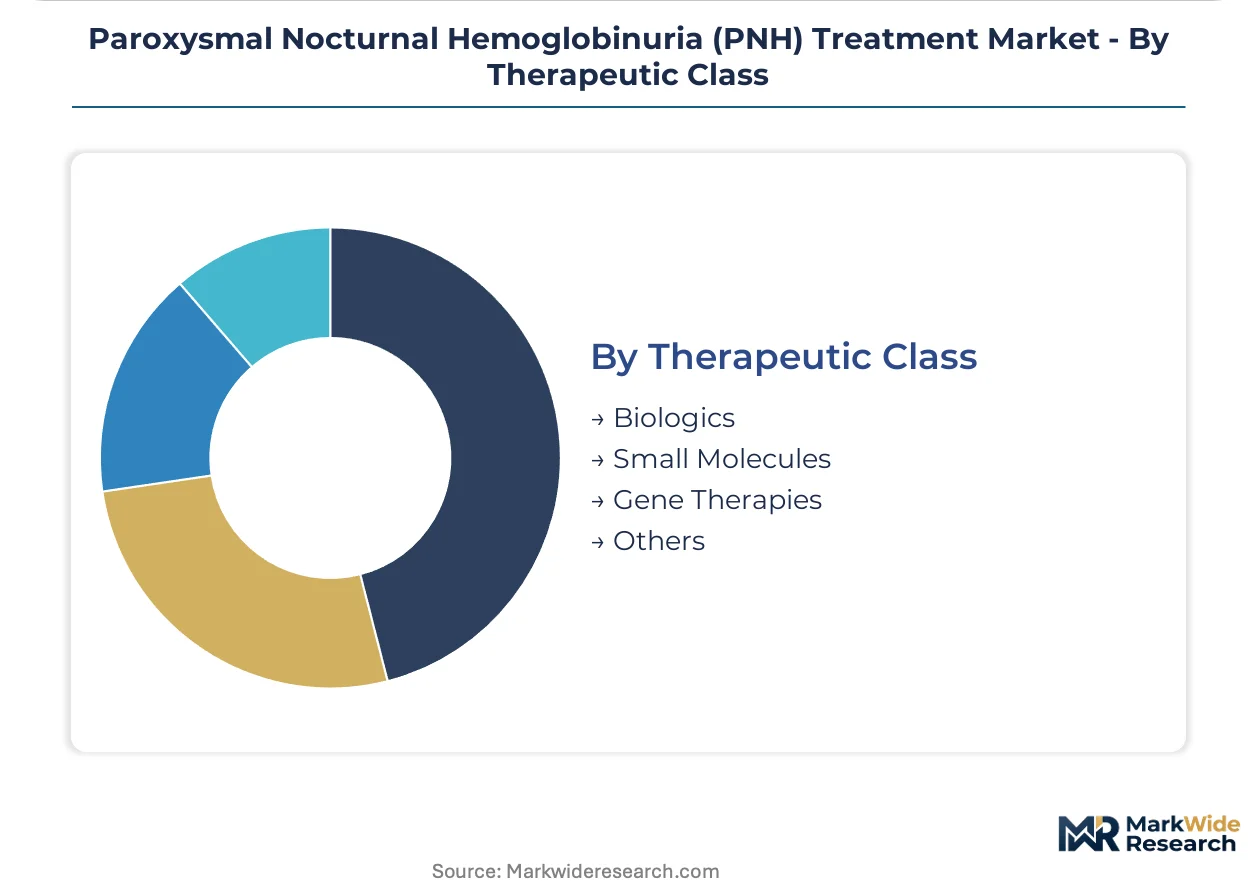
Paroxysmal Nocturnal Hemoglobinuria treatment encompasses therapeutic interventions targeting complement-mediated hemolysis, thrombosis prevention, and bone marrow failure management through monoclonal antibodies, small molecules, and emerging gene-editing approaches. The therapeutic class dimension shows biologics commanding dominant value share as C5 and C3 inhibitors displace legacy immunosuppressant protocols, while gene therapies represent the fastest-expanding development pipeline despite manufacturing complexity. Administration route segmentation reveals subcutaneous formulations gaining traction against intravenous standards as patient convenience and site-of-care economics reshape prescribing behavior across hospital and homecare settings.
The FDA orphan drug program and EMA's PRIME designation scheme collectively accelerate PNH therapy development timelines while tightening post-market pharmacovigilance requirements for complement inhibitors. Health Technology Assessment bodies in Germany and France increasingly condition reimbursement on real-world hemolysis control metrics rather than trial endpoints alone. Stakeholders must monitor evolving biosimilar entry timelines for established C5 inhibitors and prepare portfolio decisions around next-generation C3-targeted mechanisms and gene therapy durability data.
Market Dynamics
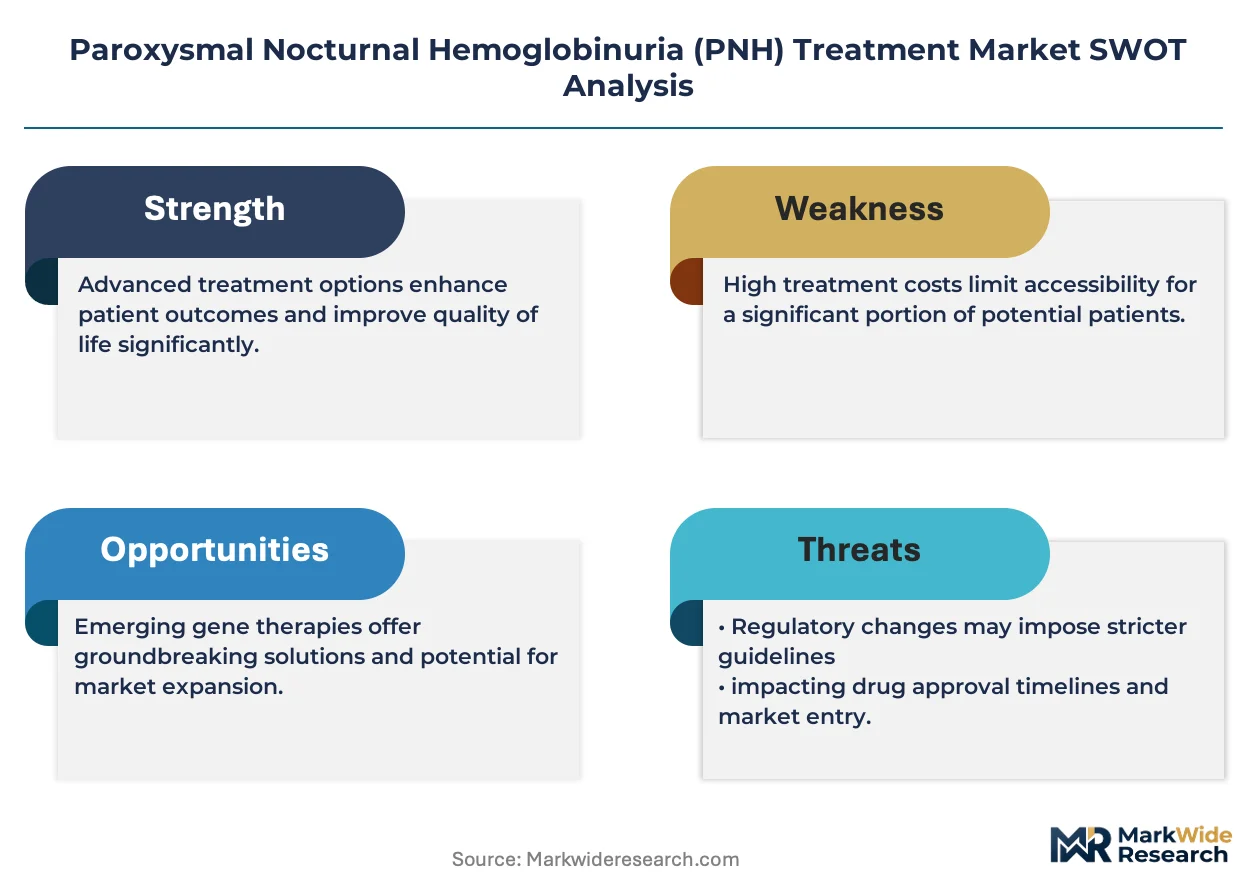
Complement inhibitor pipeline maturation is restructuring competitive boundaries in PNH therapeutics, as upstream C3 targeting displaces established C5 blockade protocols and gene-editing durability data redraws long-term patient management economics.
Growth Catalysts
- FDA Orphan Drug Exclusivity:Extended market protection windows incentivize rare disease biologic development, accelerating clinical trial enrollment through tax credit provisions and waived user fees.
- Hospital Hematology Expansion:Academic medical centers in the United States are building dedicated complement disorder clinics, concentrating specialist expertise and streamlining patient referral pathways.
- Subcutaneous Formulation Innovation:Self-administration protocols reduce infusion center dependency, shifting site-of-care economics toward home-based delivery models.
Market Restraints
- Plasma-Derived Input Volatility:Complement protein supply concentrates among fractionators in the United States and Germany, exposing manufacturers to raw material batch variability and viral safety testing costs.
- EMA Post-Market Surveillance Burden:Pharmacovigilance requirements for complement inhibitors mandate extensive real-world hemolysis tracking, extending regulatory compliance timelines beyond initial approval.
- Allogeneic Stem Cell Substitution:Bone marrow transplant protocols retain curative positioning for younger PNH patients with marrow failure, limiting addressable population for chronic pharmacotherapy.
Strategic Opportunities
- Japan's Rare Disease Framework:PMDA's Sakigake designation pathway offers priority review and early reimbursement negotiation for novel complement mechanisms entering the Asia-Pacific market.
- Real-World Evidence Integration:Germany's G-BA now accepts registry-derived hemolysis control metrics alongside trial endpoints, opening faster market access for therapies with strong observational data.
- Gene Therapy-Conventional Drug Convergence:Lentiviral vector manufacturing advances and CRISPR editing precision are converging to enable durable C3 knockout protocols, potentially eliminating chronic dosing requirements.
Industry Challenges
- Complement Biology Talent Scarcity:Specialized immunology expertise for C3/C5 pathway drug development concentrates among a limited pool of academic and industry researchers, inflating compensation and extending hiring cycles.
- Multi-Site Manufacturing Validation:Biologics license applications require demonstration of batch consistency across geographically dispersed production facilities, complicating capacity expansion for pegylated peptide inhibitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paroxysmal Nocturnal Hemoglobinuria (PNH) Treatment Market |
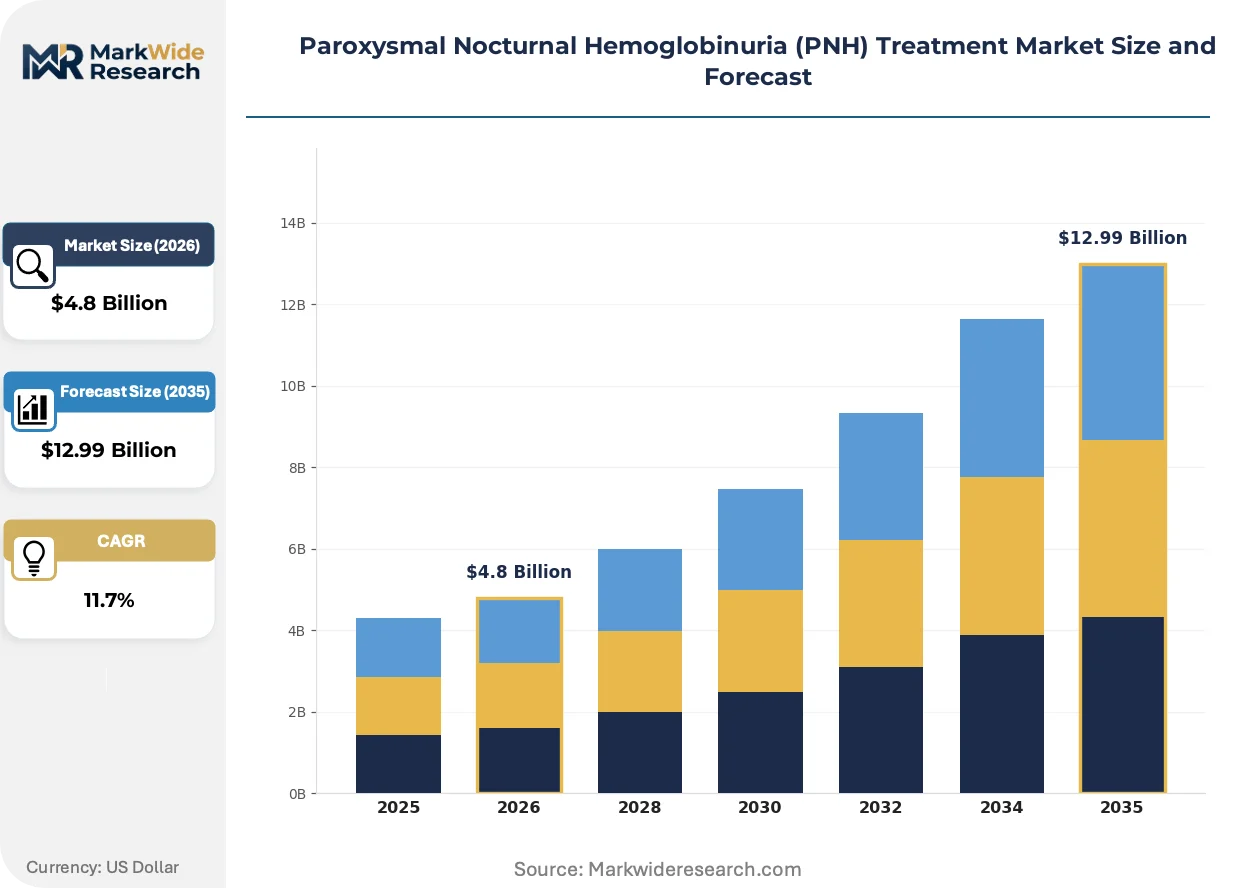
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Complement Inhibitors, Antineoplastic Agents, Corticosteroids, Immunosuppressants Administration Route: Intravenous, Subcutaneous, Oral, Intramuscular End User: Hospitals, Clinics, Homecare Settings, Specialty Pharmacies Therapeutic Class: Biologics, Small Molecules, Gene Therapies, Others |
| Companies Covered | AstraZeneca, Apellis Pharmaceuticals, Novartis, Hoffmann-La Roche, Regeneron Pharmaceuticals, BioCryst Pharmaceuticals, Amgen, Sanofi, AKARI Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paroxysmal Nocturnal Hemoglobinuria (PNH) Treatment Market Strategic Shifts
Upstream complement targeting is rewriting therapeutic hierarchies in PNH management, as C3 inhibition demonstrates superior control over extravascular hemolysis and reshapes prescriber preferences across hospital-based hematology departments.
C3-targeted peptide inhibitors are rewriting the clinical calculus for PNH patients with residual anemia. Hospital formulary committees are prioritizing these agents for cases refractory to C5 blockade. The technology is rewriting competitive positioning by compressing differentiation windows between first- and second-generation complement therapies.
EMA's PRIME designation scheme is compressing development timelines for breakthrough PNH therapies through enhanced scientific dialogue and accelerated assessment pathways. Industrial sponsors gain clarity on evidentiary requirements earlier in Phase II. European Health Technology Assessment bodies are responding by front-loading economic modeling exercises to align with compressed regulatory clocks.
Site-of-care migration is fragmenting traditional infusion center relationships in PNH therapy delivery. Home health nursing networks are displacing hospital outpatient departments for stable patients on subcutaneous regimens. This pattern is most visible in the United States, where Medicare reimbursement differentials favor home administration and specialty pharmacy distribution channels capture patient management functions previously held by academic medical centers.
Paroxysmal Nocturnal Hemoglobinuria (PNH) Treatment Market Segmentation
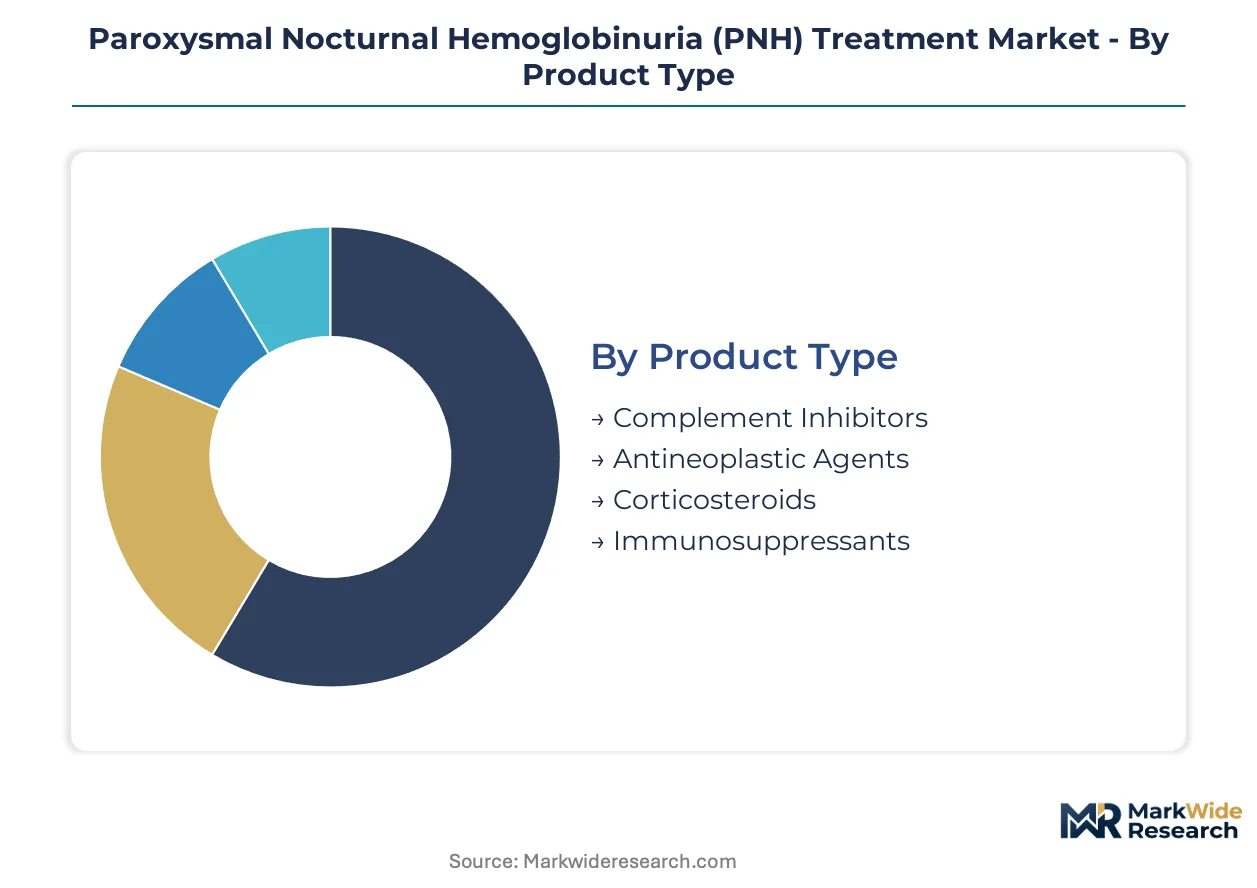
PNH treatment segmentation reveals how therapeutic innovation fragments across delivery modalities and care settings. Manufacturers must align portfolio investments with the shift toward patient-administered biologics and the consolidation of complex case management in academic hematology centers.
Product Type:
Standalone biologic therapies dominate prescription volume, while combination protocols embed complement inhibitors within broader immunomodulatory regimens for marrow failure presentations.
- Complement Inhibitors:C5 and C3-targeted monoclonal antibodies and peptides constitute the therapeutic backbone. Hospital formulary committees in the United States prioritize these agents for confirmed PNH cases with hemolysis-driven anemia, driven by FDA orphan drug exclusivity that protects developer margins.
- Antineoplastic Agents:Cytotoxic protocols retain niche application in PNH clones with concurrent myelodysplastic features. Demand concentrates in German university hospitals where integrated hematology-oncology departments manage complex dual diagnoses.
- Corticosteroids:Bridge therapy for acute hemolytic crises and pre-transplant conditioning.
- Immunosuppressants:Legacy protocols for hypoplastic PNH variants with bone marrow failure.
Volume placements concentrate in Complement Inhibitors; the faster expansion belongs to C3-targeted mechanisms displacing established C5 blockade.
Administration Route:
Cost tier stratification separates infusion-dependent hospital administration from premium-priced self-injection formulations that shift site-of-care economics toward outpatient and home settings.
- Intravenous:Established delivery for C5 inhibitors requiring supervised loading doses and maintenance infusions. Academic medical centers in the United States capture patient volumes through dedicated complement disorder clinics, though capacity constraints limit throughput expansion.
- Subcutaneous:Self-administered C3 peptide inhibitors and biosimilar formulations reduce facility dependency. French and German reimbursement frameworks now favor home nursing support for stable patients, compressing total cost of care.
- Oral:Small-molecule complement pathway modulators in Phase II development.
- Intramuscular:Adjunctive corticosteroid and immunoglobulin delivery.
Patient throughput peaks with Intravenous administration; Subcutaneous protocols are climbing the fastest as prescriber comfort with home-based biologic management expands.
End User:
Customer type fragmentation follows the severity gradient of PNH presentations, with curative-intent transplant evaluation reserved for tertiary centers while chronic maintenance disperses toward community-accessible channels.
- Hospitals:Academic medical centers anchor PNH care through integrated diagnostic and therapeutic capabilities. The United States maintains concentration of complement science expertise at centers like Boston and New York, where multidisciplinary teams manage thrombosis risk and marrow failure progression.
- Clinics:Community hematology practices handle stable patients on established regimens. Japanese metropolitan clinics leverage PMDA Sakigake pathway familiarity to accelerate novel therapy access for appropriate candidates.
- Homecare Settings:Nursing networks manage subcutaneous administration and adverse event monitoring.
- Specialty Pharmacies:Distribution hubs for cold-chain biologics with patient adherence programs.
Complex case volume concentrates in Hospitals; Homecare Settings show the steepest expansion trajectory as subcutaneous formulation adoption accelerates.
Therapeutic Class:
Supply concentration distinguishes plasma-derived and recombinant biologics from small-molecule manufacturing, while gene therapy production remains captive to viral vector capacity constraints at specialized facilities.
- Biologics:Recombinant proteins and monoclonal antibodies command dominant value share. C5 inhibitor manufacturing concentrates at AstraZeneca and Apellis production networks, with batch release timelines tied to FDA viral safety testing protocols.
- Gene Therapies:Lentiviral and CRISPR-edited stem cell approaches target curative outcomes. Manufacturing complexity limits initial capacity to contract development and manufacturing organizations with established viral vector suites.
- Small Molecules:Oral complement pathway modulators in preclinical and early clinical stages.
- Others:Plasma-derived immunoglobulins and supportive care agents.
Revenue concentration sits with Biologics; Gene Therapies are expanding most quickly as durability data from early-phase studies reshape long-term patient management economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orphan drug tax credits and priority review vouchers concentrate PNH therapy development in jurisdictions with formal rare disease frameworks. The United States, Germany, Japan, France, and the United Kingdom anchor clinical trial density and complement science infrastructure.
United States
FDA orphan drug exclusivity and waived user fees incentivize biologic development for ultra-rare indications. The 21st Century Cures Act accelerates breakthrough therapy designation pathways. Boston and New York metropolitan areas concentrate academic hematology centers with dedicated complement disorder clinics managing complex PNH cases.
Germany
G-BA health technology assessments now integrate real-world hemolysis registry data alongside traditional trial endpoints. The country's national pharmaceutical regulator maintains stringent post-market pharmacovigilance for complement inhibitors. Heidelberg and Munich university hospitals anchor European complement research coordination and patient referral networks.
Japan
PMDA's Sakigake designation compresses review timelines for novel complement mechanisms targeting rare diseases. The Ministry of Economy, Trade and Industry supports domestic biomanufacturing capacity for peptide inhibitors. Tokyo metropolitan clinics leverage early reimbursement negotiation pathways to accelerate patient access to upstream C3-targeted therapies.
France
ANSM orphan drug frameworks align with EMA centralized procedures while preserving national pricing autonomy. Haute Autorité de Santé evaluates complement inhibitors against hospitalization reduction metrics rather than surrogate endpoints alone. Paris and Lyon academic centers concentrate multidisciplinary teams managing thrombosis risk in PNH patients with concurrent marrow failure.
United Kingdom
NICE technology appraisals increasingly condition PNH therapy reimbursement on quality-adjusted life year thresholds specific to rare disease populations. The Medicines and Healthcare products Regulatory Agency participates in EMA parallel scientific advice for complement inhibitor development. London and Cambridge clusters integrate gene therapy manufacturing capabilities with National Health Service specialized commissioning frameworks.
Paroxysmal Nocturnal Hemoglobinuria (PNH) Treatment Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the PNH treatment landscape, creating a tiered structure where portfolio breadth confronts targeted therapeutic depth. Large-cap pharmaceutical companies leverage hematology franchise infrastructure to sustain complement inhibitor market positions. Mid-cap biotech specialists concentrate manufacturing control and regulatory expertise around single-mechanism platforms. The dominant competitive moves involve upstream integration into peptide manufacturing and subcutaneous formulation development to capture site-of-care economics.
Within the large-cap diversified tier, AstraZeneca and Novartis occupy positions defined by complement science infrastructure and hematology portfolio breadth respectively. Among mid-cap specialists, Apellis Pharmaceuticals exemplifies the focused development model anchored in manufacturing control over pegylated peptide production. These three entities represent the competitive archetypes reshaping prescriber preferences and formulary positioning across hospital-based hematology departments.
| Leading Market Players |
|---|
| AstraZeneca |
| Apellis Pharmaceuticals |
| Novartis |
| Hoffmann-La Roche |
| Regeneron Pharmaceuticals |
| BioCryst Pharmaceuticals |
| Amgen |
| Sanofi |
| AKARI Therapeutics |
| Others |
Value Chain & Pricing Dynamics
Complement biology expertise concentration in Boston and Cambridge biotech clusters widens labor-cost differentials between premium-tier C3 peptide inhibitors and standard C5 monoclonal antibodies, compressing margin structures for manufacturers lacking captive manufacturing talent.
Pricing Analysis
Lead-time-driven pricing stratification rewards manufacturers with validated viral vector capacity, where premium tiers command immediate batch release and spot inventory discounts attract price-sensitive hospital systems awaiting standard queue positions. Price differentiation rests on FDA orphan drug exclusivity windows and subcutaneous formulation convenience, with cost compression in intravenous C5 inhibitors intensifying as biosimilar development advances. Academic medical centers in the United States exhibit lowest price sensitivity given bundled reimbursement pathways, while European hospital procurement coalitions leverage volume aggregation for steeper discounts.
Supply Chain Analysis
Regional distribution centers in the United States and Germany anchor cold-chain logistics for complement inhibitors, with hub-and-spoke patterns radiating from fractionation facilities in North Carolina and Frankfurt. Plasma-derived protein supply concentrates in the United States and Germany, exposing manufacturers to raw material batch variability and extended viral safety testing timelines. Single-source vulnerability for pegylated peptide manufacturing feeds from limited contract development organizations with validated peptide synthesis suites. Distribution runs through specialty pharmacy networks capturing patient adherence programs previously managed by hospital outpatient departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PNH treatment market sits in a technology-transition phase, with C3-targeted upstream complement inhibition displacing established C5 blockade protocols and gene-editing durability data reshaping long-term patient management economics.
For Market Incumbents: To counter biosimilar pressure on legacy C5 inhibitors, AstraZeneca and Novartis must deepen backward integration into peptide manufacturing capacity and secure subcutaneous formulation patents that extend market protection beyond orphan drug exclusivity windows. Capacity expansion in Singapore and Switzerland biologics hubs reduces single-source manufacturing risk.
For New Entrants and Emerging Players: Capture white-space opportunity in Japan's Sakigake-designated fast-track pathway for novel complement mechanisms, where PMDA priority review compresses development timelines relative to FDA standard pathways. Homecare delivery infrastructure for stable PNH patients on subcutaneous regimens represents the most penetrable service layer, with specialty pharmacy partnerships as the essential go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap specialists possessing validated lentiviral vector manufacturing platforms given durability data from early-phase gene therapy studies. Long-term viability over the next decade hinges on convergence between conventional biologics and curative gene-editing protocols. The signal to watch is EMA approval of CRISPR-edited stem cell therapies, which would validate manufacturing scalability and trigger portfolio reallocation toward durable intervention models.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Peptide inhibitor capacity expansion in Singapore reduces batch release bottlenecks tied to FDA viral safety protocols. |
| Regulatory Approval Pathway | PMDA Sakigake designation accelerates Japanese market entry for C3-targeted mechanisms against established C5 blockade. |
| Pipeline Diversification | Gene therapy programs targeting C3 knockout validate curative positioning beyond chronic pharmacotherapy maintenance models. |
| Licensing Agreement | Subcutaneous formulation partnerships with specialty pharmacy networks capture site-of-care economics from hospital outpatient departments. |
| Clinical Trial Advancement | Real-world hemolysis registry integration satisfies Germany's G-BA evidence requirements for faster reimbursement decisions. |
Study Parameters
Multi-period observation of complement inhibitor prescription volumes, formulary placement timelines, and orphan drug exclusivity expirations anchored the trend analysis, supplemented by interviews with drug development executives at biologics manufacturers, regulatory affairs leads navigating FDA and EMA pathways, formulary directors at academic medical centers, hospital procurement managers overseeing biologic acquisition, and payer access specialists managing prior authorization protocols. Secondary validation drew from FDA orphan drug designations, EMA PRIME scheme submissions, ClinicalTrials.gov protocol registrations, and hospital procurement database extracts. Bottom-up patient flow modeling and top-down therapeutic class revenue estimates were triangulated to constrain forecast variance.
Segment-weighting approaches assigned differential growth coefficients across administration route, therapeutic class, and end-user dimensions, with subcutaneous formulations and gene therapies receiving higher trajectory assumptions over the projection horizon. CAGRs were derived from log-linear regression of historical biologics adoption curves, adjusted for regulatory clock compression under breakthrough therapy and Sakigake designations. Forecast inputs incorporated plasma-derived protein supply constraints, viral vector manufacturing capacity buildouts, and real-world evidence integration timelines for Health Technology Assessment bodies.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to gene therapy durability data, biosimilar entry timelines for C5 inhibitors, and EMA pharmacovigilance burden evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Pancytopenia Market
Hematology
Sickle-Cell Anemia Therapeutics Market
Hematology
Graft vs Host Disease Market
Hematology
Erythropoietic Protoporphyria (EPP) Treatment Market
Hematology
Patient Blood Management Market
Hematology
Global Hematopoietic Stem Cell Transplantation Market
Hematology
Neutropenia Treatment Market
Hematology
Allogeneic Stem Cell Therapy Market
Hematology
Non-Hodgkin Lymphoma Treatment Market
Hematology
Sickle Cell Anemia Market
Hematology
Alpha Thalassemia Market
Hematology
Hematologic Malignancies Market
Hematology
Peripheral T-Cell Lymphoma Treatment Market
Hematology
Congenital Amegakaryocytic Thrombocytopenia (CAMT) Market
Hematology
At-Home Hematology Testing Market
Hematology
Global Hematologic Malignancies Treatment Market