
 Middle East and Africa General Surgical Devices Market | 2026-2036
Middle East and Africa General Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa General Surgical Devices Market Foresight
Modular instrument kits is expanding across Middle East and Africa procurement channels, letting buyers customize sets by procedure rather than purchasing fixed bundles. Medtronic leverages its broad electrosurgery portfolio to anchor large hospital contracts in Gulf states. Johnson & Johnson sustains competitive positioning through deep specialization in sutures and wound closure across sub-Saharan markets. Smith & Nephew differentiates via advanced arthroscopy tools targeting orthopedic growth in South Africa and Nigeria.
General surgical devices encompass manually operated and powered instruments—including scalpels, forceps, clamps, needle holders, and electrosurgical units—fabricated from medical-grade stainless steel, titanium, or polymer composites, designed to cut, grasp, coagulate, or retract tissue during operative procedures. Electrosurgery leads technology adoption as hospitals replace conventional cautery with precision radiofrequency platforms that reduce operative blood loss and recovery time. Robotic surgery represents the fastest-growing technology segment, though from a narrow installed base concentrated in Saudi Arabia and UAE tertiary centers. Among end users, ambulatory surgical centers capture disproportionate investment growth as Gulf health ministries push same-day procedures to manage chronic disease prevalence.
SFDA in Saudi Arabia and MOHAP in the UAE enforce medical device registration and post-market surveillance requirements that filter non-compliant suppliers from procurement tenders. South Africa's Health Products Regulatory Authority applies stringent quality standards that delay market entry but protect established manufacturers with robust technical files. Stakeholders must monitor how Egypt's drug authority expands device oversight capacity, as Cairo's emerging hospital clusters become pivotal volume outlets.
Market Dynamics
Electrosurgical platform upgrades are compressing replacement cycles across Middle East and Africa hospital procurement, as facilities prioritize radiofrequency systems that reduce operative blood loss over conventional cautery instruments.
Growth Catalysts
- Vision 2030 Health Privatization:Saudi Arabia's hospital construction pipeline is expanding surgical capacity in Riyadh and Jeddah, creating sustained demand for modular instrument kits and powered surgical platforms.
- SFDA Registration Protocols:Saudi Arabia's tightened medical device registration requirements are filtering non-compliant suppliers from tenders, consolidating procurement around manufacturers with robust technical files.
- Radiofrequency Electrosurgery:Tertiary centers in UAE and South Africa are replacing thermal cautery with precision coagulation systems that shorten patient recovery time and reduce transfusion rates.
Market Restraints
- Titanium Alloy Input Costs:Surgical instrument fabricators face margin pressure from volatile medical-grade titanium pricing, particularly affecting forceps and needle holder production.
- European Supply Concentration:High-performance electrosurgical generators rely heavily on German and Swiss component suppliers, exposing procurement to euro-denominated cost fluctuations and extended lead times.
- South Africa HPRA Delays:South Africa's Health Products Regulatory Authority applies stringent quality standards that extend market entry timelines for new device categories.
Strategic Opportunities
- Nigeria Orthopedic Expansion:Lagos and Abuja hospital clusters are investing in arthroscopy suites, creating demand for advanced visualization and shaver systems previously concentrated in South Africa.
- MOHAP Compliance Investment:UAE's Ministry of Health and Prevention registration acceleration is rewarding manufacturers who pre-invest in post-market surveillance infrastructure.
- Same-Day Surgery Mandates:Gulf health ministries are directing chronic disease procedures toward ambulatory surgical centers, reshaping device specifications toward compact, portable electrosurgical units.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Electrosurgical platform maintenance and calibration require specialized technicians that remain concentrated in Cairo, Johannesburg, and Dubai medical device hubs.
- Legacy System Integration:Robotic surgery adoption in Saudi tertiary centers faces friction from incompatible sterilization workflows and instrument tracking systems designed for conventional open procedures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa General Surgical Devices Market |
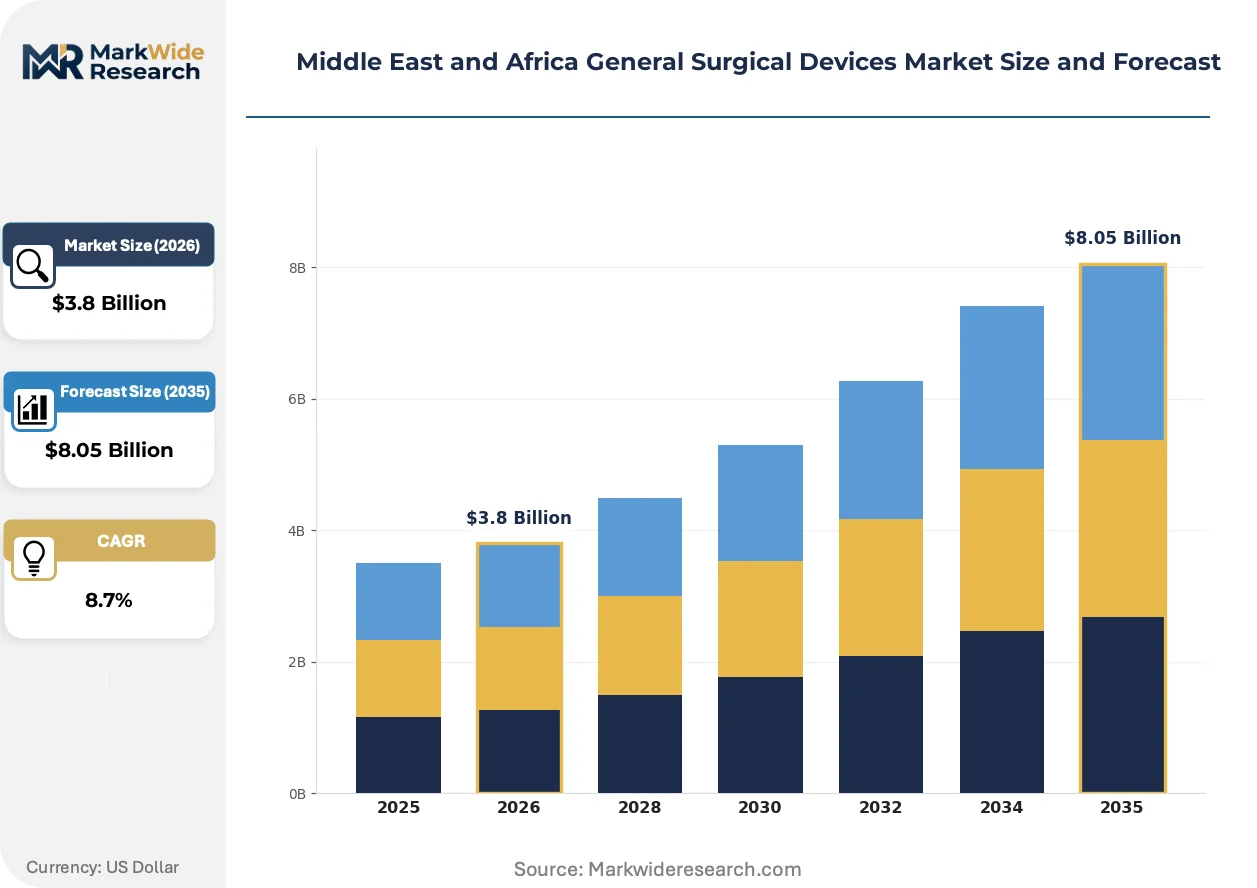
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scissors, Forceps, Clamps, Needle Holders End User: Hospitals, Ambulatory Surgical Centers, Clinics, Specialty Centers Technology: Electrosurgery, Laser Surgery, Robotic Surgery, Open Surgery Application: General Surgery, Orthopedic Surgery, Cardiothoracic Surgery, Neurosurgery |
| Companies Covered | Johnson & Johnson, Medtronic, Smith & Nephew, Stryker Corporation, GE Healthcare, B. Braun Melsungen AG, 3M Company, Koninklijke Philips N.V., Olympus Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa General Surgical Devices Market Shifts & Advancements
Device connectivity and procedure-specific customization are reshaping competitive positioning in Middle East and Africa surgical markets, compressing the gap between premium and mid-tier feature sets.
Radiofrequency-based vessel sealing systems are automating hemostasis during laparoscopic procedures, reducing reliance on manual suturing. Tertiary hospitals in Riyadh and Dubai are adopting these platforms at accelerated replacement cycles. This automation is compressing training timelines for surgical residents while standardizing operative outcomes across high-volume general surgery departments.
SFDA and MOHAP are synchronizing post-market surveillance requirements with EU MDR technical documentation standards, forcing manufacturers to unify quality management systems across Gulf and European submissions. Industrial consequence includes accelerated consolidation of distributor networks around entities with dual-territory regulatory expertise. Electrosurgical and powered instrument categories face the steepest compliance investment thresholds.
Hospital procurement committees are unbundling after-sales service from capital equipment contracts, negotiating separate multi-year maintenance agreements with third-party biomedical engineering firms. This disintermediation is displacing manufacturer-captive service revenue in UAE and Saudi Arabia. South African private hospital groups pioneered this model, with Netcare and Life Healthcare now replicating the structure across their expanding Nigerian and Kenyan facility networks.
Middle East and Africa General Surgical Devices Market Segmentation
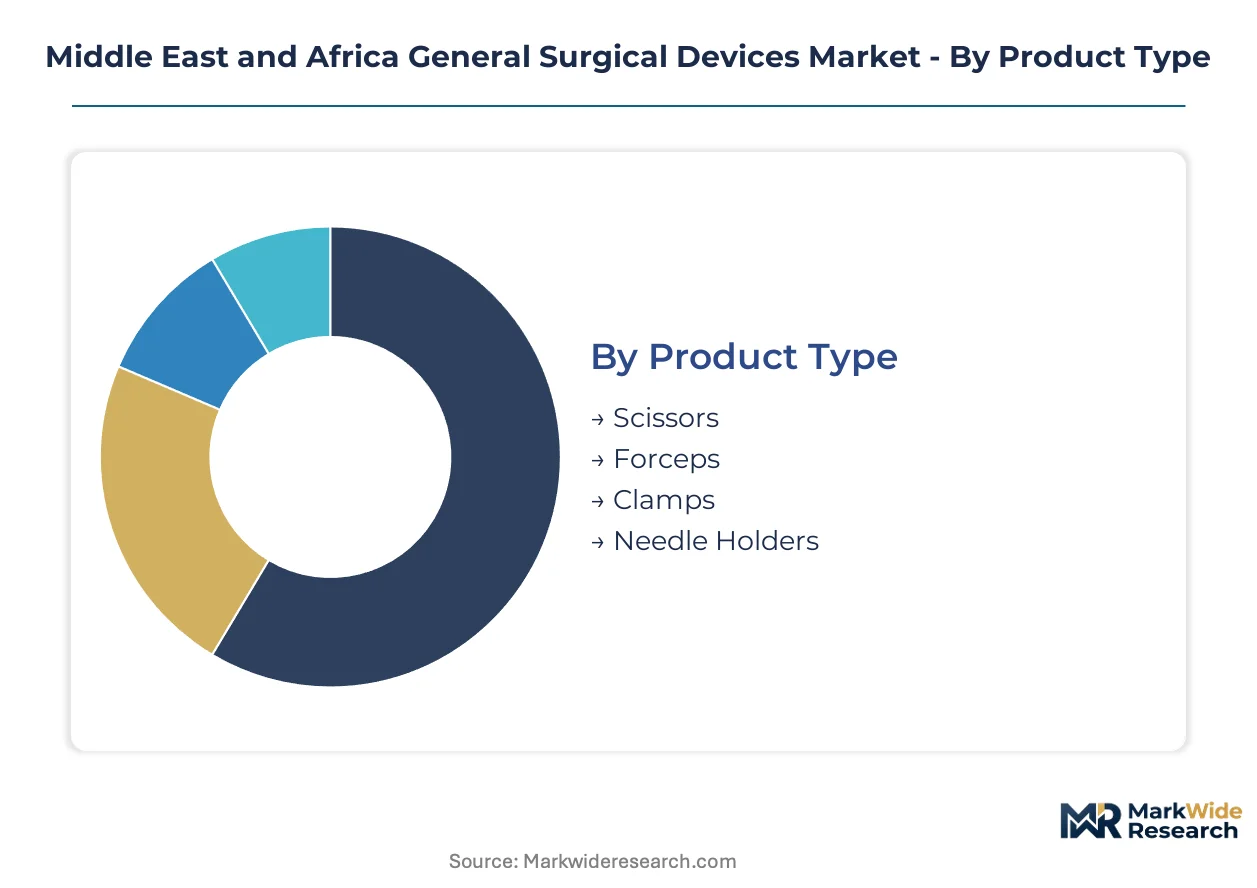
Device specification and procurement authority vary sharply across Middle East and Africa surgical settings. Segmentation reveals where radiofrequency platforms displace conventional instruments and which facility types drive modular kit adoption.
Product Type:
Material composition and sterilization durability separate procurement tiers across Gulf and sub-Saharan hospital systems.
- Scissors:Fabricated from medical-grade stainless steel or titanium alloys, these instruments withstand repeated autoclave cycles in high-throughput Saudi tertiary centers. Demand concentrates in Riyadh and Jeddah hospital construction pipelines where Vision 2030 expansion mandates bulk instrument procurement.
- Forceps:Tissue-grasping instruments with serrated or atraumatic tip configurations dominate open procedure volumes. South Africa's private hospital groups standardize on premium-grade forceps for arthroscopy suites, though titanium input cost volatility compresses manufacturer margins.
- Clamps:Hemostatic and non-crushing variants serve vascular and gastrointestinal applications across UAE MOHAP-regulated facilities.
- Needle Holders:Carbide-insert jaw designs target microsurgical suturing in Cairo and Lagos emerging hospital clusters.
Volume sits with forceps and scissors; growth tilts toward needle holders as microsurgical specialization expands.
End User:
Capital intensity and procedure mix determine device category priorities across the care continuum.
- Hospitals:Tertiary medical centers in Saudi Arabia and the UAE anchor demand for integrated electrosurgical platforms with vessel-sealing capabilities. SFDA registration compliance filters procurement toward established manufacturers with robust technical files.
- Ambulatory Surgical Centers:Compact, portable radiofrequency units serve same-day procedure mandates from Gulf health ministries. Dubai and Abuja ASC networks are gaining share fastest as chronic disease management shifts to outpatient settings.
- Clinics:Basic manual instrument sets predominate in primary care surgical interventions across Kenya and Ethiopia.
- Specialty Centers:Dedicated orthopedic and ophthalmic facilities in Johannesburg and Cape Town require procedure-specific visualization systems.
Procurement authority concentrates in hospitals; expansion momentum belongs to ambulatory surgical centers.
Technology:
Precision requirements and training infrastructure shape technology adoption curves.
- Electrosurgery:Radiofrequency-based coagulation and cutting systems reduce operative blood loss and transfusion rates. UAE tertiary centers and South Africa's Netcare network are replacing thermal cautery at accelerated replacement cycles.
- Robotic Surgery:Da Vinci and comparable platforms enable minimally invasive procedures with enhanced visualization. Saudi Arabia's King Faisal Specialist Hospital and Dubai's Mediclinic City Hospital anchor the narrow installed base.
- Laser Surgery:Tissue ablation and photocoagulation systems serve specialized ophthalmic and dermatological applications.
- Open Surgery:Conventional manual instrumentation persists in resource-constrained settings and emergency interventions.
Electrosurgery commands current procurement volumes; robotic platforms claim the steepest expansion trajectory.
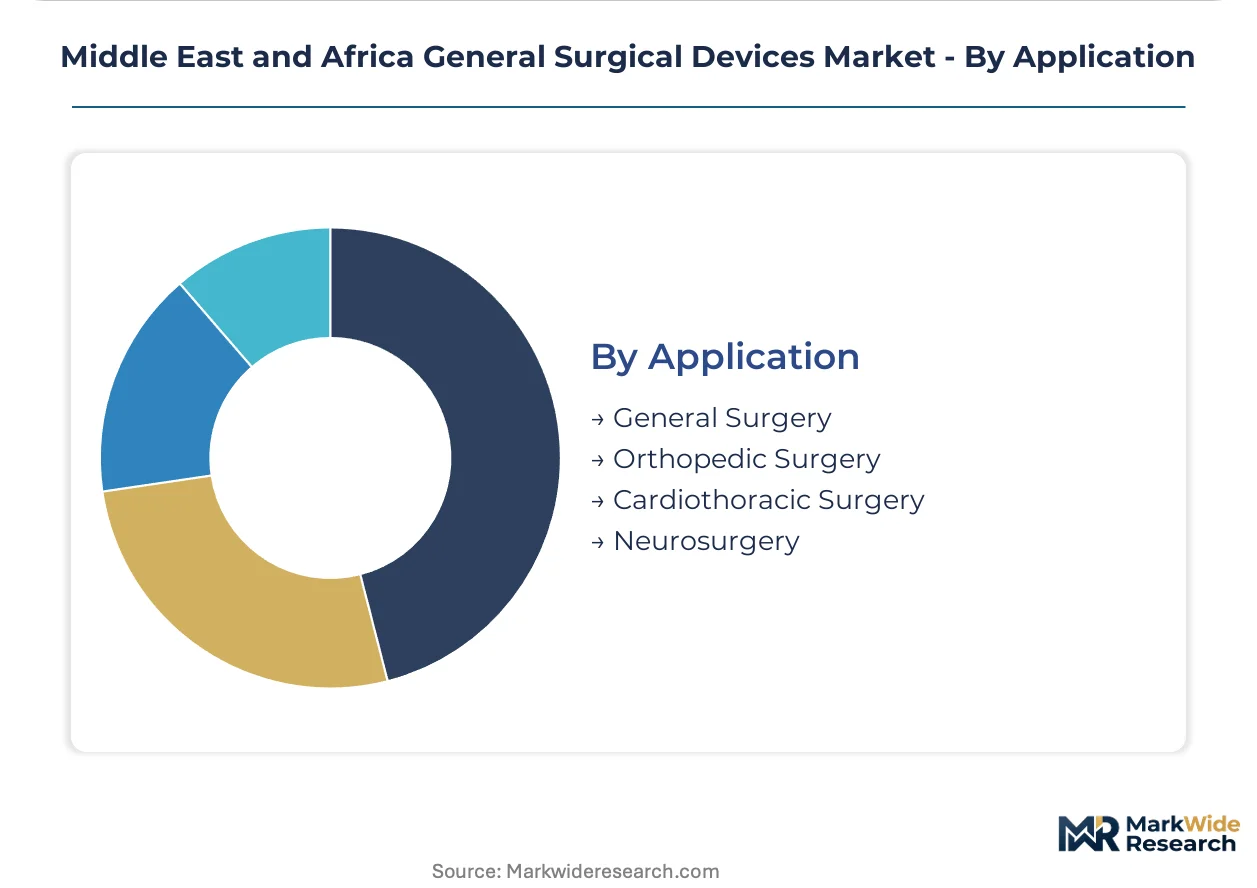
Application:
Surgical volume and reimbursement structure determine device sophistication requirements.
- General Surgery:Appendectomy, cholecystectomy, and hernia repair procedures generate baseline demand for laparoscopic and open instrument sets. Egypt's emerging hospital clusters in Cairo and Alexandria are scaling general surgery capacity.
- Orthopedic Surgery:Arthroscopy, joint replacement, and trauma fixation drive demand for powered shavers, reamers, and advanced visualization. Nigeria's Lagos and Abuja hospital networks are replicating South Africa's orthopedic specialization model.
- Cardiothoracic Surgery:Sternum saws, retractors, and bypass cannulae serve coronary and valve procedures in Saudi and UAE cardiac centers.
- Neurosurgery:High-speed drills, micro-instruments, and navigation-compatible retractors target cranial and spinal interventions.
General surgery anchors procedure volume; orthopedic applications are expanding most quickly across West Africa.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
King Abdullah Economic City anchors surgical device distribution networks serving the Red Sea corridor. Jebel Ali Free Zone concentrates Gulf re-export logistics for European and Asian manufacturers. Special economic zone incentives are reshaping where multinational suppliers locate regional headquarters and service infrastructure.
Saudi Arabia
Vision 2030 hospital construction in Riyadh and Jeddah is generating procurement demand for electrosurgical platforms and modular instrument kits. SFDA registration protocols filter tenders toward suppliers with robust technical documentation. The King Faisal Specialist Hospital cluster anchors robotic surgery adoption in the Eastern Province.
United Arab Emirates
Dubai Healthcare City and Abuja's Cleveland Clinic Abu Dhabi drive demand for precision radiofrequency systems. MOHAP has synchronized post-market surveillance with EU MDR standards, raising compliance investment thresholds. Jebel Ali Free Zone serves as the Gulf's primary re-export hub for sub-Saharan markets.
South Africa
Netcare and Life Healthcare private hospital groups are standardizing procurement of arthroscopy suites and advanced visualization systems. Health Products Regulatory Authority quality standards extend market entry timelines but protect established manufacturers. Johannesburg and Cape Town orthopedic centers anchor regional specialization.
Egypt
Cairo and Alexandria hospital clusters are scaling general surgery capacity for a population exceeding 100 million. The national drug authority is expanding medical device oversight capacity to match procurement growth. New administrative capital medical city projects concentrate demand in Greater Cairo.
Nigeria
Lagos and Abuja hospital networks are replicating South Africa's orthopedic specialization model with arthroscopy investments. Federal Ministry of Health procurement reforms are opening tenders to international suppliers with local distribution partnerships. Private hospital construction in Lekki Free Trade Zone concentrates high-end surgical capacity.
Middle East and Africa General Surgical Devices Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers in Middle East and Africa surgical markets. The vendor base stratifies into three layers: multinational manufacturers with full electrosurgery portfolios, regional distributors with regulatory expertise, and local fabricators serving price-sensitive clinic segments. Two dominant competitive moves are reshaping positioning: M&A activity consolidating distributor networks around dual-territory regulatory capability, and strategic partnerships between global manufacturers and Gulf-based service providers.
Within the diversified multinational tier, Johnson & Johnson and Medtronic occupy anchor positions across hospital procurement channels. Smith & Nephew exemplifies the focused specialist archetype targeting orthopedic visualization growth. These three entities represent the competitive spectrum from broad portfolio coverage to procedure-specific depth that characterizes Middle East and Africa market structure.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Medtronic |
| Smith & Nephew |
| Stryker Corporation |
| GE Healthcare |
| B. Braun Melsungen AG |
| 3M Company |
| Koninklijke Philips N.V. |
| Olympus Corporation |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between SFDA-compliant electrosurgical platforms and non-registered imports manifests in procurement premiums reaching threefold multiples, with Gulf hospital systems paying accelerated delivery charges to bypass European component lead times while sub-Saharan clinics absorb extended waits for economy-grade manual instrument shipments.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with UAE tertiary centers paying substantial uplifts for German-manufactured radiofrequency generators delivered within eight weeks versus spot-market discounts on Asian-sourced thermal cautery units held in Jebel Ali bonded warehouses. Three-tier pricing structure across premium, standard, and economy levels reflects CE-marked versus non-CE instrument grades and bundled after-sales service inclusion. Pricing pressure stems from titanium alloy spot market volatility compressing forceps manufacturer margins. Government hospital procurement committees in Saudi Arabia exhibit lowest price sensitivity due to Vision 2030 budget allocation, while Kenyan district clinics face severe cost constraints.
Supply Chain Analysis
SFDA and MOHAP registration requirements gate market access, filtering supplier networks toward entities with dual-territory EU MDR technical documentation capability and established post-market surveillance infrastructure. Manufacturing concentrates in Germany, Switzerland, and Malaysia for electrosurgical generators and precision instruments, with Pakistan and India supplying economy-grade stainless steel manual tools. Supply chains draw from medical-grade titanium sponge processed in China and Japan, radiofrequency power electronics from German semiconductor foundries, and polymer composite instrument handles from Malaysian molders. Single-source vulnerability concentrates in European electrosurgical generator component suppliers exposed to euro-denominated cost fluctuations. Distribution runs through Jebel Ali Free Zone re-export hubs serving sub-Saharan markets, with Johannesburg and Lagos anchoring regional logistics nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
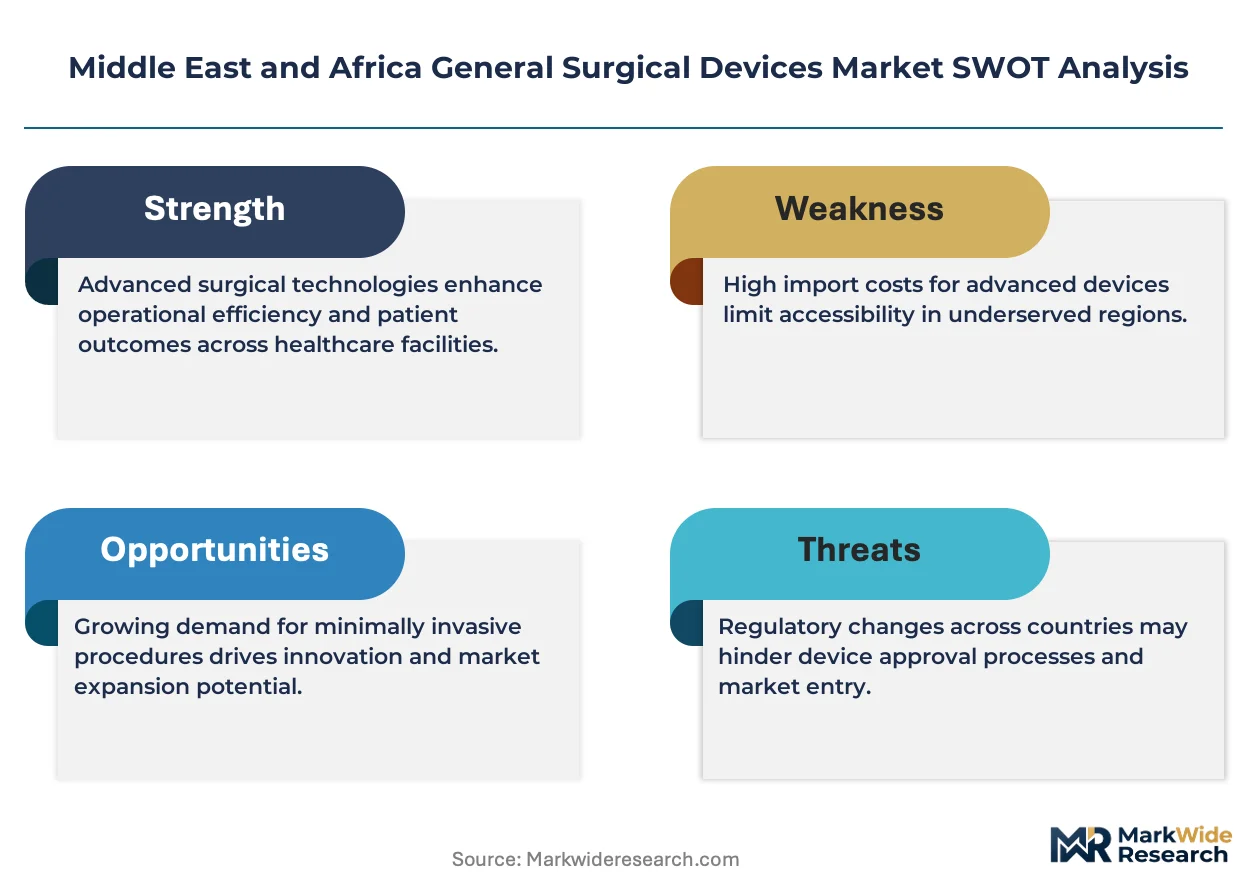
SFDA registration protocols function as a cost-of-compliance moat, consolidating procurement around manufacturers with robust technical files and filtering price-competitive but documentation-deficient entrants from Saudi hospital tenders.
For Market Incumbents: Lock in multi-year service contracts with Gulf hospital networks before procurement committees complete their shift toward third-party biomedical engineering disintermediation. Anchor exclusive electrosurgical platform placements in Riyadh and Jeddah construction pipelines to preempt competitive displacement, while investing in backward integration into titanium instrument forging to offset raw material margin compression from volatile alloy pricing. For New Entrants and Emerging Players: Enter via Nigeria's Lagos and Abuja orthopedic expansion corridors, where arthroscopy suite investments outpace established supplier service capacity and federal procurement reforms open tenders to international distributors with local partnership structures. Target ambulatory surgical center networks in Dubai and Abuja for compact radiofrequency unit placement, leveraging same-day surgery mandates that reshape device specifications toward portable formats underserved by incumbent hospital-focused portfolios. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified medtech conglomerates seeking Gulf regulatory expertise, with IPO windows contingent on demonstrating sustained SFDA registration renewal rates across product portfolios. Acquisition target archetypes include regional distributors with dual-territory EU MDR and Gulf compliance capability and specialized arthroscopy visualization firms with Nigerian hospital network relationships. Watch Egyptian drug authority device oversight expansion as inflection signal, as Cairo hospital cluster procurement volume acceleration will reward early compliance infrastructure positioning.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Acceleration | Pre-emptive technical file investment secures preferential tender positioning in Saudi Vision 2030 hospital construction. |
| Hospital System Partnership | Exclusive electrosurgical platform agreements with Netcare or Life Healthcare lock out competitor access across Southern Africa. |
| Backward Integration | In-house titanium alloy forging capability insulates margin structure from spot market volatility affecting forceps production. |
| Software Companion Development | Procedure-specific radiofrequency parameter libraries differentiate platforms in UAE tertiary center replacement cycles. |
| Reimbursement Strategy | Same-day surgery outcome documentation supports Gulf health ministry ASC procurement mandate alignment. |
Research Methodology
Trade databases, hospital procurement registries, and regulatory filing repositories formed the secondary backbone, supplemented by structured interviews with biomedical engineering directors, hospital purchasing committee members, GPO contracts managers, and SFDA regulatory consultants. Primary fieldwork validated secondary estimates against actual tender award values and instrument replacement cycle documentation. Bottom-up modeling triangulated against top-down macroeconomic healthcare expenditure projections.
Analytical lenses combined facility-level capital equipment installation tracking with national health budget allocation patterns across the projection horizon. Segmentation dimensions modeled include product material grade, end-user facility type, technology platform, surgical application, and national regulatory cluster. CAGRs derived from fitted growth curves anchored to documented hospital construction pipelines and documented electrosurgical platform replacement intervals. Forecast inputs incorporated titanium alloy price series and documented SFDA registration timeline distributions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained euro appreciation or extended South Africa HPRA review queue backlogs. Model assumptions reflect documented procurement committee decision criteria and verified distributor network structures. A model refresh is warranted upon material change in Saudi Vision 2030 hospital privatization timeline or Egyptian device authority oversight capacity expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Surgical Clips Market
Surgical Instruments
Dermal Curettes Market
Surgical Instruments
Global Plastic Surgery Instruments Market
Surgical Instruments
Surgical Stents Market
Surgical Instruments
US Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Japan General Surgical Devices Market
Surgical Instruments
Ophthalmology Surgical Devices Market
Surgical Instruments
Ultrasonic Surgical Cutters Market
Surgical Instruments
Operating Room Smoke Aspirators Market
Surgical Instruments
Hemostatic Instruments Market
Surgical Instruments
Argentina General Surgical Devices Market
Surgical Instruments
Endometrial Ablation Market
Surgical Instruments
Global Bipolar Electrosurgical Devices Market
Surgical Instruments
Plastic Wound Retractor Market
Surgical Instruments
Global Surgical Stapler Market
Surgical Instruments
Special Purpose Needles Market