
 Langerhans Cell Histiocytosis Management Market | 2026-2036
Langerhans Cell Histiocytosis Management Market Size, Share, and Industry Trends Forecast 2026-2036
Langerhans Cell Histiocytosis Management Market Foresight
Targeted small-molecule compounds are consolidating position against conventional cytotoxic chemotherapy in LCH treatment protocols. Sanofi S.A. leverages its rare disease infrastructure to sustain clinical trial access across European academic centers. Regeneron Pharmaceuticals Inc. anchors its position through cytokine pathway research, while Eli Lilly and Company differentiates via precision oncology investments in MAPK-driven malignancies.
Langerhans Cell Histiocytosis Management encompasses the clinical coordination of diagnostic workup, risk-stratified therapy selection, and long-term surveillance for a clonal myeloid neoplasm driven by MAPK pathway mutations, with BRAF V600E present in approximately half of cases. The primary purpose is preventing permanent organ damage—particularly diabetes insipidus, skeletal deformity, and pulmonary fibrosis—while minimizing treatment-related toxicity in a predominantly pediatric population. Chemotherapy retains the largest patient volume among treatment types, though targeted therapy captures the fastest expansion as BRAF and MEK inhibitors secure label extensions. Pediatric patients dominate incident cases, yet adults generate disproportionate per-patient expenditure due to refractory disease patterns and prolonged salvage therapy requirements.
The FDA's Orphan Drug Designation program and EMA's Priority Medicines scheme jointly shape development incentives, compressing regulatory review timelines for histiocytosis-directed agents. Both agencies mandate robust pharmacovigilance frameworks given the narrow safety database inherent to ultra-rare indications. Stakeholders must monitor biomarker-driven trial designs and companion diagnostic partnerships, as these will determine which developers secure preferential formulary positioning in academic medical centers.
Market Dynamics
The transition from empirical chemotherapy to mutation-directed therapy is compressing treatment timelines and reshaping competitive positioning in LCH management. BRAF inhibitor protocols are automating patient stratification decisions previously managed through histopathologic consensus.
Growth Catalysts
- FDA Accelerated Approval Pathway:The streamlined review mechanism for rare disease therapeutics compresses development-to-market intervals for histiocytosis-directed agents. Developers leverage this framework to bypass traditional Phase III requirements.
- MAPK Pathway Biomarker Penetration:BRAF V600E testing is automating diagnostic workup in pediatric oncology centers across Germany and the United States. Academic medical centers now mandate molecular profiling prior to therapy selection.
- Long-term Surveillance Protocols:Endocrine sequelae monitoring programs in major referral networks sustain recurring patient touchpoints. Diabetes insipidus prevention drives sustained clinical engagement beyond initial treatment completion.
Market Restraints
- Ultra-rare Trial Recruitment:EMA's stringent pharmacovigilance mandates for Priority Medicines candidates require safety databases that prove statistically underpowered. Single-arm study designs face heightened scrutiny.
- Targeted Therapy Cost Structure:BRAF and MEK inhibitor pricing reflects orphan drug premiums that strain pediatric hospital pharmacy budgets. Payer negotiations in the United States concentrate on indication-based value frameworks.
- Diagnostic Pathway Fragmentation:Skin biopsy interpretation varies across community pathology practices lacking LCH-specific expertise. Misdiagnosis delays definitive therapy initiation in adult-presenting cases.
Strategic Opportunities
- Adult Refractory Disease Segment:Pulmonary and multisystem adult LCH generates disproportionate per-patient expenditure through prolonged salvage regimens. Specialized centers in the United States are consolidating this high-value cohort.
- Companion Diagnostic Partnerships:Liquid biopsy platforms for circulating tumor DNA detection enable real-time treatment response monitoring. Academic-industry collaborations are securing preferential formulary positioning.
- European Academic Network Expansion:EMA's Priority Medicines scheme incentivizes trial site activation across France, Germany, and Italy. Sanofi S.A. leverages this infrastructure for patient access.
Industry Challenges
- Histiocytosis-specialized Pathologist Scarcity:CD1a and S100 immunohistochemistry interpretation requires fellowship-trained expertise concentrated in major academic centers. Community hospitals face diagnostic backlogs.
- Cross-border Referral Coordination:Pediatric patients requiring BRAF inhibitor therapy often need transfer to designated comprehensive centers. Insurance authorization complexity delays treatment initiation.
- Long-term Toxicity Surveillance Infrastructure:MEK inhibitor cardiac and ocular adverse event monitoring demands dedicated nursing resources. Smaller treatment sites lack capacity for protocol-mandated assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Langerhans Cell Histiocytosis Management Market |
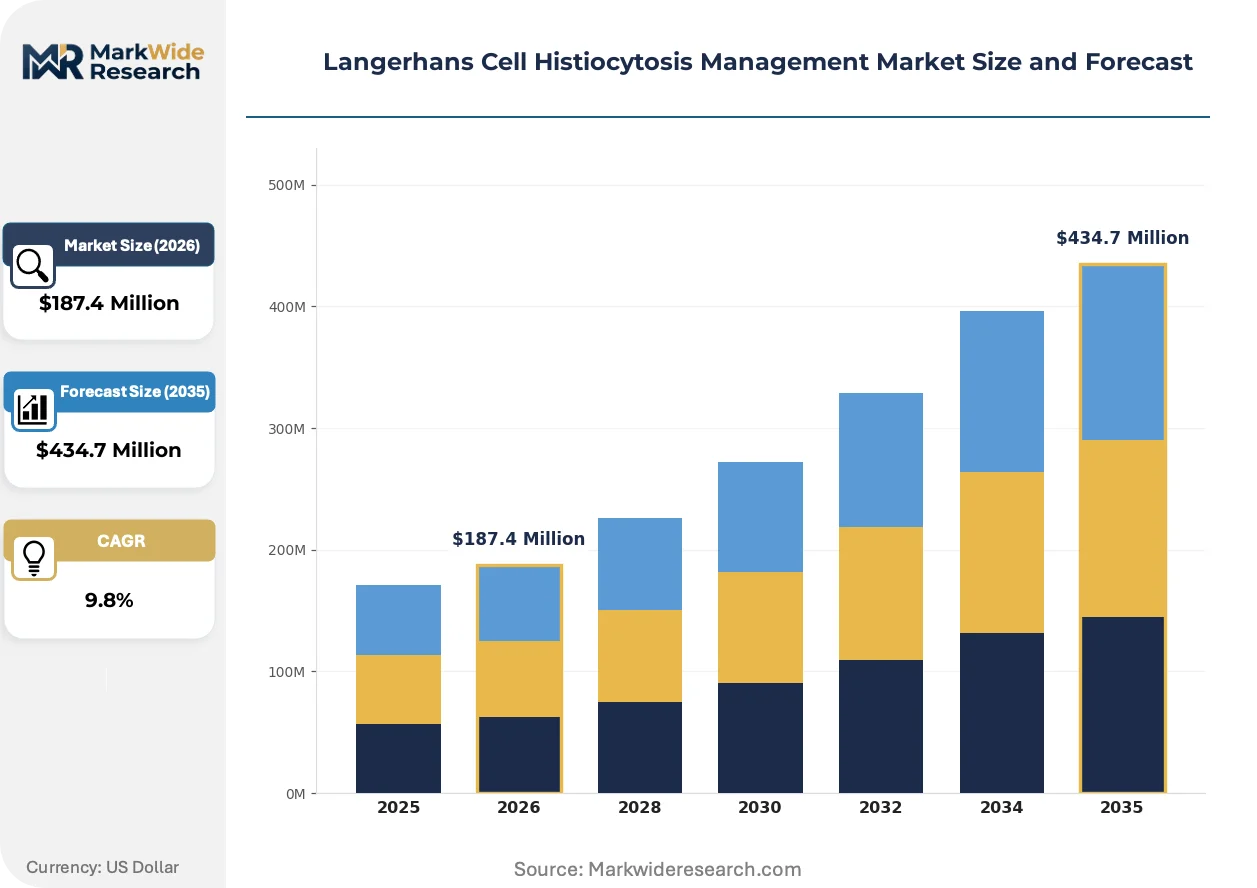
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $434.7 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Surgery, Chemotherapy, Radiotherapy, Targeted Therapy Patient Age Group: Pediatrics, Adolescents, Adults, Seniors Distribution Channel: Hospitals, Retail Pharmacies, Online Pharmacies, Specialty Stores Healthcare Provider: Oncologists, Hematologists, Pediatricians, General Practitioners |
| Companies Covered | Sanofi S.A., Regeneron Pharmaceuticals Inc., Innovent Biologics Inc., Affimed GmbH, Eli Lilly and Company, Amgen Inc., F. Hoffmann-La Roche Ltd, TG Therapeutics Inc., AstraZeneca plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Langerhans Cell Histiocytosis Management Market Shifts & Advancements
Digital pathology integration and real-world evidence generation are converging to reshape how LCH treatment decisions are validated outside traditional clinical trial frameworks. These forces are compressing the feedback loop between molecular diagnosis and therapeutic selection.
Next-generation sequencing panels are automating the detection of MAPK pathway alterations beyond BRAF V600E, including NRAS, KRAS, and MAP2K1 mutations. Pediatric oncology centers in Germany and the United States are adopting these platforms as standard-of-care for risk stratification. This technology is automating the identification of patients eligible for targeted therapy trials, reducing reliance on empirical chemotherapy assignment.
EMA's Priority Medicines scheme now explicitly incorporates histiocytic disorders within its accelerated assessment framework, creating regulatory precedent for ultra-rare myeloid neoplasms. The industrial consequence is a pipeline compression where developers pursue conditional marketing authorization based on single-arm efficacy data. European academic centers are responding by centralizing pharmacovigilance reporting to satisfy post-authorization safety commitments.
Academic medical center procurement departments are consolidating LCH drug purchasing through specialty pharmacy networks rather than traditional hospital wholesalers. This channel shift enables direct manufacturer engagement for patient assistance programs and risk-sharing agreements. The United States exhibits the most pronounced migration, with major pediatric oncology consortia negotiating indication-specific contracts for BRAF inhibitors.
Langerhans Cell Histiocytosis Management Market Segmentation
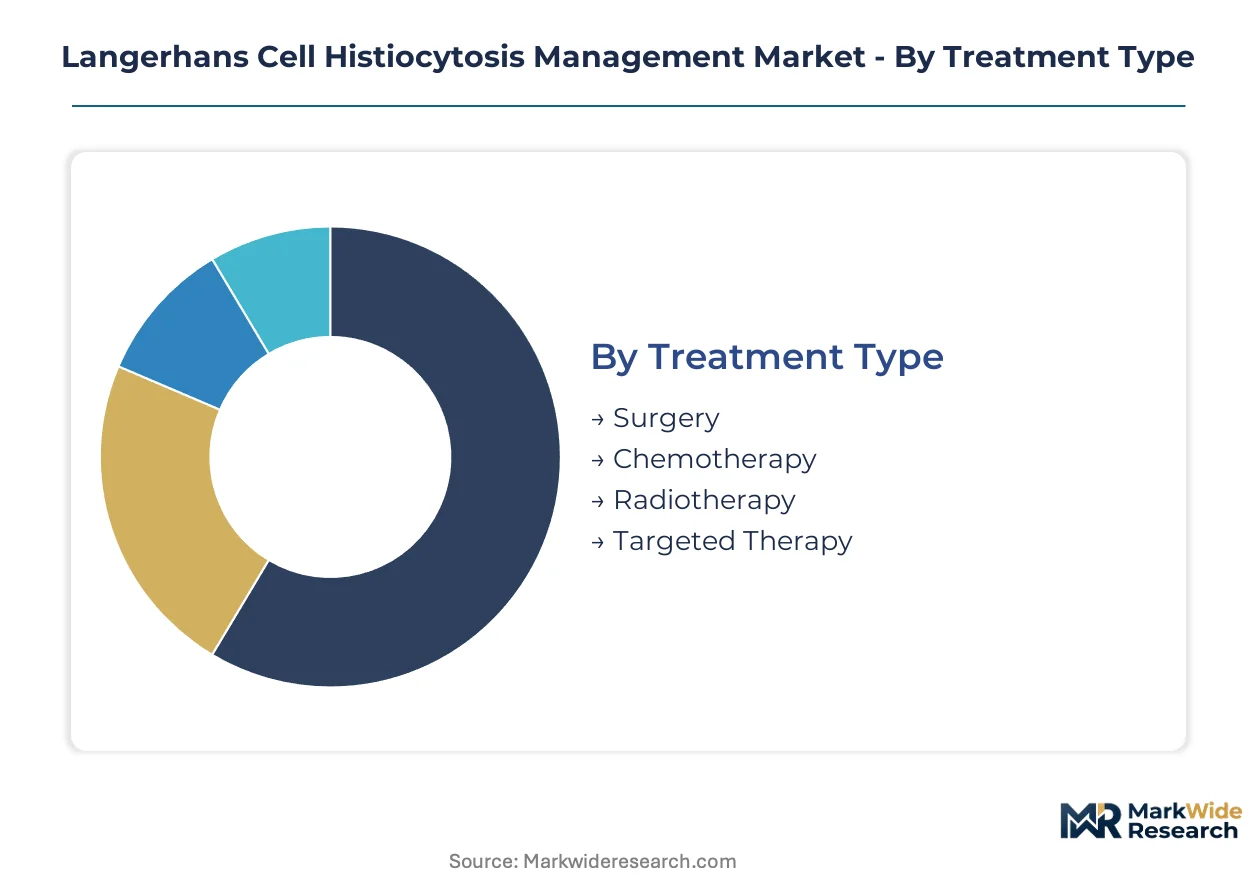
Treatment selection in LCH management follows a risk-stratified algorithm where molecular profiling increasingly displaces empirical protocols. Segmentation reveals how targeted therapy is capturing premium positioning while chemotherapy retains volume dominance across pediatric networks.
Treatment Type:
Protocol upgrades from cytotoxic regimens to mutation-directed therapy are compressing treatment timelines and reshaping hospital pharmacy procurement priorities.
- Chemotherapy:Empirical multi-agent protocols combining vinblastine and prednisone remain the first-line standard for multisystem disease without BRAF V600E mutation. Pediatric oncology centers in Germany and the United States deploy these regimens across high-volume induction protocols, though cumulative toxicity limits cumulative dosing cycles.
- Targeted Therapy:BRAF and MEK inhibitors deliver durable responses in refractory or relapsed cases with MAPK pathway alterations. Academic medical centers mandate molecular profiling prior to therapy assignment, concentrating demand in comprehensive histiocytosis referral networks.
- Surgery:Curative excision of isolated bone lesions in single-system disease eliminates need for systemic therapy. Orthopedic oncology units perform these procedures in tertiary pediatric hospitals.
- Radiotherapy:Localized delivery targets symptomatic bone lesions or compressive disease in adults with pulmonary involvement. Use is restricted to salvage settings due to secondary malignancy risk in young patients.
Volume placements concentrate in chemotherapy; the faster expansion belongs to targeted therapy.
Patient Age Group:
Cost tier stratification separates intensive pediatric protocols from prolonged adult salvage regimens with disproportionate per-patient expenditure.
- Pediatrics:Children under 15 years constitute the dominant incident population, with multisystem disease requiring risk-adapted therapy intensity. Pediatric oncology consortia in the United States standardize enrollment in cooperative group trials.
- Adults:Patients 18-64 years present with pulmonary-predominant or multisystem patterns generating extended treatment duration. Specialized centers manage refractory cases through sequential targeted agent trials.
- Adolescents:Patients 15-17 years occupy a transitional risk category with protocol assignment varying by institutional practice. Some centers align with pediatric regimens; others transition to adult management frameworks.
- Seniors:Patients over 65 years exhibit reduced treatment tolerance and higher comorbidity burden. Conservative management approaches prioritize quality of life over aggressive disease control.
Case volume clusters in pediatrics; steepest expansion trajectory appears in adults.
Distribution Channel:
Supply concentration in specialty pharmacy networks is displacing traditional hospital wholesale procurement for high-cost targeted agents.
- Hospitals:Inpatient and infusion center administration dominates chemotherapy and biologic delivery. Major pediatric oncology centers maintain captive pharmacies for investigational agent management.
- Retail Pharmacies:Community dispensing handles supportive care medications and oral maintenance therapies. Geographic access advantages serve patients in non-metropolitan catchment areas.
- Online Pharmacies:Digital platforms enable home delivery for chronic oral targeted therapy with cold-chain requirements. Patient assistance program coordination flows through manufacturer-affiliated channels.
- Specialty Stores:Limited role in LCH-specific care; primarily serves durable medical equipment for endocrine sequelae management including diabetes insipidus supplies.
Procurement volume anchors in hospital channels; specialty pharmacy networks are gaining share fastest.
Healthcare Provider:
Referral pathway maturity determines which specialists capture initial diagnostic workup versus definitive therapy management.
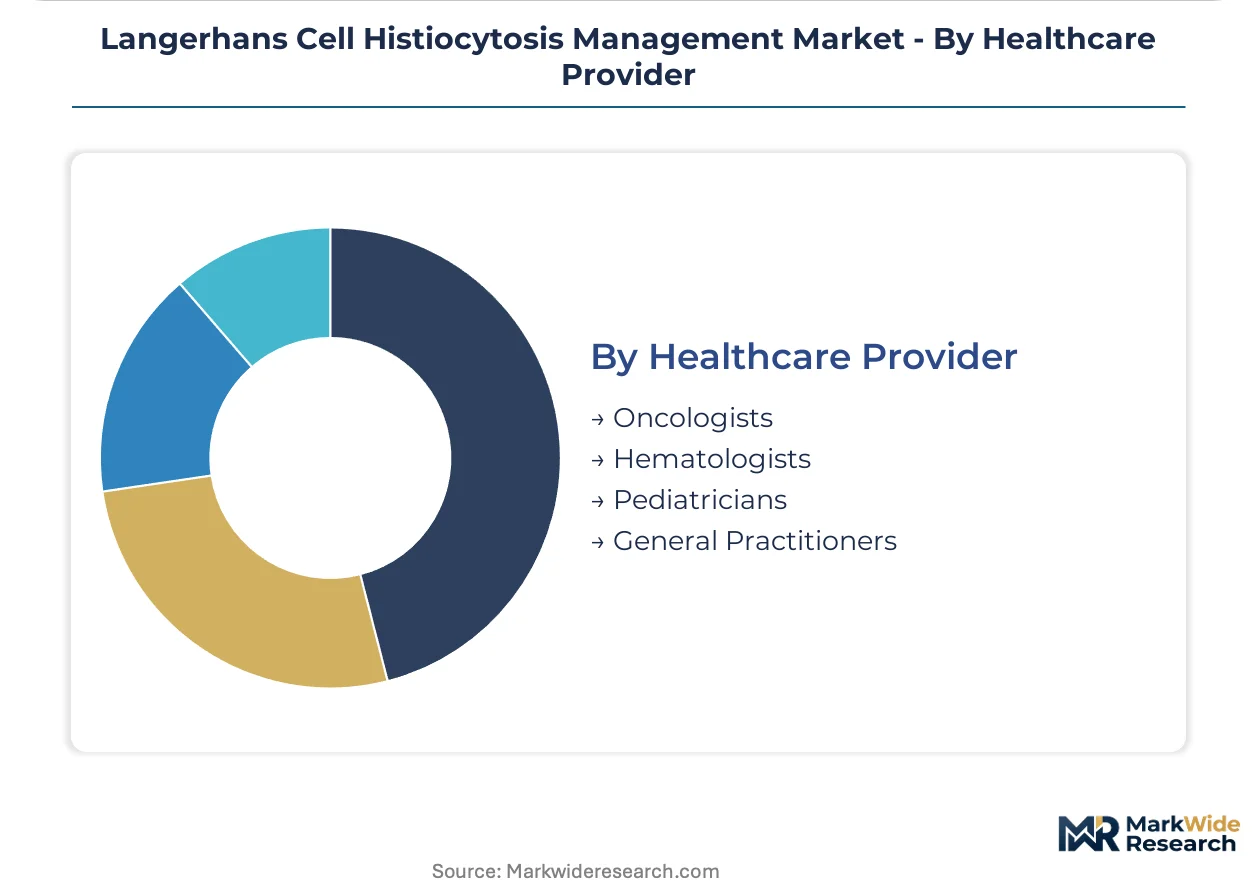
- Oncologists:Pediatric and medical oncologists direct risk-stratified therapy selection and clinical trial enrollment. Comprehensive cancer centers consolidate complex multisystem cases.
- Hematologists:Myeloid neoplasm expertise aligns with LCH clonal pathophysiology, particularly in adult-presenting cases. Academic centers integrate hematology-oncology joint management.
- Pediatricians:Primary care and subspecialty pediatricians frequently identify initial disease manifestations through skin or bone lesion evaluation. Referral activation to oncology determines diagnostic interval.
- General Practitioners:Adult primary care encounters often delay recognition of pulmonary or bone LCH due to nonspecific symptom overlap. Misdiagnosis extends time to definitive therapy.
Clinical volume concentrates with oncologists; hematology involvement is climbing fastest in adult referral networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for LCH management concentrates in the United States and Germany, where pediatric oncology referral networks and regulatory frameworks for rare disease therapeutics have matured fastest. Academic medical centers in both countries now mandate molecular profiling prior to therapy selection.
United States
FDA's Orphan Drug Designation program compresses development timelines for histiocytosis-directed agents, attracting biopharma investment toward accelerated approval pathways. Pediatric oncology consortia standardize enrollment in cooperative group trials across major referral networks. Boston and New York Metro academic centers anchor clinical trial access for BRAF inhibitor protocols.
Germany
Pediatric oncology centers in Bavaria and North Rhine-Westphalia are expanding adoption of targeted BRAF inhibitor protocols for multisystem disease. EMA's Priority Medicines scheme incentivizes trial site activation across academic networks. Heidelberg and Berlin-Brandenburg clusters concentrate histiocytosis-specific diagnostic expertise and pharmacovigilance reporting infrastructure.
France
ANSM mandates robust pharmacovigilance frameworks for ultra-rare indications, shaping post-authorization safety commitments for MEK inhibitors. The French national healthcare system reimburses molecular profiling for risk-stratified therapy selection. Paris and Lyon academic centers coordinate cross-border referral protocols for complex adult-presenting cases.
United Kingdom
NHS England's specialized commissioning framework consolidates LCH management within designated supraregional centers. The MHRA operates accelerated assessment pathways aligned with EMA Priority Medicines criteria. London and Manchester pediatric hematology-oncology units generate real-world evidence for targeted therapy outcomes.
Japan
PMDA's Sakigake designation system provides priority review for innovative therapies addressing unmet needs in pediatric rare diseases. Japanese academic medical centers participate in multinational trials for MAPK pathway inhibitors. Tokyo and Osaka clusters integrate liquid biopsy platforms for circulating tumor DNA monitoring.
Langerhans Cell Histiocytosis Management Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated biopharmas commanding premium positioning in targeted therapy while regional distributors handle conventional chemotherapy procurement. The vendor base organizes around three strategic archetypes: rare disease infrastructure owners, precision oncology investors, and cytokine pathway researchers. Consolidation pressures favor players with captive academic center relationships over standalone commercial operations. Dominant competitive moves include companion diagnostic partnerships and indication-based risk-sharing agreements with hospital pharmacy networks.
Among the integrated biopharma tier, Sanofi S.A., Eli Lilly and Company, and Regeneron Pharmaceuticals Inc. occupy positions defined by their respective infrastructure investments. Sanofi exemplifies the rare disease specialist archetype through its European academic network leverage. Eli Lilly represents precision oncology commitment via MAPK-driven malignancy programs. Regeneron anchors cytokine pathway research positioning. These three entities collectively illustrate how therapeutic platform choices determine formulary access in academic medical centers.
| Leading Market Players |
|---|
| Sanofi S.A. |
| Regeneron Pharmaceuticals Inc. |
| Innovent Biologics Inc. |
| Affimed GmbH |
| Eli Lilly and Company |
| Amgen Inc. |
| F. Hoffmann-La Roche Ltd |
| TG Therapeutics Inc. |
| AstraZeneca plc |
| Others |
Supply & Pricing Matrix
Fellowship-trained histopathologist scarcity in Heidelberg and Berlin-Brandenburg clusters widens labor-cost differentials between academic medical centers and community hospitals, compressing margin spreads across premium molecular-diagnostic tiers and economy chemotherapy protocols.
Pricing Analysis
Volume placements anchor in vinblastine-prednisone chemotherapy regimens with thin margins, while BRAF and MEK inhibitor protocols capture premium orphan-drug pricing in refractory segments. Price differentiation rests on molecular profiling certification tier and indication-based value frameworks negotiated with pediatric hospital pharmacy networks. Cost compression in first-line cytotoxic therapy intensifies as biosimilar pressure accumulates. Community hospital procurement committees exhibit highest price sensitivity; comprehensive cancer centers with captive specialty pharmacies demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and France maintain hub-and-spoke patterns for temperature-sensitive biologics with cold-chain requirements. Active pharmaceutical ingredient sourcing draws from Switzerland, Ireland, and Singapore for high-purity oncology inputs. Single-source vulnerability concentrates in BRAF inhibitor manufacturing where sole-supplier contracts dominate. Distribution runs through manufacturer-affiliated specialty pharmacy networks rather than traditional hospital wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
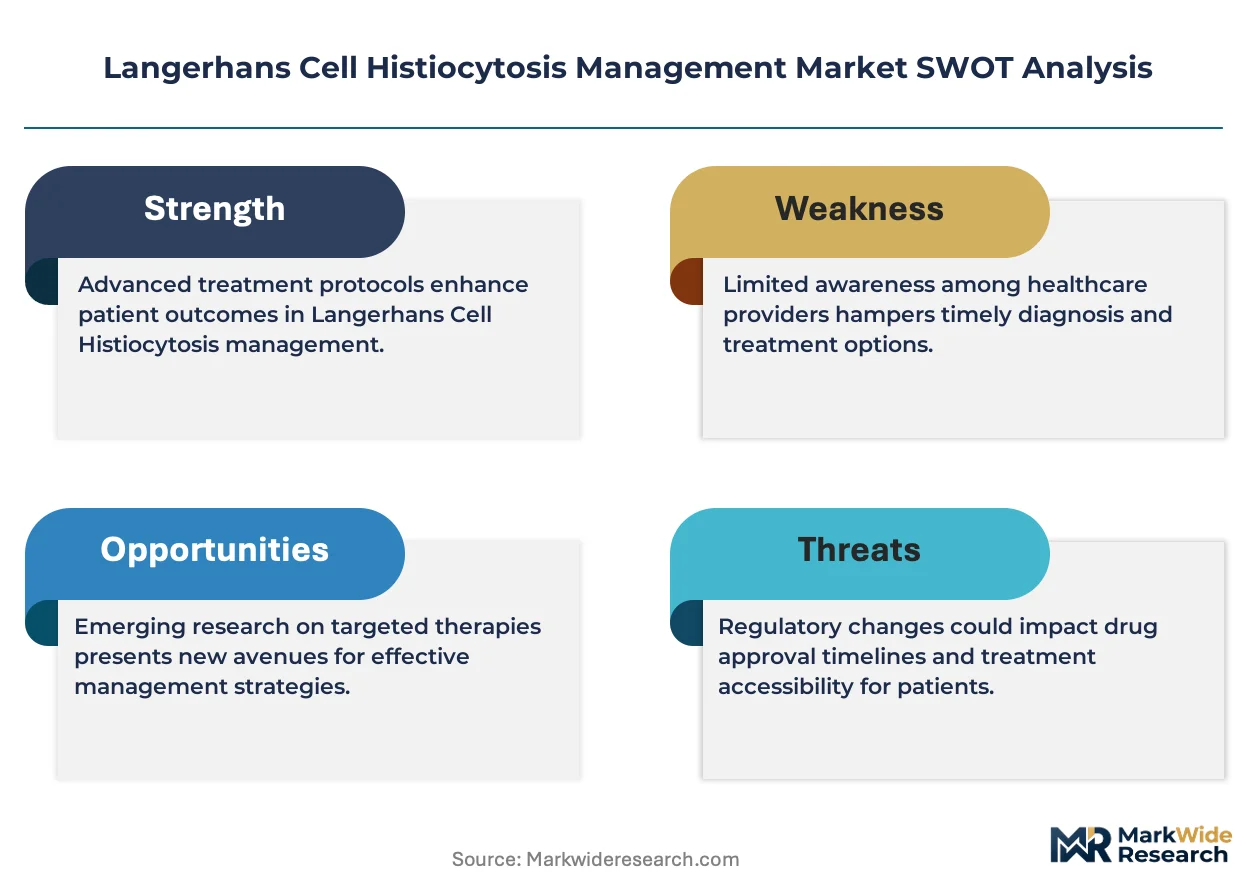
Ultra-rare trial recruitment bottlenecks and EMA pharmacovigilance mandates force consolidation among developers lacking captive academic center relationships, eliminating standalone commercial operators without rare disease infrastructure.
For Market Incumbents: Deepen companion diagnostic partnerships with liquid biopsy platform developers to secure preferential formulary positioning in molecular profiling-mandated centers. Expand pharmacovigilance reporting infrastructure across European academic networks to satisfy post-authorization safety commitments. Vertical integration into real-world evidence generation capabilities counters pricing pressure from indication-based value frameworks.
For New Entrants and Emerging Players: The premium-economy price-point gap in adult refractory pulmonary LCH presents white-space capture opportunity through sequential salvage regimen positioning. Target adult multisystem cases in United States specialized centers with disproportionate per-patient expenditure profiles. Pursue EMA Priority Medicines scheme alignment for accelerated assessment pathway access.
For Investors and Strategic Acquirers: Re-rating potential sits with rare disease infrastructure owners given FDA Orphan Drug Designation program compression of development timelines. Long-term viability favors developers with MAPK pathway biomarker-driven trial designs and academic medical center procurement relationships. Monitor liquid biopsy platform adoption curves as inflection indicator for targeted therapy penetration rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Partnership | Liquid biopsy platform integration enables real-time treatment response monitoring in BRAF-mutant cases. |
| Regulatory Approval Pathway | FDA accelerated approval and EMA Priority Medicines scheme access compresses histiocytosis-directed agent timelines. |
| Academic Network Expansion | Heidelberg and Berlin-Brandenburg cluster activation secures patient access for ultra-rare indication trials. |
| Pharmacovigilance Infrastructure | Centralized adverse event reporting satisfies post-authorization commitments for MEK inhibitor cardiac monitoring. |
| Specialty Pharmacy Integration | Direct manufacturer engagement through captive channels enables risk-sharing agreements with pediatric consortia. |
Research Methodology
FDA filings, EMA submission documents, and ClinicalTrials.gov records formed the secondary backbone, cross-referenced with formulary database audits and hospital procurement records. Primary interviews with pediatric oncology consortium directors, regulatory affairs leads, hospital pharmacy procurement managers, and payer access specialists validated quantitative assumptions. Bottom-up patient-volume modeling and top-down revenue triangulation anchored forecast construction.
Bottom-up segmentation by treatment type, patient age group, and distribution channel fed into analytical framework development across the projection horizon. Modeled dimensions encompassed risk-stratified therapy intensity, molecular profiling penetration, and regional regulatory cluster adoption curves. CAGRs derived from patient incidence extrapolation, pricing trajectory assumptions, and channel shift elasticity estimates. Forecast inputs incorporated BRAF V600E testing adoption rates and targeted therapy label expansion timelines.
Inputs from FDA and EMA regulatory databases were available through the study window; gaps in real-world evidence generation timelines for MEK inhibitor long-term toxicity introduce uncertainty bands around adult salvage regimen projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Myelofibrosis Treatment Market
Hematology
Patient Blood Management Market
Hematology
APAC Acute Myeloid Leukemia Treatment Market
Hematology
Graft vs Host Disease Market
Hematology
Paroxysmal Nocturnal Hemoglobinuria (PNH) Treatment Market
Hematology
AL Amyloidosis Therapeutics Market
Hematology
Single Blood Drop Analysis Market
Hematology
Hematologic Malignancies Market
Hematology
Hemostatic Spray Market
Hematology
Global Hodgkin Lymphoma Treatment Market
Hematology
Global Hematologic Malignancies Treatment Market
Hematology
Bleeding Disorders Therapeutics Market
Hematology
Hairy Cell Leukemia Treatment Market
Hematology
Sickle Cell Disease Market
Hematology
Venous Blood Collection Market
Hematology
Transfusion Dependent Thalassaemia Management Market