
 Impetigo Therapeutic Market | 2026-2036
Impetigo Therapeutic Market Size, Share, and Industry Trends Forecast 2026-2036
Impetigo Therapeutic Market Foresight
Single-source reliance on legacy topical antibiotic suppliers is recalibrating toward multi-source procurement as healthcare systems seek supply security. GlaxoSmithKline plc leverages its established dermatology infrastructure across developed markets. Pfizer Inc. anchors its position through manufacturing scale in systemic antibiotic production. Teva Pharmaceutical Industries Ltd. competes aggressively in generic oral antibiotic segments where price sensitivity dominates purchasing decisions.
Impetigo therapeutics comprise pharmaceutical agents designed to eradicate Staphylococcus aureus and Streptococcus pyogenes from superficial skin lesions, with topical mupirocin formulations typically containing two percent active concentration in polyethylene glycol ointment bases. These products serve primarily to prevent cellulitis progression and post-streptococcal glomerulonephritis in community and clinical settings. Topical antibiotics occupy the largest revenue pool due to first-line prescribing guidelines, while oral antibiotics capture faster volume expansion in recurrent or extensive infection cases. Pediatric patients concentrate disproportionate demand, with hospital settings and dermatology clinics representing the highest-margin delivery channels.
FDA standards for topical anti-infective efficacy endpoints shape clinical trial designs and label claims for US market entrants. EMA's MDR requirements for antimicrobial resistance surveillance increasingly influence post-market obligations for European suppliers. Health Canada and WHO prequalification pathways create parallel access tracks for emerging market procurement. Stakeholders must monitor evolving resistance surveillance data and regulatory pressure on antibiotic stewardship to align pipeline investments with sustainable demand.
Market Dynamics
Antibiotic stewardship mandates from FDA and EMA are compressing prescription volumes while forcing manufacturers toward narrow-spectrum formulations and resistance surveillance integration.
Growth Catalysts
- Staphylococcus aureus decolonization protocols:Hospital infection control programs now incorporate nasal mupirocin regimens for MRSA carriers, expanding therapeutic touchpoints beyond active infection treatment.
- EMA MDR post-market surveillance requirements:Mandatory antimicrobial resistance tracking creates recurring revenue streams for diagnostic-therapeutic bundled offerings across European dermatology networks.
- Pediatric urgent care expansion:Retail clinic chains in the United States deploy point-of-care bacterial diagnostics, accelerating appropriate topical prescribing for school-age populations.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production for mupirocin calcium clusters in Chinese chemical manufacturing zones, exposing formulators to export license volatility.
- Topical bioequivalence thresholds:FDA's stringent Q1/Q2 sameness requirements for generic ointments extend development timelines and elevate clinical pharmacology costs for abbreviated new drug applications.
- Phage therapy substitution pressure:Experimental bacteriophage cocktails targeting S. aureus biofilms attract venture funding, threatening long-term antibiotic maintenance indications in chronic wound settings.
Strategic Opportunities
- Indian primary care networks:Ayushman Bharat health insurance expansion creates reimbursement infrastructure for standardized impetigo treatment protocols in rural clinic settings.
- Telemedicine prescribing integration:Asynchronous dermatology platforms in Australia and Canada enable remote diagnosis with e-prescription fulfillment, bypassing traditional clinic density constraints.
- WHO prequalification pathway:Stringent quality benchmarks for tropical disease programs create procurement eligibility for topical anti-infectives in sub-Saharan African public health systems.
Industry Challenges
- Clinical microbiology workforce scarcity:Laboratory capacity for culture-based resistance surveillance strains under stewardship compliance burdens in community hospital systems.
- Legacy formulation compatibility:Polyethylene glycol ointment bases face stability conflicts with novel permeation enhancers, complicating line extension strategies.
- Pharmacovigilance signal detection:Post-market allergic contact dermatitis reporting requires rapid label revision cycles that strain regulatory affairs bandwidth at mid-size dermatology divisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Impetigo Therapeutic Market |
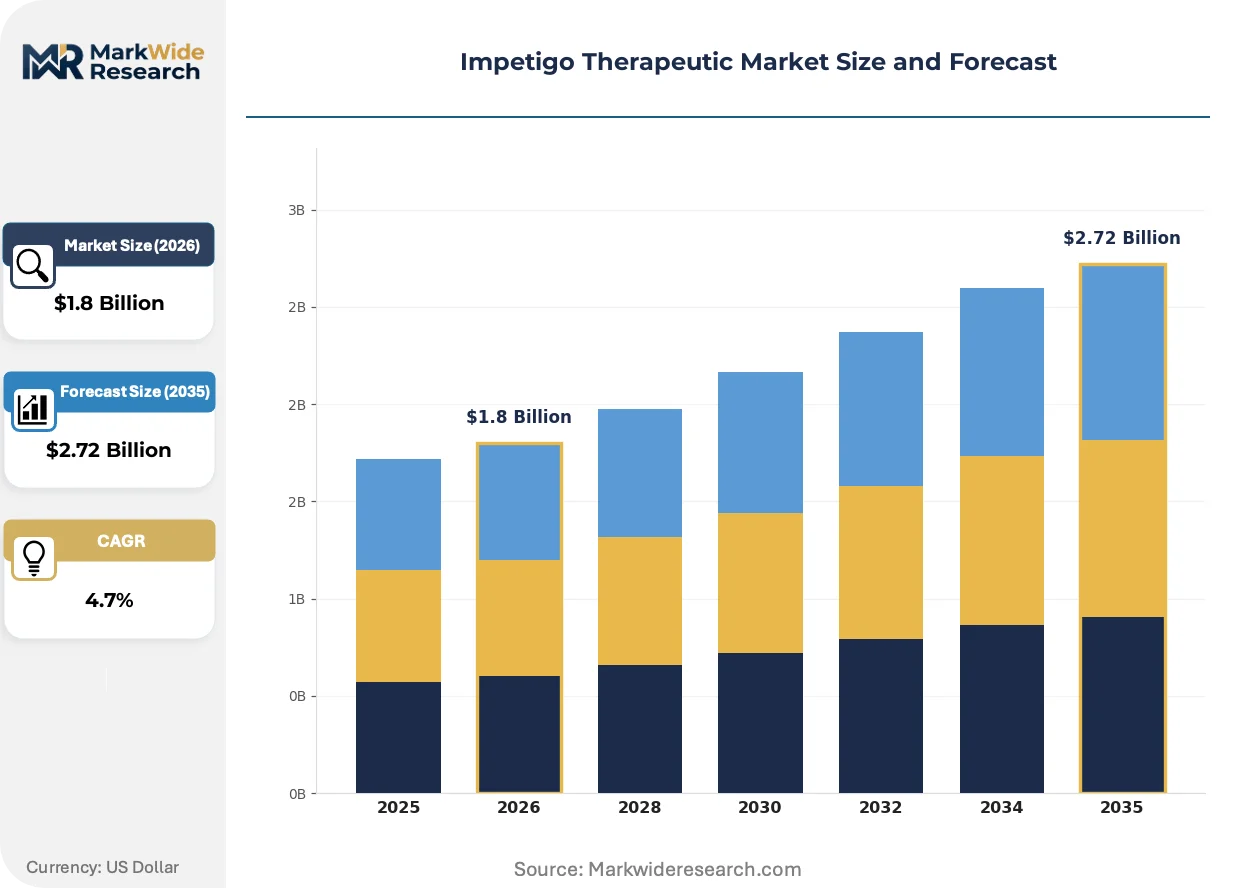
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Antibiotics, Oral Antibiotics, Antiseptics, Antiviral Agents Application: Hospital Settings, Home Care, Dermatology Clinics, Emergency Care Delivery Mode: Topical Application, Oral Administration, Intravenous Injection, Spray Formulation End User: Pediatric Patients, Adult Patients, Healthcare Providers, Caregivers |
| Companies Covered | GlaxoSmithKline plc, Pfizer Inc., Teva Pharmaceutical Industries Ltd., Novartis AG, Sun Pharmaceutical Industries Ltd., LEO Pharma A/S, NovaBay Pharmaceuticals Inc., Medimetriks Pharmaceuticals, Inc., Taro Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Impetigo Therapeutic Market Shifts & Advancements
Formulation science and diagnostic integration are compressing the gap between empirical and targeted therapy, reshaping how superficial skin infections enter clinical workflows.
Microbiome-sparing topical agents are integrating into development pipelines. These formulations selectively suppress pathogenic S. aureus while preserving commensal skin flora. Pediatric dermatology practices in the United States and Germany pilot these agents for recurrent impetigo populations. The technology is integrating into premium pricing tiers as differentiation from commodity mupirocin ointments.
FDA's 2023 guidance on topical anti-infective clinical endpoints now mandates quantified bacterial load reduction rather than lesion resolution alone. This elevates microbiological endpoint standards for abbreviated new drug applications. Generic sponsors must invest in culture-based efficacy trials, compressing the cost advantage traditionally held against innovator formulations.
Retail clinic prescribing networks now bypass traditional dermatology referral channels for uncomplicated superficial pyoderma. MinuteClinic and similar operators in the United States deploy algorithm-driven treatment protocols with automated prior authorization. This channel shift concentrates volume in high-throughput, low-margin settings while hospital outpatient departments retain complex or recurrent cases.
Impetigo Therapeutic Market Segmentation
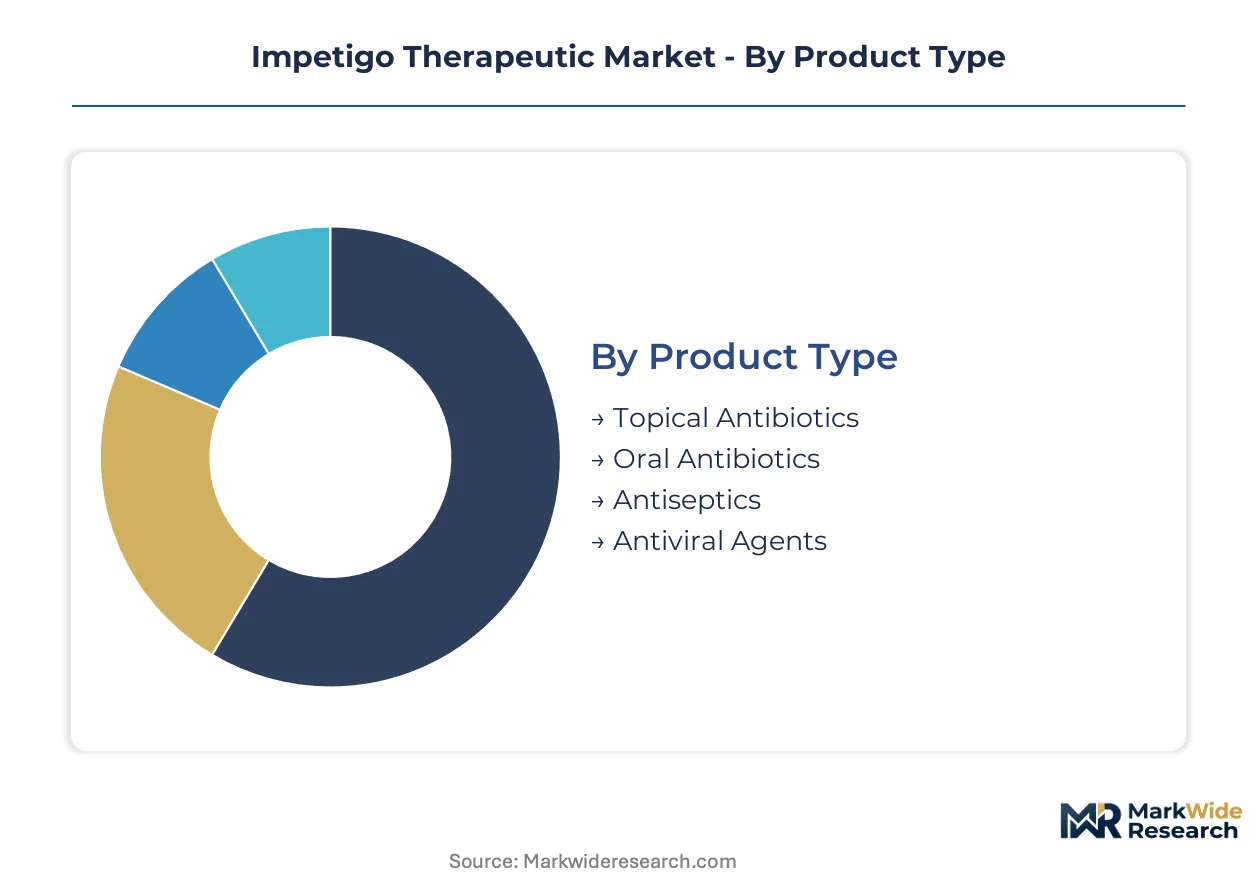
Impetigo therapeutics fragment across formulation science, care setting economics, and patient population vulnerability. Understanding these divisions exposes where pricing power concentrates and where volume expansion outpaces value growth.
Product Type:
Customization intensity varies sharply across this category, from commodity ointments to resistance-engineered systemic agents.
- Topical Antibiotics:Mupirocin calcium in polyethylene glycol bases dominates first-line prescribing. Hospital infection control programs in the United States drive volume through MRSA decolonization protocols, though FDA bioequivalence thresholds compress generic margins.
- Oral Antibiotics:Cephalexin and clindamycin formulations address recurrent or extensive infections. Pediatric urgent care expansion accelerates appropriate systemic prescribing when topical therapy fails.
- Antiseptics:Povidone-iodine and chlorhexidine preparations serve prophylactic and adjunctive roles. Limited reimbursement codes constrain revenue per unit in retail pharmacy channels.
- Antiviral Agents:Acyclovir and penciclovir creams address herpetic lesions mimicking impetigo. Misdiagnosis rates in primary care settings create off-label utilization patterns.
Most installed capacity flows through Topical Antibiotics. Expansion is steepest in Oral Antibiotics.
Application:
Margin structures diverge based on reimbursement complexity and clinical acuity requirements.
- Hospital Settings:Inpatient dermatology and infectious disease services manage complicated pyoderma with bundled diagnostic-therapeutic protocols. EMA MDR surveillance mandates create recurring compliance costs for European suppliers.
- Dermatology Clinics:Specialized practices command premium pricing for culture-directed therapy. Telemedicine platforms in Australia and Canada now capture uncomplicated cases through asynchronous consultation models.
- Home Care:Family-administered topical regimens minimize total cost of care. Caregiver education gaps in rural India limit protocol adherence despite Ayushman Bharat reimbursement infrastructure.
- Emergency Care:Triage-driven empirical prescribing dominates throughput. Antibiotic stewardship audits increasingly challenge unnecessary systemic antibiotic initiation.
Revenue per patient peaks in Dermatology Clinics. Volume expansion concentrates in Home Care.
Delivery Mode:
Patient compliance and pharmacokinetic requirements shape technology selection across age and severity spectrums.
- Topical Application:Ointment and cream vehicles enable localized drug deposition without systemic exposure. Polyethylene glycol base stability conflicts complicate line extension strategies for novel permeation enhancers.
- Oral Administration:Suspension and tablet formulations address extensive or recurrent disease. Palatability engineering for pediatric populations drives formulation differentiation investments.
- Intravenous Injection:Reserved for cellulitis progression or systemic toxicity. Hospital pharmacy and therapeutics committees increasingly restrict empiric IV antibiotic initiation.
- Spray Formulation:Aerosolized delivery targets large surface area involvement or patient mobility limitations. Limited commercial availability constrains adoption despite theoretical advantages.
Topical Application carries the highest patient-day volume. Oral Administration is gaining share fastest among delivery technologies.
End User:
Risk stratification and caregiver involvement create distinct service requirements across patient categories.
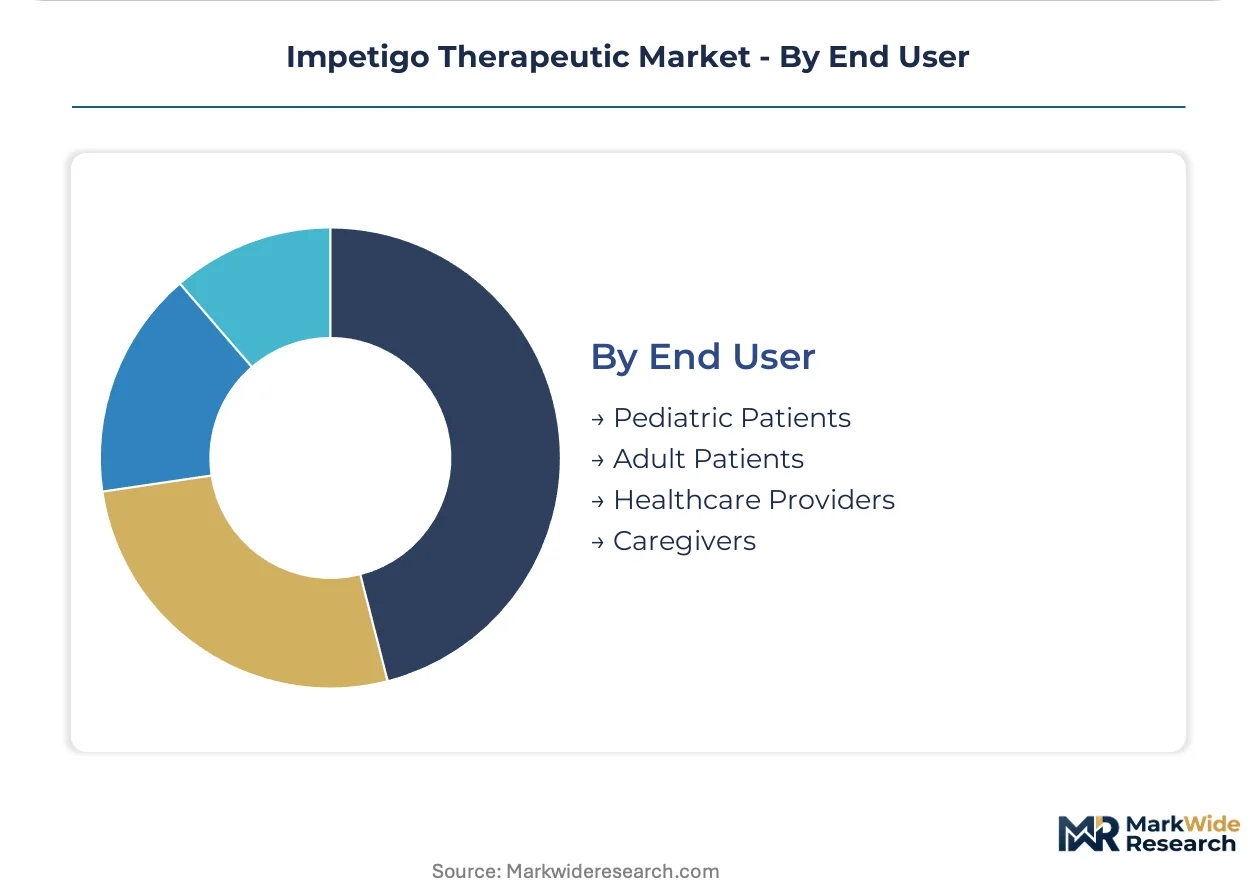
- Pediatric Patients:School-age populations concentrate disease burden and transmission risk. Retail clinic chains in the United States deploy point-of-care diagnostics to accelerate appropriate prescribing.
- Adult Patients:Occupational exposure and comorbid skin conditions drive incidence in agricultural and healthcare worker populations. Diabetic foot protocols in Germany integrate impetigo surveillance into chronic wound management.
- Healthcare Providers:Institutional procurement decisions balance acquisition cost against resistance surveillance obligations. Clinical microbiology workforce scarcity strains stewardship compliance in community hospital systems.
- Caregivers:Family members administer majority of topical regimens in home settings. Training material localization requirements complicate standardized protocol deployment in multilingual markets.
Pediatric Patients generate the highest episode frequency. Adult Patients show the steepest expansion trajectory as occupational health screening intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing manufacturing footprints as producers seek jurisdictions with streamlined antibiotic approval pathways and lower post-market surveillance burdens. Cost-of-compliance gaps between mature and emerging regulatory regimes are accelerating API sourcing diversification away from single-country dependencies.
United States
High dermatology clinic density and established reimbursement pathways concentrate demand for topical mupirocin formulations. FDA's evolving guidance on topical antibiotic bioequivalence shapes generic development timelines. Hospital infection control programs in the Southeast deploy MRSA decolonization protocols at scale.
Germany
Diabetic foot protocols integrate impetigo surveillance into chronic wound management across Bavarian hospital networks. EMA MDR requirements for antimicrobial resistance surveillance create recurring compliance obligations for European suppliers. Baden-Württemberg hosts specialized dermatology research clusters advancing microbiome-sparing formulations.
India
Ayushman Bharat health insurance expansion creates reimbursement infrastructure for standardized treatment protocols in rural Maharashtra and Gujarat. CDSCO's streamlined approval tracks for essential medicines accelerate market entry for domestic manufacturers. Hyderabad- and Ahmedabad-based API producers supply mupirocin calcium to global formulators.
Australia
Asynchronous dermatology platforms enable remote diagnosis with e-prescription fulfillment, bypassing traditional clinic density constraints in Queensland and Western Australia. TGA's alignment with FDA bioequivalence standards reduces regulatory duplication for sponsors. Sydney and Melbourne anchor telemedicine prescribing network expansion.
China
Active pharmaceutical ingredient production for mupirocin calcium clusters in Zhejiang and Jiangsu chemical manufacturing zones. NMPA's priority review pathways for anti-infectives attract multinational licensing activity. Export license volatility from these coastal provinces exposes formulators to supply interruption risks.
Impetigo Therapeutic Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue microbiome-sparing and resistance-engineered adjacents. The vendor base stratifies across multinational innovators with dermatology infrastructure, generic specialists with manufacturing scale, and mid-size players with regional distribution depth. Three archetypes dominate: integrated pharmaceutical conglomerates with stewardship compliance capabilities, API-forward formulators with vertical cost control, and niche dermatology divisions with pediatric positioning. Competitive moves concentrate on M&A for resistance surveillance technology and capacity expansion into prequalified supply chains for emerging market procurement.
Within the integrated conglomerate tier, GlaxoSmithKline plc and Pfizer Inc. exemplify archetypes leveraging established regulatory affairs bandwidth and manufacturing scale across developed markets. Teva Pharmaceutical Industries Ltd. occupies a position representing generic specialists competing aggressively in price-sensitive oral antibiotic segments. These three anchors illustrate how competitive positioning diverges between innovation-driven and cost-optimized vectors.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Novartis AG |
| Sun Pharmaceutical Industries Ltd. |
| LEO Pharma A/S |
| NovaBay Pharmaceuticals Inc. |
| Medimetriks Pharmaceuticals, Inc. |
| Taro Pharmaceutical Industries Ltd. |
| Others |
Supply & Pricing Matrix
Commodity-generic and microbiome-sparing formulation tiers diverge sharply in both pricing power and sourcing architecture, with the former anchored in high-volume Chinese API contracts and the latter drawing from specialized German and Swiss fermentation facilities under EMA MDR compliance obligations.
Pricing Analysis
Distributor margins on topical mupirocin formulations compress under generic substitution pressure in United States retail pharmacy chains, while dermatology clinics capture premium spreads on culture-directed therapy bundles. Three-tier pricing structure across premium, standard, and economy levels reflects FDA bioequivalence certification status, with Q1/Q2 sameness thresholds acting as the primary quality-grade delimiter. Pricing pressure stems from retail clinic algorithm-driven protocols that standardize empirical prescribing around lowest-acquisition-cost options. Hospital procurement committees show least price sensitivity due to bundled diagnostic-therapeutic reimbursement codes, whereas independent pharmacies face maximum margin compression.
Supply Chain Analysis
Mupirocin calcium API production rests on Zhejiang and Jiangsu chemical manufacturing zones in China, with secondary fermentation capacity concentrated in Hyderabad and Ahmedabad, India. Polyethylene glycol ointment bases and specialized permeation enhancers draw from German specialty chemical producers and Indian excipient manufacturers. Single-source vulnerability in Chinese coastal export licensing exposes formulators to supply interruption during regulatory enforcement cycles. Distribution runs through three-tier wholesaler networks in developed markets and direct government procurement channels in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with pediatric dermatology practices in Germany and the United States shifting procurement toward microbiome-sparing agents that command sustainable premium positioning.
For Market Incumbents: Hedge against phage therapy substitution by securing resistance surveillance data partnerships with European hospital networks under EMA MDR mandates. Prioritize backward integration into Indian API production to offset Chinese export license volatility. Lock in long-term supply agreements with polyethylene glycol base suppliers before novel permeation enhancer compatibility conflicts escalate. For New Entrants and Emerging Players: Microbiome-sparing topical formulations offer the clearest technology-first wedge for premium positioning against commodity mupirocin. Target Australian asynchronous dermatology platforms and Indian Ayushman Bharat rural clinic networks as the most penetrable channels. Lead with telemedicine-integrated diagnostic-therapeutic bundles that bypass traditional clinic density constraints. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-size dermatology divisions possessing pediatric positioning and FDA regulatory affairs bandwidth. Five-to-ten year viability hinges on stewardship compliance capabilities rather than manufacturing scale alone. Watch for inflection signals in venture funding flows toward bacteriophage wound care platforms.| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Compliance Investment | Creates recurring revenue streams through mandatory antimicrobial resistance surveillance across European dermatology networks. |
| Microbiome-Sparing Formulation Development | Captures premium pricing tiers in German and United States pediatric practices seeking commensal flora preservation. |
| Indian API Manufacturing Scale-Up | Reduces single-country dependency on Chinese mupirocin calcium production clusters in Zhejiang province. |
| Telemedicine Prescribing Integration | Enables volume capture in Australian and Canadian markets with asynchronous dermatology platform partnerships. |
| WHO Prequalification Pathway Entry | Unlocks procurement eligibility for sub-Saharan African public health systems with stringent quality benchmarks. |
Research Methodology
Coverage spans the United States, Germany, India, Australia, and China, with primary inputs from each market cluster combined with secondary validation. Interviews with dermatology formulary directors, hospital infection control officers, regulatory affairs leads at topical antibiotic manufacturers, and retail clinic procurement managers informed demand-side assumptions. Secondary sources include FDA bioequivalence guidance documents, EMA MDR surveillance requirements, CDSCO approval tracks, ClinicalTrials.gov endpoint designs, and hospital procurement database extracts. Bottom-up patient-volume estimates triangulate against top-down pharmaceutical expenditure data.
Granularity-level modeling disaggregates revenue across product type, application setting, delivery mode, and end-user population, with regional regulatory clusters treated as distinct forecast dimensions. CAGRs derive from segment-specific volume trajectories and pricing elasticity assumptions across the projection horizon. Treatment line positioning, culture-based versus empirical prescribing ratios, and pediatric versus adult episode frequency serve as industry-specific forecast inputs.
The model holds under stable antibiotic stewardship enforcement and continued FDA bioequivalence threshold consistency; deviation in phage therapy clinical trial outcomes or Chinese API export restriction intensity would shift volume and value projections. A small set of named triggers—venture funding flows into bacteriophage platforms, EMA MDR audit enforcement patterns, and Indian PLI scheme pharmaceutical manufacturing incentives—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
United States Specialty Generics Market
Specialty Medicine
Radiation Toxicity Treatment Market
Specialty Medicine
Hypoactive Sexual Desire Disorder Treatment Market
Specialty Medicine
Gouty Arthritis Market
Specialty Medicine
Global Tourette Syndrome Treatment Market
Specialty Medicine
Primary Biliary Cholangitis (PBC) Treatment Market
Specialty Medicine
Middle East and Africa Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Toxoplasmosis Treatment Market
Specialty Medicine
Endometrial Cancer Treatment Market
Specialty Medicine
China Ulcerative Colitis Market
Specialty Medicine
Ankylosing Spondylitis Treatment Market
Specialty Medicine
Global Chronic Lymphocytic Leukemia Treatment Market
Specialty Medicine
Cat Scratch Disease (CSD) Treatment Market
Specialty Medicine
Amyotrophic Lateral Sclerosis (ALS) Market
Specialty Medicine
Tinea Corporis Market
Specialty Medicine
Global Attention Deficit Hyperactivity Disorder Market