
 Global Hematopoietic Stem Cell Transplantation Market | 2026-2036
Global Hematopoietic Stem Cell Transplantation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hematopoietic Stem Cell Transplantation Market Foresight
Project finance for dedicated cell therapy manufacturing facilities is narrowing the competitive field to well-capitalized operators. Lonza Group leverages its global CDMO infrastructure to sustain long-term supply agreements with gene therapy developers. Novartis anchors its position through in-house production of CAR-T platforms and related transplant support services. Merck KGaA differentiates via specialized media and reagent portfolios that feed into clinical and commercial workflows.
Hematopoietic stem cell transplantation encompasses the infusion of multipotent progenitor cells derived from bone marrow, peripheral blood, or umbilical cord blood to reconstitute hematopoietic function after myeloablative conditioning. The procedure requires human leukocyte antigen matching, cryopreservation protocols, and post-transplant immunosuppression to engraft donor cells and prevent graft-versus-host disease. Allogeneic transplants command the largest share of clinical activity due to curative potential in hematologic malignancies, while haploidentical protocols represent the fastest-expanding category as post-transplant cyclophosphamide regimens broaden donor pools. Umbilical cord blood sourcing retains structural importance for pediatric indications and ethnic minority patients lacking matched adult donors.
FDA's regenerative medicine advanced therapy designation and EMA's priority medicines pathway accelerate review timelines for novel transplant adjuncts and cell processing technologies. Japan's PMDA operates a conditional early approval system for regenerative products that shapes commercial launch sequencing across Asia-Pacific. Stakeholders must monitor evolving reimbursement frameworks for outpatient transplant management and decide on manufacturing scale commitments before payer evidence requirements harden.
Market Dynamics
Post-transplant cyclophosphamide regimens are collapsing the traditional HLA-matching barrier, enabling haploidentical donor expansion and reshaping donor pool economics across transplant networks.
Growth Catalysts
- FDA Regenerative Medicine Advanced Therapy designation:The expedited review pathway compresses development timelines for novel cell processing technologies, accelerating commercial access for transplant adjuncts.
- Leukemia and lymphoma caseload concentration:Academic medical centers in the United States, Germany, and Japan are expanding dedicated transplant programs to address rising hematologic malignancy volumes.
- Cryopreservation protocol advances:Improved dimethyl sulfoxide-free solutions and automated controlled-rate freezing are extending viable cell storage windows and reducing infusion-related toxicities.
Market Restraints
- Donor cell supply concentration:Matched unrelated donor registries concentrate in North American and European tissue-typing networks, limiting access for ethnic minority populations in Asia-Pacific and Middle East markets.
- Myeloablative conditioning toxicity:High-dose chemotherapy and total body irradiation protocols impose organ damage risks that exclude frail patients and compress the addressable patient pool.
- Graft-versus-host disease prophylaxis costs:Extended immunosuppression with tacrolimus, methotrexate, and emerging JAK inhibitors creates substantial post-transplant pharmacy expenditure burdens.
Strategic Opportunities
- India's emerging transplant infrastructure:Private hospital chains in Mumbai, Delhi, and Chennai are building dedicated cellular therapy units to capture outbound medical travel from South Asia and Africa.
- Outpatient transplant management:Ambulatory care models for autologous transplantation are reducing inpatient bed days and opening reimbursement negotiations with Medicare Advantage and commercial payers.
- Gene editing convergence:CRISPR-mediated HLA engineering of donor stem cells promises universal off-the-shelf products, collapsing donor search timelines and matching complexity.
Industry Challenges
- Cell therapy manufacturing workforce scarcity:Qualified aseptic processing technicians and quality control specialists command premium compensation, constraining facility expansion timelines.
- Cross-border cryogenic logistics:Dry shipper validation, customs clearance for biological specimens, and chain-of-custody documentation create friction in international donor cell transport.
- Real-world evidence generation:Payer demands for long-term graft-versus-host disease and relapse outcome data extend post-approval study commitments and inflate pharmacovigilance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hematopoietic Stem Cell Transplantation Market |
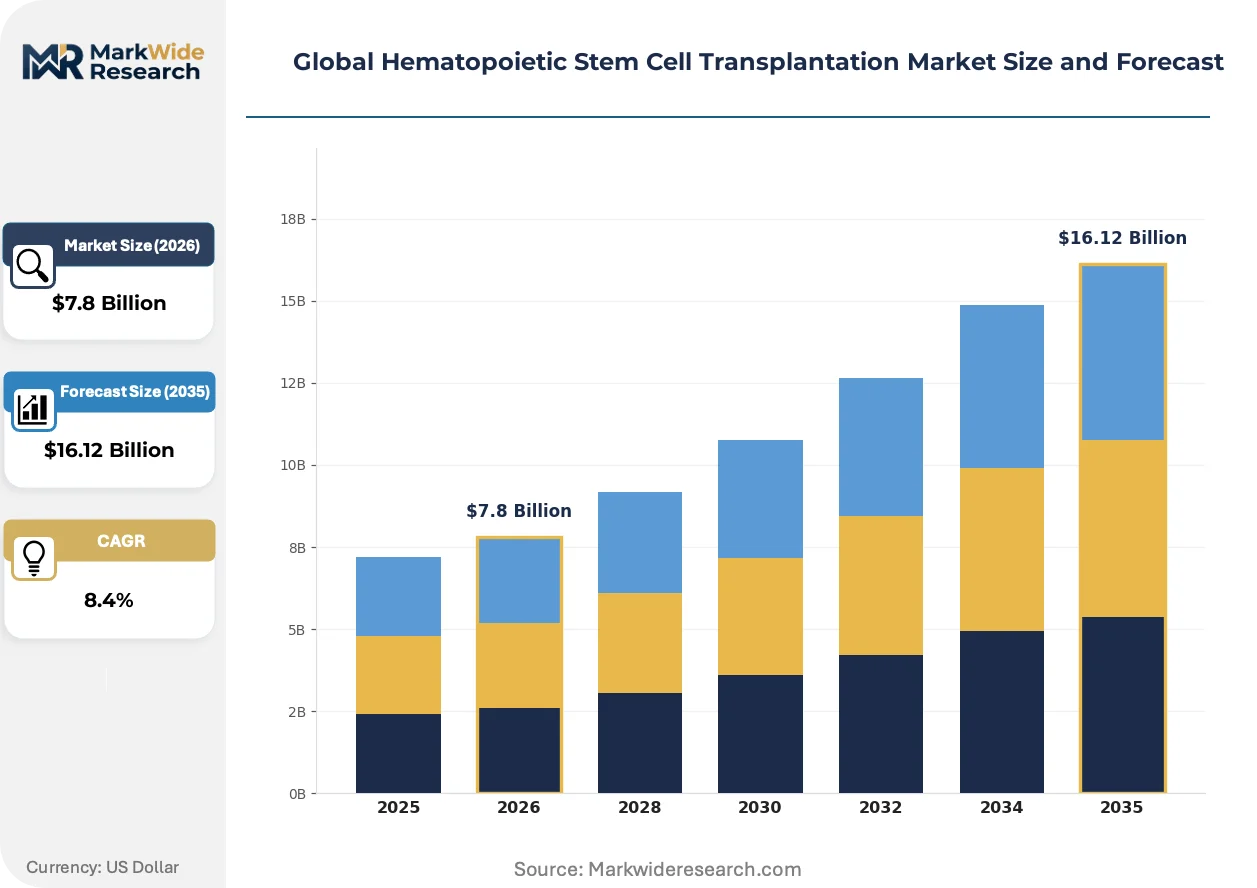
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transplant Type: Autologous, Allogeneic, Syngeneic, Haploidentical Source Cell Type: Bone Marrow, Peripheral Blood, Umbilical Cord Blood, Induced Pluripotent Stem Cells Indication: Leukemia, Lymphoma, Multiple Myeloma, Aplastic Anemia, Myelodysplastic Syndromes Recipient Age Group: Paediatric, Adult, Geriatric, Adolescent |
| Companies Covered | Merck KGaA, Lonza Group, Stemcell Technologies, Novartis, Takeda Pharmaceutical Company Limited, Sanofi, Bluebird Bio, Pluristem Therapeutics, CellGenix GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hematopoietic Stem Cell Transplantation Market Shifts & Advancements
Cell processing automation and point-of-care manufacturing are compressing production timelines and relocating value capture from centralized facilities toward transplant centers themselves.
Microfluidic cell selection platforms are collapsing the labor intensity and contamination risk of traditional density-gradient separation and magnetic bead protocols. Transplant centers in the Netherlands and Singapore are piloting closed-system devices that reduce cleanroom footprint and operator dependence. This automation is collapsing the cost structure of graft engineering and enabling same-day processing workflows.
EMA's priority medicines pathway is compressing review timelines for advanced therapy medicinal products, with recent designations covering ex vivo expanded cord blood units and T-cell receptor engineering platforms. The industrial consequence is earlier revenue recognition for developers willing to commit to conditional approval frameworks. Pediatric oncology indications in France, Italy, and Spain are responding fastest, leveraging hospital exemption provisions for compassionate use.
Buyer concentration among integrated delivery networks is consolidating procurement leverage and unbundling traditional device-reagent-service bundles. Major hospital systems in Texas, California, and Pennsylvania are negotiating direct sourcing agreements with media manufacturers, bypassing historical distributor markups. This channel disintermediation is most visible in autologous transplantation programs where volume thresholds justify captive supply chain investment.
Global Hematopoietic Stem Cell Transplantation Market Segmentation
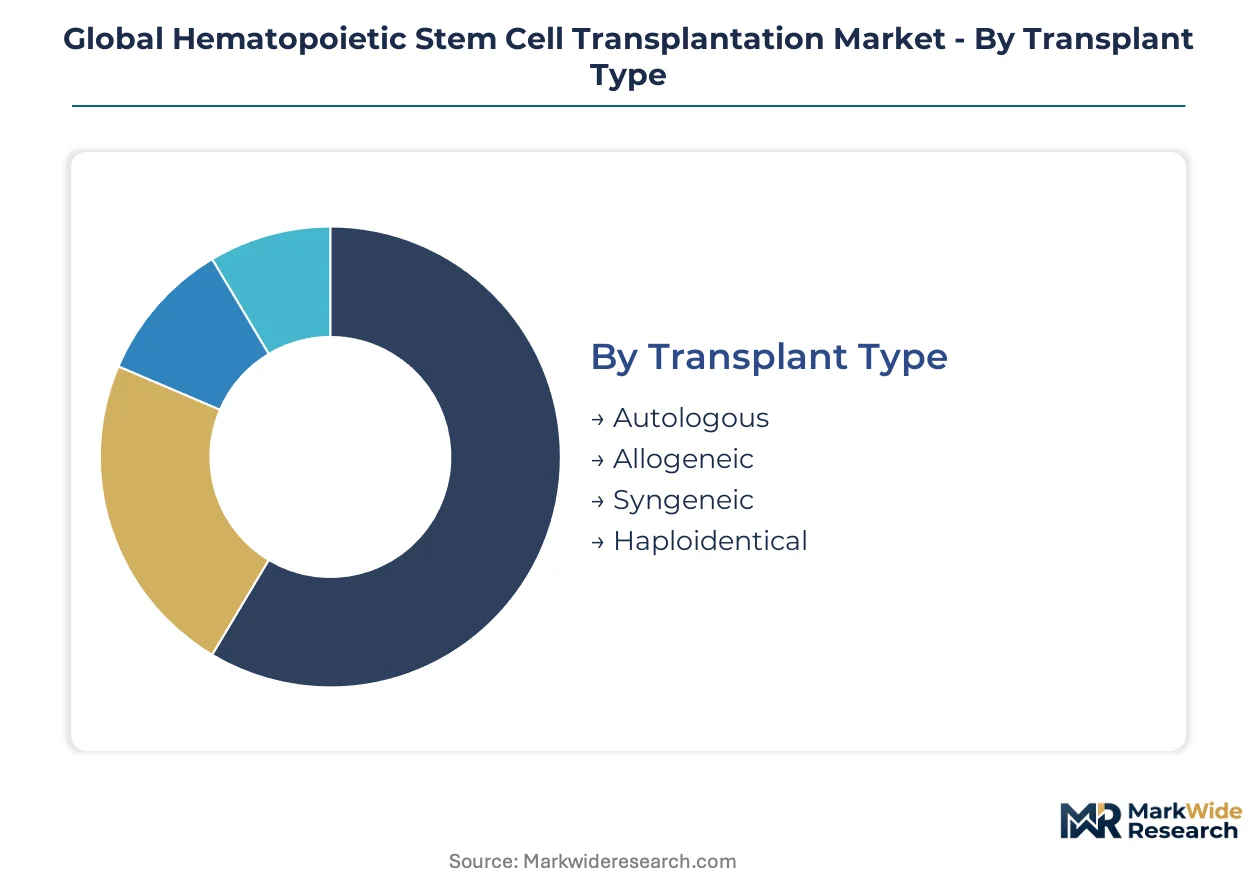
Market segmentation in hematopoietic stem cell transplantation reveals distinct clinical workflows, donor logistics, and reimbursement pathways. Each dimension shapes facility investment priorities and supply chain configuration decisions.
Transplant Type:
Application focus determines conditioning intensity, donor matching requirements, and post-transplant care protocols across transplant networks.
- Allogeneic:Donor-derived stem cells from matched related or unrelated donors enable graft-versus-tumor effects in hematologic malignancies. Academic medical centers in the United States, Germany, and Japan concentrate procedure volume due to complex HLA-matching infrastructure and dedicated graft-versus-host disease management programs.
- Haploidentical:Half-matched family donors combined with post-transplant cyclophosphamide regimens collapse traditional matching barriers. Demand accelerates fastest in India and Brazil where unrelated donor registry penetration remains limited and family-directed donation dominates clinical practice.
- Autologous:Patient-derived cell reinfusion after high-dose chemotherapy eliminates graft-versus-host disease risk entirely. Multiple myeloma and lymphoma protocols drive volume in outpatient-capable centers.
- Syngeneic:Identical twin donation offers immunological perfection without conditioning toxicity. Ultra-rare indication limited to specific congenital disorders and research protocols.
Allogeneic procedures command the established base. The steepest expansion runs through haploidentical protocols.
Source Cell Type:
Cell origin shapes collection logistics, processing complexity, and engraftment kinetics in clinical workflows.
- Peripheral Blood:Granulocyte colony-stimulating factor mobilization yields higher CD34+ cell doses than bone marrow harvest. Adult transplantation programs in the United States and Germany prefer this source for faster neutrophil recovery and reduced procedural morbidity.
- Bone Marrow:Direct harvest from iliac crest under anesthesia preserves stem cell quiescence and reduces chronic graft-versus-host disease incidence. Pediatric centers and specific leukemia protocols maintain preference for this traditional source.
- Umbilical Cord Blood:Cryopreserved allografts from public and private banks enable rapid deployment without full HLA matching. Ethnic minority patients in the United Kingdom and France benefit from expanded inventory access.
- Induced Pluripotent Stem Cells:Laboratory-derived pluripotent cells promise unlimited autologous supply after genetic correction. Early clinical translation concentrates in Japan under PMDA conditional approval frameworks.
Peripheral blood collections dominate current volume. The steepest expansion trajectory belongs to induced pluripotent stem cell platforms.
Indication:
Disease biology determines transplant timing, conditioning intensity, and post-procedure surveillance requirements.
- Leukemia:Acute myeloid and lymphoblastic variants constitute the foundational indication for allogeneic transplantation. Academic networks in the United States and Germany maintain highest procedure density for high-risk and relapsed cases.
- Multiple Myeloma:Autologous stem cell rescue following proteasome inhibitor and immunomodulatory therapy sequences extends survival in eligible patients. Outpatient-capable centers in California and Texas drive volume growth through reduced-length-of-stay protocols.
- Lymphoma:Hodgkin and aggressive non-Hodgkin subtypes respond to both autologous and allogeneic approaches depending on chemosensitivity and prior therapy exposure.
- Aplastic Anemia:Immune-mediated bone marrow failure requires allogeneic rescue with reduced-intensity conditioning to minimize organ toxicity in younger patients.
- Myelodysplastic Syndromes:Clonal hematopoietic disorders with progression risk to acute leukemia drive early transplantation in fit patients with matched donors.
Leukemia indications anchor the established clinical base. Multiple myeloma autologous protocols are gaining share fastest.
Recipient Age Group:
Patient physiology dictates conditioning tolerance, donor selection flexibility, and supportive care intensity.
- Adult:Patients aged 18-65 years constitute the procedural volume core with established performance status criteria and standard conditioning regimens. Transplant centers in Pennsylvania and North Carolina concentrate this demographic through insurance network density.
- Paediatric:Congenital immunodeficiencies, inherited metabolic disorders, and high-risk leukemia drive specialized pediatric programs. Dedicated units in Boston and London maintain distinct regulatory frameworks and family-centered care models.
- Geriatric:Patients over 65 years increasingly qualify through reduced-intensity conditioning and comorbidity scoring tools. Medicare Advantage penetration in Florida and Arizona shapes reimbursement access.
- Adolescent:Transitional age patients require coordinated pediatric-to-adult program handoffs and distinct psychosocial support structures.
Adult recipients command the established base. Geriatric qualification expansion represents the steepest growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell therapy logistics favor jurisdictions with dense referral networks and established cryogenic transport corridors. The United States, Germany, and Japan maintain net export positions in donor cell sourcing and processing technologies, while India and Brazil import expertise through outbound medical travel and training partnerships.
United States
Academic medical centers in Boston, Houston, and Seattle drive procedure volume through National Marrow Donor Program infrastructure. FDA's Regenerative Medicine Advanced Therapy designation compresses review timelines for novel transplant adjuncts. The National Institutes of Health funds graft-versus-host disease consortia that anchor clinical trial activity in Maryland and North Carolina.
Germany
DKMS and other tissue-typing networks concentrate unrelated donor registries in Leipzig and Tübingen, facilitating rapid HLA matching across European transplant networks. EMA's priority medicines pathway accelerates commercial access for ex vivo expanded cell products. The Heidelberg-Mannheim corridor hosts specialized leukemia protocols that draw cross-border patient referrals.
Japan
PMDA's conditional early approval system for regenerative products shapes commercial launch sequencing across Asia-Pacific markets. Tokyo and Osaka transplant centers leverage public cord blood bank inventory for ethnic minority patients lacking matched adult donors. METI funding supports induced pluripotent stem cell manufacturing scale-up in Kobe and Kyoto.
India
Private hospital chains in Mumbai, Delhi, and Chennai build dedicated cellular therapy units to capture outbound medical travel from Bangladesh, Nigeria, and Afghanistan. The country's national pharmaceutical regulator streamlines import licensing for cryopreserved donor units. Tata Memorial Centre and All India Institute of Medical Sciences anchor haploidentical protocol training for South Asian transplant networks.
Brazil
Family-directed donation dominates clinical practice where unrelated donor registry penetration remains limited. ANVISA oversees conditional approval frameworks for advanced cell therapies that reference EMA and FDA precedent. São Paulo and Rio de Janeiro transplant centers participate in Latin American cooperative groups for post-transplant cyclophosphamide regimen validation.
Global Hematopoietic Stem Cell Transplantation Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: diversified pharmaceutical conglomerates with captive cell therapy manufacturing, specialized contract development and manufacturing organizations with global cold-chain infrastructure, and focused reagent and media suppliers that feed into clinical workflows. Competitive positioning depends on securing long-term supply agreements with academic medical centers and gene therapy developers before payer evidence requirements harden. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players racing to lock in GMP facility slots and donor registry network access.
Within the diversified pharmaceutical tier, Novartis and Takeda Pharmaceutical Company Limited exemplify integrated operators that combine in-house production with transplant support services. Among specialized manufacturing infrastructure providers, Lonza Group anchors global CDMO positioning through multi-continent facility networks. Merck KGaA occupies a distinct position in the reagent and media segment, supplying the specialized consumables that underpin clinical and commercial processing workflows. These three archetypes represent the structural fault lines around which competitive dynamics organize.
| Leading Market Players |
|---|
| Merck KGaA |
| Lonza Group |
| Stemcell Technologies |
| Novartis |
| Takeda Pharmaceutical Company Limited |
| Sanofi |
| Bluebird Bio |
| Pluristem Therapeutics |
| CellGenix GmbH |
| Others |
Supply & Pricing Matrix
Single-source dependency on cryopreserved cord blood inventories from North American and European public banks determines both pricing tier spreads and supply chain shape in hematopoietic stem cell transplantation. Regulatory chokepoints at FDA and EMA for donor cell import licensing compress margins for transplant centers in India and Brazil while amplifying price premiums for expedited HLA-matched units.
Pricing Analysis
Academic medical center buyers anchor a contract-based pricing structure tied to per-procedure allograft sourcing and long-term post-transplant pharmacy management. Price differentiation rests on HLA matching precision, cryopreservation protocol certification, and bundled graft-versus-host disease prophylaxis services. Cost compression in haploidentical protocols is intensifying as post-transplant cyclophosphamide regimens reduce dependency on matched unrelated donor searches. Community hospital systems exhibit highest price sensitivity due to limited transplant volume and payer negotiation leverage, while integrated delivery networks command volume discounts through direct media sourcing agreements.
Supply Chain Analysis
Lonza Group and specialized CDMOs hold captive capacity for clinical-grade cell processing and cryogenic logistics across Switzerland, United States, and Singapore manufacturing nodes. Raw material dependencies center on GMP-grade cytokines, dimethyl sulfoxide-free cryopreservation media, and validated dry shipper hardware. Single-source vulnerability concentrates in qualified aseptic processing technician pools, where workforce scarcity constrains facility expansion timelines. Distribution runs through National Marrow Donor Program infrastructure and cross-border cryogenic transport corridors linking donor registries to transplant centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Post-transplant immunosuppression management and outpatient graft monitoring represent service-attach layers expanding faster than allograft sourcing revenue across transplant networks. These recurring clinical touchpoints command higher margin stability than one-time cell procurement.
For Market Incumbents: Harden supply chain resilience through backward integration into cryopreservation media manufacturing and captive quality control laboratory networks. Defend against emerging point-of-care cell processing device entrants by locking exclusive service agreements with high-volume academic medical centers. Priority investment in automated closed-system platforms reduces cleanroom footprint dependence and operator labor intensity. For New Entrants and Emerging Players: Pursue white-space positioning in haploidentical protocol training and graft engineering services for private hospital chains in Mumbai, Delhi, and Chennai. India's outbound medical travel capture from Bangladesh and Nigeria offers the most penetrable geographic entry point. Go-to-market angle centers on turnkey cellular therapy unit design bundled with staff credentialing programs. For Investors and Strategic Acquirers: The market sits at a manufacturing scale-up phase that favors CDMOs with validated cold-chain infrastructure and long-term gene therapy developer contracts. Long-term viability over the coming decade hinges on CRISPR-mediated HLA engineering platforms achieving clinical translation. Signal to watch is PMDA conditional approval expansion for induced pluripotent stem cell products, which would validate universal off-the-shelf manufacturing economics.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Lonza Group's multi-continent GMP facility expansion secures long-term gene therapy supply agreements. |
| Regulatory Approval Pathway | FDA Regenerative Medicine Advanced Therapy designation compresses timelines for novel transplant adjuncts. |
| Long-term Supply Agreement | Direct sourcing contracts between hospital systems and media manufacturers bypass historical distributor markups. |
| Hospital System Partnership | Integrated delivery networks in Texas and California consolidate procurement leverage for autologous programs. |
| Pipeline Diversification | CRISPR-mediated HLA engineering promises universal off-the-shelf products collapsing donor search complexity. |
Research Methodology
Operator-level perspectives from transplant program directors, cellular therapy manufacturing heads, graft-versus-host disease specialists, and hospital procurement managers anchored the qualitative base. These primary insights combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and National Marrow Donor Program registry data. Bottom-up procedure volume modeling and top-down market sizing triangulation ensured cross-verification across data streams.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity testing around regulatory approval timelines and reimbursement policy shifts. Segmentation dimensions modeled encompass transplant type, source cell origin, indication category, and recipient age group alongside regional regulatory cluster differentiation. CAGRs derived from procedure volume trajectories, pricing trend synthesis, and payer coverage expansion patterns. Forecast inputs incorporated cryopreservation protocol adoption curves and haploidentical regimen penetration rates.
Sensitivities concentrate around graft-versus-host disease outcome data requirements hardening payer evidence thresholds and cross-border cryogenic logistics disruptions from customs clearance friction. Quarterly review of FDA and EMA cell therapy designations, CDMO capacity utilization announcements, and cord blood bank inventory reports is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Multiple Myeloma Market
Hematology
Lymphoma Treatment Market
Hematology
Allogeneic Stem Cell Therapy Market
Hematology
Heparin-Induced Thrombocytopenia (HIT) Treatment Market
Hematology
Langerhans Cell Histiocytosis Management Market
Hematology
Hematology Analyzers Market
Hematology
Hemocytometer Market
Hematology
Radiation-Induced Myelosuppression Treatment Market
Hematology
Venous Blood Collection Market
Hematology
Multiple Myeloma Therapeutics Market
Hematology
Sickle Cell Disease Market
Hematology
APAC Acute Myeloid Leukemia Treatment Market
Hematology
Burkitt Lymphoma Treatment Market
Hematology
Global Hematology Market
Hematology
Global Hemoglobin Meter Market
Hematology
Hematologic Malignancies Market