
 Plasma-Derived Drugs Market | 2026-2036
Plasma-Derived Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Plasma-Derived Drugs Market Analytics
Hospital and specialty pharmacy procurement is fragmenting as integrated delivery networks negotiate directly with fractionators. CSL Limited dominates plasma collection infrastructure across multiple continents. Grifols sustains one of the largest donor networks in the industry. Takeda Pharmaceutical anchors its position through immunoglobulin specialization and rare disease portfolio depth.
Plasma-derived drugs are biologic therapeutics manufactured through fractionation of human blood plasma, typically requiring cold-chain preservation and viral inactivation steps to ensure safety and potency. These products replace deficient proteins in patients with congenital or acquired disorders. Immunoglobulin commands the largest revenue pool due to chronic administration in primary immunodeficiency and neurologic indications. Coagulation factors occupy a high-margin niche serving hemophilia populations with recombinant alternatives pressing from above. Albumin functions as a volume expander in surgical and critical care settings where pricing pressure from synthetic colloids has compressed margins.
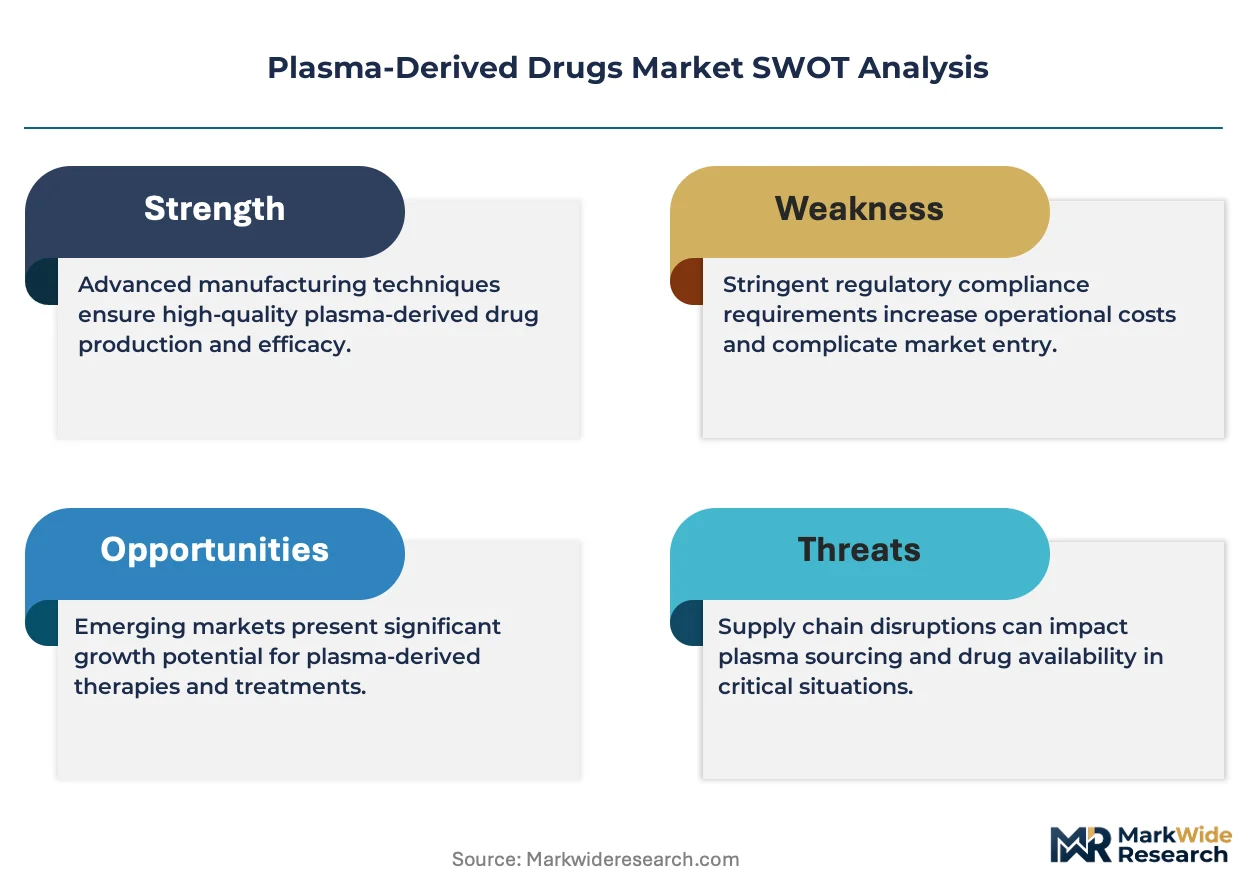
The FDA enforces Current Good Manufacturing Practice for plasma fractionation facilities and inspects donor centers for compliance with collection standards. The EMA oversees centralized marketing authorizations through its Committee for Medicinal Products for Human Use, while national regulators like Germany's Paul-Ehrlich-Institut conduct batch release testing for products distributed in Europe. Stakeholders must monitor regulatory divergence between FDA and EMA pathways for biosimilar immunoglobulins, as asynchronous approvals could reshape competitive access and pricing dynamics in overlapping territories.
Market Dynamics
Fractionation capacity concentration in the United States is creating supply asymmetry, as domestic plasma collection volumes exceed all other national markets combined and FDA donor qualification tightening constrains raw material expansion elsewhere.
Growth Catalysts
- Outpatient infusion center proliferation:Hospital systems are decentralizing immunoglobulin administration to ambulatory settings, expanding addressable patient throughput and therapy initiation rates.
- EMA centralized marketing authorization pathways:Streamlined batch release coordination across member states is reducing time-to-market for fractionated products entering European distribution.
- Primary immunodeficiency diagnosis expansion:Newborn screening program adoption in multiple jurisdictions is identifying treatment-naive patient cohorts earlier in disease progression.
Market Restraints
- Plasma donor pool constraints:FDA's updated donor qualification standards are disqualifying historical donor demographics and compressing collection center yield per location.
- Recombinant coagulation factor substitution:Bayer and Roche pipeline advances in hemophilia gene therapy threaten long-term factor VIII and IX concentrate demand.
- Albumin margin compression:Synthetic colloid volume expanders manufactured by Fresenius Kabi and Baxter are capturing price-sensitive surgical segments in emerging markets.
Strategic Opportunities
- Subcutaneous immunoglobulin formulation expansion:Home administration protocols are unlocking rural and homebound patient populations previously excluded from intravenous infusion requirements.
- India's PLI scheme for biologics:Domestic fractionation infrastructure investment incentives could establish South Asia as a plasma collection and processing alternative to Western supply concentration.
- Neurologic indication label extensions:CIDP and multifocal motor neuropathy approvals are diversifying immunoglobulin revenue beyond infectious disease prophylaxis.
Industry Challenges
- Viral inactivation validation complexity:FDA and EMA divergent expectations for pathogen reduction technology qualification are extending facility approval timelines.
- Cold-chain infrastructure capex requirements:Plasma-derived biologics require continuous temperature monitoring from collection through patient administration, demanding fleet and warehouse investment.
- Fractionation specialist workforce scarcity:Protein purification and chromatography expertise concentrates among retiring cohorts in Basel, Barcelona, and North Carolina research triangles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasma-Derived Drugs Market |
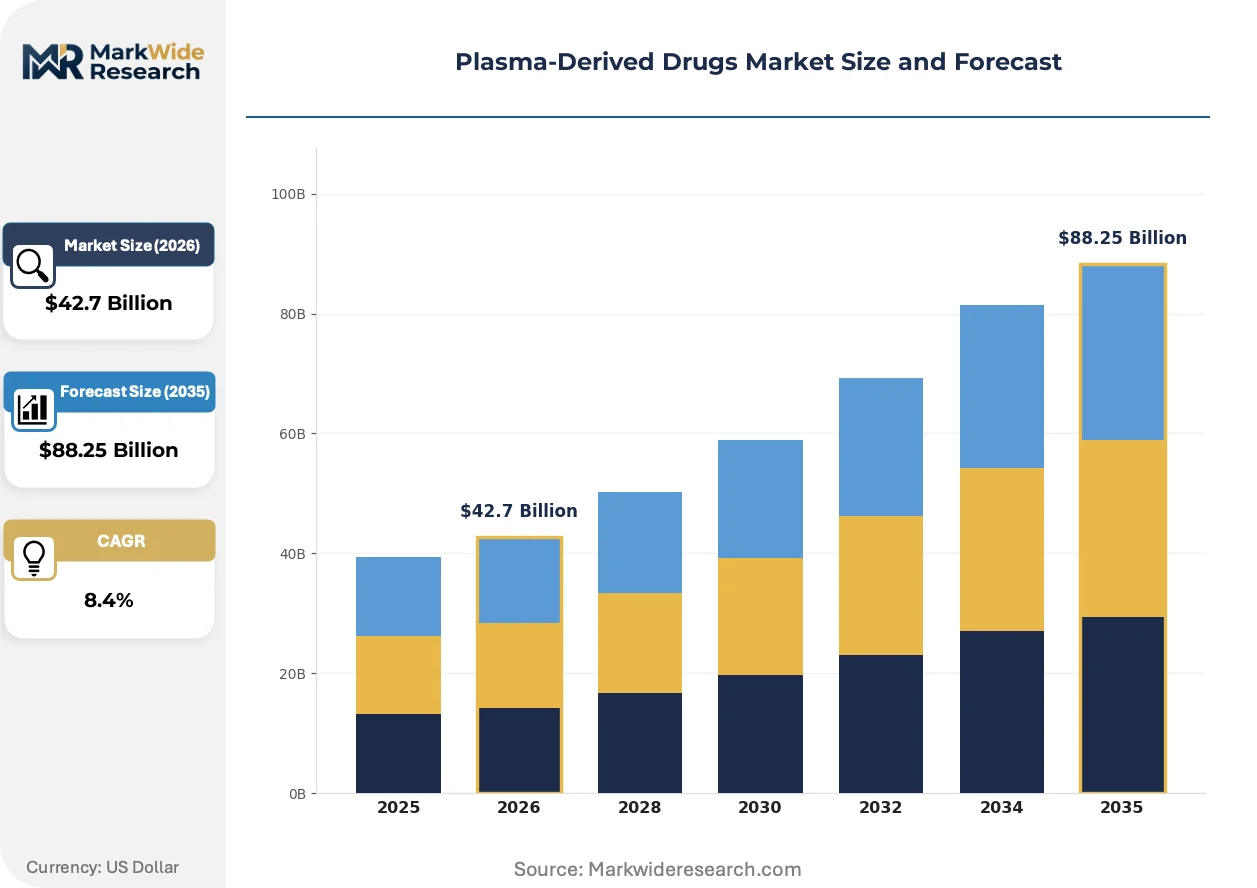
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $88.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoglobulin, Coagulation Factors, Albumin, Proteins Therapy Area: Hemophilia, Immunodeficiencies, Liver Disease, Neurology End User: Hospitals, Clinics, Blood Banks, Research Institutions Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Others |
| Companies Covered | CSL Limited, Grifols, Takeda Pharmaceutical, Octapharma, Kedrion Biopharma, Bio Products Laboratory, ADMA Biologics, Biotest, SK Plasma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasma-Derived Drugs Market Evolving Landscape
Continuous processing technologies and personalized dosing algorithms are compressing production batch cycles and challenging the economics of traditional fractionation scale.
Capto adhere chromatography resin systems are replacing ethanol precipitation as the dominant plasma protein separation mechanism. Fractionators in Germany and Switzerland are retrofitting legacy Cohn-Oncley cold ethanol lines with multimodal resin capture. This shift is rendering obsolete the energy-intensive deep-freeze storage requirements that historically dominated facility operating costs.
The EU's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in plasma cold-chain logistics. Fractionators must retrofit transport containers and storage facilities with natural refrigerant alternatives or pay escalating carbon-equivalent levies. Albumin and immunoglobulin distributors with pan-European depot networks face the steepest compliance cost concentration.
Integrated delivery networks in the United States are consolidating immunoglobulin purchasing through specialty pharmacy carve-outs. Hospital systems are displacing traditional wholesale distribution with direct fractionator contracting and 340B program optimization. Texas and Florida IDNs exhibit the most advanced procurement centralization, capturing volume rebates previously retained by distributor intermediaries.
Plasma-Derived Drugs Market Segmentation
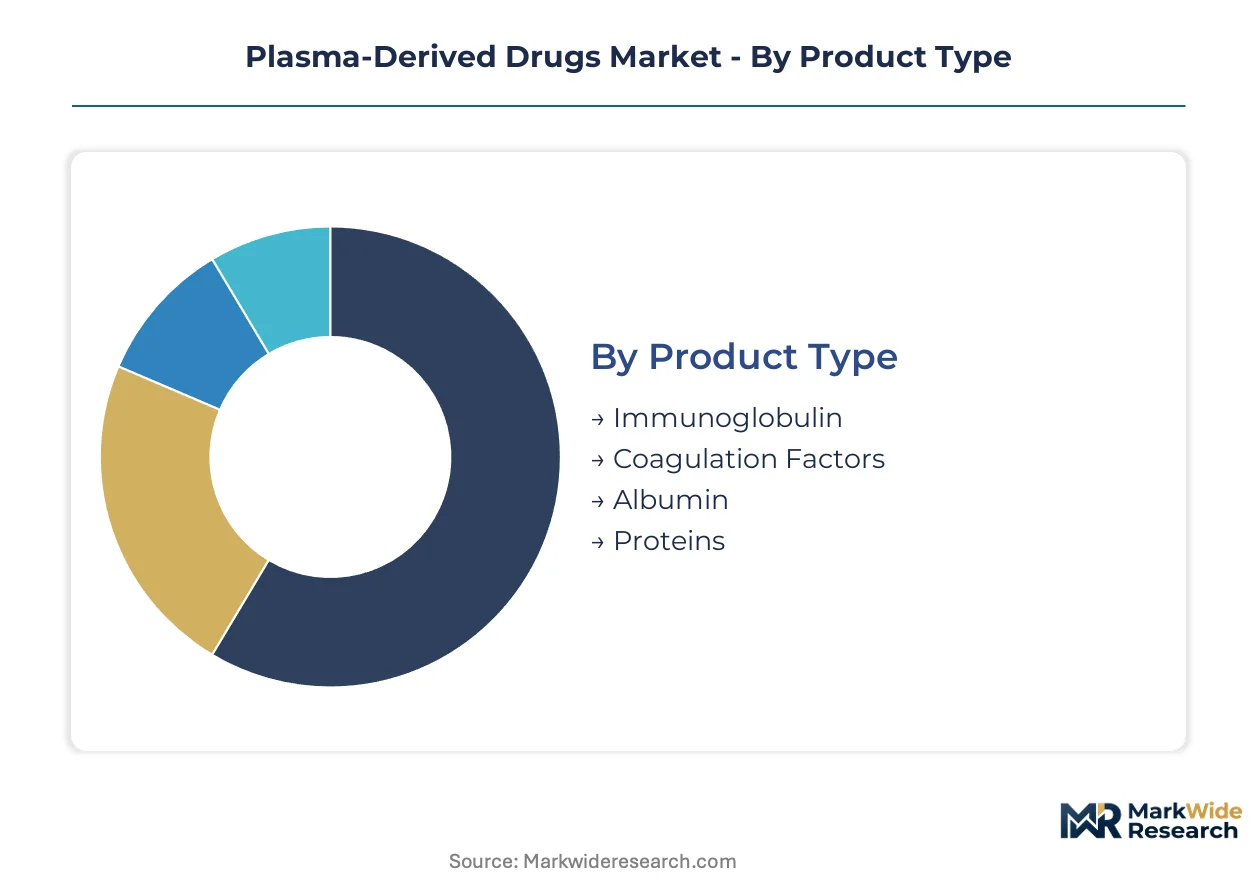
Plasma-derived drugs fragment across multiple intersecting dimensions that reshape procurement patterns and margin structures. Product type determines fractionation complexity and cold-chain requirements, while therapy area governs reimbursement intensity and prescriber specialization.
Product Type:
Cost tier stratification separates high-value immunoglobulin from commoditized albumin and intermediate coagulation factors.
- Immunoglobulin:Polyclonal antibody preparations derived from pooled plasma donations undergo chromatographic purification and viral inactivation. Chronic administration in primary immunodeficiency and CIDP creates recurring revenue streams with limited therapeutic substitution. Hospital outpatient centers in Texas and Florida drive volume concentration through integrated delivery network contracting.
- Coagulation Factors:Factor VIII and IX concentrates serve hemophilia populations with recombinant alternatives pressing from above. Gene therapy advances from Bayer and Roche threaten long-term concentrate demand in established markets. Specialty pharmacy distribution maintains grip on patient adherence monitoring and bleed event documentation.
- Albumin:Volume expander for surgical and critical care applications faces synthetic colloid competition. Pricing compression is most acute in emerging markets where Fresenius Kabi and Baxter capture price-sensitive segments.
- Proteins:Alpha-1 antitrypsin and C1 esterase inhibitor serve niche congenital deficiency populations. Orphan disease designation preserves premium positioning against limited addressable patient pools.
Immunoglobulin commands the established base. The steepest expansion runs through proteins with rare disease label extensions.
Therapy Area:
Application intensity varies by prescriber specialization and treatment chronicity across immunology, hematology, and critical care.
- Hemophilia:Lifelong factor replacement creates predictable consumption patterns with gene therapy threatening modality substitution. Treatment centers concentrate in Germany, the United States, and Japan with established comprehensive care models.
- Immunodeficiencies:Primary immunodeficiency diagnosis through newborn screening is expanding treatable cohorts in multiple jurisdictions. Subcutaneous administration protocols are unlocking home-based therapy initiation.
- Liver Disease:Albumin replacement in hepatic cirrhosis and paracentesis procedures faces synthetic volume expander competition. Reimbursement pressure compresses margins in European hospital procurement.
- Neurology:CIDP and multifocal motor neuropathy indications are diversifying immunoglobulin utilization beyond infectious disease prophylaxis. Medicare coverage determinations in the United States shape access expansion velocity.
Immunodeficiencies anchor the revenue foundation. Neurology applications are climbing the fastest as label extensions multiply.
End User:
Customer type determines procurement sophistication, with hospital systems consolidating purchasing power against fragmented clinic networks.
- Hospitals:Integrated delivery networks in Texas and Florida are displacing wholesale distribution through direct fractionator contracting and 340B program optimization.
- Clinics:Outpatient infusion center proliferation is decentralizing immunoglobulin administration and expanding rural patient throughput.
- Blood Banks:Plasma collection infrastructure operators maintain vertical integration into fractionation supply or supply contracted volume to independent processors.
- Research Institutions:Academic medical centers drive clinical trial enrollment for novel indications and biosimilar immunoglobulin development.
Hospitals retain procurement dominance. Clinics are gaining share fastest through ambulatory site-of-care migration.
Delivery Mode:
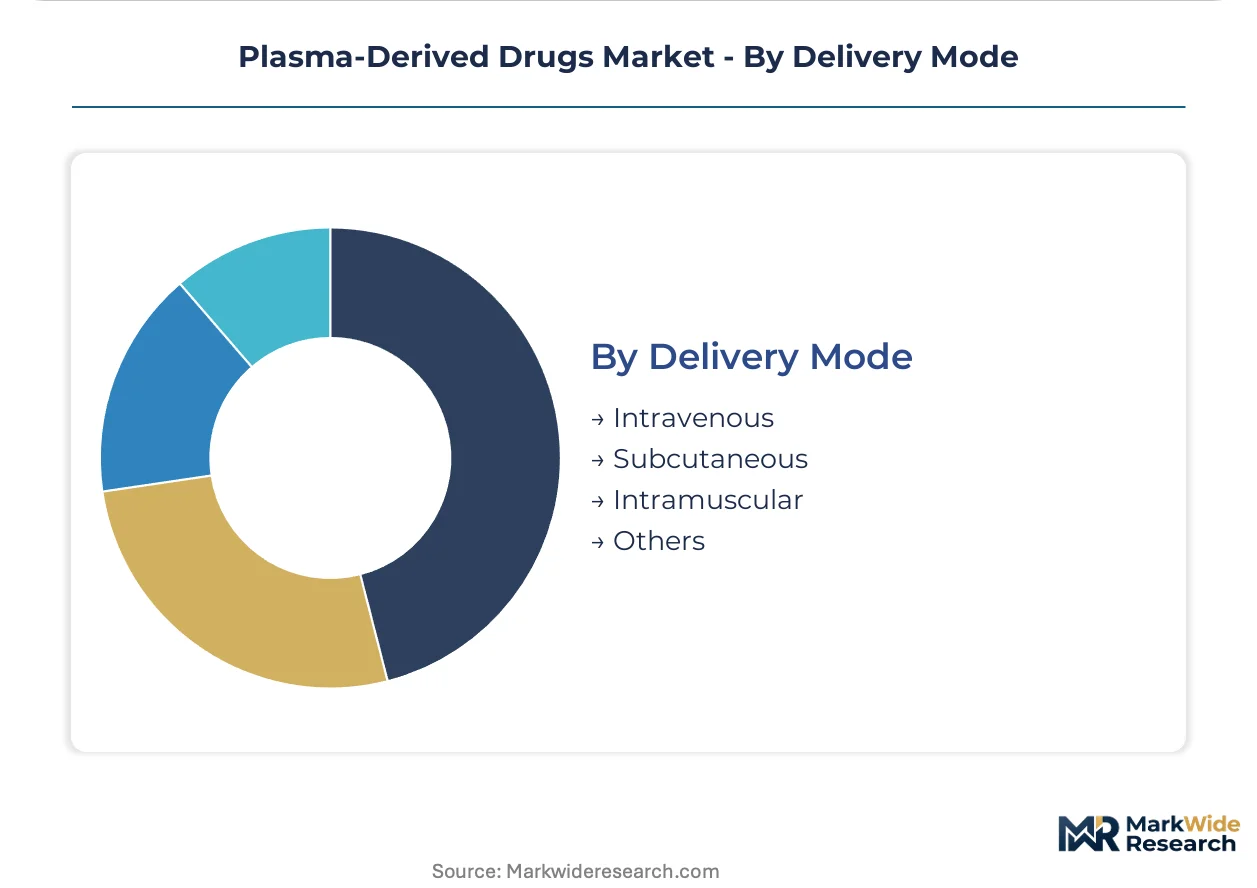
Volume concentration favors intravenous administration, though formulation innovation is reshaping patient access geography.
- Intravenous:Hospital and infusion center-based administration requires clinical infrastructure and nursing supervision. Established reimbursement pathways preserve volume concentration despite patient convenience limitations.
- Subcutaneous:Home administration protocols reduce infusion center dependency and unlock rural and homebound populations previously excluded from therapy. Training burden and needle anxiety constrain adoption velocity in certain demographics.
- Intramuscular:Limited to specific immunoglobulin indications and prophylactic applications with lower volume requirements.
- Others:Investigational routes including intrathecal and intraocular administration for specialized neurologic and ophthalmic indications.
Intravenous delivery maintains the volume base. Subcutaneous formulations are expanding most quickly through home care enablement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasma-derived drugs command pricing premiums in the United States that European procurement systems cannot replicate, creating a structural margin asymmetry that shapes fractionation investment geography. Collection infrastructure concentrates where donor compensation is permitted, while regulatory divergence fragments market access velocity.
United States
Integrated delivery networks in Texas and Florida drive immunoglobulin procurement centralization through direct fractionator contracting. FDA's updated donor qualification standards are compressing collection center yield per location while tightening viral inactivation validation requirements. The Research Triangle in North Carolina anchors protein purification expertise concentration as retiring cohorts threaten workforce continuity.
Germany
Paul-Ehrlich-Institut batch release testing governs European distribution access with centralized marketing authorization coordination through EMA pathways. The EU's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in cold-chain logistics, forcing depot network retrofits. Bavaria and Baden-Württemberg host multimodal resin capture retrofitting of legacy Cohn-Oncley fractionation lines.
China
NMPA oversight of plasma collection stations constrains raw material expansion as domestic fractionation capacity scales. Provincial regulators in Shandong and Henan enforce donor health screening protocols that limit collection volume growth. The Yangtze River Delta cluster attracts cold-chain infrastructure investment for biologics distribution.
India
CDSCO marketing authorization pathways and the PLI scheme for biologics are incentivizing domestic fractionation infrastructure investment. Maharashtra and Gujarat are emerging as plasma collection alternatives to Western supply concentration. National pharmaceutical procurement price controls compress albumin margins in hospital segments.
Switzerland
Swissmedic batch release coordination supports pan-European distribution while Basel anchors chromatography expertise concentration. Natural refrigerant retrofitting of transport containers is accelerating under carbon-equivalent levy pressure. The Basel research corridor sustains continuous processing technology development for protein purification.
Plasma-Derived Drugs Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on fractionation technology and collection infrastructure. The vendor base concentrates among five integrated plasma collectors with fractionation capacity, while regional specialists occupy national market niches. Three archetypes dominate: vertically integrated global collectors, immunoglobulin-focused biologics specialists, and national champions with captive donor networks. Capacity expansion and subcutaneous formulation development represent the dominant competitive vectors as gene therapy threats reshape coagulation factor portfolios.
Among Australian-integrated global collectors, CSL Limited exemplifies the platform archetype with multi-continent collection infrastructure. Spanish-based Grifols, S.A. occupies a position representing large-scale donor network concentration. Japanese-headquartered Takeda Pharmaceutical anchors the immunoglobulin specialization tier through rare disease portfolio depth. These three entities collectively represent the structural concentration that defines competitive dynamics in plasma-derived therapeutics.
| Leading Market Players |
|---|
| CSL Limited |
| Grifols |
| Takeda Pharmaceutical |
| Octapharma |
| Kedrion Biopharma |
| Bio Products Laboratory |
| ADMA Biologics |
| Biotest |
| SK Plasma |
| Others |
Value Network & Pricing Analysis
United States plasma collection infrastructure concentration funnels margin capture downstream toward fractionators with captive donor networks and FDA-inspected viral inactivation capacity. Pricing power pools with integrated collectors that control both raw material access and finished product release, while buyers in European hospital procurement systems face compressed reimbursement ceilings.
Pricing Analysis
Configured-to-order pricing for patient-specific immunoglobulin dosing commands substantial premiums over standard intravenous formulations in hospital outpatient settings. Three-tier pricing structure across premium, standard, and economy levels separates subcutaneous home-administration kits from bulk intravenous bags and synthetic colloid alternatives. Cost compression in albumin intensifies because Fresenius Kabi and Baxter capture price-sensitive surgical segments in emerging markets. Price sensitivity concentrates among integrated delivery networks negotiating volume rebates, while orphan disease protein therapies retain the least sensitivity due to limited therapeutic substitution.
Supply Chain Analysis
Export-control regimes on chromatography resin systems and viral inactivation technologies limit technology transfer to emerging fractionation markets. Raw material supply concentrates in the United States, Germany, and Switzerland where donor compensation policies and fractionation expertise cluster. Production draws from human plasma donations, Capto adhere resin systems, and hydrofluorocarbon refrigerant cold-chain infrastructure. Single-source vulnerability sits with CSL Limited's multi-continent collection network dominance. Distribution runs through integrated delivery network direct contracting and specialty pharmacy carve-outs displacing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflects as continuous processing technologies and subcutaneous formulation standardization create interoperability between home administration protocols and infusion center infrastructure. This ecosystem shift rewards collectors with integrated formulation development capabilities.
For Market Incumbents: Harden viral inactivation validation protocols against FDA-EMA divergence to extend facility approval timelines as a competitive moat. Consolidate chromatography expertise concentration in Basel and North Carolina through targeted retention programs addressing retiring workforce cohorts. Gene therapy advances from Bayer and Roche threaten hemophilia concentrate portfolios; diversify revenue through neurologic indication label extensions for immunoglobulin. For New Entrants and Emerging Players: Pursue India's PLI scheme for biologics to establish South Asian plasma collection and processing capacity as an alternative to Western supply concentration. Target Maharashtra and Gujarat for donor network development under CDSCO oversight with lower regulatory barriers than FDA qualification standards. Penetrate through subcutaneous formulation partnerships with rural clinic networks previously excluded from intravenous infusion requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional fractionators in Europe lacking immunoglobulin specialization depth. Long-term viability over a multi-year window favors collectors with backward integration into donor networks over pure-play processors dependent on contracted plasma supply. Acquisition candidates with captive collection infrastructure and EMA centralized marketing authorization pathways offer the strongest positioning. Watch for asynchronous biosimilar immunoglobulin approvals between FDA and EMA as an inflection signal reshaping competitive access dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Home administration protocols unlock rural patient populations previously excluded from intravenous requirements. |
| Continuous Processing Technology Adoption | Capto adhere chromatography resin systems replace energy-intensive Cohn-Oncley cold ethanol precipitation lines. |
| Natural Refrigerant Cold-Chain Retrofit | EU F-Gas Regulation compliance avoids escalating carbon-equivalent levies on hydrofluorocarbon transport containers. |
| Direct IDN Contracting Structure | Texas and Florida integrated delivery networks capture volume rebates previously retained by distributor intermediaries. |
| Neurologic Indication Label Extension | CIDP and multifocal motor neuropathy approvals diversify immunoglobulin revenue beyond infectious disease prophylaxis. |
Research Methodology
A spread of perspectives from plasma collection center operators, fractionation facility managers, hospital formulary directors, and specialty pharmacy procurement leads converged on the working assumptions underlying demand projections. Primary fieldwork combined structured interviews with secondary validation against FDA donor qualification guideline updates, EMA centralized marketing authorization pathway documentation, Paul-Ehrlich-Institut batch release protocols, and integrated delivery network 340B program optimization disclosures. Bottom-up patient population modeling triangulated against top-down fractionation capacity utilization data.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, therapy area, end user, and delivery mode, with regional regulatory cluster differentiation across FDA, EMA, and CDSCO oversight jurisdictions. CAGRs derived from patient cohort expansion rates, newborn screening program adoption curves, and outpatient infusion center proliferation trajectories. Forecast inputs incorporated gene therapy pipeline progression from Bayer and Roche and subcutaneous formulation adoption velocity in rural demographics.
Sensitivities concentrate around FDA donor qualification tightening, EMA-FDA biosimilar approval asynchrony, and gene therapy substitution timelines in hemophilia populations. Forecasts reflect documented assumptions regarding fractionation capacity expansion and cold-chain infrastructure investment. Cross-checking against hospital procurement database benchmarks and GPO contract pricing disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Paracetamol IV Market
Pharmaceuticals
Small Molecule Innovator CDMO Market
Pharmaceuticals
Liver Fibrosis Drugs Market
Pharmaceuticals
Contraceptive Pills Market
Pharmaceuticals
Asia-Pacific Biguanide Market
Pharmaceuticals
Europe Generic Drug Market
Pharmaceuticals
Long-Acting Beta-Agonists Market
Pharmaceuticals
Dipeptide Peptidase 4 Inhibitors Market
Pharmaceuticals
Global Erythropoietin Stimulating Agents Market
Pharmaceuticals
Varicella Attenuated Live Vaccination Market
Pharmaceuticals
Drug-Loaded Oral Thin Films Market
Pharmaceuticals
Plasma-Derived Protein Therapies Market
Pharmaceuticals
Fibroblast Activation Protein Inhibitors Market
Pharmaceuticals
Immunoglobulin Market
Pharmaceuticals
Xerostomia Therapeutics Market
Pharmaceuticals
Global Atosiban Market