
 Epileptic Seizures Treatment Market | 2026-2036
Epileptic Seizures Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Epileptic Seizures Treatment Market Analysis
Aftermarket service revenue for implanted neurostimulation devices is tilting toward manufacturers with direct patient monitoring platforms. UCB Pharma anchors its position through deep European hospital relationships and specialized epilepsy sales forces. Pfizer competes via broad AED portfolio scale and established payer contracts across North American formularies. Eisai differentiates through Japanese market dominance and long-standing regulatory rapport with PMDA for novel antiepileptic submissions.
Epileptic seizures treatment encompasses pharmacological, neuromodulation, and surgical interventions designed to suppress abnormal neuronal electrical discharges, with drug-refractory cases increasingly managed through implantable pulse generators delivering programmable electrical stimulation to the vagus nerve or responsive cortical targets. The primary purpose spans seizure frequency reduction, severity attenuation, and quality-of-life preservation across pediatric through geriatric populations. AEDs occupy the mature volume base while responsive neurostimulation captures premium positioning among drug-resistant candidates. Implantable delivery modes concentrate margin pools due to recurring device replacement cycles and proprietary programming ecosystems.
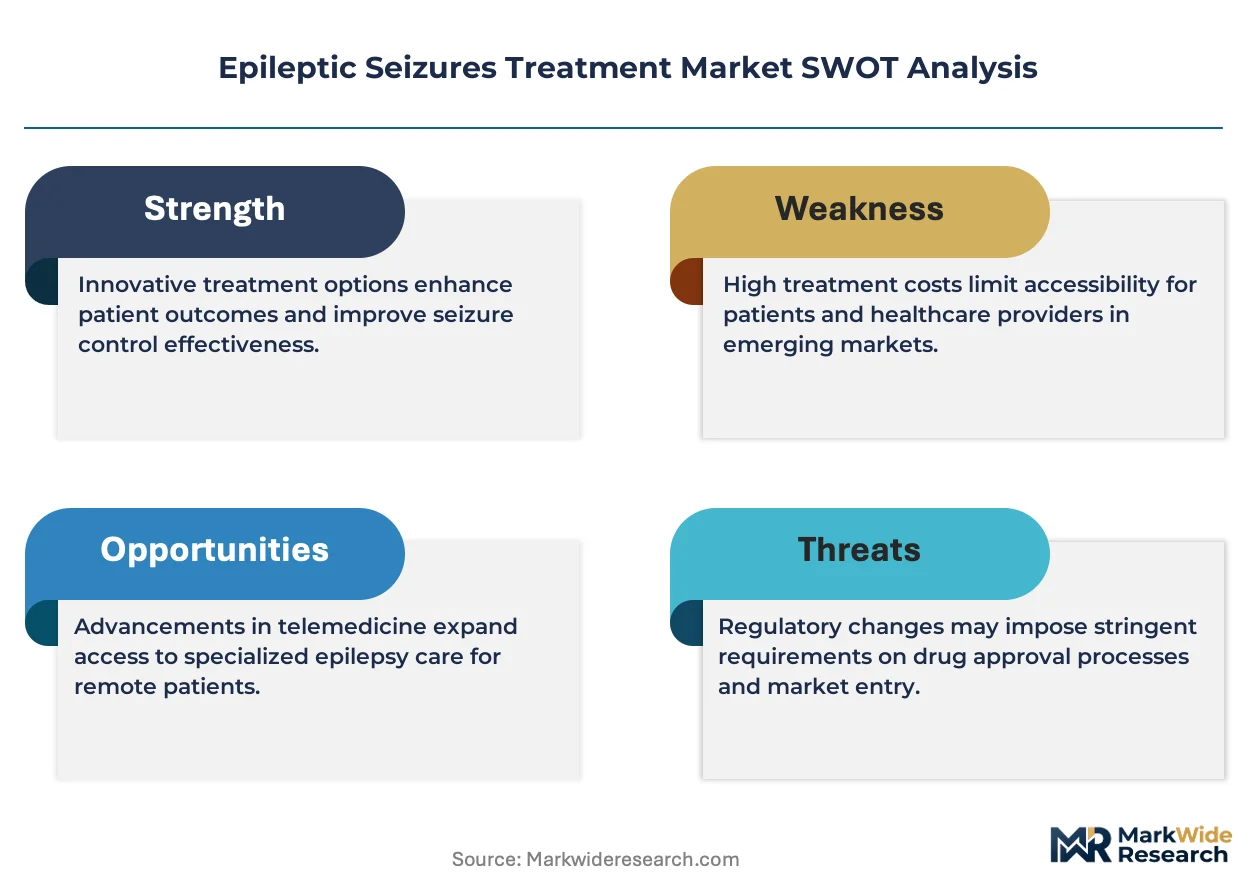
FDA breakthrough device designation and EMA PRIME eligibility for neurological orphans are compressing development timelines and reshaping how sponsors allocate clinical trial investment. PMDA's Sakigake framework further accelerates Japanese market entry for innovative epilepsy therapies, creating parallel regulatory tracks that demand distinct evidence-generation strategies. Stakeholders must monitor how CMS and national European health technology assessment bodies recalibrate coverage for closed-loop neurostimulation against generic AED cost benchmarks.
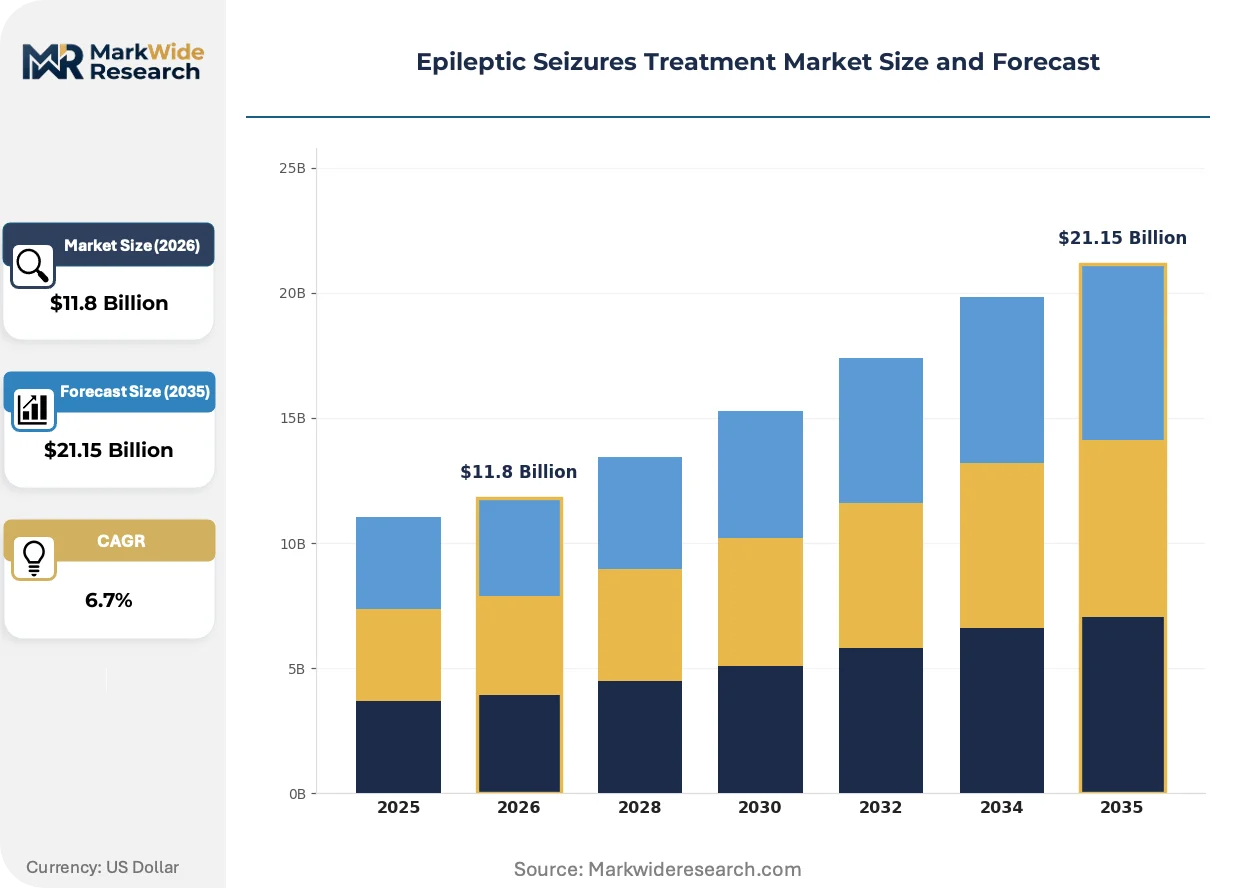
Market Dynamics
Closed-loop neurostimulation systems are compressing the clinical pathway for drug-resistant epilepsy, forcing AED manufacturers to defend reimbursement positioning against implantable device ecosystems with superior long-term adherence profiles.
Growth Catalysts
- FDA Breakthrough Device Designation:Compressed review timelines for vagus nerve stimulation upgrades are accelerating commercialization of next-generation pulse generators with predictive seizure detection algorithms.
- Japan Sakigake Framework:PMDA's early approval pathway for innovative neurological therapies is pulling multinational sponsors toward simultaneous Japanese development programs.
- Responsive Cortical Stimulation:Implantable devices with real-time intracranial EEG monitoring are capturing surgical candidates previously managed through repeated resections.
Market Restraints
- Neurostimulator Battery Replacement Cycles:Three-to-five-year surgical revision requirements create cumulative cost burdens that HTA bodies in Germany and France benchmark against lifetime generic AED therapy.
- Specialized Epilepsy Monitoring Unit Concentration:Level 3 and 4 epilepsy centers cluster in urban academic medical centers, limiting rural patient access to device candidacy evaluation.
- Pharmacoresistant Definition Variability:Inconsistent criteria across NHS England, CMS, and Japanese reimbursement frameworks delay standardized patient routing toward surgical or neuromodulation pathways.
Strategic Opportunities
- Pediatric Drug-Resistant Epilepsy:Underpenetrated surgical and neuromodulation candidacy in patients under 18 years represents expansion potential as FDA expands humanitarian device exemptions.
- Telemedicine-Enabled Device Programming:Remote parameter adjustment for implanted neurostimulators is opening direct manufacturer-patient relationships outside traditional hospital-based neurology follow-up.
- EMA PRIME Eligibility for Orphan Neurological Indications:Accelerated assessment pathways for rare epilepsy syndromes are incentivizing development of precision AEDs targeting genetic channelopathies.
Industry Challenges
- Epilepsy Monitoring Unit Technologist Shortage:Specialized neurophysiology technicians capable of intracranial EEG interpretation remain concentrated at a handful of training programs in the United States, Germany, and Japan.
- Cross-Border Device Servicing Complexity:Implantable pulse generator warranty and explant logistics fragment across divergent national medical device vigilance reporting requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epileptic Seizures Treatment Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $21.15 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AEDs, Vagus Nerve Stimulators, Responsive Neurostimulation, Surgery Delivery Mode: Oral, Injectable, Transdermal, Implantable End User: Hospitals, Clinics, Homecare, Rehabilitation Centers Patient Type: Pediatric, Adult, Geriatric, Others |
| Companies Covered | Pfizer, UCB Pharma, Novartis, GSK, Eisai, Jazz Pharmaceuticals, Sanofi, AbbVie, Xenon Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epileptic Seizures Treatment Market Emerging Trajectories
Digital biomarker integration and predictive algorithm deployment are redefining how seizure burden is quantified, shifting clinical trial endpoints from patient-reported diaries toward objective neurophysiological data streams.
Responsive neurostimulation technology is migrating from open-loop vagus nerve stimulation toward closed-loop cortical target detection with automated therapeutic response. Academic medical centers in the United States and Germany are prioritizing these systems for temporal lobe epilepsy surgical candidates. The technology is migrating from hospital-based programming dependence toward manufacturer-managed remote monitoring platforms that capture recurring revenue through subscription-based algorithm updates.
EMA's Medical Device Regulation (MDR) reclassification of active implantable neurological devices is tightening clinical evidence requirements for neurostimulator market authorization renewals. Manufacturers must now submit post-market surveillance data with patient-level outcomes rather than aggregate safety summaries. Implantable device sponsors with legacy CE marks under the Medical Devices Directive face compressed timelines for MDR technical documentation resubmission.
Hospital procurement departments are consolidating AED purchasing through centralized pharmacy and therapeutics committees with mandatory generic substitution protocols. Academic medical centers and integrated delivery networks are displacing individual prescriber autonomy with formulary-driven therapy selection algorithms. This concentration is most pronounced in United States health systems where pharmacy benefit managers have extended prior authorization requirements to neurology specialty tiers.
Epileptic Seizures Treatment Market Segmentation
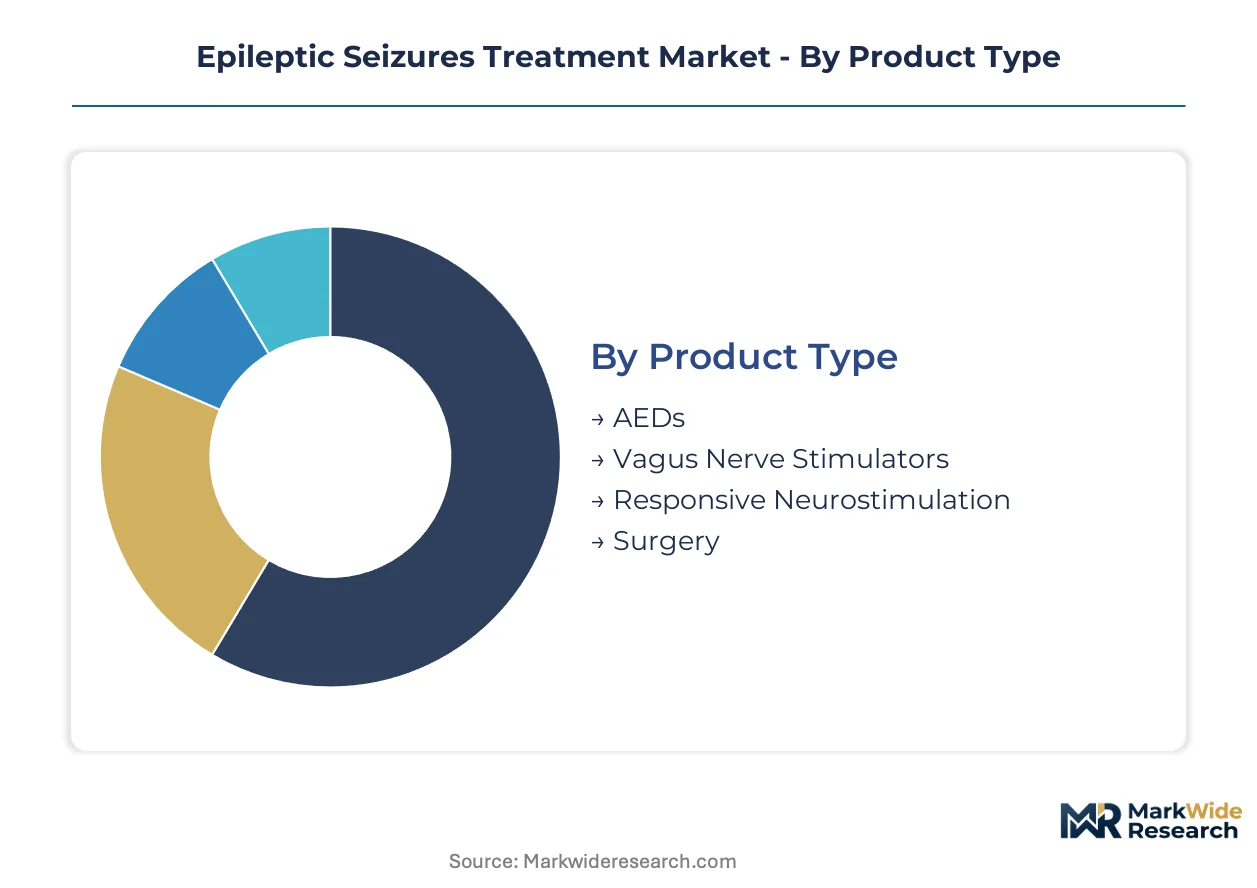
Treatment modality segmentation determines service revenue architecture, with implantable devices demanding manufacturer-managed follow-up ecosystems while pharmaceuticals flow through centralized pharmacy procurement. Understanding these structural divides clarifies where margin pools concentrate and how competitive positioning shifts across the patient journey.
Product Type:
After-sales service intensity varies dramatically across this category, with implantable neurostimulation systems generating recurring revenue through battery replacement cycles and remote programming subscriptions that AED manufacturers cannot replicate.
- AEDs:Oral and intravenous formulations dominate prescription volume, with hospital formularies in the United States and Germany enforcing mandatory generic substitution protocols that compress branded pricing power. Payer concentration through pharmacy benefit managers limits prescriber autonomy.
- Vagus Nerve Stimulators:Open-loop pulse generators with fixed stimulation parameters require surgical battery replacement every three to five years, creating predictable aftermarket revenue streams. FDA breakthrough device designation for next-generation models with predictive seizure detection is accelerating upgrade cycles among implanted patients.
- Responsive Neurostimulation:Closed-loop cortical monitoring with automated therapeutic response captures surgical candidates at academic medical centers. Real-time intracranial EEG interpretation demands specialized neurophysiology technologists concentrated in United States, German, and Japanese training programs.
- Surgery:Resective procedures for temporal lobe epilepsy require Level 4 epilepsy center concentration, limiting rural patient access. Reimbursement variability across NHS England, CMS, and Japanese frameworks delays standardized candidacy evaluation.
AEDs holds the largest share; momentum sits with Responsive Neurostimulation.
Delivery Mode:
Cost tier stratification separates high-touch implantable ecosystems from commoditized oral generics, with transdermal patches occupying an intermediate position where formulation patents defend pricing.
- Oral:Immediate-release and extended-release tablets constitute the volume base, with centralized pharmacy and therapeutics committees displacing individual prescriber autonomy through formulary-driven selection algorithms in United States health systems.
- Injectable:Intravenous fosphenytoin and intramuscular midazolam serve emergency and status epilepticus protocols in hospital emergency departments. Payer prior authorization requirements increasingly extend to neurology specialty tiers.
- Transdermal:Patch formulations for pediatric and geriatric populations with swallowing difficulties command formulation premiums. EMA MDR reclassification is tightening clinical evidence requirements for renewed market authorization.
- Implantable:Pulse generators and responsive neurostimulation systems concentrate margin pools through proprietary programming ecosystems. Remote parameter adjustment capabilities are opening direct manufacturer-patient relationships outside traditional hospital-based neurology follow-up.
Oral dominates prescription volume; Implantable captures premium positioning.
End User:
Customer type determines procurement channel and reimbursement complexity, with hospitals managing capital-intensive neurostimulation placements while homecare settings drive AED adherence monitoring.
- Hospitals:Academic medical centers and integrated delivery networks house Level 3 and 4 epilepsy centers where device candidacy evaluation concentrates. Epilepsy monitoring unit expansion is capturing complex surgical and neuromodulation cases.
- Clinics:Community neurology practices manage stable AED regimens with limited access to intracranial EEG interpretation capabilities. Telemedicine-enabled consultations are extending specialist reach into underserved geographies.
- Homecare:Pediatric drug-resistant epilepsy patients and adult candidates with transportation barriers receive nursing support for device maintenance and seizure diary management. Remote monitoring platforms are displacing in-person follow-up for stable implanted patients.
- Rehabilitation Centers:Post-surgical recovery and neurostimulation programming adjustment occur in specialized facilities with neurophysiology technician staffing. Cross-border device servicing complexity fragments warranty logistics across divergent national medical device vigilance requirements.
Hospitals anchor device placement volume; Homecare represents the steepest expansion trajectory for remote monitoring adoption.
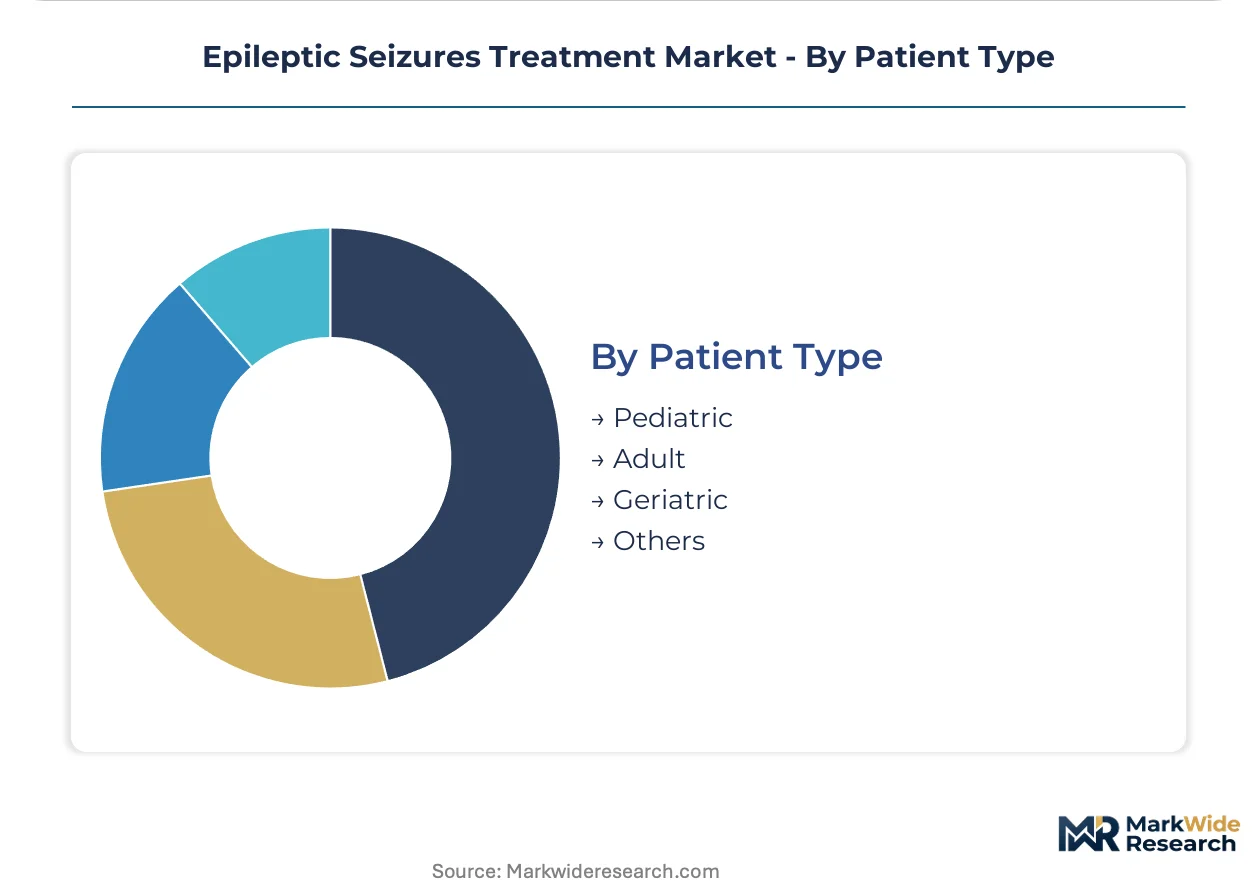
Patient Type:
Maturity differentiation separates established adult protocols from underpenetrated pediatric surgical candidacy, with geriatric populations presenting polypharmacy challenges that complicate AED selection.
- Pediatric:Drug-resistant epilepsy in patients under 18 years remains underpenetrated for surgical and neuromodulation intervention. FDA humanitarian device exemptions are expanding pediatric-responsive neurostimulation indications.
- Adult:Temporal lobe epilepsy surgical candidates between 18 and 65 years drive responsive neurostimulation placement at German and United States academic centers. Employment and driving restrictions create quality-of-life pressures that accelerate treatment escalation.
- Geriatric:Late-onset epilepsy with cerebrovascular etiology requires careful AED selection to avoid cognitive and bone density adverse effects. PMDA Sakigake framework incentives for innovative therapies are pulling sponsors toward simultaneous Japanese development programs for this population.
- Others:Pregnancy-related epilepsy management and comorbid psychiatric conditions demand specialized multidisciplinary coordination. Pharmacoresistant definition variability across reimbursement frameworks delays standardized routing toward advanced interventions.
Adult captures current procedural volume; Pediatric presents the greatest expansion potential as humanitarian exemptions mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets, with the United States and Japan favoring implantable neurostimulation for drug-resistant cases while Germany and emerging markets lean on AED pharmacotherapy due to divergent reimbursement architectures and specialist concentration.
United States
Academic medical centers in Boston, Cleveland, and Houston drive responsive neurostimulation adoption through Level 4 epilepsy center concentration. FDA breakthrough device designation compresses review timelines for next-generation pulse generators. CMS reimbursement for closed-loop cortical stimulation creates predictable access pathways at major referral hubs.
Germany
Hospital-based neurology departments in Munich and Berlin expand epilepsy monitoring units to capture complex surgical candidates. EMA PRIME eligibility accelerates assessment of orphan neurological indications. IQWiG health technology assessment benchmarks neurostimulator costs against lifetime generic AED therapy, slowing device penetration outside academic centers.
Japan
Geriatric late-onset epilepsy with cerebrovascular etiology dominates prescription volume in Tokyo and Osaka metropolitan areas. PMDA's Sakigake framework pulls multinational sponsors toward simultaneous Japanese development programs. Long-standing regulatory rapport between domestic sponsors and PMDA streamlines novel antiepileptic submissions.
United Kingdom
NHS England's pharmacoresistant definition variability delays standardized patient routing toward surgical pathways. Level 3 and 4 epilepsy centers cluster in London, Manchester, and Glasgow. NICE technology appraisal processes create reimbursement uncertainty for neurostimulation relative to pharmacological alternatives.
India
Oral AED generics dominate prescription volume through centralized hospital pharmacy procurement in Delhi, Mumbai, and Bangalore. CDSCO accelerated approval pathways for innovative neurological therapies remain underutilized due to cost barriers. Rural patient access to epilepsy monitoring unit evaluation remains severely limited outside tertiary urban centers.
Epileptic Seizures Treatment Market Vendor Landscape
Capability concentration sits with specialized epilepsy-focused developers possessing deep hospital relationships and regulatory rapport; scale advantage sits with diversified pharmaceutical conglomerates leveraging broad AED portfolios and established payer contracts. The market structures around three archetypes: European specialists with dedicated neurology sales forces, diversified multinationals with formulary-driven volume plays, and Japanese-domestic players with PMDA pathway expertise. Competitive moves center on M&A for precision AED pipelines and strategic partnerships for remote monitoring platform integration.
Within the specialized European tier, UCB Pharma anchors through deep hospital relationships and dedicated epilepsy sales forces. Pfizer occupies the scale-driven position via broad AED portfolio breadth and established North American formulary contracts. Eisai exemplifies the domestic-Japanese archetype through market dominance and long-standing PMDA regulatory rapport for novel submissions.
| Leading Market Players |
|---|
| Pfizer |
| UCB Pharma |
| Novartis |
| GSK |
| Eisai |
| Jazz Pharmaceuticals |
| Sanofi |
| AbbVie |
| Xenon Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
Undercapacity at specialized neurophysiology technician training programs in the United States, Germany, and Japan constrains implantable device servicing capacity while simultaneously supporting premium pricing for manufacturer-managed remote monitoring subscriptions that bypass hospital-based follow-up bottlenecks.
Pricing Analysis
Long-term service contracts dominate implantable neurostimulation economics, with manufacturers capturing recurring revenue through battery replacement cycles and algorithm update subscriptions that AED suppliers cannot replicate. Price differentiation rests on proprietary programming ecosystem lock-in and FDA breakthrough device certification tier. Cost compression in oral generic AEDs intensifies as pharmacy benefit managers enforce mandatory substitution protocols across United States formularies. Hospital procurement committees exhibit highest price sensitivity for commoditized oral formulations; academic medical centers show lowest sensitivity for closed-loop cortical stimulation systems with real-time seizure detection capabilities.
Supply Chain Analysis
Upstream feedstock concentration for active implantable pulse generators centers on specialized semiconductor foundries in Taiwan, precision battery cell manufacturers in South Korea, and biocompatible housing fabricators in Germany. Raw material dependencies include lithium-ion cells for extended-cycle power, platinum-iridium electrodes for cortical signal acquisition, and medical-grade titanium enclosures. Single-source vulnerability for intracranial EEG interpretation algorithms creates supply chain risk given specialized neurophysiology technician scarcity. Distribution runs through hospital-based epilepsy monitoring units at Level 3 and 4 academic centers, with direct-to-patient remote monitoring platforms emerging as parallel channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in pediatric drug-resistant epilepsy, where humanitarian device exemption expansion and telemedicine-enabled candidacy evaluation are creating addressable niches outside established adult surgical pathways.
For Market Incumbents: Insulate proprietary programming ecosystems by deepening remote monitoring platform integration and securing exclusive hospital system partnerships for epilepsy monitoring unit staffing. Threat from generic AED manufacturers intensifies as formulary substitution protocols displace branded oral formulations. Priority lever centers on backward integration into neurophysiology technician training programs to constrain competitor device servicing capacity.
For New Entrants and Emerging Players: Build out telemedicine-enabled device programming capabilities targeting rural patient populations with transportation barriers to academic medical centers. Most penetrable segment sits with homecare nursing support for pediatric seizure diary management and stable implanted patient follow-up. Go-to-market angle emphasizes direct manufacturer-patient relationships outside traditional hospital-based neurology channels.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because implantable device battery replacement cycles and subscription-based algorithm updates generate predictable cash flows decoupled from pharmaceutical patent cliffs. Acquisition target archetype includes remote monitoring platform specialists with FDA breakthrough device pathway experience. Signal to watch is CMS reimbursement recalibration for closed-loop neurostimulation against generic AED lifetime cost benchmarks.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerates review timelines for predictive seizure detection algorithms in next-generation pulse generators. |
| Hospital System Partnership | Secures exclusive epilepsy monitoring unit staffing contracts that constrain competitor device placement access. |
| Software Companion Development | Enables remote parameter adjustment and direct manufacturer-patient relationships outside hospital follow-up. |
| CE Marking Pathway | Addresses EMA MDR reclassification requirements for active implantable neurological device authorization renewals. |
| Reimbursement Strategy | Positions closed-loop neurostimulation against lifetime generic AED cost benchmarks in German IQWiG assessments. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Interview program engaged drug development executives at specialized epilepsy-focused developers, regulatory affairs leads navigating PMDA Sakigake pathways, formulary directors at United States pharmacy benefit managers, hospital procurement managers at German academic medical centers, and payer access specialists advising on CMS coverage determinations. Bottom-up patient flow modeling triangulated against top-down market sizing across treatment modalities.
Forecast inputs incorporate treatment line progression rates, dosage form substitution elasticities, administration route adoption curves, patient population aging demographics, and regional regulatory cluster heterogeneity across the projection horizon. Segmentation dimensions modeled span product type, delivery mode, end user, and patient age cohort. CAGRs derived from historical procedure volume trajectories and reimbursement policy elasticity estimates. Industry-specific inputs include epilepsy monitoring unit expansion rates and neurostimulator battery replacement cycle frequencies.
Stress conditions across PMDA regulatory timeline compression, CMS neurostimulation coverage recalibration, and EMA MDR technical documentation resubmission deadlines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding stable pharmacoresistant definition convergence and continued concentration of specialized neurophysiology technologists. Cross-checking against IQWiG health technology assessment cost-effectiveness thresholds is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Bipolar Disorder Therapeutics Market
Specialty Medicine
Global Major Depressive Disorder (MDD) Market
Specialty Medicine
Global Alcoholic Hepatitis Therapeutics Market
Specialty Medicine
Narcolepsy Market
Specialty Medicine
Toxoplasmosis Treatment Market
Specialty Medicine
Global Scleroderma Diagnostics and Therapeutics Market
Specialty Medicine
Personalized Medicine Market
Specialty Medicine
Cytomegalovirus Retinitis Market
Specialty Medicine
Global Sarcopenia Treatment Market
Specialty Medicine
Rheumatoid Arthritis Treatment Market
Specialty Medicine
HTLV-1 Associated Myelopathy (HAM) Market
Specialty Medicine
Short Bowel Syndrome Market
Specialty Medicine
Listeriosis Treatment Market
Specialty Medicine
Global Spinal Muscular Atrophy Treatment Market
Specialty Medicine
Enzyme Replacement Therapy Market
Specialty Medicine
Global Calciphylaxis Treatment Market