
 Latin America Liver Cancer Treatment Market | 2026-2036
Latin America Liver Cancer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Liver Cancer Treatment Market Foresight
Modular combination regimens is repositioning buyer choice across Latin America, as payers and clinicians evaluate bundled immunotherapy-chemotherapy protocols against standalone alternatives. Bayer AG leverages its established hepatocellular carcinoma portfolio to anchor market presence in Brazil and Mexico. Bristol-Myers Squibb Company competes through checkpoint inhibitor specialization, while Merck & Co Inc sustains R&D investment in regional trial networks.
Liver cancer treatment encompasses surgical resection, systemic drug therapy, locoregional interventions, and radiation modalities targeting malignant hepatic tumors, with therapeutic selection governed by Barcelona Clinic Liver Cancer staging and underlying cirrhosis severity. Immunotherapy segments command premium positioning as PD-1/PD-L1 inhibitors expand reimbursement access, while targeted therapy categories anchored by tyrosine kinase inhibitors retain volume leadership across hospital formularies. Radiofrequency ablation technology occupies a mature but essential role in early-stage disease management, and stereotactic body radiation therapy segments attract capital investment as linear accelerator infrastructure proliferates.
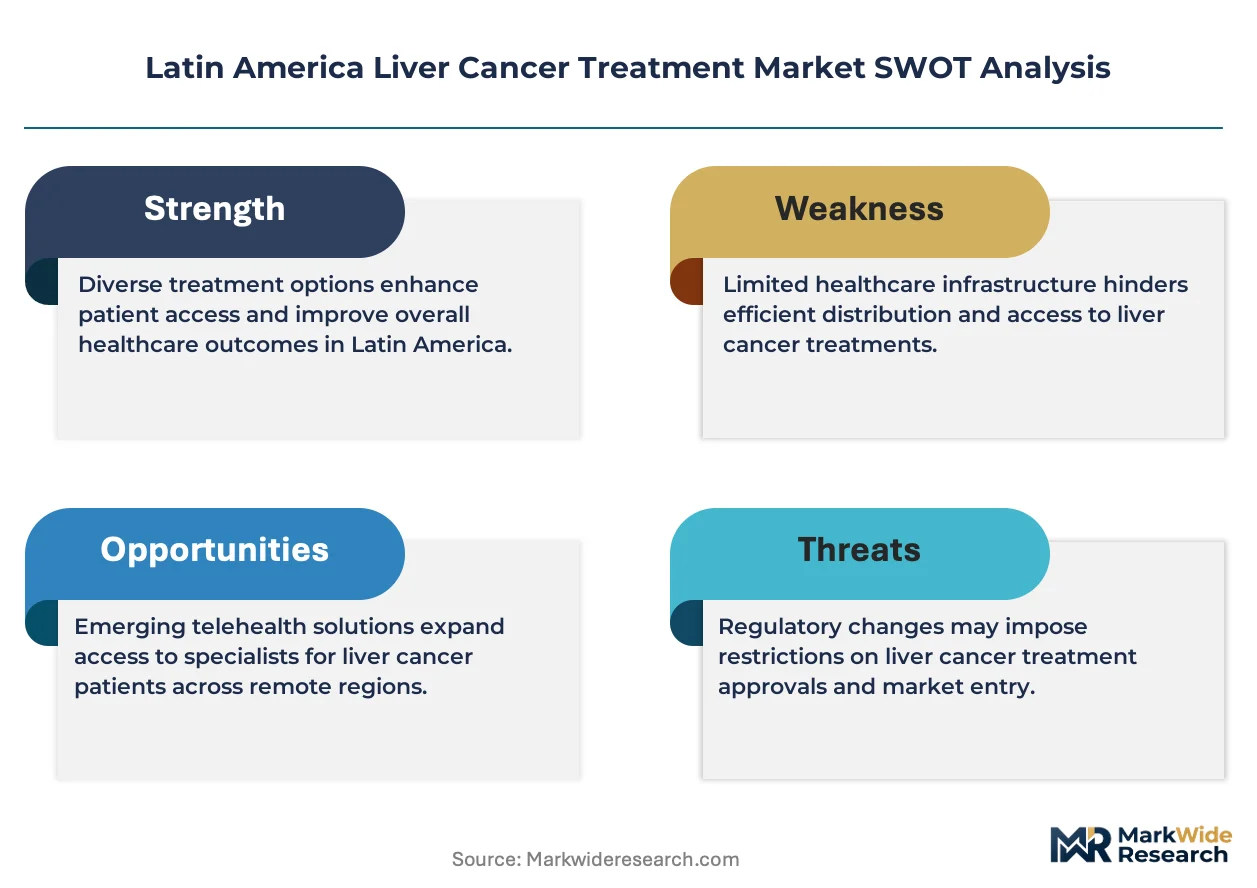
ANVISA in Brazil, COFEPRIS in Mexico, and INVIMA in Colombia each enforce distinct pharmacovigilance and clinical evidence standards that shape market entry timelines and product labeling requirements for oncology therapeutics. These regulatory frameworks create compliance cost barriers that favor manufacturers with established Latin American regulatory affairs capabilities and localized pharmacovigilance infrastructure. Stakeholders must monitor pending biosimilar pathway clarifications and evolving health technology assessment methodologies as these will determine competitive positioning for novel agents entering the region.
Market Dynamics
Modular immunotherapy-chemotherapy combination protocols are restructuring treatment selection criteria across Latin America, as payers and clinicians reassess bundled regimens against standalone alternatives amid evolving reimbursement frameworks.
Growth Catalysts
- ANVISA pathway streamlining:Brazil's national pharmaceutical regulator has compressed oncology drug registration timelines, accelerating market entry for novel hepatocellular carcinoma therapeutics.
- Linear accelerator infrastructure expansion:Stereotactic body radiation therapy capacity is proliferating across Mexican oncology centers, widening access to precision radiation modalities.
- Public reimbursement maturation:Argentina's expanding coverage frameworks for checkpoint inhibitors are pulling immunotherapy demand into the public hospital sector.
Market Restraints
- Biosimilar pathway uncertainty:Pending clarifications from COFEPRIS and ANVISA on substitution protocols create labeling and pharmacovigilance compliance cost barriers for manufacturers.
- Clinical evidence heterogeneity:INVIMA's distinct pharmacovigilance standards in Colombia force redundant trial documentation, extending product launch timelines.
- Tyrosine kinase inhibitor price compression:Generic competition in targeted therapy categories is narrowing margin structures for premium positioning.
Strategic Opportunities
- Colombian market penetration:Underdeveloped immunotherapy access in Bogotá and Medellín oncology networks offers first-mover positioning for PD-1/PD-L1 portfolio expansion.
- Regional trial network integration:Multi-site clinical infrastructure spanning São Paulo, Mexico City, and Buenos Aires enables accelerated patient recruitment for novel agent development.
- Telemedicine-enabled treatment monitoring:Remote patient management platforms are opening distribution channels for oral systemic therapies outside major metropolitan centers.
Industry Challenges
- Hepatology-oncology specialist scarcity:Limited fellowship-trained clinicians in Brazil's interior states constrains Barcelona Clinic Liver Cancer staging protocol implementation.
- Radiofrequency ablation equipment standardization:Fragmented device certification timelines across ANVISA, COFEPRIS, and INVIMA create supply chain reconfiguration friction for capital equipment vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Liver Cancer Treatment Market |
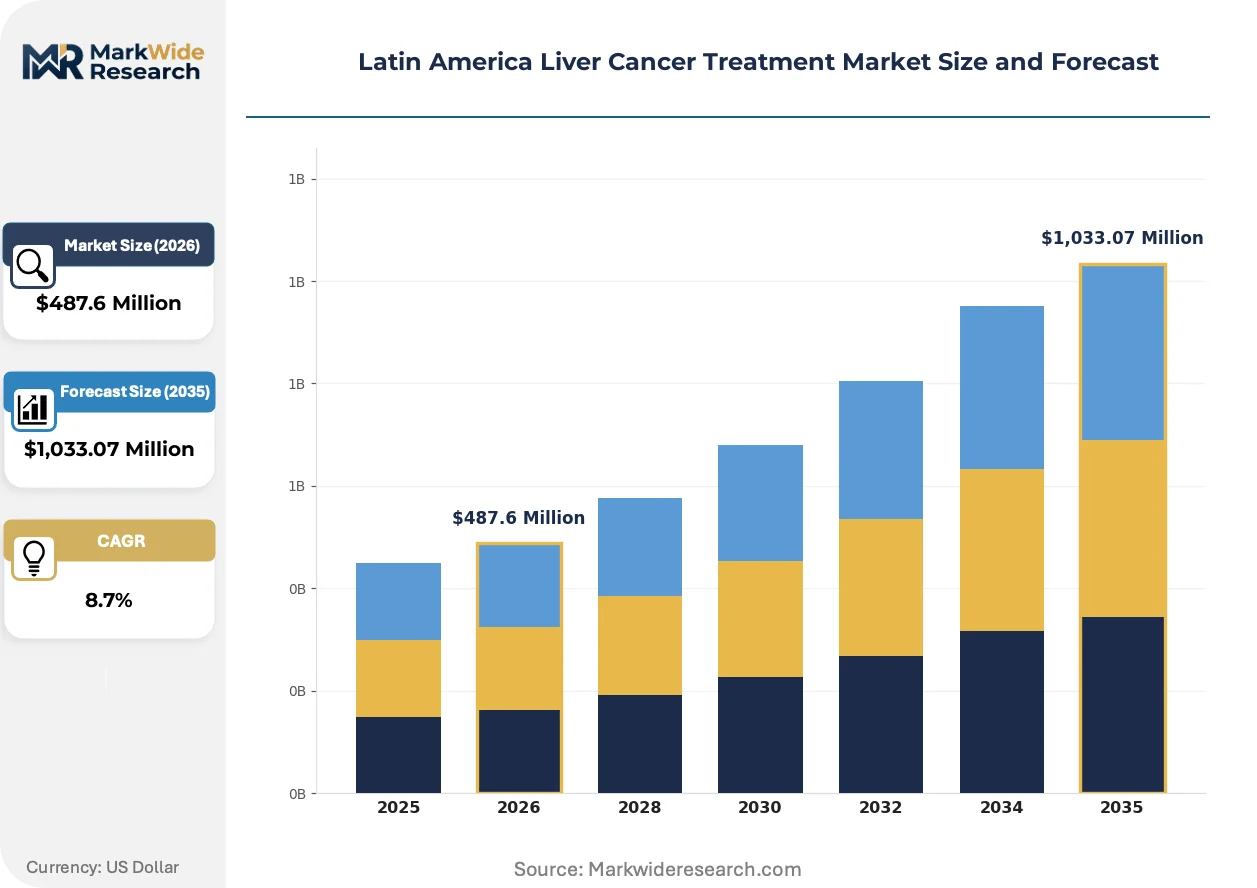
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgery, Chemotherapy, Targeted Therapy, Immunotherapy Delivery Mode: Intravenous, Oral, Intra-arterial, Topical End User: Hospitals, Oncology Clinics, Ambulatory Surgical Centers, Research Institutions Technology: Radiofrequency Ablation, Cryoablation, Microspheres, Stereotactic Body Radiation Therapy |
| Companies Covered | Bayer AG, Bristol-Myers Squibb Company, Merck & Co Inc, Eisai Inc, Exelixis Inc, Alnylam Pharmaceuticals Inc, Eli Lilly And Co, Pfizer Inc, Onyx Pharmaceuticals Inc, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Liver Cancer Treatment Market Shifts & Advancements
Treatment modality convergence is compressing traditional boundaries between systemic therapy and locoregional intervention, with technology and regulatory forces simultaneously expanding access and tightening evidence requirements.
Artificial intelligence-assisted diagnostic imaging is electrifying hepatocellular carcinoma detection protocols across Argentine and Chilean oncology networks. Radiology departments in Buenos Aires academic centers are deploying machine-learning algorithms for early lesion identification at twice conventional screening throughput. This capability compression is enabling stage migration toward resectable disease categories previously captured at advanced Barcelona Clinic Liver Cancer stages.
COFEPRIS in Mexico has implemented accelerated review pathways for breakthrough-designated oncology therapeutics, cutting regulatory review phases by approximately one-third for qualifying agents. This policy shift is redirecting multinational sponsor submission strategies toward Mexico as a Latin American launch priority. Immunotherapy developers are responding by front-loading Mexican pharmacovigilance infrastructure investment ahead of Colombian and Peruvian regulatory filings.
Hospital formulary committees are consolidating purchasing authority for high-cost systemic therapies into centralized pharmacy and therapeutics panels across Brazilian public health networks. This buyer concentration is displacing individual physician preference-based prescribing for hepatocellular carcinoma regimens. The shift is most visible in São Paulo's unified health system districts, where bundled immunotherapy-chemotherapy protocols now dominate tender specifications.
Latin America Liver Cancer Treatment Market Segmentation
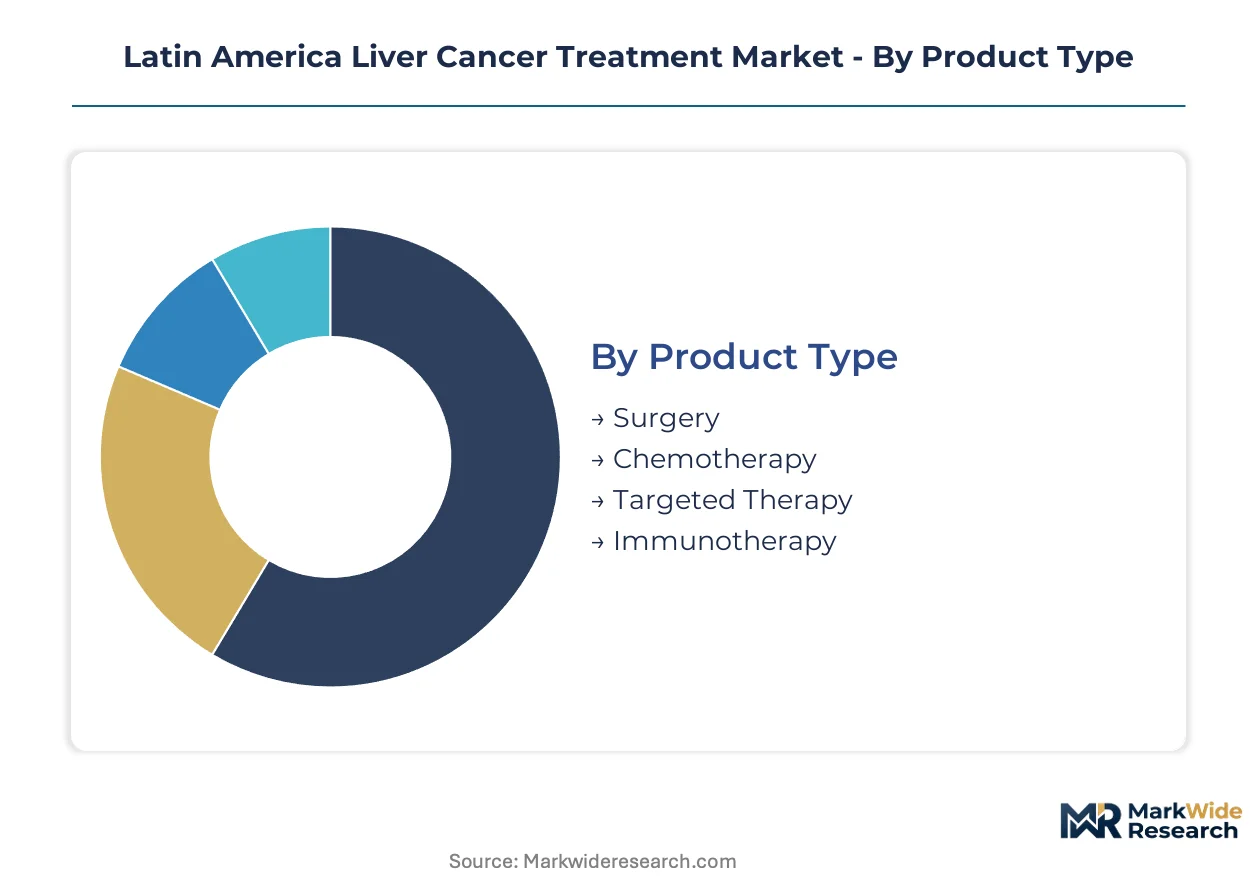
Therapeutic modality selection across Latin America follows Barcelona Clinic Liver Cancer staging protocols, with reimbursement frameworks and infrastructure availability determining which segments capture patient volume in public versus private treatment networks.
Product Type:
Standalone systemic therapies dominate outpatient administration, while embedded surgical and locoregional interventions require integrated hospital infrastructure.
- Surgery:Hepatic resection and liver transplantation procedures demand specialized hepatobiliary surgical teams concentrated in São Paulo, Mexico City, and Buenos Aires academic medical centers. Brazil's Sistema Único de Saúde reimburses transplantation at tertiary hospitals, though donor organ scarcity constrains volume expansion.
- Targeted Therapy:Tyrosine kinase inhibitors including sorafenib and lenvatinib anchor first-line systemic treatment across Latin American hospital formularies. Mexican oncology clinics report sustained demand despite generic price compression, as physician familiarity and established reimbursement codes sustain prescribing patterns.
- Immunotherapy:PD-1/PD-L1 checkpoint inhibitors require cold-chain distribution networks and infusion center capacity.
- Chemotherapy:Cytotoxic regimens persist as backbone therapy in resource-constrained settings.
Targeted therapy leads volumes today; immunotherapy is gaining share fastest.
Delivery Mode:
Cost tier differentiation separates hospital-based administration from take-home oral regimens that reduce facility utilization.
- Intravenous:Infusion-dependent biologics and cytotoxic agents require nursing supervision and adverse event monitoring infrastructure. Brazilian oncology clinics are expanding chair capacity to accommodate rising immunotherapy patient volumes.
- Intra-arterial:Transarterial chemoembolization and radioembolization deliver concentrated drug doses to hepatic tumors while sparing systemic circulation. Colombian interventional radiology departments in Bogotá are building dedicated angiography suites to capture this high-margin segment.
- Oral:Tyrosine kinase inhibitors enable outpatient management but require adherence monitoring programs.
- Topical:Limited applicability in hepatocellular carcinoma; experimental protocols only.
Intravenous administration retains volume leadership; intra-arterial delivery is expanding most quickly.
End User:
Customer type concentration shifts toward centralized purchasing authority as public health systems consolidate procurement.
- Hospitals:Tertiary academic centers in Brazil, Mexico, and Argentina perform complex resections, transplantation, and combination systemic therapy. ANVISA-licensed hospital pharmacies manage high-cost oncology drug distribution under strict chain-of-custody protocols.
- Oncology Clinics:Specialized infusion centers capture stable-stage patient volumes seeking convenience outside hospital settings. São Paulo's private clinic networks are consolidating through acquisition to achieve formulary negotiating scale.
- Ambulatory Surgical Centers:Limited to diagnostic biopsy and minor interventions; restricted by anesthesia and emergency capability requirements.
- Research Institutions:Academic medical centers in Buenos Aires and Mexico City host Phase II/III trials for novel hepatocellular carcinoma agents.
Hospitals dominate value capture; oncology clinics are climbing the fastest.
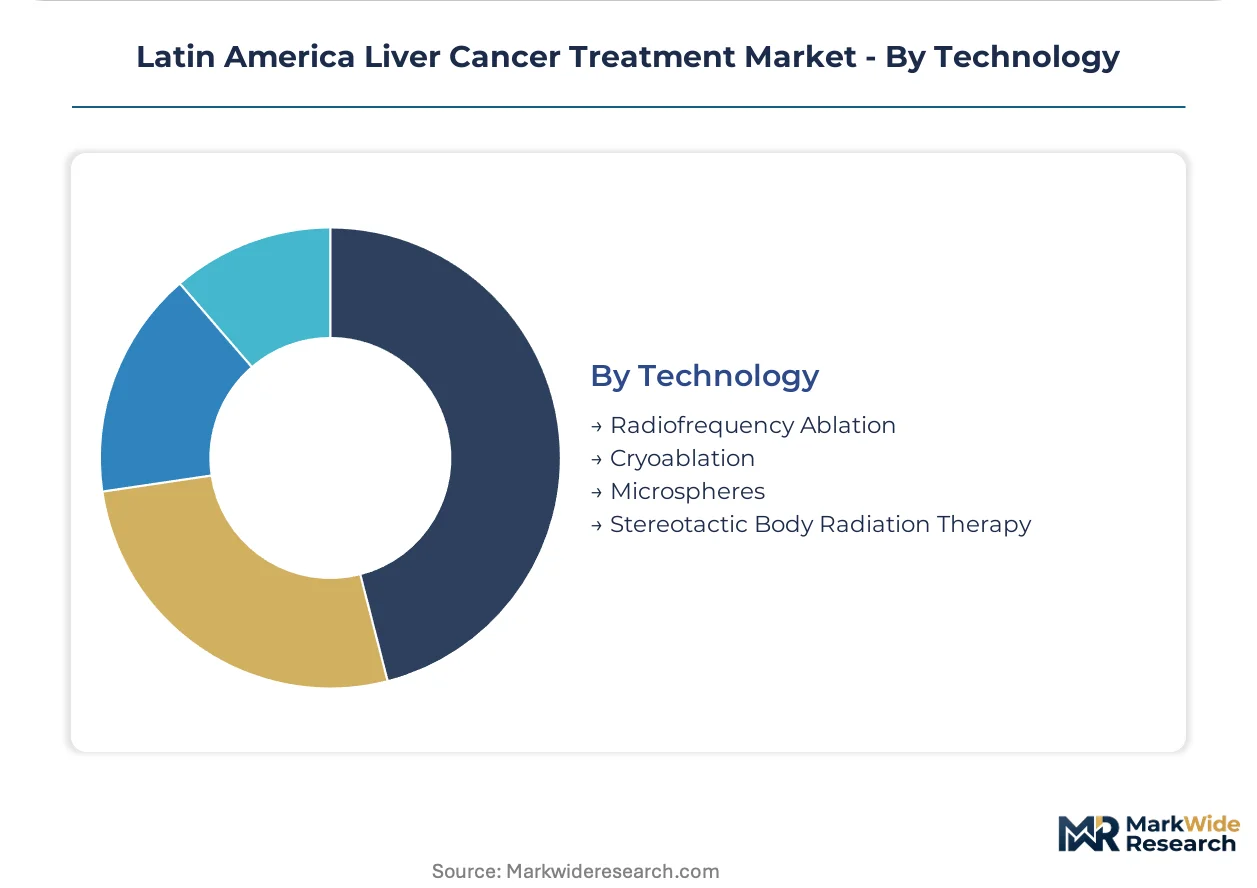
Technology:
Maturity gradients separate established thermal ablation from capital-intensive radiation platforms requiring linear accelerator investment.
- Radiofrequency Ablation:Percutaneous thermal destruction of early-stage lesions using electrode probes. Argentine interventional radiology networks in Córdoba and Rosario maintain high utilization for tumors under three centimeters.
- Stereotactic Body Radiation Therapy:Precision-targeted high-dose fractions delivered via image-guided linear accelerators. Mexican oncology centers are prioritizing CyberKnife and TrueBeam installations to compete for insured patient referrals.
- Cryoablation:Argon-helium probe systems for perivascular lesions where heat-based ablation risks thermal sink effects.
- Microspheres:Yttrium-90 and drug-eluting bead platforms for transarterial delivery.
Radiofrequency ablation retains installed base dominance; stereotactic body radiation therapy shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Liver cancer treatment infrastructure across Latin America traces its modern lineage to the 1990s expansion of hepatobiliary surgery programs in São Paulo and Mexico City academic centers. These institutions established the staging protocols and transplantation networks that subsequently diffused to secondary markets. Today, regulatory harmonization efforts and reimbursement framework maturation are reshaping patient access patterns across five core national markets.
Brazil
ANVISA's streamlined oncology registration pathways and Sistema Único de Saúde transplantation reimbursement sustain treatment volume leadership. São Paulo's tertiary hospital networks concentrate hepatic resection capacity, while interior states face hepatology specialist scarcity that constrains Barcelona Clinic Liver Cancer protocol implementation.
Mexico
COFEPRIS accelerated review pathways for breakthrough-designated therapeutics are redirecting multinational launch sequencing toward Mexico City. Linear accelerator infrastructure expansion across Nuevo León and Jalisco oncology centers is widening stereotactic body radiation therapy access for insured patient segments.
Argentina
Expanding public reimbursement frameworks for checkpoint inhibitors are pulling immunotherapy demand from private clinics into hospital formularies. Buenos Aires academic radiology departments deploy artificial intelligence-assisted imaging for early lesion detection, enabling stage migration toward resectable disease categories.
Colombia
INVIMA's distinct pharmacovigilance standards create compliance cost barriers that extend product launch timelines relative to regional peers. Bogotá and Medellín interventional radiology departments are building dedicated angiography suites to capture transarterial chemoembolization volume, though immunotherapy access remains underdeveloped.
Chile
Machine-learning diagnostic deployment in Santiago oncology networks supports screening throughput expansion. The country's centralized health system procurement structure concentrates purchasing authority for high-cost systemic therapies, displacing individual physician preference-based prescribing patterns.
Latin America Liver Cancer Treatment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory affairs capabilities and pharmacovigilance infrastructure depth. The vendor base organizes into three tiers: multinational pharmaceutical conglomerates with established Latin American regulatory affairs capabilities, biotechnology specialists pursuing regional trial network integration, and generic manufacturers competing on tyrosine kinase inhibitor price compression. Consolidation pressure is intensifying through hospital formulary committee centralization and bundled protocol tender specifications. Geographic expansion and localized pharmacovigilance infrastructure investment represent the dominant competitive moves.
Among Germany-based diversified pharmaceutical conglomerates, Bayer AG anchors the hepatocellular carcinoma portfolio tier through established market presence in Brazil and Mexico. Bristol-Myers Squibb Company and Merck & Co Inc occupy positions within the checkpoint inhibitor specialization archetype, with the former competing through PD-1/PD-L1 portfolio development and the latter sustaining regional trial network infrastructure. These three entities exemplify the regulatory affairs capability differentiation that separates premium-margin positioning from commodity-tier competition.
| Leading Market Players |
|---|
| Bayer AG |
| Bristol-Myers Squibb Company |
| Merck & Co Inc |
| Eisai Inc |
| Exelixis Inc |
| Alnylam Pharmaceuticals Inc |
| Eli Lilly And Co |
| Pfizer Inc |
| Onyx Pharmaceuticals Inc |
| Others |
Supply & Pricing Matrix
Brazilian hospital formulary committee centralization into unified pharmacy and therapeutics panels is compressing procurement discretion for hepatocellular carcinoma therapies, forcing manufacturers toward bundled protocol tenders and volume-based contracting that narrows margin structures for standalone agents.
Pricing Analysis
Three-tier pricing structure across premium immunotherapy, standard targeted therapy, and economy cytotoxic levels governs Latin American hospital procurement. Price differentiation separates checkpoint inhibitors requiring cold-chain infrastructure from generic tyrosine kinase inhibitors facing COFEPRIS and ANVISA biosimilar pathway pressure. Cost compression in the targeted therapy tier is intensifying because of lenvatinib and sorafenib generic entry. Public hospital systems exhibit highest price sensitivity; private oncology clinics in São Paulo and Mexico City demonstrate lowest sensitivity to infusion-based biologic premiums.
Supply Chain Analysis
Checkpoint inhibitor supply rests on North American and European biologics manufacturing, with cold-chain distribution feeding Brazilian and Mexican infusion centers. Active pharmaceutical ingredients for tyrosine kinase inhibitors draw from Indian and Chinese specialty chemical producers. Single-source vulnerability concentrates in monoclonal antibody fill-finish capacity. Distribution runs through ANVISA-licensed hospital pharmacies managing chain-of-custody protocols for high-cost oncology drugs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as Barcelona Clinic Liver Cancer staging protocol maturation pulls patient identification toward resectable and intermediate-stage categories amenable to higher-value combination regimens.
For Market Incumbents: Hedge against biosimilar pathway clarifications from COFEPRIS and ANVISA by deepening localized pharmacovigilance infrastructure ahead of competitors. Anchor formulary positioning through bundled immunotherapy-chemotherapy protocol tenders that displace standalone prescribing. Prioritize backward integration into regional trial networks spanning São Paulo, Mexico City, and Buenos Aires to accelerate novel agent development timelines. For New Entrants and Emerging Players: The mid-tier price-point gap between premium checkpoint inhibitors and economy cytotoxic regimens creates entry space for oral targeted therapy alternatives with streamlined adherence monitoring. Colombian immunotherapy access underdevelopment in Bogotá and Medellín oncology networks offers first-mover positioning for PD-1/PD-L1 portfolio expansion. Target telemedicine-enabled distribution channels for oral systemic therapies outside major metropolitan centers. For Investors and Strategic Acquirers: Asymmetric upside sits with biotechnology specialists possessing regional trial network integration capabilities and established INVIMA regulatory affairs expertise. Long-term viability over the next decade hinges on pharmacovigilance infrastructure depth rather than manufacturing scale alone. Watch ANVISA and COFEPRIS biosimilar substitution protocol clarifications as the inflection signal determining competitive positioning stability.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Trial Network Integration | Multi-site infrastructure across São Paulo, Mexico City, and Buenos Aires accelerates novel hepatocellular carcinoma agent patient recruitment. |
| Localized Pharmacovigilance Investment | ANVISA, COFEPRIS, and INVIMA compliance capabilities compress oncology therapeutic launch timelines relative to competitors. |
| Linear Accelerator Infrastructure Expansion | CyberKnife and TrueBeam installations in Mexican oncology centers capture stereotactic body radiation therapy referrals from insured segments. |
| Bundled Protocol Tender Positioning | Immunotherapy-chemotherapy combination specifications in Brazilian Sistema Único de Saúde procurement displace standalone regimen prescribing. |
| Telemedicine-Enabled Distribution | Remote patient management platforms extend oral tyrosine kinase inhibitor reach beyond São Paulo and Mexico City metropolitan clusters. |
Research Methodology
Bottom-up hospital and oncology clinic demand modeling reconciled against top-down pharmaceutical manufacturer supply tracking forms the analytical core of this study. Primary interviews with hepatobiliary surgeons, oncology formulary directors, ANVISA regulatory affairs leads, and hospital procurement managers combined with secondary validation against ANVISA registration databases, COFEPRIS approval filings, ClinicalTrials.gov protocol records, and Latin American hospital procurement tender documents. Triangulation between patient volume estimates from Barcelona Clinic Liver Cancer staging protocol implementation and manufacturer-reported distribution volumes ensures consistency.
Historical treatment modality adoption curves across surgery, targeted therapy, immunotherapy, and radiation segments inform the projection framework. Segmentation dimensions span therapeutic modality, delivery mode, end-user facility type, and technology platform across the analysis window. CAGRs derive from regression analysis against staging protocol penetration rates, reimbursement framework maturation indicators, and linear accelerator infrastructure installation trajectories. Forecast inputs incorporate ANVISA pathway streamlining impact assumptions and checkpoint inhibitor public reimbursement expansion patterns.
Caveats apply where biosimilar pathway clarifications from COFEPRIS or ANVISA, hepatology-oncology specialist training pipeline constraints in Brazil's interior states, or transarterial chemoembolization equipment certification timeline harmonization failures could materially shift the outlook. A small set of named triggers—regulatory substitution protocols, fellowship program expansion rates, and angiography suite buildout completion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Liver Metastases Treatment Market
Specialty Medicine
Middle East and Africa Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Nonerosive Reflux Disease Treatment Market
Specialty Medicine
Carcinoid Tumor Syndrome Management Market
Specialty Medicine
Thyroid Cancer Therapeutics Market
Specialty Medicine
Hashimoto's Thyroiditis Therapeutics Market
Specialty Medicine
Spinal and Bulbar Muscular Atrophy Treatment Market
Specialty Medicine
Narcolepsy Market
Specialty Medicine
Microcephaly Market
Specialty Medicine
Ulcerative Colitis Therapeutics Market
Specialty Medicine
Wet Age-Related Macular Degeneration (Wet AMD) Market
Specialty Medicine
Primary Sclerosing Cholangitis Treatment Market
Specialty Medicine
Immunoglobulin (Igg) Replacement Therapy Market
Specialty Medicine
Whim Syndrome Management Market
Specialty Medicine
Global Nephropathic Cystinosis Treatment Market
Specialty Medicine
Toxic Epidermal Neurolysis Market