
 Global Melanoma Diagnostics and Therapeutics Market | 2026-2036
Global Melanoma Diagnostics and Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Melanoma Diagnostics and Therapeutics Market Foresight
The capability gap between integrated molecular diagnostic platforms and conventional histopathology workflows is redrawing competitive boundaries across the melanoma care continuum. Bristol-Myers Squibb leverages its immuno-oncology franchise to anchor combination therapy development in checkpoint modulation. Amgen specializes in targeted pathway inhibition, competing through precision biomarker alignment with companion diagnostic partners. Thermo Fisher Scientific controls the upstream reagent and instrument ecosystem, extending its position into clinical NGS laboratory services.
Melanoma diagnostics and therapeutics encompass molecular and histopathological methods for detecting cutaneous malignancies alongside pharmacologic and surgical interventions designed to interrupt oncogenic signaling and immune evasion. Diagnostic imaging and next-generation sequencing platforms detect BRAF V600 mutations and PD-L1 expression status, guiding therapeutic selection. Immunotherapy occupies the dominant revenue position among product types, while diagnostic laboratories represent the fastest-growing end-user channel as decentralized molecular testing expands. Cancer institutes sustain premium pricing power through integrated tumor board decision frameworks that bundle genomic profiling with treatment planning.
The FDA accelerates market entry through breakthrough therapy and priority review designations, while the EMA's centralized marketing authorization process shapes commercial sequencing across European member states. ISO 15189 accreditation requirements for molecular diagnostic laboratories constrain market access for non-compliant testing facilities. Stakeholders must monitor evolving reimbursement policies for liquid biopsy applications as payers reassess coverage criteria for minimal residual disease monitoring in adjuvant settings.
Market Dynamics
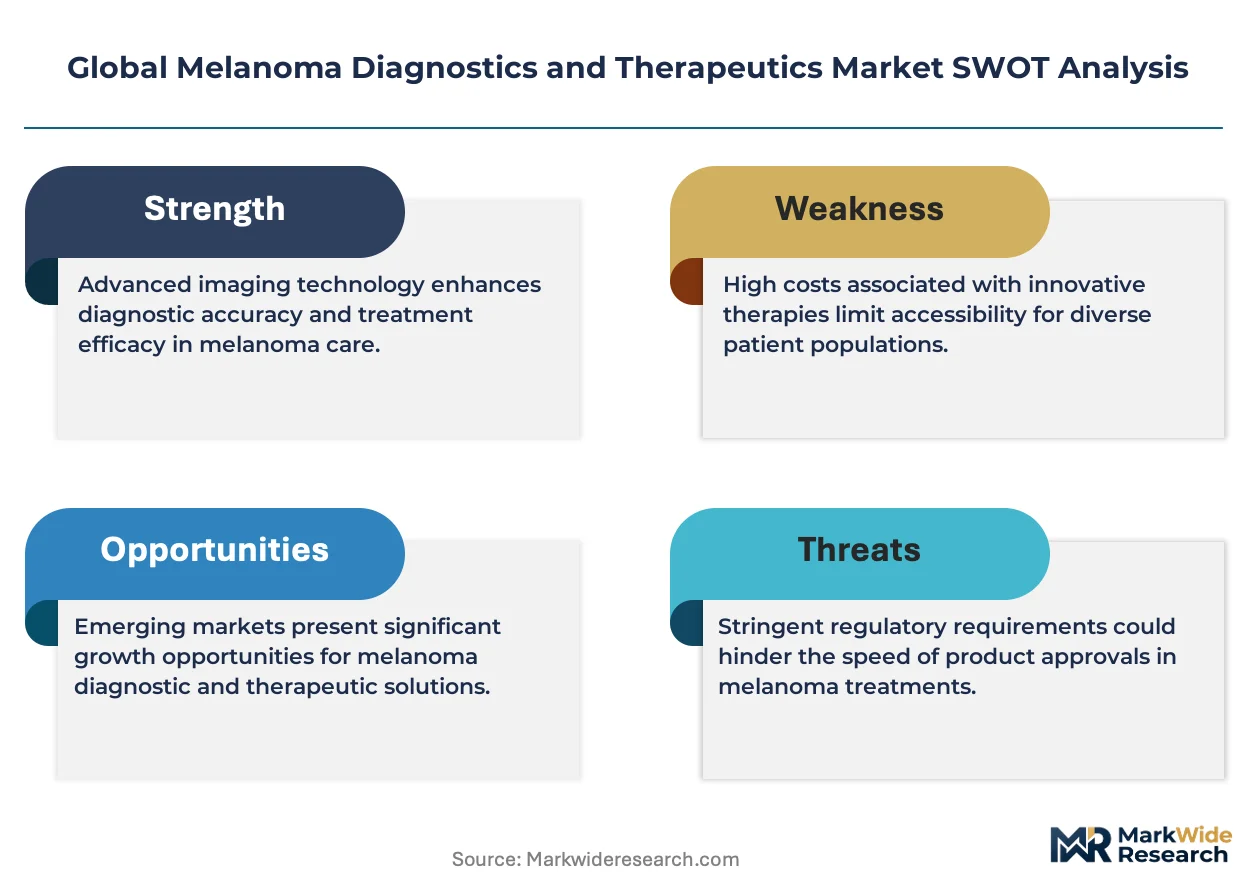
The convergence of liquid biopsy technologies with real-time genomic surveillance is collapsing the traditional staging-treatment gap across melanoma care pathways. This structural compression forces diagnostic laboratories and oncology departments into tighter operational coupling than histopathology workflows previously required.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Accelerated approval pathways compress clinical trial timelines for combination immunotherapies, pulling forward revenue recognition for developers of PD-1/CTLA-4 regimens.
- Medicare Coverage Expansion:Companion diagnostic reimbursement policies in the United States now bundle molecular profiling with targeted therapy administration, removing prior authorization friction for BRAF testing.
- Decentralized NGS Platforms:Hospital-based laboratories deploy point-of-care sequencing instruments, shifting specimen volume from centralized reference labs toward integrated health systems.
Market Restraints
- Reagent Supply Concentration:Thermo Fisher Scientific and Illumina control critical sequencing chemistry and flowcell manufacturing, creating single-source dependency for high-throughput diagnostic facilities.
- EMA Centralized Authorization Delays:The European Medicines Agency's marketing authorization process imposes 12-18 month lag versus FDA timelines, compressing commercial runway before patent expiry.
- FFPE Tissue Degradation:Formalin-fixed paraffin-embedded specimens yield suboptimal nucleic acid quality in 15-20% of community pathology submissions, forcing repeat biopsies and diagnostic delays.
Strategic Opportunities
- Minimal Residual Disease Monitoring:Circulating tumor DNA assays for adjuvant therapy surveillance represent reimbursement white space as private payers evaluate coverage criteria for relapse prediction.
- Japan's Sakigake Designation:Japan's PMDA offers priority review for innovative oncology diagnostics, creating regulatory fast-track for companies validating ctDNA platforms in Asian populations.
- AI-Augmented Histopathology:Deep learning algorithms for melanocytic lesion classification converge with whole-slide imaging systems, enabling pathologist workflow automation in high-volume dermatopathology practices.
Industry Challenges
- Bioinformatics Pipeline Validation:Clinical laboratories face ISO 15189 accreditation requirements for variant interpretation workflows, demanding specialized computational pathology expertise that outstamps current training pipelines.
- Cross-Platform Assay Harmonization:Discordant PD-L1 scoring between 22C3, 28-8, and SP142 antibody clones forces laboratories to maintain multiple immunohistochemistry protocols, inflating operational complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Melanoma Diagnostics and Therapeutics Market |
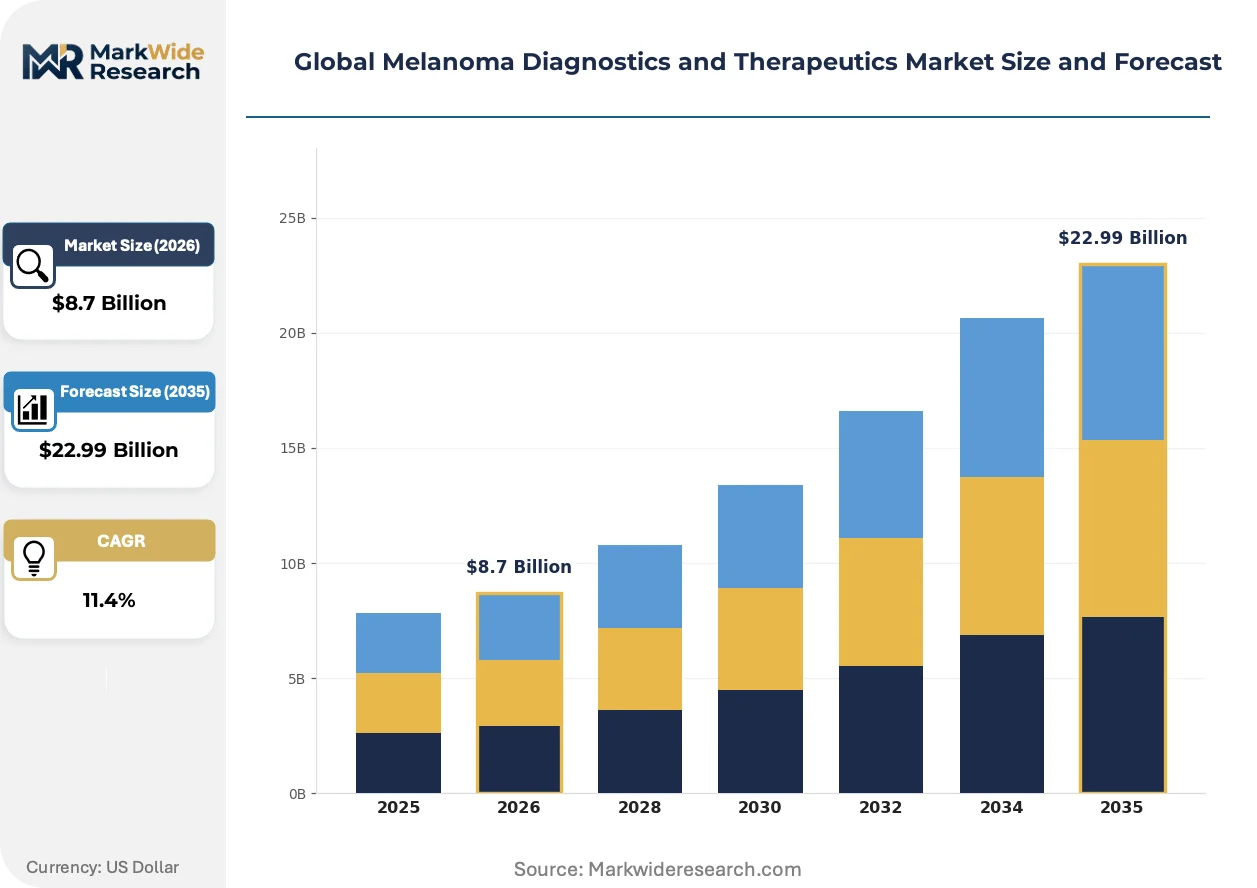
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunotherapy, Targeted Therapy, Chemotherapy, Diagnostic Imaging, Surgical Instruments Application: Early Detection, Treatment Monitoring, Recurrence Assessment, Risk Stratification, Prognostic Evaluation End User: Specialty Clinics, Diagnostic Laboratories, Cancer Institutes, Research Centers, Physician Offices Technology: Polymerase Chain Reaction, Immunohistochemistry, Digital Dermoscopy, Next-Generation Sequencing, Fluorescence In Situ Hybridization |
| Companies Covered | Abbott Laboratories, Amgen, Bristol-Myers Squibb, Novartis, F. Hoffmann-La Roche, Merck & Co., AstraZeneca, Pfizer, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Melanoma Diagnostics and Therapeutics Market Shifts & Advancements
Liquid biopsy platforms are fragmenting the tissue-centric diagnostic paradigm, enabling serial molecular monitoring without invasive sampling. This shift reconfigures stakeholder economics across pharmaceutical, diagnostic, and clinical service boundaries.
Multiplexed circulating tumor DNA panels are decomposing the single-gene testing model that dominated melanoma molecular profiling through 2020. Community oncology practices adopt these platforms within 18-24 months of analytical validation, compressing referral volumes to academic molecular pathology centers. The technology is decomposing traditional revenue pools for centralized reference laboratories while enabling pharmaceutical sponsors to enrich clinical trials with real-time resistance monitoring.
The EMA's In Vitro Diagnostic Medical Devices Regulation imposes notified body oversight on companion diagnostic conformity assessments, elevating documentation burdens for CE-marked assays. Manufacturers must maintain post-market surveillance systems capturing device performance across diverse European laboratory environments. High-complexity NGS-based tests face 18-month certification timelines, disadvantaging smaller diagnostic developers against established platform holders.
Integrated tumor board procurement now bundles genomic profiling with treatment authorization, collapsing separate diagnostic and therapeutic purchasing decisions. Cancer institutes in Germany and the Netherlands negotiate combined contracts with molecular diagnostic providers and pharmaceutical manufacturers. This consolidation is most visible in university hospital networks where pathology departments report directly to oncology service lines rather than independent diagnostic divisions.
Global Melanoma Diagnostics and Therapeutics Market Segmentation
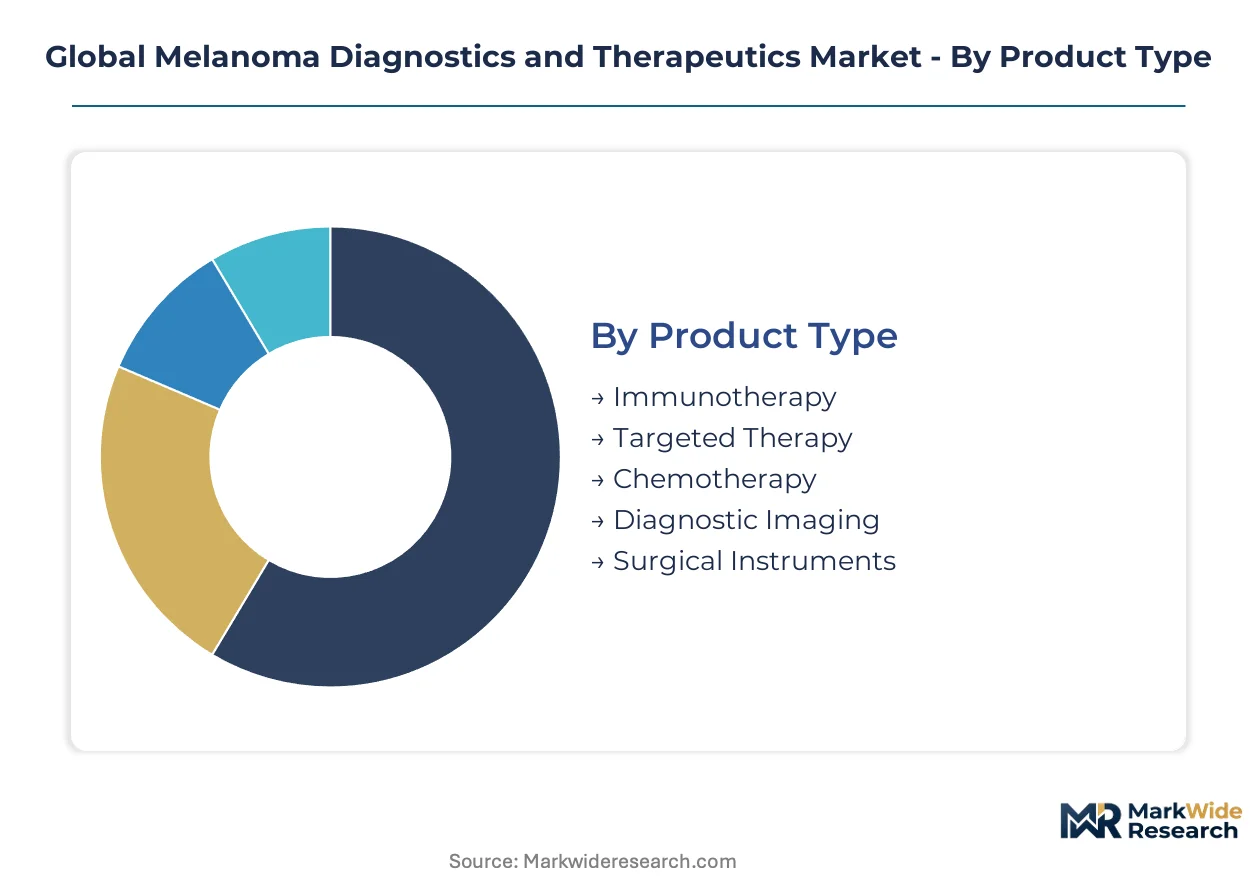
Molecular stratification of melanoma patients creates distinct revenue pools across diagnostic modalities and therapeutic classes. Pharmaceutical and diagnostic companies allocate R&D budgets based on segment-specific reimbursement dynamics and clinical trial enrollment feasibility.
Product Type:
Premium pricing power concentrates in biologics with companion diagnostic requirements, while hardware-dependent segments compete on capital equipment financing terms.
- Immunotherapy:Checkpoint inhibitors targeting PD-1 and CTLA-4 pathways command the highest per-patient revenue in melanoma care. United States oncology practices drive demand concentration as Medicare reimbursement policies bundle these agents with molecular profiling.
- Targeted Therapy:BRAF and MEK inhibitor combinations deliver precision intervention for mutation-positive patients. German cancer institutes represent a concentrated demand node due to integrated tumor board procurement frameworks that link diagnostic authorization to therapy selection.
- Chemotherapy:Cytotoxic agents retain niche utility in refractory cases with limited alternative options.
- Diagnostic Imaging:Advanced dermoscopy and confocal microscopy systems support non-invasive lesion characterization.
- Surgical Instruments:Mohs surgery tools and sentinel lymph node biopsy kits serve curative-intent resection protocols.
The dominant share belongs to Immunotherapy, while Targeted Therapy is closing the gap fastest.
Application:
Clinical utility and reimbursement coverage diverge sharply between curative-stage and surveillance-stage applications.
- Early Detection:Population-based screening programs and high-risk patient surveillance generate volume demand for dermoscopy and molecular assays. Australia's national skin cancer screening infrastructure creates concentrated procurement for automated lesion analysis platforms.
- Treatment Monitoring:Serial imaging and circulating tumor DNA surveillance track therapeutic response during active intervention. Japanese oncology networks are expanding adoption of liquid biopsy monitoring under PMDA Sakigake fast-track designations.
- Recurrence Assessment:Post-treatment surveillance protocols rely on combined imaging and biomarker strategies.
- Risk Stratification:Genomic classifiers guide adjuvant therapy decisions based on recurrence probability scores.
- Prognostic Evaluation:Integrated molecular and histopathologic scoring systems inform long-term outcome prediction.
Treatment Monitoring captures expanding reimbursement attention, though Early Detection maintains the volume base.
End User:
Procurement authority and technical capability determine segment access for diagnostic platform vendors.
- Specialty Clinics:Dermatology-focused practices integrate dermoscopy with biopsy referral workflows. United States dermatopathology groups in Florida and California represent high-volume specimen sources for molecular send-out testing.
- Diagnostic Laboratories:Centralized reference labs and hospital-based molecular pathology units process complex NGS panels. Academic medical centers in the Netherlands deploy automated variant interpretation pipelines under ISO 15189 accreditation frameworks.
- Cancer Institutes:Comprehensive cancer centers bundle genomic profiling with clinical trial access.
- Research Centers:Translational oncology programs drive demand for exploratory biomarker discovery platforms.
- Physician Offices:Community dermatology practices represent the lowest-complexity diagnostic tier with limited in-house molecular capability.
Diagnostic Laboratories command the highest per-account value, while Specialty Clinics are expanding molecular service lines most aggressively.
Technology:
Capital intensity and regulatory burden vary dramatically across analytical modalities.
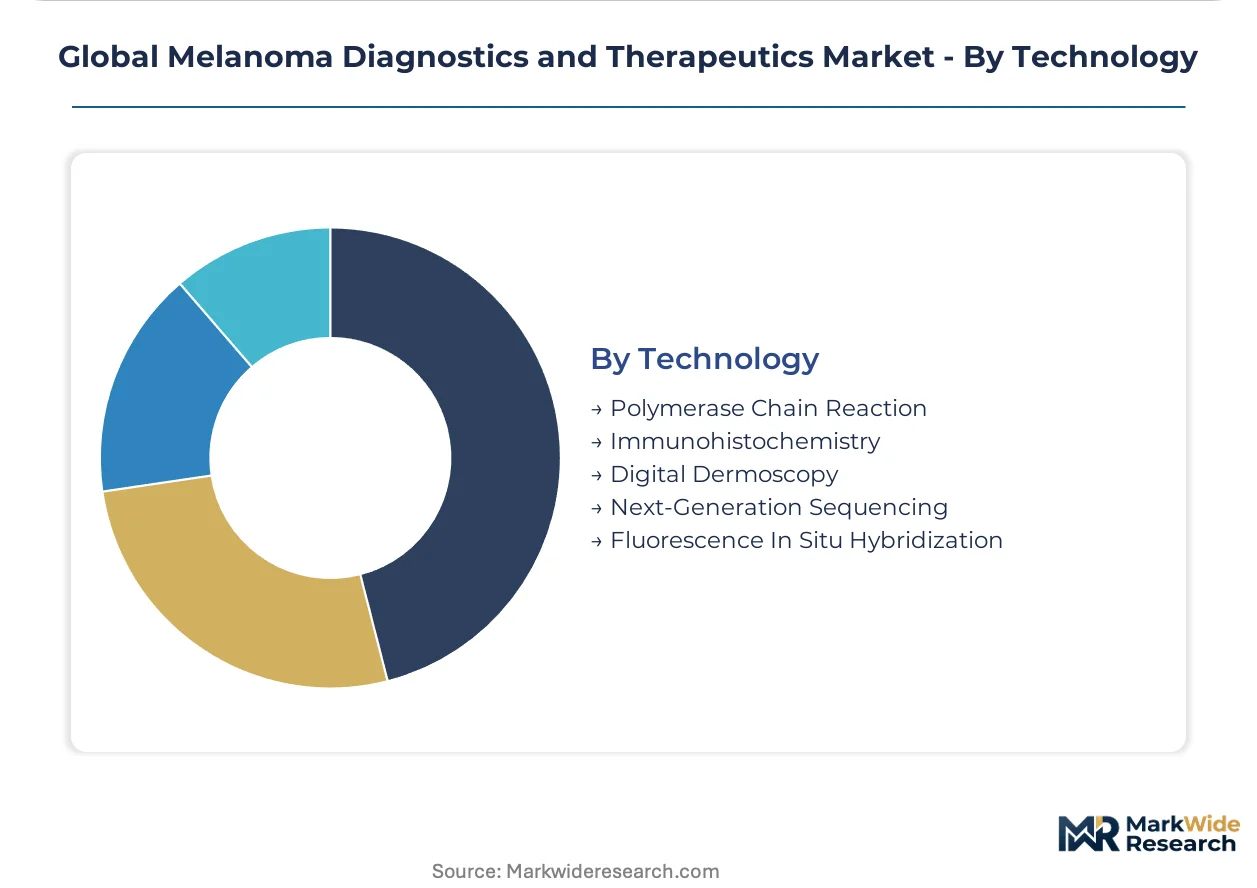
- Next-Generation Sequencing:Comprehensive genomic profiling platforms detect actionable mutations across BRAF, NRAS, and KIT loci simultaneously. Thermo Fisher Scientific and Illumina instrument placements in United States health systems are displacing single-gene PCR workflows.
- Immunohistochemistry:PD-L1 expression scoring and melanocytic marker panels remain essential for histopathologic diagnosis. European pathology laboratories face operational complexity from multiple antibody clone requirements under IVDR conformity assessment timelines.
- Polymerase Chain Reaction:Rapid BRAF V600 mutation testing supports same-day treatment decisions.
- Digital Dermoscopy:AI-augmented image analysis platforms automate lesion classification in high-volume screening settings.
- Fluorescence In Situ Hybridization:Chromosomal aberration detection aids ambiguous melanocytic lesion classification.
Next-Generation Sequencing anchors platform consolidation strategies, with Digital Dermoscopy expanding fastest into community screening workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a substantial trade surplus in melanoma therapeutics through biologics exports, while diagnostic instrument imports from European and Asian manufacturers shape domestic laboratory infrastructure. Germany and Japan anchor precision diagnostic equipment production, with Switzerland specializing in oncology biologics manufacturing for global distribution.
United States
Medicare reimbursement expansion for companion diagnostics and breakthrough therapy designations from the FDA accelerate commercialization timelines for combination immunotherapies. The Centers for Medicare & Medicaid Services now bundles molecular profiling with targeted therapy administration, removing prior authorization barriers. Boston and San Francisco biotech clusters concentrate clinical trial enrollment and translational research infrastructure.
Germany
Integrated tumor board procurement frameworks at university hospital networks bundle genomic profiling with treatment authorization, collapsing separate purchasing decisions. The EMA's centralized marketing authorization process shapes commercial sequencing timelines across European member states. Heidelberg and Munich cancer institutes deploy automated variant interpretation pipelines under ISO 15189 accreditation requirements.
Japan
PMDA Sakigake fast-track designations prioritize review for innovative oncology diagnostics, accelerating ctDNA platform validation in Asian populations. METI funding programs support precision medicine infrastructure development at designated core hospitals. Tokyo and Osaka oncology networks are expanding liquid biopsy monitoring adoption for adjuvant therapy surveillance.
Australia
National skin cancer screening infrastructure generates concentrated procurement demand for automated lesion analysis platforms and dermoscopy systems. The Therapeutic Goods Administration aligns with FDA breakthrough pathways for priority device reviews. Sydney and Melbourne dermatopathology groups represent high-volume specimen sources for molecular send-out testing.
Switzerland
Swissmedic marketing authorizations for oncology biologics leverage parallel EMA assessments, streamlining European commercial access. The country's pharmaceutical manufacturing base specializes in high-value biologics production for global export. Basel and Zurich clusters anchor precision oncology research and companion diagnostic co-development partnerships.
Global Melanoma Diagnostics and Therapeutics Market Competitive Landscape
Concentration sits with integrated pharmaceutical-diagnostic conglomerates and specialized immuno-oncology developers. The vendor base stratifies across three tiers: global biopharmaceutical majors with companion diagnostic partnerships, precision medicine platform specialists, and molecular diagnostic instrument manufacturers. Two dominant competitive moves define current positioning: backward integration into sequencing chemistry supply chains, and strategic alliances between therapy developers and liquid biopsy platform companies.
Among integrated biopharmaceutical developers, Bristol-Myers Squibb, Amgen, and Novartis exemplify distinct archetype strategies. Bristol-Myers Squibb occupies a position anchoring combination therapy development through checkpoint modulation franchises. Amgen represents targeted pathway inhibition specialization with precision biomarker alignment. Novartis sits within the targeted therapy tier through BRAF and MEK inhibitor portfolio concentration. Thermo Fisher Scientific anchors the upstream reagent and instrument ecosystem, extending control into clinical NGS laboratory services.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Amgen |
| Bristol-Myers Squibb |
| Novartis |
| F. Hoffmann-La Roche |
| Merck & Co. |
| AstraZeneca |
| Pfizer |
| Thermo Fisher Scientific |
| Others |
Supply & Pricing Matrix
Ninety-day reagent inventory cycles at United States hospital laboratories concentrate purchasing leverage with Thermo Fisher Scientific and Illumina, compressing margin negotiation space for mid-tier diagnostic developers while amplifying price premiums for ISO 15189-accredited testing services.
Pricing Analysis
The customization-premium spread between configured-to-order companion diagnostic panels and standard BRAF single-gene assays runs wide across the United States and German markets. Three-tier pricing structure across premium, standard, and economy levels dominates, with premium tiers capturing FDA breakthrough-designated assay bundles and economy tiers serving community pathology overflow. Price differentiation hinges on CE-IVDR certification status and vertical integration depth in sequencing chemistry manufacturing. Pricing pressure stems from Medicare reimbursement compression for liquid biopsy applications, forcing margin recapture through higher-complexity NGS panel bundling. Community oncology practices exhibit acute price sensitivity, while comprehensive cancer centers prioritize analytical validity over per-test cost.
Supply Chain Analysis
The ninety-day inventory observation reveals critical vulnerability in flowcell and sequencing reagent availability, with hospital laboratories maintaining buffer stocks against supply interruptions. Manufacturing concentrates in the United States, Germany, and Japan for precision diagnostic instruments, while reagent production draws from Singapore and Ireland contract facilities. Raw material dependencies center on semiconductor-grade silicon for flowcell substrates, fluorophore chemistry for detection systems, and recombinant polymerases for amplification protocols. Single-source vulnerability in next-generation sequencing instrument platforms creates lock-in risk for clinical laboratories. Distribution runs through authorized distributor networks for capital equipment, with consumables flowing via direct-to-laboratory contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized computational pathology expertise for variant interpretation pipelines remains scarce relative to expanding ISO 15189 accreditation requirements, constraining laboratory capacity expansion and amplifying acquisition premiums for qualified bioinformatics teams.
For Market Incumbents: Secure captive supply of sequencing reagents through backward integration into fluorophore chemistry manufacturing, insulating margin structures against Thermo Fisher Scientific pricing leverage. Lock in exclusive companion diagnostic co-development partnerships with emerging immuno-oncology developers before FDA breakthrough designation filings, preempting competitive positioning for combination therapy trials. For New Entrants and Emerging Players: Lead with AI-augmented histopathology platforms targeting high-volume dermatopathology practices in Florida and California, where pathologist workflow automation commands immediate operational savings. Capture the minimal residual disease monitoring white space in adjuvant therapy surveillance, where private payer coverage criteria remain unsettled and first-mover analytical validation secures preferred network status. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because diagnostic laboratories and oncology service lines are collapsing separate purchasing decisions into integrated tumor board procurement frameworks. Target acquisition candidates with ISO 15189-accredited variant interpretation pipelines and existing pharmaceutical co-development contracts. Watch for inflection in Medicare reimbursement determinations for circulating tumor DNA assays in minimal residual disease monitoring.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development Partnership | FDA breakthrough therapy designation pathways compress timelines for PD-1/CTLA-4 regimen developers. |
| ISO 15189 Accreditation Investment | European IVDR conformity assessments elevate documentation burdens for CE-marked assay manufacturers. |
| Liquid Biopsy Platform Validation | PMDA Sakigake fast-track designations accelerate ctDNA adoption in Japanese oncology networks. |
| AI-Augmented Histopathology Deployment | Deep learning algorithms for melanocytic lesion classification automate pathologist workflows in high-volume practices. |
| Integrated Tumor Board Procurement Contract | German and Dutch university hospital networks bundle genomic profiling with treatment authorization decisions. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the melanoma care continuum, including molecular pathology laboratory directors, oncology service line administrators, regulatory affairs specialists at diagnostic manufacturers, and reimbursement strategy leads at pharmaceutical developers. Secondary validation drew from FDA 510(k) and PMA filings, EMA centralized marketing authorization assessments, ClinicalTrials.gov protocol registries, and CMS Medicare coverage determinations. Bottom-up patient-flow modeling and top-down therapeutic market sizing were triangulated against hospital procurement database extracts.
Across the analysis window, the analytical framework modeled revenue trajectories by product type, application stage, end-user channel, and technology platform, with regional regulatory clusters treated as distinct adoption environments. CAGRs were derived from segment-level enrollment velocity in clinical trials, reimbursement policy shift probabilities, and instrument placement pipelines reported by sequencing platform manufacturers. Forecast inputs incorporated companion diagnostic co-approval timelines and liquid biopsy analytical validation milestones.
Forecasts assume regulatory continuity in FDA breakthrough therapy pathways and EMA centralized authorization procedures; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Eisenmenger Complex Management Market
Specialty Medicine
Whim Syndrome Management Market
Specialty Medicine
Global Allergy Vaccine Market
Specialty Medicine
Healthcare Specialty Enzymes Market
Specialty Medicine
Eosinophilia Therapeutics Market
Specialty Medicine
Disruptive Behavior Disorder (DBD) Treatment Market
Specialty Medicine
Kaposi Sarcoma Market
Specialty Medicine
Factor V Leiden Thrombophilia Treatment Market
Specialty Medicine
Abetalipoproteinemia Management Market
Specialty Medicine
CARD9 Deficiency Treatment Market
Specialty Medicine
Bipolar Disorders Treatment Market
Specialty Medicine
Gastritis Market
Specialty Medicine
Progressive Multifocal Leukoencephalopathy Treatment Market
Specialty Medicine
Nasal Polyposis Treatment Market
Specialty Medicine
Whipple's Disease Market
Specialty Medicine
Veno-Occlusive Hepatic Disease Therapeutics Market