
 Bartonellosis Therapeutics Market | 2026-2036
Bartonellosis Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Bartonellosis Therapeutics Market Outlook
Maintenance contracts for post-treatment monitoring is shifting the commercial model from episodic prescribing to longitudinal care relationships. Pfizer Inc. leverages its anti-infective manufacturing infrastructure to sustain supply continuity across endemic regions. Teva Pharmaceuticals anchors its position through generic antibiotic portfolios that compete on cost in price-sensitive markets.
Bartonellosis therapeutics comprise pharmaceutical agents targeting Bartonella species infections, with azithromycin and doxycycline representing first-line antibiotic compositions against intracellular bacterial persistence. These treatments serve both human clinical settings and veterinary applications where Bartonella henselae causes cat-scratch disease and related zoonotic conditions. Oral antibiotics dominate current prescribing patterns due to outpatient convenience and established bioavailability profiles, while intravenous delivery commands premium positioning in severe or refractory cases. Specialty clinics capture concentrated margin pools through diagnostic-treatment integration, whereas primary care channels handle the bulk of standard case management.
The FDA oversees human therapeutic approvals and orphan drug incentives, while the USDA regulates veterinary biologics and antimicrobial use in food-producing animals. These frameworks shape development priorities by channeling R&D investment toward species-specific indications and resistance-monitoring compliance. Stakeholders must monitor evolving antimicrobial stewardship mandates that restrict empirical prescribing and reshape reimbursement criteria across both human and animal health sectors.
Market Dynamics
The Bartonellosis therapeutics sector pivots on antimicrobial stewardship mandates that restrict empirical prescribing and reshape reimbursement criteria across human and veterinary channels. Regulatory pressure from FDA orphan drug incentives and USDA veterinary biologics oversight channels R&D investment toward species-specific indications.
Growth Catalysts
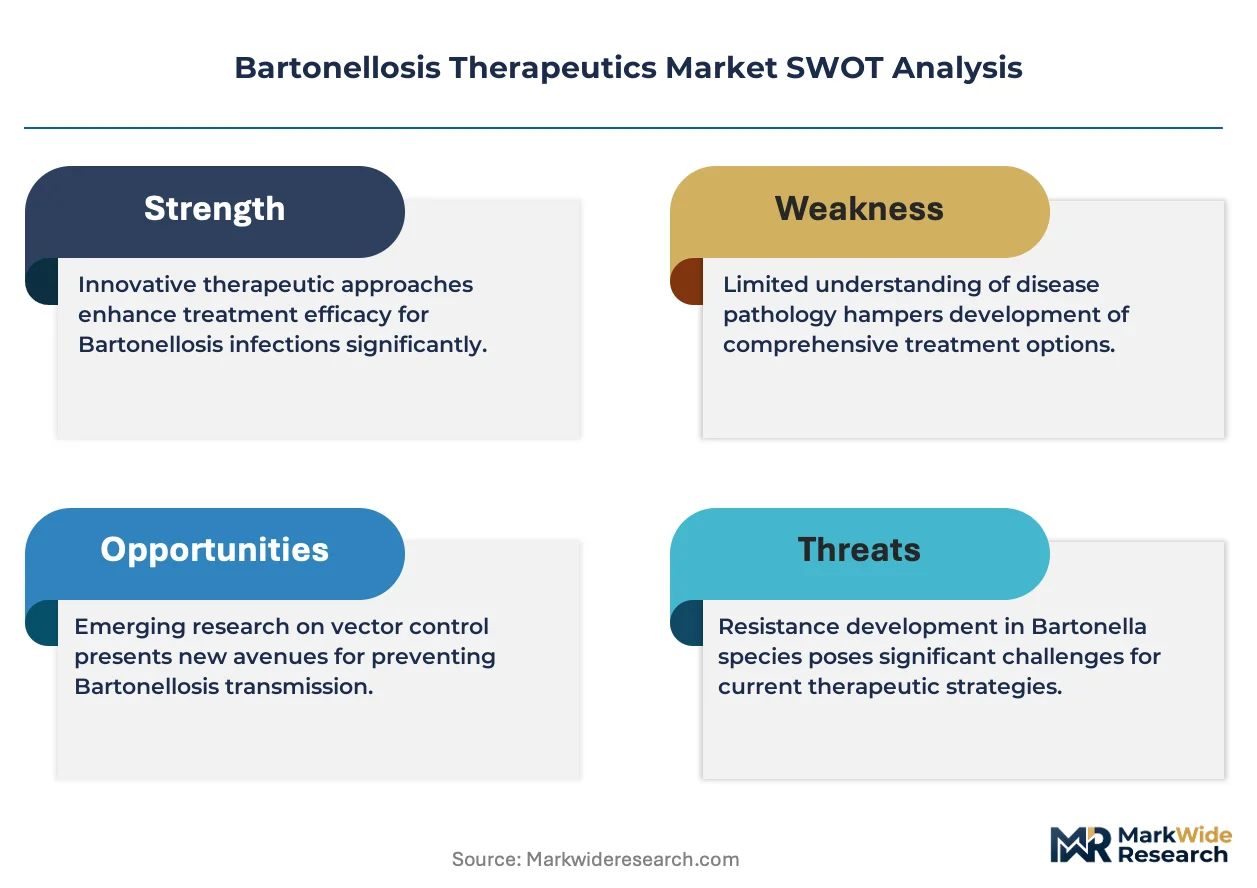
- Orphan Drug Incentives:The FDA's streamlined designation process accelerates therapeutic development timelines for rare Bartonella indications. Developers leverage tax credits and market exclusivity provisions to offset clinical trial costs.
- Zoonotic Surveillance Networks:Tick-borne disease monitoring systems in the United States drive diagnostic volume and standardize treatment protocols. Expanded testing capacity identifies subclinical infections previously missed.
- Veterinary Channel Expansion:Pet ownership growth and cat-scratch disease awareness elevate veterinary clinic demand for Bartonella henselae therapeutics. Companion animal practices integrate diagnostic-treatment workflows.
Market Restraints
- Generic Antibiotic Saturation:Doxycycline and azithromycin commoditization compresses margins for novel formulations. Price-sensitive markets default to established oral generics.
- Intracellular Persistence Limitations:Bartonella species evade standard antibiotic regimens through endothelial cell sequestration. Relapse rates necessitate extended treatment courses.
- Diagnostic Access Fragmentation:Specialized serology and PCR testing concentrates in urban academic medical centers. Rural and developing regions lack confirmatory capacity.
Strategic Opportunities
- Longitudinal Care Contracts:Post-treatment monitoring subscriptions convert episodic prescribing into recurring revenue streams. Specialty clinics bundle diagnostic follow-up with therapeutic protocols.
- One Health Regulatory Alignment:USDA-FDA coordinated frameworks for zoonotic disease therapeutics reduce dual-track approval burdens. Cross-species indication expansion leverages shared safety databases.
- Intravenous Premium Positioning:Severe and refractory case segments command higher reimbursement for parenteral delivery. Hospital outpatient departments capture concentrated margin pools.
Industry Challenges
- Antimicrobial Resistance Surveillance:Stewardship mandates require real-time resistance monitoring and reporting compliance. Clinical laboratories must upgrade informatics infrastructure.
- Cross-Species Formulation Complexity:Veterinary-human therapeutic differentiation demands separate manufacturing lines and stability testing. Dual registration timelines extend capital deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bartonellosis Therapeutics Market |
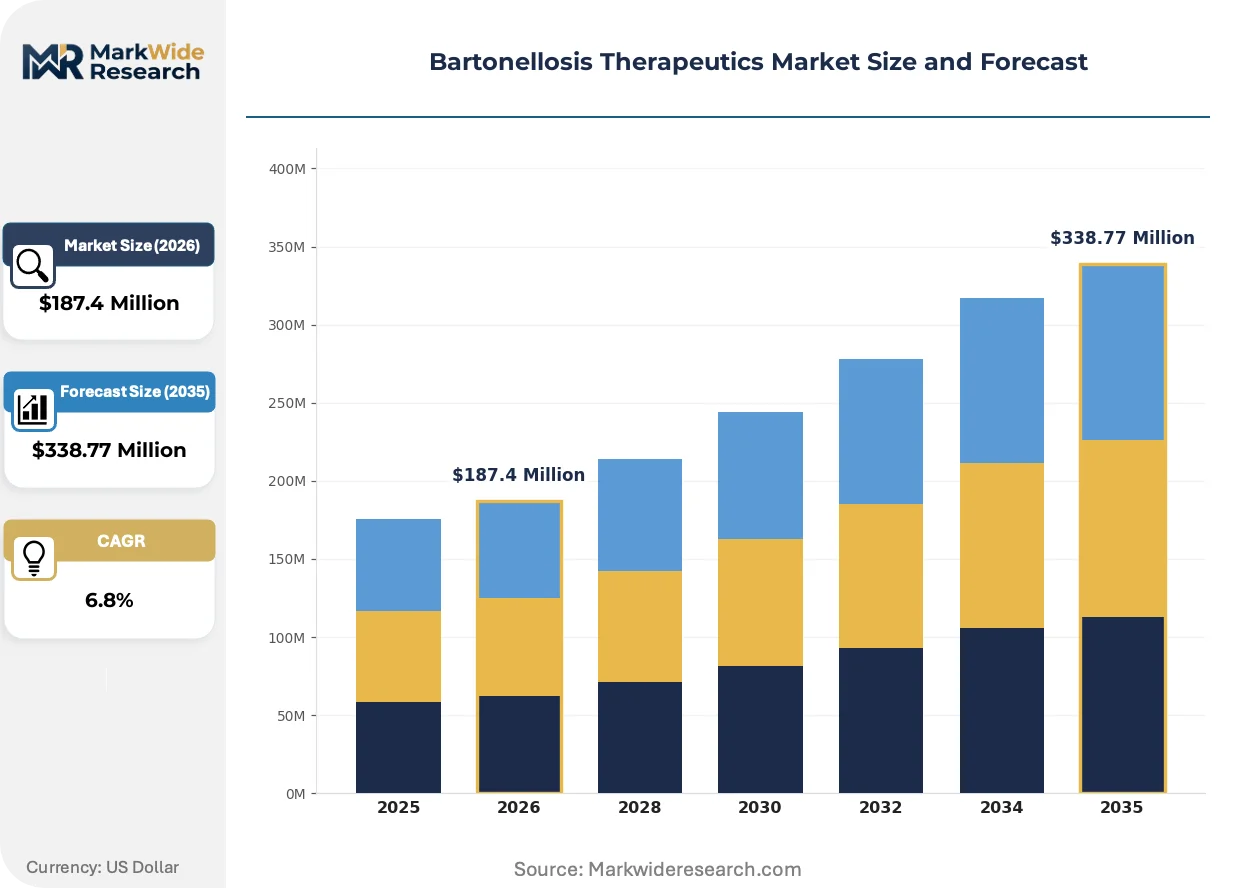
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antivirals, Vaccines, Supportive Therapies Application: Primary Care, Specialty Clinics, Research Labs, Emergency Care Delivery Mode: Oral, Intravenous, Topical, Subcutaneous End User: Hospitals, Homecare, Rehabilitation Centers, Clinics |
| Companies Covered | Pfizer Inc., Abbott Laboratories, Teva Pharmaceuticals, Perrigo Company plc, Lupin Pharmaceuticals, Bayer AG, Zoetis Inc., Merck & Co., Inc., Elanco Animal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bartonellosis Therapeutics Market Strategic Shifts
Diagnostic-treatment integration is compressing the time from symptom presentation to targeted therapy initiation across endemic regions. Technology convergence and regulatory alignment are reshaping competitive positioning.
Pharmacokinetic modeling software is integrating with clinical decision support platforms to optimize dosing regimens for intracellular bacterial infections. Academic medical centers in the United States deploy these tools to reduce relapse rates. The technology is integrating patient-specific variables with population resistance patterns.
The FDA's streamlined orphan drug designation process is accelerating therapeutic development timelines for rare Bartonella indications. Developers leverage tax credits and market exclusivity provisions to offset clinical trial costs. Human specialty clinics and veterinary biologics manufacturers both navigate this framework.
Subscription-based post-treatment monitoring is displacing episodic prescribing in specialty clinic channels. Bundled diagnostic follow-up contracts lock in longitudinal patient relationships. This shift concentrates in United States urban markets with integrated electronic health record systems.
Bartonellosis Therapeutics Market Segmentation
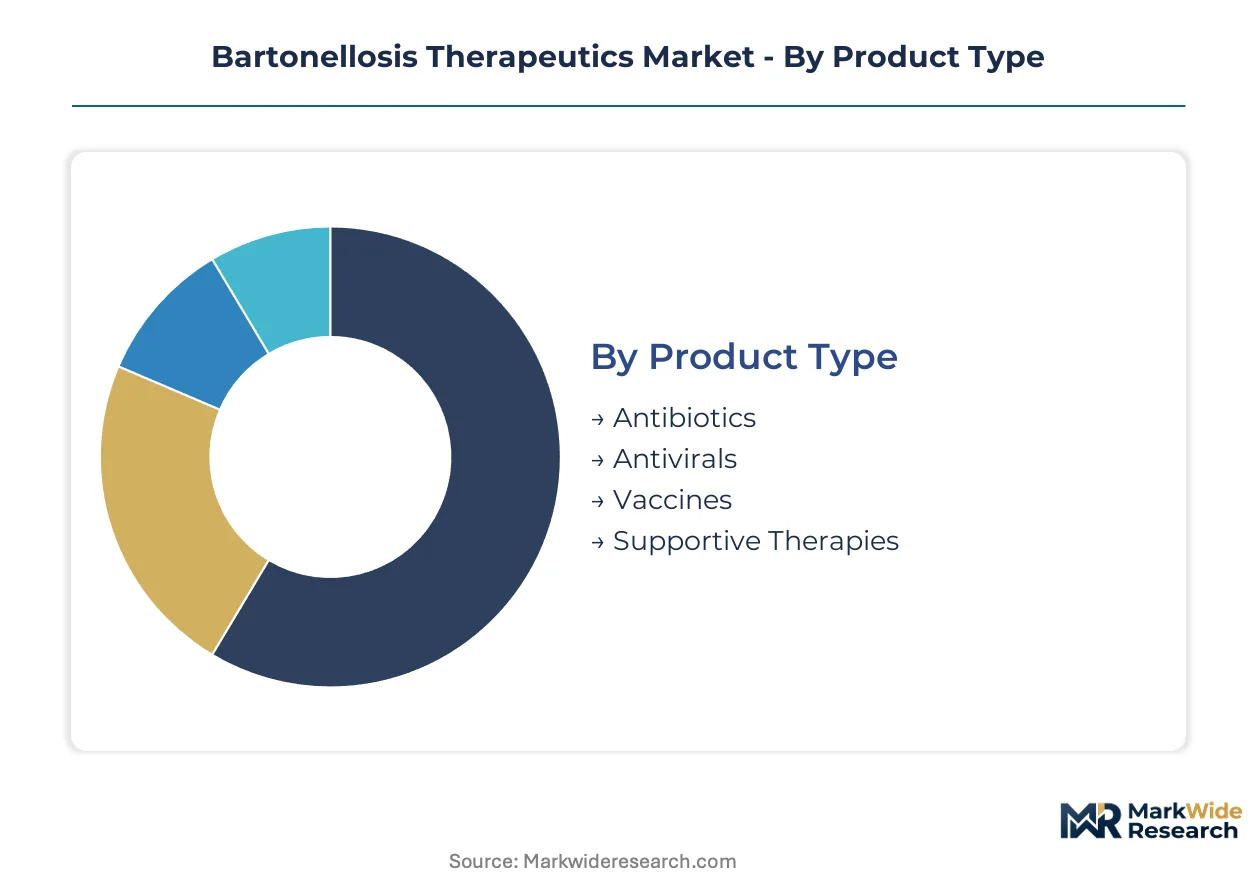
Segmentation in the Bartonellosis therapeutics market reveals distinct capital requirements and margin profiles across product categories and delivery modes. Manufacturers prioritize segments with higher reimbursement rates and lower generic competition.
Product Type:
Antibiotics command the highest upfront manufacturing investment due to fermentation infrastructure and sterility validation requirements.
- Antibiotics:Azithromycin and doxycycline formulations dominate prescribing patterns through established bioavailability against intracellular Bartonella persistence. Demand concentrates in United States specialty clinics where zoonotic surveillance networks drive diagnostic-treatment integration and extended course protocols.
- Vaccines:Development pipelines target prophylactic indications for veterinary and high-risk human populations, requiring substantial Phase III investment and cold-chain distribution infrastructure. United States academic medical centers sponsor the bulk of clinical evaluation programs.
- Antivirals:Adjunctive therapies address co-infection management in immunocompromised patient cohorts.
- Supportive Therapies:Immunomodulatory agents manage inflammatory complications in refractory cases.
Antibiotics absorb the bulk of installed capacity; vaccines are expanding most quickly.
Application:
Channel selection determines pricing power through reimbursement tier access and patient acuity levels.
- Specialty Clinics:Integrated diagnostic-treatment workflows capture premium reimbursement for PCR-confirmed infections and extended monitoring protocols. United States urban markets with electronic health record integration drive subscription-based post-treatment contract adoption.
- Primary Care:Volume-heavy channel handles standard cat-scratch disease presentations with oral generic antibiotics, competing on formulary placement and physician familiarity.
- Emergency Care:Severe disseminated infections requiring parenteral initiation command higher per-case revenue.
- Research Labs:Reference testing and clinical trial sites support development pipeline enrollment.
Primary Care handles the majority of case volume; Specialty Clinics generate the steepest expansion trajectory.
Delivery Mode:
Route selection shapes manufacturing complexity through formulation science and stability testing requirements.
- Oral:Tablet and capsule formulations dominate outpatient prescribing through convenience and established pharmacokinetic profiles. United States retail pharmacy networks sustain volume leadership despite generic price compression.
- Intravenous:Hospital outpatient departments and infusion centers capture concentrated margin pools for severe or refractory cases requiring endothelial penetration.
- Topical:Limited application for cutaneous manifestations in veterinary settings.
- Subcutaneous:Emerging depot formulations for long-acting prophylaxis in development pipelines.
Oral delivery maintains the largest patient base; Intravenous administration delivers the highest per-dose revenue.
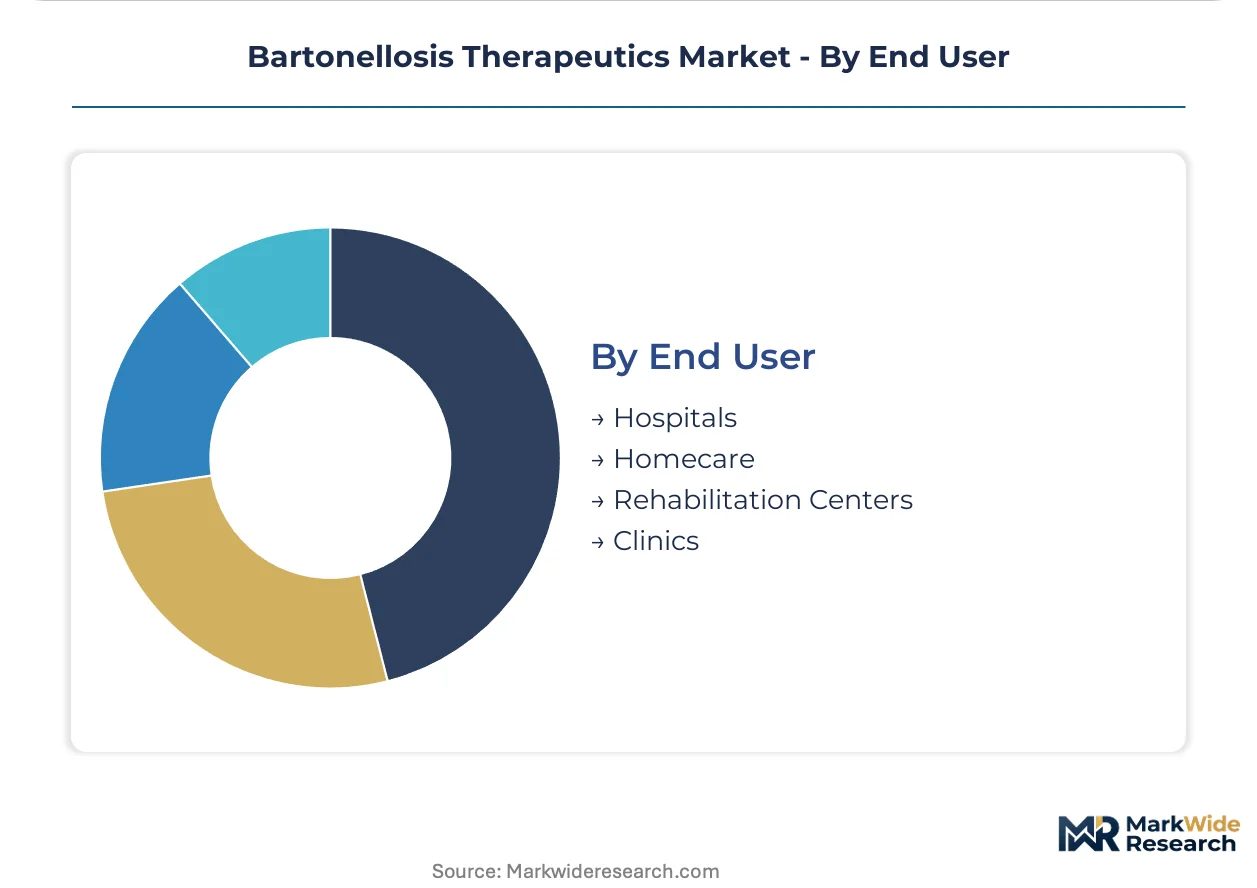
End User:
Site-of-care economics determine procurement patterns and inventory management requirements.
- Hospitals:Inpatient and outpatient departments manage severe disseminated bartonellosis with parenteral-to-oral step-down protocols. United States health systems negotiate formulary placement through group purchasing organizations.
- Homecare:Infusion services extend IV antibiotic courses for patients with vascular access devices, requiring nursing coordination and adverse event monitoring.
- Clinics:Ambulatory settings handle the majority of uncomplicated cases with oral regimens.
- Rehabilitation Centers:Post-acute facilities manage neurological sequela in chronic infection survivors.
Hospitals anchor the highest-acuity segment; Homecare is gaining share fastest through site-of-care shift incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for Bartonella therapeutics concentrates in established pharmaceutical clusters, while diagnostic demand and treatment protocols diverge sharply across regulatory environments. Consumption patterns track zoonotic surveillance intensity and veterinary care access rather than production geography.
United States
Tick-borne disease surveillance networks in the Northeast and Upper Midwest drive diagnostic volume for Bartonella infections. The FDA's orphan drug designation streamlines development timelines for rare indication therapeutics. Academic medical centers in Boston and New York anchor clinical trial enrollment and post-treatment monitoring subscription models.
Germany
EMA centralized procedures accelerate market access for novel anti-infective formulations targeting refractory cases. The country's antimicrobial stewardship mandates reshape reimbursement criteria across hospital outpatient departments. Pharmaceutical manufacturing clusters in Baden-Württemberg sustain fermentation infrastructure for antibiotic production.
Japan
PMDA priority review vouchers incentivize development for neglected tropical disease indications with Bartonella co-infection relevance. Aging companion animal populations elevate veterinary clinic demand for feline zoonotic therapeutics. The Kansai region's biomedical corridor integrates diagnostic reference testing with therapeutic distribution.
Brazil
ANVISA's streamlined registration for essential medicines expands access to oral generic antibiotics in price-sensitive markets. Rural diagnostic access gaps concentrate confirmatory testing in São Paulo and Rio de Janeiro academic centers. The country's One Health surveillance programs link human and veterinary case reporting.
Australia
TGA orphan drug incentives parallel FDA frameworks for rare disease therapeutic development. Queensland and New South Wales wildlife reservoirs drive veterinary research investment into Bartonella species cross-species transmission. Sydney and Melbourne specialty clinics pilot subscription-based post-treatment monitoring contracts.
Bartonellosis Therapeutics Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the Bartonella therapeutics landscape. Large-cap pharmaceutical manufacturers with anti-infective fermentation infrastructure dominate antibiotic supply continuity, while specialty biologics developers target orphan indications with premium positioning. Three archetypes structure competition: integrated multinationals with veterinary-human dual registration capabilities, generic-focused cost competitors, and emerging biotechs leveraging FDA orphan incentives. Consolidation activity concentrates on diagnostic-treatment integration assets, while portfolio diversification into zoonotic disease adjacencies reshapes R&D allocation.
Among integrated multinationals, Pfizer Inc. and Bayer AG exemplify the capital-intensive archetype with cross-species therapeutic portfolios, while Teva Pharmaceuticals occupies a position within the generic cost-competition tier. These anchors demonstrate how regulatory navigation capabilities and manufacturing scale separate sustainable market presence from marginal positioning in antibiotic commoditization environments.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Abbott Laboratories |
| Teva Pharmaceuticals |
| Perrigo Company plc |
| Lupin Pharmaceuticals |
| Bayer AG |
| Zoetis Inc. |
| Merck & Co., Inc. |
| Elanco Animal Health |
| Others |
Value Chain & Pricing Dynamics
Fermentation-grade dextrose price volatility cascades through antibiotic manufacturing into three-tier pricing structure across premium, standard, and economy levels. Contract manufacturers in India and China absorb input cost swings through volume commitments to United States specialty clinics, while Brazilian retail pharmacies face spot-market exposure for oral generic azithromycin.
Pricing Analysis
Margin tightening in oral generic tiers reflects doxycycline commoditization and azithromycin biosimilar entry. Three-tier pricing structure across premium, standard, and economy levels separates intravenous hospital formulations from outpatient tablets and veterinary bulk compounds. Certification investment for FDA orphan drug designation props premium positioning, while Brazilian ANVISA-registered generics compete on landed cost. Primary care channels exhibit highest price sensitivity; refractory case specialists accept value-based premiums for parenteral delivery.
Supply Chain Analysis
Dual-sourcing mandates from United States group purchasing organizations require qualified backup suppliers for intravenous antibiotic fermentation batches. Active pharmaceutical ingredient production concentrates in India, China, and Germany, with sterile fill-finish capacity tethered to Baden-Württemberg and Gujarat clusters. Doxycycline precursors and azithromycin macrolide backbones face tariff exposure from trade policy shifts. Distribution runs through cold-chain logistics networks serving hospital outpatient departments and veterinary wholesale distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation capacity constraints in sterile antibiotic manufacturing prop pricing power for qualified suppliers. Extended course protocols for intracellular Bartonella persistence lock in recurring API demand across the projection horizon.
For Market Incumbents: Anticipate generic antibiotic saturation by deepening captive supply of fermentation-grade raw materials through backward integration into Indian and Chinese API hubs. Secure orphan drug exclusivity windows through FDA tax credit utilization before antimicrobial stewardship mandates tighten empirical prescribing criteria. Channel control through specialty clinic diagnostic-treatment integration defends margin pools against retail pharmacy commoditization. For New Entrants and Emerging Players: Veterinary clinic networks represent the most penetrable channel for novel formulation entry, given cat-scratch disease awareness growth and subscription-based post-treatment monitoring adoption. Target United States urban markets with electronic health record integration for longitudinal care contract pilots. Go-to-market leverage rests on USDA-FDA coordinated One Health regulatory alignment for cross-species indication expansion. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialty biologics developers with FDA orphan drug designations in United States academic medical center corridors. Five-to-ten year viability hinges on diagnostic-treatment integration asset consolidation and resistance surveillance informatics capability. The signal to watch is antimicrobial stewardship mandate enforcement intensity shifting reimbursement criteria toward PCR-confirmed versus empirical prescribing.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA tax credits and market exclusivity offset clinical trial costs for rare Bartonella indications. |
| Diagnostic-Treatment Integration | Specialty clinic workflows capture premium reimbursement through PCR-confirmed infection protocols. |
| API Backward Integration | Captive fermentation capacity in India and China insulates margin from dextrose price volatility. |
| Veterinary Channel Expansion | Companion animal practice integration elevates Bartonella henselae therapeutic demand. |
| Subscription Monitoring Contracts | Post-treatment bundles convert episodic prescribing into recurring revenue streams. |
Study Parameters
Document review covered FDA orphan drug filings, EMA centralized procedure submissions, USDA veterinary biologics registrations, and ClinicalTrials.gov enrollment records, complemented by interviews with drug development executives, regulatory affairs leads, hospital formulary directors, and veterinary clinic practice managers. Secondary validation drew from customs trade data, SEC 10-K pharmaceutical segment disclosures, and academic medical center procurement databases. Bottom-up prescription volume modeling triangulated against top-down therapeutic class expenditure estimates.
Historical antibiotic pricing series cross-referenced against panel input from group purchasing organization contract managers and API procurement leads anchored the analytical framework. Segmentation dimensions spanned product type, delivery mode, application channel, and regional regulatory cluster across the modeling period. CAGRs derived from infection incidence projections, surveillance network expansion timelines, and stewardship mandate implementation curves. Forecast inputs incorporated zoonotic disease reporting system upgrades and companion animal demographic shifts.
Caveats apply where antimicrobial resistance surveillance mandate delays, generic antibiotic manufacturing inspections, or veterinary diagnostic access fragmentation could materially shift the outlook. Deviation in FDA orphan drug review queue timing or USDA-FDA One Health coordination intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Anaplastic Large Cell Lymphoma (ALCL) Therapeutics Market
Specialty Medicine
Head and Neck Cancer Therapeutics Market
Specialty Medicine
North America Dry Eye Syndrome Market
Specialty Medicine
Global Primary Angle-Closure Glaucoma Market
Specialty Medicine
Hypersensitivity Pneumonitis Market
Specialty Medicine
Chromoblastomycosis Treatment Market
Specialty Medicine
Psychedelic Medicine Market
Specialty Medicine
Global Spinal Muscular Atrophy Treatment Market
Specialty Medicine
Listeriosis Treatment Market
Specialty Medicine
Toxic Shock Syndrome Treatment Market
Specialty Medicine
Neuromuscular Disorders Treatment Market
Specialty Medicine
Global Gastroparesis Treatment Market
Specialty Medicine
Global Constipation Treatment Market
Specialty Medicine
Paediatric Sports Medicine Market
Specialty Medicine
Liver Cirrhosis Treatment Market
Specialty Medicine
Global Primary Immunodeficiency Therapeutics Market