
 Global Treatment-Resistant Depression Market | 2026-2036
Global Treatment-Resistant Depression Market Size, Share, and Industry Trends Forecast 2026-2036
Global Treatment-Resistant Depression Market Foresight
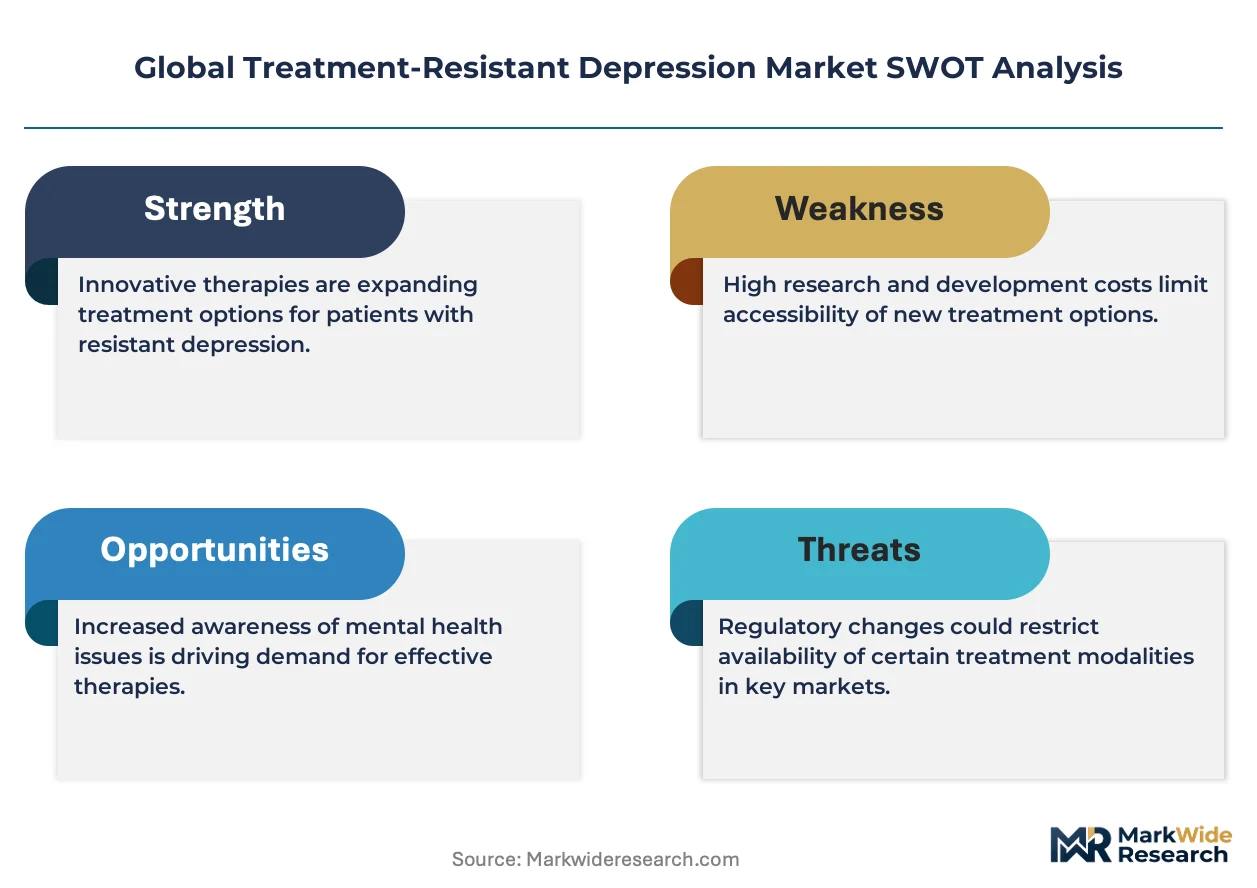
Psychiatrist shortages in rural and underserved regions are unwinding traditional care delivery models and pushing investment toward scalable neurostimulation and digital platforms. Eli Lilly and Company leverages its neuroscience pipeline depth to sustain leadership in novel antidepressant development. Pfizer Inc. anchors its position through established distribution networks for psychiatric therapeutics. H. Lundbeck A/S specializes in mood disorder research with particular depth in European and North American markets.
Treatment-resistant depression describes a condition where patients fail to achieve adequate response after two or more antidepressant trials of adequate dose and duration, typically assessed using the Montgomery-Åsberg Depression Rating Scale or Hamilton Depression Rating Scale with remission thresholds below specific score cutoffs. The condition drives demand for alternative pharmacological mechanisms, device-based neuromodulation, and combination therapeutic approaches. Neurostimulation Devices represent the fastest-growing product category as transcranial magnetic stimulation gains insurance coverage and outpatient clinic integration. Ketamine Therapy commands premium pricing and concentrated provider networks but faces manufacturing and compounding standardization challenges. Digital Therapeutics remain nascent with regulatory clarity from the FDA still crystallizing reimbursement pathways.
The FDA's breakthrough therapy designation and EMA's priority medicines scheme are accelerating market access for novel mechanisms, while WHO depression treatment guidelines shape lower-income country procurement priorities. The DEA's scheduling controls on esketamine and emerging psychedelic compounds create distribution bottlenecks that favor established hospital networks over independent clinics. Stakeholders must monitor how CMS national coverage determinations for device-based therapies reshape site-of-service economics and competitive positioning.
Market Dynamics
Accelerated FDA breakthrough therapy pathways are compressing clinical-to-commercial timelines for novel antidepressant mechanisms, forcing established psychiatric care infrastructure to absorb device-based neuromodulation and psychedelic-assisted protocols simultaneously.
Growth Catalysts
- Esketamine REMS framework:The FDA's Risk Evaluation and Mitigation Strategy for intranasal esketamine has created certified treatment center networks that standardize administration protocols and expand eligible patient pools through controlled distribution.
- Transcranial magnetic stimulation:Outpatient psychiatric clinics are integrating repetitive TMS systems as first-line augmentation therapy, driven by CMS national coverage determinations that established reimbursement parity with pharmacological interventions.
- Psychiatrist concentration in urban corridors:Supply scarcity in rural United States regions is pushing telepsychiatry platforms and mobile neuromodulation units into previously underserved catchment areas.
Market Restraints
- Ketamine API supply concentration:Bulk pharmaceutical chemical manufacturing for racemic ketamine concentrates in a limited number of inspected facilities, exposing compounding pharmacies to import delays and quality variation.
- DEA Schedule III controls:Distribution bottlenecks for esketamine and investigational psychedelic compounds favor hospital-based administration over independent clinic models, limiting site-of-service expansion.
- Device capital intensity:Transcranial magnetic stimulation systems require substantial upfront investment and specialized technician training, constraining deployment to well-capitalized health systems.
Strategic Opportunities
- EMA priority medicines scheme:European regulatory acceleration for novel antidepressant mechanisms offers parallel market entry pathways that reduce development cost duplication across jurisdictions.
- Digital therapeutic integration:FDA-cleared prescription digital therapeutics for depression augmentation are creating reimbursement codes that enable bundled care models combining pharmacology with cognitive behavioral protocols.
- Psychedelic-assisted therapy protocols:MDMA and psilocybin investigational programs are establishing therapist certification frameworks that will govern future service delivery standards and training revenue streams.
Industry Challenges
- Psychotherapist certification bottlenecks:Psychedelic-assisted therapy protocols require specialized training programs that currently graduate insufficient practitioners to meet projected service demand.
- Legacy EHR interoperability:Device-based neuromodulation platforms generate treatment parameter data that lacks standardized exchange formats with dominant electronic health record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Treatment-Resistant Depression Market |
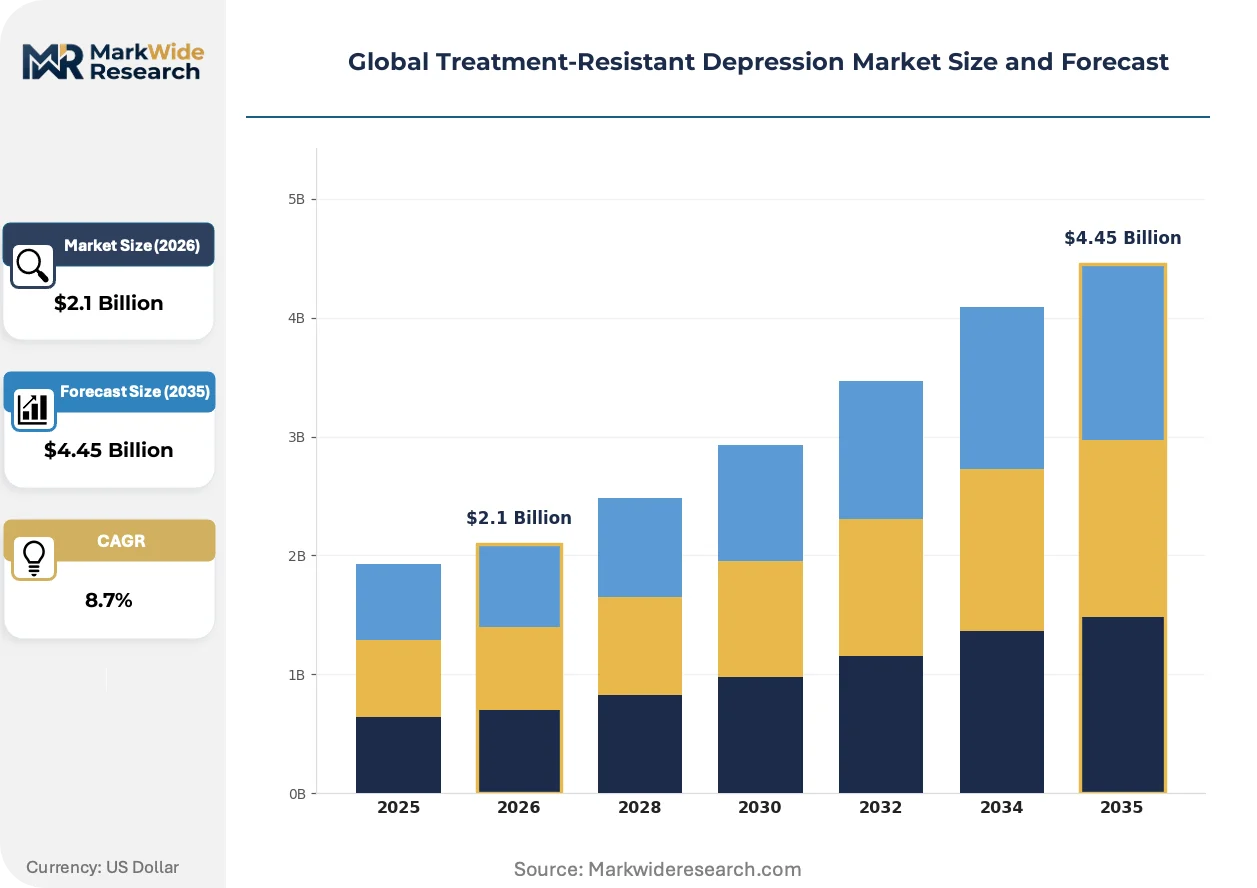
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Psychotherapy, Neurostimulation Devices, Ketamine Therapy, Digital Therapeutics Therapy Area: Major Depressive Disorder, Bipolar Depression, Persistent Depressive Disorder, Postpartum Depression, Seasonal Affective Disorder End User: Psychiatric Clinics, Mental Health Centers, Neurology Departments, Research Institutes, Counseling Services Delivery Mode: Oral Administration, Intravenous Infusion, Transcranial Magnetic Stimulation, Electroconvulsive Therapy, Mobile App-Based Platforms |
| Companies Covered | Eli Lilly and Company, Pfizer Inc., GlaxoSmithKline, AbbVie Inc., AstraZeneca, Johnson & Johnson, H. Lundbeck A/S, Otsuka Pharmaceutical Co., Ltd., Sandoz International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Treatment-Resistant Depression Market Shifts & Advancements
Novel therapeutic modalities are fragmenting the traditional antidepressant development pipeline, with device-based interventions and psychedelic compounds establishing parallel commercialization tracks that reshape prescriber education and site certification requirements.
Repetitive transcranial magnetic stimulation is decomposing the historical dominance of pharmacological monotherapy in treatment-resistant depression protocols. Academic medical centers and large multi-site psychiatric groups are deploying theta-burst stimulation variants that compress treatment sessions from 37 minutes to 3 minutes. This compression is enabling higher patient throughput per device and expanding addressable clinic populations without proportional capital expansion.
EMA's priority medicines scheme and FDA breakthrough therapy designation are creating harmonized regulatory acceleration pathways that reduce time-to-market for novel mechanisms. These frameworks compress Phase II-to-approval intervals by mandating rolling review procedures and adaptive trial designs. European and North American markets are responding by front-loading health technology assessment submissions to secure reimbursement pre-positioning alongside regulatory approval.
Psychiatric service procurement is consolidating around integrated care contracts that bundle device-based neuromodulation, pharmacological management, and digital therapeutic monitoring into single episode-based payments. Large employer health plans and Medicaid managed care organizations in the United States are driving this consolidation through narrow network arrangements that favor vertically organized provider systems over independent practitioners.
Global Treatment-Resistant Depression Market Segmentation
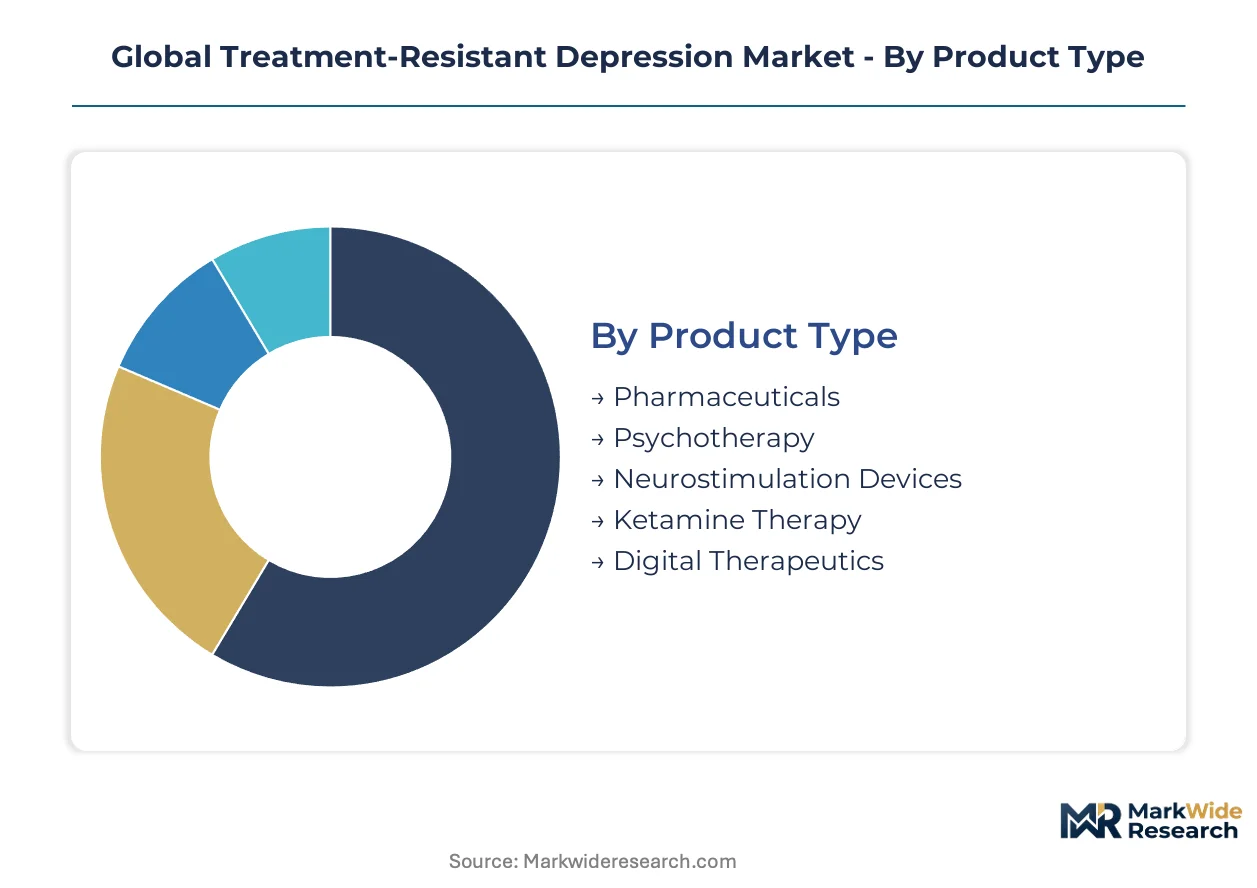
Treatment-resistant depression interventions fragment across four critical dimensions that determine reimbursement pathways, site certification requirements, and prescriber training investments. Each segmentation axis carries distinct regulatory and commercial logic that shapes how novel mechanisms achieve market penetration.
Product Type:
Neurostimulation Devices face the most acute substitution pressure from emerging psychedelic protocols and next-generation pharmacology, forcing manufacturers to demonstrate durable efficacy against rapidly evolving alternatives.
- Neurostimulation Devices:Transcranial magnetic stimulation and vagus nerve stimulation systems deliver non-invasive neuromodulation through electromagnetic pulse delivery. Demand concentrates in United States outpatient psychiatric clinics where CMS reimbursement parity with pharmacotherapy has accelerated capital deployment. Device manufacturers compete on treatment session compression and technician training efficiency.
- Ketamine Therapy:Racemic ketamine infusion and intranasal esketamine protocols require certified treatment centers under FDA REMS frameworks. United States hospital networks dominate service delivery due to DEA Schedule III distribution controls and complex adverse event monitoring requirements that independent clinics struggle to satisfy.
- Pharmaceuticals:Novel antidepressant mechanisms targeting glutamate, GABA, and inflammatory pathways seek breakthrough therapy designation to compress development timelines.
- Psychotherapy:Cognitive behavioral therapy and interpersonal psychotherapy adaptations for treatment-resistant populations require specialized practitioner certification.
- Digital Therapeutics:FDA-cleared prescription software delivering cognitive behavioral protocols through mobile interfaces remain nascent with reimbursement codes still crystallizing.
Pharmaceuticals retain volume leadership; Neurostimulation Devices hold the steepest expansion curve.
Therapy Area:
Cost tier stratification separates acute intervention protocols from chronic maintenance programs, with bipolar depression commanding premium pricing due to comorbidity complexity and liability exposure.
- Major Depressive Disorder:The core indication driving clinical trial enrollment and regulatory approval pathways, characterized by recurrent episodes and substantial functional impairment. United States academic medical centers generate the highest protocol volumes through integrated research and service delivery models.
- Bipolar Depression:Depressive episodes within bipolar spectrum disorders require mood stabilizer co-administration and carry elevated suicide risk profiles. European markets, particularly Germany and the United Kingdom, show concentrated demand through specialized mood disorder clinics.
- Persistent Depressive Disorder:Chronic low-grade depression with early onset drives long-term maintenance therapy demand.
- Postpartum Depression:Time-limited intervention windows and breastfeeding safety considerations shape product selection.
- Seasonal Affective Disorder:Recurrent winter-pattern depression in northern latitude populations creates predictable demand seasonality.
Major Depressive Disorder anchors prescription volume; Bipolar Depression captures the highest per-patient revenue.
End User:
Customer type fragmentation reflects divergent capital intensity, with psychiatric clinics absorbing device-based therapies while research institutes concentrate investigational psychedelic protocols.
- Psychiatric Clinics:Outpatient specialty practices integrating pharmacological management with device-based neuromodulation and psychotherapy. United States multi-site groups in Texas, California, and Florida lead TMS system deployment through narrow network contracts with regional health plans.
- Neurology Departments:Hospital-based specialists managing comorbid neurological conditions and severe treatment-resistant cases requiring electroconvulsive therapy or deep brain stimulation evaluation.
- Mental Health Centers:Community-based facilities serving Medicaid and uninsured populations with constrained formularies.
- Research Institutes:Academic medical centers conducting Phase II and III trials for novel mechanisms under FDA and EMA accelerated pathways.
- Counseling Services:Independent practitioners delivering psychotherapy augmentation with limited pharmacological authority.
Psychiatric Clinics dominate commercial volume; Research Institutes control pipeline access for emerging mechanisms.
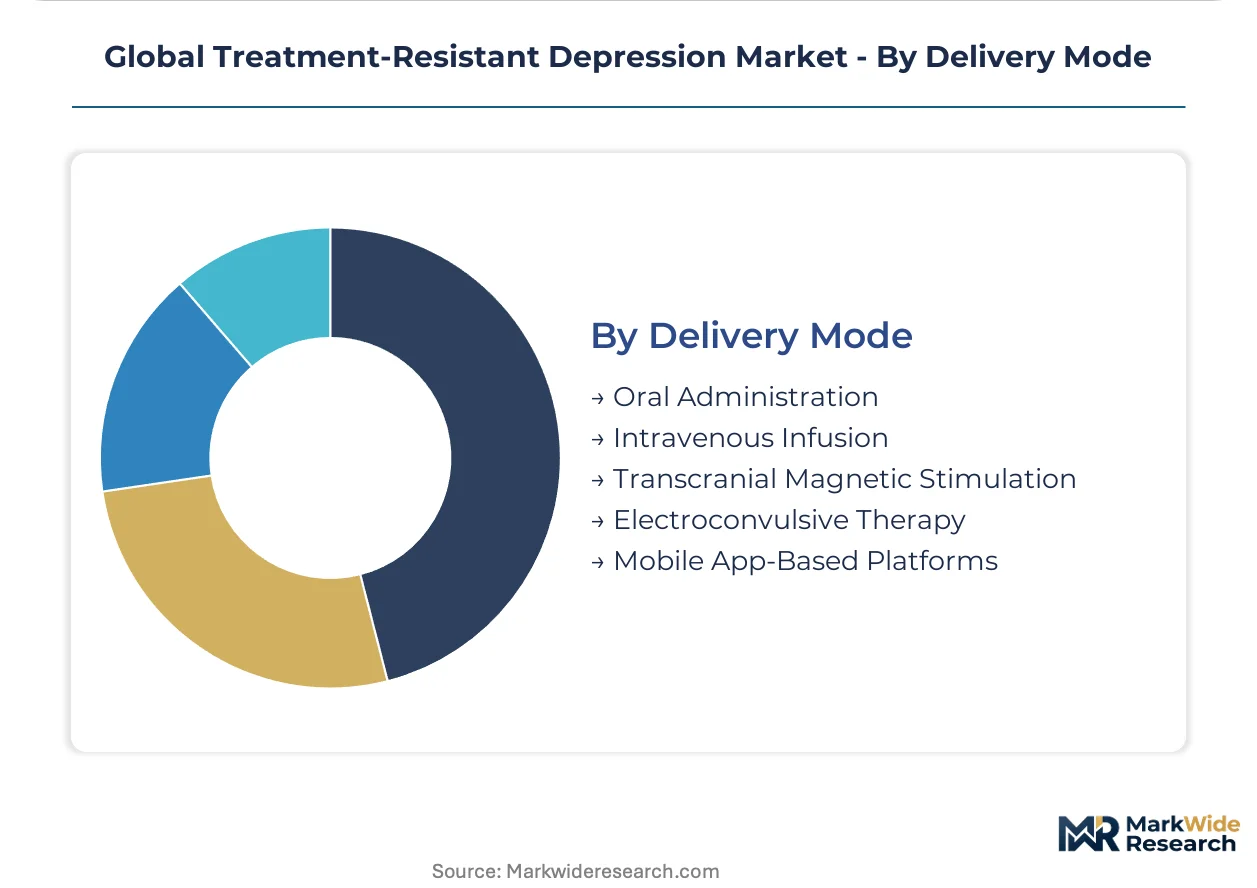
Delivery Mode:
Supply concentration in sterile manufacturing and electromagnetic device production creates divergent margin structures across administration pathways.
- Transcranial Magnetic Stimulation:Non-invasive neuromodulation through magnetic coil positioning over dorsolateral prefrontal cortex. United States equipment manufacturers in Massachusetts and California supply integrated systems to clinic networks seeking theta-burst protocol differentiation.
- Intravenous Infusion:Racemic ketamine and investigational psychedelic compounds require compounding pharmacy relationships and infusion suite infrastructure. DEA quotas and API manufacturing concentration in inspected facilities constrain supply elasticity.
- Oral Administration:Traditional antidepressant augmentation and novel oral mechanisms targeting inflammation or opioid systems.
- Electroconvulsive Therapy:Hospital-based anesthesia-requiring intervention for the most severe, medication-refractory cases.
- Mobile App-Based Platforms:Prescription digital therapeutics requiring FDA software-as-medical-device clearance and pharmacy benefit integration.
Oral Administration maintains prescription dominance; Transcranial Magnetic Stimulation is expanding most quickly through outpatient integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough therapy designations and CMS reimbursement parity for device-based interventions have concentrated commercial activity in the United States, while EMA priority medicines schemes accelerate parallel development across European markets.
United States
Academic medical centers in Massachusetts and California generate the highest protocol volumes for novel antidepressant mechanisms. The FDA's Risk Evaluation and Mitigation Strategy for intranasal esketamine has created certified treatment center networks that standardize administration protocols. Multi-site psychiatric groups in Texas and Florida lead transcranial magnetic stimulation deployment through narrow network contracts with regional health plans.
Germany
Specialized mood disorder clinics in Munich and Berlin drive concentrated demand for bipolar depression interventions. The Federal Institute for Drugs and Medical Devices maintains accelerated assessment pathways for psychiatric therapeutics that align with EMA priority medicines timelines. Baden-Württemberg hosts several university hospitals integrating theta-burst stimulation protocols into outpatient psychiatric services.
United Kingdom
National Health Service mental health trusts in London and Manchester are piloting bundled care models combining pharmacological management with device-based neuromodulation. The National Institute for Health and Care Excellence issues technology appraisal guidance that shapes commissioning decisions for treatment-resistant depression interventions. Oxford and Cambridge academic medical centers concentrate early-phase clinical trial activity for investigational psychedelic compounds.
Japan
Pharmaceutical and Medical Devices Agency consultations for novel antidepressant mechanisms proceed through Sakigake designation pathways that compress review timelines. Tokyo and Osaka metropolitan areas host the highest density of psychiatric clinics equipped for neurostimulation device integration. PMDA guidance on digital therapeutics is creating reimbursement clarity for prescription software delivering cognitive behavioral protocols.
Australia
Therapeutic Goods Administration approvals for transcranial magnetic stimulation systems have expanded Medicare reimbursement coverage for outpatient psychiatric services. Sydney and Melbourne academic medical centers participate in multinational clinical trials for ketamine-derived therapies under TGA clinical trial notification schemes. Victoria's specialized mental health services are integrating repetitive TMS as first-line augmentation therapy for medication-refractory cases.
Global Treatment-Resistant Depression Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that concentrates on mechanism-specific development programs. The upper tier commands distribution infrastructure for controlled substances and device-based service networks, while specialists pursue accelerated regulatory pathways for novel targets. Three archetypes dominate: diversified pharmaceutical conglomerates with neuroscience pipeline depth, mid-cap mood disorder specialists with European and North American market focus, and emerging psychedelic therapy developers establishing certification frameworks. Competitive intensity centers on breakthrough therapy designation acquisition and site-of-service expansion through certified treatment center networks.
Within the diversified pharmaceutical tier, Eli Lilly and Company and Pfizer Inc. anchor positions through established psychiatric therapeutic portfolios and distribution infrastructure. H. Lundbeck A/S exemplifies the mood disorder specialist archetype with concentrated research depth in European and North American markets. These three entities represent the structural poles around which partnership and licensing activity organizes, with smaller developers seeking commercialization alliances to access REMS-certified treatment networks and established reimbursement relationships.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Pfizer Inc. |
| GlaxoSmithKline |
| AbbVie Inc. |
| AstraZeneca |
| Johnson & Johnson |
| H. Lundbeck A/S |
| Otsuka Pharmaceutical Co., Ltd. |
| Sandoz International GmbH |
| Others |
Supply & Pricing Matrix
Capacity reservation agreements with certified ketamine compounding pharmacies lock in REMS-compliant supply access and stabilize per-dose pricing visibility for United States hospital networks administering intranasal esketamine. These contracts insulate buyers from API manufacturing bottlenecks while exposing them to minimum volume commitments that reshape site-of-service economics.
Pricing Analysis
United States esketamine protocols command substantial premiums over European markets where EMA parallel trade and national health technology assessment reference pricing compress reimbursement ceilings. Pricing stratifies across REMS-certified premium tiers, standard hospital-based administration, and emerging economy compounding models driven by FDA certification level and adverse event monitoring infrastructure. Cost compression in the standard tier is intensifying because CMS national coverage determinations for transcranial magnetic stimulation have established reimbursement parity that pressures ketamine therapy margins. Medicaid managed care organizations exhibit highest price sensitivity due to constrained behavioral health budgets, while self-funded employer plans show lowest sensitivity when bundled into integrated care contracts.
Supply Chain Analysis
Inventory buffers for racemic ketamine API extend lead times substantially when bulk pharmaceutical chemical manufacturing concentrates in inspected Indian and Chinese facilities subject to unpredictable FDA inspection scheduling. Device-based neuromodulation draws from electromagnetic coil production in Massachusetts and California, software control systems from Japanese suppliers, and cryogenic cooling components from German manufacturers. Single-source vulnerability in DEA-scheduled substance quotas creates distribution bottlenecks that favor hospital networks with established controlled substance vault infrastructure. Distribution runs through REMS-certified treatment center networks for esketamine, direct-to-clinic capital equipment leases for transcranial magnetic stimulation systems, and compounding pharmacy relationships for off-label racemic ketamine.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in this market rests on accelerating FDA breakthrough therapy designations that compress clinical-to-commercial timelines for novel antidepressant mechanisms and expand addressable patient pools beyond traditional pharmacological responders.
For Market Incumbents: Consolidate certified treatment center networks through exclusive REMS pharmacy partnerships that foreclose independent clinic access to esketamine distribution, and deepen backward integration into transcranial magnetic stimulation device manufacturing to capture margin from theta-burst protocol differentiation. Emerging psychedelic therapy developers threaten first-mover positioning in therapist certification frameworks, making channel control through academic medical center alliances the priority defensive lever. For New Entrants and Emerging Players: Anchor in rural United States psychiatric service deserts where telepsychiatry platforms and mobile neuromodulation units address supply scarcity that incumbent hospital networks cannot economically serve. Digital therapeutic developers represent the most penetrable segment given nascent FDA reimbursement code crystallization and limited incumbent software-as-medical-device expertise. A direct-to-clinic SaaS pricing model bypasses pharmacy benefit manager complexity and accelerates provider adoption. For Investors and Strategic Acquirers: Mood disorder specialists with EMA priority medicines scheme experience and established European reimbursement relationships offer asymmetric upside from parallel regulatory acceleration. Long-term viability across a decade horizon hinges on psychedelic-assisted therapy protocol standardization that converts investigational programs into durable service revenue streams. Watch CMS national coverage determination expansion for device-based interventions as the signal indicating inflection in site-of-service economics and competitive consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Certification Expansion | Hospital networks securing FDA Risk Evaluation and Mitigation Strategy designation capture controlled substance distribution exclusivity. |
| Theta-Burst Stimulation Deployment | Academic medical centers in Massachusetts compressing treatment sessions from 37 minutes to 3 minutes expand patient throughput. |
| Digital Therapeutic FDA Submission | Prescription software seeking breakthrough therapy designation creates bundled reimbursement codes combining pharmacology with cognitive protocols. |
| Psychedelic Therapist Certification | Investigational MDMA and psilocybin programs establish training revenue streams governing future service delivery standards. |
| EMA Priority Medicines Parallel Entry | European regulatory acceleration reduces development cost duplication across jurisdictions for novel antidepressant mechanisms. |
Research Methodology
A standing panel of psychiatric clinic operators, hospital formulary directors, neurostimulation device technicians, DEA compliance officers, and digital health reimbursement specialists provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against FDA REMS enrollment data, CMS national coverage determination filings, ClinicalTrials.gov protocol registries, and EMA priority medicines assessment reports. Bottom-up demand modeling from certified treatment center capacity and top-down triangulation against pharmaceutical manufacturer shipment disclosures ensured cross-verification.
Consistency checks validated volume and value outputs against external benchmarks including academic medical center protocol volume disclosures and neurostimulation device manufacturer installed base reports across the analysis window. The analytical framework modeled segmentation across product type, therapy area, end user, and delivery mode dimensions with particular granularity on REMS certification status and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating esketamine patient enrollment trajectories, transcranial magnetic stimulation reimbursement expansion timelines, and psychedelic investigational new drug application progression rates.
Decision-makers should treat outputs as directional under assumptions of sustained FDA breakthrough therapy pathway utilization and stable DEA scheduling frameworks; material deviation in regulatory acceleration timelines or controlled substance policy would warrant model refresh. Specific risks that could revise forecasts include psychedelic therapy protocol delays, neurostimulation device recall events, and ketamine API manufacturing inspection failures. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Repurposed Human Immunosuppressants Market
Pharmaceuticals
Antimalarial Drugs Market
Pharmaceuticals
Brain Tumor Drugs Market
Pharmaceuticals
Asia-Pacific Meglitinide Market
Pharmaceuticals
Nicorandil Market
Pharmaceuticals
Drug Designing Tools Market
Pharmaceuticals
Netupitant-Palonosetron FDC Market
Pharmaceuticals
Telmisartan Market
Pharmaceuticals
Malaysia Oral Anti-Diabetic Drug Market
Pharmaceuticals
Brazil Diabetes Drugs Market
Pharmaceuticals
Antidiuretic Drugs Market
Pharmaceuticals
Global Neuroprotective Agents Market
Pharmaceuticals
North America Glucagon-Like Peptide-1 Agonists Market
Pharmaceuticals
Global Anesthesia Drugs Market
Pharmaceuticals
Alkaptonuria Drugs Market
Pharmaceuticals
Pharmaceuticals Lipids Market