
 Antidiuretic Drugs Market | 2026-2036
Antidiuretic Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Antidiuretic Drugs Market Outlook
The divergence between premium peptide formulations and commodity vasopressin generics is hardening around bioequivalence certification and cold-chain reliability. Ferring Pharmaceuticals anchors European supply through specialized desmopressin manufacturing, while Novartis AG competes on hospital formulary access across North American urology networks. Teva Pharmaceutical Industries Ltd leverages its generic infrastructure to sustain pricing pressure on standard vasopressin vials.
Antidiuretic drugs comprise synthetic and semi-synthetic analogues of arginine vasopressin that modulate renal water reabsorption via V2 receptor agonism, with desmopressin acetate formulated at 0.1-0.2 mg tablet strengths or 10 mcg/spray intranasal solutions for diabetes insipidus and nocturia management. The therapeutic area segmentation shows diabetes insipidus commanding stable hospital demand, while nocturia applications in outpatient settings represent the fastest-expanding margin pool as aging demographics shift treatment loci from acute to chronic care. Administration route preferences are fragmenting, with intranasal delivery dominating pediatric compliance and injectable terlipressin capturing critical-care shock management protocols where rapid hemodynamic stabilization determines clinical outcomes.
FDA peptide purity guidelines and EMA's MDR device-drug combination rules are tightening documentation burdens for intranasal spray mechanisms, while India's CDSCO is aligning import licensing with BIS stability-testing protocols for temperature-sensitive biologics. These frameworks are elevating capital requirements for market access and compressing margins for non-integrated manufacturers. Stakeholders must monitor regulatory divergence between peptide-specific and device-mediated approval pathways to anticipate where compliance costs will reshape competitive viability.
Market Dynamics
FDA and EMA peptide purity mandates are compressing manufacturing margins while hospital formulary consolidation concentrates purchasing power among integrated health networks, forcing suppliers to absorb certification costs or exit.
Growth Catalysts
- Nocturia Protocol Expansion:Urology departments in Germany and France are embedding intranasal desmopressin into standardized nocturia care pathways, creating recurring hospital procurement volumes.
- EMA MDR Device-Drug Rules:Stricter documentation requirements for intranasal spray mechanisms are accelerating replacement of legacy devices with compliant next-generation delivery systems.
- Terlipressin Shock Adoption:Specialized endocrinology centers across Italy and Spain are expanding terlipressin use for hepatorenal syndrome, displacing older vasopressor alternatives.
Market Restraints
- Cold-Chain Cost Escalation:Temperature-sensitive peptide formulations require validated 2-8°C distribution infrastructure, elevating logistics spend for non-integrated distributors.
- Peptide Purity Thresholds:FDA's tightened impurity specifications for synthetic vasopressin analogues are forcing capital-intensive chromatography upgrades at manufacturing sites.
- Generic Vasopressin Commoditization:Standard injectable vasopressin vials face pricing compression from multi-source generic competition, eroding margin pools for undifferentiated suppliers.
Strategic Opportunities
- Pediatric Intranasal Compliance:Palatability-enhanced desmopressin formulations targeting diabetes insipidus in children represent an underserved segment with limited current competition.
- India CDSCO Alignment:BIS stability-testing protocol harmonization for temperature-sensitive biologics is streamlining import licensing for cold-chain-compliant manufacturers.
- Critical-Care Protocol Integration:Injectable terlipressin positioning within sepsis and shock management algorithms offers expansion beyond traditional hepatorenal applications.
Industry Challenges
- Peptide Synthesis Talent Scarcity:Specialized expertise in solid-phase peptide synthesis and purification at pharmaceutical-grade scale commands premium compensation and limited labor pool availability.
- Dual Certification Timelines:Simultaneous FDA peptide-drug and EMA MDR device compliance for intranasal combination products extends approval cycles by 18-24 months.
- Legacy Spray Device Obsolescence:Existing intranasal delivery platforms require redesign to meet revised dose-precision and contamination-control standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antidiuretic Drugs Market |
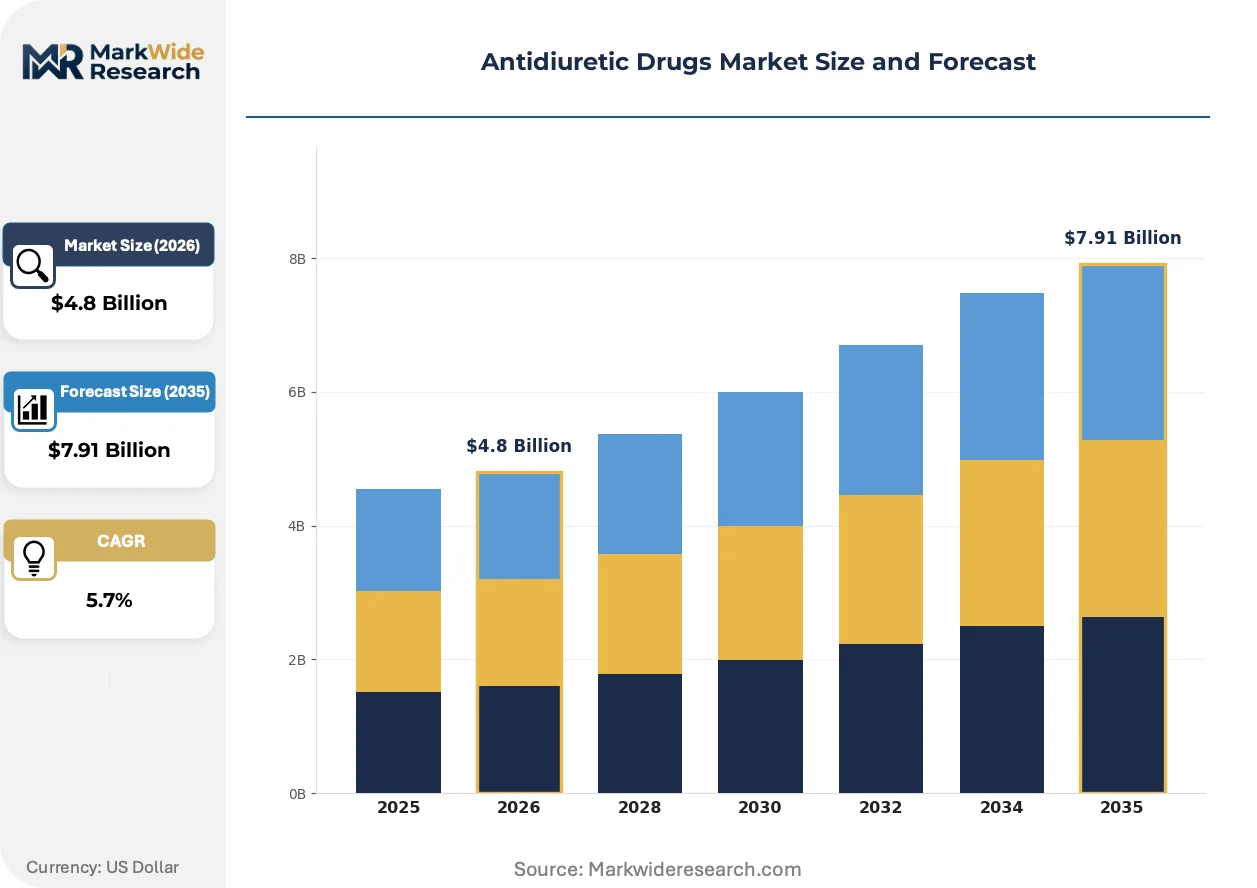
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Desmopressin, Vasopressin, Lypressin, Terlipressin Administration Route: Oral, Intranasal, Injectable, Sublingual Therapeutic Area: Diabetes Insipidus, Nocturia, Hemophilia, Shock Management End User: Hospitals, Clinics, Home Care, Long-term Care Facilities |
| Companies Covered | Par Sterile Products, Otsuka Holdings Co. Ltd, Ferring Pharmaceuticals, Novartis AG, Azevan Pharmaceuticals, Teva Pharmaceutical Industries Ltd, Avadel, ADH Health, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antidiuretic Drugs Market Strategic Shifts
Peptide formulation science and delivery mechanism engineering are converging to reshape competitive differentiation, with regulatory compliance emerging as a primary innovation axis rather than secondary obligation.
Microcrystalline cellulose-based sustained-release matrices are absorbing the formulation burden for once-daily desmopressin tablets, replacing immediate-release architectures. Pediatric endocrinology practices in France and pediatric nephrology units in the UK are transitioning compliance-critical patient cohorts to these platforms. The technology is absorbing patient-adherence risk while compressing reimbursement negotiation leverage for multi-dose generic alternatives.
EMA's Medical Device Regulation device-drug combination framework is mandating human-factors validation for intranasal spray actuation force and plunger travel distance. Manufacturers must now submit clinical usability studies alongside traditional bioequivalence data. Pediatric formulations and geriatric nocturia applications face the steepest compliance ramps, with several legacy devices failing to meet the new actuation-precision thresholds.
Hospital procurement departments are consolidating antidiuretic purchasing through centralized pharmacy and therapeutics committees, displacing individual physician preference as the primary demand determinant. Integrated delivery networks in Germany and the Netherlands are negotiating multi-year sole-source agreements for desmopressin across tablet and intranasal formats. This concentration is most pronounced in academic medical centers with captive endocrinology and urology specialty volumes.
Antidiuretic Drugs Market Segmentation
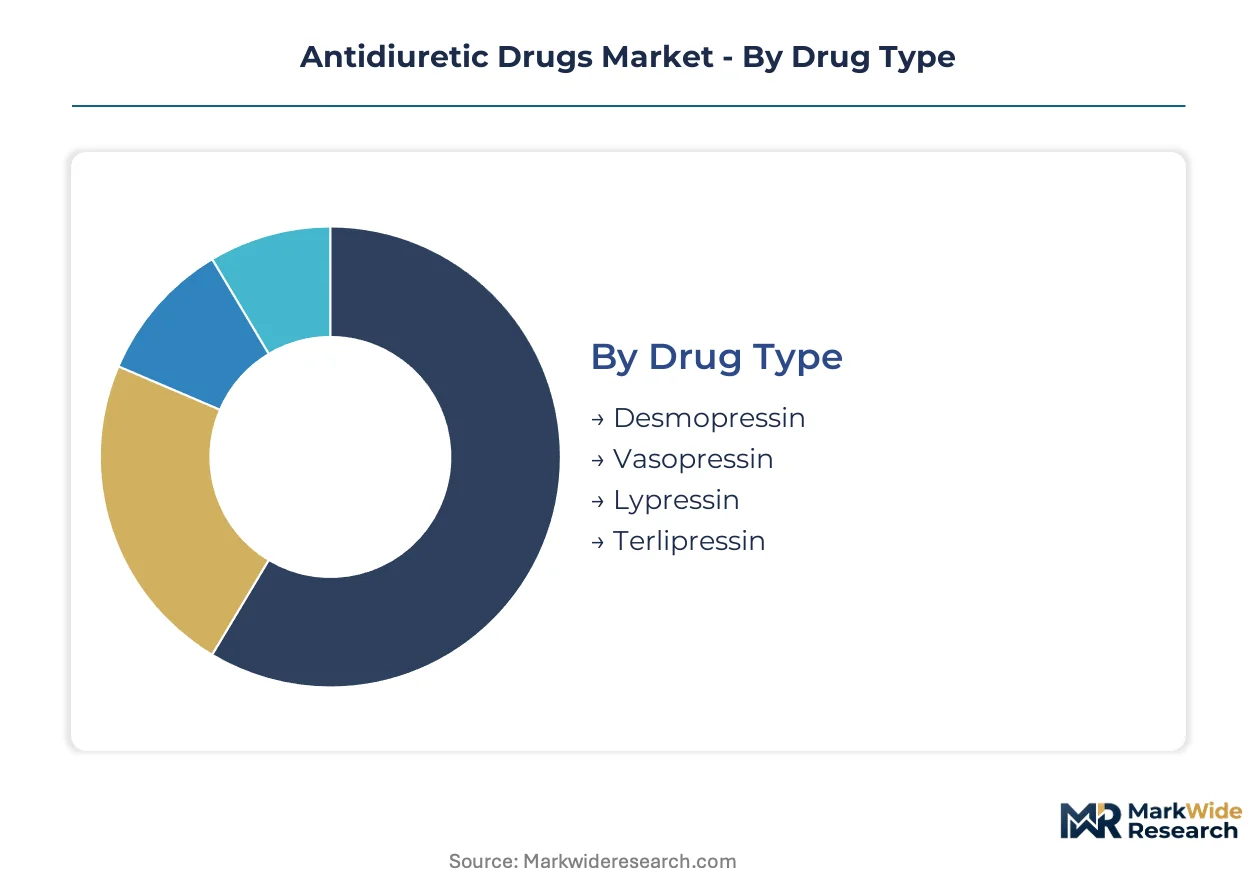
Antidiuretic drug segmentation reveals how formulation chemistry, delivery mechanics, and care setting economics create distinct margin architectures. Manufacturers must align R&D investment with the specific compliance burdens and reimbursement dynamics of each segment cluster.
Drug Type:
The customization-vs-standardization spectrum runs from bespoke peptide synthesis requiring chromatographic purity certification to commodity vasopressin manufactured through established fermentation protocols.
- Desmopressin:Synthetic arginine vasopressin analogue with modified amino acid structure conferring prolonged antidiuretic effect without pressor activity. Hospital procurement in Germany and France concentrates around intranasal formulations for nocturia protocols, driven by EMA bioequivalence mandates for peptide-based products. Most installed capacity flows through Desmopressin. Expansion is steepest in Terlipressin.
- Terlipressin:Prodrug of lysine vasopressin with selective V1 receptor agonism enabling systemic vasoconstriction. Specialized endocrinology centers in Italy and Spain are embedding this agent into hepatorenal syndrome and shock management algorithms, displacing older vasopressor alternatives where rapid hemodynamic stabilization determines outcomes.
- Vasopressin:Endogenous nonapeptide hormone produced through synthetic or extraction methods; standard injectable vials face pricing compression from multi-source generic competition eroding margin pools for undifferentiated suppliers.
- Lypressin:Synthetic analogue with shorter half-life requiring more frequent dosing; limited commercial footprint concentrates in legacy diabetes insipidus regimens where patients exhibit desmopressin intolerance.
Manufacturing investment clusters around desmopressin and terlipressin where purity thresholds and cold-chain requirements create defendable competitive moats.
Administration Route:
Route selection determines the regulatory pathway complexity and the capital intensity of compliance, with device-drug combinations facing steeper documentation burdens than simple parenteral solutions.
- Intranasal:Spray-delivered desmopressin solutions at 10 mcg/actuation strength; EMA MDR rules now mandate human-factors validation for actuation force and plunger travel distance, accelerating replacement of legacy devices with compliant next-generation delivery systems.
- Injectable:Parenteral terlipressin and vasopressin for critical-care settings; hospital formulary consolidation in the Netherlands and Germany concentrates purchasing power among integrated health networks demanding validated cold-chain documentation.
- Oral:Tablet formulations at 0.1-0.2 mg desmopressin strengths; microcrystalline cellulose-based sustained-release matrices are absorbing patient-adherence risk while compressing reimbursement negotiation leverage for multi-dose generic alternatives.
- Sublingual:Rapid-dissolve wafer technologies for pediatric and geriatric compliance; limited current availability creates whitespace for palatability-enhanced formulations targeting diabetes insipidus in children.
Intranasal delivery commands the steepest compliance investment. Injectable formats retain the highest per-dose revenue concentration.
Therapeutic Area:
Application segmentation separates acute institutional demand from chronic outpatient management, with reimbursement pathways and prescriber specialization creating distinct competitive arenas.
- Nocturia:Outpatient urology applications represent the fastest-expanding margin pool as aging demographics shift treatment loci from acute to chronic care; standardized care pathways in French and German hospital systems are embedding intranasal desmopressin into recurring procurement volumes.
- Diabetes Insipidus:Stable hospital demand for both intranasal and oral desmopressin in pediatric endocrinology and nephrology practices; pediatric formulations face the steepest EMA MDR compliance ramps for device-mediated delivery.
- Shock Management:Critical-care protocols for hepatorenal syndrome and sepsis; injectable terlipressin captures this segment where rapid hemodynamic stabilization determines clinical outcomes and justifies premium pricing.
- Hemophilia:Adjunctive desmopressin for mild hemophilia A and von Willebrand disease; concentrated demand in specialized hematology centers with captive pharmacy operations.
Nocturia applications absorb the majority of new patient initiations. Shock management retains the highest per-treatment value.
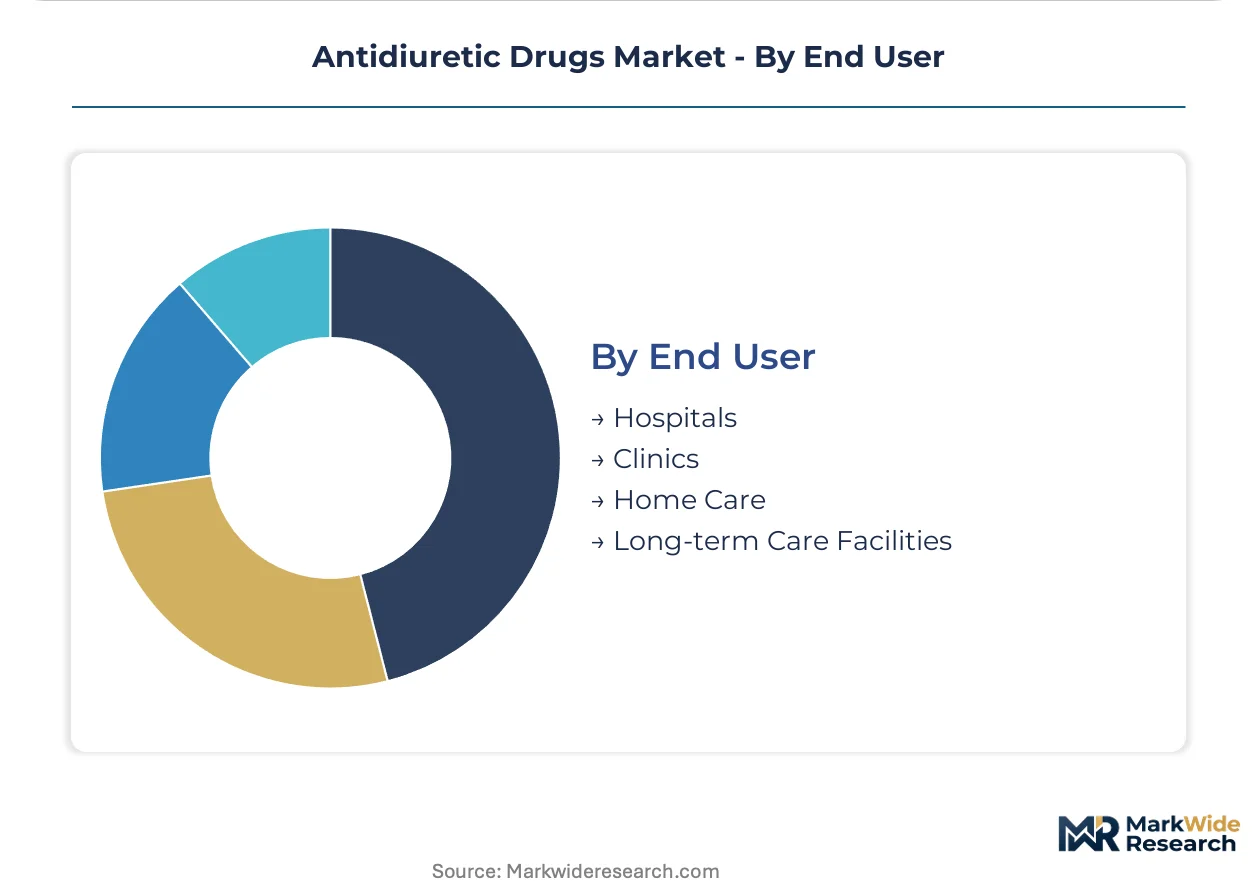
End User:
Customer segmentation reflects the concentration of purchasing authority, with centralized pharmacy and therapeutics committees displacing individual physician preference as the primary demand determinant.
- Hospitals:Academic medical centers with captive endocrinology and urology specialty volumes negotiate multi-year sole-source agreements across tablet and intranasal formats; procurement consolidation in Germany and the Netherlands elevates supplier qualification barriers.
- Clinics:Outpatient urology and endocrinology practices drive nocturia and diabetes insipidus prescribing; reimbursement complexity varies by national health technology assessment frameworks.
- Home Care:Self-administered intranasal and oral regimens for stable chronic patients; patient adherence platforms and remote monitoring integration are emerging differentiation vectors.
- Long-term Care Facilities:Geriatric nocturia management with polypharmacy considerations; dosing simplicity and fall-risk profiles influence formulary decisions.
Hospital networks concentrate volume authority. Home care channels offer the longest prescription duration economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands hospital procurement volumes for intranasal desmopressin, while the United States concentrates outpatient nocturia prescribing within integrated urology networks. France and Italy anchor terlipressin adoption for critical-care shock protocols. India emerges as a manufacturing hub for peptide synthesis serving regulated export markets.
Germany
Academic medical centers in North Rhine-Westphalia and Bavaria negotiate multi-year sole-source agreements for desmopressin across tablet and intranasal formats. The BfArM enforces EMA bioequivalence standards for peptide-based formulations with tightened purity thresholds. Frankfurt and Munich host specialized endocrinology centers driving terlipressin adoption for hepatorenal syndrome management.
United States
Hospital formulary consolidation concentrates purchasing power among integrated health networks in the Northeast and California. FDA peptide purity guidelines mandate capital-intensive chromatography upgrades for synthetic vasopressin analogues. The Boston and San Francisco corridor anchors urology department expansion of nocturia treatment protocols with intranasal delivery systems.
France
Pediatric endocrinology practices in Paris and Lyon transition compliance-critical patient cohorts to sustained-release desmopressin matrices. ANSM alignment with EMA MDR device-drug combination rules mandates human-factors validation for intranasal spray mechanisms. The Île-de-France region concentrates hospital pharmacy and therapeutics committees embedding desmopressin into standardized nocturia care pathways.
Italy
Specialized endocrinology centers in Lombardy and Emilia-Romagna expand terlipressin use for hepatorenal syndrome, displacing older vasopressor alternatives. AIFA enforces cold-chain documentation requirements for temperature-sensitive peptide formulations. Milan anchors critical-care protocol integration where rapid hemodynamic stabilization determines clinical outcomes and justifies premium pricing.
India
CDSCO alignment with BIS stability-testing protocols streamlines import licensing for cold-chain-compliant manufacturers of peptide-based biologics. Hyderabad and Bangalore host contract manufacturing organizations specializing in solid-phase peptide synthesis at pharmaceutical-grade scale. Maharashtra-based facilities serve as export hubs for desmopressin active pharmaceutical ingredients meeting FDA and EMA certification standards.
Antidiuretic Drugs Market Competitive Environment
Top-tier vendors anchor hospital formulary access, while mid-scale manufacturers compete on generic vasopressin pricing and regional distribution reach. The market structure fragments across three strategic archetypes: integrated pharmaceutical conglomerates with captive peptide synthesis capabilities, specialized endocrinology-focused firms, and multi-source generic houses leveraging fermentation-based manufacturing. Dominant competitive moves include backward integration into peptide synthesis capacity and geographic expansion through regulatory harmonization in emerging markets.
Within the specialized endocrinology tier, Ferring Pharmaceuticals and Novartis AG occupy positions anchored by European manufacturing infrastructure and North American hospital network penetration. Teva Pharmaceutical Industries Ltd exemplifies the generic-scale archetype, sustaining pricing pressure on standard vasopressin vials through multi-source competition. Otsuka Holdings Co. Ltd represents the Asia-Pacific headquartered contingent with exposure to both regulated and emerging market channels.
| Leading Market Players |
|---|
| Par Sterile Products |
| Otsuka Holdings Co. Ltd |
| Ferring Pharmaceuticals |
| Novartis AG |
| Azevan Pharmaceuticals |
| Teva Pharmaceutical Industries Ltd |
| Avadel |
| ADH Health |
| Sanofi |
| Others |
Value Chain & Pricing Dynamics
Solid-phase peptide synthesis specialists concentrated in Hyderabad and Bangalore command compensation premiums that compress margin spreads between certified biologic formulations and commodity vasopressin generics. Labor-cost differentials between Indian contract manufacturing clusters and European captive facilities translate directly into pricing-tier stratification across the antidiuretic market.
Pricing Analysis
Bundle-unbundle service splits separate cold-chain-validated distribution packages from bare API supply. Three-tier pricing structure across premium peptide formulations, standard hospital-contract desmopressin, and economy vasopressin vials reflects certification-grade differentiation. Cost compression in the generic injectable tier is intensifying because multi-source competition erodes supplier pricing power. Hospital procurement committees exhibit lowest price sensitivity for terlipressin shock protocols, while outpatient nocturia prescriptions face steepest reimbursement pressure.
Supply Chain Analysis
Direct-to-hospital channels handle formulary-integrated demand from German academic medical centers and Dutch integrated delivery networks. Manufacturing concentrates in India for peptide API synthesis, Germany for finished-dose desmopressin, and Italy for terlipressin critical-care supply. Production draws from protected amino acid building blocks, chromatography resins, and validated cold-chain packaging. Single-source vulnerability in specialized solid-phase synthesis capacity elevates supply risk. Distribution runs through hospital-centric pharmacy and therapeutics committees with multi-year contracting authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The antidiuretic drugs market functions as a stable compounder anchored by irreversible demographic shifts toward aging populations requiring chronic nocturia management.
For Market Incumbents: Deepen backward integration into peptide synthesis capacity to defend against Indian CMO pricing pressure. Secure multi-year sole-source agreements with German hospital networks before EMA MDR compliance costs escalate. Prioritize chromatography purification investments that satisfy FDA tightened impurity specifications. For New Entrants and Emerging Players: Capture whitespace in pediatric palatability-enhanced desmopressin formulations where device-drug combination rules have stalled legacy competitors. Enter through sublingual wafer technologies for diabetes insipidus compliance-critical cohorts. Leverage CDSCO-BIS harmonization to establish cold-chain credibility for Indian export manufacturing. For Investors and Strategic Acquirers: Specialized endocrinology-focused pharmaceutical firms are the most active acquirer in this space, seeking captive peptide synthesis capabilities. The five-to-ten year viability window favors targets with EMA MDR-compliant intranasal device platforms and hospital formulary lock-in. Watch for FDA peptide purity enforcement actions as inflection indicators for manufacturing consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Peptide Synthesis Capacity Expansion | Hyderabad facilities with FDA certification capture hospital procurement volumes from European incumbents. |
| EMA MDR Device Compliance Program | Human-factors validation investments separate next-generation intranasal platforms from obsolete legacy devices. |
| Hospital Formulary Partnership | Multi-year agreements with Bavarian academic centers lock out competitor access across tablet and spray formats. |
| Pediatric Formulation Development | Palatability-enhanced desmopressin wafers address unmet compliance needs in French pediatric endocrinology practices. |
| Cold-Chain Distribution Certification | BIS-validated 2-8°C logistics documentation streamlines CDSCO import licensing for temperature-sensitive biologics. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from drug development executives at peptide synthesis firms, regulatory affairs leads navigating FDA-EMA divergence, hospital procurement managers in German integrated networks, and formulary directors at Dutch academic medical centers. Secondary validation drew from FDA peptide guidance documents, EMA MDR submission databases, ClinicalTrials.gov hepatorenal syndrome protocols, and hospital pharmacy committee minutes. Bottom-up patient-flow modeling and top-down manufacturer capacity assessments were cross-referenced for triangulation.
Historical reference periods anchored volume and value projections across the modeling period. Segmentation dimensions included drug type chemistry, administration route mechanics, therapeutic area economics, and end-user purchasing authority concentration. CAGRs were derived from installed base erosion rates and new patient initiation curves. Forecast inputs incorporated EMA MDR implementation timelines and CDSCO regulatory harmonization progress.
Regulatory enforcement intensity, cold-chain infrastructure investment cycles, and hospital formulary consolidation pace are the dominant revision risks. Forecasts reflect assumptions about peptide purity standard stability and generic competition entry thresholds. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Alpha-Blocker Market
Pharmaceuticals
Alkylating Agents Market
Pharmaceuticals
Attenuated Vaccines Market
Pharmaceuticals
Plasma-Derived Drugs Market
Pharmaceuticals
Levofloxacin Lactate Injection Market
Pharmaceuticals
Nephrology Drugs Market
Pharmaceuticals
Unfractionated Heparin Market
Pharmaceuticals
H1N1 Vaccination Market
Pharmaceuticals
Organ Transplant Immunosuppressant Drugs Market
Pharmaceuticals
Asia-Pacific Contraceptives Market
Pharmaceuticals
Lipid Injectable Market
Pharmaceuticals
Novel Drug Delivery Systems in Cancer Therapy Market
Pharmaceuticals
Europe FMD Vaccine Market
Pharmaceuticals
Europe Pharmaceutical Market
Pharmaceuticals
Trenbolone Enanthate Market
Pharmaceuticals
Amoxicillin Sodium Clavulanate Potassium for Injection Market