
 Global DNA Repair Drugs Market | 2026-2036
Global DNA Repair Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global DNA Repair Drugs Market Foresight
Buyer concentration among oncology clinics and cancer treatment centers is realigning procurement power toward integrated health networks with dedicated precision medicine programs. AstraZeneca leverages its established PARP inhibitor portfolio to sustain leadership in ovarian and breast cancer indications. Merck & Co. anchors its position through broad immuno-oncology platforms that complement DNA damage response mechanisms. Pfizer competes via global manufacturing scale and hospital system partnerships that secure formulary placement.
DNA repair drugs comprise synthetic and biologic agents that modulate enzymatic pathways—including poly(ADP-ribose) polymerase, ataxia telangiectasia mutated kinase, and DNA ligase—to restore or exploit genomic integrity in malignant cells, typically formulated as oral tablets or intravenous solutions requiring cold-chain distribution. PARP inhibitors occupy the dominant revenue position due to established reimbursement in platinum-sensitive ovarian cancer and metastatic castration-resistant prostate cancer. The therapy area dimension shows prostate cancer applications expanding fastest as biomarker testing penetrates community oncology settings, while breast cancer maintains mature volume leadership with narrowing margin pools from biosimilar competition.
The FDA, EMA, and WHO collectively shape market access through oncology drug evaluation frameworks, post-market surveillance requirements, and international harmonization of genotoxicity testing standards that manufacturers must satisfy for cross-border commercialization. China's NMPA accelerates local approval timelines for DNA repair modalities through its breakthrough therapy designation, creating parallel regulatory tracks alongside Western agencies. Stakeholders must monitor evolving biomarker coverage policies from national payers to anticipate which patient subpopulations will command premium pricing versus standardized reimbursement tiers.
Market Dynamics
Oncology clinics and integrated health networks are consolidating procurement power around precision medicine programs, compressing vendor selection cycles and favoring suppliers with companion diagnostic capabilities and cold-chain reliability.
Growth Catalysts
- Biomarker Testing Expansion:Community oncology settings in the United States are deploying next-generation sequencing panels to identify homologous recombination deficiency, expanding addressable patient populations for targeted DNA repair therapies.
- Accelerated Approval Pathways:The FDA's breakthrough therapy designation compresses clinical development timelines from Phase I to commercial launch, rewarding sponsors with robust biomarker-stratified trial designs.
- Platinum-Sensitivity Protocols:Oncology treatment centers are embedding PARP inhibitor maintenance into standard-of-care pathways for ovarian and prostate malignancies, creating durable demand pull through integrated cancer networks.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Synthesis of PARP inhibitor scaffolds depends on a limited base of contract manufacturers in India and China, exposing supply continuity to geopolitical friction and import inspection backlogs.
- Reimbursement Compression:Medicare's inflation rebate provisions under the IRA are narrowing net pricing flexibility for oral oncology agents, constraining commercial strategy options for pipeline candidates.
- Resistance Mechanism Evasion:Secondary mutations in BRCA-reverted alleles and SLFN11 loss are shortening duration of response in relapsed patients, limiting long-term therapy adherence and lifetime value per patient.
Strategic Opportunities
- Combination Regimen Development:Pairing ATR inhibitors with anti-PD-1 antibodies in synthetic lethality protocols opens addressable markets beyond monotherapy-responsive subpopulations, with early signals in lung and gastric malignancies.
- Japan's Sakigake Designation:PMDA's priority review track for innovative oncology modalities offers twelve-month approval timelines, enabling first-mover positioning in Asia-Pacific's second-largest pharmaceutical market.
- At-Home Oral Administration:Tablet formulations with ambient stability profiles enable direct-to-patient distribution models, reducing infusion center burden and capturing pharmacy benefit manager channel economics.
Industry Challenges
- Companion Diagnostic Co-Development:Synchronized validation of tissue-based and liquid biopsy assays with drug candidates demands cross-functional coordination between pharmaceutical and diagnostic development teams, extending program timelines.
- Cold-Chain Integrity at Last Mile:Intravenous DNA repair agents require uninterrupted temperature control through hospital pharmacy receipt, with deviation events triggering batch quarantine and patient treatment delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global DNA Repair Drugs Market |
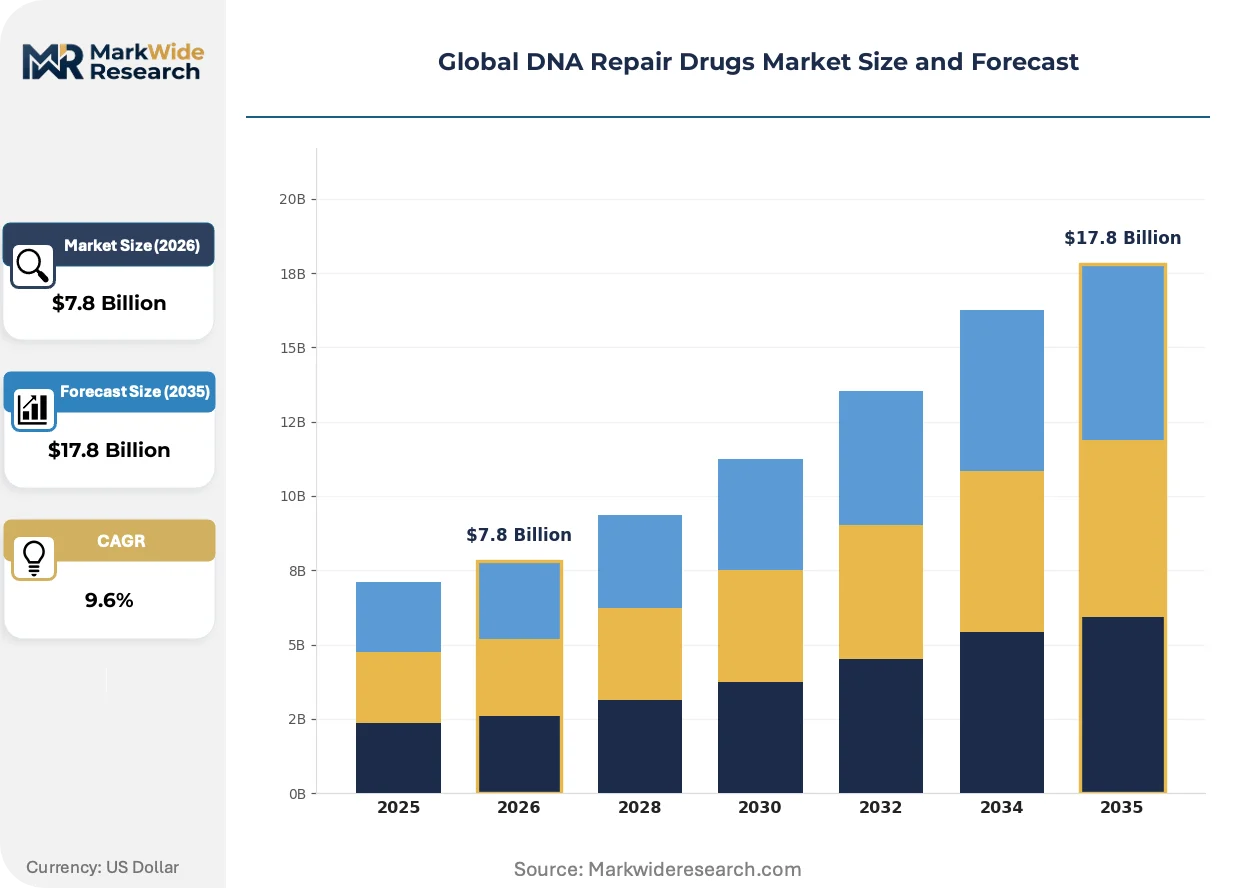
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $17.8 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PARP Inhibitors, DNA Ligase Inhibitors, ATM Kinase Inhibitors, DNA Polymerase Inhibitors, Others Therapy Area: Ovarian Cancer, Prostate Cancer, Breast Cancer, Lung Cancer, Pancreatic Cancer End User: Hospitals, Oncology Clinics, Research Institutes, Cancer Treatment Centers Delivery Mode: Oral, Intravenous, Subcutaneous, Topical |
| Companies Covered | AstraZeneca, Pfizer, Merck & Co., AbbVie, GlaxoSmithKline, Bristol-Myers Squibb, Johnson & Johnson, Novartis, Clovis Oncology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global DNA Repair Drugs Market Shifts & Advancements
DNA repair drug development is pivoting from single-agent PARP inhibition toward rational combination protocols and allosteric mechanism targeting, compressing the competitive window for established therapeutic classes.
Allosteric ATR kinase inhibitors are consolidating preclinical and early clinical portfolios as the next mechanistic wave beyond ATP-competitive PARP blockade. Biopharmaceutical sponsors are prioritizing these candidates for combination with platinum chemotherapy and immune checkpoint blockade. The technology is consolidating investment allocation away from incremental PARP inhibitor formulation improvements toward novel DNA damage response nodes.
The EMA's oncology drug evaluation framework now mandates real-world evidence generation plans at initial marketing authorization, conditioning full approval on post-market outcome validation. This industrial consequence forces sponsors to build European patient registry infrastructure during Phase III execution. Metastatic castration-resistant prostate cancer indications face the steepest evidentiary burden, with conditional approvals requiring survival endpoint confirmation within defined timelines.
Integrated delivery networks are unbundling oncology pharmacy procurement from group purchasing organization contracts, negotiating direct manufacturer agreements for oral oncolytics. Hospital system formularies are replacing traditional wholesaler relationships with specialty pharmacy carve-outs and 340B program optimization. This behavioral shift is most visible in United States community oncology practices consolidating under regional health system umbrellas, where pharmacy benefit integration enables risk-based contracting for precision therapies.
Global DNA Repair Drugs Market Segmentation
Segmentation in DNA repair therapeutics reveals how mechanistic specificity, biomarker-defined patient populations, and site-of-care economics reshape procurement patterns across oncology networks. Understanding these divides exposes where pricing power concentrates and which development pipelines face compressed commercial windows.
Product Type:
Oncology formularies prioritize agents with companion diagnostic validation and established reimbursement pathways, concentrating procurement around proven mechanisms.
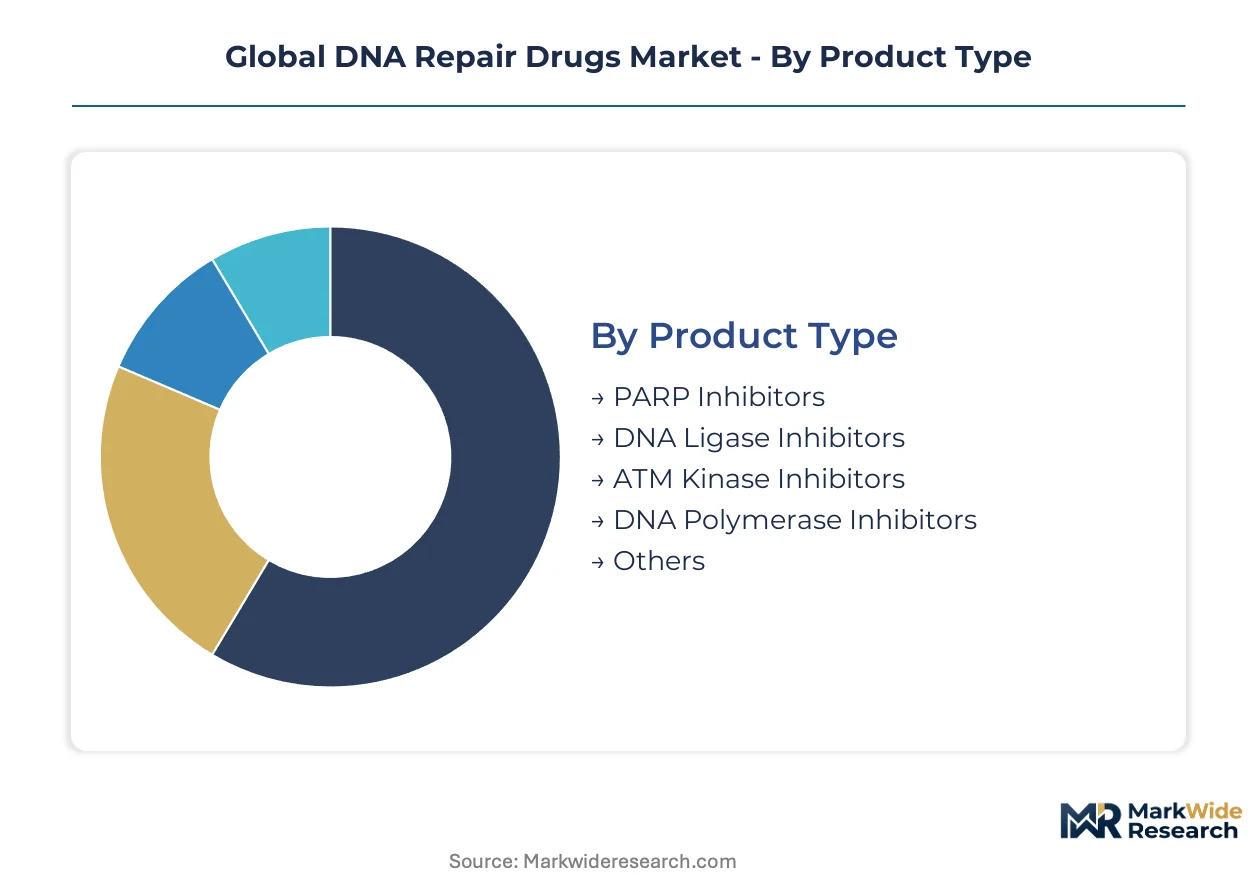
- PARP Inhibitors:Synthetic agents blocking poly(ADP-ribose) polymerase enzymes dominate current prescribing in platinum-sensitive ovarian and metastatic castration-resistant prostate malignancies. United States integrated cancer networks embed these agents into maintenance protocols, though Medicare inflation rebate provisions constrain net pricing flexibility.
- ATM Kinase Inhibitors:Small-molecule inhibitors targeting ataxia telangiectasia mutated kinase are advancing through combination trials with immune checkpoint blockade. Early clinical signals in lung and gastric settings are attracting biopharmaceutical investment toward synthetic lethality protocols beyond PARP-responsive populations.
- DNA Ligase Inhibitors:Agents disrupting DNA strand ligation represent an emerging mechanistic class with preclinical focus on combination with platinum chemotherapy.
- DNA Polymerase Inhibitors:Compounds interfering with replicative polymerases occupy niche development portfolios targeting hypermutated tumor subtypes.
- Others:Experimental modalities including RAD51 inhibitors and POLQ-targeting agents populate early-stage pipelines.
Volume sits with PARP inhibitors; growth tilts toward ATM kinase inhibitors.
Therapy Area:
Biomarker testing penetration and regulatory precedent determine which malignancies command development resources and premium access.
- Ovarian Cancer:Homologous recombination deficiency testing in first-line settings has cemented PARP inhibitor maintenance as standard of care. United States community oncology consolidation under regional health systems accelerates protocol adoption through integrated pharmacy benefit structures.
- Prostate Cancer:Metastatic castration-resistant indications are expanding most quickly as germline and somatic BRCA testing penetrates urology and community oncology practices. The EMA now mandates real-world evidence generation plans at initial marketing authorization for this indication, conditioning full approval on survival endpoint confirmation.
- Breast Cancer:Germline BRCA-mutated HER2-negative disease maintains mature prescribing volumes with narrowing margin pools from biosimilar competition and payer consolidation.
- Lung Cancer:Squamous and non-squamous histologies represent emerging targets for ATR inhibitor combinations with anti-PD-1 antibodies.
- Pancreatic Cancer:Germline BRCA-mutated subpopulations comprise a small addressable market with significant unmet need and limited therapeutic alternatives.
Breast cancer commands current volume leadership; prostate cancer applications are climbing the fastest.
End User:
Site-of-care economics and reimbursement complexity filter which institutions can sustain precision oncology programs.
- Oncology Clinics:Community-based infusion centers and physician office laboratories are consolidating under integrated health network umbrellas. These entities negotiate direct manufacturer agreements for oral oncolytics, bypassing traditional group purchasing organization contracts.
- Hospitals:Academic medical centers and tertiary care institutions anchor clinical trial infrastructure and early adoption of novel DNA damage response agents. Cold-chain reliability requirements for intravenous formulations favor hospital pharmacy receipt capabilities.
- Cancer Treatment Centers:Dedicated oncology facilities with embedded pathology and molecular diagnostics enable biomarker-driven treatment selection at scale.
- Research Institutes:Translational medicine centers and cooperative oncology groups generate the real-world evidence increasingly required by EMA and FDA for full regulatory approval.
Procurement concentrates in oncology clinics; capability investment tilts toward cancer treatment centers.
Delivery Mode:
Formulation stability and administration setting determine distribution economics and patient adherence profiles.
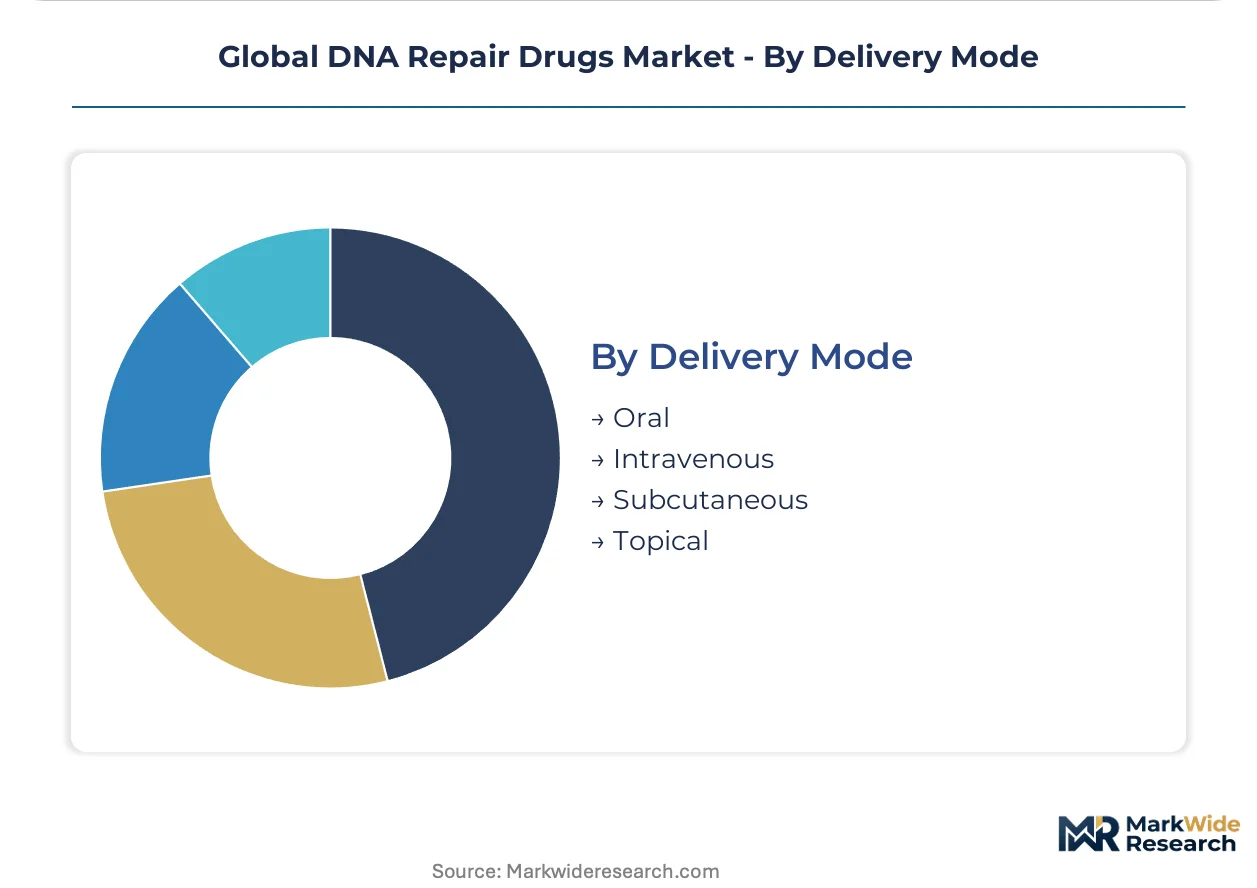
- Oral:Tablet formulations with ambient stability enable direct-to-patient distribution models and pharmacy benefit manager channel capture. Ambient stability profiles reduce infusion center burden and support at-home administration protocols.
- Intravenous:Hospital-administered solutions require uninterrupted cold-chain integrity through pharmacy receipt, with temperature deviation events triggering batch quarantine and treatment delays.
- Subcutaneous:Self-administered injections occupy limited current portfolios but offer potential for reduced healthcare utilization.
- Topical:Localized delivery remains experimental for DNA repair modulation in cutaneous malignancies.
Revenue pools favor oral delivery; infrastructure investment addresses intravenous cold-chain requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision oncology procurement concentrates in the United States, where Medicare reimbursement and dense clinical trial infrastructure create unmatched demand pull for DNA repair therapeutics. Secondary markets in Western Europe and East Asia follow with differentiated regulatory pathways and biomarker testing penetration rates.
United States
Oncology clinics in Texas and Florida are consolidating under regional health system umbrellas, embedding PARP inhibitor maintenance into standard-of-care pathways. The FDA's breakthrough therapy designation compresses development timelines for sponsors with biomarker-stratified trial designs. The Greater Boston corridor anchors translational research infrastructure for synthetic lethality protocols.
Germany
Academic medical centers in Bavaria and Baden-Württemberg drive early adoption of novel DNA damage response agents through embedded pathology and molecular diagnostics. The EMA's oncology drug evaluation framework mandates real-world evidence generation plans at initial marketing authorization. Heidelberg and Munich clusters concentrate Phase III execution capabilities for European patient registry infrastructure.
Japan
Community oncology settings in the Kanto region are deploying next-generation sequencing panels to identify homologous recombination deficiency. The PMDA's Sakigake designation offers twelve-month approval timelines for innovative oncology modalities. The Tokyo-Osaka corridor anchors Asia-Pacific's second-largest pharmaceutical market for first-mover positioning.
China
Contract manufacturers in Jiangsu and Zhejiang provinces supply active pharmaceutical ingredients for PARP inhibitor scaffolds, exposing supply continuity to import inspection backlogs. The NMPA accelerates local approval timelines through breakthrough therapy designation. The Yangtze River Delta concentrates biopharmaceutical investment toward novel DNA damage response nodes.
Switzerland
Specialty pharmacy operations in Basel and Zurich enable direct-to-patient distribution models for oral oncolytics with ambient stability profiles. Swissmedic harmonizes cross-border commercialization standards with EMA genotoxicity testing requirements. The Basel cluster anchors European headquarters for integrated precision medicine programs.
Global DNA Repair Drugs Market Competitive Landscape
United States-based pharmaceutical conglomerates anchor one tier; European and Japanese specialists hold differentiated positions through regional regulatory expertise and targeted oncology portfolios. The vendor base stratifies across three tiers: integrated multinationals with companion diagnostic capabilities, mid-cap biopharmaceuticals with synthetic letharity-focused pipelines, and emerging specialists in allosteric kinase modulation. Consolidation favors suppliers with cold-chain reliability and hospital system partnerships. Competitive moves center on combination regimen development and biomarker co-validation strategies.
Among integrated multinationals, AstraZeneca, Pfizer, and Merck & Co. exemplify the dominant competitive archetype. AstraZeneca represents sustained leadership in established PARP inhibitor portfolios. Pfizer occupies a position anchored by global manufacturing scale. Merck & Co. sits within the tier defined by broad immuno-oncology platforms that complement DNA damage response mechanisms.
| Leading Market Players |
|---|
| AstraZeneca |
| Pfizer |
| Merck & Co. |
| AbbVie |
| GlaxoSmithKline |
| Bristol-Myers Squibb |
| Johnson & Johnson |
| Novartis |
| Clovis Oncology |
| Others |
Supply & Pricing Matrix
Synthetic chemists concentrated in Hyderabad and Shanghai create labor-cost differentials that widen pricing-tier spreads between originator PARP inhibitors and contract-manufactured alternatives. API synthesis complexity and cold-chain logistics costs further stratify procurement economics across oncology networks.
Pricing Analysis
Volume pools in oral PARP inhibitors while margins compress under Medicare inflation rebate provisions; premium-mid-economy pricing differentiation separates patented maintenance therapies from authorized generics and biosimilar entrants. Price differentiation hinges on companion diagnostic bundling and platinum-sensitivity biomarker validation. Pricing pressure stems from IRA rebate mechanics constraining net pricing flexibility for oral oncology agents. Community oncology clinics under integrated health networks exhibit highest price sensitivity; academic medical centers with research funding show lowest.
Supply Chain Analysis
Single-source vulnerability sits with contract manufacturers in Jiangsu and Zhejiang provinces for PARP inhibitor scaffolds. Active pharmaceutical ingredient production draws from India, China, and Switzerland; formulation and fill-finish rest on facilities in the United States, Germany, and Ireland. Supply chain risk centers on import inspection backlogs and geopolitical friction affecting API continuity. Distribution runs through specialty pharmacy carve-outs and hospital pharmacy direct agreements, bypassing traditional wholesaler channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
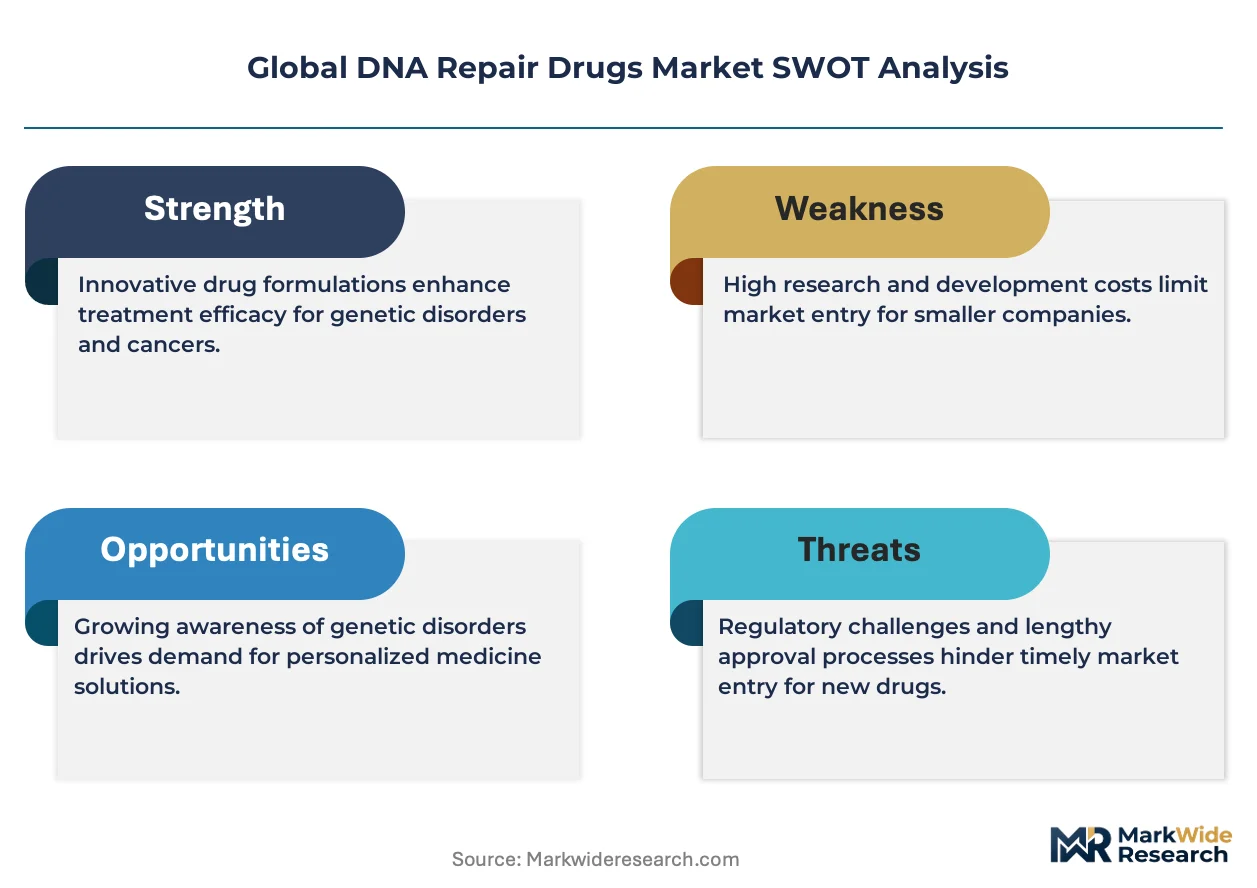
The DNA repair drugs market is becoming a vertical-integration race as players pursue captive supply of companion diagnostic capabilities to secure formulary placement and biomarker co-validation.
For Market Incumbents: Lock in cold-chain reliability partnerships with integrated cancer networks to defend against ATR inhibitor entrants threatening PARP market share. Prioritize backward integration into liquid biopsy assay development to synchronize diagnostic validation with drug approval timelines. Invest in ambient-stable tablet formulations to capture pharmacy benefit manager channel economics away from infusion-dependent competitors.
For New Entrants and Emerging Players: The FDA's breakthrough therapy designation in the United States opens a window for synthetic lethality candidates with robust biomarker-stratified trial designs to accelerate commercial timelines. Target prostate cancer maintenance settings where germline BRCA testing penetration remains incomplete in community urology practices. Pursue direct-to-patient distribution partnerships with specialty pharmacies to bypass hospital formulary gatekeeping.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap biopharmaceuticals possessing allosteric ATR kinase inhibitor pipelines given combination regimen validation with anti-PD-1 antibodies. Long-term viability favors sponsors with integrated diagnostic capabilities and hospital system partnerships spanning the analysis window. Monitor EMA real-world evidence generation mandates as the signal for which prostate cancer candidates will secure full versus conditional approval.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Synchronized FDA validation of tissue-based and liquid biopsy assays compresses approval timelines for targeted therapies. |
| At-Home Oral Formulation Development | Ambient-stable tablets enable pharmacy benefit manager channel capture and reduce infusion center dependency. |
| Combination Regimen Clinical Trials | ATR inhibitor pairing with anti-PD-1 antibodies expands addressable markets beyond monotherapy-responsive populations. |
| Cold-Chain Infrastructure Investment | Uninterrupted temperature control through hospital pharmacy receipt prevents batch quarantine and treatment delays. |
| Real-World Evidence Registry Buildout | European patient registry infrastructure satisfies EMA conditional approval requirements for metastatic castration-resistant prostate cancer indications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers cross-validated quantitative assumptions. FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases supplied segmentation inputs. Bottom-up patient-flow modeling and top-down revenue reconciliation triangulated market size estimates.
Segmentation granularity operated at the mechanism-of-action, therapy-area, end-user, and delivery-mode dimensions across the projection horizon. Treatment line, biomarker status, and regional regulatory cluster variables shaped patient-access modeling. CAGRs derived from epidemiology-adjusted penetration curves and pricing scenario analysis. Forecast inputs incorporated companion diagnostic adoption rates and reimbursement policy trajectories without year-specific assumptions.
Caveats apply where biomarker testing reimbursement shifts or resistance mechanism emergence could materially shift the outlook. Forecasts reflect assumptions about regulatory pathway continuity and platinum-chemotherapy standard-of-care persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Calcium Channel Blocker Market
Pharmaceuticals
SGLT2 Inhibitors Market
Pharmaceuticals
Global Varicella Vaccine Market
Pharmaceuticals
Global Equine Pharmaceuticals and Supplements Market
Pharmaceuticals
Trulicity Market
Pharmaceuticals
Pharma 4.0 Market
Pharmaceuticals
Authorized Generics Market
Pharmaceuticals
Cerumenolytic Agents Market
Pharmaceuticals
South Africa Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Injectable Potassium Phosphate Market
Pharmaceuticals
Vaginal Antifungals Market
Pharmaceuticals
Global Nasal Drug Delivery Market
Pharmaceuticals
Hospital Pharmaceuticals Market
Pharmaceuticals
Global Anthrax Vaccine Market
Pharmaceuticals
US Generic Injectables Pharmaceutical Contract Manufacturing Market