
 Zoledronic Acid Market | 2026-2036
Zoledronic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Zoledronic Acid Market Analysis
The Zoledronic Acid Market is repositioning around a widening split between premium branded infusion therapies and commoditized generic injectables. Novartis AG anchors the premium segment through its established intravenous oncology and osteoporosis protocols. Teva Pharmaceutical Industries Ltd competes aggressively in generic injectable supply across regulated markets. Dr. Reddy's Laboratories Ltd leverages cost-optimized manufacturing to extend its presence in emerging markets where price sensitivity dominates purchasing decisions.
Zoledronic acid is a nitrogen-containing bisphosphonate with a heterocyclic imidazole ring, synthesized through a multi-step organic route involving phosphonic acid substitution; it functions primarily as an osteoclast inhibitor for treating hypercalcemia of malignancy, multiple myeloma bone disease, and Paget's disease. The therapy area dimension shows oncology applications commanding the deepest margin pools due to longer treatment durations and higher reimbursement tiers, while osteoporosis represents the largest volume base with accelerating generic substitution. Injectable delivery dominates hospital and clinic channels, though infusion formulations sustain premium positioning in cancer care settings where dosing precision and patient monitoring requirements are most stringent.
FDA bioequivalence standards and EMA Good Manufacturing Practice directives shape product approval pathways and facility inspection intensity for zoledronic acid manufacturers. The central bank and national health technology assessment bodies in major markets increasingly condition reimbursement on demonstrated clinical equivalence against reference products. Stakeholders must monitor evolving pharmacovigilance requirements for renal safety labeling and the pace of biosimilar-like competition in infusion formats.
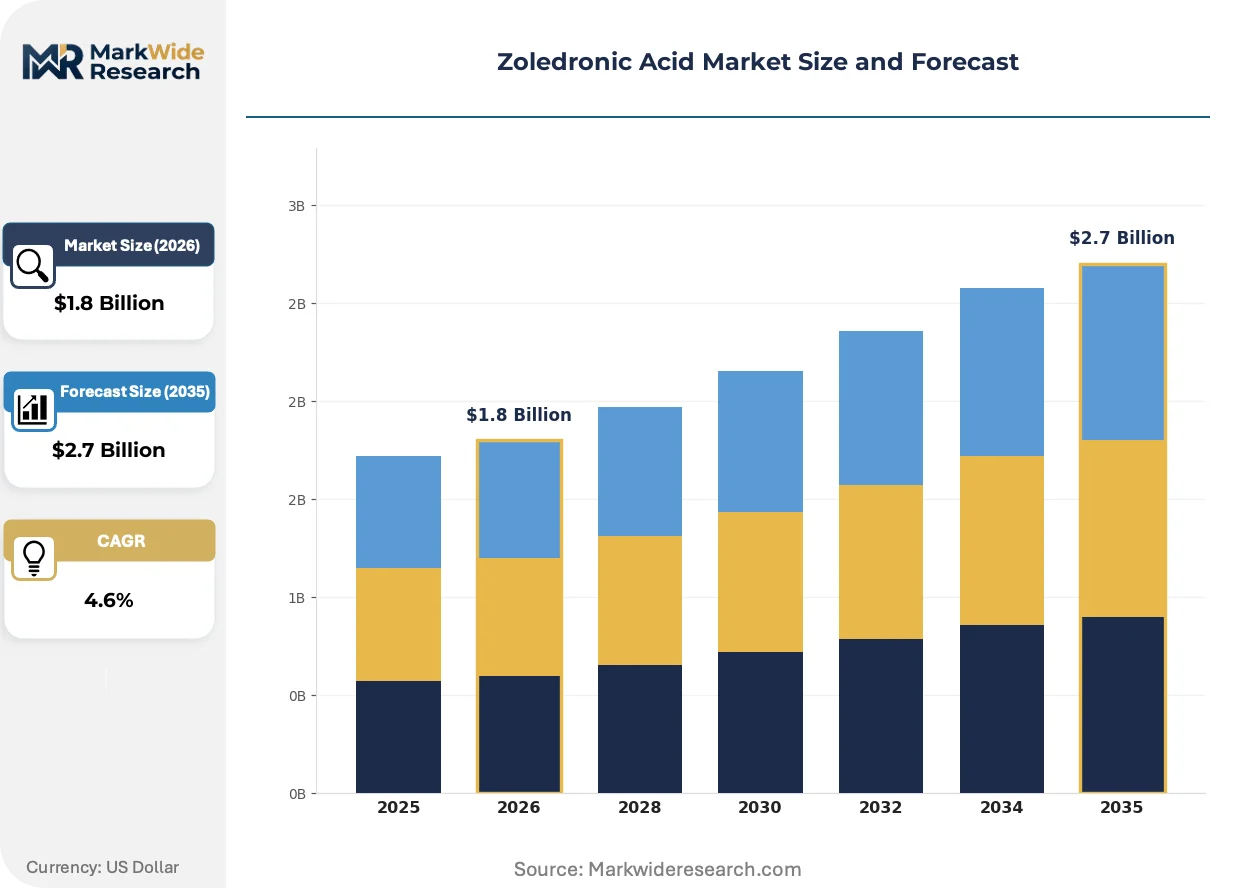
Market Dynamics
The Zoledronic Acid Market is splitting along a fault line between hospital-administered infusion protocols and outpatient generic injectables, with FDA and EMA bioequivalence standards tightening the technical barrier between these two tiers and concentrating margin capture in oncology settings.
Growth Catalysts
- Oncology infusion protocols:Extended treatment durations for multiple myeloma and bone metastases generate recurring revenue streams. Hospital networks in the United States, Germany, and Japan are expanding dedicated infusion centers.
- EMA Good Manufacturing Practice directives:Stringent facility inspection protocols are filtering out substandard manufacturers. Surviving suppliers capture volume from decommissioned production lines.
- Reimbursed access expansion:National health technology assessment bodies in major markets are broadening coverage criteria for osteoporosis and cancer-related bone disease management.
Market Restraints
- Phosphonic acid feedstock volatility:Multi-step organic synthesis requires specialized precursors with concentrated supply origins. Input cost swings compress margins for non-integrated manufacturers.
- Renal safety labeling requirements:Pharmacovigilance mandates from FDA and EMA impose additional monitoring burdens. Dosing restrictions limit addressable patient populations.
- Oral bisphosphonate substitution:Alendronate and risedronate tablets compete for first-line osteoporosis therapy. Payer preference for oral routes erodes zoledronic acid volume in non-oncology indications.
Strategic Opportunities
- Underpenetrated emerging markets:India and Brazil present volume expansion potential where price sensitivity currently favors generic injectables. Local manufacturing partnerships can circumvent import cost barriers.
- Dual carbon goals in China:NMPA green chemistry incentives reward process optimization. Manufacturers adopting cleaner synthesis routes gain regulatory priority review.
- Home infusion channel development:Specialty pharmacy networks are building capacity for ambulatory bisphosphonate administration. This channel bypasses hospital capacity constraints.
Industry Challenges
- Sterile injectable manufacturing expertise:Aseptic processing and pyrogen control require specialized workforce capabilities. Talent scarcity constrains capacity expansion timelines.
- Cross-reference product dossier complexity:Generic applicants must demonstrate bioequivalence against originator infusion protocols. FDA bioequivalence study design requirements extend development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zoledronic Acid Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Oral, Infusion, Solution Therapy Area: Osteoporosis, Oncology, Paget's Disease, Dental End User: Hospitals, Clinics, Homecare, Research Institutions Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Others |
| Companies Covered | Abbott Laboratories, Cipla Limited, Novartis AG, Hetero Labs Limited, Intas Pharmaceuticals Limited, Teva Pharmaceutical Industries Ltd, Dr. Reddy's Laboratories Ltd, Alkem Laboratories Limited, Amgen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zoledronic Acid Market Emerging Trajectories
Manufacturing technology and regulatory scrutiny are converging to reshape competitive positioning in bisphosphonate supply, with process innovation and compliance automation emerging as the primary vectors of differentiation.
Continuous flow chemistry is absorbing traditional batch synthesis for zoledronic acid production. Mid-scale manufacturers in regulated markets are retrofitting facilities to reduce solvent waste and improve yield consistency. This technology is absorbing cost premiums previously justified by originator brand positioning.
EMA's updated Good Manufacturing Practice Annex 1 for sterile medicinal products imposes enhanced environmental monitoring requirements. Facility upgrade costs are diverting capital from commercial expansion toward compliance infrastructure. Oncology infusion formats face the steepest validation burdens due to extended shelf-life claims.
Hospital procurement committees are consolidating supplier rosters around dual-source security requirements. Single-source generic relationships are losing share to manufacturers with redundant production sites. This concentration is most visible in German hospital networks, where regional purchasing cooperatives enforce supply resilience criteria.
Zoledronic Acid Market Segmentation
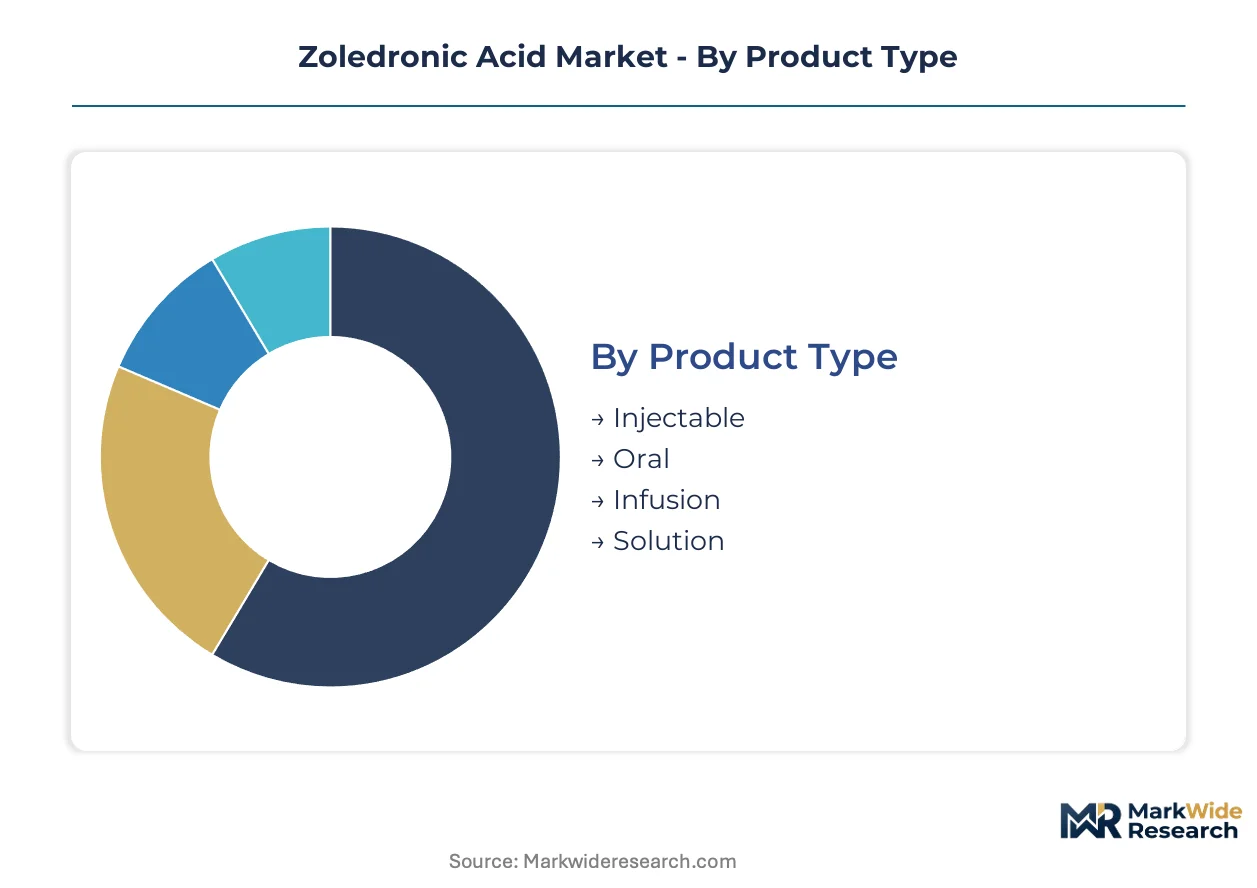
Zoledronic acid's therapeutic versatility demands granular segmentation to capture divergent margin structures across oncology and osteoporosis settings. Product format and delivery mode selections directly determine reimbursement tiers and manufacturing compliance burdens.
Product Type:
Customization intensity varies sharply across this category, with infusion formats requiring sterile facility validation while oral alternatives compete on cost.
- Injectable:Prefilled syringes and vials dominate outpatient osteoporosis protocols. Demand concentrates in United States Medicare-reimbursed clinic settings where annual dosing drives patient compliance.
- Infusion:Hospital-administered intravenous bags command premium positioning through longer oncology treatment courses. German hospital networks enforce dual-source procurement requirements for this format.
- Oral:Bioavailability challenges limit uptake to markets with severe infusion capacity constraints.
- Solution:Concentrated liquid formulations serve compounding pharmacies with specialized preparation licenses.
Injectable leads on scale; Infusion leads on momentum.
Therapy Area:
Margin profiles diverge by treatment duration and monitoring intensity, with cancer applications sustaining higher per-patient revenue despite smaller addressable populations.
- Oncology:Multiple myeloma and bone metastasis protocols generate recurring hospital revenue through extended treatment durations. Japanese reimbursement policies favor zoledronic acid over denosumab in specific cancer lines.
- Osteoporosis:Postmenopausal and glucocorticoid-induced indications represent the largest volume base. United Kingdom NICE guidelines restrict first-line access, compressing margins through generic substitution.
- Paget's Disease:Niche indication with limited protocol diversity and concentrated specialist prescriber networks.
- Dental:Off-label osteonecrosis prophylaxis generates sporadic demand tied to oral surgery referral patterns.
Osteoporosis leads on scale; Oncology leads on momentum.
End User:
Channel selection dictates compliance architecture, with hospital networks imposing sterility validation standards that filter supplier participation.
- Hospitals:Integrated delivery networks consolidate purchasing across infusion centers and inpatient units. FDA bioequivalence documentation requirements extend supplier onboarding timelines.
- Clinics:Outpatient rheumatology and oncology practices favor single-dose convenience packaging. German regional purchasing cooperatives enforce supply resilience criteria for clinic contracts.
- Homecare:Specialty pharmacy networks build ambulatory bisphosphonate administration capacity. This channel bypasses hospital capacity constraints in United States markets.
- Research Institutions:Clinical trial supply demands batch-level documentation and cold chain integrity.
Hospitals lead on scale; Homecare leads on momentum.
Delivery Mode:
Technical sophistication and patient monitoring requirements stratify competitive positioning across administration routes.
- Intravenous:Fifteen-minute infusion protocols balance efficacy with clinic throughput. Renal function monitoring requirements limit administration to settings with laboratory access.
- Subcutaneous:Emerging delivery formats seek to displace infusion dependency in select osteoporosis populations. EMA pharmacovigilance frameworks impose additional safety documentation burdens.
- Intramuscular:Limited bioavailability restricts application to markets with severe intravenous infrastructure gaps.
- Others:Investigational routes including transdermal patches remain preclinical.
Intravenous leads on scale; Subcutaneous leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized workforce concentrations in sterile injectable manufacturing anchor geographic demand clusters. Hospital pharmacy technicians and infusion nursing specialists concentrate in markets with mature oncology infrastructure. Regulatory harmonization efforts are redistributing production capacity across jurisdictions with aligned GMP standards.
United States
Medicare reimbursement expansion for annual zoledronic acid infusions drives outpatient clinic demand. FDA bioequivalence study requirements for generic applicants extend development timelines. The Greater Boston corridor hosts concentrated clinical trial infrastructure for bisphosphonate safety monitoring.
Germany
Regional hospital purchasing cooperatives enforce dual-source procurement mandates for infusion therapies. EMA Annex 1 sterile manufacturing directives accelerate facility upgrade cycles. The Rhine-Ruhr metropolitan area concentrates aseptic processing talent pools serving hospital network contracts.
Japan
PMDA reimbursement policies favor zoledronic acid over alternative bone-modifying agents in specific oncology lines. METI industrial policy supports domestic sterile injectable capacity retention. The Kansai region maintains specialized phosphonate synthesis expertise.
India
CDSCO accelerated approval pathways for generic injectables attract export-oriented manufacturing investment. PLI scheme incentives for active pharmaceutical ingredient production reduce phosphonic acid import dependency. Hyderabad and Ahmedabad clusters specialize in cost-optimized bisphosphonate synthesis.
China
NMPA green chemistry incentives reward process optimization in zoledronic acid manufacturing. Dual carbon goals pressure solvent-intensive batch synthesis operations. The Yangtze River Delta concentrates contract development and manufacturing organizations serving regulated markets.
Zoledronic Acid Market Vendor Landscape
Capital-heavy producers compete with asset-light formulation specialists across the zoledronic acid supply base. The market structure tilts toward tiered consolidation, with originator-backed infusion protocols commanding premium positioning while generic injectable supply fragments across cost-optimized manufacturers. Three archetypes dominate: integrated pharmaceutical conglomerates with hospital channel control, mid-scale generic houses with sterile facility specialization, and emerging market producers leveraging process chemistry advantages. Competitive moves center on capacity expansion in EMA-inspected facilities and strategic partnerships with regional hospital purchasing cooperatives.
Among Swiss-anchored conglomerates, Novartis AG exemplifies the premium-tier archetype through established intravenous oncology protocols. Teva Pharmaceutical Industries Ltd and Dr. Reddy's Laboratories Ltd occupy positions on the generic-specialist vector, with the former representing Israeli sterile injectable expertise and the latter exemplifying Indian cost-optimized manufacturing scale. These three anchors illustrate the geographic and strategic segmentation structuring competitive rivalry.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Cipla Limited |
| Novartis AG |
| Hetero Labs Limited |
| Intas Pharmaceuticals Limited |
| Teva Pharmaceutical Industries Ltd |
| Dr. Reddy's Laboratories Ltd |
| Alkem Laboratories Limited |
| Amgen |
| Others |
Supply Flow & Price Mechanics
German hospital purchasing cooperatives enforcing dual-source procurement mandates for infusion therapies are compressing supplier margins while filtering participation toward manufacturers with redundant sterile production sites. This buyer consolidation dynamic forces supply base rationalization and concentrates pricing power among EMA-inspected facilities with validated aseptic processing capabilities.
Pricing Analysis
Bundled oncology infusion services commanding premium positioning separate from commoditized outpatient injectable supply. Pricing stratifies across originator-branded hospital protocols, multi-source generic injectables, and economy-tier emerging market supply. Cost compression in osteoporosis generics intensifies because oral bisphosphonate substitution erodes volume. Clinic buyers exhibit highest price sensitivity; integrated hospital networks prioritize supply security over unit cost.
Supply Chain Analysis
Cold chain logistics and specialized freight handling for sterile injectables elevate distribution costs above standard pharmaceutical freight. Manufacturing concentrates in India, China, and Switzerland with phosphonic acid feedstock sourcing from concentrated chemical suppliers. Single-source vulnerability in heterocyclic imidazole ring precursors creates exposure to input disruption. Distribution runs through hospital purchasing cooperatives and specialty pharmacy networks with direct-to-clinic bypass emerging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in oncology infusion formats where extended treatment duration and bundled service pricing offset generic pressure in osteoporosis. Continuous flow chemistry adoption and EMA Annex 1 compliance automation represent the primary cost-down vectors enabling premium-tier positioning.
For Market Incumbents: Cement hospital channel control through redundant EMA-inspected facility investment and long-term procurement contracts with German regional purchasing cooperatives. Threat from denosumab and oral bisphosphonate substitution demands defensive formulary access maintenance. Backward integration into phosphonic acid precursors secures input cost stability against feedstock volatility. For New Entrants and Emerging Players: Capture volume in Indian and Brazilian outpatient clinic segments where price sensitivity favors cost-optimized generic injectables. Homecare specialty pharmacy channels present the most penetrable white-space with ambulatory bisphosphonate administration bypassing hospital capacity constraints. Partner with regional distributors possessing existing cold chain infrastructure to accelerate market access. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale sterile injectable specialists possessing EMA-inspected capacity and established hospital network relationships. Long-term viability hinges on oncology infusion format retention against biosimilar-like competition. Monitor PMDA reimbursement policy shifts in Japan as inflection indicator for regional pricing power migration.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Annex 1 Compliance Investment | Facility upgrades filter substandard manufacturers and capture decommissioned competitor volume. |
| Continuous Flow Chemistry Retrofit | Process innovation reduces solvent waste and narrows cost gap with originator positioning. |
| Dual-Source Hospital Contracting | German purchasing cooperative mandates reward redundant production site operators. |
| Homecare Channel Partnership | Specialty pharmacy networks bypass hospital capacity constraints in United States markets. |
| Phosphonic Acid Backward Integration | Captive precursor supply insulates margins against concentrated feedstock price volatility. |
Methodological Framework
Bottom-up hospital and clinic demand modeling reconciled against top-down sterile injectable manufacturing capacity tracking forms the analytical core. Primary interviews with hospital procurement managers, regulatory affairs directors, formulary committee chairs, and specialty pharmacy network executives combined with secondary validation from FDA bioequivalence filings, EMA GMP inspection records, and national health technology assessment reimbursement databases. Triangulation across supply-side facility audits and demand-side purchasing pattern analysis ensures coverage completeness.
Input-output matrices map phosphonic acid feedstock availability through finished zoledronic acid dosage form output across the projection horizon. Segmentation dimensions modeled include therapy area, product format, delivery mode, and end-user channel with regional regulatory cluster overlays. CAGRs derive from volume trajectory analysis against pricing tier migration patterns. Forecast inputs incorporate EMA Annex 1 implementation timelines and PMDA reimbursement policy evolution.
Phosphonic acid supply disruption, accelerated oral bisphosphonate substitution, and renal safety labeling expansion are the dominant revision risks. Forecasts reflect documented assumptions regarding hospital infusion center capacity expansion and generic penetration rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Water for Injection Market
Pharmaceuticals
Galculus Bovis and Metronidazole Market
Pharmaceuticals
Congestive Heart Failure Drugs Market
Pharmaceuticals
Global Esketamine Market
Pharmaceuticals
Cervical Cancer Vaccine Market
Pharmaceuticals
US Intravenous Immunoglobulin Market
Pharmaceuticals
North America Biguanide Market
Pharmaceuticals
Hepatitis - B Therapeutics Market
Pharmaceuticals
Cholinesterase Inhibitors Market
Pharmaceuticals
Oral Anti-Diabetic Drugs Market
Pharmaceuticals
Middle-East and Africa Meglitinide Market
Pharmaceuticals
Sterile Dosage Form Market
Pharmaceuticals
US Pharmacy Market
Pharmaceuticals
Lamotrigine API Market
Pharmaceuticals
Normal Saline for Parenteral Use Market
Pharmaceuticals
Compound Acetaminophen Market