
 US Pharmaceutical CMO Market | 2026-2036
US Pharmaceutical CMO Market Size, Share, and Industry Trends Forecast 2026-2036
US Pharmaceutical CMO Market Analytics
Biologics manufacturing is shifting from stainless steel to single-use systems, cutting changeover costs and contamination risk. Thermo Fisher Scientific leverages its integrated service platform across drug substance and drug product stages. Lonza Group AG anchors cell and gene therapy capacity through specialized biologics facilities. Catalent Inc. dominates oral solid dose and softgel technologies with broad FDA-inspected site coverage.
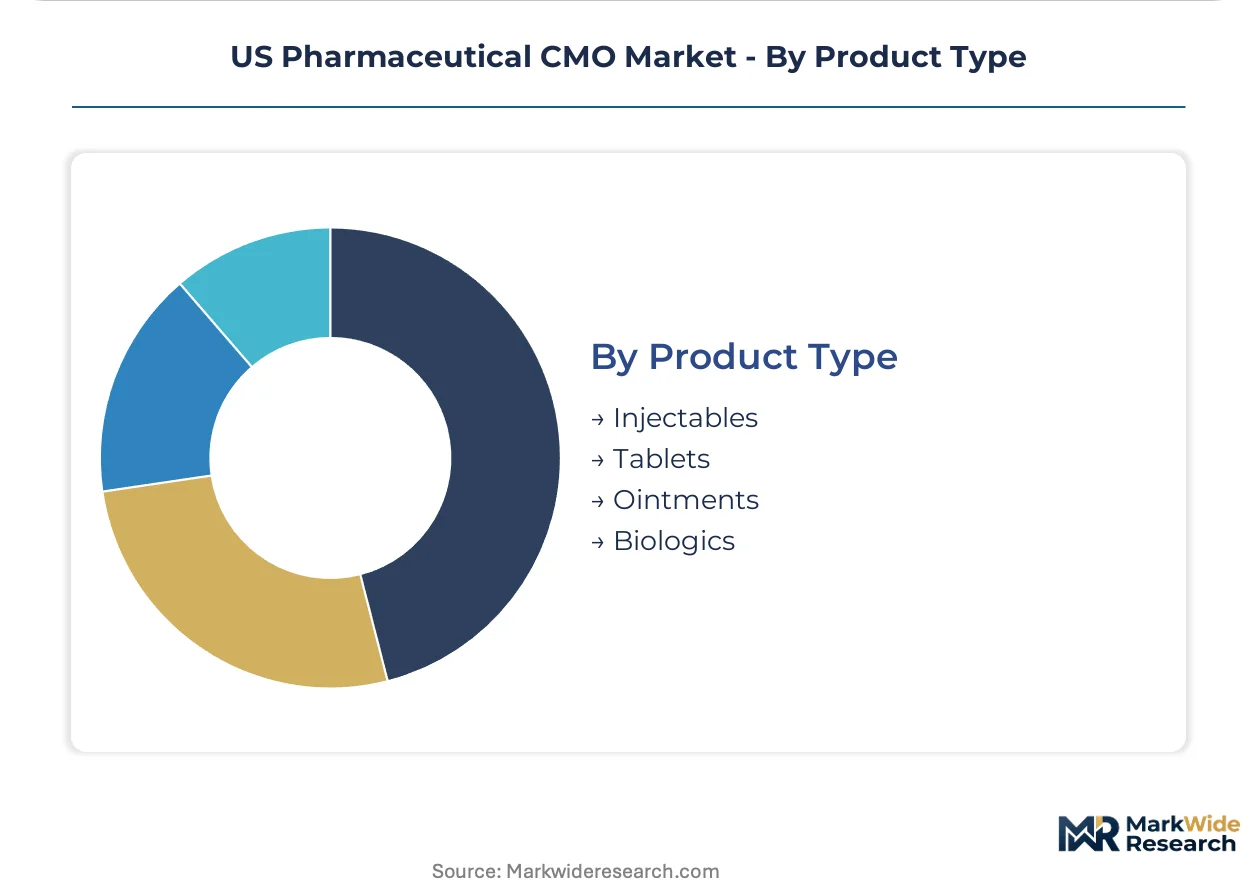
A pharmaceutical contract manufacturing organization provides outsourced development and production services spanning active pharmaceutical ingredients, finished dosage forms, and packaging, operating under current Good Manufacturing Practice standards with batch records typically reviewed by FDA investigators. The service type dimension shows API manufacturing and sterile processing capturing premium margins due to technical complexity and regulatory scrutiny, while formulation development grows fastest among biotech firms lacking in-house capabilities. The product type split reveals biologics and injectables expanding share as specialty pharmaceuticals and novel modalities multiply pipeline candidates requiring aseptic fill-finish expertise.
FDA current Good Manufacturing Practice enforcement and the Drug Supply Chain Security Act serialization requirements shape facility investment priorities and qualification timelines for CMO operators. OSHA process safety management standards and EPA hazardous waste regulations add compliance layers that favor larger organizations with dedicated regulatory affairs infrastructure. Stakeholders must weigh capacity commitments against the accelerating shift toward continuous manufacturing and personalized medicine modalities that demand flexible, smaller-batch production architectures.
Market Dynamics
Single-use bioreactor systems are compressing facility qualification timelines and redrawing capital deployment strategies across contract manufacturing networks. FDA enforcement patterns around data integrity and cross-contamination protocols are simultaneously elevating compliance costs and consolidating viable supplier pools.
Growth Catalysts
- Biotech pipeline expansion:Venture-funded biotech firms without manufacturing infrastructure are outsourcing end-to-end development, creating sustained demand for integrated CMO partnerships from early-phase through commercial supply.
- Drug Supply Chain Security Act:FDA serialization mandates for unit-level traceability are forcing manufacturers to upgrade packaging lines, benefiting CMOs with pre-qualified track-and-trace infrastructure.
- Massachusetts biotech corridor concentration:Cambridge-Boston cluster density generates localized demand for sterile injectable capacity and specialized logistics supporting cell and gene therapy cold chain requirements.
Market Restraints
- Stainless steel asset stranding:Legacy multi-product facilities face write-down pressure as single-use systems capture biologics share, constraining capital recovery for CMOs with sunk infrastructure investments.
- Specialized resin supply concentration:Bioprocess film and tubing suppliers cluster in limited geographies, exposing CMOs to input cost volatility and qualification delays for alternative sourcing.
- OSHA process safety management:High-potency compound handling requirements impose fixed compliance costs that disproportionately burden mid-scale operators lacking dedicated safety infrastructure.
Strategic Opportunities
- North Carolina Research Triangle expansion:RTP's emerging cell therapy manufacturing base offers greenfield site advantages for CMOs building modular, flexible production architectures.
- Continuous manufacturing adoption:FDA's emerging guidance on real-time release testing creates first-mover positioning for CMOs integrating process analytical technology with oral solid dose lines.
- Personalized medicine modality convergence:Autologous cell therapy and mRNA manufacturing platforms share cleanroom and aseptic processing requirements, enabling capacity repurposing across pipeline phases.
Industry Challenges
- Aseptic processing technician scarcity:FDA investigator training emphasis on media fill violations has tightened qualification standards, extending hiring timelines for fill-finish operations.
- Multi-product facility changeover complexity:Campaign scheduling conflicts between biologics and small molecules strain cleaning validation protocols, compressing effective utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Pharmaceutical CMO Market |
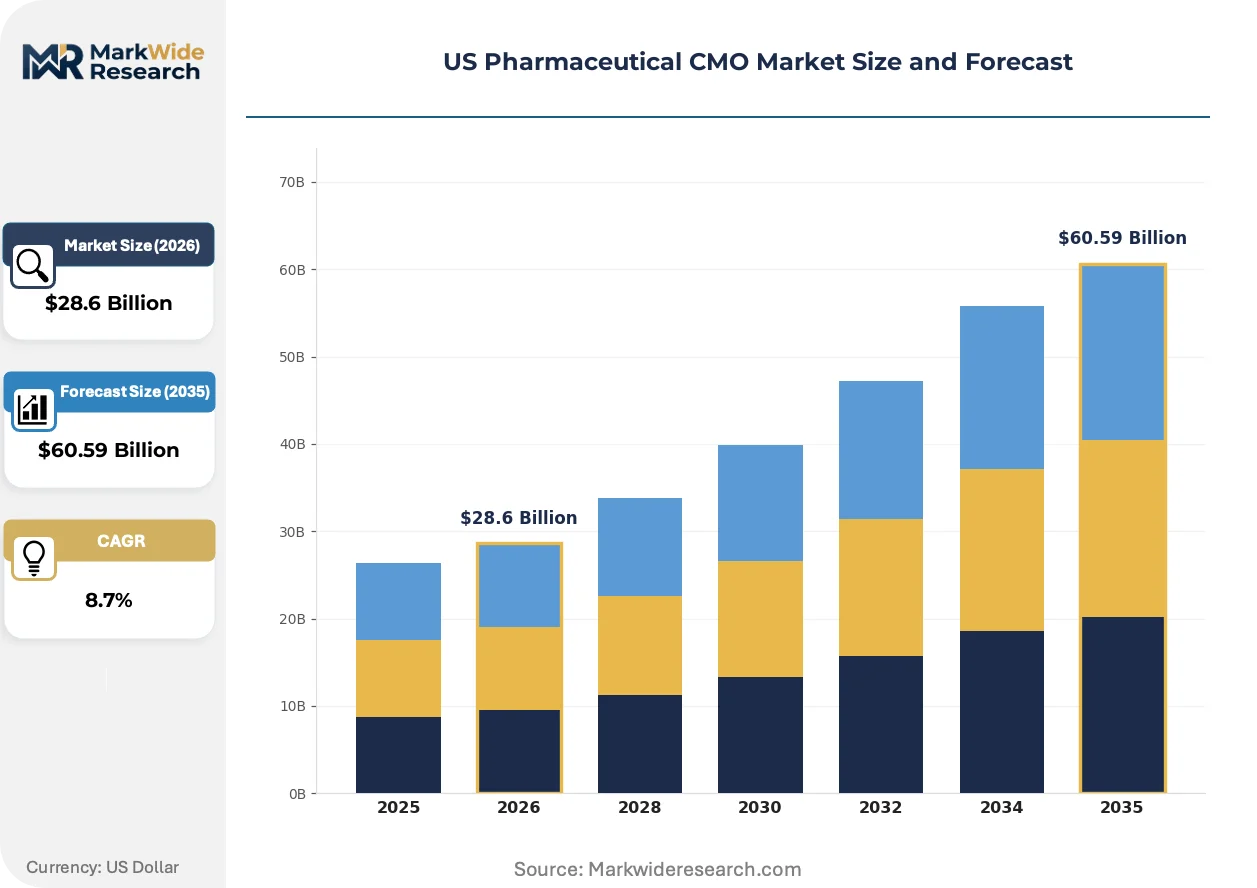
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: API Manufacturing, Formulation Development, Packaging, Quality Control End User: Biotech Firms, Generic Drug Manufacturers, Research Organizations, Specialty Pharmaceuticals Technology: Continuous Manufacturing, Batch Processing, Solid Dosage, Sterile Processing Product Type: Injectables, Tablets, Ointments, Biologics |
| Companies Covered | Catalent Inc., Thermo Fisher Scientific Inc., Lonza Group AG, Pfizer CentreOne, Baxter International Inc., AbbVie Contract Manufacturing, Recipharm AB, Jubilant Pharmova Limited, FUJIFILM Diosynth Biotechnologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Pharmaceutical CMO Market Evolving Landscape
Modular facility architectures and distributed manufacturing networks are fragmenting traditional centralized production models. These shifts compress supply chain risk concentration while demanding new competency sets around real-time quality oversight.
Single-use bioreactor assemblies are decentralizing biologics manufacturing from purpose-built campuses to portable, containerized production units. Mid-stage biotech sponsors are adopting these systems for Phase II material supply, avoiding capital-intensive stainless steel commitments. This technology is decentralizing geographic production concentration and enabling CMOs to position capacity closer to clinical trial sites.
FDA's Quality Management Maturity program is elevating inspection intensity around data integrity and deviation management. CMOs with established quality systems gain preferential positioning in sponsor qualification processes. Oral solid dose and sterile injectable segments are responding by accelerating investments in electronic batch records and automated environmental monitoring.
Biotech procurement functions are consolidating vendor panels and extending master service agreement durations to secure capacity commitments. Large pharmaceutical sponsors are displacing transactional project-based contracting with multi-year platform partnerships. This pattern is most visible in Massachusetts and North Carolina, where sponsor co-location with CMO facilities enables integrated supply planning and rapid technical transfer cycles.
US Pharmaceutical CMO Market Segmentation
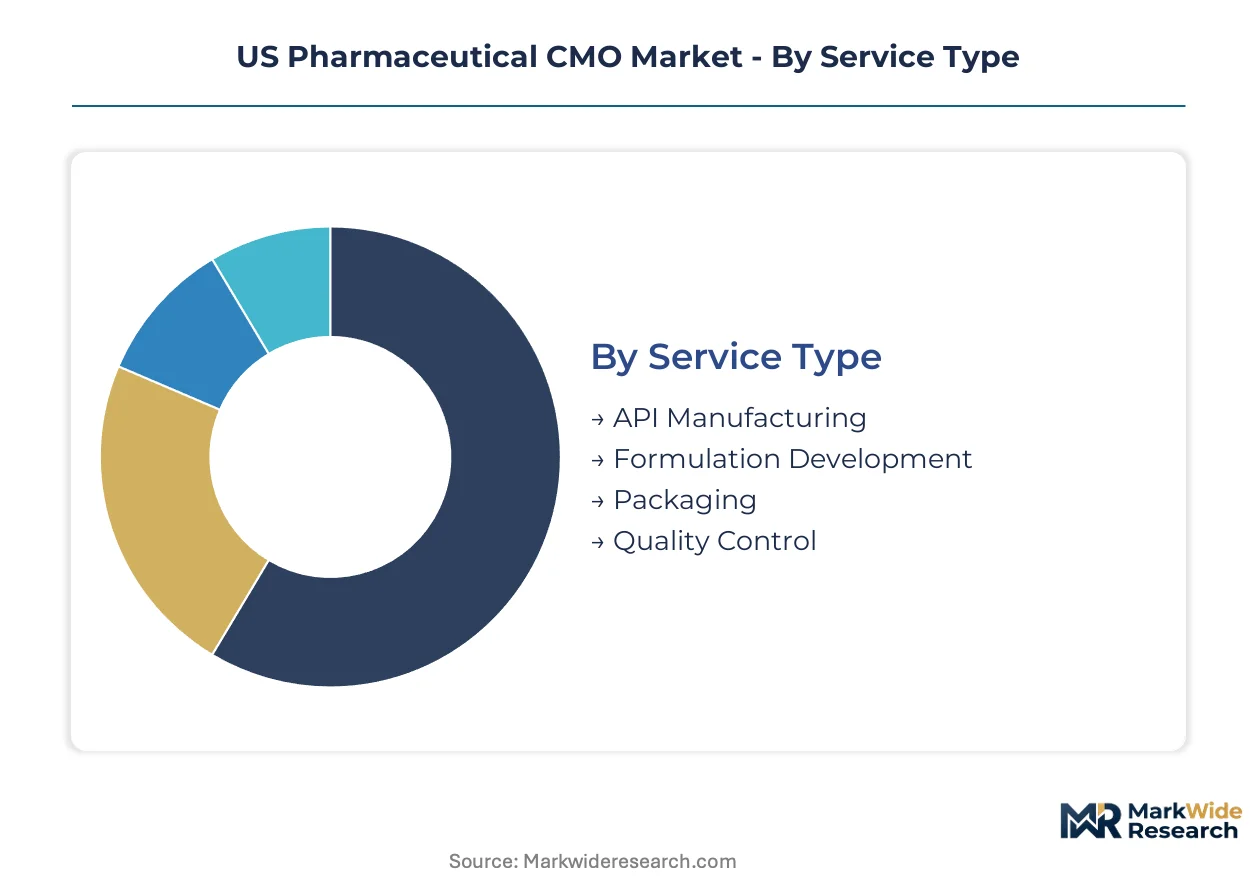
Service configuration, technology platform, and product modality choices determine capital allocation and margin structure for contract manufacturing operators. Segmentation reveals where FDA compliance burdens concentrate and which sponsor types drive capacity expansion.
Service Type:
Customization intensity spans from commodity packaging to bespoke API synthesis requiring dedicated reactor trains and specialized containment.
- API Manufacturing:Active pharmaceutical ingredient production demands containment infrastructure for high-potency compounds and controlled substance handling. Massachusetts biotech corridor sponsors anchor demand for specialized synthesis capabilities supporting oncology and rare disease programs.
- Formulation Development:Early-phase clinical material preparation integrates preformulation, stability testing, and scale-up design. Biotech firms lacking in-house capabilities outsource end-to-end development, making this the category expanding most quickly.
- Packaging:Secondary packaging and kit assembly operations integrate FDA Drug Supply Chain Security Act serialization requirements.
- Quality Control:Release testing and stability monitoring services operate under current Good Manufacturing Practice with batch records subject to FDA investigator review.
Leading the category by volume: API Manufacturing. Growing fastest: Formulation Development.
End User:
Customer scale and internal capability depth shape outsourcing scope from transactional projects to integrated partnerships.
- Biotech Firms:Venture-funded developers without manufacturing infrastructure contract end-to-end services from preclinical through commercial supply. North Carolina Research Triangle concentration generates localized demand for cell and gene therapy manufacturing support.
- Specialty Pharmaceuticals:Niche therapeutic area sponsors require aseptic processing for limited-population indications with complex supply chain requirements.
- Generic Drug Manufacturers:Cost-competitive finished dosage form production emphasizes high-volume batch efficiency and abbreviated new drug application filings.
- Research Organizations:Academic and government sponsors contract small-scale clinical trial material preparation with flexible scheduling priorities.
Dominant volume contributor: Biotech Firms. Steepest expansion trajectory: Specialty Pharmaceuticals.
Technology:
Capital intensity and operational flexibility trade off across fixed stainless steel installations and adaptable single-use configurations.
- Sterile Processing:Aseptic fill-finish operations for injectables and biologics demand ISO 5 cleanroom environments with isolator or restricted access barrier systems. Technician scarcity and FDA media fill validation requirements constrain effective capacity expansion.
- Continuous Manufacturing:Real-time release testing integration with process analytical technology reduces batch cycle times and quality testing burdens. FDA emerging guidance creates first-mover positioning for operators with installed continuous oral solid dose lines.
- Batch Processing:Traditional campaign-based manufacturing dominates small molecule and solid dosage production with established cleaning validation protocols.
- Solid Dosage:Tablet compression and coating operations serve high-volume generic and established brand pharmaceutical supply.
Highest margin capture: Sterile Processing. Gaining share fastest: Continuous Manufacturing.
Product Type:
Complexity gradient runs from topical semisolids to living biologic systems requiring cold chain integrity and specialized handling.
- Biologics:Recombinant proteins, monoclonal antibodies, and cell culture products demand single-use bioreactor systems and specialized purification trains. Massachusetts and North Carolina corridor concentration drives regional capacity investment for mammalian and microbial expression platforms.
- Injectables:Parenteral dosage forms including vials, prefilled syringes, and cartridges require aseptic processing with particulate and endotoxin control. FDA enforcement around data integrity and cross-contamination elevates compliance costs and consolidates viable supplier pools.
- Tablets:Oral solid dose compression and film-coating operations serve highest-volume therapeutic categories with established bioequivalence pathways.
- Ointments:Topical semisolid formulations for dermatologic and ophthalmic applications employ lower-complexity manufacturing with reduced aseptic requirements.
Revenue concentration leader: Biologics. Climbing the fastest: Injectables.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in coastal biotech corridors where venture-funded sponsors cluster near specialized manufacturing infrastructure. Massachusetts and North Carolina anchor capacity expansion, while Texas and California emerge as secondary nodes for cell therapy and continuous manufacturing investment.
Massachusetts
The Cambridge-Boston corridor generates concentrated demand for sterile injectable capacity and specialized cold chain logistics. FDA's Quality Management Maturity program elevates inspection intensity around data integrity protocols. Kendall Square and Seaport District biotech density drives integrated supply planning with co-located CMO facilities.
North Carolina
The Research Triangle Park anchors emerging cell therapy manufacturing with greenfield site advantages for modular production architectures. OSHA process safety management standards impose fixed compliance costs that favor operators with dedicated infrastructure. RTP's mammalian expression platform concentration attracts platform partnerships from mid-stage biotech sponsors.
California
San Francisco Bay Area and San Diego biotech clusters sustain demand for single-use bioreactor systems and aseptic fill-finish operations. EPA hazardous waste regulations add compliance layers that consolidate viable supplier pools. South San Francisco's antibody development density supports regional capacity for biologics drug substance production.
Texas
The Dallas-Fort Worth and Houston metros attract distributed manufacturing investments for mRNA and personalized medicine modalities. FDA Drug Supply Chain Security Act serialization requirements favor CMOs with pre-qualified track-and-trace infrastructure. Texas Medical Center proximity enables rapid technical transfer cycles for autologous cell therapy programs.
New Jersey
The state maintains legacy pharmaceutical manufacturing density with established oral solid dose and packaging operations. FDA current Good Manufacturing Practice enforcement patterns around cross-contamination protocols elevate compliance costs. Princeton and New Brunswick corridor sponsors leverage existing infrastructure for commercial supply continuity.
US Pharmaceutical CMO Market Competitive Landscape
Capacity expansion dominates the current landscape as operators deploy single-use bioreactor systems and modular cleanroom architectures. The vendor base organizes around three tiers: integrated platform providers spanning drug substance through drug product, specialized biologics operators with cell and gene therapy focus, and regional solid dose specialists with high-volume efficiency. Consolidation pressures intensify as FDA enforcement patterns around data integrity and media fill validation favor organizations with established quality systems and dedicated regulatory affairs infrastructure.
Within the integrated platform tier, Thermo Fisher Scientific Inc. and Catalent Inc. exemplify end-to-end service architectures spanning early-phase development through commercial supply. Lonza Group AG occupies a specialized position in cell and gene therapy capacity with dedicated biologics facilities. These operators anchor multi-year platform partnerships that displace transactional project-based contracting, particularly in Massachusetts and North Carolina corridor concentrations where sponsor co-location enables rapid technical transfer cycles.
| Leading Market Players |
|---|
| Catalent Inc. |
| Thermo Fisher Scientific Inc. |
| Lonza Group AG |
| Pfizer CentreOne |
| Baxter International Inc. |
| AbbVie Contract Manufacturing |
| Recipharm AB |
| Jubilant Pharmova Limited |
| FUJIFILM Diosynth Biotechnologies |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up CMO specialists have consolidated fragmented regional operators across Massachusetts and North Carolina, compressing pricing discipline through centralized procurement leverage and standardized quality systems that feed into sponsor contract negotiations.
Pricing Analysis
Volume-driven generic solid-dose manufacturing captures thin margins through batch efficiency, while sterile biologics processing commands premium pricing anchored in FDA compliance tiering and technician scarcity. Three-tier pricing structure across premium, standard, and economy levels separates cell and gene therapy capacity from conventional injectables and commodity oral dosage forms. Pricing pressure stems from single-use consumable cost inflation and resin supply concentration. Generic drug manufacturers exhibit highest price sensitivity, while venture-funded biotech firms prioritize speed-to-clinic over unit cost.
Supply Chain Analysis
Domestic-content mandates under the Drug Supply Chain Security Act are reshaping CMO sourcing toward qualified US-based film and tubing suppliers, reducing reliance on Asian bioprocess material networks. Critical inputs draw from specialized resin producers in Germany, single-use assembly manufacturers in Ireland, and domestic cleanroom component fabricators. Single-source vulnerability concentrates in cell culture media and chromatography resin supply. Distribution runs through sponsor-co-located hub facilities with cold chain integrity monitoring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with incumbents pursuing backward integration into single-use consumable production to capture margin leakage and secure supply continuity.
For Market Incumbents: Anchor market position through dedicated cell therapy capacity additions in North Carolina Research Triangle and Massachusetts corridor co-location. Stainless steel asset stranding from single-use adoption threatens legacy facility valuations. FDA Quality Management Maturity program compliance investments create qualification barriers against mid-scale competitors lacking dedicated regulatory infrastructure. For New Entrants and Emerging Players: Continuous manufacturing technology platforms offer entry positioning in oral solid dose segments where FDA process analytical technology guidance creates first-mover certification advantages. North Carolina greenfield sites enable modular facility architectures without legacy cleaning validation burden. Target platform partnerships with mid-stage biotech sponsors seeking integrated drug substance-to-product services. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized biologics operators in Massachusetts with isolator-equipped fill-finish lines and established FDA inspection histories. Five-to-ten-year viability hinges on capacity utilization rates across personalized medicine modality convergence. Watch FDA enforcement intensity around data integrity protocols as inflection signal for quality-system differentiation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Single-Use Capacity Expansion | Modular bioreactor installations in North Carolina and Massachusetts compress qualification timelines for biotech sponsors. |
| Cell Therapy Manufacturing Buildout | Dedicated cleanroom suites with isolator technology capture autologous therapy demand from Kendall Square sponsors. |
| Continuous Manufacturing Adoption | Real-time release testing integration with FDA process analytical technology guidance creates oral solid dose differentiation. |
| Quality System Certification Investment | Electronic batch record implementation elevates FDA Quality Management Maturity program positioning against mid-scale competitors. |
| Co-Location Partnership Structuring | Integrated supply planning with Cambridge-Boston corridor sponsors accelerates technical transfer cycles and capacity commitments. |
Research Methodology
Document review covered FDA warning letters, EMA inspection observations, and SEC 10-K filings from publicly traded CMO operators, complemented by interviews with drug development executives, regulatory affairs leads, and hospital procurement managers. Secondary validation drew from ClinicalTrials.gov sponsor-CMO relationship mapping, formulary database reviews, and customs import records for bioprocess equipment. Bottom-up capacity modeling triangulated against top-down sponsor outsourcing spend estimates.
Output metrics span drug substance batch volumes, fill-finish unit counts, and service revenue across API manufacturing, formulation development, packaging, and quality control segments. Segmentation dimensions include service type, product modality, technology platform, end-user category, and regional regulatory cluster. CAGRs derive from sponsor pipeline progression rates, facility utilization assumptions, and outsourcing penetration trends by development phase.
Several conditions sit outside the modeled scope, including geopolitical trade restrictions on bioprocess materials, abrupt FDA enforcement pattern shifts, and sponsor vertical integration decisions. Forecasts reflect assumptions around single-use technology adoption velocity and continuous manufacturing regulatory pathway clarity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Prescription Drugs Market
Pharmaceuticals
Hyperphosphatemia Market
Pharmaceuticals
Nicorandil Market
Pharmaceuticals
Global Bendamustine Injection Market
Pharmaceuticals
Hydroxypropyl Methylcellulose (HPMC) Capsules Market
Pharmaceuticals
Global Pneumococcal Vaccines Market
Pharmaceuticals
Global Inhaled Antibiotics Market
Pharmaceuticals
South Africa Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Musculoskeletal Disorders Drugs Market
Pharmaceuticals
Antimalarial Drugs Market
Pharmaceuticals
Adamantane Antiviral Drugs Market
Pharmaceuticals
Antiepileptic Drugs (AED) Market
Pharmaceuticals
Middle-East and Africa Meglitinide Market
Pharmaceuticals
Urban Pharma Micro-Depot and Delivery Network Market
Pharmaceuticals
Placental Protein Market
Pharmaceuticals
Global Human Vaccines Market