
 Middle East and Africa Ceramic Membranes Market | 2026-2036
Middle East and Africa Ceramic Membranes Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Ceramic Membranes Market Foresight
Project finance for desalination and water reuse infrastructure is reconfiguring competitive access across the Middle East and Africa ceramic membranes landscape. Nanostone leverages its flat-sheet ceramic platform to anchor municipal contracts in the Gulf states where long-term off-take agreements dominate. TAMI Industries sustains its position through specialized tubular geometries that dominate high-solids industrial streams in North African phosphate processing. Aquatech International LLC competes via integrated build-own-operate frameworks that bundle ceramic membrane units into multi-year service contracts.
Ceramic membranes are inorganic, thermally stable filtration barriers typically manufactured from alumina, zirconia, or titania through sintering at temperatures exceeding 1600°C, engineered to separate particulates, macromolecules, or dissolved ions under aggressive chemical and thermal conditions. Ultrafiltration segments lead current revenue generation due to their deployment in oilfield produced water and dairy protein concentration across the region. Microfiltration dominates installed base volume in municipal pre-treatment trains protecting reverse osmosis modules from fouling in Saudi and UAE seawater desalination plants. Hybrid technology configurations are gaining fastest traction where composite layers combine microfiltration support with nanofiltration selectivity for pharmaceutical solvent recovery applications.
Saudi Arabia's Saline Water Conversion Corporation standards and South Africa's Department of Water and Sanitation discharge permits collectively shape membrane performance benchmarks and replacement cycles across the region. The UAE's MOHAP pharmaceutical manufacturing guidelines and Egypt's environmental compliance frameworks for industrial zones further define product certification requirements for ceramic membrane suppliers. Stakeholders must monitor how tightening effluent quality mandates in Gulf petrochemical zones and South African mining jurisdictions will redirect procurement specifications toward higher-porosity, chemically resistant ceramic architectures.
Market Dynamics
Project finance reconfiguration for desalination infrastructure is concentrating procurement power among Gulf utilities with multi-decade off-take agreements, forcing membrane suppliers to absorb construction risk and guarantee performance over extended operational periods.
Growth Catalysts
- Saline Water Conversion Corporation standards:Saudi Arabia's tightened discharge mandates for petrochemical complexes are mandating ceramic membrane replacements of legacy polymeric systems in high-temperature process streams.
- Acid mine drainage treatment:South Africa's mining belt is deploying high-flux ceramic ultrafiltration trains to address heavy metal contamination, creating sustained demand for chemically resistant membrane architectures.
- Alumina-zirconia composite layers:Advances in hybrid ceramic configurations combining microfiltration supports with nanofiltration selectivity are opening pharmaceutical solvent recovery applications across UAE manufacturing zones.
Market Restraints
- Sintering energy costs:Manufacturing temperatures exceeding 1600°C for alumina, zirconia, and titania substrates expose producers to volatile natural gas and electricity pricing across North African industrial zones.
- Flat-sheet supply concentration:Gulf municipal contracts for ceramic membranes depend on a narrow supplier base for large-format flat-sheet geometries, creating procurement vulnerability for Saline Water Conversion Corporation projects.
- Polymeric membrane substitution:Tightened municipal budgets in secondary Egyptian and Moroccan cities favor lower-capital polymeric ultrafiltration for pre-treatment trains despite shorter replacement cycles.
Strategic Opportunities
- Phosphate processing expansion:North African fertilizer complexes in Morocco and Tunisia present untapped demand for tubular ceramic geometries handling high-solids industrial streams with extreme pH cycling.
- MOHAP pharmaceutical guidelines:UAE manufacturing standards for sterile water systems are creating certification-driven preference shifts toward ceramic membranes in biologics production facilities.
- Build-own-operate frameworks:Integrated service contracts bundling membrane units with long-term operational responsibility are penetrating Saudi industrial zones where capital constraints limit direct equipment purchases.
Industry Challenges
- Ceramic sintering specialists:The region lacks sufficient trained technicians for high-temperature membrane manufacturing, forcing reliance on expatriate expertise or imported finished substrates.
- Multi-year performance guarantees:Gulf utility procurement frameworks require membrane suppliers to warranty flux stability and chemical resistance across 15-20 year operational horizons, compressing margin structures.
- Reverse osmosis integration protocols:Municipal pre-treatment trains demand precise ceramic membrane specification to protect downstream desalination modules, requiring extensive pilot testing that extends sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Ceramic Membranes Market |
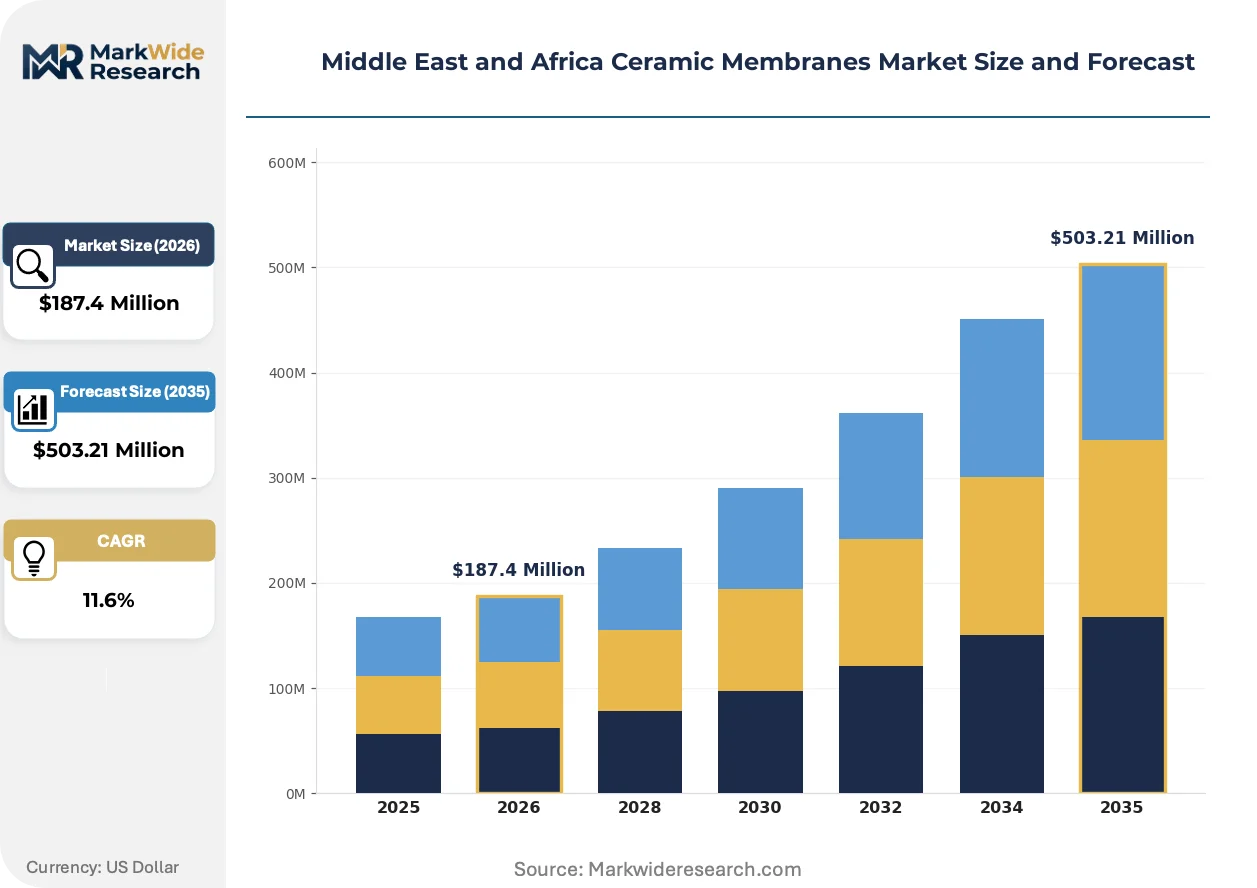
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfiltration, Ultrafiltration, Nanofiltration, Reverse Osmosis End User: Water Treatment, Food & Beverage, Petrochemical, Pharmaceutical Technology: Sintered Porous, Composite, Hybrid, Coated Application: Separation, Filtration, Concentration, Purification |
| Companies Covered | Nanostone, Qua Group LLC, TAMI Industries, Aquatech International LLC, TORAY INDUSTRIES, INC., atech innovations gmbh, LiqTech Holding A/S, Pall Corporation, GEA Group Aktiengesellschaft, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Ceramic Membranes Market Shifts & Advancements
Digital monitoring systems and hybrid material architectures are reconfiguring how ceramic membranes are specified, operated, and maintained across Middle Eastern and African water infrastructure.
Multi-layer ceramic composites integrating microfiltration substrates with nanofiltration top layers are digitizing performance tracking through embedded flux sensors and predictive cleaning algorithms. Saudi petrochemical operators are adopting these configurations for produced water treatment, enabling real-time fouling detection that extends cleaning intervals and reduces chemical consumption. The technology is digitizing maintenance scheduling across Gulf industrial zones, compressing total cost of ownership calculations in procurement evaluations.
South Africa's Department of Water and Sanitation discharge permits are tightening heavy metal limits for mining effluent, mandating ceramic ultrafiltration as final polishing stages before environmental release. The regulatory revision is accelerating replacement of legacy lime precipitation systems in the Witwatersrand and Mpumalanga mining belts. Acid mine drainage projects are responding with modular ceramic train configurations that allow capacity scaling as treatment volumes fluctuate seasonally.
Long-term offtake agreements are consolidating buyer power among Gulf Cooperation Council utilities, unbundling equipment supply from operational service contracts. Membrane suppliers now compete primarily on guaranteed water quality output rather than unit capital cost, with Saudi and UAE municipal buyers transferring operational risk to vendors. This restructuring is most visible in Saudi Arabia's independent water and power project frameworks, where ceramic membrane performance bonds determine vendor selection.
Middle East and Africa Ceramic Membranes Market Segmentation
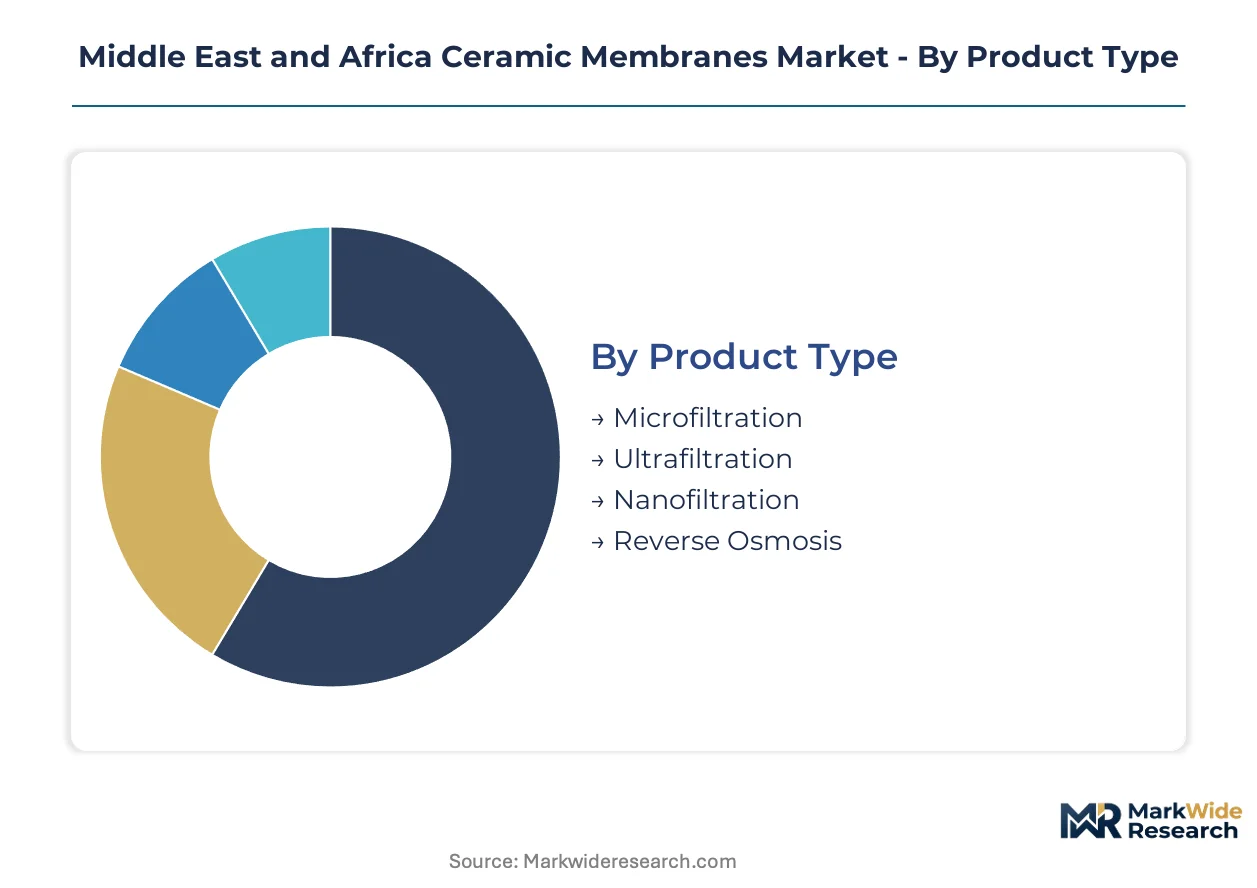
Ceramic membrane procurement across the Middle East and Africa fragments along technical specifications, end-use chemistry, and operational intensity. Each dimension carries distinct margin profiles and replacement cycle dynamics that reshape vendor positioning.
Product Type:
Cost tier separation drives specification choices between mature polymeric replacements and premium ceramic architectures for aggressive process streams.
- Microfiltration:Pore sizes ranging 0.1-10 micrometers manufactured from alumina or titania substrates deliver high permeability for suspended solids removal. Saudi and UAE seawater desalination plants deploy these as reverse osmosis pre-treatment barriers, with Saline Water Conversion Corporation procurement volumes concentrating in tubular geometries for high-solids intake waters.
- Ultrafiltration:1-100 nanometer pore structures in zirconia-alumina composites separate macromolecules and colloids under thermal stress. South Africa's mining belt demands these for acid mine drainage polishing stages, where heavy metal rejection must meet Department of Water and Sanitation discharge limits.
- Nanofiltration:Divalent ion-selective layers engineered through sol-gel deposition achieve molecular weight cutoffs of 200-1000 Daltons. UAE pharmaceutical manufacturing under MOHAP guidelines is adopting these for solvent recovery and API concentration.
- Reverse Osmosis:Dense ceramic layers with sub-nanometer selectivity remain nascent in regional deployment due to extreme sintering costs and brittleness constraints.
Microfiltration holds installed capacity. Ultrafiltration is rotating up the share rankings.
End User:
Application chemistry determines membrane material selection, with pH extremes and oxidant exposure eliminating polymeric alternatives.
- Water Treatment:Municipal desalination pre-treatment and industrial wastewater reuse dominate procurement volumes. Gulf Cooperation Council utilities specify flat-sheet ceramic configurations for long-term offtake agreements.
- Petrochemical:High-temperature process streams and aromatic solvent exposure mandate zirconia-toughened alumina membranes. Saudi Arabia's tightened discharge standards under its national water regulator are accelerating ceramic replacements of legacy polymeric systems.
- Food & Beverage:Dairy protein concentration and edible oil clarification deploy microfiltration for hygienic operation without steam sterilization degradation.
- Pharmaceutical:Sterile water systems and biologics processing require certification-compliant membranes under UAE MOHAP manufacturing guidelines.
Water treatment commands the largest installed base. Petrochemical is climbing the fastest as discharge standards tighten.
Technology:
Manufacturing maturity separates cost-competitive sintered substrates from developmental hybrid architectures.
- Sintered Porous:Conventional alumina and titania substrates fired above 1600°C constitute the majority of regional installed base. North African phosphate processing in Morocco and Tunisia relies on these tubular geometries for extreme pH cycling durability.
- Hybrid:Multi-layer composites combining microfiltration supports with nanofiltration selectivity are gaining fastest traction. Saudi petrochemical operators adopt these for produced water treatment with embedded flux sensors enabling predictive maintenance.
- Composite:Polymer-ceramic interpenetrating networks reduce brittleness while retaining chemical resistance.
- Coated:Surface-modified membranes with catalytic or hydrophilic layers address specific fouling challenges in food processing.
Sintered porous dominates current procurement. Hybrid configurations are expanding most quickly through digital monitoring integration.
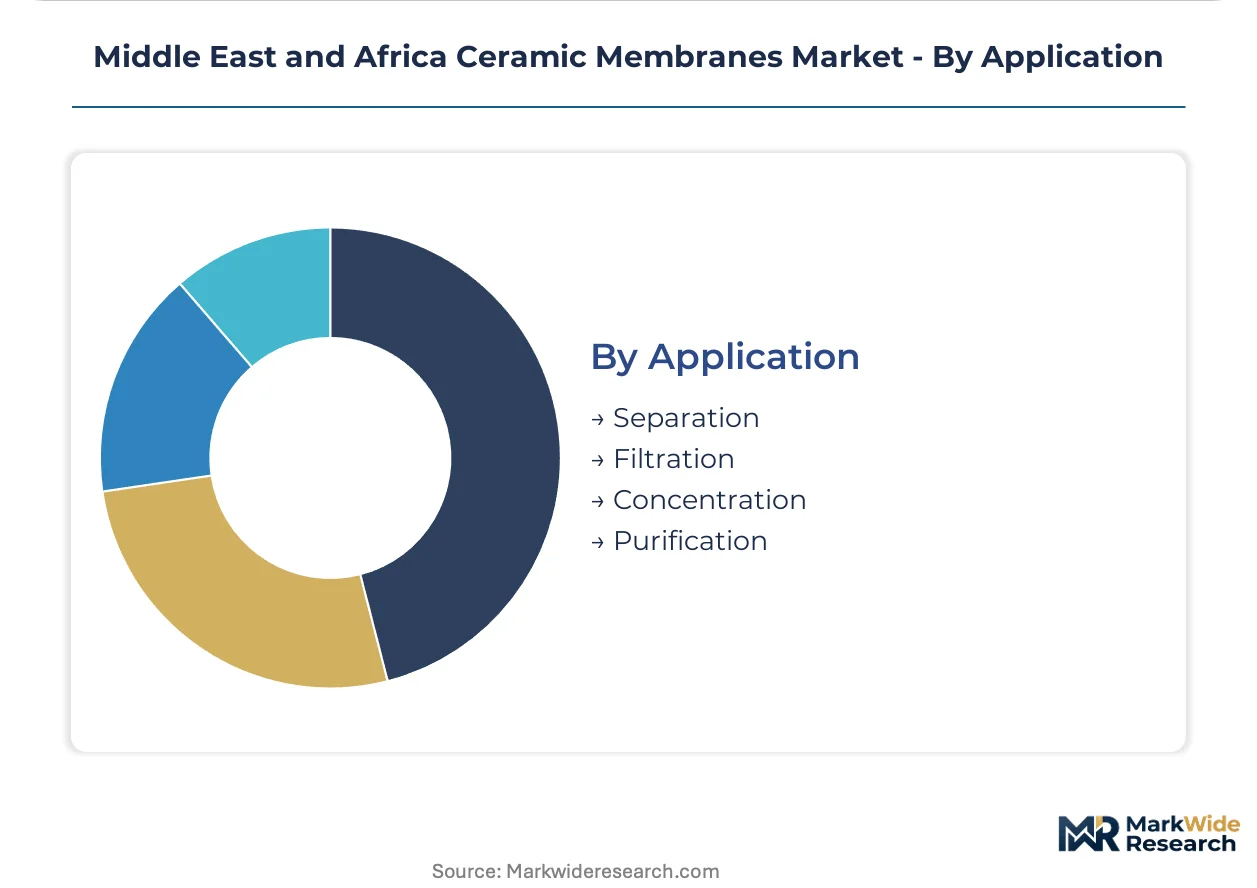
Application:
Operational function determines module configuration, with batch versus continuous processing driving geometry selection.
- Filtration:Solid-liquid separation for pre-treatment and clarification constitutes the primary revenue driver across municipal and industrial installations.
- Purification:Final polishing stages for pharmaceutical water and mining effluent demand highest membrane integrity.
- Concentration:Dairy protein and API processing leverage ultrafiltration for volume reduction without thermal damage.
- Separation:Solvent recovery and oil-water splitting in petrochemical complexes require chemically resistant ceramic architectures.
Filtration maintains the greatest installed capacity. Purification is gaining share fastest through regulatory tightening in pharmaceutical and mining discharge standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Gulf Cooperation Council utilities with multi-decade off-take agreements, while North African phosphate processors face procurement constraints from currency volatility and sintering energy exposure.
Saudi Arabia
Petrochemical complexes in Jubail and Yanbu drive demand for zirconia-toughened alumina membranes in high-temperature process streams. The Saline Water Conversion Corporation tightened discharge mandates under its national water regulator, accelerating ceramic replacements of legacy polymeric systems. Eastern Province industrial zones anchor procurement volumes for tubular geometries handling aromatic solvent exposure.
UAE
Pharmaceutical manufacturing under MOHAP guidelines generates demand for nanofiltration selectivity in sterile water systems and biologics processing. Dubai and Abu Dhabi municipal utilities specify flat-sheet ceramic configurations for reverse osmosis pre-treatment in seawater desalination plants. Jebel Ali industrial corridor deploys hybrid ceramic composites with embedded flux sensors for predictive maintenance.
South Africa
The Witwatersrand and Mpumalanga mining belts require high-flux ceramic ultrafiltration trains for acid mine drainage polishing stages. Department of Water and Sanitation discharge permits tightened heavy metal limits, mandating final ceramic barriers before environmental release. Modular train configurations allow capacity scaling as treatment volumes fluctuate seasonally.
Egypt
Environmental compliance frameworks for industrial zones shape certification requirements for ceramic membrane suppliers serving Alexandria and Suez Canal economic zones. Tightened municipal budgets in secondary cities favor lower-capital polymeric ultrafiltration for pre-treatment despite shorter replacement cycles. Cairo metropolitan utilities pilot ceramic systems for wastewater reuse expansion.
Morocco
Phosphate processing complexes in Khouribga and Youssoufia present untapped demand for tubular ceramic geometries handling high-solids industrial streams with extreme pH cycling. Fertilizer sector expansion drives procurement of sintered alumina substrates fired above 1600°C. OCP Group facilities anchor North African demand for chemically resistant membrane architectures.
Middle East and Africa Ceramic Membranes Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with substrate and module manufacturing. The vendor base stratifies between Gulf-focused municipal contractors and industrial specialists serving petrochemical and mining applications. Three archetypes dominate: flat-sheet platform providers, tubular geometry specialists, and integrated build-own-operate service bundlers. Competitive moves center on performance guarantee structures and long-term operational risk absorption rather than unit pricing.
Within the flat-sheet platform tier, Nanostone anchors municipal contracting positions across Gulf Cooperation Council states. Tubular geometry specialists include TAMI Industries and atech innovations gmbh, occupying positions in high-solids industrial streams. Aquatech International LLC exemplifies the integrated service archetype, bundling membrane units into multi-year operational contracts. These three represent distinct competitive vectors: platform standardization, geometric specialization, and capital-light service models.
| Leading Market Players |
|---|
| Nanostone |
| Qua Group LLC |
| TAMI Industries |
| Aquatech International LLC |
| TORAY INDUSTRIES, INC. |
| atech innovations gmbh |
| LiqTech Holding A/S |
| Pall Corporation |
| GEA Group Aktiengesellschaft |
| Others |
Supply & Pricing Matrix
Undercapacity in North African sintering facilities is compressing margin structures for ceramic membrane producers serving Gulf municipal utilities, forcing suppliers to absorb construction risk in long-term offtake agreements while passing energy volatility exposure downstream.
Pricing Analysis
Configured-to-order pricing for tubular geometries in petrochemical applications commands substantial premiums over standard flat-sheet municipal configurations. Contract-based long-term offtake structures dominate Gulf Cooperation Council procurement, with price differentiation driven by certification grade under Saline Water Conversion Corporation standards and volume scale in multi-year frameworks. Cost compression in standard microfiltration tiers is intensifying because polymeric substitution threatens replacement-cycle revenue. Municipal buyers in secondary Egyptian and Moroccan cities exhibit highest price sensitivity, while Saudi petrochemical operators under tightened discharge mandates show lowest sensitivity due to operational risk transfer requirements.
Supply Chain Analysis
Tariff exposure between European substrate suppliers and North African manufacturing zones dominates supply chain risk assessment for regional ceramic membrane producers. Sintered alumina and zirconia substrates draw from Germany, France, and Japan, while high-purity titania feedstocks rest on South African mining output and Ukrainian processed ores. Single-source vulnerability concentrates in large-format flat-sheet geometries where Gulf municipal contracts depend on limited qualified suppliers. Distribution runs through integrated build-own-operate frameworks that bundle membrane units with operational service contracts, compressing traditional equipment-only channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from cyclical trough conditions as Gulf wastewater reuse investment accelerates under national water security frameworks, with procurement volumes expanding through independent water and power project structures.
For Market Incumbents: Insulate margin structures by deepening backward integration into zirconia-alumina substrate manufacturing in Saudi Arabia's Eastern Province industrial zones, reducing exposure to European energy cost volatility. Secure Saline Water Conversion Corporation certification renewals ahead of tightened petrochemical discharge mandates to lock out polymeric substitution threats in high-temperature process streams. For New Entrants and Emerging Players: Pursue phosphate processing applications in Morocco's Khouribga and Youssoufia fertilizer complexes, where tubular ceramic demand for extreme pH cycling remains underserved by incumbent flat-sheet specialists. Target build-own-operate service bundling in Egyptian industrial zones facing capital constraints, leveraging operational risk absorption as differentiation against equipment-only competitors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated service providers with multi-year operational contracts in Saudi industrial zones, offering superior cash flow visibility across the analysis window. Acquisition focus should center on hybrid technology developers with embedded digital monitoring capabilities, as predictive maintenance integration represents the fastest-expanding competitive wedge. Monitor Saline Water Conversion Corporation procurement framework revisions as the critical inflection signal for vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Manufacturing | Saudi sintering capacity reduces European energy cost exposure for Gulf petrochemical suppliers. |
| Hybrid Technology Certification | UAE MOHAP pharmaceutical guidelines create preference shift toward nanofiltration-selective composites. |
| Build-Own-Operate Framework Expansion | Egyptian capital constraints favor service bundling over direct equipment purchases in industrial zones. |
| Digital Monitoring Platform Integration | Embedded flux sensors in Saudi petrochemical operations compress total cost of ownership calculations. |
| Phosphate Processing Market Entry | Morocco OCP Group facilities anchor untapped North African demand for tubular geometries. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC filings from listed membrane technology providers, Saline Water Conversion Corporation procurement disclosures, and South African Department of Water and Sanitation permit databases. Primary interviews engaged ceramic membrane plant managers, Gulf utility procurement officers, petrochemical process engineers, phosphate processing technical directors, and mining effluent treatment specialists. Bottom-up unit deployment estimates triangulate against top-down market sizing derived from sintering capacity utilization rates and replacement cycle assumptions across municipal and industrial installation bases.
Forecast inputs include membrane pore size segmentation, end-use chemistry intensity, operational temperature regimes, and regulatory compliance tier requirements modeled across the projection horizon. Analytical framework incorporates petrochemical discharge standard evolution, mining effluent permit tightening trajectories, and pharmaceutical manufacturing guideline revisions as scenario-weighted demand drivers. CAGRs derive from iterative convergence between installed base depreciation schedules and new capacity commissioning timelines.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing, Gulf utility borrowing costs, or South African mining sector investment cycles would shift the trajectory. Forecasts reflect documented assumptions regarding sintering energy cost stability and regulatory implementation pacing. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Liquid Applied Membranes Market
Membrane Materials
Global Membrane Water and Wastewater Treatment Market
Membrane Materials
Nanofiltration Membrane Market
Membrane Materials
Breathable Films and Membranes Market
Membrane Materials
Global Nanomembrane Market
Membrane Materials
Global Tubular Membranes Market
Membrane Materials
Global Transfer Membrane Market
Membrane Materials
Global Polymer Nanomembrane Market
Membrane Materials
Global Track Etched Membrane Market
Membrane Materials
Reverse Osmosis (RO) Membrane Market
Membrane Materials
North America Ceramic Membranes Market
Membrane Materials
Nanoporous Membranes Market
Membrane Materials
Nafion Market
Membrane Materials
Fuel Cell Gas Diffusion Layer Market
Membrane Materials
APP and SBS Modified Bitumen Membrane Market
Membrane Materials
Membrane Filter Cartridge Market