
 Global Membrane Chromatography Market | 2026-2036
Global Membrane Chromatography Market Size, Share, and Industry Trends Forecast 2026-2036
Global Membrane Chromatography Market Foresight
The EU Green Deal is consolidating downstream bioprocessing standards across European pharmaceutical supply chains, pushing manufacturers toward single-use membrane formats that slash solvent volumes and carbon intensity. Sartorius AG leverages its German engineering base to dominate industrial-scale capsule supply for monoclonal antibody facilities. Danaher Corporation anchors North American demand through Pall Corporation's integrated membrane and hardware portfolios. Merck KGaA competes on R&D intensity, sustaining a pipeline of novel affinity chemistries for viral vector purification.
Membrane chromatography employs porous polymeric membranes—typically derivatized with ion-exchange ligands, protein A mimetic surfaces, or hydrophobic moieties—to bind and separate biomolecules under convective mass transport, eliminating the diffusional limitations of packed-bed resins. The technique achieves processing velocities tenfold higher than conventional column chromatography while reducing buffer consumption by half, making it indispensable for polishing steps in biopharmaceutical manufacturing. Ion exchange membranes currently lead product type revenue due to their versatility in clearing host cell proteins and DNA from antibody streams, while affinity formats are expanding fastest as gene therapy vectors require gentler capture chemistries. Pilot scale deployment captures disproportionate margin pools because process development contracts command premium pricing before technology transfer to industrial scale.
FDA enforces current Good Manufacturing Practice guidelines that mandate validated clearance of adventitious agents and process-related impurities, directly shaping membrane selection criteria for BLA submissions. EMA's Annex 1 revision on sterile manufacturing and the EU AI Act's emerging quality-system requirements are forcing vendors to document membrane extractables and batch-to-batch consistency with greater granularity. China's NMPA alignment with ICH Q5A through its updated technical guidelines is opening regulatory pathways for imported membrane devices in domestic biologics facilities. Stakeholders must monitor how FDA's quality metrics program and EMA's rolling review frameworks will reshape validation timelines for disposable chromatography systems.
Market Dynamics
The FDA's quality metrics program and EMA's rolling review frameworks are compressing validation timelines for disposable chromatography systems, forcing membrane vendors to pre-validate extractables documentation and batch consistency protocols before technology transfer.
Growth Catalysts
- Monoclonal antibody pipeline expansion:Contract manufacturing organizations in the United States, Germany, and China are scaling membrane-based capture steps to accommodate thickening therapeutic pipelines.
- EU Green Deal solvent reduction mandates:The framework's carbon intensity targets for pharmaceutical manufacturing are pushing facilities toward single-use membrane formats that slash buffer volumes by half versus packed-bed resins.
- Gene therapy vector purification demand:Viral vector manufacturing requires gentler affinity chemistries that membrane chromatography delivers through convective mass transport, eliminating diffusional limitations.
Market Restraints
- Polymeric membrane raw material concentration:Specialized derivatized substrates for ion-exchange and affinity ligands concentrate among a limited supplier base, creating input cost volatility.
- Extractables documentation burden:EMA's Annex 1 revision on sterile manufacturing and the EU AI Act's quality-system requirements force vendors to generate granular batch-to-batch consistency data at substantial compliance cost.
- Resin column substitution in legacy facilities:Established biopharmaceutical plants with sunk capital in packed-bed infrastructure face switching friction despite membrane velocity advantages.
Strategic Opportunities
- China's NMPA regulatory alignment:The agency's ICH Q5A technical guideline updates are opening pathways for imported membrane devices in domestic biologics facilities previously restricted to local suppliers.
- Continuous bioprocessing integration:Membrane chromatography is modularizing into connected processing trains that eliminate hold steps, creating white space for integrated hardware-software platforms.
- Pilot scale premium service contracts:Process development engagements command pricing power before technology transfer, capturing disproportionate margin pools through specialized application support.
Industry Challenges
- Bioprocess engineering talent scarcity:The specialized skill set combining membrane chemistry knowledge with current Good Manufacturing Practice validation protocols remains concentrated among experienced practitioners.
- Legacy quality system integration:Facilities with established resin-based standard operating procedures face retraining and documentation overhaul to accommodate membrane-specific validation protocols for BLA submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Membrane Chromatography Market |
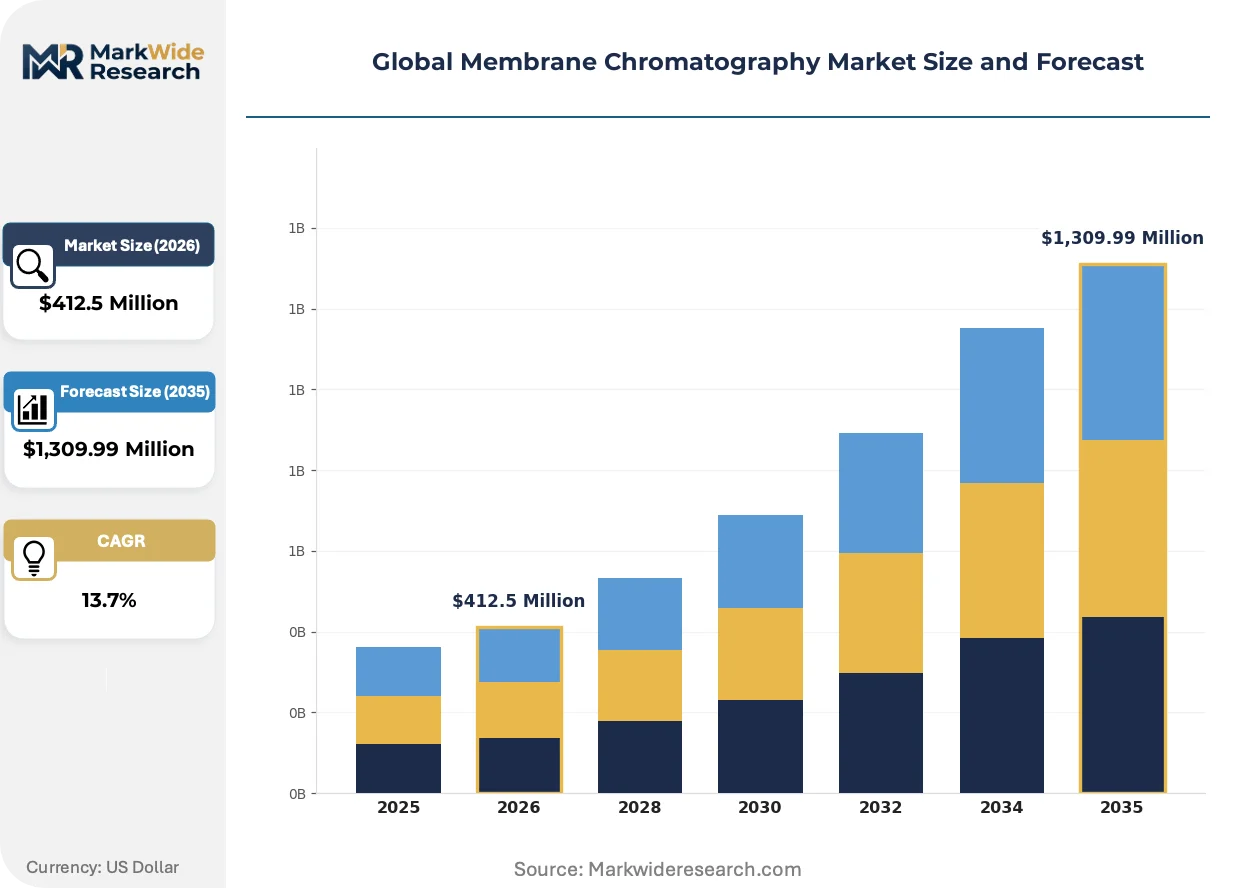
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,309.99 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ion Exchange, Affinity, Hydrophobic Interaction, Size Exclusion, Mixed Mode, Reverse Phase Application: Biopharmaceutical Purification, Food & Beverage Processing, Environmental Testing, Chemical Analysis End User: Biotechnology Firms, Pharmaceutical Manufacturers, Research Laboratories, Quality Control Units Deployment: Laboratory Scale, Pilot Scale, Industrial Scale, Continuous Processing |
| Companies Covered | Sartorius AG, Danaher Corporation, Merck KGaA, Thermo Fisher Scientific Inc., 3M, Pall Corporation, Asahi Kasei Corporation, Cole-Parmer Instrument Company LLC, Restek Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Membrane Chromatography Market Shifts & Advancements
Membrane chromatography is undergoing functional specialization as convective mass transport advantages compress processing economics and regulatory pressure accelerates format standardization across biopharmaceutical supply chains.
Multi-layer stacked membrane formats are modularizing into configurable capsule architectures that separate flow distribution from binding chemistry. Biopharmaceutical facilities in Germany and Switzerland are adopting these configurations for polishing steps. The approach compresses hardware footprint while enabling rapid format swaps between ion-exchange and affinity chemistries within single campaigns.
EMA's Annex 1 revision on sterile manufacturing is mandating extractables testing protocols that membrane vendors must complete before device qualification. The industrial consequence is a documentation arms race where suppliers pre-generate toxicological risk assessments and batch release criteria. Viral vector manufacturing segments are most affected, responding by specifying membrane devices with pre-validated extractables packages in procurement contracts.
Process development outsourcing is consolidating purchasing authority among contract manufacturing organizations that bundle membrane selection with integrated hardware platforms. Traditional distributor channels face compression as these buyers negotiate direct supply agreements with membrane vendors for multi-site technology transfers. The shift is most visible in the United States, where large CMOs are consolidating vendor panels to three qualified suppliers per membrane format.
Global Membrane Chromatography Market Segmentation
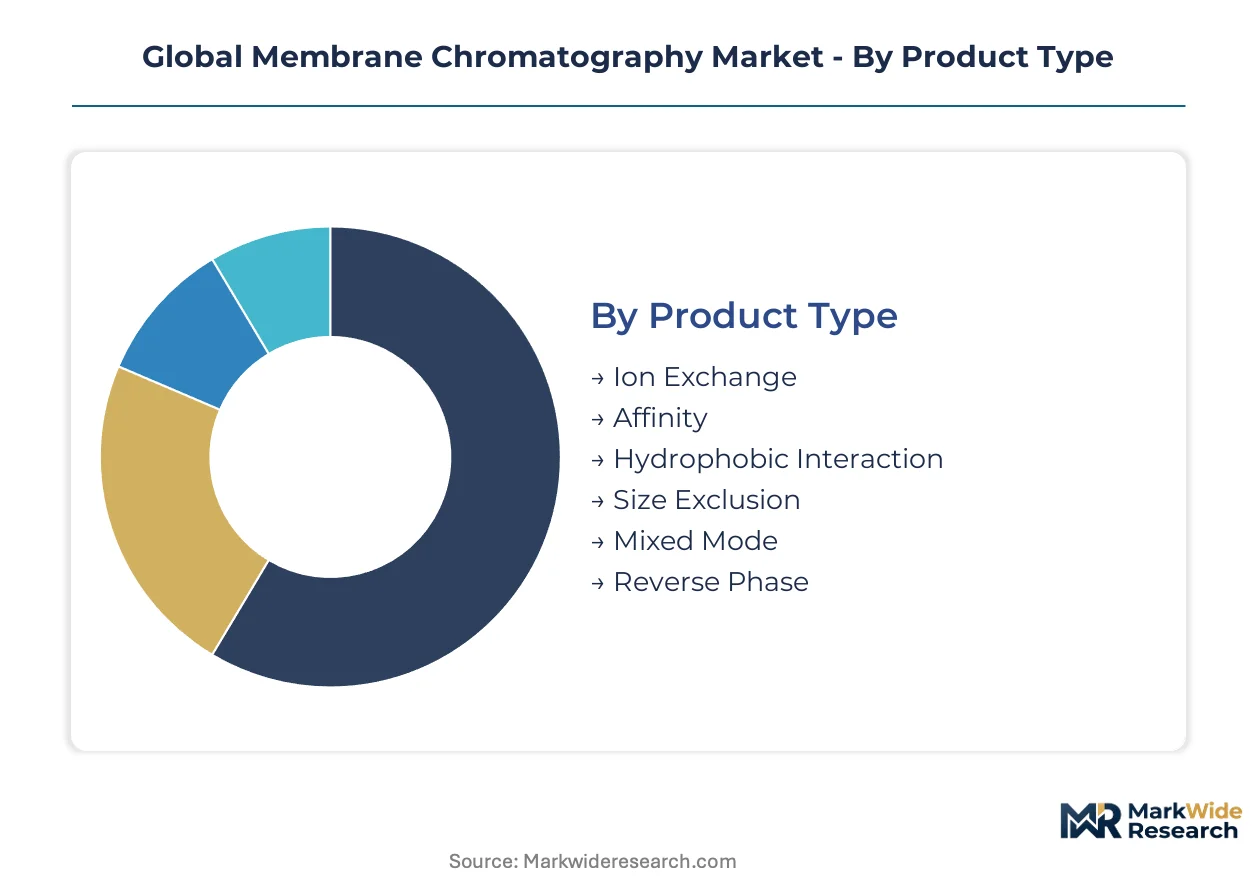
Membrane chromatography vendors configure product portfolios around purification intensity requirements and regulatory validation burdens that differ sharply between laboratory development and commercial manufacturing. Segmentation discipline separates high-margin pilot-scale engagements from commodity industrial-scale supply contracts.
Product Type:
Upgrade cycles accelerate when facilities replace legacy resin columns with membrane formats that slash buffer consumption and processing time for validated biologics manufacturing.
- Ion Exchange:Positively or negatively charged ligands derivatized onto polymeric substrates bind target molecules through electrostatic interactions. Demand concentrates in United States monoclonal antibody facilities where FDA cGMP mandates drive validated clearance of host cell proteins and DNA from harvest streams.
- Affinity:Protein A mimetic surfaces or biospecific ligands enable gentle capture of viral vectors and recombinant proteins. Gene therapy manufacturers in Germany and Switzerland specify these formats for convective mass transport that eliminates diffusional damage to sensitive payloads.
- Hydrophobic Interaction:Ligands with phenyl or butyl moieties separate biomolecules based on surface hydrophobicity under high salt conditions.
- Size Exclusion:Pore-size-controlled membranes fractionate molecules by hydrodynamic radius without binding interactions.
- Mixed Mode:Combinatorial ligand chemistries deliver orthogonal selectivity for complex impurity profiles.
- Reverse Phase:Hydrophobic alkyl chains capture small molecules and peptide fragments in analytical and preparative workflows.
Ion Exchange sits at the top of the volume ranking, with Affinity climbing the fastest.
Application:
Cost tiering separates validated biopharmaceutical applications commanding premium pricing from analytical segments competing on throughput economics.
- Biopharmaceutical Purification:Downstream processing of monoclonal antibodies, vaccines, and gene therapy vectors employs membrane chromatography for capture, intermediate, and polishing steps. Contract manufacturing organizations in China scale membrane-based capture steps as NMPA alignment with ICH Q5A opens import pathways for foreign devices.
- Food & Beverage Processing:Membrane adsorbers remove endotoxins and pathogens from dairy and beverage streams. European facilities deploy single-use formats under EU Green Deal solvent reduction mandates that favor low-carbon purification technologies.
- Environmental Testing:Trace contaminant detection in water and soil samples utilizes membrane concentration prior to analytical confirmation.
- Chemical Analysis:Sample preparation for chromatographic separations leverages membrane extraction and pre-concentration.
Biopharmaceutical Purification dominates absolute revenue, with Food & Beverage Processing expanding most quickly.
End User:
Customer type determines procurement authority concentration, with large pharmaceutical manufacturers bundling multi-site contracts versus fragmented research laboratory purchasing.
- Biotechnology Firms:Venture-backed developers of novel modalities specify membrane chromatography for rapid process development and technology transfer to manufacturing partners.
- Pharmaceutical Manufacturers:Integrated biologics producers with BLA-track molecules drive industrial-scale membrane adoption for validated commercial supply.
- Research Laboratories:Academic and government facilities employ laboratory-scale formats for method development and proof-of-concept studies.
- Quality Control Units:Analytical groups within manufacturing organizations utilize membrane devices for in-process testing and release assays.
Pharmaceutical Manufacturers command the largest procurement volumes, with Biotechnology Firms gaining share fastest.
Deployment:
Maturity gradients separate established laboratory formats from emerging continuous processing architectures that eliminate hold steps between unit operations.
- Laboratory Scale:Small-volume devices support method development and screening studies with minimal sample requirements.
- Pilot Scale:Process development campaigns generate premium service revenue through specialized application support before technology transfer. United States contract manufacturing organizations concentrate purchasing authority for these engagements.
- Industrial Scale:Manufacturing campaigns for commercial biologics deploy configurable capsule architectures that enable rapid format swaps between chemistries.
- Continuous Processing:Integrated membrane chromatography modules connect to perfusion bioreactors and downstream operations in connected processing trains.
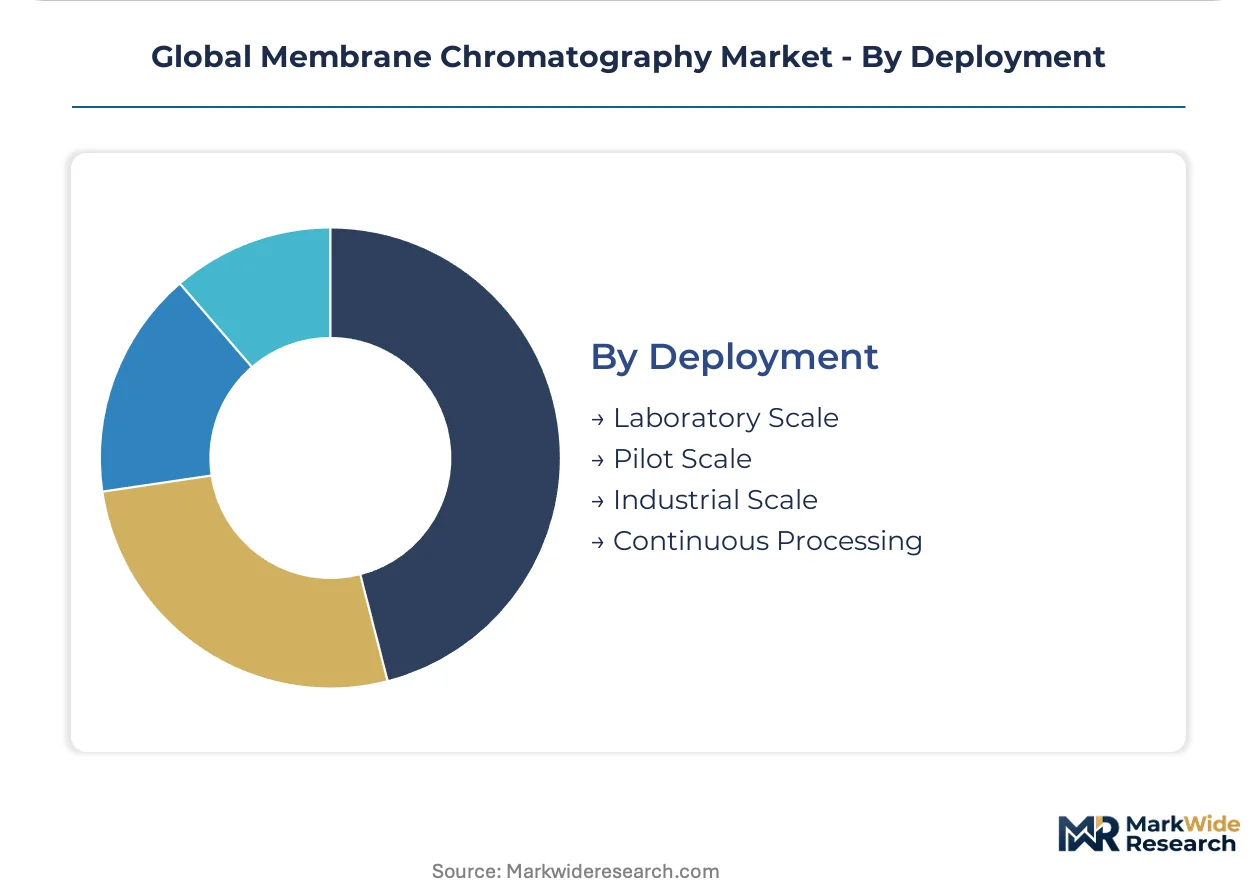
Industrial Scale leads deployment volumes, with Continuous Processing climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Membrane chromatography originated in German chemical engineering laboratories during the 1980s before scaling through Swiss and American biopharmaceutical clusters. The technology diffused through contract manufacturing networks in the 2000s, establishing production footprints across three continents.
United States
FDA cGMP mandates for BLA-track monoclonal antibodies drive validated membrane adoption at industrial scale. The agency's quality metrics program compresses validation timelines for disposable chromatography systems. Massachusetts and North Carolina biomanufacturing clusters concentrate purchasing authority among large contract manufacturing organizations bundling multi-site contracts.
Germany
EU Green Deal carbon intensity targets push pharmaceutical facilities toward single-use membrane formats that halve buffer consumption versus resin columns. EMA Annex 1 extractables documentation requirements force vendors to pre-validate batch consistency protocols. Baden-Württemberg and Bavaria host engineering-intensive capsule production serving European monoclonal antibody facilities.
China
NMPA alignment with ICH Q5A technical guidelines opens import pathways for foreign membrane devices in domestic biologics manufacturing. Shanghai and Suzhou biomanufacturing parks scale membrane-based capture steps for thickening therapeutic pipelines. Contract manufacturing organizations in the Yangtze River Delta concentrate procurement authority for technology transfer engagements.
Switzerland
Swissmedic sterile manufacturing standards mandate granular extractables documentation for membrane devices used in viral vector production. Basel and Zurich biopharmaceutical clusters specify affinity membrane formats for gene therapy polishing steps. The country's precision engineering base supports configurable capsule architectures enabling rapid chemistry swaps.
Japan
PMDA quality guidelines for biologics manufacturing accelerate membrane chromatography adoption in legacy facilities facing resin column substitution friction. Kanto and Kansai pharmaceutical corridors deploy ion-exchange membranes for host cell protein clearance. Domestic suppliers compete on batch-to-batch consistency documentation for regional procurement panels.
Global Membrane Chromatography Market Competitive Landscape
Premium-margin players sit above commodity-margin players across validation documentation and application support depth. The vendor base stratifies between integrated life science conglomerates with full hardware-software portfolios and specialized membrane chemistry houses. Three archetypes dominate: German-engineering precision suppliers, American integrated platform providers, and diversified chemical conglomerates with bioprocessing divisions. Competitive moves concentrate on pre-validated extractables packages and direct supply agreements with large contract manufacturing organizations.
Among German-engineering precision suppliers, Sartorius AG anchors the premium tier through industrial-scale capsule supply. Danaher Corporation, through its Pall Corporation subsidiary, exemplifies the integrated platform archetype bundling membrane and hardware portfolios. Merck KGaA occupies a position within the diversified chemical conglomerate tier, sustaining R&D pipelines for novel affinity chemistries. These three entities represent distinct strategic positions without overlapping core value propositions.
| Leading Market Players |
|---|
| Sartorius AG |
| Danaher Corporation |
| Merck KGaA |
| Thermo Fisher Scientific Inc. |
| 3M |
| Pall Corporation |
| Asahi Kasei Corporation |
| Cole-Parmer Instrument Company LLC |
| Restek Corporation |
| Others |
Supply & Pricing Matrix
EU Green Deal carbon intensity mandates gate qualified supply for membrane chromatography vendors, reserving premium-tier pricing access to manufacturers with pre-validated extractables documentation and single-use format capabilities. Contract manufacturing organizations in Germany and the United States concentrate procurement authority, linking price premiums to batch consistency protocols that satisfy EMA Annex 1 and FDA cGMP requirements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the membrane chromatography market by validation depth and application support intensity. Premium tiers command substantial markups for pre-qualified extractables packages and direct technical service, while standard tiers compete on throughput economics for established monoclonal antibody polishing steps. Price differentiation hinges on certification grade against FDA and EMA standards plus volume scale commitments from multi-site contract manufacturing organizations. Cost compression in economy tiers is intensifying because raw material suppliers for specialized derivatized polymeric substrates concentrate among limited sources. Biotechnology firms developing novel viral vectors exhibit lowest price sensitivity, prioritizing gentle affinity chemistries and rapid technology transfer support over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, Switzerland, and the United States anchor hub-and-spoke patterns for membrane chromatography device fulfillment, with Baden-Württemberg engineering clusters feeding European monoclonal antibody facilities and Massachusetts-North Carolina corridors serving North American biomanufacturing. Specialized derivatized polymeric membranes, protein A mimetic ligands, and ion-exchange functionalization chemistries draw from concentrated chemical supplier bases in Germany and Japan. Single-source vulnerability for affinity ligand substrates creates exposure to input cost volatility and qualification timeline extensions. Distribution runs through direct supply agreements negotiated by large contract manufacturing organizations, bypassing traditional distributor channels for industrial-scale capsule procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane chromatography functions as a regulatory compounder, with FDA quality metrics programs and EMA rolling review frameworks accelerating demand for pre-validated disposable formats that compress BLA submission timelines.
For Market Incumbents: Acquire novel affinity chemistry patent portfolios to defend against emerging entrants specializing in viral vector purification formats. Backward integration into specialized derivatized polymeric membrane production mitigates raw material concentration risk from limited German and Japanese chemical suppliers. Pre-emptive capacity addition in Switzerland and the United States captures contract manufacturing organization consolidation toward three-vendor panels per membrane format. For New Entrants and Emerging Players: Begin with pilot-scale premium service contracts in China's Yangtze River Delta biomanufacturing parks, where NMPA regulatory alignment with ICH Q5A creates import pathway opportunities previously restricted to domestic suppliers. Food and beverage processing applications under EU Green Deal solvent reduction mandates offer the most penetrable segment, with lower validation documentation burdens than biopharmaceutical purification. Position around rapid format swap capabilities for configurable capsule architectures serving multi-product facilities. For Investors and Strategic Acquirers: Roll-up economics work for specialized membrane chemistry houses because EMA Annex 1 extractables documentation requirements create scale advantages in toxicological risk assessment generation and batch release protocol standardization. Target acquisition archetypes include mid-scale affinity ligand developers with pre-validated viral vector purification packages and regional distribution infrastructure in Switzerland or Germany. Watch for inflection when FDA quality metrics program adoption rates cross threshold levels among top-twenty contract manufacturing organizations by revenue.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Validated Extractables Package Development | EMA Annex 1 compliance accelerates device qualification timelines for viral vector manufacturers in Basel and Zurich clusters. |
| Direct Supply Agreement Consolidation | Large United States contract manufacturing organizations bundle multi-site contracts, compressing distributor channel margins. |
| Affinity Chemistry R&D Expansion | Gene therapy vector manufacturing demands gentler capture chemistries that eliminate diffusional payload damage. |
| Continuous Processing Module Integration | Connected processing trains eliminating hold steps create white space for hardware-software platform bundling. |
| China NMPA Regulatory Pathway Investment | ICH Q5A alignment opens import channels for foreign membrane devices in Shanghai and Suzhou biomanufacturing parks. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region triangulated against secondary validation. Bioprocess engineering directors, regulatory affairs specialists at contract manufacturing organizations, membrane chemistry R&D leads, and procurement managers at biotechnology firms provided structured interviews on technology adoption timelines and vendor selection criteria. FDA 483 observations, EMA inspection reports, NMPA technical guideline updates, and customs trade data for chromatography device categories furnished secondary anchors. Bottom-up membrane unit demand estimates and top-down biopharmaceutical purification market sizing were cross-referenced for convergence.
Rate-of-change decomposition across the analysis window separates volume expansion from price-mix effects in membrane chromatography revenue projections. Segmentation dimensions modeled include product type, application intensity tier, deployment scale, and regional regulatory cluster alignment. CAGRs were derived from fitted growth curves against monoclonal antibody pipeline data and gene therapy clinical trial enrollment trajectories. Forecast inputs incorporate contract manufacturing organization capacity expansion announcements and EU Green Deal implementation schedules for pharmaceutical manufacturing carbon intensity targets.
Several conditions sit outside the modeled scope, including sudden regulatory revocation of pre-validated extractables protocols, raw material supply disruptions from geopolitical conflict, and technological substitution by continuous precipitation or crystallization methods. Forecasts reflect documented assumptions about pipeline progression rates and regulatory timeline compression. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Membrane Chemicals Market
Membrane Materials
Global Nanomembrane Market
Membrane Materials
Liquid Applied Membranes Market
Membrane Materials
Polysulfone Market
Membrane Materials
Global Polymer Nanomembrane Market
Membrane Materials
Middle East and Africa Ceramic Membranes Market
Membrane Materials
Membrane Filter Cartridge Market
Membrane Materials
North America Single-Ply Membrane Market
Membrane Materials
Bitumen Waterproofing Membrane Market
Membrane Materials
Global Medical Membranes Market
Membrane Materials
Asia-Pacific, Middle East and Africa Macrofiltration Market
Membrane Materials
Spiral Wound Membrane Market
Membrane Materials
Global Microfiltration Membranes Market
Membrane Materials
Polyvinyl Butyral (PVB) Films and Sheets Market
Membrane Materials
Specialty Breathable Membranes Market
Membrane Materials
Global Membrane Separation Technology Market