
 Membrane Separation Materials Market | 2026-2036
Membrane Separation Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Membrane Separation Materials Market Outlook
Membrane engineering talent scarcity is unwinding capacity expansion timelines across the supply base. DuPont de Nemours, Inc. leverages its fluoropolymer heritage to dominate high-performance reverse osmosis sheet production. Toray Industries, Inc. anchors East Asian supply through integrated hollow-fiber manufacturing. Asahi Kasei Corporation specializes in ultrafiltration modules for biopharmaceutical clients.
Membrane separation materials are engineered thin films—typically 0.1 to 500 microns thick—with controlled pore architectures that selectively permit or block molecular transport based on size, charge, or affinity. These materials separate phases without phase change, cutting energy demand versus thermal distillation. Polymeric membranes occupy the volume base due to scalable solution-casting and phase-inversion manufacturing, though ceramic segments command premium pricing in corrosive high-temperature environments. Reverse osmosis technology leads installed capacity for desalination, while nanofiltration grows fastest in food processing and pharmaceutical concentration steps where divalent ion selectivity matters.
EPA discharge rules and China's MEE effluent standards are tightening permissible contaminant levels, forcing industrial end users toward higher-rejection membrane systems. REACH compliance in Europe and FDA validation requirements for pharmaceutical applications add certification layers that favor established suppliers with documented quality systems. Buyers must weigh material durability against energy efficiency as operating cost pressures intensify and regulatory thresholds continue descending.
Market Dynamics
Zero-liquid-discharge mandates from China's MEE are compressing procurement timelines for high-rejection membrane systems while fluoropolymer supply concentration in East Asia creates material availability bottlenecks for Western membrane fabricators.
Growth Catalysts
- China's MEE effluent standards:Coastal manufacturing provinces now require membrane-based ZLD systems for industrial discharge permits, forcing facility retrofits across chemicals and electronics sectors.
- Food processing concentration steps:Nanofiltration modules for divalent ion selectivity are replacing thermal evaporation in dairy and beverage applications, cutting energy intensity by half.
- Biopharmaceutical ultrafiltration:FDA validation requirements for sterile filtration are driving replacement cycles and premium module specifications across mAb production facilities.
Market Restraints
- PVDF and PTFE resin concentration:Fluoropolymer feedstock production clusters in Japan and China, exposing membrane fabricators to export control and logistics volatility.
- REACH compliance friction:ECHA substance restrictions on perfluorinated compounds are forcing reformulation of high-performance RO membranes before alternatives achieve equivalent rejection rates.
- Ceramic membrane cost structure:Alumina and zirconia feedstocks require sintering furnaces operating above 1,600°C, limiting production to capital-intensive facilities with 18-24 month lead times.
Strategic Opportunities
- India's municipal water utilities:BIS drinking water standards tightening under the Jal Jeevan Mission are creating procurement pipelines for desalination and tertiary treatment membranes in Gujarat and Tamil Nadu.
- Electrodialysis-membrane bioreactor convergence:Hybrid systems for nutrient recovery from wastewater are opening revenue streams in agricultural processing and aquaculture effluent treatment.
- EU Green Deal industrial water reuse targets:Mandatory recycling thresholds for process water in steel and paper mills are mandating membrane installation regardless of payback periods.
Industry Challenges
- Phase-inversion process engineering talent:Solution-casting and controlled precipitation expertise concentrates in aging workforces at Japanese and German membrane specialists, constraining technology transfer.
- FDA 510(k) validation timelines:Biopharmaceutical membrane modules require 14-18 month approval cycles for sterile filtration claims, freezing product development roadmaps.
- Legacy thermal distillation asset stranding:Industrial end-users face write-down pressure when replacing multi-effect evaporators with membrane trains before depreciation cycles complete.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Membrane Separation Materials Market |
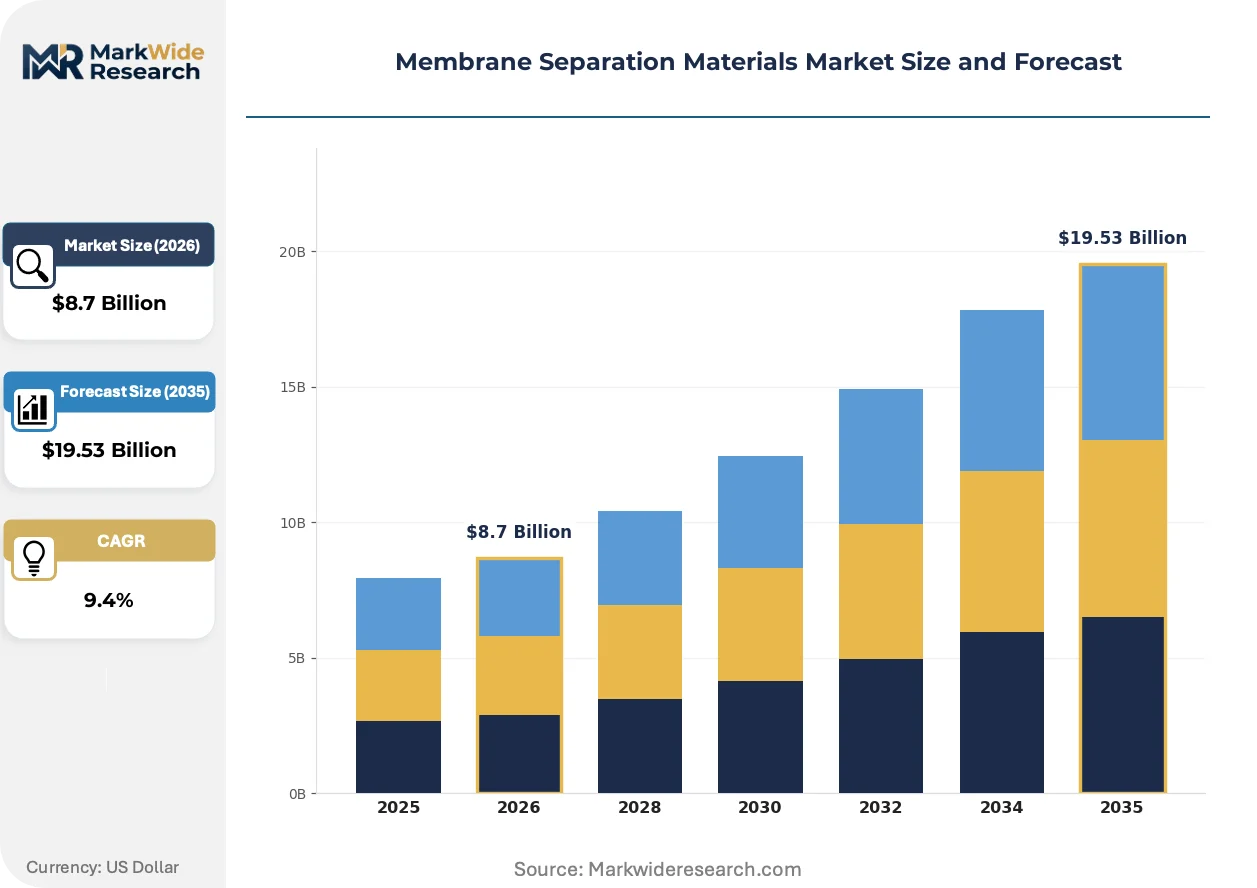
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polymeric, Ceramic, Metallic, Composite Application: Water Treatment, Gas Separation, Biotechnology, Food Processing Technology: Microfiltration, Ultrafiltration, Nanofiltration, Reverse Osmosis End User: Utilities, Pharmaceutical, Food & Beverage, Chemical |
| Companies Covered | DuPont de Nemours, Inc., Toray Industries, Inc., Asahi Kasei Corporation, Pall Corporation, Koch Membrane Systems, Inc., Merck KGaA, SUEZ Group, 3M Company, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Membrane Separation Materials Market Strategic Shifts
Thin-film composite architectures are supplanting asymmetric cellulose acetate structures in desalination, while regulatory pressure on perfluorinated chemistries forces material science pivots across the supply base.
Graphene oxide laminates are displacing conventional polyamide active layers in next-generation reverse osmosis elements. Singapore's national water agency PUB is piloting these modules at scale for municipal NEWater production. The technology is displacing energy-intensive thermal desalination in island nations where electricity costs dominate operating economics.
REACH restrictions on per- and polyfluoroalkyl substances are compelling membrane suppliers to document fluoropolymer alternatives for high-rejection applications. ECHA's 2023 restriction proposal covers PFAS in industrial processes, forcing reformulation of PVDF-based ultrafiltration membranes. European pharmaceutical and food processors are accelerating qualification of sulfonated polysulfone substitutes despite shorter membrane lifetimes.
Integrated service contracts bundling membrane replacement, cleaning chemicals, and performance guarantees are displacing component-only procurement in industrial water treatment. Large chemical manufacturers in Germany's Ruhr region are signing five-year total-cost-of-ownership agreements with membrane system operators. The model is concentrating purchasing power among national water service companies and marginalizing independent membrane distributors.
Membrane Separation Materials Market Segmentation
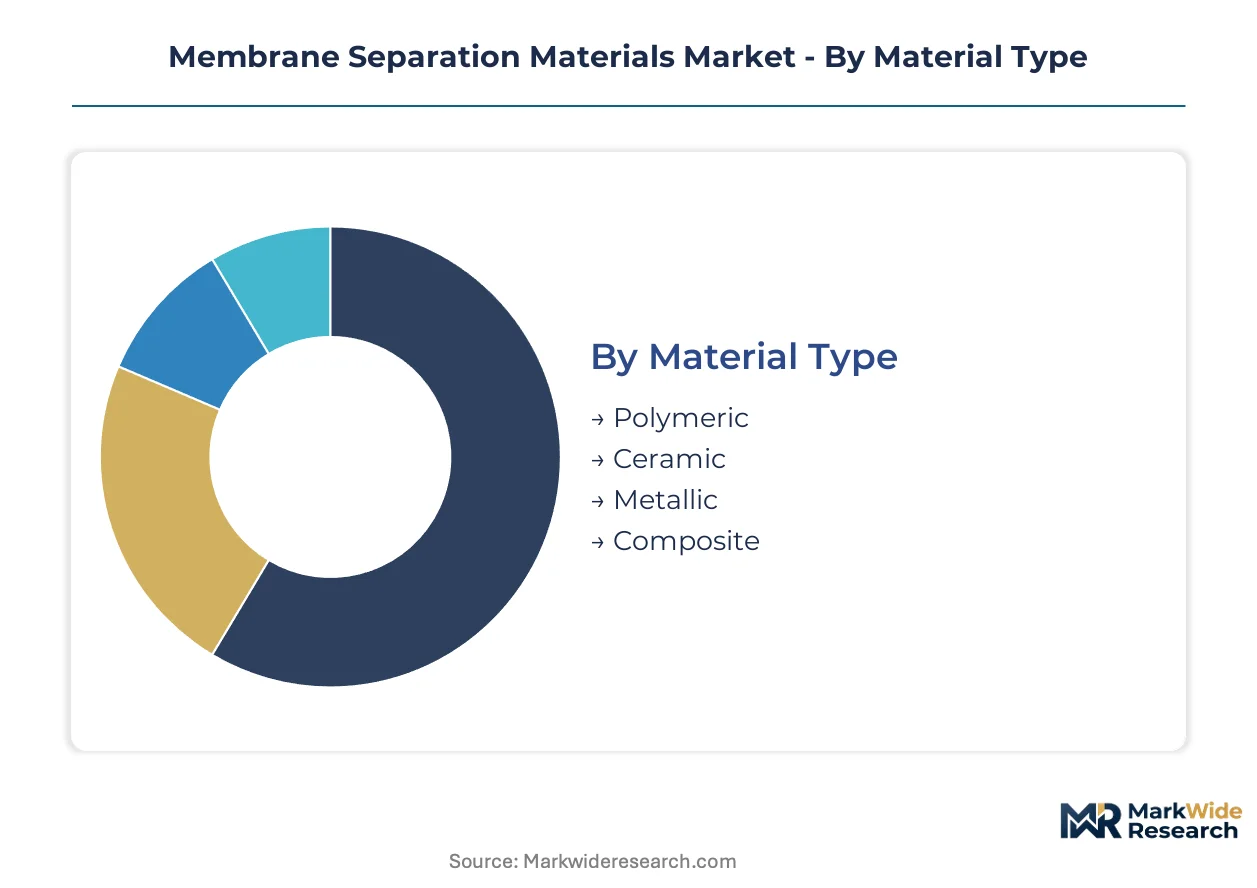
Membrane separation materials fragment across four critical dimensions that determine procurement specifications, certification requirements, and supplier selection criteria. Each segmentation axis carries distinct margin profiles and regulatory compliance burdens that reshape competitive positioning across water treatment, biopharmaceutical, and industrial gas markets.
Material Type:
Polymeric membranes dominate export volumes from East Asian manufacturing clusters, while ceramic and metallic segments serve corrosive high-temperature applications concentrated in domestic European and North American facilities.
- Polymeric:Solution-cast films from phase-inversion processes—typically polysulfone, PVDF, or polyamide—deliver scalable production economics. Demand clusters in China's coastal ZLD installations and India's Jal Jeevan Mission municipal tenders where cost-per-m2 drives procurement.
- Ceramic:Alumina and zirconia structures sintered above 1,600°C withstand aggressive chemical cleaning and thermal cycling. German chemical manufacturers in the Ruhr region specify these for process water reuse under EU Green Deal mandates.
- Metallic:Porous stainless steel and titanium substrates serve high-pressure gas separation and steam sterilization cycles. Niche adoption concentrates in North American pharmaceutical sterile filtration where FDA 510(k) validation requirements favor documented durability.
- Composite:Thin-film polyamide layers on polysulfone supports merge selectivity with mechanical strength. Singapore's PUB NEWater facilities pilot graphene oxide laminate variants for next-generation desalination energy efficiency.
Polymeric commands the established base. The steepest expansion runs through ceramic.
Application:
Cost tier stratification separates commodity water treatment from premium biotechnology applications, with gas separation and food processing occupying intermediate positions defined by membrane replacement frequency and chemical cleaning intensity.
- Water Treatment:Municipal desalination and industrial effluent polishing consume the highest membrane volumes. China's MEE zero-liquid-discharge rules in Jiangsu and Zhejiang provinces force membrane retrofits across electronics and chemicals sectors regardless of payback periods.
- Gas Separation:Hydrogen recovery from refinery streams and carbon capture pre-combustion applications drive hollow-fiber module specifications. Japanese METI hydrogen roadmap targets are accelerating qualification of polyimide membranes for high-pressure CO2/H2 selectivity.
- Biotechnology:Monoclonal antibody concentration and sterile filtration command premium pricing validated to FDA and EMA standards. Replacement cycles run 12-18 months with documented integrity testing protocols.
- Food Processing:Nanofiltration for dairy protein concentration and beverage clarification cuts energy intensity versus thermal evaporation. European dairy cooperatives in the Netherlands and Denmark lead adoption of divalent ion-selective modules.
Water treatment absorbs the volume base. Biotechnology captures the margin premium.
Technology:
Customer type fragmentation splits municipal utilities seeking standardized low-cost elements from pharmaceutical manufacturers demanding validated custom specifications with full batch documentation.
- Microfiltration:0.1-10 micron pore structures remove suspended solids and bacteria without demineralization. Wastewater tertiary treatment in India's Gujarat state deploys these for BIS-compliant drinking water production.
- Ultrafiltration:1-100 nanometer pores retain viruses and macromolecules while passing salts and small organics. Biopharmaceutical tangential flow filtration systems from Asahi Kasei and Toray anchor East Asian supply for mAb production.
- Nanofiltration:Divalent ion selectivity enables softening and partial desalination at lower operating pressures than reverse osmosis. Food processing concentration steps in France and Germany displace multi-effect evaporators with these modules.
- Reverse Osmosis:Dense polyamide active layers reject monovalent ions for seawater and brackish water desalination. DuPont's FilmTec elements dominate high-rejection applications where EPA and China's MEE effluent standards tighten permissible TDS levels.
Reverse osmosis holds the installed capacity base. Nanofiltration posts the steepest climb in food and pharmaceutical process streams.
End User:
Supply concentration varies sharply across end-user categories, with pharmaceutical and chemical sectors sourcing from validated supplier lists while utilities and food processors compete on total cost of ownership.
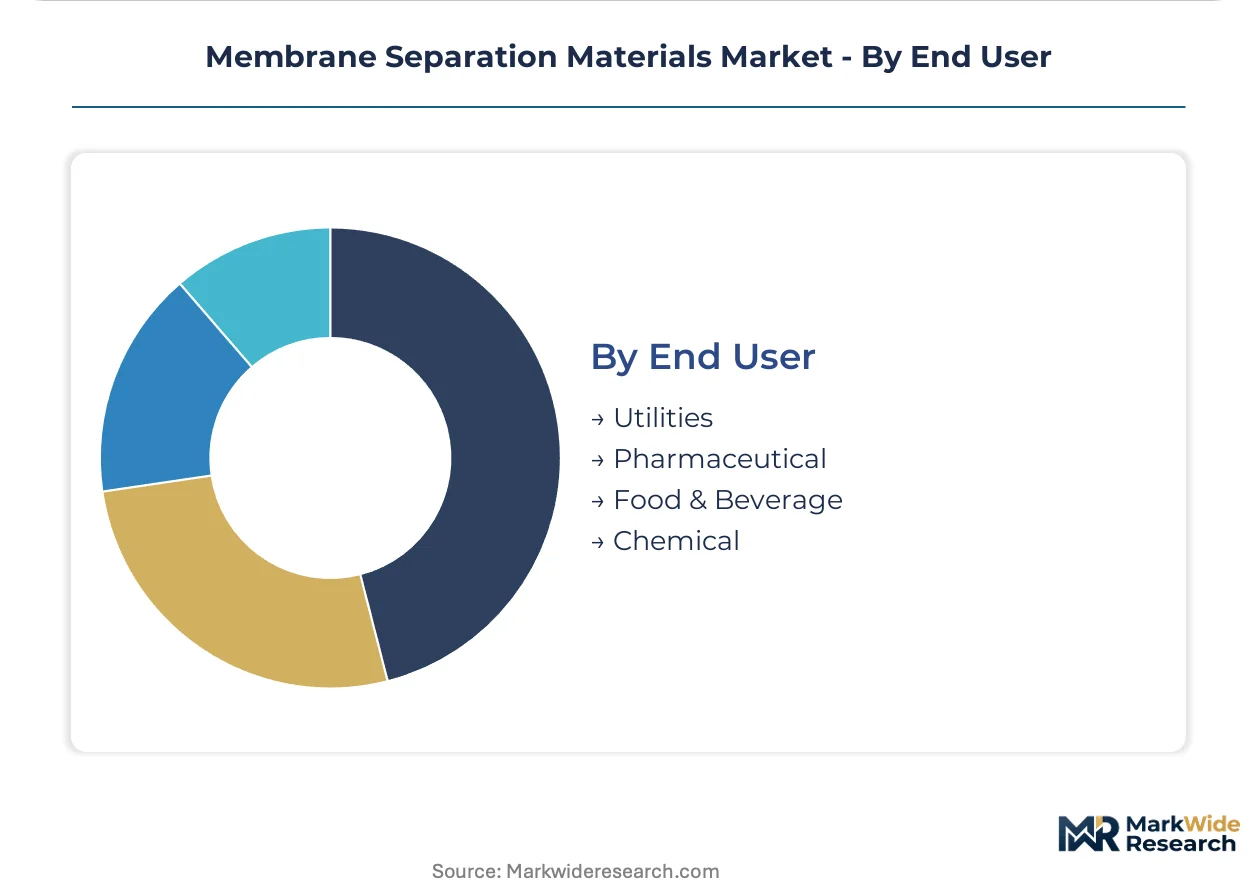
- Utilities:Municipal water and wastewater operators procure through five-year service contracts bundling membranes, chemicals, and performance guarantees. Germany's Ruhr region chemical manufacturers are consolidating purchasing power through national water service companies.
- Pharmaceutical:Sterile filtration validation requirements freeze supplier relationships for 14-18 month FDA 510(k) cycles. EMA and FDA dual filings for European and North American market access add documentation layers favoring established suppliers.
- Food & Beverage:Dairy and beverage processors balance membrane lifetime against cleaning chemical costs. REACH restrictions on perfluorinated compounds are forcing European processors to qualify sulfonated polysulfone substitutes.
- Chemical:Zero-liquid-discharge mandates in China's coastal provinces and EU Green Deal industrial water reuse targets mandate membrane installation regardless of capital recovery timelines. Alumina ceramic membranes serve aggressive solvent and high-temperature process streams.
Utilities represent the volume anchor. Pharmaceutical commands the specification premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE anchors regulatory momentum for membrane separation materials through zero-liquid-discharge mandates that cascade across East Asian manufacturing corridors. The report maps demand concentration across five national markets where effluent standards and industrial water reuse policies are tightening procurement specifications.
China
Jiangsu and Zhejiang provinces drive membrane demand through electronics and chemicals sector retrofits. MEE effluent standards now mandate membrane-based ZLD systems for coastal manufacturing discharge permits. Suzhou and Hangzhou industrial clusters are replacing thermal evaporation with nanofiltration and reverse osmosis trains at scale.
United States
EPA discharge rules are forcing higher-rejection membrane specifications across Texas and Louisiana petrochemical corridors. The agency's tightening permissible contaminant levels for industrial effluent are accelerating replacement cycles in Gulf Coast refineries. Houston-area chemical manufacturers are bundling membrane service contracts with national water operators.
Germany
Ruhr region chemical manufacturers specify alumina ceramic membranes for aggressive solvent process streams under EU Green Deal industrial water reuse targets. ECHA REACH restrictions on perfluorinated compounds are compelling qualification of sulfonated polysulfone substitutes. Düsseldorf and Essen clusters are signing five-year total-cost-of-ownership agreements with membrane system operators.
India
Gujarat and Tamil Nadu municipal utilities are procuring desalination and tertiary treatment membranes as BIS drinking water standards tighten under Jal Jeevan Mission targets. The national mission is creating procurement pipelines for microfiltration modules in coastal cities. Ahmedabad and Chennai water authorities are deploying standardized low-cost elements for BIS-compliant production.
Japan
METI hydrogen roadmap targets are accelerating qualification of polyimide membranes for high-pressure CO2/H2 selectivity in Kansai and Chubu industrial zones. Osaka and Nagoya manufacturing clusters are integrating hollow-fiber modules for refinery hydrogen recovery. Japanese membrane specialists are concentrating phase-inversion process engineering expertise in aging workforces.
Membrane Separation Materials Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the membrane separation materials market. Fluoropolymer heritage and integrated hollow-fiber manufacturing anchor premium positioning, while solution-casting scale economies dominate volume segments. The structure splits between diversified materials conglomerates with polymer feedstock control and specialized membrane fabricators with validation documentation depth. Consolidation pressure is intensifying through strategic partnerships bundling membrane replacement with chemical cleaning services, alongside capacity expansion timelines constrained by engineering talent scarcity.
Among diversified materials conglomerates, DuPont de Nemours, Inc. and BASF SE exemplify archetypes with upstream polymer feedstock integration, while Toray Industries, Inc. represents East Asian fabricators with integrated hollow-fiber manufacturing capabilities. These three occupy positions spanning premium reverse osmosis sheet production, fluoropolymer resin supply concentration, and hollow-fiber module scale respectively.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| Toray Industries, Inc. |
| Asahi Kasei Corporation |
| Pall Corporation |
| Koch Membrane Systems, Inc. |
| Merck KGaA |
| SUEZ Group |
| 3M Company |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
China's MEE zero-liquid-discharge certification gates both supplier qualification and price stratification simultaneously, forcing membrane fabricators to document rejection performance under effluent mandates before bidding on coastal manufacturing retrofits. Buyers in Jiangsu and Zhejiang provinces now bundle validation documentation into total-cost-of-ownership calculations, compressing price competition into certified supplier pools while elevating premium tiers for fluoropolymer-based systems.
Pricing Analysis
East Asian membrane modules trade at 15-25% discounts to European equivalents, though REACH compliance costs for PFAS alternatives erode that spread in EU tenders. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated biopharmaceutical modules from municipal desalination elements and unbranded replacement cartridges. Cost compression in ceramic segments is intensifying because sintering furnace capacity constraints limit supply expansion. Municipal utilities in India exhibit the highest price sensitivity, while pharmaceutical sterile filtration buyers prioritize batch documentation over unit economics.
Supply Chain Analysis
PVDF and PTFE resin concentration in Japan and China exposes membrane fabricators to export control volatility and logistics chokepoints. Fluoropolymer feedstock production draws from Kureha Corporation and Daikin Industries facilities in Ibaraki and Osaka prefectures, while phase-inversion casting equipment sources from German and Japanese precision engineering suppliers. Single-source vulnerability concentrates in high-purity PVDF grades for semiconductor-grade ultrafiltration. Distribution runs through national water service companies in Germany's Ruhr region and direct OEM relationships in China's coastal electronics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane separation materials represent a high-growth disruption as graphene oxide laminates displace polyamide active layers in municipal desalination, with Singapore's PUB pilots validating energy efficiency gains that rewrite operating economics for island nations.
For Market Incumbents: Compound fluoropolymer heritage advantages by securing captive PVDF supply agreements with Japanese resin producers before export control tightening. Expand hollow-fiber capacity in East Asian manufacturing corridors to capture China's MEE-mandated retrofit wave. Counter graphene oxide substitution threats by accelerating thin-film composite R&D roadmaps. For New Entrants and Emerging Players: Lead with sulfonated polysulfone formulations for European food and pharmaceutical processors navigating REACH PFAS restrictions. India's Jal Jeevan Mission municipal tenders offer the most penetrable geography, with standardized low-cost microfiltration modules displacing legacy suppliers. Pursue integrated service contracts bundling membranes and cleaning chemicals to bypass established distribution channels. For Investors and Strategic Acquirers: ECHA's 2023 PFAS restriction proposal reshapes the acquisition landscape toward fluoropolymer-free technology platforms. Five-to-ten-year viability favors ceramic membrane specialists with sintering furnace assets and documented alumina supply chains. Watch for qualification completion of graphene oxide laminates at Singapore PUB scale as the signal for polyamide displacement inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Resin | Captive PVDF supply from Kureha or Daikin insulates against Japanese export controls. |
| Graphene Oxide Laminate Qualification | Singapore PUB validation positions suppliers for NEWater desalination replacement cycles. |
| Integrated Service Contract Expansion | Germany's Ruhr chemical manufacturers consolidate purchasing through five-year TCO agreements. |
| Sulfonated Polysulfone Reformulation | REACH-compliant alternatives capture European dairy and pharmaceutical processor switching. |
| Phase-Inversion Process Engineering Acquisition | Japanese and German specialist talent scarcity extends capacity expansion timelines. |
Study Parameters
A standing panel of membrane plant managers, municipal procurement officers, biopharmaceutical process engineers, and fluoropolymer resin sourcing leads provided ongoing calibration across primary interview rounds. Secondary validation drew from EPA discharge rule filings, ECHA REACH restriction proposals, China's MEE effluent standard updates, and Singapore PUB pilot documentation. Customs data on PVDF and PTFE resin trade flows, SEC 10-K disclosures from diversified materials conglomerates, and ceramic membrane sintering furnace capacity announcements furnished quantitative anchors. Bottom-up membrane volume estimates from end-use applications triangulated against top-down materials consumption models.
Consistency checks against external benchmarks validated projection outputs across the analysis window. The analytical framework modeled material type, application, technology, and end-user segmentation dimensions alongside regional regulatory cluster variations. CAGRs derived from installed capacity buildout timelines, replacement cycle frequencies, and regulatory mandate compliance deadlines. Industry-specific forecast inputs included China's MEE zero-liquid-discharge enforcement trajectory and FDA 510(k) validation pipeline durations for sterile filtration modules.
Underlying assumptions cover sustained fluoropolymer resin availability, REACH restriction implementation timelines, and municipal utility procurement budget continuity, with deviation risk concentrated in export control expansion and graphene oxide scale-up delays. Practitioners should keep alternative scenarios live as ECHA PFAS regulatory finalization and Singapore PUB pilot results evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Geosynthetic Clay Liner Market
Membrane Materials
Global Ceramic Membrane Market
Membrane Materials
Global Roofing Membranes Market
Membrane Materials
Membrane Filter Cartridge Market
Membrane Materials
Global Membrane Technology Market
Membrane Materials
PTFE Membrane Market
Membrane Materials
Global Waterproofing Membrane Market
Membrane Materials
Global Microfiltration Membranes Market
Membrane Materials
Asia-Pacific, Middle East and Africa Macrofiltration Market
Membrane Materials
North America Transparent Conductive Films Market
Membrane Materials
North America Roofing Membranes Market
Membrane Materials
SBS Modified Bitumen Membrane Market
Membrane Materials
Asia Pacific Waterproofing Membrane Market
Membrane Materials
Middle East and Africa Ceramic Membranes Market
Membrane Materials
Membranes Market
Membrane Materials
Global Membrane Filters Market