
 Modified Bitumen Market | 2026-2036
Modified Bitumen Market Size, Share, and Industry Trends Forecast 2026-2036
Modified Bitumen Market Outlook
A shortage of certified polymer-modification technicians is unwinding capacity expansion timelines across multiple production facilities. TotalEnergies SE leverages integrated refining and petrochemical assets to secure consistent SBS feedstock for modified binder output. ExxonMobil Corporation anchors its position through proprietary catalyst technologies that enhance asphalt compatibility with high-performance polymers. Sika AG specializes in application-system solutions that bundle modified bitumen membranes with installation equipment and contractor training programs.
Modified bitumen consists of distilled crude residue blended with synthetic elastomers or plastomers—typically SBS, APP, or SEBS—at temperatures between 160°C and 190°C to achieve enhanced elasticity, thermal stability, and fatigue resistance for roofing and pavement applications. The SBS product category dominates volume owing to its superior low-temperature flexibility in cold-climate roofing and road surfacing, while torch-applied installation retains the largest share of commercial roofing work despite growing regulatory scrutiny of open-flame methods. Self-adhered systems are gaining fastest in residential and confined-space applications where fire codes restrict torch use.
Federal Highway Administration specifications, EPA volatile organic compound limits, and OSHA workplace exposure standards collectively shape formulation choices, installation protocols, and contractor certification requirements across the United States. State departments of transportation in California, Texas, and New York impose additional performance-graded binder specifications that filter market access for non-compliant suppliers. Stakeholders must monitor evolving polymer supply chain configurations and state-level low-carbon procurement mandates to align product portfolios with emerging qualification criteria.
Market Dynamics
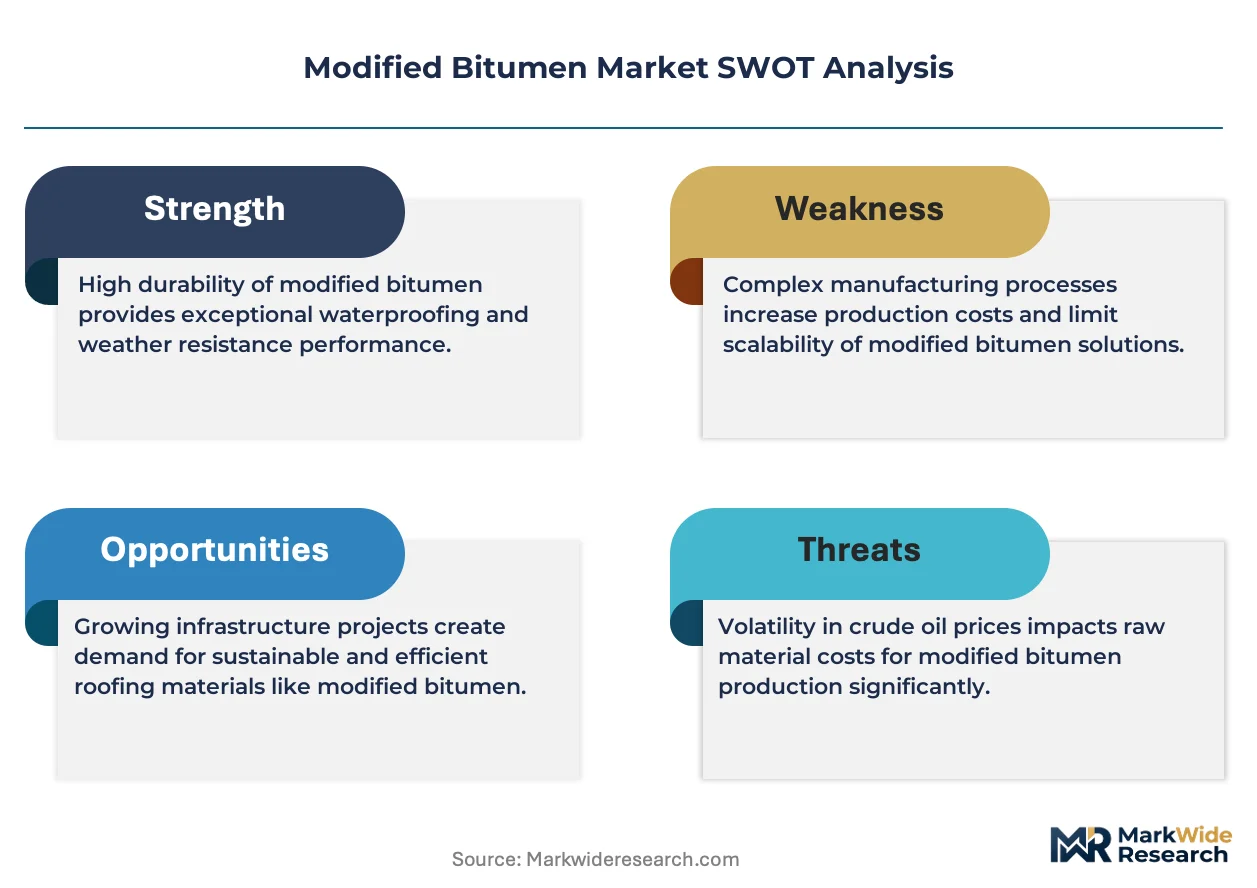
Federal infrastructure spending in the United States is compressing project timelines and forcing rapid qualification of polymer-modified binders, creating simultaneous pull for SBS-enhanced formulations and bottlenecks in certified technician availability.
Growth Catalysts
- FHWA Performance-Graded Specifications:Federal Highway Administration mandates for extreme climate zones accelerate specification upgrades across state transportation departments.
- Roofing Membrane Demand:Commercial building envelope retrofits in cold-climate zones favor SBS-modified sheets for low-temperature flexibility.
- Polymer Stabilization:Advanced cross-linking chemistries extend pavement service life in freeze-thaw cycling zones.
Market Restraints
- Styrene-Butadiene Feedstock Volatility:SBS block copolymer prices track butadiene monomer swings from Asian petrochemical complexes.
- Technician Certification Bottlenecks:OSHA workplace exposure standards and manufacturer warranty requirements constrain qualified installer pools.
- Torch-Applied Regulatory Friction:Municipal fire codes in dense urban cores restrict open-flame membrane installation methods.
Strategic Opportunities
- Self-Adhered System Expansion:Solvent-free adhesive technologies unlock residential and confined-space applications where torch methods face prohibition.
- State Low-Carbon Procurement Mandates:California Department of Transportation performance specifications increasingly weight embodied carbon in binder selection.
- Recycled Polymer Integration:Post-consumer tire rubber and plastic waste streams offer feedstock diversification for cost-competitive modification.
Industry Challenges
- Polymer-Modification Technician Scarcity:Specialized blending equipment operation and quality control protocols require training pipelines that lag capacity expansion schedules.
- Multi-Jurisdictional Compliance Burden:State-specific binder grading systems force formulation fragmentation and inventory complexity for national suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modified Bitumen Market |
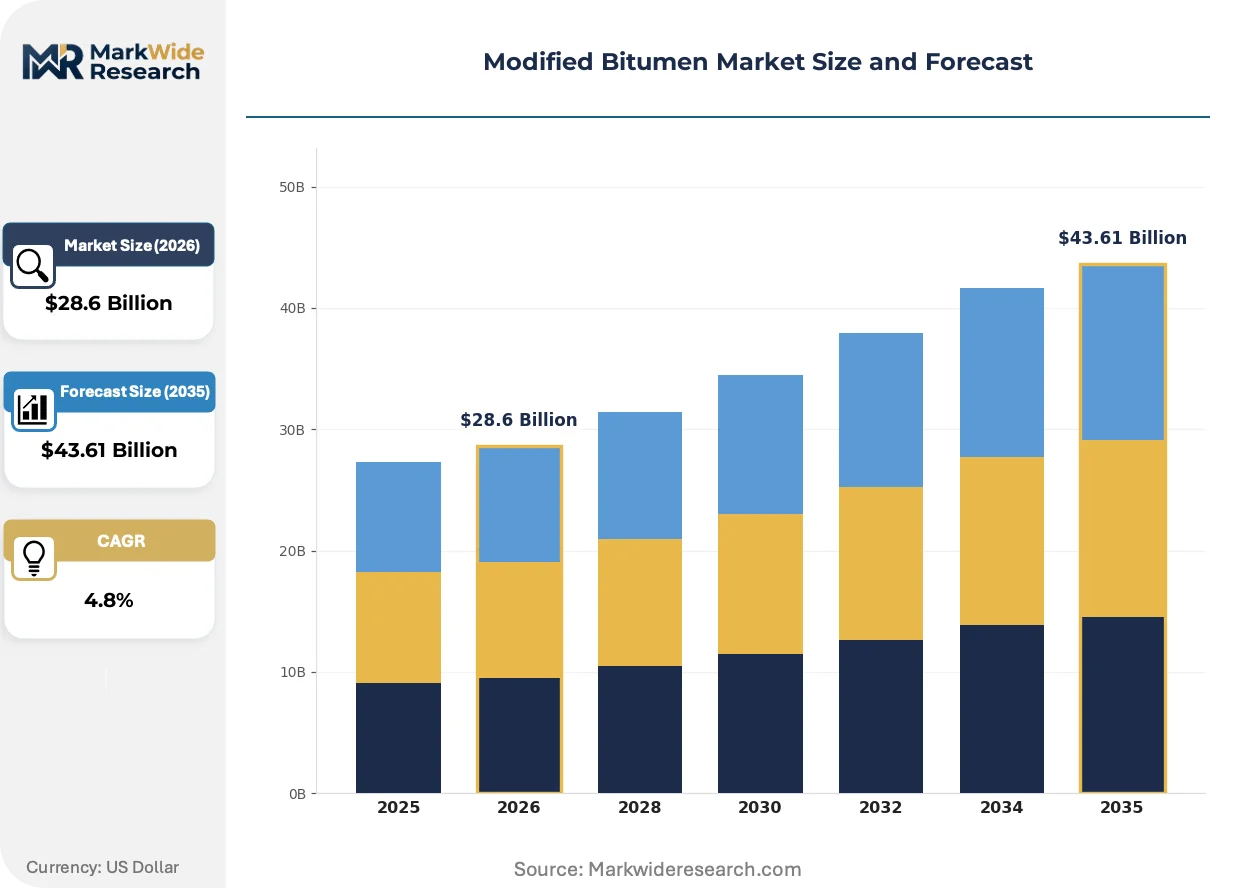
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SBS, APP, SEBS, PE Application: Roofing, Waterproofing, Pavement, Insulation End User: Construction, Transportation, Industrial, Residential Installation Type: Mechanically Attached, Torch Applied, Self-Adhered, Cold Adhesive |
| Companies Covered | TotalEnergies SE, ExxonMobil Corporation, Shell plc, Sika AG, COLAS S.A., Gazprom Neft PJSC, Nynas AB, GAF Materials LLC, Bitumina Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modified Bitumen Market Strategic Shifts
Modified bitumen production is pivoting toward cold-process emulsion technologies and bio-based polymer alternatives as thermal energy costs and carbon accounting reshape formulation economics.
Warm-mix asphalt additive packages are miniaturizing the thermal footprint of polymer incorporation, allowing SBS dispersion at reduced temperatures. State departments of transportation in Minnesota and Wisconsin are piloting these systems to cut fuel consumption during production. The technology is miniaturizing energy intensity benchmarks that previously locked out smaller regional blenders from high-performance specification markets.
EPA volatile organic compound limits under the National Emission Standards for Hazardous Air Pollutants are tightening storage tank and loading rack requirements. Roofing membrane manufacturers are reformulating cutback adhesives and solvent-based primers to water-borne alternatives. Commercial contractors in California and New York metropolitan areas face accelerated compliance timelines that favor pre-certified system suppliers.
Building owners now specify single-source accountability for membrane performance, bundling material supply with installation labor and long-term maintenance. This consolidates purchasing authority away from independent roofing contractors toward manufacturer-direct programs. The shift concentrates contract value in the United States commercial sector where warranty-backed performance guarantees carry premium pricing power.
Modified Bitumen Market Segmentation
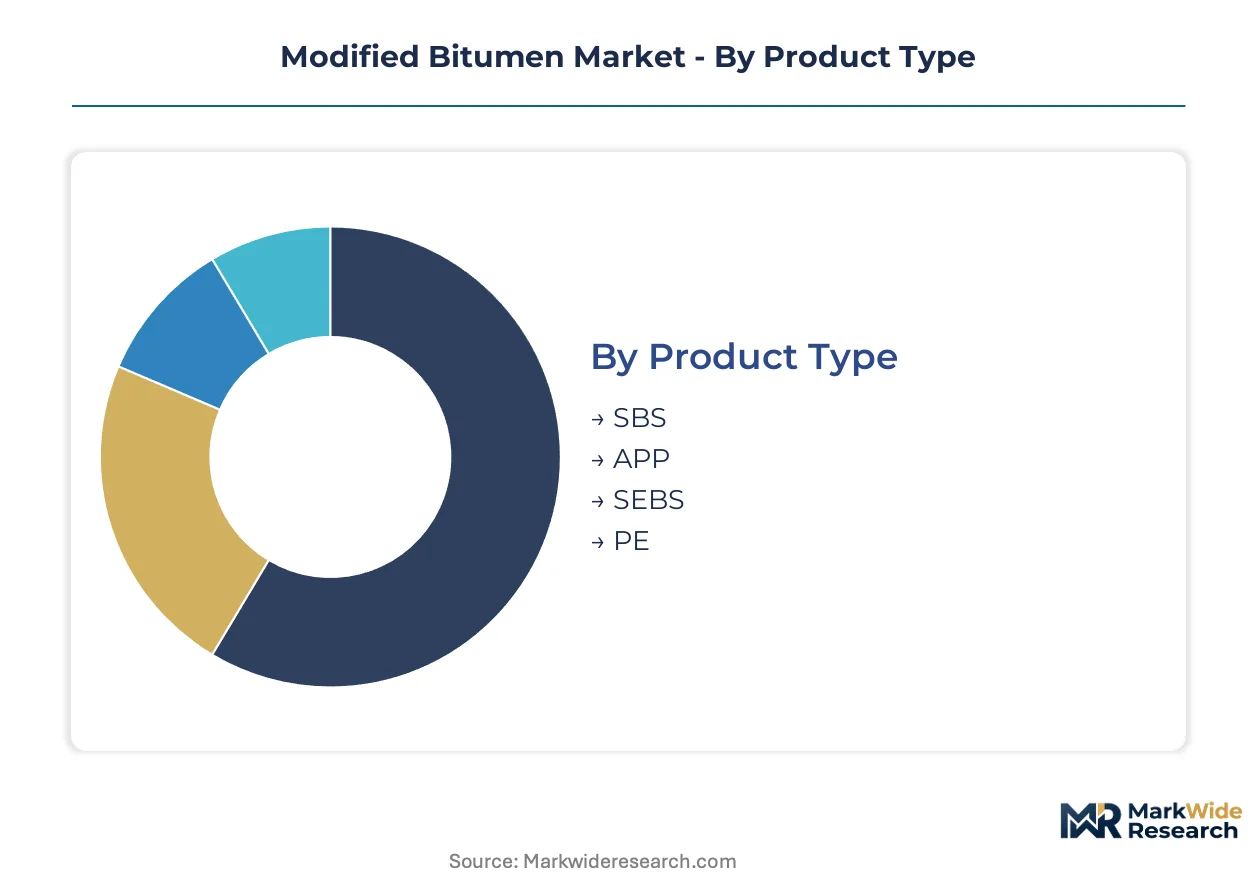
Segmentation in modified bitumen reveals how polymer chemistry, installation constraints, and end-use durability requirements fragment demand across distinct qualification tiers. Specification-grade products command premium positioning in federal highway contracts, while commodity-grade formulations serve residential roofing through distributor channels.
Product Type:
SBS and APP formulations flow through specification-grade channels serving state transportation departments, while SEBS and PE grades reach commercial roofing via distributor networks with lighter certification burdens.
- SBS:Styrene-butadiene-styrene block copolymer delivers superior low-temperature flexibility and elastic recovery for freeze-thaw cycling environments. Demand concentrates in Minnesota, Wisconsin, and New York state highway specifications where FHWA performance-graded binder requirements mandate SBS modification for extreme climate zones.
- APP:Atactic polypropylene enhances thermal stability and UV resistance for high-temperature roofing applications. Commercial building envelope retrofits in Texas and Arizona specify APP-modified membranes where torch-applied installation dominates and heat resistance outweighs cold-flex requirements.
- SEBS:Hydrogenated SBS variant offers enhanced oxidation stability for long-service-life waterproofing systems.
- PE:Polyethylene modification provides cost-competitive stiffness for industrial pavement base courses and secondary road applications.
By volume, SBS leads. By growth pace, SEBS is ahead.
Application:
Cost tier separation distinguishes specification-driven pavement work from price-sensitive waterproofing jobs, with roofing occupying the mid-tier where membrane warranty terms drive material selection.
- Roofing:SBS and APP modified bitumen membranes dominate commercial low-slope applications, with thickness and reinforcement specifications varying by building code wind-uplift requirements. Self-adhered systems are displacing torch methods in California and New York metropolitan areas where municipal fire codes restrict open-flame installation.
- Waterproofing:Below-grade foundation and plaza deck applications demand seamless membrane integrity with high puncture resistance. Transportation infrastructure projects in coastal cities specify multi-layer modified bitumen protection boards for bridge decks and tunnel linings exposed to chloride intrusion.
- Pavement:Polymer-modified binder extends asphalt service life in heavy-traffic corridors and airport runways.
- Insulation:Modified bitumen facers on rigid foam boards serve commercial building thermal envelope assemblies.
Pavement commands the highest specification burden. Waterproofing is climbing the fastest as coastal infrastructure resilience spending accelerates.
End User:
Customer type determines procurement channel: federal and state agencies mandate certified installer networks, while residential buyers route through retail building supply.
- Construction:General and specialty contractors purchase through manufacturer-direct programs where bundled material-labor warranties consolidate purchasing authority. Commercial sector concentration in the United States favors single-source accountability models over independent distributor relationships.
- Transportation:State departments of transportation and federal highway administration contracts impose performance-graded binder specifications with polymer content verification. California, Texas, and New York DOT qualification requirements filter market access to pre-approved suppliers with certified technician networks.
- Industrial:Refinery, power generation, and manufacturing facility owners specify chemical-resistant modified bitumen systems for process areas.
- Residential:Homeowners and small roofing contractors access modified bitumen through retail building supply channels with limited technical support.
Transportation consumes the most polymer by tonnage. Construction is expanding most quickly as building envelope retrofit mandates multiply.
Installation Type:
Maturity stage separates established torch methods from emerging cold-process technologies, with regulatory pressure accelerating the transition timeline in dense urban jurisdictions.
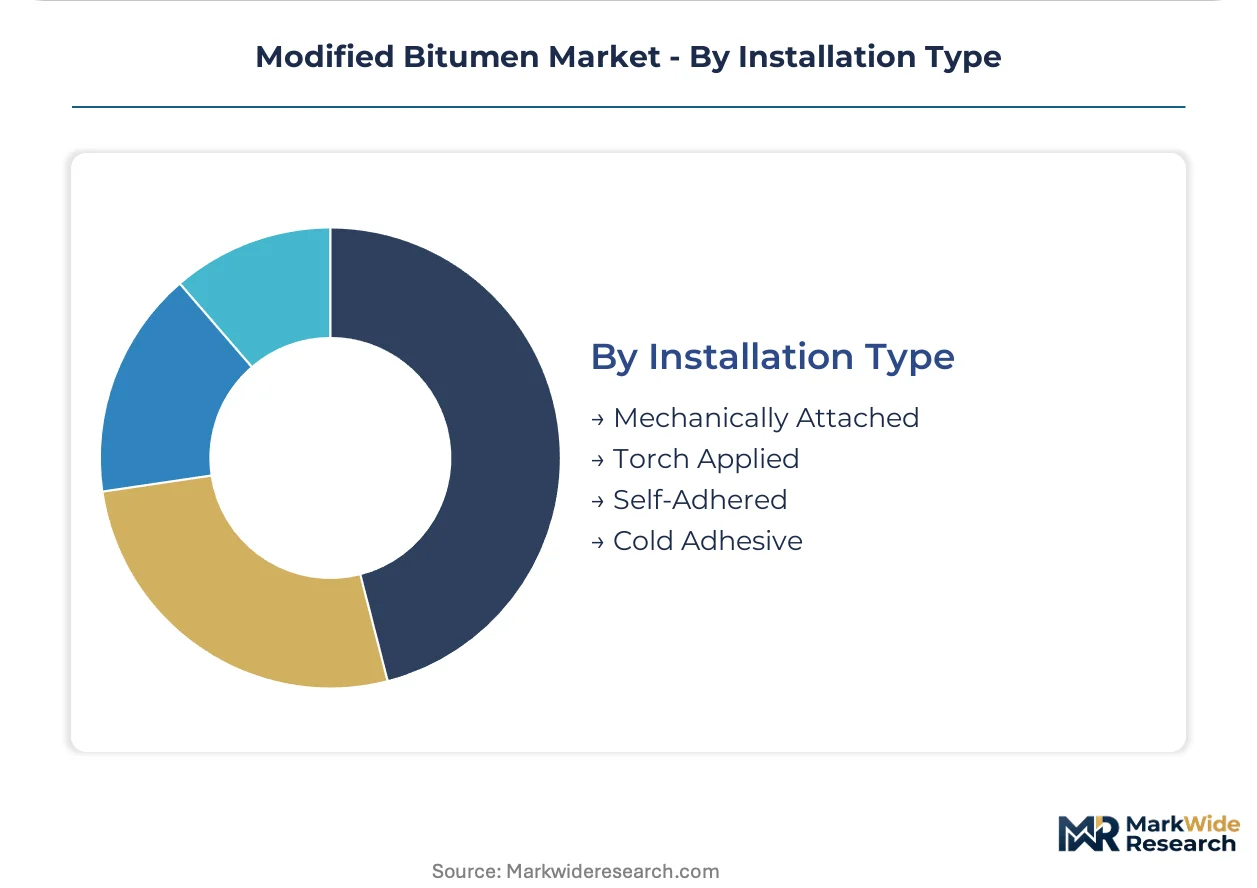
- Torch Applied:Open-flame heating of membrane underside creates molten bitumen bond to substrate, delivering reliable seam integrity in experienced hands. Regulatory friction is mounting in Chicago, Boston, and San Francisco where municipal fire codes increasingly restrict torch use on occupied buildings and confined roof decks.
- Self-Adhered:Factory-applied adhesive backing enables solvent-free installation without flame equipment, unlocking residential and confined-space applications. California and New York metropolitan contractors face accelerated compliance timelines that favor pre-certified self-adhered system suppliers under EPA volatile organic compound limits.
- Mechanically Attached:Fastener-based securing suits high-wind zones and lightweight substrates where adhesive bond strength is uncertain.
- Cold Adhesive:Solvent-based or water-borne bituminous adhesives serve detailing and repair work.
Torch applied retains volume leadership. Self-adhered is gaining share fastest as fire code restrictions proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes modified bitumen disproportionately for pavement binders under federal highway specifications, while European and Asian markets emphasize roofing membranes and waterproofing systems with distinct polymer preferences.
United States
Federal infrastructure spending through the Infrastructure Investment and Jobs Act accelerates state transportation department procurement of SBS-modified binders. The Federal Highway Administration mandates performance-graded specifications for extreme climate zones. California, Texas, and New York state DOTs operate pre-approval systems that filter supplier access based on certified technician networks and polymer content verification protocols.
Germany
Commercial building envelope retrofits and industrial waterproofing drive APP and SBS membrane specifications. The country's national construction regulator enforces energy efficiency standards that favor durable roofing systems with extended service life guarantees. The Rhine-Ruhr industrial corridor concentrates modified bitumen blending capacity serving Benelux export markets.
China
High-speed rail expansion and urban subway tunnel waterproofing create concentrated demand for SEBS-modified systems with oxidation stability. The Ministry of Ecology and Environment enforces dual carbon goals that pressure manufacturers toward warm-mix additive packages and reduced thermal processing. The Yangtze River Delta hosts integrated refining and modification complexes supplying coastal infrastructure projects.
India
National highway widening programs and smart city mission investments expand polymer-modified binder offtake for heavy-traffic corridors. The Bureau of Indian Standards issues performance specifications for modified bitumen that align with IRC guidelines for flexible pavements. Gujarat and Maharashtra states concentrate domestic blending capacity near petrochemical feedstock sources and western port export infrastructure.
Brazil
Agricultural road networks and port terminal expansions specification-grade binders for load-bearing surfaces. The national petroleum regulator oversees asphalt quality standards through ANP resolutions governing polymer content and performance testing. São Paulo state anchors domestic production with backward integration into SBS feedstock through local petrochemical complexes.
Modified Bitumen Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with petroleum majors leveraging captive bitumen supply against chemical companies emphasizing formulation expertise. The market structure rewards backward integration into SBS polymer production and forward integration into certified installation networks. Three archetypes dominate: integrated energy majors with refining assets, construction chemical specialists with application-system bundling, and regional blenders with state-level DOT qualifications. Competitive moves concentrate on securing pre-approval status with transportation departments and acquiring certified technician training capacity.
Among energy-integrated majors, TotalEnergies SE and ExxonMobil Corporation exemplify the upstream-controlled archetype with captive bitumen and polymer feedstock positions. Sika AG occupies the construction chemical specialist tier, bundling membrane supply with installation equipment and contractor certification programs. These three companies anchor distinct competitive vectors: feedstock security, proprietary catalyst technologies, and application-system integration respectively.
| Leading Market Players |
|---|
| TotalEnergies SE |
| ExxonMobil Corporation |
| Shell plc |
| Sika AG |
| COLAS S.A. |
| Gazprom Neft PJSC |
| Nynas AB |
| GAF Materials LLC |
| Bitumina Group |
| Others |
Value Chain & Pricing Dynamics
FHWA performance-graded binder specifications gate both supplier qualification and price differentiation simultaneously, compressing market access to pre-certified blenders while creating tiered value capture across specification-grade and commodity-grade product streams.
Pricing Analysis
Long-term offtake contracts dominate state transportation department procurement, with spot markets serving emergency repair and residential roofing channels. Three-tier pricing structure across premium, standard, and economy levels separates FHWA-certified SBS formulations from distributor-grade APP membranes and unmodified base courses. Cost compression in the commodity tier is intensifying because recycled polymer feedstocks are eroding traditional SBS cost structures. Residential roofing contractors exhibit highest price sensitivity, while state DOTs prioritize performance guarantees over unit economics.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes elevates inbound logistics costs for butadiene monomer and SBS block copolymer feedstocks, compressing blender margins on imported polymer volumes. Supply concentrates in the United States, Germany, and China, with backward integration into captive bitumen refining anchoring competitive positioning for integrated majors. Raw material dependencies span crude residue distillation, synthetic elastomer production, and cross-linking chemical additives. Single-source vulnerability in certified technician training pipelines constrains capacity expansion timelines. Distribution runs through manufacturer-direct programs for specification-grade pavement binders and distributor networks for commercial roofing membranes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory entrenchment story where FHWA and state DOT pre-approval systems create switching costs that lock qualified suppliers into multi-year contract cycles.
For Market Incumbents: Shield market position by deepening certified technician training pipelines ahead of federal infrastructure spending waves, and secure backward integration into SBS polymer production to neutralize Asian petrochemical feedstock volatility. Emerging cold-process emulsion technologies threaten thermal-blending incumbents with lower capital intensity entry paths. For New Entrants and Emerging Players: State-level DOT fast-track certification programs in Texas and California offer the most penetrable entry vectors for regional blenders lacking federal pre-approval status. Self-adhered membrane systems in fire-code restricted metropolitan areas present white-space expansion with lighter regulatory burdens than pavement binders. Partner with roofing contractor associations to bypass manufacturer-direct distribution control. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cold-process modification technologies, enabling asset-light entry models that challenge thermal-blending incumbents. Target regional blenders with established state DOT qualifications and captive polymer supply agreements as acquisition candidates. Watch for inflection when California Department of Transportation low-carbon procurement mandates trigger reformulation cost spikes that favor integrated suppliers with bio-based polymer alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SBS Production | Captive feedstock supply neutralizes Asian butadiene price volatility for qualified blenders. |
| Certified Technician Network Expansion | FHWA and state DOT warranty requirements constrain installer pools, creating bottleneck control. |
| Cold-Process Emulsion Technology Deployment | Warm-mix additive packages cut thermal energy costs and open specification markets to regional players. |
| Self-Adhered System Portfolio Buildout | Solvent-free adhesive technologies unlock residential and confined-space applications under EPA VOC limits. |
| Recycled Polymer Feedstock Integration | Post-consumer tire rubber and plastic waste streams diversify input costs and align with state low-carbon mandates. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across modified bitumen value chains, blending primary interviews with state DOT procurement officers, roofing contractor association leaders, polymer modification plant managers, and commercial building envelope consultants with secondary validation from FHWA specification databases, EPA NESHAP regulatory filings, state transportation department bid tabulations, and customs trade data on SBS polymer imports. Bottom-up volume estimates triangulated against top-down infrastructure spending allocations.
Across the analysis window, forecasts model polymer chemistry type, installation method, end-use application, and regional specification-grade tier as segmentation dimensions. CAGRs derive from elasticity-adjusted demand projections tied to federal highway appropriation trajectories and commercial construction permit flows. Industry-specific inputs include state DOT pre-approval status transitions and torch-applied regulatory restriction timelines in dense urban jurisdictions.
Decision-makers should treat outputs as directional under assumptions of sustained federal infrastructure spending and stable Asian petrochemical feedstock availability; material deviation in either would warrant model refresh. Polymer price volatility, technician certification bottlenecks, and accelerated low-carbon procurement mandates represent primary forecast revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Volatile Organic Compounds (VOC) Concentrator Market
Industrial Chemicals
Beneficiation Reagents Market
Industrial Chemicals
North America Paper Machine Oil Market
Industrial Chemicals
Cryolite Market
Industrial Chemicals
Thermic Fluids Market
Industrial Chemicals
Commercial Electronic Detonator Market
Industrial Chemicals
Antiscalant Market
Industrial Chemicals
Molecular Sieve for Air Separation Market
Industrial Chemicals
Global Biochemical Market
Industrial Chemicals
Methylene Diphenyl Di-Isocyanate (MDI) Market
Industrial Chemicals
Enzymes for Laundry Detergent Market
Industrial Chemicals
Hydro Fluorocarbon Market
Industrial Chemicals
Global Microencapsulated Pesticides Market
Industrial Chemicals
High Viscosity Mixer Market
Industrial Chemicals
Reconditioned Drums Market
Industrial Chemicals
Global N-MDEA Market