
 Global Geomembrane Market | 2026-2036
Global Geomembrane Market Size, Share, and Industry Trends Forecast 2026-2036
Global Geomembrane Market Analysis
ISO 10318 qualification for geosynthetics certification is reorganizing competitive access in geomembrane supply, forcing manufacturers to demonstrate consistent seam strength and chemical resistance under standardized test protocols. Solmax leverages integrated resin-to-liner production across North American and European facilities to control material consistency. AGRU America anchors its position through specialized textured HDPE grades engineered for steep slope mining applications. NAUE Group differentiates via geosynthetic system bundling that combines geomembranes with geotextiles and drainage composites for turnkey containment projects.
Geomembranes are impermeable synthetic membrane liners, typically manufactured from polymeric sheets ranging from 0.5 to 3.0 millimeters in thickness, designed to control fluid migration in engineered containment systems. High-Density Polyethylene formulations dominate landfill and mining installations due to superior chemical resistance and weldability under thermal fusion processes. Low-Density Polyethylene occupies niche agricultural pond applications where flexibility and conformability to uneven subgrades outweigh puncture resistance requirements. Water Management applications represent the fastest-expanding demand cluster as drought-prone regions invest in reservoir and canal lining infrastructure.
The EPA's Resource Conservation and Recovery ActSubtitle D standards mandate composite liner systems for municipal solid waste landfills, directly specifying minimum geomembrane thickness and hydraulic conductivity thresholds. EMA and national regulators across Germany, France, and Italy enforce REACH-compliant resin formulations that restrict phthalate plasticizers in PVC geomembranes, reshaping material selection in European environmental projects. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions under EU and US frameworks, as fluorinated polymer alternatives face prospective phase-downs that could disrupt existing product portfolios and qualification timelines.
Market Dynamics
Copper heap leach operations in Chile and Peru are driving specification intensity for geomembrane liners, as mining operators expand pad footprints and tighten seam performance requirements under rising extraction volumes.
Growth Catalysts
- EU Green Deal Landfill Directive:Containment standards across Germany, France, and Italy mandate thicker liner specifications and composite barrier systems, forcing upgrade cycles at municipal waste facilities.
- Water-scarce agricultural regions:Australia's irrigation districts and coal seam gas water storage projects specify HDPE geomembranes for evaporation control and aquifer protection.
- ISO 10318 certification protocols:Standardized seam strength and chemical resistance testing is filtering supplier access, concentrating procurement toward qualified manufacturers.
Market Restraints
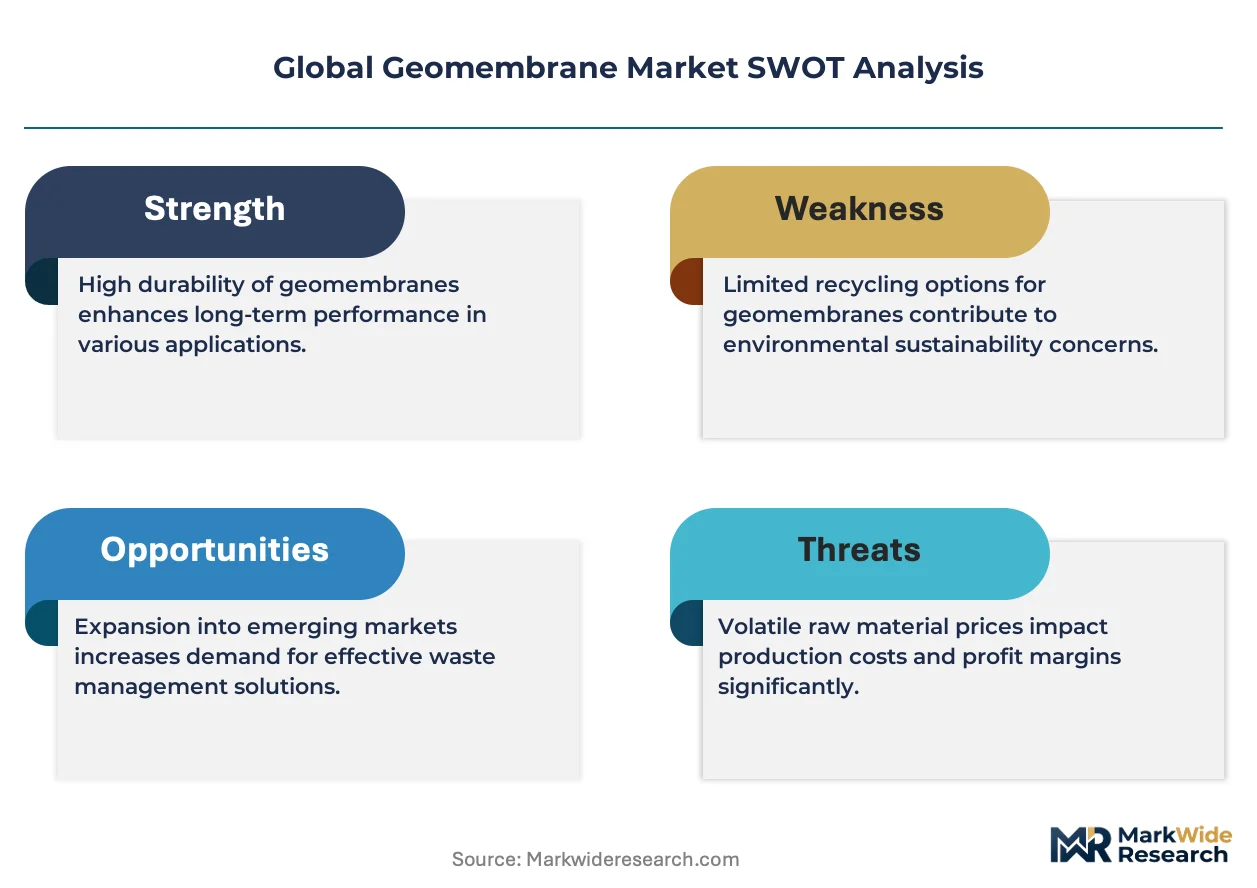
- HDPE resin price volatility:Feedstock costs tied to ethylene crackers concentrate margin pressure on extrusion-dependent producers.
- Fluorinated polymer restrictions:EU and US frameworks targeting per- and polyfluoroalkyl substances threaten qualification timelines for existing PVC and specialty liner portfolios.
- Steep-slope mining limitations:Textured HDPE grades face puncture resistance trade-offs that constrain deployment angles beyond 2.5:1 gradients.
Strategic Opportunities
- India's water infrastructure:Canal lining and reservoir projects under the Jal Jeevan Mission create specification openings for HDPE and LLDPE geomembrane suppliers.
- Geosynthetic system bundling:Turnkey containment combining geomembranes with geotextiles and drainage composites captures higher project value in European environmental remediation.
- Carbon capture sequestration:Saline aquifer containment and injection well pad lining emerges as a novel application requiring chemically resistant barrier systems.
Industry Challenges
- Welding technician certification:Thermal fusion seam integrity depends on scarce qualified installers, creating project timeline risk in remote mining locations.
- REACH compliance documentation:European resin formulation restrictions require extensive substance tracking that extends qualification cycles for new product grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Geomembrane Market |
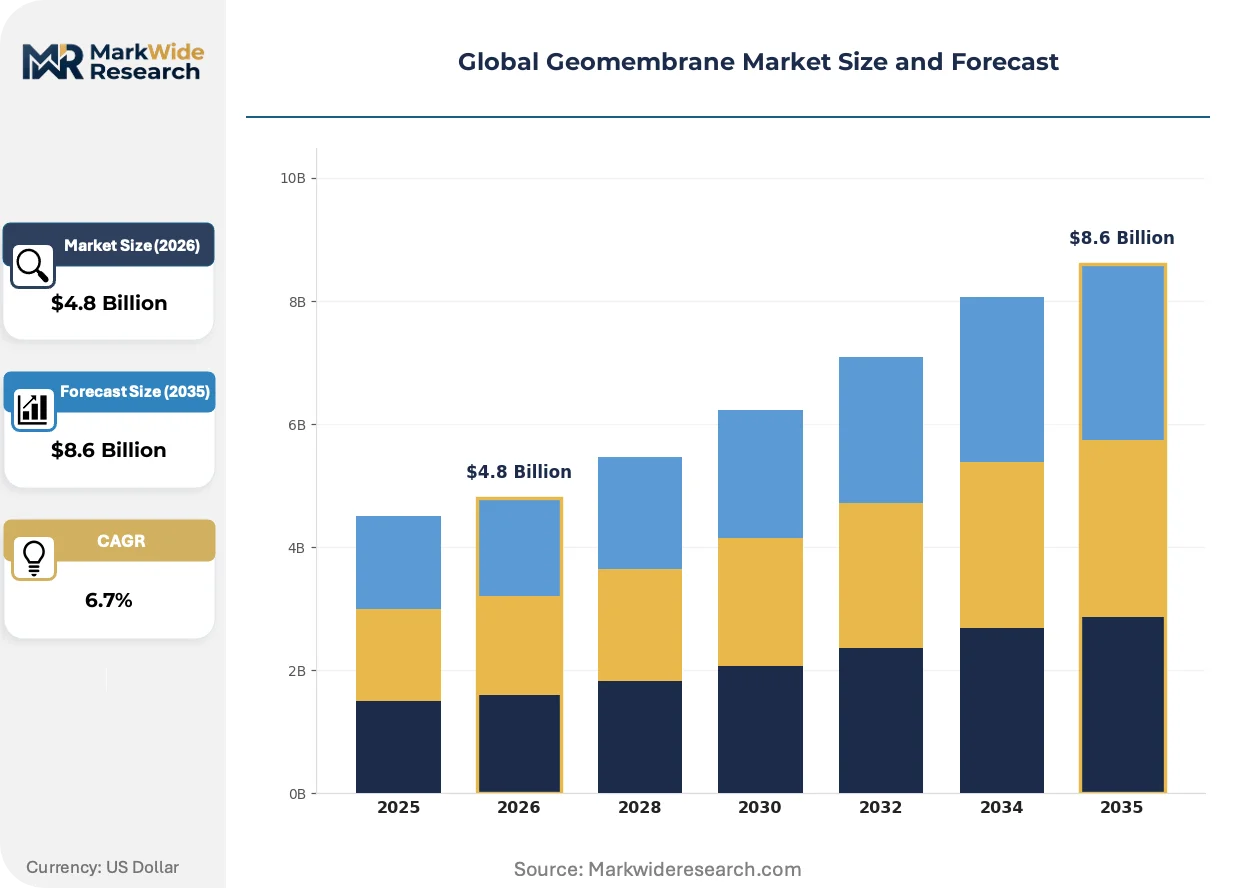
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Density Polyethylene, Low-Density Polyethylene, Polyvinyl Chloride, Ethylene Propylene Diene Monomer Application: Landfills, Mining, Water Management, Agriculture Installation Method: Glue Bonding, Thermal Welding, Mechanical Fastening, Injection End User: Construction, Environmental, Industrial, Civil Engineering |
| Companies Covered | Solmax, AGRU America, NAUE Group, Atarfil, Plastika Kritis, Raven Industries, Carlisle SynTec Systems, Maccaferri, Layfield Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Geomembrane Market Emerging Trajectories
Geomembrane specification is diverging between commodity landfill applications and engineered mining containment, creating parallel technology tracks with distinct performance thresholds and supplier qualification barriers.
Multi-layer co-extruded HDPE is fragmenting the traditional single-ply liner market by embedding conductive layers for electrical leak detection and enhanced puncture resistance. Mining operators in Chile and Peru specify these structures for heap leach pads exceeding 50-meter stacking heights. The technology is compressing price competition at the premium tier while leaving commodity landfill specifications exposed to resin-cost volatility.
REACH-compliant resin formulations are reshaping European material selection by restricting phthalate plasticizers in PVC geomembranes and mandating substance disclosure across the supply chain. German and French environmental contractors now prioritize HDPE and LLDPE alternatives to avoid registration delays. The shift is accelerating qualification investments among resin producers serving the geosynthetics sector.
Specification-driven procurement now dominates water management projects, where engineering consultants embed ISO 10318 test protocols directly into tender documents. Australia's irrigation authorities and coal seam gas operators require third-party seam peel and shear documentation before contract award. This behavior concentrates volume toward vertically integrated manufacturers with captive testing laboratories, marginalizing traders and re-sellers in high-specification segments.
Global Geomembrane Market Segmentation
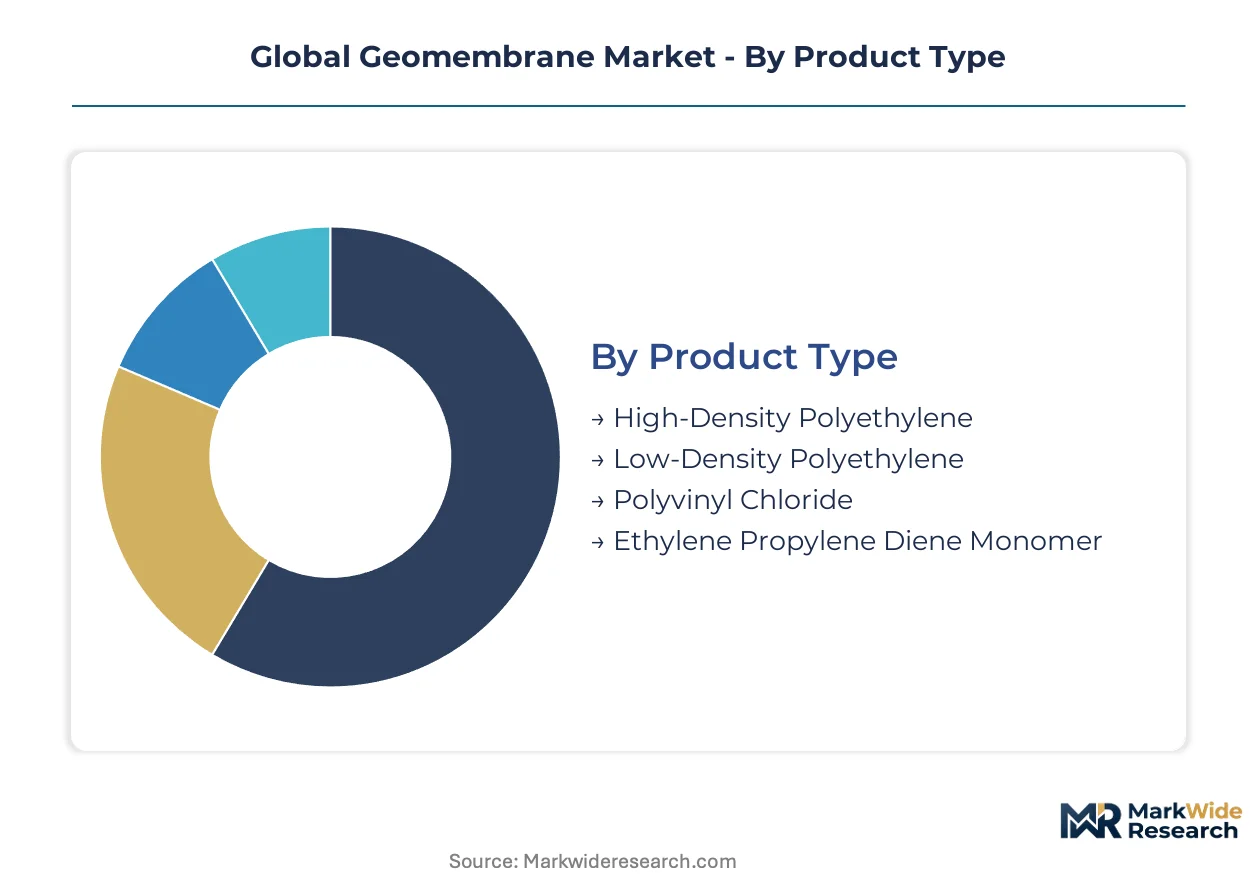
Geomembrane procurement decisions split across polymer chemistry, installation constraints, and project-scale requirements. Specification intensity varies sharply between commodity landfill liners and engineered mining containment, creating distinct margin tiers and supplier qualification barriers.
Product Type:
Substitution pressure concentrates on PVC formulations facing REACH-mandated plasticizer restrictions, while HDPE and LLDPE capture displaced volume.
- High-Density Polyethylene:Manufactured from linear ethylene polymers with density exceeding 0.941 g/cm³, delivering superior chemical resistance and thermal fusion weldability. Mining operators in Chile and Peru specify textured HDPE grades for heap leach pads exceeding 50-meter stacking heights, driven by copper extraction expansion and seam integrity requirements under extreme loading.
- Low-Density Polyethylene:Branched polymer structure with density below 0.925 g/cm³ provides conformability to uneven subgrades. Australia's irrigation districts and coal seam gas water storage projects specify LLDPE for reservoir lining where puncture resistance trade-offs are acceptable against installation speed on rough terrain.
- Polyvinyl Chloride:Flexible calendered sheets with embedded plasticizers face ECHA registration delays; German and French contractors now avoid PVC to circumvent substance disclosure burdens.
- Ethylene Propylene Diene Monomer:Synthetic rubber membranes serve specialized pond and floating cover applications requiring extreme elongation and ozone resistance.
High-Density Polyethylene retains volume leadership; Low-Density Polyethylene holds the steepest expansion curve.
Application:
Cost tier separation runs deepest between municipal landfill commodity specifications and engineered mining systems with third-party certification requirements.
- Landfills:EPA Subtitle D mandates composite liner systems with minimum thickness and hydraulic conductivity thresholds. German, French, and Italian facilities face EU Green Deal upgrade cycles forcing thicker specifications and composite barrier replacements.
- Mining:Heap leach pad liners in Chile and Peru require conductive-layer HDPE for electrical leak detection at extreme stacking heights; ISO 10318 seam documentation is embedded directly in tender protocols.
- Water Management:Canal lining and reservoir projects under India's Jal Jeevan Mission create specification openings for HDPE and LLDPE suppliers.
- Agriculture:Evaporation control ponds in water-scarce regions prioritize conformability over puncture resistance, favoring flexible polymer grades on irregular subgrades.
Landfills dominate installed base volume; Water Management is expanding most quickly as drought-prone regions invest in containment infrastructure.
Installation Method:
Customer type stratification separates qualified welding technicians from general construction labor, creating capability scarcity in remote mining locations.
- Thermal Welding:Hot wedge and extrusion techniques produce fusion-bonded seams with strength exceeding parent material; certification scarcity constrains project timelines in Chilean and Peruvian mining districts.
- Glue Bonding:Solvent and adhesive systems serve PVC and EPDM applications where thermal equipment access is limited; REACH compliance restricts adhesive formulations in European projects.
- Mechanical Fastening:Batten bar and anchor trench systems supplement welded seams on steep slopes exceeding 2.5:1 gradients where thermal equipment positioning is hazardous.
- Injection:Specialized grouting and injection techniques seal penetrations and pipe boot details in complex containment geometries.
Thermal Welding commands specification preference for critical containment; Glue Bonding faces steepest decline as REACH restrictions proliferate.
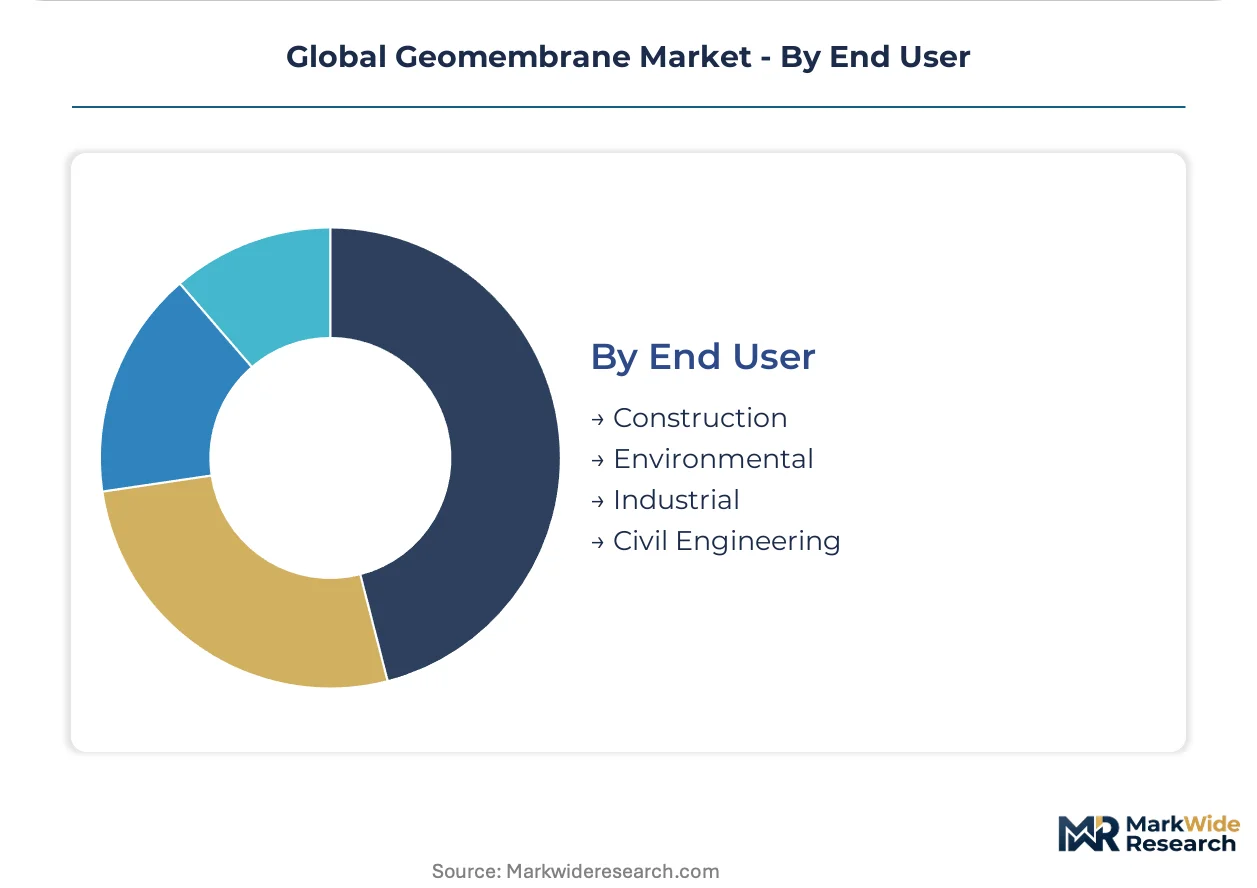
End User:
Supply concentration aligns with project scale and certification burden, concentrating procurement toward vertically integrated manufacturers in high-specification segments.
- Environmental:Remediation contractors in Germany and France bundle geomembranes with geotextiles and drainage composites for turnkey containment, capturing higher project value through system integration.
- Civil Engineering:Canal lining and reservoir authorities embed ISO 10318 test protocols directly in tender documents, requiring third-party seam documentation before contract award.
- Construction:General building applications represent price-sensitive volume where resin cost volatility transmits directly to margin pressure.
- Industrial:Carbon capture sequestration projects emerge as novel demand for saline aquifer containment and injection well pad lining with chemically resistant barrier specifications.
Environmental end users drive premium specification intensity; Civil Engineering posts the fastest share gains as water infrastructure investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mining operators and water infrastructure authorities drive procurement concentration across five national markets. Each geography presents distinct specification intensity, regulatory frameworks, and project-scale requirements.
United States
EPA Subtitle D landfill mandates sustain baseline demand for composite liner systems across municipal waste facilities. State-level environmental agencies in California and Texas enforce stricter hydraulic conductivity thresholds than federal minimums. The Permian Basin and Appalachian coal regions deploy geomembranes for produced water containment and coal ash remediation.
Germany
Remediation contractors bundle geomembranes with geotextiles for turnkey containment at brownfield industrial sites. ECHA REACH restrictions on phthalate plasticizers displace PVC formulations toward HDPE alternatives. The Ruhr industrial corridor and Bavarian chemical clusters specify ISO 10318-certified systems for groundwater protection projects.
Chile
Copper heap leach pad expansion at Escondida and Collahuasi mines drives specification intensity for textured HDPE with conductive leak detection layers. Mining regulators enforce seam documentation protocols under environmental impact assessments. The Atacama Desert mining district concentrates demand for extreme-stacking-height containment systems.
Australia
Irrigation authorities in New South Wales and Queensland specify HDPE geomembranes for canal lining and reservoir evaporation control. Coal seam gas operators in the Surat Basin require aquifer protection barriers under state petroleum regulations. The Murray-Darling Basin water recovery program funds large-scale lining infrastructure.
India
The Jal Jeevan Mission canal lining program creates specification openings for HDPE and LLDPE suppliers in water-scarce states. Central Public Health and Environmental Engineering Organisation standards mandate liner thickness for rural water storage. Gujarat and Maharashtra industrial corridors deploy geomembranes for effluent containment at chemical processing zones.
Global Geomembrane Market Vendor Landscape
Player mix skews toward integrated resin-to-liner manufacturers with captive testing laboratories and specialized textured-grade producers serving steep-slope mining applications. The vendor base separates into three archetypes: vertically integrated polymer producers controlling material consistency, regional fabricators competing on installation proximity, and system bundlers combining geomembranes with complementary geosynthetics. Dominant competitive moves include backward integration into resin production and qualification investments for ISO 10318 certification protocols.
Within the integrated-manufacturer tier, Solmax and AGRU America exemplify contrasting geographic anchoring strategies—North American and European production footprints versus specialized textured-grade engineering for mining containment. NAUE Group occupies a position among system bundlers that combine geomembranes with geotextiles and drainage composites. These three entities represent the competitive spectrum from material control through installation capability to turnkey project delivery.
| Leading Market Players |
|---|
| Solmax |
| AGRU America |
| NAUE Group |
| Atarfil |
| Plastika Kritis |
| Raven Industries |
| Carlisle SynTec Systems |
| Maccaferri |
| Layfield Group |
| Others |
Supply Flow & Price Mechanics
Extrusion capacity utilization above 85% at integrated North American and European facilities creates margin leverage for resin-to-liner manufacturers while compressing price floors for regional fabricators dependent on spot resin purchases. Scale concentration among qualified ISO 10318 producers enables premium tier pricing for mining containment specifications, whereas commodity landfill volumes transmit HDPE resin volatility directly to margin pressure.
Pricing Analysis
Cost-plus contracts indexed to ethylene cracker feedstock prices dominate procurement between mining operators and integrated manufacturers, insulating qualified suppliers from margin erosion while exposing regional fabricators to raw material swings. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10318-certified conductive-layer HDPE for Chilean heap leach pads from commodity single-ply liners for municipal landfills and price-sensitive agricultural pond applications. Pricing pressure stems from HDPE resin volatility concentrated at ethylene crackers, with mining operators least price-sensitive due to seam integrity requirements and irrigation authorities most sensitive due to public-budget constraints.
Supply Chain Analysis
China, Saudi Arabia, and the United States anchor global polyethylene resin production, with geosynthetics-grade HDPE drawing from petrochemical complexes serving construction and packaging downstream. Resin formulation, carbon black masterbatch, and conductive-layer co-extrusion equipment constitute critical input dependencies. Single-source vulnerability concentrates at specialized textured-grade extrusion lines serving steep-slope mining applications. Distribution runs through qualified welding technician networks and regional geosynthetics distributors, with project-scale procurement increasingly direct from integrated manufacturers for high-specification containment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geomembrane procurement is approaching a platform-economics inflection where ISO 10318 certification interoperability creates winner-take-most dynamics among qualified manufacturers, marginalizing non-certified suppliers across mining and water infrastructure tenders.
For Market Incumbents: Fortify backward integration into resin production to control formulation consistency and REACH compliance documentation, while expanding captive testing laboratory capacity to accelerate qualification cycles for emerging carbon capture sequestration specifications. Threat concentration resides in REACH-mandated plasticizer restrictions displacing PVC toward HDPE alternatives, favoring integrated producers with substance-tracking systems already deployed. For New Entrants and Emerging Players: Lead with India's Jal Jeevan Mission canal lining segment, where specification barriers remain lower than mining containment and procurement authority fragmentation creates entry openings for LLDPE specialists with installation speed advantages on rough terrain. Go-to-market positioning should emphasize turnkey bundling of geomembranes with geotextiles and drainage composites to capture higher project value in European environmental remediation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated manufacturers with long-term offtake agreements to mining operators in Chile and Peru, where heap leach pad expansion cycles extend contract visibility. Acquisition target archetype: mid-cap textured-grade specialists with ISO 10318 certification and established welding technician networks in remote mining districts. Signal to watch: ECHA acceleration of per- and polyfluoroalkyl substance restrictions disrupting PVC qualification timelines and accelerating HDPE displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive HDPE supply secures formulation control for REACH compliance and mining certification requirements. |
| ISO 10318 Certification Investment | Third-party seam documentation unlocks tender access for Chilean copper heap leach pad expansions. |
| Geosynthetic System Bundling | Turnkey containment combining geomembranes with drainage composites captures premium project value in Germany and France. |
| Conductive-Layer Co-Extrusion Capacity | Electrical leak detection capability differentiates suppliers for extreme stacking heights exceeding 50 meters. |
| Welding Technician Network Expansion | Qualified installer scarcity in Atacama Desert mining districts creates timeline risk and procurement concentration. |
Methodological Framework
The analysis maps polymer chemistry segments, installation method categories, and end-user archetypes, each validated through plant managers at extrusion facilities, procurement leads at mining operators, and engineering consultants specifying containment systems. Primary interview findings triangulate against secondary sources including EPA Subtitle D regulatory filings, ECHA REACH substance registration databases, and customs trade data for polyethylene resin flows. Bottom-up project pipeline assessment across Chilean mining districts, Australian irrigation authorities, and Indian water infrastructure programs reconciles with top-down polymer consumption estimates.
Consistency checks validated volume and value outputs against external benchmarks from national geosynthetics associations and petrochemical industry reports. Segmentation dimensions modeled include polymer density tier, application criticality, certification grade, and regional regulatory framework. CAGRs derive from project-level procurement timelines and resin capacity expansion schedules. Industry-specific inputs incorporate copper extraction forecasts for heap leach pad sizing and EU Green Deal landfill directive implementation calendars.
Forecasts assume regulatory continuity in EPA, ECHA, and ISO certification regimes; material policy shifts such as accelerated fluorinated polymer restrictions or modified seam documentation requirements would necessitate re-modeling. Recalibration cycles align with material shifts in mining investment cycles, water infrastructure appropriations, and REACH substance restriction timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Global Transfer Membrane Market
Membrane Materials
Global Membrane Technology Market
Membrane Materials
Nanoporous Membranes Market
Membrane Materials
North America Single-Ply Membrane Market
Membrane Materials
Global Gas Separation Membranes Market
Membrane Materials
Global Membrane Chromatography Market
Membrane Materials
Global Membrane Water and Wastewater Treatment Market
Membrane Materials
Hollow Fibers Membrane Market
Membrane Materials
Reverse Osmosis (RO) Membrane Market
Membrane Materials
Membrane Filter Cartridge Market
Membrane Materials
Fuel Cell Gas Diffusion Layer Market
Membrane Materials
Global Waterproofing Membrane Market
Membrane Materials
Bitumen Waterproofing Membrane Market
Membrane Materials
Reverse Osmosis Films Market
Membrane Materials
Membrane Polymers Market
Membrane Materials
Global Microfiltration Membranes Market