
 Global Membrane Separation Technology Market | 2026-2036
Global Membrane Separation Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Membrane Separation Technology Market Analysis
Buyer concentration across municipal water utilities is broadening as smaller municipalities in Southeast Asia and sub-Saharan Africa deploy decentralized membrane systems. DuPont leverages its fluoropolymer chemistry leadership to dominate high-pressure reverse osmosis module supply. Toray Industries anchors Asian demand through integrated hollow-fiber manufacturing. Koch Membrane Systems competes in industrial wastewater with specialized spiral-wound configurations.
Membrane separation technology employs semi-permeable barriers with pore sizes ranging from 0.1 microns in microfiltration to sub-nanometer dimensions in reverse osmosis, fabricated from polyamide thin-film composites, ceramic alumina, or polysulfone substrates to selectively separate solutes, particles, and solvents under pressure-driven or concentration-gradient operation. Reverse osmosis leads installed capacity for seawater desalination while membrane bioreactors represent the fastest-growing technology segment as wastewater treatment plants retrofit for nutrient removal and water reuse. Polymer membranes occupy the largest share of unit shipments though ceramic membranes command premium pricing in high-temperature chemical processing applications.
The EPA's Clean Water Act enforcement and the EU Water Framework Directive tighten effluent discharge limits, compelling industrial facilities to upgrade from conventional clarification to membrane-based treatment. China's MEE enforces stricter wastewater reuse quotas for heavy industry in the Yangtze River basin. India's CPCB mandates zero-liquid-discharge compliance for textile clusters in Tamil Nadu. Stakeholders must monitor regulatory divergence between jurisdictions as membrane specification requirements fragment across export markets.
Market Dynamics
Reverse osmosis membrane suppliers face intensifying specification pressure as municipal utilities in water-stressed regions mandate stricter contaminant rejection thresholds while industrial buyers demand longer module lifespans under aggressive chemical cleaning protocols.
Growth Catalysts
- EU Green Deal water reuse mandates:Industrial facilities across Germany, France, and Spain must retrofit effluent treatment to achieve 90% reuse rates, forcing adoption of membrane bioreactor systems.
- Seawater desalination expansion:Saudi Arabia, UAE, and Chile are commissioning gigawatt-scale desalination plants that specify high-flux polyamide thin-film composite modules.
- Pharmaceutical purity requirements:Injectable drug manufacturers in India and Ireland now require ultrafiltration for endotoxin removal, creating dedicated membrane procurement channels.
Market Restraints
- Fluoropolymer feedstock concentration:PTFE and PVDF resin supply concentrates among Japanese and Chinese chemical conglomerates, exposing membrane fabricators to price volatility and allocation constraints.
- Energy intensity of high-pressure operation:Reverse osmosis systems for seawater desalination consume 3-4 kWh per cubic meter, limiting deployment where electricity costs exceed renewable parity thresholds.
- Fouling-induced performance degradation:Organic and biological fouling in wastewater applications necessitates frequent chemical cleaning, compressing effective membrane lifespan below theoretical ratings.
Strategic Opportunities
- Decentralized rural water systems:Sub-Saharan African municipalities lack centralized infrastructure, creating demand for containerized ultrafiltration units with solar-powered pumping.
- Zero-liquid-discharge mandates:India's CPCB enforcement in Tamil Nadu textile clusters requires crystallizer-integrated membrane trains, opening specialized system integration contracts.
- Ceramic-polymer hybrid architectures:Alumina-coated polymeric substrates combine chemical resistance with mechanical flexibility, targeting high-temperature food processing applications.
Industry Challenges
- Membrane characterization expertise shortage:Accurate pore size distribution measurement and fouling mechanism diagnosis require specialized analytical chemists, with training programs lagging installation growth.
- Legacy control system integration:Municipal utilities operating SCADA platforms from the 1990s face protocol incompatibility with modern membrane skid telemetry, necessitating costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Membrane Separation Technology Market |
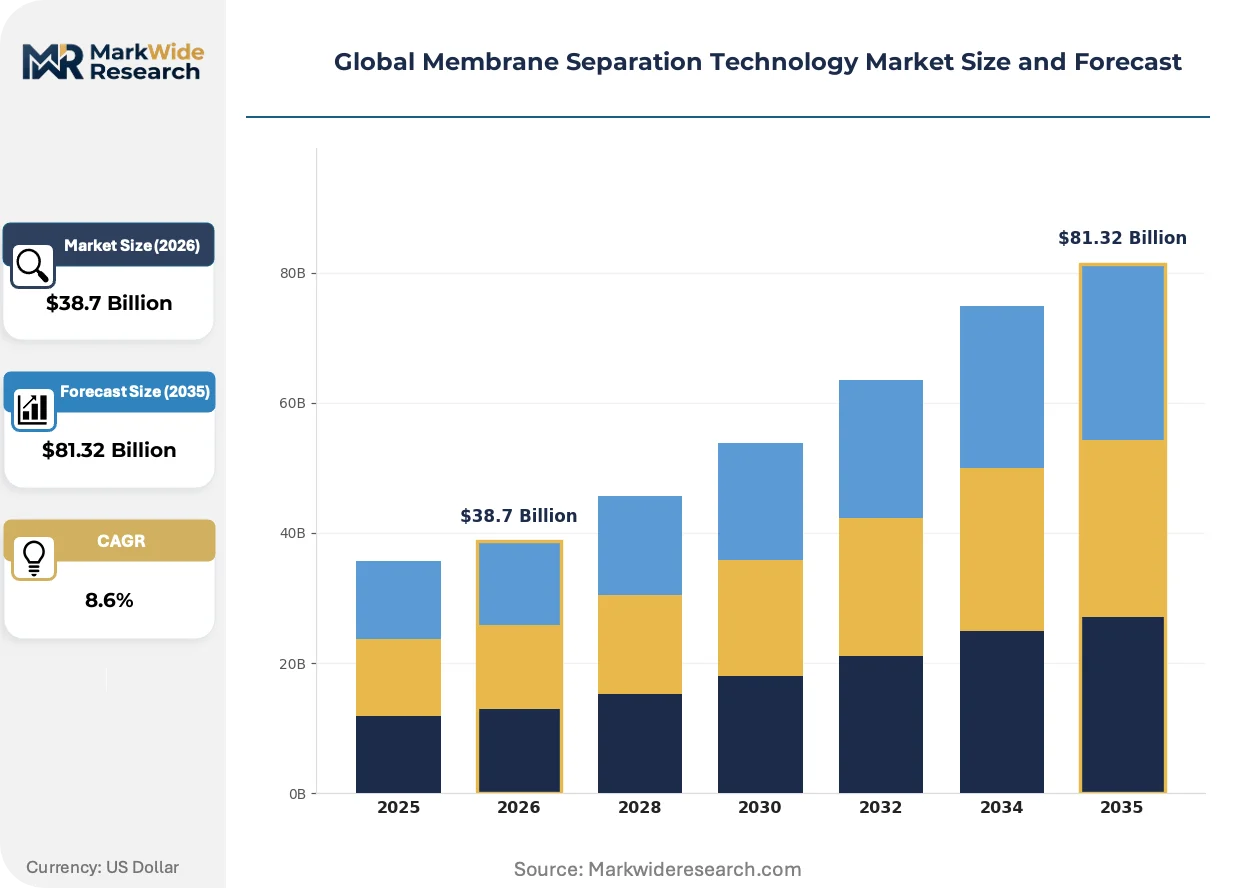
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfiltration, Ultrafiltration, Nanofiltration, Reverse Osmosis End User: Water Treatment, Food & Beverage, Pharmaceuticals, Chemicals Technology: Ceramic Membranes, Polymer Membranes, Composite Membranes, Membrane Bioreactors Application: Desalination, Wastewater Treatment, Juice Clarification, Dye Recovery |
| Companies Covered | 3M, Nitto Denko Corporation, DuPont, Koch Membrane Systems, Veolia Water Technologies, Toray Industries, Pall Corporation, GEA Group Aktiengesellschaft, Asahi Kasei Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Membrane Separation Technology Market Emerging Trajectories
Membrane technology evolution centers on material science breakthroughs that simultaneously reduce energy demand and extend operational lifespan, while regulatory frameworks in major economies increasingly embed membrane performance into compliance architectures.
Graphene oxide laminates are expanding into nanofiltration applications for selective ion separation. Water utilities in Singapore and Israel pilot these two-dimensional materials for brackish water softening without chemical pretreatment. The structural consequence is a compression of conventional polyamide market share in monovalent-selective segments.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of hydrophobic membrane coatings across European manufacturing. Industrial membrane buyers now face supplier qualification timelines extending 18-24 months as alternative surface chemistries undergo validation. The food and beverage segment is responding fastest, with dairy processors in the Netherlands and Denmark already specifying PFAS-free module certifications.
Performance-based service contracting is displacing capital purchase models for large municipal installations. French and Australian water utilities now contract membrane availability rather than owning assets, transferring fouling risk and replacement liability to OEM service arms. This restructuring concentrates in desalination and water reuse projects exceeding 50,000 cubic meters daily capacity.
Global Membrane Separation Technology Market Segmentation
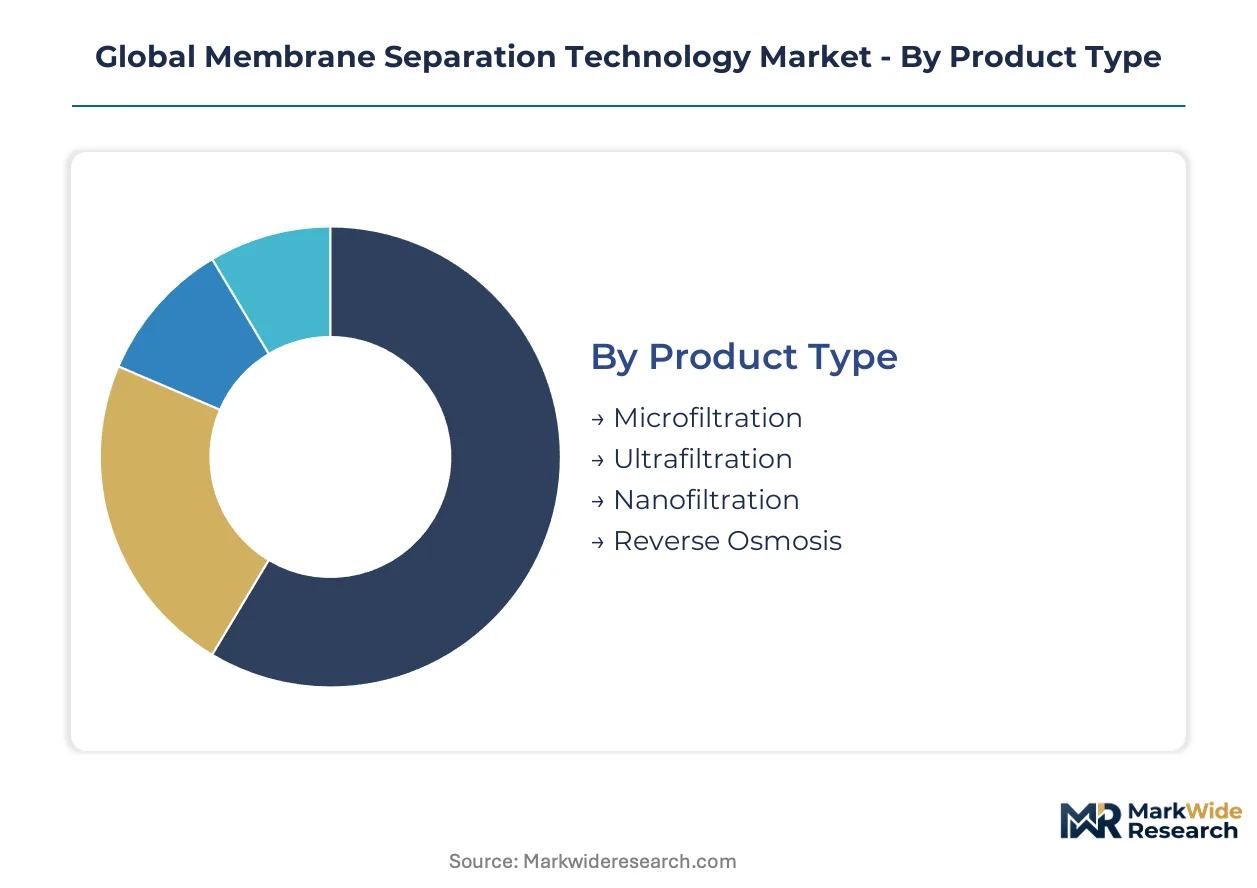
Membrane separation technology spans divergent performance requirements across pressure ratings, pore architectures, and chemical compatibility matrices. Buyers select specifications based on feedwater chemistry, target contaminant profiles, and cleaning protocol intensity rather than standardized product tiers.
Product Type:
Customization intensity decreases as pore size shrinks, with reverse osmosis modules exhibiting the most standardized specifications while microfiltration retains broader format variability.
- Microfiltration:Pore sizes ranging from 0.1 to 10 microns remove suspended solids and bacteria through low-pressure operation. Demand clusters in dairy processing facilities across the Netherlands and New Zealand for milk fat standardization and bacterial stabilization. Fouling tolerance from hollow-fiber geometries reduces cleaning frequency in high-solids feed streams.
- Reverse Osmosis:Sub-nanometer dense polyamide layers reject dissolved salts and small organics under 15-85 bar operating pressure. Saudi Arabia's Saline Water Conversion Corporation and Chile's Aguas de Antofagasta specify high-flux thin-film composite modules for seawater and brackish feedwaters. Energy recovery device integration has reduced specific consumption below 3 kWh per cubic meter in new installations.
- Ultrafiltration:0.01-0.1 micron pores retain macromolecules, viruses, and colloids for drinking water and process stream purification.
- Nanofiltration:Divalent ion selectivity enables water softening and small organic removal without full desalination energy burden.
Leading the category by volume: Reverse Osmosis. Expanding most quickly: Ultrafiltration.
End User:
Volume concentration tracks regulatory enforcement intensity, with water treatment commanding unit shipments while pharmaceuticals extract premium pricing through validation requirements.
- Water Treatment:Municipal utilities and industrial facilities deploy membrane trains for potable production, wastewater polishing, and reuse compliance. Southeast Asian cities including Jakarta and Ho Chi Minh City are expanding ultrafiltration capacity for surface water clarification. The EU Water Framework Directive tightens nutrient discharge limits, forcing membrane bioreactor adoption for biological nutrient removal.
- Pharmaceuticals:Injectable drug manufacturing requires endotoxin-retentive ultrafiltration and virus filtration per FDA and EMA guidelines. Hyderabad and Ahmedabad corridors in India concentrate sterile filtration demand as CDMO capacity expands. Validation documentation and extractables testing extend procurement cycles to 12-18 months.
- Food & Beverage:Dairy, juice, and wine processors leverage membrane clarification for shelf-life extension and quality consistency.
- Chemicals:Solvent recovery and catalyst separation applications favor ceramic membranes for thermal and chemical resistance.
Water Treatment dominates shipment volume. Pharmaceuticals generates highest margin per square meter of membrane area.
Technology:
Material selection pivots on chemical compatibility versus mechanical flexibility tradeoffs, with polymer platforms serving volume markets and ceramics capturing harsh-duty niches.
- Polymer Membranes:Polyamide thin-film composites, polysulfone, and PVDF substrates dominate unit economics through solution-phase fabrication scalability. Spiral-wound and hollow-fiber configurations serve desalination and ultrafiltration respectively. REACH restrictions on PFAS surface treatments are forcing European suppliers to reformulate hydrophobic coatings with 18-24 month requalification timelines.
- Membrane Bioreactors:Immersed or sidestream configurations combine biological treatment with membrane solids separation for compact footprint and high-quality effluent. Germany's Erftverband and Australia's Melbourne Water have adopted MBR technology for water reuse schemes. The segment benefits from EU Green Deal mandates requiring 90% industrial effluent reuse rates.
- Ceramic Membranes:Alumina, titania, and zirconia structures withstand aggressive cleaning chemistries and elevated temperatures.
- Composite Membranes:Ceramic-coated polymers or mixed-matrix materials target intermediate performance requirements.
Polymer Membranes lead installed base. Membrane Bioreactors are climbing the fastest as wastewater treatment plants retrofit for nutrient removal.
Application:
Application selection correlates with feedwater salinity and product recovery requirements, with desalination representing capital-intensive anchor demand and dye recovery emerging from regulatory pressure.
- Desalination:Seawater and brackish water reverse osmosis plants supply municipal and industrial freshwater in water-stressed regions. Saudi Arabia's Ras Al-Khair and UAE's Taweelah facilities operate at gigawatt-scale energy integration. Chilean mining corridors around Antofagasta deploy desalination for copper processing water supply.
- Wastewater Treatment:Membrane bioreactors and tertiary filtration enable direct potable reuse and industrial recycling. India's CPCB zero-liquid-discharge mandates for Tamil Nadu textile clusters require crystallizer-integrated membrane trains. Singapore's NEWater facilities demonstrate advanced reuse for indirect potable supplementation.
- Juice Clarification:Ultrafiltration replaces enzyme treatment and fining agents for natural cloud stability.
- Dye Recovery:Nanofiltration concentrates textile dyes for reuse while reducing effluent color loading.
Desalination anchors capital deployment. Wastewater Treatment is gaining share fastest as reuse regulations proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for membrane separation technology concentrates in water-stressed economies with aggressive regulatory mandates. Saudi Arabia, China, Germany, India, and the United States collectively anchor procurement volume across desalination, industrial reuse, and pharmaceutical purity applications.
Saudi Arabia
Seawater desalination drives procurement as the Saline Water Conversion Corporation expands Ras Al-Khair and Jubail facilities. The country's National Water Strategy mandates 70% desalinated water supply by 2030. NEOM's northwest development specifies membrane-integrated water recycling for its linear city infrastructure.
China
Industrial wastewater reuse quotas tighten across the Yangtze River basin manufacturing corridors. The MEE enforces stricter discharge standards for heavy industry, compelling membrane bioreactor retrofits. Zhejiang and Jiangsu provinces concentrate textile and chemical processing facilities upgrading to zero-liquid-discharge configurations.
Germany
The EU Green Deal's 90% industrial effluent reuse mandate reshapes Rhineland chemical complexes. Erftverband operates Europe's largest membrane bioreactor installation for municipal water reuse. Bavarian dairy processors deploy ultrafiltration for whey protein concentration under EFSA hygiene standards.
India
Pharmaceutical manufacturing corridors around Hyderabad and Ahmedabad generate sterile filtration demand for injectable drug exports. The CPCB's zero-liquid-discharge enforcement in Tamil Nadu textile clusters requires crystallizer-integrated membrane trains. Gujarat's Dahej petrochemical zone specifies high-temperature ceramic membranes for solvent recovery.
United States
EPA Clean Water Act enforcement tightens nutrient discharge limits for municipal utilities. California's Orange County Water District operates the world's largest indirect potable reuse facility using microfiltration-reverse osmosis trains. Texas oilfield operators deploy ceramic membranes for produced water treatment under Railroad Commission guidelines.
Global Membrane Separation Technology Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue ceramic-polymer hybrid architectures and decentralized system integration. The market exhibits moderate consolidation among fluoropolymer chemistry leaders and hollow-fiber manufacturers, with fragmentation in specialized wastewater configurations. Three archetypes dominate: integrated chemical conglomerates with captive resin supply, dedicated membrane fabricators with format-specific expertise, and water treatment OEMs bundling membranes into turnkey systems. Competitive moves center on backward integration into fluoropolymer resin production and geographic expansion through local manufacturing joint ventures.
Among Japanese chemical conglomerates, Toray Industries and Asahi Kasei Corporation anchor Asian demand through integrated manufacturing positions. DuPont represents the fluoropolymer chemistry leadership tier in high-pressure reverse osmosis supply. Koch Membrane Systems occupies a specialized position in industrial wastewater configurations with spiral-wound expertise. These three exemplify how material science control, regional manufacturing integration, and application-specific engineering respectively define competitive positioning in this market.
| Leading Market Players |
|---|
| 3M |
| Nitto Denko Corporation |
| DuPont |
| Koch Membrane Systems |
| Veolia Water Technologies |
| Toray Industries |
| Pall Corporation |
| GEA Group Aktiengesellschaft |
| Asahi Kasei Corporation |
| Others |
Supply Flow & Price Mechanics
Performance-grade bifurcation between pharmaceutical-validated ultrafiltration modules and commodity municipal reverse osmosis units manifests in both pricing spreads and supply chain architectures, with EU REACH compliance timelines and fluoropolymer resin allocation constraints tightening the premium tier while standardized spiral-wound configurations face cost compression from Chinese hollow-fiber imports.
Pricing Analysis
Volume-margin splits separate thin-film composite desalination modules shipped at scale to Saudi Arabia's Saline Water Conversion Corporation from endotoxin-retentive ultrafiltration skids procured by Hyderabad pharmaceutical corridors. Three-tier pricing structure across premium, standard, and economy levels tracks validation documentation intensity, with FDA 510(k) clearance extending procurement cycles and inflating unit economics. Cost compression in standardized reverse osmosis spirals is intensifying because Chinese manufacturers are expanding PVDF hollow-fiber capacity. Municipal utilities in Southeast Asia exhibit highest price sensitivity, while Irish injectable drug manufacturers absorb premiums for extractables-tested configurations.
Supply Chain Analysis
REACH and FDA qualification gating stretches supplier onboarding to 18-24 months, concentrating approved membrane fabricator relationships among incumbents with established validation dossiers. Fluoropolymer resin production centers on Japan and China, with Asahi Kasei and Dongyue Group anchoring PTFE and PVDF supply. Polyamide thin-film chemistry draws from German and American specialty chemical houses, while ceramic alumina substrates source from French and Japanese precision ceramics manufacturers. Single-source vulnerability runs through Japanese fluoropolymer feedstock given concentration among two chemical conglomerates. Distribution runs through water treatment OEMs bundling membranes into turnkey skids, with direct procurement limited to pharmaceutical and food-grade validated buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluoropolymer resin concentration among Japanese chemical conglomerates props pricing power for validated membrane tiers, with capacity expansion timelines lagging demand acceleration from EU Green Deal reuse mandates and India's zero-liquid-discharge enforcement.
For Market Incumbents: Hedge fluoropolymer exposure through backward integration into PVDF resin production or long-term offtake agreements with Asahi Kasei and Kureha. Deepen captive supply of polyamide thin-film chemistry to defend margin position against Chinese hollow-fiber entrants targeting standardized desalination modules. Prioritize certification investment for REACH-compliant PFAS-free surface treatments ahead of European dairy processor procurement shifts. For New Entrants and Emerging Players: Regional water utility consortia in sub-Saharan Africa represent the most penetrable channel, given absence of centralized infrastructure and demand for containerized solar-powered ultrafiltration units. Target Tamil Nadu textile clusters requiring crystallizer-integrated membrane trains under CPCB zero-liquid-discharge mandates, where system integration capabilities outweigh brand recognition. Pursue ceramic-polymer hybrid architectures for high-temperature food processing applications as a differentiation angle against established polymer membrane suppliers. For Investors and Strategic Acquirers: Re-rating potential sits with specialized wastewater configuration fabricators given membrane bioreactor retrofit acceleration across EU industrial corridors and China's Yangtze River basin. Long-term viability favors suppliers with in-house fluoropolymer chemistry and validated pharmaceutical-grade production lines. Watch for MEE enforcement intensity in Zhejiang and Jiangsu provinces as inflection indicator for Chinese domestic demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Resin | Captive PTFE and PVDF supply secures allocation priority during Japanese chemical conglomerate capacity constraints. |
| REACH-Compliant PFAS-Free Coating Development | Netherlands and Denmark dairy processors already specify certified modules, compressing qualification timelines for laggards. |
| Containerized Rural System Deployment | Sub-Saharan African municipalities lack centralized infrastructure, creating first-mover advantage for solar-integrated ultrafiltration. |
| Ceramic-Polymer Hybrid Architecture Launch | Alumina-coated substrates target high-temperature food processing gaps left by pure polymer and pure ceramic alternatives. |
| Performance-Based Service Contracting | French and Australian utilities now contract membrane availability rather than capital purchase, transferring fouling risk to OEMs. |
Methodological Framework
Multi-period observation of membrane installation data, regulatory enforcement intensity, and fluoropolymer resin pricing anchored the trend analysis, supplemented by interviews with municipal utility procurement directors, pharmaceutical manufacturing engineers, water treatment OEM technical sales leads, and ceramic membrane R&D heads. Secondary validation drew from EPA Clean Water Act enforcement records, EU Water Framework Directive implementation reports, China MEE discharge standard filings, and India CPCB zero-liquid-discharge compliance data. Bottom-up membrane unit shipment tallies triangulated against top-down capital expenditure tracking across desalination and wastewater reuse projects.
Input-output matrices modeled membrane demand across technology type, end-use industry, application, and regional regulatory cluster, with value outputs derived from module pricing spreads and system integration margins. CAGRs were computed from geometric progression of annual installation forecasts, incorporating energy recovery device penetration rates for desalination and membrane bioreactor retrofit ratios for wastewater treatment. Forecast inputs included Saudi Arabia's National Water Strategy capacity targets, EU Green Deal reuse mandate implementation timelines, and India's pharmaceutical corridor expansion plans.
Caveats apply where fluoropolymer feedstock allocation disruptions, REACH restriction scope expansions, or MEE enforcement intensity shifts could materially shift the outlook. Model refresh is warranted upon material change in Japanese chemical conglomerate capacity expansion announcements or EU PFAS regulatory finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Breather Membranes Market
Membrane Materials
Polyvinyl Chloride Membranes Market
Membrane Materials
North America Roofing Membranes Market
Membrane Materials
Global Membrane Chromatography Market
Membrane Materials
Bitumen Waterproofing Membrane Market
Membrane Materials
PTFE Membrane Market
Membrane Materials
Global Track Etched Membrane Market
Membrane Materials
Geosynthetic Clay Liner Market
Membrane Materials
Membrane Filter Cartridge Market
Membrane Materials
Gas Barrier Membranes Market
Membrane Materials
Membrane Separation Materials Market
Membrane Materials
Polysulfone Market
Membrane Materials
Polytetrafluoroethylene (PTFE) Filter Membranes Market
Membrane Materials
Membrane Touch Switch Material Market
Membrane Materials
Polyvinyl Butyral (PVB) Films and Sheets Market
Membrane Materials
US Commercial Restoration Waterproofing Membranes Market