
 Geosynthetic Clay Liner Market | 2026-2036
Geosynthetic Clay Liner Market Size, Share, and Industry Trends Forecast 2026-2036
Geosynthetic Clay Liner Market Analysis
Geomembrane-composite specification tiers is reorganizing procurement patterns across the geosynthetic clay liner industry. Solmax leverages its integrated polyethylene resin-to-liner production chain to control raw material quality from source to finished membrane. CETCO anchors the sodium bentonite supply layer through captive mining operations in Wyoming that feed its liner manufacturing. Naue GmbH & Co. KG differentiates through geosynthetic design engineering that pairs clay liners with geotextile drainage composites for European containment projects.
A geosynthetic clay liner is a factory-manufactured hydraulic barrier consisting of sodium bentonite clay encased between geotextiles or bonded to a geomembrane, typically achieving permeability coefficients below 5×10⁻⁹ cm/sec for containment applications. The product serves as a low-permeability substitute for compacted clay in environmental containment systems where natural soils fail to meet regulatory hydraulic conductivity thresholds. Polymer-coated variants command premium positioning in aggressive chemical environments such as mining heap leach pads where liner integrity faces prolonged solvent exposure. Sodium bentonite-based configurations dominate landfill applications where cost-sensitive municipal buyers prioritize proven hydration-swelling performance over advanced chemical resistance. Composite product structures capture expanding share in wastewater treatment lagoon upgrades where operators seek dual hydraulic and mechanical protection.
The EPA enforces Subtitle D liner performance standards that mandate minimum 30-mil geomembrane overlays or equivalent composite systems for municipal solid waste units, directly specifying geosynthetic clay liner inclusion in alternative designs. ISO 10318 provides international terminology and classification frameworks that harmonize cross-border procurement specifications for bentonite-based barrier materials. ASTM D5887 and D5890 test protocols govern hydraulic conductivity and fluid compatibility validation, creating compliance gateways that filter out unqualified suppliers. Stakeholders must track evolving state-level landfill closure mandates and mining tailings dam integrity regulations to anticipate replacement cycle timing and specification escalation pathways.
Market Dynamics
Geomembrane-composite specification tiers is reorganizing procurement patterns across the geosynthetic clay liner industry, forcing sodium bentonite suppliers and liner fabricators to align production capabilities with tiered hydraulic performance standards rather than commodity pricing.
Growth Catalysts
- EPA Subtitle D mandates:Municipal solid waste landfill operators in the United States must install composite liner systems, creating baseline demand for geosynthetic clay liners as the bentonite layer in approved alternative designs.
- Mining tailings containment:Heap leach pad operators in Chile and Peru specify polymer-coated variants for solvent resistance, expanding the addressable market beyond traditional landfill applications.
- Aging infrastructure replacement:Closure mandates for unlined legacy landfills in Germany and France trigger upgrade cycles where compacted clay fails to meet modern hydraulic conductivity thresholds.
Market Restraints
- Sodium bentonite supply concentration:Wyoming deposits control over 70% of global high-swelling clay feedstock, exposing liner manufacturers to single-source geological risk and freight cost volatility.
- Geomembrane price sensitivity:HDPE resin fluctuations directly compress margins for composite product fabricators who cannot pass through raw material swings to municipal procurement offices.
- Compacted clay substitution:Site-specific geotechnical conditions in Scandinavia and the UK allow engineered natural clay to satisfy regulatory requirements at lower installed cost in certain containment applications.
Strategic Opportunities
- Carbon capture sequestration wells:Injection facility operators in Texas and Alberta evaluate bentonite-based annular seals for CO2 containment, opening an entirely new end-use vertical with stringent permeability requirements.
- EU Green Deal funding streams:Circular economy construction grants in Italy and Spain subsidize geosynthetic barrier adoption in brownfield remediation projects that previously relied on imported compacted clay.
- Digital specification platforms:Engineering procurement networks in the Netherlands now integrate ASTM D5887 test data directly into bidding workflows, reducing qualification friction for certified suppliers.
Industry Challenges
- Geosynthetic installation certification gaps:Field seaming and overlap verification for composite systems requires CQA-trained technicians that remain scarce outside established North American and Western European markets.
- Multi-standard compliance burdens:Suppliers serving both EPA-regulated US landfills and ECHA-monitored European hazardous waste facilities must maintain parallel testing protocols under ASTM and EN ISO frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geosynthetic Clay Liner Market |
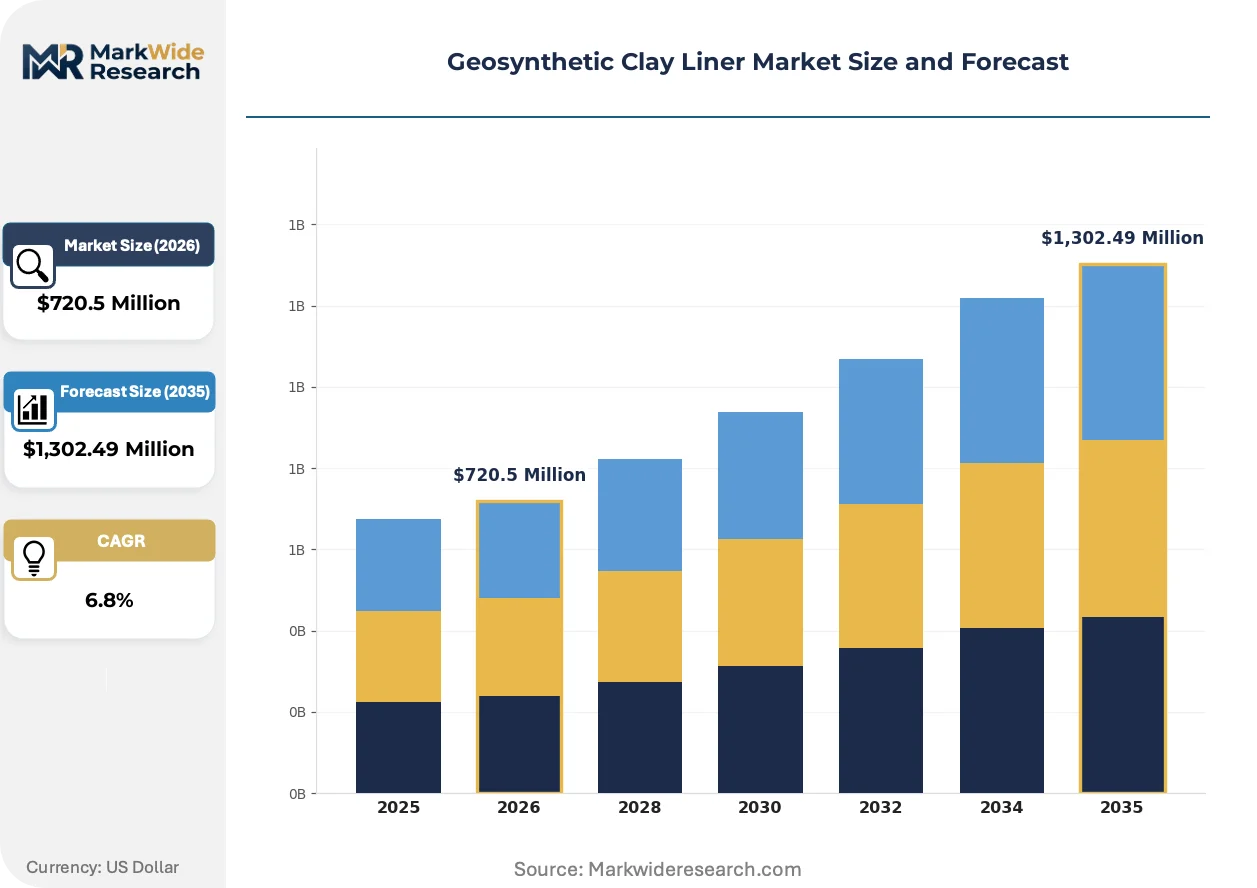
| Market Size in 2026 | $720.5 Million |
| Market Size in 2035 | $1,302.49 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer-Coated, Non-Woven, Composite, Sodium Bentonite Application: Landfills, Mining, Wastewater Treatment, Hydraulic Structures End User: Municipalities, Construction Companies, Environmental Agencies, Agriculture Installation Type: On-site, Pre-Manufactured, Modular, Custom Solutions |
| Companies Covered | Solmax, Minerals Technologies Inc., CETCO, Naue GmbH & Co. KG, HUESKER Synthetic GmbH, Terrafix Geosynthetics Inc., GSE Environmental, Geofabrics Australasia Pty Ltd., Global Synthetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geosynthetic Clay Liner Market Emerging Trajectories
Material science advances and regulatory digitization are compressing product development cycles while fragmenting the traditional specification hierarchy that once separated landfill, mining, and wastewater applications into distinct procurement silos.
Polymer-modified bentonite formulations is decomposing the historical performance gap between standard sodium-based liners and exotic geomembrane composites. Mining operators in Nevada and Arizona now specify these intermediate-grade products for intermediate chemical exposure profiles, collapsing the three-tier specification structure into a more continuous performance spectrum. The shift enables mid-tier fabricators to capture contracts previously reserved for integrated resin-to-liner producers.
REACH chemical registration requirements in the European Union now mandate full supply chain disclosure for polymer additives used in coated liner variants. German and French environmental agencies have begun rejecting bids that lack ECHA-compliant safety data sheets, forcing reformulation of legacy products. The regulatory pressure concentrates most intensely on mining applications where polymeric binders face prolonged solvent contact.
Consolidated municipal procurement consortia in California, Texas, and Ohio now negotiate multi-year framework agreements that bundle geosynthetic clay liner supply with installation and post-closure monitoring services. The bundled model displaces traditional bid-item contracting where liner fabricators competed separately from civil contractors. California's regional waste authorities pioneered this structure, and neighboring states are adopting similar consolidated tender formats.
Geosynthetic Clay Liner Market Segmentation
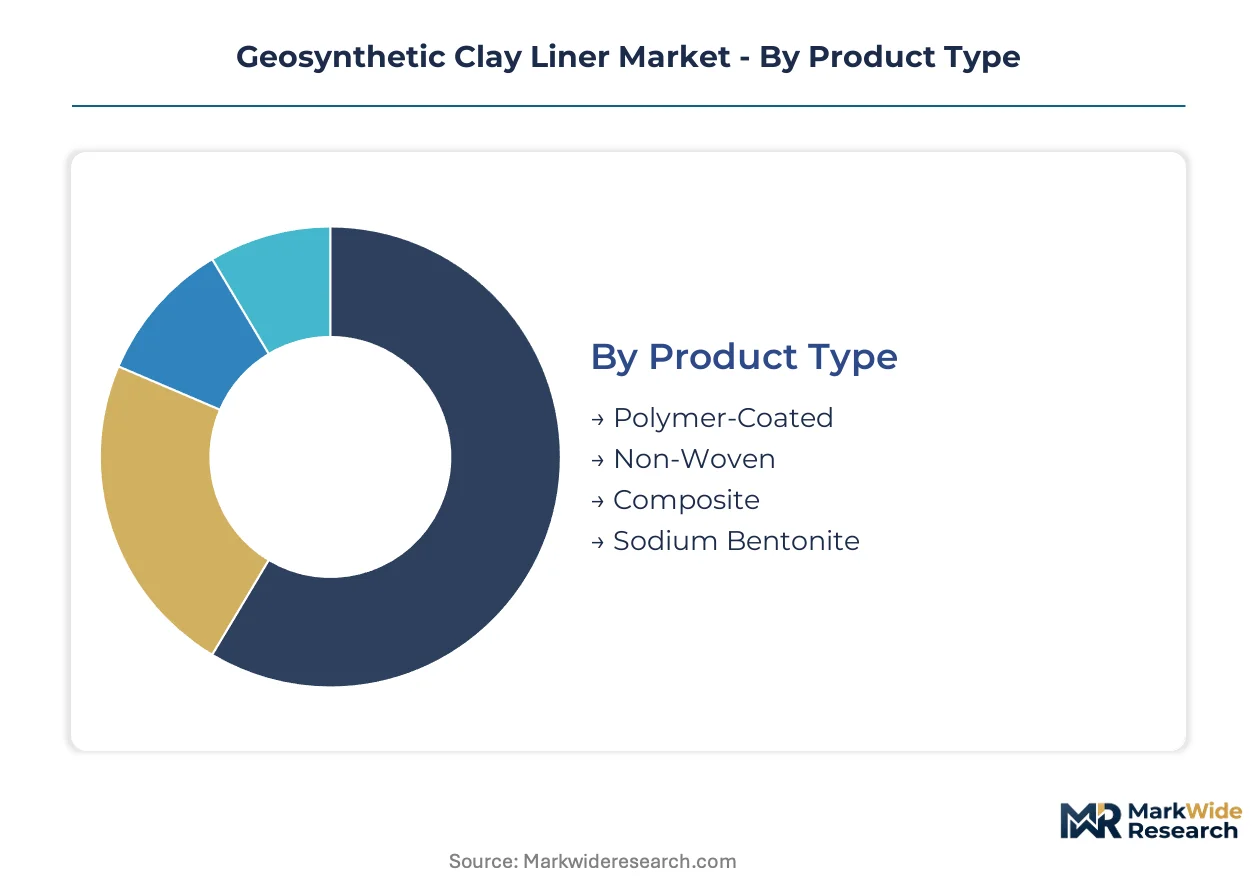
Product differentiation in geosynthetic clay liners follows hydraulic performance tiers that map directly to containment risk profiles and regulatory stringency. Specification engineers select liner configurations based on chemical exposure duration, substrate conditions, and post-installation access constraints rather than unit cost alone.
Product Type:
Substitution pressure from compacted clay and spray-applied geomembranes falls most heavily on standard sodium bentonite configurations, while polymer-coated variants defend their position through chemical resistance premiums that natural alternatives cannot replicate.
- Sodium Bentonite:Factory-bonded layers of Wyoming-sourced high-swelling clay achieve permeability below 5×10⁻⁹ cm/sec. Landfill operators in the United States specify this configuration for municipal solid waste cells where EPA Subtitle D mandates baseline hydraulic performance.
- Polymer-Coated:Extruded polyethylene or polypropylene films encapsulate the bentonite core to block ion exchange in aggressive leachates. Mining heap leach pads in Nevada and Arizona require these variants for prolonged solvent exposure cycles that would degrade unprotected clay.
- Composite:Geomembrane-bentonite laminates pair HDPE barriers with self-healing clay layers. Wastewater treatment lagoon upgrades in Texas and California specify these for dual mechanical and hydraulic protection.
- Non-Woven:Needle-punched geotextile encapsulation provides the lowest installed cost for temporary containment or low-risk applications.
Sodium Bentonite retains volume leadership; Polymer-Coated holds the steepest expansion curve.
Application:
Cost-tier differentiation separates capital-intensive mining projects from municipal procurement cycles constrained by tax-backed financing structures.
- Landfills:Municipal solid waste containment drives baseline demand through EPA-mandated composite liner systems. Closure mandates for unlined legacy facilities in Germany and France trigger replacement cycles where compacted clay fails modern conductivity thresholds.
- Mining:Heap leach pads and tailings dams specify polymer-enhanced variants for chemical resistance. Chilean and Peruvian copper operations specify coated liners for sulfuric acid exposure profiles that exclude standard bentonite.
- Wastewater Treatment:Lagoon upgrades and anaerobic digester containment require intermediate-grade products. Italian and Spanish brownfield remediation projects under EU Green Deal funding increasingly specify geosynthetic barriers over imported compacted clay.
- Hydraulic Structures:Canal lining and reservoir sealing applications favor cost-optimized non-woven configurations where mechanical loading remains moderate.
Landfills command the largest installed base; Mining applications gain share fastest through specification escalation in copper and lithium extraction.
End User:
Customer-type concentration shapes procurement modality, with municipal consortia consolidating purchasing power while environmental agencies drive specification tightening.
- Municipalities:Regional waste authorities in California, Texas, and Ohio negotiate multi-year framework agreements bundling supply with installation and post-closure monitoring. Consolidated tender formats displace traditional bid-item contracting.
- Environmental Agencies:State-level regulators in Germany and France enforce closure mandates that trigger upgrade cycles. ECHA-compliant safety data sheet requirements now filter non-compliant bids from coated liner procurement.
- Construction Companies:Civil contractors serving industrial clients specify intermediate-grade products for project-based procurement with shorter decision cycles.
- Agriculture:Irrigation pond and manure lagoon operators represent price-sensitive demand concentrated in water-stressed regions.
Municipalities retain volume leadership; Environmental Agencies drive the steepest specification escalation through regulatory tightening.
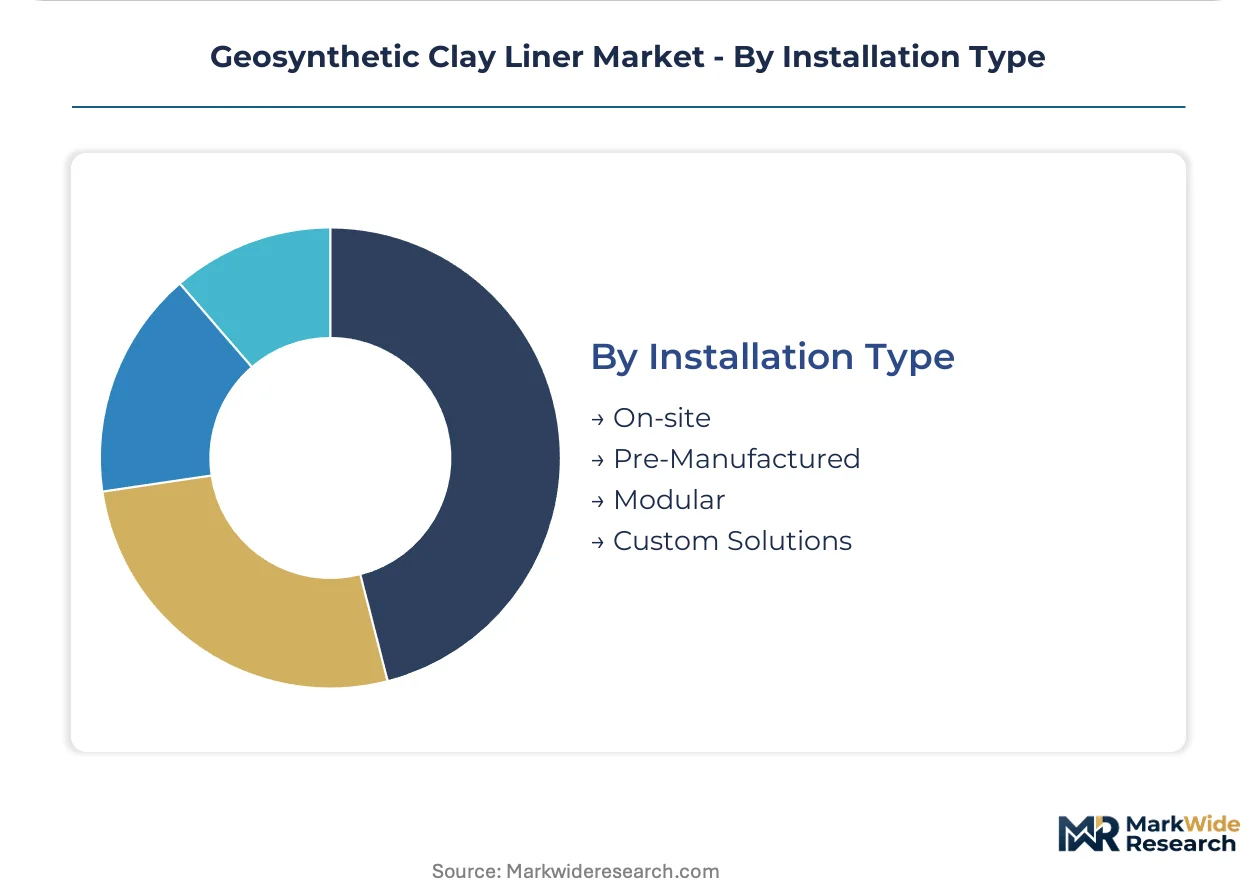
Installation Type:
Supply concentration in certified installation capacity favors pre-manufactured and modular approaches where field quality assurance gaps constrain on-site alternatives.
- Pre-Manufactured:Factory-controlled seaming and overlap geometry reduce field variability. Large landfill projects in the United States specify roll dimensions optimized for rapid deployment.
- Modular:Panelized systems enable confined-space installation in retrofit applications. Wastewater treatment facility upgrades in the Netherlands specify these where existing infrastructure limits access.
- On-site:Field fabrication of composite systems requires CQA-trained technicians that remain scarce outside established North American and Western European markets.
- Custom Solutions:Project-specific geometries serve irregular containment footprints in mining and hydraulic structure applications.
Pre-Manufactured retains volume leadership; Modular formats climb fastest through retrofit demand in constrained sites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal procurement offices in Germany enforce strict hydraulic conductivity thresholds that eliminate price competition, while landfill operators in India select geosynthetic clay liners primarily on unit cost metrics. This demand-elasticity contrast separates specification-driven European markets from cost-sensitive emerging economies.
United States
EPA Subtitle D regulations mandate composite liner systems for municipal solid waste landfills, creating baseline demand across all fifty states. Regional waste authorities in California negotiate multi-year framework agreements that bundle supply with installation services. The Permian Basin in Texas generates specialized demand from carbon capture sequestration pilot projects evaluating bentonite-based annular seals.
Germany
Closure mandates for unlined legacy landfills trigger replacement cycles where compacted clay fails modern conductivity standards. ECHA-compliant safety data sheet requirements filter non-compliant bids from coated liner procurement. Industrial clusters in North Rhine-Westphalia concentrate engineering procurement networks that integrate ASTM D5887 test data directly into bidding workflows.
Chile
Copper heap leach pad operators specify polymer-coated variants for sulfuric acid exposure profiles that exclude standard bentonite configurations. Mining tailings dam integrity regulations anticipate replacement cycle timing for aging containment infrastructure. The Antofagasta Region concentrates lithium extraction projects that escalate specification requirements for chemical-resistant barrier systems.
Australia
Iron ore tailings containment in Western Australia drives demand for intermediate-grade polymer-modified bentonite formulations. State-level environmental agencies enforce closure mandates that accelerate upgrade cycles for legacy mining infrastructure. The Pilbara region concentrates large-scale extraction operations where liner procurement follows project-based financing structures.
France
EU Green Deal circular economy construction grants subsidize geosynthetic barrier adoption in brownfield remediation projects. ANSM and environmental agencies coordinate specification tightening for hazardous waste facility containment. The Provence-Alpes-Côte d'Azur region hosts wastewater treatment lagoon upgrades where operators seek dual hydraulic and mechanical protection.
Geosynthetic Clay Liner Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the geosynthetic clay liner industry. Integrated resin-to-liner producers control raw material quality from source to finished membrane, while specialized bentonite suppliers anchor the sodium clay feedstock layer through captive mining operations. The market structure fragments across three strategic archetypes: upstream-integrated material suppliers, design-engineering specialists, and regional fabrication contractors. Dominant competitive moves include backward integration into Wyoming bentonite deposits and capacity expansion into polymer-coating production lines.
Among integrated material suppliers, Solmax and CETCO occupy positions that exemplify upstream control strategies, with the former representing polyethylene resin-to-liner integration and the latter anchoring captive sodium bentonite supply. Naue GmbH & Co. KG sits within the design-engineering specialist tier, pairing clay liners with geotextile drainage composites for European containment projects. These three entities represent distinct competitive positioning vectors that shape procurement patterns across municipal, mining, and wastewater end-use segments.
| Leading Market Players |
|---|
| Solmax |
| Minerals Technologies Inc. |
| CETCO |
| Naue GmbH & Co. KG |
| HUESKER Synthetic GmbH |
| Terrafix Geosynthetics Inc. |
| GSE Environmental |
| Geofabrics Australasia Pty Ltd. |
| Global Synthetics |
| Others |
Supply Flow & Price Mechanics
Compacted clay substitution in Scandinavian containment projects simultaneously reshapes supply geography toward regional bentonite deposits and compresses pricing economics for standard sodium bentonite configurations. Municipal procurement offices in cost-sensitive markets exploit this alternative to force margin concessions from liner fabricators who lack polymer-coating differentiation.
Pricing Analysis
Installation and post-closure monitoring service bundles now drive lifetime value capture in consolidated municipal procurement frameworks. Project-based contracting dominates landfill applications where California regional waste authorities negotiate multi-year agreements spanning supply through monitoring. Price differentiation separates EPA Subtitle D-compliant composite systems from economy-grade non-woven configurations. Cost compression in standard sodium bentonite tiers intensifies because Wyoming freight volatility and HDPE resin fluctuations squeeze composite fabricator margins. Municipal buyers in the United States exhibit highest price sensitivity; mining operators in Nevada and Arizona demonstrate lowest sensitivity due to chemical resistance premiums.
Supply Chain Analysis
Wyoming's Powder River Basin geological chokepoint underwrites global high-swelling sodium bentonite availability, exposing liner manufacturers to single-source concentration risk. Manufacturing draws from captive mining operations in Wyoming, polyethylene resin production in Texas and Louisiana, and needle-punched geotextile fabrication in the Carolinas. Single-source geological vulnerability represents the dominant structural risk, compounded by rail freight cost volatility to coastal export terminals. Distribution runs through engineering procurement networks that integrate ASTM D5887 test data directly into bidding workflows for certified suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installation certification and post-closure monitoring services represent a service-attach opportunity expanding faster than liner hardware supply, as consolidated municipal procurement bundles displace traditional bid-item contracting.
For Market Incumbents: Fortify upstream control over Wyoming bentonite deposits through lease consolidation or captive mining expansion, while investing in CQA-trained technician certification programs to defend against installation quality gaps that expose composite systems to field failure liability. CETCO's captive mining model and Solmax's resin-to-liner integration demonstrate defensible positioning against mid-tier fabricators collapsing specification tiers. For New Entrants and Emerging Players: Digital specification platform integration gaps where incumbents under-serve create entry points for certified suppliers with ASTM D5887 test data directly embedded in procurement workflows. Target Netherlands engineering procurement networks and German brownfield remediation projects under EU Green Deal funding streams, leveraging modular panelized systems for confined-space retrofit applications where pre-manufactured roll deployment proves impractical. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional fabrication contractors lacking polymer-coating production capabilities or captive bentonite supply. Five-to-ten year viability hinges on regulatory continuity in EPA Subtitle D enforcement and ECHA REACH compliance escalation. Watch carbon capture sequestration well deployment in Texas and Alberta as the signal indicating bentonite-based annular seal specification expansion beyond traditional containment applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wyoming Bentonite Deposits | Captive clay supply secures feedstock quality and insulates against geological concentration risk. |
| Polymer-Coating Production Line Expansion | Chemical-resistant variants capture mining heap leach pad specifications in Nevada and Arizona. |
| CQA Installation Certification Program Development | Trained technician scarcity outside North America creates qualification barriers for competitors. |
| Digital Specification Platform Integration | ASTM D5887 test data embedding reduces bidding friction in Netherlands procurement networks. |
| EU Green Deal Compliance Positioning | ECHA-compliant safety data sheets filter non-compliant bids from coated liner procurement in Germany. |
Methodological Framework
Initial hypotheses were tested against primary input from landfill engineering consultants, municipal procurement directors, mining tailings facility operators, CQA installation technicians, and geosynthetic product R&D managers and refined through secondary validation. Sources included EPA Subtitle D regulatory filings, ASTM D5887 and D5890 test protocol documentation, ECHA REACH registration databases, state-level landfill closure mandate records, and customs trade data on bentonite and HDPE resin movements. Bottom-up project pipeline enumeration triangulated against top-down market sizing from regulatory mandate coverage rates.
Variance decomposition across product type, application, end user, and installation format dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level demand elasticity modeling against regulatory mandate timing and replacement cycle phasing. Industry-specific inputs incorporated Wyoming bentonite production capacity utilization, municipal bond financing cycles for landfill infrastructure, and copper heap leach pad development pipelines in Chile and Peru.
Forecasts assume regulatory continuity in EPA Subtitle D enforcement and ECHA REACH compliance regimes; material policy shifts would require re-modeling of municipal procurement timing and coated liner formulation requirements. Practitioners should keep alternative scenarios live as carbon capture sequestration well deployment rates and EU Green Deal funding allocation patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Global Ceramic Membrane Market
Membrane Materials
Nanofiltration Membrane Market
Membrane Materials
Asia Pacific Waterproofing Membrane Market
Membrane Materials
Membrane Chemicals Market
Membrane Materials
Membrane Filter Cartridge Market
Membrane Materials
Reverse Osmosis (RO) Membrane Market
Membrane Materials
Membrane Separation Materials Market
Membrane Materials
SBS Modified Bitumen Membrane Market
Membrane Materials
Self-Adhered Roofing Membranes Market
Membrane Materials
Specialty Breathable Membranes Market
Membrane Materials
Single-Ply Membranes Market
Membrane Materials
Thermoplastic Polyolefin Membranes Market
Membrane Materials
Hollow Fibers Membrane Market
Membrane Materials
Global Microfiltration Membranes Market
Membrane Materials
North America Ceramic Membranes Market
Membrane Materials
Fuel Cell Gas Diffusion Layer Market