
 North America Roofing Membranes Market | 2026-2036
North America Roofing Membranes Market Size, Share, and Industry Trends Forecast 2026-2036
North America Roofing Membranes Market Insights
Aftermarket service revenue from membrane inspection, repair, and recertification is rewriting how suppliers capture lifetime value from installed roofing assets. Carlisle SynTec Systems leverages its national contractor certification network to lock in recurring maintenance contracts. Johns Manville sustains competitive advantage through backward integration into polymer feedstocks for modified bitumen production. Soprema Group anchors its North American position with specialized fluid-applied systems that complement sheet membrane portfolios.
Roofing membranes are synthetic or bituminous sheets, typically 40-90 mils thick, engineered to provide watertight building envelopes across flat or low-slope structures through heat-welded seams, adhesive bonding, or mechanical fastening. TPO membranes lead volume share due to heat-reflective surfaces that satisfy stringent thermal emittance requirements, while EPDM dominates longevity-sensitive applications with proven 30-year service life in extreme temperature cycling. Modified bitumen retains share in multi-ply recovery applications where contractors prioritize torch-applied familiarity over newer single-ply methods.
ASHRAE 90.1 energy standards, California Title 24 building codes, and EPA cool roof programs collectively mandate minimum solar reflectance indices that disqualify dark-surfaced membranes from public and commercial procurement. These frameworks force manufacturers to reformulate compounds or forfeit specification eligibility in the largest North American construction markets. Stakeholders must monitor state-level stretch code adoptions and utility rebate program shifts that could abruptly revalue white versus dark membrane portfolios.
Market Dynamics
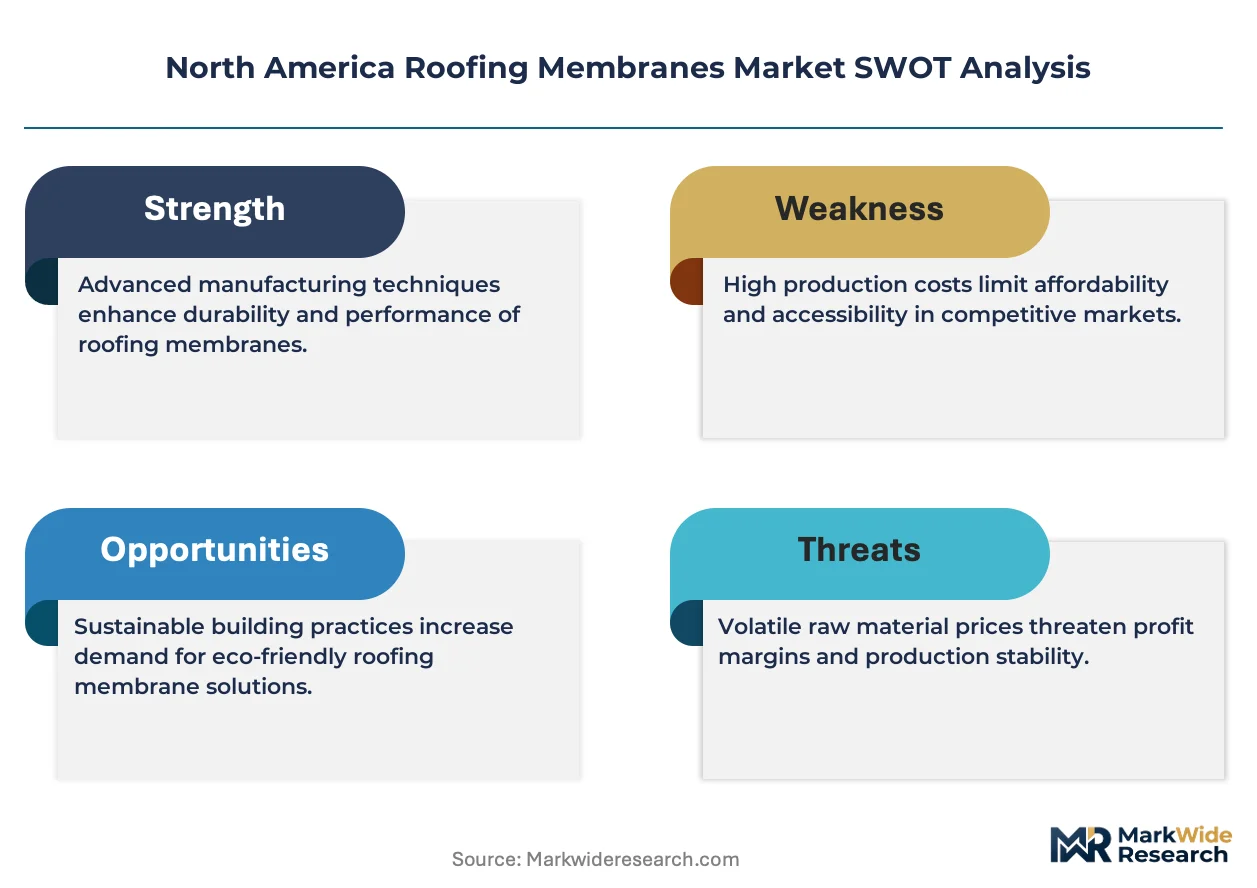
California Title 24 and ASHRAE 90.1 revisions are compressing specification windows for non-reflective roofing systems, forcing manufacturers to reformulate polymer compounds or surrender eligibility in the continent's largest commercial construction markets. This regulatory tightening is the dominant structural force reshaping competitive positioning across membrane categories.
Growth Catalysts
- Sun Belt cooling-load mandates:Texas, Florida, and Arizona building codes now require minimum solar reflectance indices that only white TPO membranes satisfy. Commercial developers in these states face permit delays if specifications fall below thermal emittance thresholds.
- EPA cool roof program expansion:Federal procurement guidelines now disqualify dark-surfaced membranes from government building contracts. This policy shift is redirecting municipal and institutional specification decisions toward thermoplastic systems.
- Polymer welding automation:Robotic heat-welding systems are reducing seam failure rates below 2% in large-format TPO installations. Contractors deploying this equipment are capturing premium labor rates on warranty-backed projects.
Market Restraints
- Petrochemical feedstock volatility:Propylene and ethylene price swings directly compress TPO and EPDM margin structures. Membrane manufacturers without captive polymer supply face quarterly cost renegotiations with resin suppliers.
- Torch-applied modified bitumen skill concentration:Certified torch applicators cluster in the Northeast and Upper Midwest, creating regional labor bottlenecks. Single-ply contractors in these markets struggle to displace established multi-ply specification relationships.
- EPDM dark-surface disqualification:California Title 24 and stretching municipal codes are eliminating black membrane eligibility from public procurement. EPDM producers must invest in white-surface reformulation or abandon West Coast commercial volume.
Strategic Opportunities
- Fluid-applied membrane convergence:Liquid polyurethane and silicone systems are penetrating detail-intensive roof geometries where sheet membranes require complex cutting and seaming. Soprema and specialized applicators are building dedicated crews for this hybrid installation model.
- Canadian prairie provinces:Saskatchewan and Manitoba commercial construction remains underpenetrated by thermoplastic systems. Local contractors still default to built-up roofing, creating first-mover openings for TPO specification education.
- Utility rebate program stacking:Southern California Edison and Texas municipal utilities now layer cool roof incentives atop state code requirements. Building owners in these territories capture payback periods below seven years on reflective membrane premiums.
Industry Challenges
- Heat-welding technician certification lag:Single-ply membrane quality depends on certified welder density, but training program throughput has not matched installation demand growth in the Southwest. Project timelines stretch when qualified crews are unavailable.
- Recertification documentation burden:Manufacturer warranty programs now require annual membrane inspection reports with thermal imaging evidence. Facility managers lacking in-house roofing expertise must contract third-party assessment services, adding lifecycle cost complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Roofing Membranes Market |
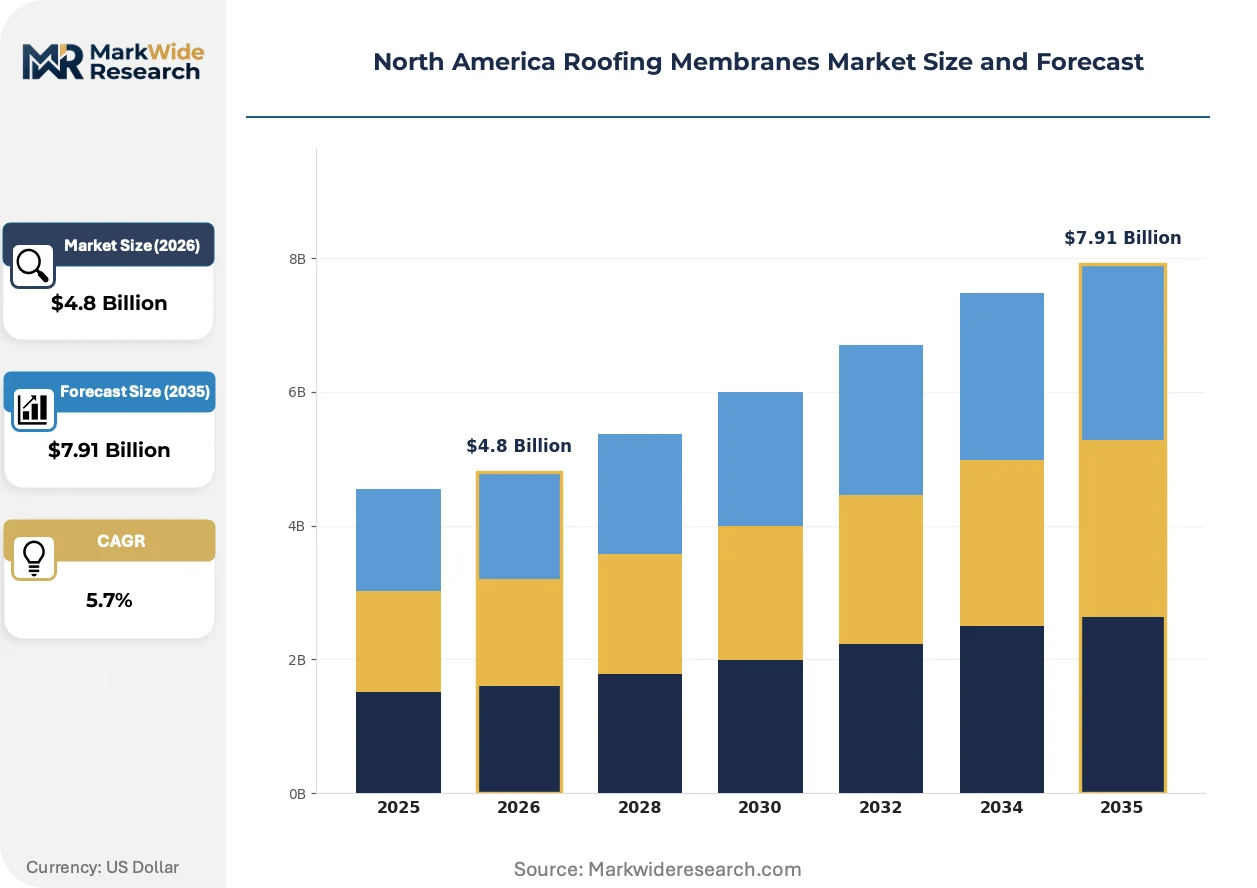
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EPDM, TPO, PVC, Modified Bitumen Installation Method: Mechanically Attached, Fully Adhered, Ballasted, Hybrid End User: Commercial, Residential, Industrial, Institutional Thickness: Single-Ply, Multi-Ply, Reinforced, Non-Reinforced |
| Companies Covered | Carlisle SynTec Systems, Sika AG, Holcim, Standard Industries Inc., Saint-Gobain, Owens Corning, Johns Manville, GAF, Soprema Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Roofing Membranes Market Trends and Innovations
Digital tools and sensor networks are penetrating membrane lifecycle management, compressing inspection cycles and enabling predictive maintenance models that shift contractor revenue from installation toward recurring service relationships.
Drone-based thermal imaging is digitizing roof condition assessment for commercial property portfolios. Large retail and logistics operators including Walmart and Amazon fulfillment network managers now mandate annual drone surveys across their building footprints. This technology is compressing leak detection from reactive emergency calls to scheduled intervention windows, redirecting contractor revenue toward subscription inspection models.
California Title 24 2022 standards and pending ASHRAE 90.1-2025 drafts are mandating cool roof performance tiers that disqualify conventional dark membranes from new construction and major renovation permits. Manufacturers are responding with advanced white-pigmented TPO compounds and reflective EPDM laminates that maintain elastomeric durability while meeting thermal emittance minimums. The commercial sector in California, Texas, and Florida faces the steepest compliance deadlines, accelerating specification migration.
Building owners are unbundling installation and warranty maintenance into separate procurement decisions. Large institutional buyers now solicit membrane supply through competitive bid while negotiating long-term service contracts directly with certified applicator networks. This pattern is most visible in healthcare and education verticals, where facility directors prioritize single-point accountability for leak performance over lowest-first-cost installation pricing.
North America Roofing Membranes Market Segmentation
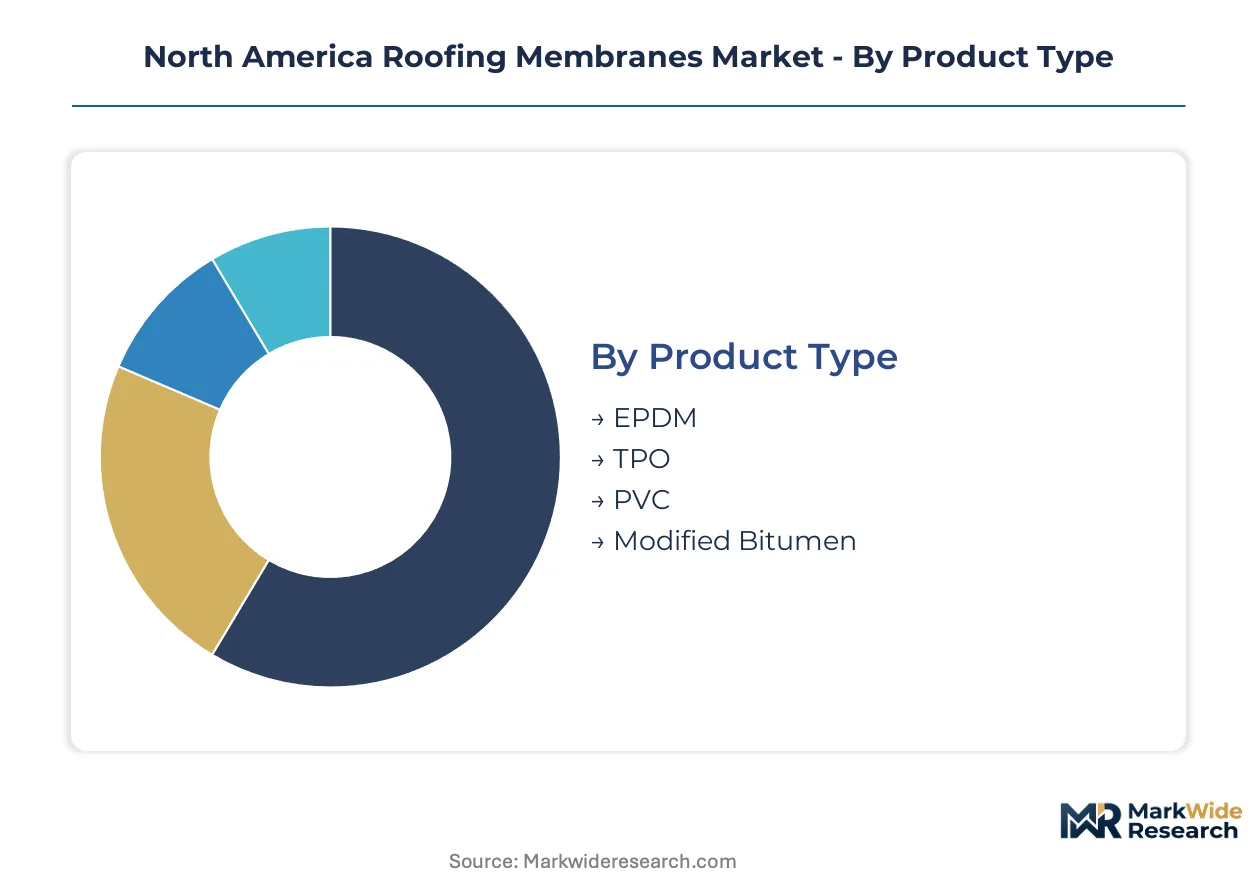
Segmentation in roofing membranes reveals how specification cycles, labor specialization, and regulatory compliance create divergent value capture across product categories. Understanding these fault lines exposes where manufacturers must anchor production capacity versus where specification education can unlock penetration.
Product Type:
TPO and EPDM turn over fastest in commercial re-roofing cycles, while modified bitumen persists longest in institutional portfolios where capital planning horizons stretch across decades.
- TPO:Thermoplastic polyolefin membranes combine polypropylene and ethylene-propylene rubber in heat-weldable sheets that satisfy stringent solar reflectance indices. Demand concentrates in Texas, Florida, and Arizona commercial construction where Title 24-adjacent municipal codes now mandate cool roof performance for permit approval.
- EPDM:Ethylene propylene diene terpolymer sheets deliver exceptional UV resistance and thermal cycling durability across 30-year service lives. Specification clusters in longevity-sensitive applications—hospitals, data centers, and cold-storage facilities—where black-surface variants still dominate outside California and coastal municipalities with strict thermal emittance rules.
- PVC:Polyvinyl chloride membranes offer superior chemical resistance and weldability for restaurants, food processing plants, and airports with grease exhaust exposure. The material commands specification premiums in high-traffic mechanical environments where membrane puncture resistance determines warranty eligibility.
- Modified Bitumen:Asphalt-based sheets polymerized with SBS or APP rubber retain contractor familiarity in the Northeast and Upper Midwest, where torch-applied installation skills concentrate and multi-ply recovery specifications dominate institutional maintenance budgets.
TPO anchors the volume base while modified bitumen gains share at the steepest rate among recovery applications where contractors resist single-ply conversion.
Installation Method:
Cost tiers separate premium fully adhered systems from economy ballasted configurations, with mechanical attachment occupying the mid-market where wind uplift ratings and labor efficiency must balance.
- Fully Adhered:Adhesive-bonded membranes eliminate fastener penetration and deliver the highest wind uplift ratings for hurricane-prone coastal zones. The method commands premium labor rates in Florida and Gulf Coast Texas where building codes now require enhanced fastening for mechanically attached alternatives.
- Mechanically Attached:Fastener-based installation dominates large-format TPO deployments across warehouse and big-box retail footprints where speed and material cost efficiency outweigh adhesive premiums. Robotic welding systems are compressing seam failure rates below 2% in these high-volume applications.
- Ballasted:Loose-laid membranes secured by gravel or concrete pavers minimize labor and adhesive costs for low-wind inland markets. The method surrenders specification eligibility in seismic zones and jurisdictions where dead load calculations restrict roof weight.
- Hybrid:Combined attachment approaches—mechanical in field areas with fully adhered perimeters—optimize cost and performance for irregular roof geometries with multiple penetrations. Soprema and specialized applicators are building dedicated crews for this detail-intensive installation model.
Mechanically attached systems anchor the volume base while fully adhered methods gain share at the steepest rate in coastal markets where windstorm insurance discounts reward enhanced uplift performance.
End User:
Application maturity separates commercial construction—where specification cycles refresh every 15-20 years—from institutional portfolios where capital planning and maintenance contracting create stickier supplier relationships.
- Commercial:Office, retail, and hospitality buildings drive specification velocity through developer-driven construction cycles and tenant improvement turnover. Property managers in Sun Belt states now bundle cool roof compliance with utility rebate capture, compressing payback periods on reflective membrane premiums.
- Industrial:Manufacturing facilities, distribution centers, and logistics hubs prioritize membrane durability under mechanical equipment loads and chemical exposure. Amazon and Walmart fulfillment networks now mandate annual drone-based thermal surveys across their building footprints, redirecting contractor revenue toward subscription inspection models.
- Institutional:Healthcare and education verticals unbundle installation from warranty maintenance into separate procurement decisions, prioritizing single-point accountability for leak performance over lowest-first-cost pricing. Carlisle's national contractor certification network locks in recurring maintenance contracts in this segment.
- Residential:Low-slope residential applications—townhome clusters, multi-family podiums, and luxury custom homes—represent underpenetrated specification territory where contractor education and distribution availability lag commercial channels.
Commercial construction anchors the volume base while industrial end users gain share at the steepest rate through predictive maintenance contracts and sensor-network deployment.
Thickness:
Supply concentration in reinforced multi-ply systems—where Johns Manville's backward integration into polymer feedstocks secures modified bitumen margins—contrasts with fragmented single-ply competition.
- Single-Ply:40-80 mil homogeneous sheets dominate new construction specification for their heat-welded seam integrity and installation speed. TPO and PVC formulations in this category satisfy ASHRAE 90.1 thermal emittance requirements that disqualify darker alternatives from public procurement.
- Reinforced:Polyester or fiberglass scrim embedded within polymer matrices enhances dimensional stability and puncture resistance for high-traffic roofs with maintenance personnel access. The construction commands specification in healthcare and data center verticals where membrane integrity failures carry catastrophic cost exposure.
- Multi-Ply:Layered bituminous or hybrid systems deliver redundancy and recovery compatibility for existing built-up roof substrates. The segment retains contractor loyalty in the Northeast where torch-applied skills concentrate and capital planning favors recover-over-replace strategies.
- Non-Reinforced:Homogeneous sheets without scrim reinforcement serve cost-sensitive applications and flashings where flexibility and conformability outweigh dimensional stability requirements. The category captures detail work and repair patches rather than field membrane specification.
Single-ply membranes anchor the volume base while reinforced constructions gain share at the steepest rate in critical facility verticals where warranty terms and insurance underwriting reward enhanced durability specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and Canada deploy roofing membranes through divergent specification logics. American building codes in Sun Belt states mandate reflective surfaces, while Canadian prairie markets retain torch-applied bitumen traditions. Mexico's commercial construction sector represents emerging specification territory where thermoplastic systems gain first-mover foothold.
United States
Texas, Florida, and Arizona commercial developers now face permit delays when specifications fall below thermal emittance thresholds established by ASHRAE 90.1-adjacent municipal codes. California Title 24 2022 standards disqualify dark-surfaced membranes from public procurement, forcing reformulation investments. The Dallas-Fort Worth metroplex anchors the continent's largest TPO specification volume, with robotic welding deployment compressing seam failure rates below 2% in warehouse installations.
Canada
Saskatchewan and Manitoba commercial construction remains underpenetrated by thermoplastic systems, with local contractors defaulting to built-up roofing methods. Health Canada and provincial building codes in Ontario and Quebec emphasize wind uplift performance for mechanically attached systems in prairie wind zones. The Greater Toronto Area concentrates specification education investments as manufacturers target first-mover conversion of multi-ply recovery applications.
Mexico
Nuevo León and Mexico City commercial construction drives emerging demand for single-ply membranes in logistics and manufacturing facilities. Federal procurement guidelines increasingly reference EPA cool roof program standards for government building contracts. The Bajío Region automotive supplier parks represent specification conversion opportunities where foreign anchor tenants import thermoplastic roofing preferences from US parent operations.
California
Los Angeles and San Francisco building departments enforce the continent's strictest cool roof performance tiers through Title 24 2022 standards. Southern California Edison utility rebates layer atop code requirements, compressing payback periods on reflective membrane premiums below seven years. The Inland Empire logistics corridor mandates annual drone-based thermal surveys for commercial portfolios exceeding 500,000 square feet.
Texas
Houston and Austin municipal utilities now stack cool roof incentives atop state energy code minimums, redirecting specification decisions toward white TPO systems. Gulf Coast windstorm insurance discounts reward fully adhered installation methods with enhanced uplift ratings. The Dallas-Fort Worth warehouse construction cluster deploys the highest robotic heat-welding equipment density in North American membrane installation.
North America Roofing Membranes Market Competitive Landscape
Capability concentration sits with integrated polymer compounders; scale advantage sits with national distribution networks. The North American roofing membranes sector structures around three tiers: captive feedstock producers securing margin through backward integration, certification-network operators capturing recurring service revenue, and regional applicators competing on installation speed. Dominant competitive moves include robotic welding equipment deployment and unbundling of installation from long-term warranty maintenance contracts.
Among integrated compounders, Johns Manville represents the captive feedstock archetype through upstream polymer production for modified bitumen systems. Carlisle SynTec Systems anchors the certification-network model with national contractor credentialing programs. Soprema Group occupies the specialized systems tier, with fluid-applied membrane portfolios complementing sheet product lines. These three patterns exemplify how manufacturers defend positioning against petrochemical price volatility and specification code tightening.
| Leading Market Players |
|---|
| Carlisle SynTec Systems |
| Sika AG |
| Holcim |
| Standard Industries Inc. |
| Saint-Gobain |
| Owens Corning |
| Johns Manville |
| GAF |
| Soprema Group |
| Others |
Pricing and Supply Chain Analysis
The Dallas-Fort Worth warehouse construction cluster concentrates North American TPO membrane production capacity, with localized compounding operations feeding robotic welding deployment across Texas commercial projects. This geographic concentration grants integrated manufacturers pricing leverage over regional contractors facing permit delays under ASHRAE 90.1-adjacent municipal codes.
Pricing Analysis
Long-term offtake contracts dominate membrane procurement for institutional portfolios, while spot purchasing prevails in commercial developer-driven projects. Pricing stratifies across premium certified-welder tiers, standard mechanical-attachment bundles, and economy ballasted configurations. Cost compression in standard tiers is intensifying because petrochemical feedstock volatility forces quarterly resin renegotiations. Commercial developers exhibit highest price sensitivity; healthcare facility directors prioritize leak-performance accountability over first-cost optimization.
Supply Chain Analysis
Export-control regimes on advanced polymer catalysts limit specialized TPO compound flows from select European suppliers into North American manufacturing. Raw material sourcing draws from Gulf Coast propylene crackers, Canadian SBS rubber production, and imported EPDM polymer. Single-source vulnerability concentrates in certified torch-applicator labor pools across the Northeast. Distribution runs through manufacturer-direct contractor networks and regional roofing supply houses serving independent applicators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified heat-welding technician density lags installation demand growth across the Southwest, constraining quality-assured membrane deployment and fragmenting contractor pricing power. This capability gap rewards stakeholders who anchor skill development investments ahead of code-compliance deadlines.
For Market Incumbents: Pre-empt specification lockout by accelerating white-surface EPDM reformulation before California Title 24 stretch codes spread to Texas and Florida municipalities. Prioritize backward integration into polymer feedstocks to buffer margin compression from propylene price swings. Anchor capacity expansion in the Inland Empire logistics corridor where drone-inspection mandates concentrate institutional maintenance contract opportunities.
For New Entrants and Emerging Players: Establish a beachhead in Saskatchewan and Manitoba commercial construction where thermoplastic specification education remains underdeveloped and built-up roofing methods dominate recovery applications. Target first-mover conversion through contractor training partnerships emphasizing ASHRAE 90.1 compliance advantages. Deploy fluid-applied membrane crews for detail-intensive hybrid installations where established sheet-membrane competitors lack dedicated expertise.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors certification-network operators with recurring inspection revenue streams over pure-play manufacturers exposed to resin cost volatility. Long-term viability hinges on predictive maintenance platform deployment and sensor-network integration. Acquisition target archetype: regional applicators with established healthcare facility relationships and drone-based thermal imaging capabilities. Watch for inflection when utility rebate program stacking reaches critical mass in Southern California Edison and Texas municipal territories.
| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Heat-Welding Equipment Deployment | Carlisle's certified contractor network compresses seam failure rates below 2% in warehouse installations. |
| Backward Integration into Polymer Feedstocks | Johns Manville secures modified bitumen margins against Gulf Coast propylene price volatility. |
| Fluid-Applied Membrane Crew Development | Soprema captures detail-intensive geometries where sheet membranes require complex cutting. |
| Drone-Based Thermal Inspection Subscriptions | Amazon and Walmart fulfillment networks mandate annual surveys across building footprints. |
| White-Surface EPDM Reformulation Investment | Manufacturers retain California commercial volume as Title 24 disqualifies black membranes. |
Research Methodology
The analysis maps TPO, EPDM, PVC, and modified bitumen membrane segments, each validated through membrane manufacturing executives, certified roofing contractor operations managers, commercial property facility directors, and institutional capital planning officers. Primary interview insights triangulate against EPA cool roof program filings, ASHRAE 90.1 revision documentation, California Title 24 compliance databases, and utility rebate program disclosures. Secondary validation incorporates customs and trade data on polymer resin imports, SEC 10-K disclosures from integrated building materials conglomerates, and regional building permit databases. Bottom-up volume estimates from contractor deployment rates reconcile with top-down construction spending allocations across commercial, industrial, and institutional verticals.
Assumptions hold fixed the current trajectory of ASHRAE 90.1 adoption across Sun Belt states, while varying petrochemical feedstock cost scenarios and utility rebate program expansion rates. Segmentation modeling incorporates product type, installation method, end-use vertical, membrane thickness, and geographic regulatory cluster dimensions. CAGRs derive from installation volume trends indexed to commercial construction permits and re-roofing cycle timing. Industry-specific forecast inputs include certified welder training program throughput and robotic welding equipment deployment density by metropolitan statistical area.
Sensitivities concentrate around state-level stretch code adoptions, propylene and ethylene price volatility, and heat-welding technician certification lag. Forecasts reflect documented assumptions on regulatory compliance timelines and contractor skill migration patterns. Material shifts in EPA cool roof program federal procurement guidelines or abrupt utility rebate program suspensions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Breather Membranes Market
Membrane Materials
SBS Modified Bitumen Membrane Market
Membrane Materials
Global Roofing Membranes Market
Membrane Materials
Global Membrane Separation Technology Market
Membrane Materials
Global Track Etched Membrane Market
Membrane Materials
Expansion Vessel Membrane Market
Membrane Materials
Global Polymer Nanomembrane Market
Membrane Materials
Global Medical Membranes Market
Membrane Materials
Membrane Bioreactor Market
Membrane Materials
North America Transparent Conductive Films Market
Membrane Materials
Asia Pacific Waterproofing Membrane Market
Membrane Materials
Global Membrane Water and Wastewater Treatment Market
Membrane Materials
Microporous Materials Market
Membrane Materials
Global Spiral Membrane Market
Membrane Materials
Inorganic Ion Exchange Materials Market
Membrane Materials
Global Membrane Chromatography Market