
 Europe Bitumen Market | 2026-2036
Europe Bitumen Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bitumen Market Insights
Multi-source procurement among European road contractors is shifting toward vertically integrated refinery-to-project supply chains. Shell Plc leverages its Rotterdam refining complex to secure volume commitments from national highway agencies. Nynas AB anchors specialty bitumen supply through its naphthenic base oil integration. TotalEnergies competes on low-carbon product lines tied to French infrastructure decarbonization targets.
Bitumen is a viscous, dark hydrocarbon residue from crude oil vacuum distillation, with penetration grades typically spanning 15–450 dmm and softening points between 35°C and 70°C, functioning primarily as a thermoplastic binder in pavement layers and protective membranes. Polymer Modified Bitumen dominates margin pools due to superior rutting resistance on high-traffic motorways. Emulsified Bitumen leads growth in cold-mix applications where temperature restrictions and emission controls tighten. Road Construction occupies the largest demand share, though Waterproofing commands premium pricing in commercial building envelopes.
REACH compliance and the EU Green Deal's carbon border adjustments constrain import competition from non-European refiners. ECHA substance evaluations and national EPA permitting in Germany and France shape product formulation standards and refinery operating licenses. Stakeholders must monitor tightening embodied-carbon thresholds for public procurement eligibility and the pace of bio-based binder commercialization.
Market Dynamics
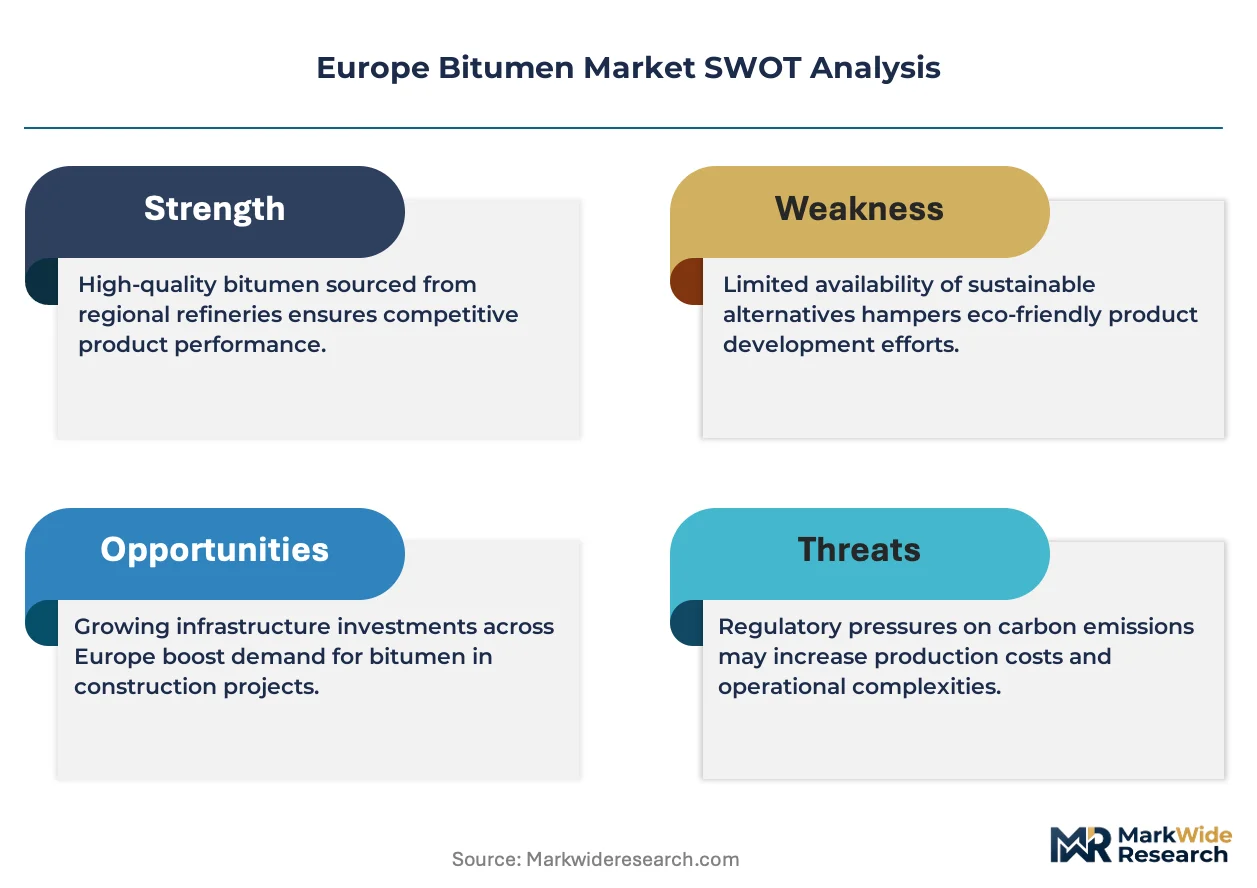
The EU Green Deal's carbon border adjustments and REACH substance evaluations are redirecting refinery investment toward lower-carbon binder formulations, compressing margins for conventional penetration-grade suppliers while rewarding polymer-modified and emulsified product lines.
Growth Catalysts
- EU cohesion fund deployment:Central and Eastern European highway modernization programs are absorbing rising bitumen volumes as Poland, Romania, and Czechia expand motorway networks.
- ECHA regulatory clarity:REACH substance evaluations provide stable formulation standards that reduce technical uncertainty for refinery product development.
- Cold-mix technology maturation:Emulsified bitumen grades are penetrating maintenance and repair contracts where temperature restrictions and emission controls tighten.
Market Restraints
- Crude slate volatility:Vacuum residue yields fluctuate with heavy sour crude availability, squeezing bitumen supply elasticity when asphalt demand peaks seasonally.
- Import competition compression:Carbon border adjustments constrain non-European refiner participation, leaving supply concentrated among Rotterdam-adjacent producers.
- Bio-based substitution timeline:Commercial-scale lignin and bio-oil binders remain pre-competitive on cost and performance, but pilot-scale validation is advancing.
Strategic Opportunities
- Baltic corridor development:Estonia, Latvia, and Lithuania are consolidating transport infrastructure planning, creating coordinated demand for polymer-modified binders on high-load corridors.
- Building envelope waterproofing:Commercial construction energy-efficiency mandates are expanding membrane specifications beyond traditional road applications.
- Refinery-to-project contracting:Direct volume commitments with national highway agencies are displacing spot-market procurement in Germany and France.
Industry Challenges
- Embodied-carbon certification:Public procurement eligibility now requires verified lifecycle emissions data that most refineries lack at batch-level granularity.
- Specialty formulation talent:Polymer modification and emulsion chemistry expertise concentrates at a handful of technical centers, constraining product line expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bitumen Market |
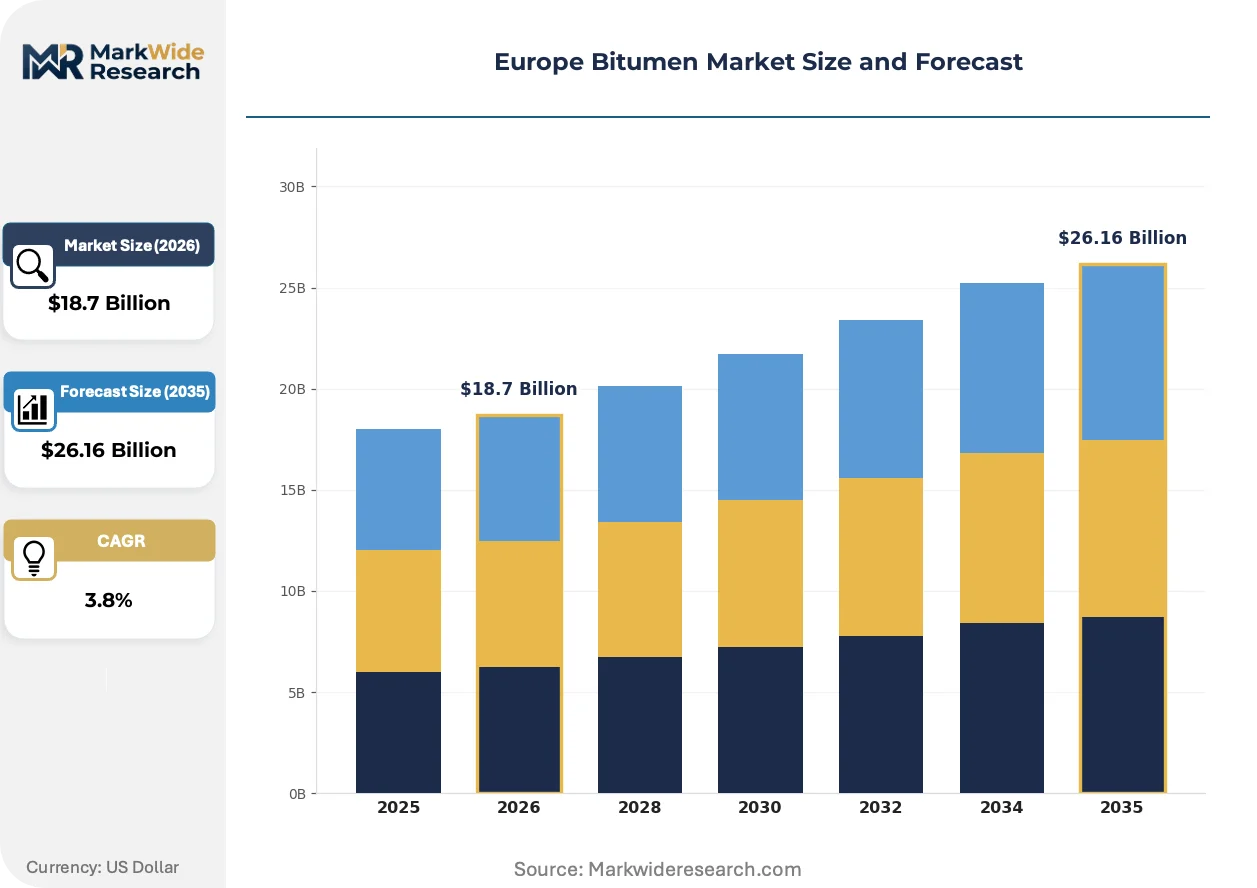
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxidized Bitumen, Cutback Bitumen, Emulsified Bitumen, Polymer Modified Bitumen Application: Road Construction, Roofing, Waterproofing, Insulation End User: Construction Companies, Manufacturing Firms, Contractors, Government Agencies Distribution Channel: Direct Sales, Distributors, Retailers, Online Platforms |
| Companies Covered | Exxon Mobil Corporation, Gazprom Neft, Shell Plc, Eurovia, Colas Group, BP Plc, Nynas AB, Orlen Lietuva, TotalEnergies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bitumen Market Trends and Innovations
Formulation chemistry and supply chain configuration are diverging as decarbonization mandates force product-level carbon accounting and as procurement centralization rewards integrated refinery-project relationships.
Polymer-modified bitumen is expanding into high-traffic motorway specifications across Germany and France. National highway agencies specify elastomer-modified binders for rutting resistance on heavy freight corridors. The technology is expanding into premium-margin pools that conventional penetration grades cannot access.
REACH substance evaluations and the EU Green Deal's carbon border adjustments are tightening formulation disclosure requirements. Refineries must now document additive chemistries and upstream emissions to maintain operating licenses. German KBA and French environmental permitting authorities are enforcing these standards most stringently, compressing import competition.
Contracting patterns are consolidating around multi-year volume agreements. National highway agencies in Poland and Romania are abandoning spot-market procurement for integrated supply chains that guarantee grade consistency and delivery scheduling. This shift is most visible in Central European cohesion fund projects where disbursement timelines require supply certainty.
Europe Bitumen Market Segmentation
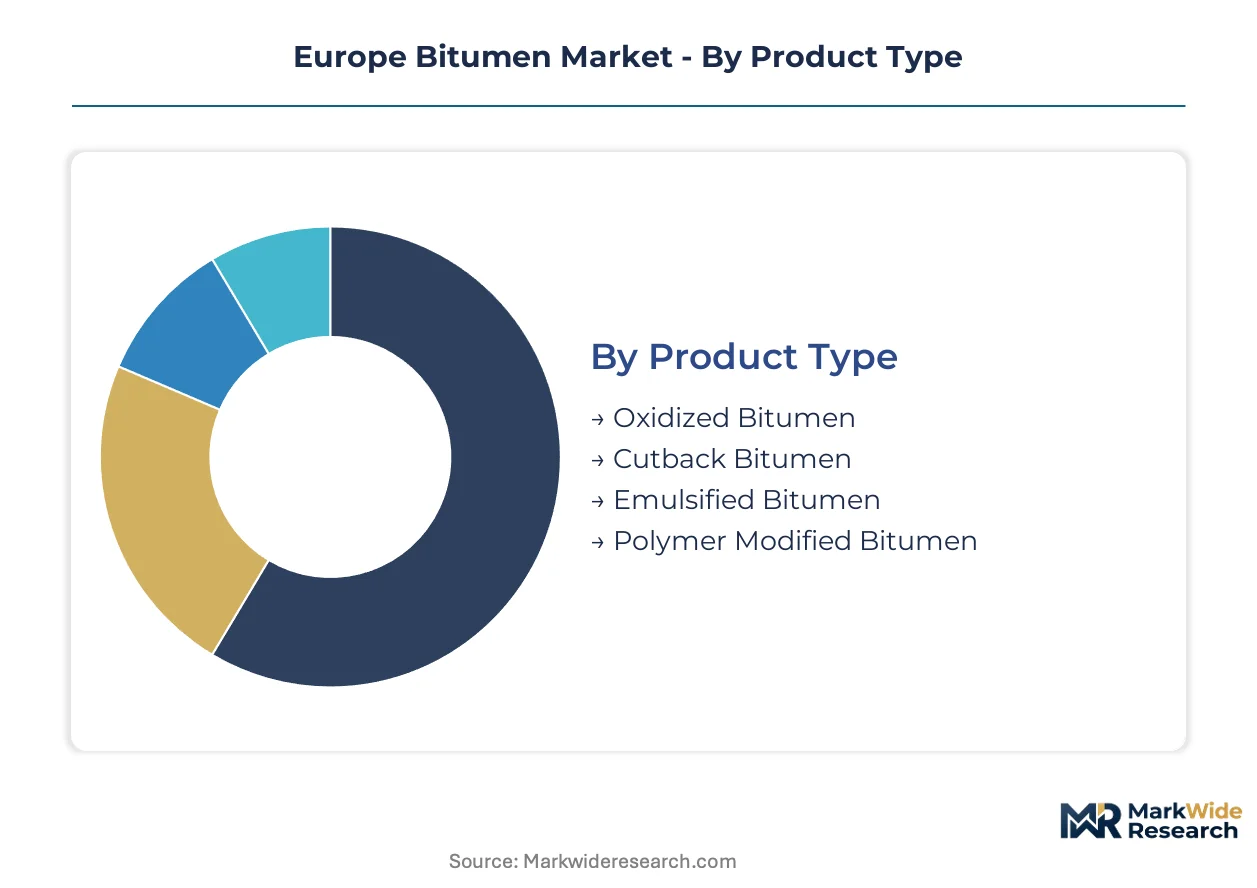
Product chemistry and application requirements fragment the Europe bitumen market into distinct margin tiers. Specification standards from German KBA and French environmental permitting authorities enforce grade-specific procurement, creating rigid segment boundaries that resist cross-category substitution.
Product Type:
Volume concentrates in conventional grades while premium pools accrue to modified formulations with performance guarantees.
- Polymer Modified Bitumen:Elastomer and plastomer additives transform thermoplastic behavior, delivering rutting resistance specifications mandatory on German and French heavy freight corridors. Central and Eastern European cohesion fund highways specify PMB for load-bearing layers where traffic density exceeds design thresholds.
- Emulsified Bitumen:Water-based dispersions enable cold-mix application where temperature restrictions and emission controls tighten. Poland and Romania specify emulsion grades for maintenance contracts in urban air quality zones where hot-mix operations face seasonal prohibitions.
- Oxidized Bitumen:Air-blown processing elevates softening points for roofing membrane specifications across commercial building envelopes in France and Germany.
- Cutback Bitumen:Solvent-thinned grades persist in remote construction sites where hot-mix plant proximity limits conventional supply economics.
Today's leader: Polymer Modified Bitumen. Tomorrow's challenger: Emulsified Bitumen.
Application:
Roadwork absorbs bulk volume while building envelope specifications command price premiums.
- Road Construction:Pavement binders consume the majority of European bitumen throughput, with German Autobahn renewal and Polish motorway expansion driving specification intensity. EU cohesion fund disbursement timelines concentrate demand into synchronized procurement windows.
- Waterproofing:Membrane applications in commercial construction energy-efficiency mandates expand specifications beyond traditional road uses, with French building codes driving premium-grade penetration.
- Roofing:Oxidized grades serve flat-roof specifications across industrial and residential stock renovation in Germany and Benelux markets.
- Insulation:Bituminous coatings protect thermal systems in building envelope retrofits where moisture barriers integrate with energy performance standards.
Road Construction maintains volume dominance. Waterproofing climbs the fastest on margin expansion.
End User:
Public procurement centralization concentrates volume with government agencies while contractors compete on formulation expertise.
- Government Agencies:National highway authorities in Germany, France, and Poland consolidate multi-year volume commitments, displacing spot-market procurement with integrated supply chain contracts.
- Construction Companies:Tier-one infrastructure contractors specify polymer-modified grades for design-build motorway contracts where performance bonding requires material traceability.
- Contractors:Regional maintenance specialists drive emulsified bitumen uptake for repair and resurfacing work in municipal jurisdictions with emission restrictions.
- Manufacturing Firms:Waterproofing membrane producers and roofing material manufacturers source oxidized grades for building product fabrication.
Government Agencies anchor procurement volume. Construction Companies capture formulation premium.
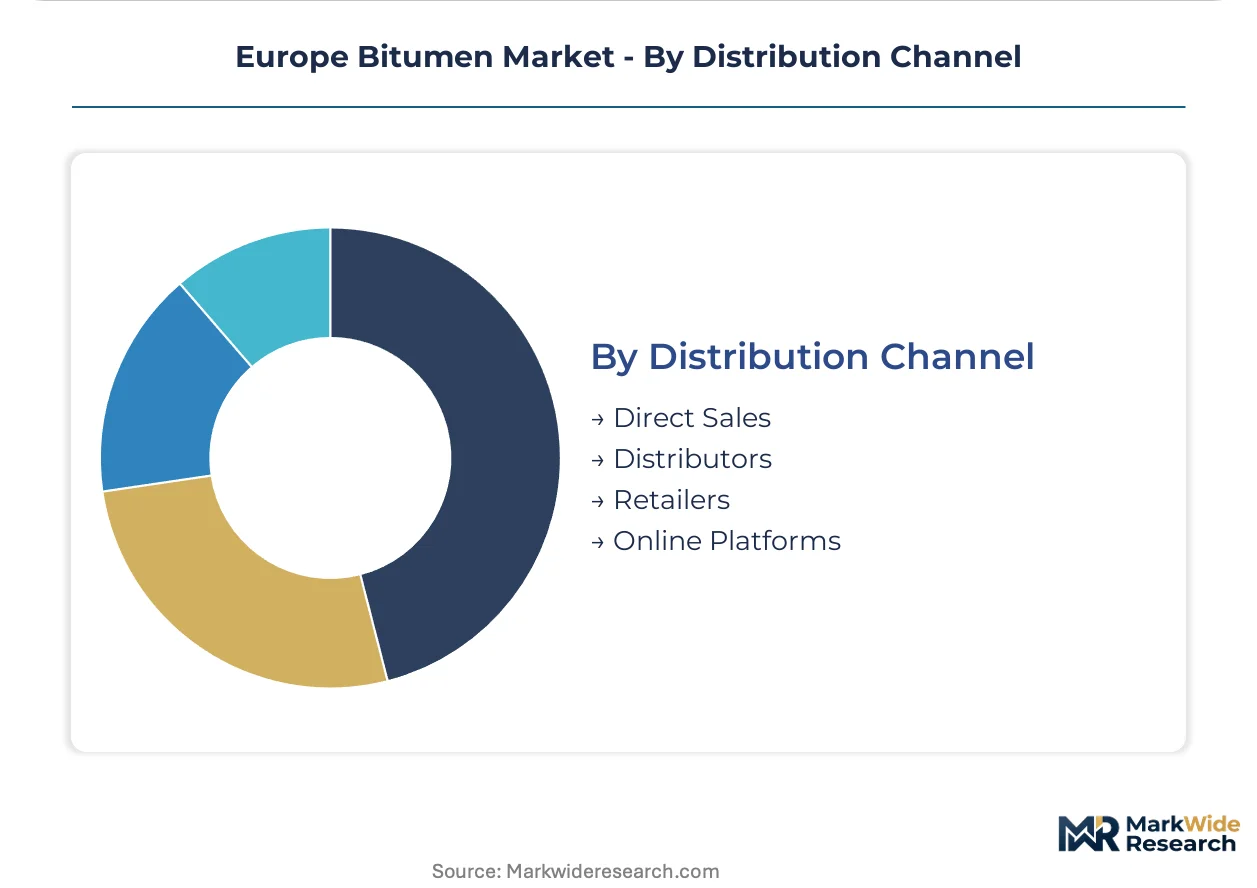
Distribution Channel:
Supply chain configuration shifts from fragmented intermediation toward refinery-direct relationships.
- Direct Sales:Rotterdam-adjacent refineries negotiate multi-year volume agreements with Polish and Romanian national highway agencies, guaranteeing grade consistency and delivery scheduling against cohesion fund disbursement timelines.
- Distributors:Regional stockists maintain grade breadth for mid-tier contractors lacking storage infrastructure, though margin compression from direct contracting erodes their historical position.
- Retailers:Limited presence in packaged specialty grades for maintenance and repair segments where small-batch requirements resist bulk logistics.
- Online Platforms:Emerging for standardized product documentation and specification matching, though physical delivery constraints limit transactional share.
Direct Sales consolidates share. Distributors defend position through formulation technical support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam refining complex anchors European bitumen supply, channeling vacuum residue derivatives through integrated pipeline networks to construction corridors across Germany, France, and Poland. National infrastructure renewal programs concentrate demand into synchronized procurement windows tied to EU cohesion fund disbursement schedules.
Germany
Autobahn renewal programs and heavy freight corridor upgrades absorb polymer-modified bitumen volumes. The KBA enforces strict rutting-resistance specifications for high-traffic motorway layers. The Rhine-Ruhr industrial belt concentrates blending capacity near Dortmund and Duisburg, where refinery-to-project supply chains guarantee grade consistency.
France
Building envelope waterproofing mandates and commercial construction energy-efficiency codes expand oxidized bitumen specifications. National environmental permitting authorities align product formulation standards with EU Green Deal carbon thresholds. The Lyon-Grenoble corridor hosts specialty binder technical centers developing low-carbon emulsion chemistries.
Poland
Motorway expansion and Baltic corridor development drive specification intensity for cohesion fund highways. The national road agency consolidates multi-year volume commitments, displacing spot-market procurement with integrated refinery contracts. Silesia and Lower Silesia concentrate asphalt mixing capacity near Katowice and Wrocław.
Romania
Trans-European transport network integration and Danube corridor modernization absorb rising emulsified bitumen volumes for maintenance contracts. EU cohesion fund disbursement timelines require supply certainty that favors direct refinery agreements. Bucharest-Ploiești anchors distribution logistics for Black Sea refining imports.
Netherlands
Rotterdam-adjacent refineries leverage vacuum distillation capacity to secure volume commitments across Northwest Europe. REACH substance evaluations and carbon border adjustment mechanisms compress import competition from non-European producers. The Port of Rotterdam cluster coordinates barge and rail distribution to German and Belgian construction markets.
Europe Bitumen Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty formulation and low-carbon certification niches. The vendor base concentrates around Rotterdam-adjacent refineries with integrated vacuum distillation capacity, while mid-tier blenders defend position through regional stockholding and technical support services. Three archetypes dominate: integrated oil majors with captive refining, naphthenic base oil specialists, and regional construction-material conglomerates. Competitive moves center on refinery-to-project contracting and polymer modification capacity expansion.
Among integrated oil majors, Shell Plc and TotalEnergies occupy positions exemplifying the vertically integrated archetype, leveraging refining complexity to secure national highway agency commitments. Nynas AB represents the specialty tier, anchoring polymer-modified and emulsified product lines through naphthenic base oil integration. These three entities illustrate how feedstock access and formulation expertise stratify competitive positioning across standard and premium grade pools.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Gazprom Neft |
| Shell Plc |
| Eurovia |
| Colas Group |
| BP Plc |
| Nynas AB |
| Orlen Lietuva |
| TotalEnergies |
| Others |
Pricing and Supply Chain Analysis
The EU Green Deal's embodied-carbon thresholds gate qualified supply and premium-tier pricing access, compressing margins for conventional penetration-grade producers while rewarding Rotterdam-adjacent refiners with verified low-carbon batch data. National highway agencies in Germany and Poland now require lifecycle emissions documentation for procurement eligibility, creating a two-tier market where certified suppliers command structural price premiums.
Pricing Analysis
Vacuum residue cost pass-through dominates European bitumen pricing, with Rotterdam-adjacent refiners leveraging captive crude distillation capacity to manage margin volatility better than importers. Price differentiation rests on carbon certification tier and polymer modification grade, with elastomer-modified binders capturing premium pools unavailable to conventional penetration grades. Cost compression in standard-grade supply is intensifying because carbon border adjustments constrain non-European refiner participation. Municipal maintenance contractors exhibit highest price sensitivity due to seasonal budget constraints, while German Autobahn agencies prioritize performance guarantees over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Rotterdam-adjacent vacuum distillation capacity, where Shell Plc and TotalEnergies control the majority of Northwest European bitumen output. Supply concentrates in the Netherlands, Germany, and Poland, with heavy sour crude availability and naphthenic base oil integration as critical feedstock dependencies. Tariff exposure through carbon border adjustment mechanisms threatens import flexibility from Russian and Middle Eastern refiners. Distribution runs through integrated barge-rail networks from the Port of Rotterdam cluster to German mixing plants and Polish construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Bitumen Market functions as a geographic-arbitrage play where Central and Eastern European cohesion fund disbursement timelines offer volume certainty unavailable in Western European maintenance markets constrained by fiscal austerity.
For Market Incumbents: Anticipate bio-based binder substitution threats by securing backward integration into naphthenic base oil supply and expanding polymer modification capacity in Poland. Prioritize carbon certification investment to defend procurement eligibility under tightening EU Green Deal thresholds. Lock multi-year volume commitments with Romanian and Czech national road agencies before pilot-scale lignin binders reach commercial scale.
For New Entrants and Emerging Players: Capture white-space opportunity in Baltic corridor polymer-modified specifications where Estonian and Latvian transport infrastructure planning consolidates demand. Target emulsified bitumen maintenance contracts in Polish urban air quality zones where seasonal hot-mix prohibitions create guaranteed demand windows. Pursue refinery-to-project contracting as the dominant go-to-market angle, displacing spot-market distributors through integrated supply chain guarantees.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional construction-material conglomerates lacking carbon certification infrastructure but holding captive distribution networks in Central Europe. Long-term viability over the mid-decade window favors specialty blenders with demonstrated REACH compliance and polymer formulation expertise. Monitor bio-based binder pilot-scale validation announcements as the critical inflection signal for conventional bitumen demand erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Naphthenic Base Oil | Nynas AB leverages captive feedstock access to secure polymer-modified margin pools. |
| Carbon Certification Program | Rotterdam-adjacent refiners document batch-level emissions to meet German KBA procurement standards. |
| Long-term Supply Agreement | Poland's national road agency consolidates multi-year volume commitments displacing spot-market procurement. |
| Capacity Expansion in Central Europe | Silesia-based blending capacity captures cohesion fund highway modernization demand. |
| Green Manufacturing Transition | French environmental permitting authorities enforce low-carbon emulsion chemistry development in Lyon-Grenoble corridor. |
Research Methodology
Bottom-up road construction modeling reconciled against top-down refinery output tracking forms the analytical core of this study. Primary interviews with asphalt mixing plant managers, national highway agency procurement officers, polymer modification R&D directors, and waterproofing membrane manufacturers were validated against secondary sources including Eurobitume industry statistics, ECHA substance evaluation filings, EU cohesion fund disbursement records, and customs trade data for vacuum residue derivatives.
Historical trendline analysis of penetration grade and polymer-modified volume flows established baseline growth patterns across the projection horizon. The forecast framework models product type chemistry, application intensity by construction segment, end-user procurement centralization, and distribution channel configuration. CAGRs were derived from elasticity-adjusted demand projections incorporating EU Green Deal regulatory phase-in schedules and crude slate yield assumptions.
Crude price volatility, bio-based binder commercialization acceleration, and cohesion fund disbursement delays are the dominant revision risks to volume and value forecasts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Rodenticides Market
Industrial Chemicals
US Anhydrous Hydrogen Fluoride Market
Industrial Chemicals
Tetrafluoroethane (R134A) Refrigerant Market
Industrial Chemicals
South America Starch Derivatives Market
Industrial Chemicals
Dewatering Aids Market
Industrial Chemicals
Foam Market
Industrial Chemicals
Global Flow Chemistry Market
Industrial Chemicals
Naphthenic Acid Market
Industrial Chemicals
Babassu Oil Market
Industrial Chemicals
Process Fluid Market
Industrial Chemicals
Hydrofluoroolefin (HFO) Blowing Agent Systems for Rigid PU Foam Market
Industrial Chemicals
Permethrin Market
Industrial Chemicals
Industrial Phosphate Market
Industrial Chemicals
Global Cyanuric Chloride Market
Industrial Chemicals
Plant-Based Hydraulic Oil Market
Industrial Chemicals
Calciner Market