
 High Pressure Oil and Gas Separators Market | 2026-2036
High Pressure Oil and Gas Separators Market Size, Share, and Industry Trends Forecast 2026-2036
High Pressure Oil and Gas Separators Market Analysis
Project finance structures tied to long-term production-sharing contracts is tilting competitive access toward capital-heavy incumbents. Baker Hughes Company leverages integrated turbomachinery portfolios to anchor offshore project bids. TechnipFMC plc sustains engineering dominance through subsea-to-surface system bundling. National Oilwell Varco controls manufacturing scale across North American fabrication yards.
High pressure oil and gas separators are pressure vessels engineered to operate above 1,000 psi, using welded carbon steel or duplex stainless steel construction with internal weir plates, mist extractors, and level control systems to partition hydrocarbon streams into distinct oil, gas, and water phases for downstream processing and custody transfer. Gravity separation technology leads installed base volumes due to operational simplicity and tolerance for high solids loading, while electrostatic separation occupies premium margin pools where emulsion-breaking efficiency determines throughput economics. Three-phase separators dominate new order books across brownfield expansions, though modular installation types are capturing share in remote basin developments where site-constrained logistics favor skid-mounted delivery.
API 12J standards enforced by OSHA-process-safety inspectors govern minimum design pressure, corrosion allowance, and safety-relief capacity for US onshore installations, while the EPA's methane-emission rules shape separator vapor-recovery unit attachment rates. Offshore regulators in Norway and Brazil impose NORSOK and ANP certification tiers that filter market access for fabricators lacking third-party witness-test protocols. Stakeholders must weigh build-to-spec contracting against performance-guarantee models as reservoir-pressure profiles shift and digital monitoring retrofits redefine asset-life valuation.
Market Dynamics
API 12J specification revisions are compressing design cycles and forcing fabricators to requalify weld procedures, while deepwater offshore projects concentrate procurement power among integrated turbomachinery suppliers capable of subsea-to-surface system bundling.
Growth Catalysts
- OSHA-process-safety enforcement:US onshore operators face mandatory vapor-recovery unit retrofits under EPA methane-emission rules, accelerating separator replacement cycles in the Permian and Bakken basins.
- Gravity separation reliability:Tolerance for high solids loading without chemical injection keeps installed base volumes elevated in shale plays where produced water carries proppant and drilling fines.
- Norway NORSOK certification tiers:Third-party witness-test protocols for high-pressure vessels filter substandard fabricators, protecting margin pools for qualified suppliers in North Sea developments.
Market Restraints
- Duplex stainless steel price volatility:Nickel and molybdenum input costs swing with London Metal Exchange futures, compressing fabrication margins on fixed-price EPC contracts.
- US Gulf Coast yard concentration:Heavy-wall pressure vessel welding capacity clusters along the Texas-Louisiana corridor, creating queue bottlenecks during offshore project sanctioning waves.
- Electrostatic separation capex threshold:Emulsion-breaking hardware requires 40% higher upfront investment than gravity units, limiting adoption to premium-margin operations where throughput economics justify outlay.
Strategic Opportunities
- Brazil pre-salt cluster:ANP certification requirements for ultra-deepwater separators create captive demand for fabricators with subsea pressure-rating experience in the Santos Basin.
- Digital twin integration:Real-time level control and predictive maintenance modules command software-recurring revenue streams atop hardware sales.
- Modular skid-mounted delivery:Remote basin developments in West Africa and Central Asia favor site-constrained logistics over field-erected vessels, opening new channel partnerships with drilling contractors.
Industry Challenges
- ASME Section VIII weld inspector scarcity:Qualified radiographic testing technicians command premium wages, extending fabrication schedules at peak demand periods.
- Legacy SCADA integration:Brownfield separators require protocol translation layers to connect new digital monitoring retrofits with existing distributed control systems, inflating commissioning costs.
- Reservoir pressure uncertainty:Build-to-spec contracting conflicts with performance-guarantee models as shale decline curves and secondary recovery timelines shift design-pressure assumptions mid-project.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Pressure Oil and Gas Separators Market |
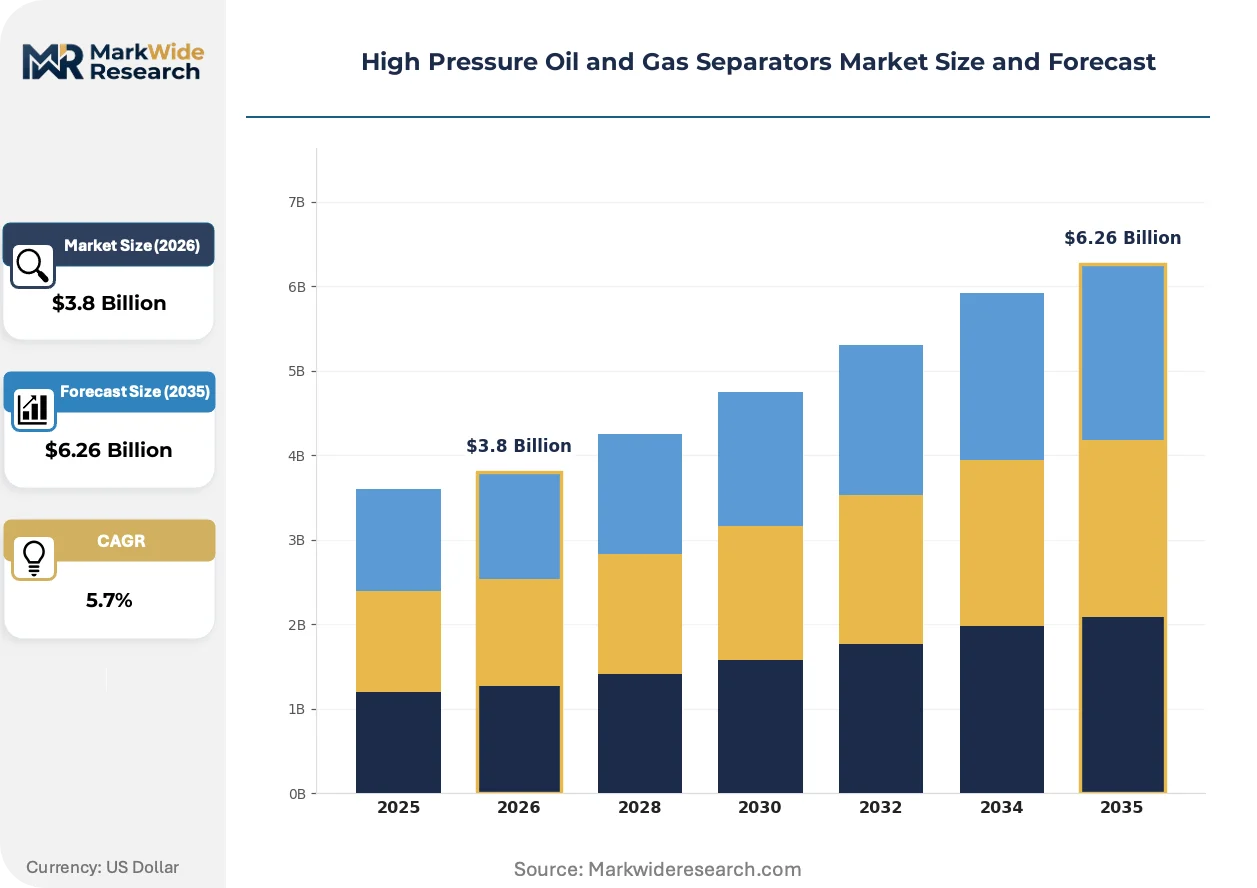
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Three-Phase Separator, Two-Phase Separator, Condensate Stabilizer, Test Separator Technology: Gravity Separation, Electrostatic Separation, Centrifugal Separation, Membrane Separation End User: Oil Producers, Gas Producers, Refineries, Petrochemical Companies Installation Type: Onshore, Offshore, Modular, Custom-built |
| Companies Covered | Schlumberger Limited, Baker Hughes Company, TechnipFMC plc, Halliburton Company, Sulzer Ltd., National Oilwell Varco, Frames Group BV, Exterran Corporation, Aker Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Pressure Oil and Gas Separators Market Emerging Trajectories
Separator architecture is converging around real-time monitoring architectures and predictive analytics, compressing the traditional divide between mechanical separation hardware and process control software.
Digital twin platforms are digitizing asset-life valuation for high-pressure vessels by integrating pressure-cycle fatigue models with live corrosion-rate telemetry from internal probes. Offshore operators in the US Gulf of Mexico deploy these systems to extend inspection intervals beyond API 510 mandatory schedules. The technology is digitizing procurement criteria, shifting buyer evaluation from upfront capex to total lifecycle cost models that incorporate predictive maintenance savings.
EPA methane-emission rules are mandating vapor-recovery unit attachment rates above 95% for new onshore separator installations, with OSHA-process-safety inspectors cross-checking relief-valve capacity calculations during commissioning. This regulatory compression is elevating engineering documentation requirements and extending pre-approval timelines by 4-6 months. Fabricators lacking in-house emissions-compliance expertise are ceding share to integrated turbomachinery suppliers with captive vapor-recovery engineering.
After-sales service unbundling is fragmenting the traditional EPC bundled model, with shale basin operators procuring level control systems, mist extractor replacements, and separator internals through separate MRO channels rather than original equipment manufacturers. Digital parts-catalog platforms are capturing this disintermediation, particularly in the Permian where drilling contractors prioritize 24-hour spares availability over OEM loyalty. The shift is most visible among independent producers operating sub-50 well programs without captive maintenance crews.
High Pressure Oil and Gas Separators Market Segmentation
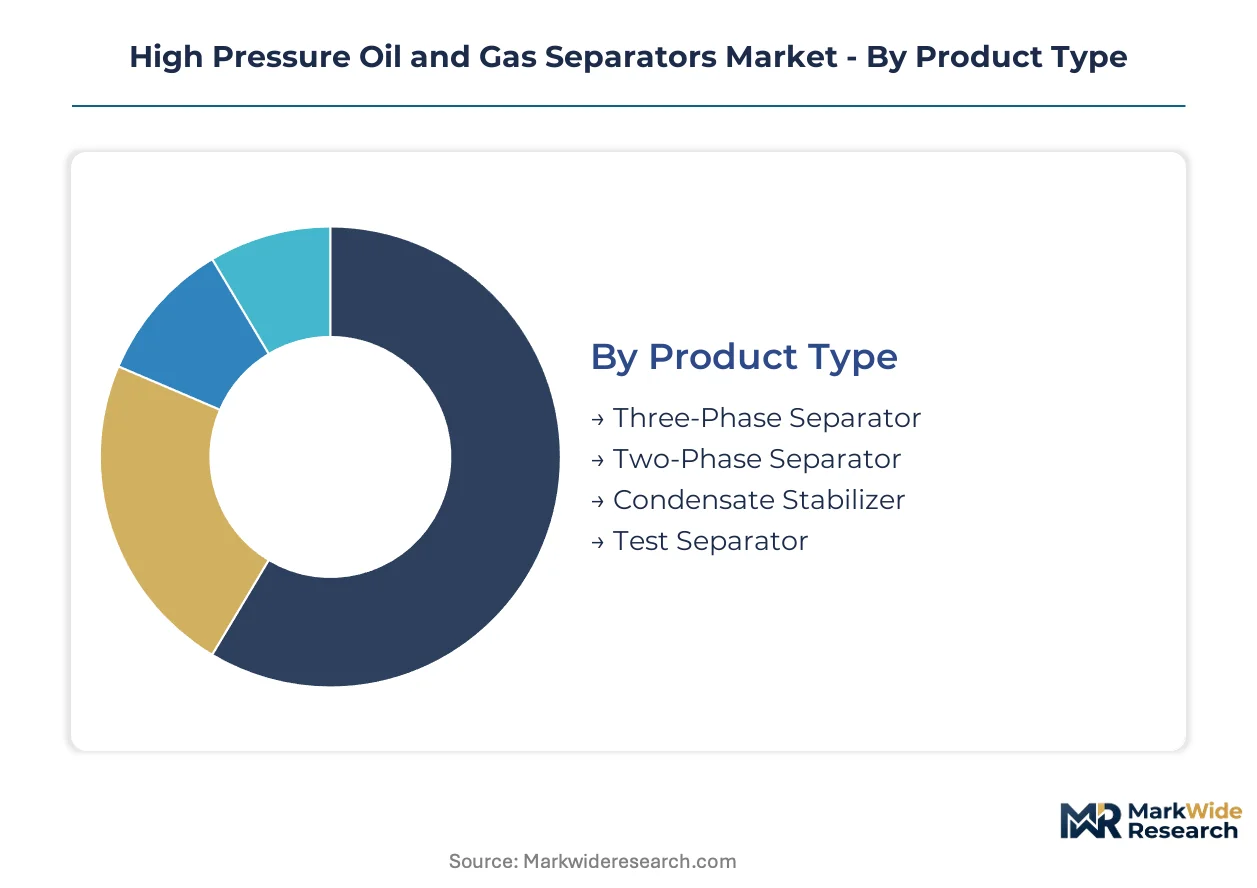
High pressure separator procurement varies sharply by reservoir chemistry, pressure profiles, and regulatory exposure across upstream and midstream operations. Segment selection determines capex intensity, certification burden, and aftermarket service attach rates.
Product Type:
Upstream operators match vessel configuration to produced fluid ratios and custody transfer requirements.
- Three-Phase Separator:Simultaneous partitioning of oil, gas, and water phases through internal weir plates and level control systems. Demand concentrates in US Permian and Bakken shale plays where high water cuts require continuous water removal to meet pipeline specifications.
- Two-Phase Separator:Simplified gas-liquid separation without dedicated water outlets, common in dry gas fields and early-stage oil developments. Operators in the Denver-Julesburg basin favor these units for lean gas processing where liquid volumes remain marginal.
- Condensate Stabilizer:Flash separation and vapor recovery to reduce Reid Vapor Pressure for transport compliance.
- Test Separator:Portable well testing units for reservoir characterization and allocation metering.
Established volume favors Three-Phase Separator; emerging adoption favors Condensate Stabilizer.
Technology:
Cost tiers separate mature gravity systems from premium electrostatic units where emulsion economics justify outlay.
- Gravity Separation:Density-driven phase partitioning without chemical injection or energy input, tolerant of high solids loading from proppant and drilling fines. Dominates Permian and Eagle Ford installations where produced water carries abrasive particulates.
- Electrostatic Separation:High-voltage fields break stable emulsions to accelerate water-oil separation, cutting residence time by 60% versus gravity units. Deepwater Gulf of Mexico operators specify these for high-pressure subsea tiebacks where platform footprint constraints limit vessel sizing.
- Centrifugal Separation:Rotational acceleration for compact footprint applications.
- Membrane Separation:Emerging ceramic and polymeric barriers for ultra-fine droplet removal.
Gravity Separation retains the largest installed base; Electrostatic Separation commands the steepest expansion trajectory in offshore procurement.
End User:
Customer type dictates specification stringency, from wellhead operators to integrated refiners with captive engineering.
- Oil Producers:Upstream operators focused on crude stabilization and basic sediment and water reduction. Independent shale producers in the Midland basin prioritize modular delivery and rapid deployment cycles over custom engineering.
- Gas Producers:Dry gas and associated gas processors requiring dew point control and liquid recovery. Marcellus and Haynesville operators drive demand for high-pressure gas-gas separation ahead of pipeline interconnections.
- Refineries:Downstream desalting and preflash vessel replacement programs.
- Petrochemical Companies:Feedstock purification for ethylene crackers and derivative units.
Oil Producers generate the heaviest replacement demand; Gas Producers are expanding most quickly on LNG export-linked infrastructure.
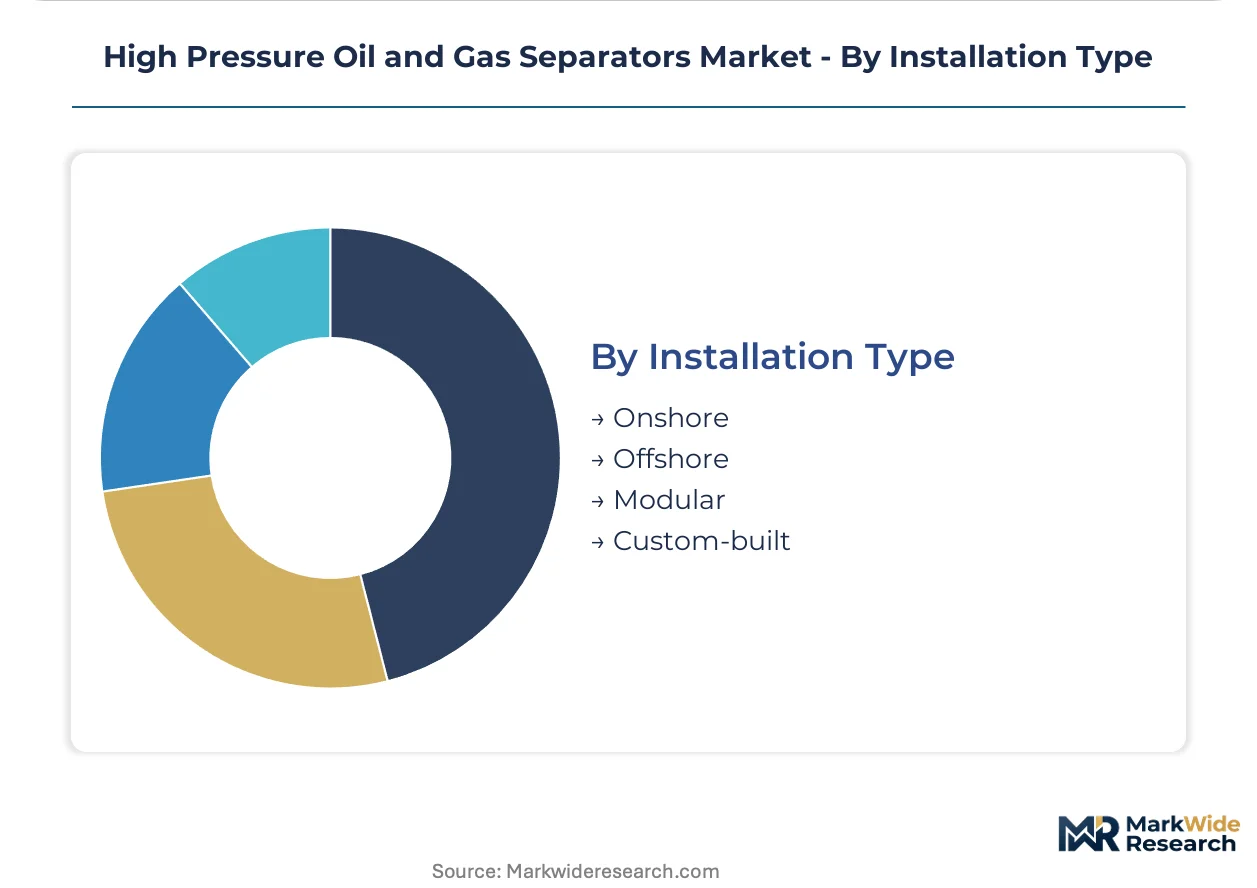
Installation Type:
Site logistics and regulatory jurisdiction determine field-erected versus skid-mounted procurement paths.
- Onshore:Fixed installations at well pads, central gathering facilities, and tank batteries. Texas and New Mexico regulators enforce API 12J and EPA vapor recovery standards, driving retrofit demand across legacy Permian infrastructure.
- Offshore:Platform-mounted and subsea pressure vessels rated for marine corrosion and dynamic loading. Brazil ANP certification requirements filter fabricator access for pre-salt developments in the Santos Basin.
- Modular:Factory-assembled skid packages for remote basin logistics.
- Custom-built:Project-specific engineering for unique pressure-temperature combinations.
Onshore maintains the deepest installed base; Modular is gaining share fastest in West Africa and Central Asia developments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated turbomachinery buyers concentrate procurement decisions among capital-heavy incumbents with subsea-to-surface bundling capabilities. Fabrication yard queues and certification tier requirements filter supplier access across producing basins.
United States
Permian Basin operators drive replacement cycles for three-phase separators under EPA methane-emission enforcement. OSHA-process-safety inspectors cross-check API 12J relief-valve calculations during commissioning. Gulf Coast fabrication yards from Houston to Lake Charles cluster heavy-wall pressure vessel welding capacity for offshore project waves.
Brazil
Pre-salt developments in the Santos Basin generate captive demand for ultra-deepwater separators with subsea pressure ratings. ANP certification tiers mandate third-party witness-test protocols that filter fabricator access. Rio de Janeiro engineering centers anchor procurement decision-making for Petrobras-led project clusters.
Norway
North Sea electrification timelines accelerate separator refresh cycles on aging platforms. NORSOK standards govern high-pressure vessel design pressure and corrosion allowance specifications. Stavanger and Bergen engineering hubs concentrate subsea system integration expertise for Equinor developments.
China
Shale gas developments in Sichuan Basin expand domestic separator demand for high-pressure gas processing. GB standards and MIIT equipment certification shape procurement criteria for state-owned operators. Yangtze River Delta fabrication clusters supply both domestic projects and export contracts across Central Asia.
United Arab Emirates
ADNOC sour gas expansion programs require separators rated for high hydrogen sulfide content and extreme pressure profiles. The country's national petroleum regulator enforces vessel integrity management standards aligned with international pressure equipment codes. Abu Dhabi engineering centers coordinate procurement for offshore Upper Zakum redevelopment phases.
High Pressure Oil and Gas Separators Market Vendor Landscape
Channel-controlling players compete with product-specialist players across segmented procurement paths. Integrated turbomachinery suppliers anchor offshore project bids through subsea-to-surface system bundling, while modular fabricators capture remote basin demand through skid-mounted delivery partnerships. The market structures around three archetypes: capital-heavy incumbents with captive engineering, regional fabricators with certification tier access, and digital-integrated specialists with predictive maintenance platforms. Dominant competitive moves include capacity expansion at Gulf Coast fabrication yards and technology licensing for digital twin integration modules.
Among US-based integrated service providers, Baker Hughes Company and Halliburton Company exemplify the turbomachinery-bundling archetype with subsea-to-surface system integration capabilities. Schlumberger Limited occupies a position representing the digital-integrated tier through real-time monitoring and predictive analytics platforms. These three anchors illustrate how procurement power concentrates among capital-heavy incumbents capable of performance-guarantee contracting across deepwater developments.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Baker Hughes Company |
| TechnipFMC plc |
| Halliburton Company |
| Sulzer Ltd. |
| National Oilwell Varco |
| Frames Group BV |
| Exterran Corporation |
| Aker Solutions |
| Others |
Supply Flow & Price Mechanics
Houston-Galveston fabrication yard queues compress pricing power for high-pressure vessel delivery slots, with backlog visibility extending 18-24 months during offshore sanctioning waves. Duplex stainless steel input cost volatility feeds directly into fixed-price EPC contract margin compression, while API 12J certification tiers stratify supplier access and sustain premium capture for qualified fabricators.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with NORSOK and ANP witness-test protocols commanding 25-35% uplifts over baseline API 12J units. Three-tier pricing structure across premium certified, standard compliant, and economy modular levels reflects welding procedure qualification depth and third-party inspection documentation. Cost compression in the economy tier is intensifying because shale basin operators prioritize rapid deployment over custom engineering. Independent Permian producers exhibit highest price sensitivity, while deepwater Gulf of Mexico operators accept premium positioning for performance-guarantee contracting.
Supply Chain Analysis
Extended payment terms from integrated turbomachinery buyers stretch fabricator working capital, with supply-chain finance facilities increasingly anchoring raw material procurement for nickel and molybdenum alloy plate. Manufacturing gravity centers on the United States Gulf Coast, China Yangtze River Delta, and Norway Stavanger-Bergen corridor. Heavy-wall pressure vessel welding draws from certified ASME Section VIII inspector pools, duplex stainless steel mill capacity, and subsea connector forging operations. Single-source vulnerability concentrates in specialist radiographic testing technician availability. Distribution runs through EPC prime contractors, OEM captive channels, and digital MRO platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around API 12J, NORSOK, and ANP certification tiers constructs formidable defensive moats for incumbent fabricators with established witness-test protocols and qualified weld procedure libraries.
For Market Incumbents: Harden certification-tier dominance by accelerating NORSOK and ANP third-party witness-test capacity expansion in Stavanger and Rio de Janeiro engineering centers. Deepen backward integration into duplex stainless steel plate processing to offset London Metal Exchange volatility exposure. Digital-native competitors threaten aftermarket service unbundling through predictive maintenance platforms. For New Entrants and Emerging Players: Build out modular skid-mounted delivery capabilities for remote basin developments in West Africa and Central Asia, where site-constrained logistics favor factory-assembled packages over field-erected vessels. Digital twin integration modules represent the most penetrable white-space, commanding software-recurring revenue streams atop commodity hardware sales. Partner with drilling contractors for channel access rather than competing directly for EPC prime contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors digital-integrated specialists with predictive maintenance platforms and real-time monitoring architectures. Long-term viability hinges on separator-as-a-service business model transition and lifecycle cost contracting adoption. Watch digital twin attach rates at brownfield retrofit installations as inflection indicator for platform valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Capacity Expansion | NORSOK and ANP witness-test protocols filter substandard fabricators from North Sea and Brazil pre-salt developments. |
| Digital Twin Platform Development | Real-time corrosion telemetry extends inspection intervals beyond API 510 mandatory schedules for offshore operators. |
| Modular Skid-Mounted Delivery | Factory-assembled packages overcome site-constrained logistics in remote West Africa and Central Asia basins. |
| Backward Integration into Alloy Processing | In-house duplex stainless steel plate processing mitigates nickel and molybdenum price volatility exposure. |
| Aftermarket Service Unbundling | Separate MRO channels for level control systems and mist extractor replacements capture Permian drilling contractor demand. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and project development databases. Interviews with pressure vessel fabrication managers, EPC procurement leads, offshore project engineers, and aftermarket service directors inform operational dynamics. Secondary validation draws from API certification records, ASME stamp holder directories, EPA enforcement actions, and ANP project registries. Bottom-up unit economics triangulate against top-down capex forecasts across shale basin and deepwater development pipelines.
Forecast inputs incorporate reservoir pressure decline curves, offshore sanctioning wave timing, and regulatory compliance retrofit cycles across the projection horizon. Segmentation dimensions model product type, technology tier, end-user category, and installation configuration alongside certification jurisdiction clustering. CAGRs derive from production growth assumptions, replacement cycle acceleration under methane-emission enforcement, and modular adoption penetration in remote basins. Vapor-recovery unit attachment rate mandates and digital twin retrofit penetration serve as industry-specific demand drivers.
Practitioners should monitor regulatory enforcement intensity, raw material price volatility, and qualified inspector availability for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Abyssinian Oil Market
Offshore Oil and Gas
Oil and Gas Fishing Market
Offshore Oil and Gas
Global Floating LNG Power Vessel Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Downstream Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Upstream Market
Offshore Oil and Gas
Europe Floating Offshore Wind Power Market
Offshore Oil and Gas
Norway Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
China Oil and Gas Downstream Market
Offshore Oil and Gas
Canada Oil and Gas Downstream Market
Offshore Oil and Gas
Europe Jackup Rig Market
Offshore Oil and Gas
Jack-Up Rigs Market
Offshore Oil and Gas
Offshore Remote Monitoring Solutions Market
Offshore Oil and Gas
Denmark Oil and Gas Market
Offshore Oil and Gas
Offshore Contract Drilling Market
Offshore Oil and Gas
Equatorial Guinea Oil and Gas Midstream Market