
 Europe Biomass Gasification Market | 2026-2036
Europe Biomass Gasification Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Biomass Gasification Market Intelligence
The capital-intensity divergence between small-scale modular providers and large integrated engineering houses is collapsing as project finance models standardize across the continent. Valmet Corporation leverages its pulp-and-paper equipment heritage to dominate fluidized bed reactor deployments in Nordic utility markets. BIOS Bioenergiesysteme GmbH specializes in fixed bed systems for agricultural residue processing, anchoring its position across Central European biogas clusters.
Biomass gasification converts solid organic feedstock into combustible syngas through partial oxidation at temperatures typically ranging from 700°C to 1,500°C, with the resulting gas mixture of hydrogen, carbon monoxide, and methane serving as a platform for power generation, chemical synthesis, or biofuel production. Fluidized bed technology leads installed capacity due to superior feedstock flexibility and thermal efficiency, while entrained flow systems command premium project values for large-scale chemical production applications. Agricultural residues represent the fastest-expanding feedstock category as EU waste hierarchy regulations tighten landfilling restrictions and incentivize circular valorization pathways.
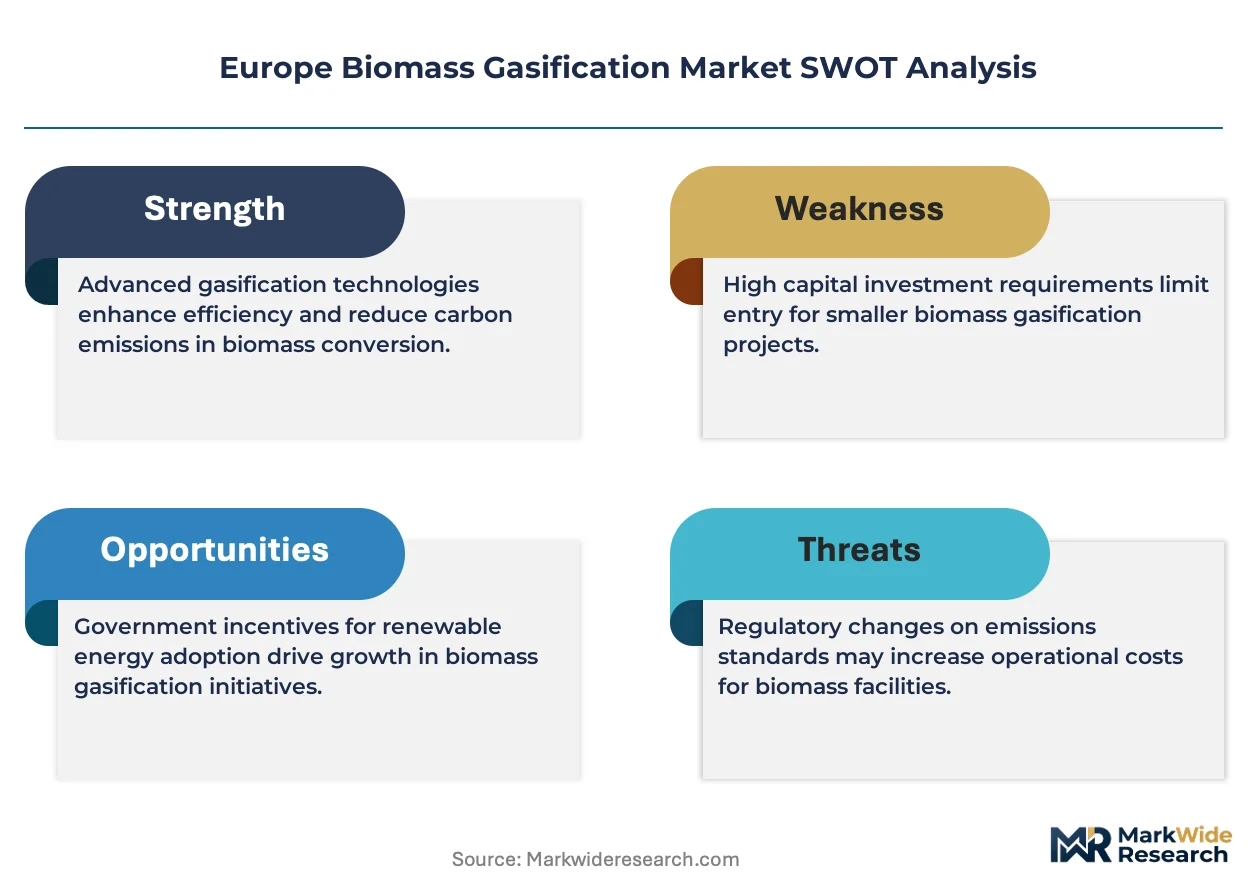
The EU Green Deal and F-Gas Regulation are reshaping compliance requirements for industrial heat users, while ECHA's REACH framework governs syngas contaminant thresholds and byproduct handling protocols. Germany's national carbon pricing scheme and the Netherlands' SDE++ subsidy program are accelerating project economics for biomass-to-hydrogen configurations. Stakeholders must monitor evolving sustainability certification criteria under the EU Renewable Energy Directive and assess feedstock traceability risks before committing to long-term offtake agreements.
Market Dynamics
The EU Green Deal's carbon pricing mechanisms are compressing project economics for fossil fuel alternatives while standardizing power purchase agreement structures across Nordic and Central European utility markets.
Growth Catalysts
- EU ETS Carbon Pricing:The EU Emissions Trading System's tightening allowance caps are forcing industrial heat users toward syngas-based alternatives. Steel and cement manufacturers in Germany and the Netherlands are accelerating offtake negotiations.
- District Heating Modernization:Scandinavian municipal utilities are retrofitting legacy combined heat and power plants with biomass gasification trains. Finland and Sweden lead deployment velocity through established district heating infrastructure.
- Agricultural Residue Mandates:The EU Waste Framework Directive's landfill diversion targets are channeling straw and forestry slash into gasification feedstock streams. Central European biogas clusters are expanding upstream into thermochemical conversion.
Market Restraints
- Feedstock Supply Concentration:Seasonal agricultural residue availability concentrates procurement risk in Poland and Romania's grain belts. Silage and storage infrastructure gaps create supply discontinuities.
- Tar Reforming Complexity:Biomass-derived syngas requires intensive cleanup to meet Fischer-Tropsch catalyst specifications. Entrained flow systems face operational penalties from alkali metal contamination.
- Natural Gas Price Volatility:European benchmark TTF hub fluctuations distort biomass gasification competitiveness. Project developers struggle to underwrite long-term offtake contracts against fossil fuel price uncertainty.
Strategic Opportunities
- Biohydrogen Production:Water-gas shift reactors paired with gasification trains enable renewable hydrogen output. The Netherlands' SDE++ subsidy program specifically incentivizes biomass-to-hydrogen configurations.
- Carbon Capture Integration:Negative emission pathways through bioenergy with carbon capture and storage are qualifying for enhanced EU Innovation Fund support. Nordic saline aquifer geology favors project siting.
- Power-to-X Convergence:Syngas methanation and e-fuel synthesis are merging with electrolytic hydrogen streams. German industrial clusters in the Rhine-Ruhr corridor are piloting hybrid production trains.
Industry Challenges
- Tar Cracking Engineering Shortage:Fluidized bed reactor operators face recruitment gaps for high-temperature gas conditioning specialists. Vocational training programs in thermochemical conversion remain underdeveloped across Central Europe.
- REACH Compliance Documentation:ECHA's registration requirements for syngas contaminants and byproduct characterization impose multi-year certification timelines. Smaller developers lack toxicology dossier preparation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Biomass Gasification Market |
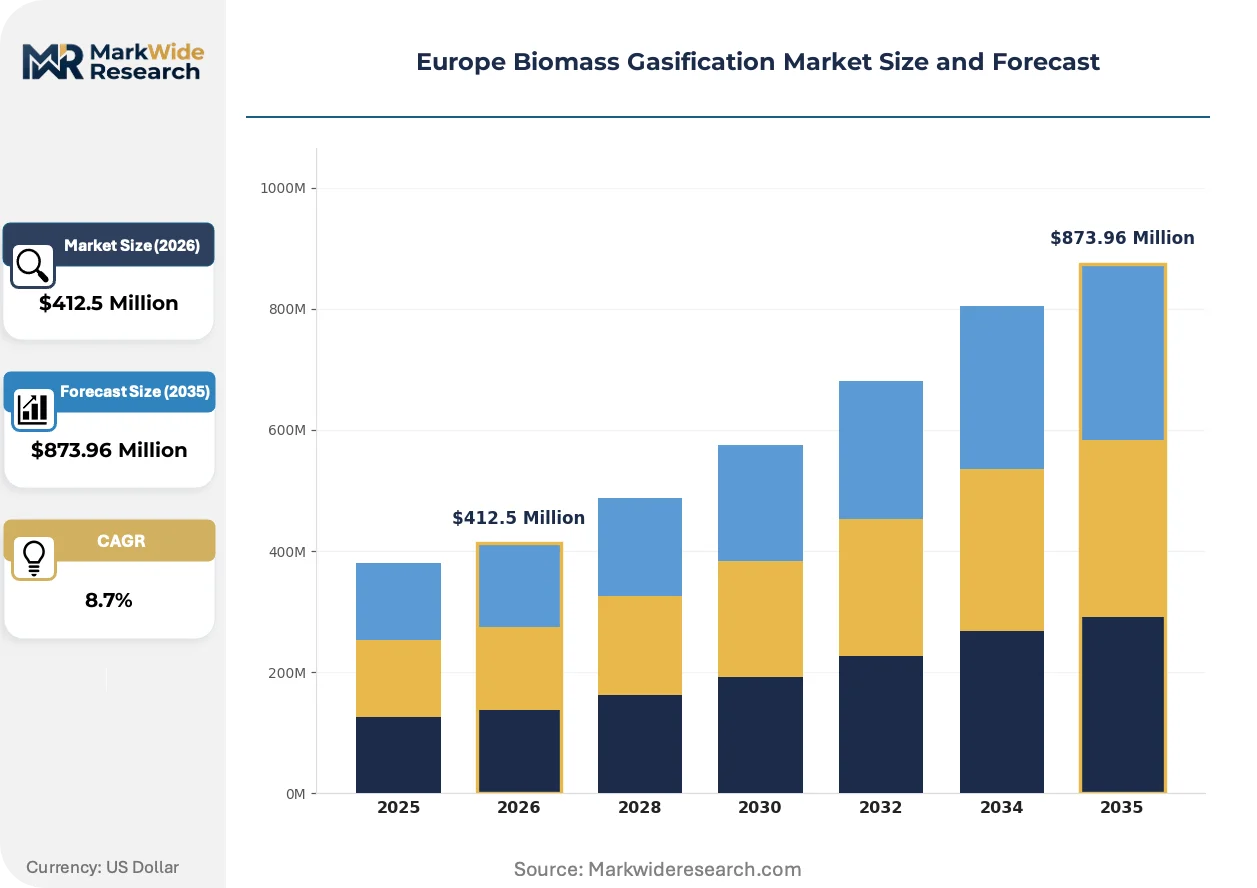
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Fixed Bed, Fluidized Bed, Entrained Flow, Pyrolysis Feedstock Type: Wood Chips, Agricultural Residues, Animal Manure, Energy Crops End User: Power Generation, Chemical Production, Transportation Fuels, Heating Application: Electricity Generation, Syngas Production, Biofuels, District Heating |
| Companies Covered | KASAG Swiss AG, Syncraft, Valmet Corporation, BIOS Bioenergiesysteme GmbH, ReGaWatt GmbH, Thyssenkrupp AG, Bio Energy Netherlands BV, WtEnergy, EQTEC plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Biomass Gasification Market Strategic Shifts & Innovations
Technology convergence between gasification and carbon capture is restructuring project development priorities. Regulatory pressure on industrial emissions is accelerating process intensification investments.
Dual fluidized bed gasification technology is fragmenting the competitive landscape between steam-blown and oxygen-blown configurations. Valmet Corporation and ANDRITZ are deploying steam-blown systems for district heating applications, while chemical producers specify oxygen-blown entrained flow reactors for methanol synthesis. The technology split is compressing equipment supplier margins as buyers demand feedstock-flexible designs spanning both thermal regimes.
EU F-Gas Regulation amendments are phasing down hydrofluorocarbon use in syngas cooling and refrigeration circuits. Industrial gas users must retrofit or replace fluorinated gas-based heat exchangers with ammonia or CO2 alternatives. German chemical parks in Ludwigshafen and Leverkusen are front-running compliance through early equipment substitution programs.
Utility procurement departments are unbundling engineering-procurement-construction contracts from long-term operation and maintenance agreements. Finnish and Swedish district heating authorities now separate technology selection from service provider appointments. This bifurcation is compressing vendor lock-in duration and forcing equipment suppliers to compete on aftermarket service pricing.
Europe Biomass Gasification Market Segmentation
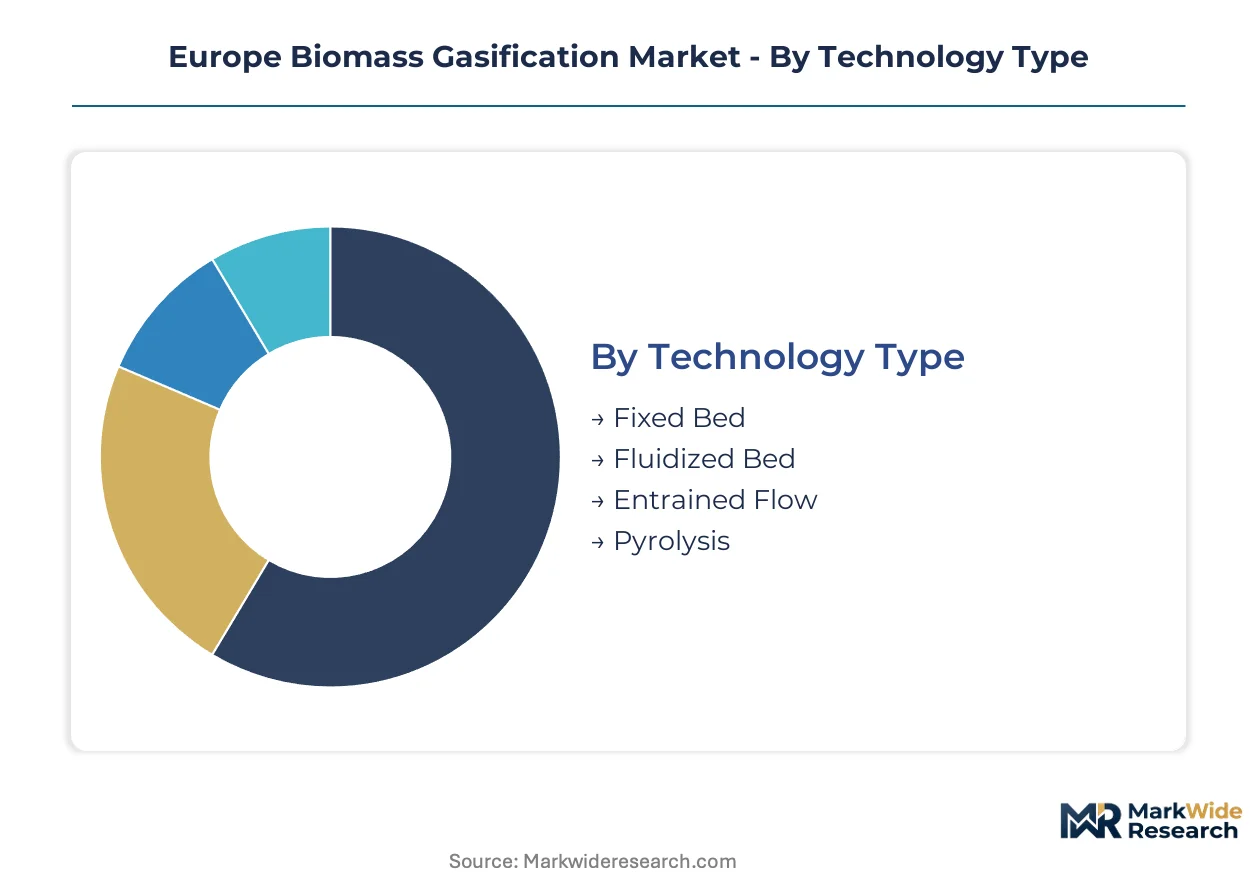
Segmentation reveals how technology maturity, feedstock logistics, and end-use economics stratify competitive returns across European biomass gasification. Each dimension carries distinct regulatory exposure and capital intensity profiles that reshape vendor positioning.
Technology Type:
Fixed bed systems face intensifying substitution pressure from fluidized bed alternatives as feedstock flexibility becomes the decisive procurement criterion for utility buyers.
- Fluidized Bed:Circulating and bubbling bed configurations achieve superior thermal efficiency and fuel adaptability across moisture content ranges. Finnish and Swedish district heating operators specify these systems for wood chip and agricultural residue co-firing. Valmet Corporation dominates Nordic deployments through pulp-and-paper equipment heritage and established service networks.
- Fixed Bed:Updraft and downdraft reactors operate at lower capital cost with simpler mechanical design. Central European agricultural clusters in Germany and Poland favor these units for straw and energy crop processing where feedstock consistency permits. BIOS Bioenergiesysteme GmbH anchors market presence across German biogas corridors.
- Entrained Flow:High-temperature oxygen-blown reactors serve chemical synthesis applications requiring tar-free syngas.
- Pyrolysis:Fast pyrolysis systems yield bio-oil intermediates for subsequent gasification or direct combustion.
Fluidized bed retains volume leadership; entrained flow holds the steepest expansion curve as chemical producers scale bio-based production.
Feedstock Type:
Cost tier stratification separates premium wood chip supply chains from emerging agricultural residue streams competing on circular economy compliance value.
- Agricultural Residues:Straw, corn stover, and forestry slash face tightening EU Waste Framework Directive landfill diversion mandates. Polish and Romanian grain belts concentrate seasonal availability, creating procurement risk for continuous reactor operation. Storage infrastructure gaps and moisture management dominate project feasibility assessments.
- Wood Chips:Forest residues and processed woody biomass deliver consistent calorific value and established supply chains. Nordic forestry economies in Finland and Sweden leverage existing harvesting logistics for district heating feedstock security. Sustainability certification under EU Timber Regulation governs import eligibility.
- Animal Manure:Dairy and poultry operations in the Netherlands and Denmark supply high-nitrogen feedstock for biogas-to-gasification integration.
- Energy Crops:Dedicated miscanthus and switchgrass cultivation competes with food production for arable land allocation.
Wood chips retain volume leadership; agricultural residues are expanding most quickly as landfill restrictions tighten across Central Europe.
End User:
Application maturity diverges sharply between established power generation buyers and emerging transportation fuel offtakers navigating certification complexity.
- Power Generation:Combined heat and power plants and dedicated biomass facilities purchase syngas for turbine combustion or engine fueling. German industrial clusters in the Rhine-Ruhr corridor retrofit coal plants for biomass gasification compliance with national carbon pricing. Baseload power purchase agreements anchor project finance structures.
- Chemical Production:Methanol, ammonia, and synthetic fuel manufacturers specify entrained flow syngas for Fischer-Tropsch synthesis. Dutch chemical parks in Rotterdam and Antwerp pilot biomass-to-hydrogen configurations under SDE++ subsidy eligibility. Catalyst contamination tolerance dictates gas cleanup investment levels.
- Transportation Fuels:Renewable diesel and jet fuel producers face EU Renewable Energy Directive sustainability verification requirements.
- Heating:Industrial process heat users in cement and steel sectors evaluate syngas against electrification alternatives.
Power generation retains volume leadership; chemical production commands the steepest expansion trajectory as industrial decarbonization accelerates.
Application:
Customer type concentration separates utility procurement departments seeking standardized equipment packages from industrial buyers demanding integrated process design.
- District Heating:Municipal utilities in Finland, Sweden, and Denmark retrofit legacy CHP infrastructure with gasification trains for renewable heat compliance. Established district heating networks enable direct syngas combustion without grid injection complexity. Finnish and Swedish procurement authorities now unbundle EPC contracts from O&M agreements.
- Syngas Production:Merchant syngas suppliers sell into chemical and fuel synthesis markets requiring contaminant specifications. German industrial clusters concentrate demand for standardized syngas quality grades. Water-gas shift reactor integration enables hydrogen fraction enhancement for ammonia and methanol feedstock.
- Electricity Generation:Grid-connected biomass facilities compete against offshore wind and solar PPA pricing.
- Biofuels:Renewable transport fuel production faces EU F-Gas Regulation compliance for process cooling circuits.
District heating retains volume leadership; syngas production is gaining share fastest as chemical sector offtake agreements multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across European markets. Scandinavian utilities exhibit low price sensitivity due to established carbon pricing acceptance, while Central European agricultural processors face acute feedstock cost pressures that compress project margins.
Germany
Industrial heat users in the Rhine-Ruhr corridor drive syngas demand for cement and steel decarbonization. The national carbon pricing scheme forces coal plant retrofits toward biomass gasification compliance. Chemical parks in Ludwigshafen and Leverkusen pilot integrated biohydrogen production trains.
Netherlands
Rotterdam-Antwerp chemical clusters concentrate demand for entrained flow syngas in methanol synthesis applications. The SDE++ subsidy program specifically incentivizes biomass-to-hydrogen configurations. Dutch dairy operations in Gelderland supply high-nitrogen feedstock for biogas-to-gasification integration.
Sweden
Municipal utilities retrofit legacy combined heat and power infrastructure with gasification trains for renewable heat compliance. The EU ETS tightening accelerates offtake negotiations from pulp-and-paper integrated sites. Stockholm district heating authorities unbundle EPC contracts from long-term O&M agreements.
Finland
Forest residue harvesting logistics enable wood chip supply security for baseload power generation. Finnish procurement departments standardize fluidized bed specifications across utility portfolios. Helsinki metropolitan district heating networks enable direct syngas combustion without grid injection complexity.
Poland
Seasonal straw availability in the grain belt creates procurement risk for continuous reactor operation. EU Waste Framework Directive landfill diversion mandates channel agricultural residues into thermochemical conversion. Lodz industrial clusters evaluate gasification against electrification alternatives for process heat.
Europe Biomass Gasification Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier that dominates fixed-bed and modular deployments. The upper tier commands project finance access through established utility relationships, while specialists compete on feedstock flexibility and aftermarket service pricing. Three archetypes define the field: Nordic engineering houses with pulp-and-paper heritage, Central European agricultural residue specialists, and industrial conglomerates with chemical process capabilities. Competitive moves concentrate on technology licensing partnerships and unbundled service contract capture.
Among Nordic integrated providers, Valmet Corporation anchors the fluidized bed reactor segment through established district heating utility relationships. BIOS Bioenergiesysteme GmbH exemplifies the Central European specialist archetype focused on agricultural residue processing systems. Thyssenkrupp AG occupies a position bridging industrial engineering scale with chemical sector process integration. These three represent distinct competitive vectors: utility heritage, feedstock specialization, and industrial conglomerate diversification.
| Leading Market Players |
|---|
| KASAG Swiss AG |
| Syncraft |
| Valmet Corporation |
| BIOS Bioenergiesysteme GmbH |
| ReGaWatt GmbH |
| Thyssenkrupp AG |
| Bio Energy Netherlands BV |
| WtEnergy |
| EQTEC plc |
| Others |
Cost & Logistics Intelligence
Capacity utilization rates across Nordic fluidized bed reactor installations establish price floors that smaller Central European fixed-bed competitors struggle to match. German industrial clusters leverage scale economies in engineering-procurement-construction bundling to compress vendor margins, while agricultural residue processors in Poland and Romania face discontinuous procurement costs that feed back into equipment pricing tiers.
Pricing Analysis
Aftermarket service contracts and extended maintenance agreements generate lifetime value that exceeds initial equipment sales for established Nordic vendors. Project-based transactional pricing dominates EPC phase awards, with premium differentiation anchored in EU Renewable Energy Directive certification tiers and feedstock flexibility guarantees. Cost compression in standard fixed-bed configurations is intensifying as BIOS Bioenergiesysteme GmbH and ReGaWatt GmbH compete on agricultural residue processing economics. District heating utilities in Finland and Sweden exhibit lowest price sensitivity due to carbon pricing pass-through mechanisms, while Polish grain-belt processors face acute margin pressure from seasonal feedstock discontinuities.
Supply Chain Analysis
Strategic stockpiling of forestry residues and wood chips dominates Nordic procurement, while Central European operators favor just-in-time agricultural residue collection constrained by silage windows. Feedstock supply concentrates in Finland, Sweden, and Poland, with reactor fabrication drawing from German engineering clusters and Austrian precision manufacturing. Single-source vulnerability in high-temperature ceramic refractory supply creates operational risk for entrained flow deployments. Distribution runs through utility procurement consortia in Scandinavia and chemical park operator networks in the Netherlands and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrolytic hydrogen cost curves pose a substitution threat that biomass-to-hydrogen configurations must outrun through carbon-negative positioning and integrated carbon capture economics.
For Market Incumbents: Shield installed base relationships in Finnish and Swedish district heating networks through predictive maintenance service bundling and feedstock-flexible reactor upgrades. Deepen backward integration into forestry residue harvesting logistics to secure cost-advantaged wood chip supply chains against agricultural residue price volatility. Anchor defensive positioning against power-to-X convergence by accelerating biohydrogen certification under EU Renewable Energy Directive sustainability criteria. For New Entrants and Emerging Players: Aftermarket service capacity gaps in tar reforming engineering and high-temperature gas conditioning present white-space opportunities for specialized technical service providers. Target Poland and Romania's agricultural processing corridors with modular fixed-bed systems configured for straw and corn stover seasonality. Pursue go-to-market partnerships with existing biogas cluster operators expanding upstream into thermochemical conversion. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated engineering houses with established utility relationships and captive service revenue streams over pure-play equipment vendors. Long-term viability hinges on carbon capture integration capabilities and EU Innovation Fund qualification for negative emission pathways. Watch for inflection when Rotterdam-Antwerp chemical cluster offtake agreements for biomass-derived methanol and ammonia reach critical mass.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | EU Innovation Fund qualification unlocks enhanced subsidy support for Nordic saline aquifer projects. |
| Feedstock Flexibility Engineering | Valmet Corporation's fluidized bed adaptability across moisture ranges secures utility procurement preference. |
| Aftermarket Service Unbundling | Finnish and Swedish district heating authorities now separate EPC awards from long-term O&M contracts. |
| Biohydrogen Certification | Netherlands SDE++ subsidy eligibility requires documented renewable hydrogen output from gasification trains. |
| Agricultural Residue Logistics | Polish and Romanian storage infrastructure investments determine continuous reactor operational economics. |
Research Approach
A spread of perspectives from utility planning officers, EPC contractors, agricultural cooperative managers, and chemical park operators converged on the working assumptions underlying demand projections. Primary fieldwork combined structured interviews with district heating procurement authorities and entrained flow reactor operators with secondary validation against EU ETS allowance auction data, national carbon pricing registry filings, and project development databases tracking SDE++ and EU Innovation Fund awards. Bottom-up capacity installation tallies triangulated against top-down energy transition scenario modeling.
Segmentation dimensions modeled span technology type, feedstock category, end-use application, and regional regulatory framework across the analysis window. CAGRs derive from installed capacity buildout trajectories, subsidy program budget envelopes, and industrial heat demand displacement curves. Forecast inputs incorporate EU Waste Framework Directive landfill diversion enforcement timelines and F-Gas Regulation amendment compliance deadlines for syngas cooling circuit retrofits.
Underlying assumptions cover EU ETS price corridor stability, agricultural residue collection infrastructure buildout rates, and entrained flow reactor commissioning timelines, with deviation risk concentrated in natural gas price volatility and REACH compliance documentation delays. Revision becomes warranted when electrolytic hydrogen production costs cross below biomass-to-hydrogen delivered cost thresholds in Rotterdam-Antwerp chemical cluster economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomass Energy Systems
Energy Harvesting Trees Market
Biomass Energy Systems
Europe Wood Pellet Heating Systems Market
Biomass Energy Systems
Modular Biomass Power Plant Market
Biomass Energy Systems
Global Biomass Power Market
Biomass Energy Systems
Global Biomass Market
Biomass Energy Systems
Global Wood Fuel Pellets Market
Biomass Energy Systems
Solar Bio-Gas Hybrid Power System Market
Biomass Energy Systems
Biomass Pellets Market
Biomass Energy Systems
Gasification Market
Biomass Energy Systems
North America Biomass Gasification Market
Biomass Energy Systems
Biomass Gasification Market
Biomass Energy Systems
Gasifier Market
Biomass Energy Systems
Biomass Power Generation Market