
 District Heating Market | 2026-2036
District Heating Market Size, Share, and Industry Trends Forecast 2026-2036
District Heating Market Analysis
Nordic utility operators is rebalancing generation portfolios toward biomass and waste heat recovery to replace retiring fossil assets. Fortum Oyj leverages its CHP footprint across Finland and the Baltic states to sustain baseload thermal output. Vattenfall AB anchors Nordic district cooling and heating synergies through integrated seawater and biomass plants. ENGIE SA competes in Eastern European retrofit markets with decentralized boiler-to-heat pump conversion programs.
District heating distributes thermal energy from centralized or decentralized generation plants to multiple buildings through insulated pipe networks, typically operating at supply temperatures between 80°C and 120°C for conventional systems and below 70°C for low-temperature fourth-generation networks. Its primary purpose is to replace individual building boilers with efficient, fuel-flexible communal heat supply that enables waste heat recovery from industry, data centers, and power generation. Biomass-fired centralized plants dominate capacity additions in Scandinavia and the Baltics where carbon taxation and forestry residue availability create structurally lower fuel costs. Smart grid system types are gaining fastest in new-build Nordic and Dutch networks where digital metering and demand-response algorithms unlock operational margin pools. Pipe network distribution infrastructure remains the most capital-intensive segment, with pre-insulated flexible piping from LOGSTOR A/S and others commanding premium pricing in retrofit corridors beneath dense urban streetscapes.
EU F-Gas Regulation phase-down schedules are forcing refrigerant choices in heat pump couplings to district loops, while Ecodesign and Energy Labelling frameworks mandate minimum seasonal performance factors for connected generation equipment. REACH compliance governs insulation foam chemistry in district pipe manufacturing, adding certification cost barriers for non-European suppliers. Stakeholders must monitor national building renovation wave fund disbursement timelines and local heat zoning ordinances that will determine which urban cores receive prioritized network extension capital.
Market Dynamics
The EU F-Gas Regulation phase-down is compressing refrigerant choices across heat pump couplings, while national building renovation wave funds are redirecting capital toward fourth-generation low-temperature networks. This dual regulatory-fiscal pressure is restructuring generation technology procurement and pipe network retrofit priorities simultaneously.
Growth Catalysts
- EU Green Deal building renovation targets:Member states must double renovation rates, channeling public capital into district heating extensions and fossil boiler replacements.
- Data center waste heat recovery:Hyperscale facilities in Denmark and Finland are signing long-term heat supply contracts with municipal utilities, converting cooling loads into revenue streams.
- Biomass fuel cost arbitrage:Scandinavian forestry residue supply chains deliver structurally lower thermal input costs versus imported natural gas.
Market Restraints
- Pre-insulated pipe input cost volatility:Polyurethane foam chemistry and steel prices fluctuate with petrochemical feedstock markets, squeezing contractor margins.
- Heat pump refrigerant supply concentration:F-Gas quotas restrict HFC availability, forcing equipment manufacturers toward CO2 and hydrocarbon alternatives with higher upfront engineering costs.
- Fourth-generation network temperature limitation:Sub-70°C distribution requires building-level heat pump installation, adding capital intensity to retrofit projects.
Strategic Opportunities
- Polish coal phase-out corridors:Silesian and Łódź urban agglomerations are replanning district heating around geothermal and biomass as mine closures accelerate.
- Seawater-source cooling-heating synergies:Coastal Nordic cities are integrating absorption chillers with district loops, capturing year-round thermal service revenue.
- Digital twin network optimization:Machine learning demand forecasting and predictive pipe maintenance are unlocking operational margin pools in Dutch and Danish smart grids.
Industry Challenges
- Fourth-generation hydraulic engineering talent scarcity:Low-temperature network design requires specialized thermohydraulic modeling skills that legacy district heating workforces lack.
- Building-level heat pump certification timelines:Ecodesign and Energy Labelling compliance testing creates procurement bottlenecks for retrofit projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | District Heating Market |
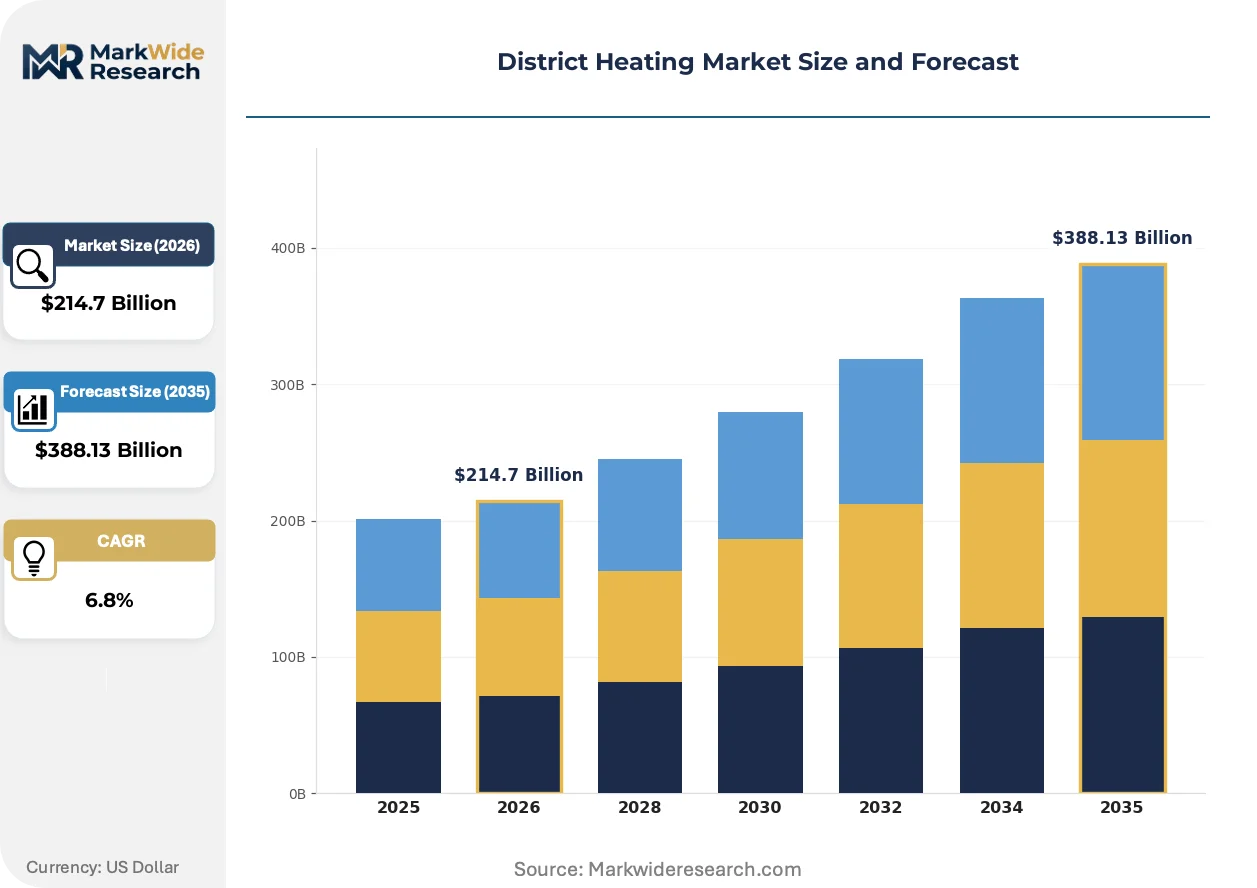
| Market Size in 2026 | $214.7 Billion |
| Market Size in 2035 | $388.13 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Source: Natural Gas, Biomass, Coal, Waste Heat Distribution Network: Pipe Networks, Radiant Systems, Direct Supply, Combined Systems End User: Residential, Commercial, Industrial, Institutional System Type: Centralized, Decentralized, Hybrid, Smart Grids |
| Companies Covered | Fortum Oyj, Vattenfall AB, ENGIE SA, Danfoss A/S, Statkraft AS, Veolia Environnement SA, Alfa Laval AB, Ramboll Group A/S, LOGSTOR A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
District Heating Market Emerging Trajectories
Electrification of heat generation is converging with digital grid management to compress operating temperatures and expand waste heat integration. These shifts are redefining competitive positioning around software-enabled thermal optimization rather than fuel sourcing alone.
Large-scale heat pumps using CO2 transcritical cycles are electrifying district heating supply in coastal German and Danish networks. Municipal utilities in Hamburg and Aarhus are deploying 50+ MW electric compressors to harvest seawater and wastewater heat. This technology is electrifying baseload thermal output that coal and gas CHP plants previously dominated, compressing fossil fuel procurement to peak shaving roles.
The EU F-Gas Regulation mandates an 80% HFC phase-down by 2030, forcing refrigerant transitions in heat pump couplings. Equipment manufacturers are accelerating R290 and CO2 system certification to maintain product eligibility. District heating projects in Germany and Poland face compressed procurement timelines as qualified heat pump supply tightens under quota constraints.
Energy-as-a-service contracting is displacing traditional capex-heavy utility ownership models. Industrial parks in Finland and the Netherlands are procuring thermal output through 15-20 year heat purchase agreements rather than self-building generation assets. This shift concentrates buyer credit risk assessment with specialized infrastructure funds and transfers operational optimization liability to technology-integrated service providers.
District Heating Market Segmentation
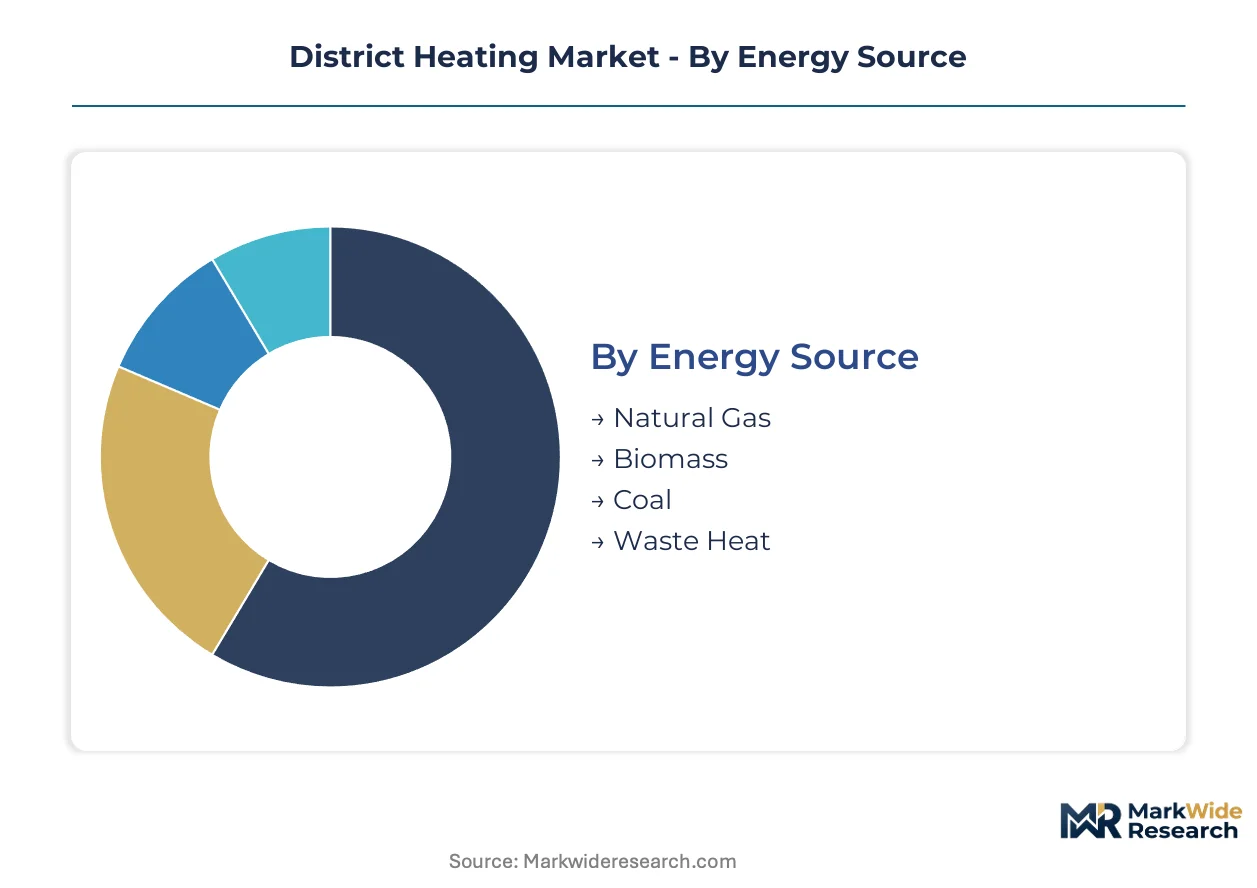
District heating procurement decisions cascade through four interconnected dimensions that determine capital allocation, operational complexity, and regulatory exposure. Energy source selection locks in fuel cost structures and carbon intensity profiles. Distribution network architecture dictates retrofit feasibility and thermal efficiency ceilings.
Energy Source:
Supply concentration in biomass procurement channels is restructuring competitive economics across Nordic and Baltic markets.
- Natural Gas:Combined-cycle CHP plants deliver dispatchable baseload with rapid ramping capability. German municipal utilities in Hamburg and Cologne retain gas-fired capacity for peak thermal demand and grid balancing services.
- Biomass:Forestry residue and wood chip combustion dominates Scandinavian capacity additions. Finnish energy clusters leverage stumpage price advantages and integrated fuel handling infrastructure to undercut fossil thermal costs.
- Coal:Legacy lignite-fired plants in Polish Silesia face accelerated retirement timelines under national decarbonization commitments.
- Waste Heat:Data center cooling loads and industrial process exhaust are capturing revenue through long-term heat purchase agreements in Denmark and the Netherlands.
Today's leader: Biomass. Tomorrow's challenger: Waste Heat.
Distribution Network:
Cost tier differentiation separates premium pre-insulated flexible piping from standard rigid conduit systems in dense urban retrofits.
- Pipe Networks:Pre-insulated steel and flexible polymer piping constitute the capital-intensive backbone of district heating infrastructure. Danish contractors specify LOGSTOR A/S flexible systems for constrained urban corridors where excavation costs dominate project economics.
- Radiant Systems:Floor and ceiling distribution panels serve low-temperature fourth-generation networks in Dutch new-build residential zones.
- Direct Supply:Steam distribution persists in legacy industrial parks with high-temperature process heat requirements.
- Combined Systems:Dual-temperature loops integrating space heating and domestic hot water circuits are expanding in German multi-family housing renovations.
Pipe Networks command current capital deployment. Combined Systems are climbing the fastest as building renovation wave funds prioritize integrated thermal solutions.
End User:
Application-specific temperature requirements and load profiles segment procurement priorities across customer categories.
- Residential:Multi-family apartment blocks constitute the core demand base for municipal district heating operators. Stockholm and Copenhagen housing associations negotiate collective supply contracts with standardized metering and billing frameworks.
- Commercial:Office complexes and retail centers require seasonal load flexibility. Helsinki commercial districts are integrating absorption cooling with heating loops to capture year-round revenue.
- Industrial:Process steam and high-temperature heat demands anchor CHP plant economics in Finnish pulp and paper clusters.
- Institutional:Hospitals and universities prioritize supply reliability over marginal cost optimization. Danish municipal utilities maintain dedicated backup capacity for healthcare critical loads.
Residential volumes dominate current connections. Commercial cooling-heating synergies represent the steepest expansion trajectory for network utilization rates.
System Type:
Technology maturity curves separate proven centralized architectures from emerging digital optimization platforms.
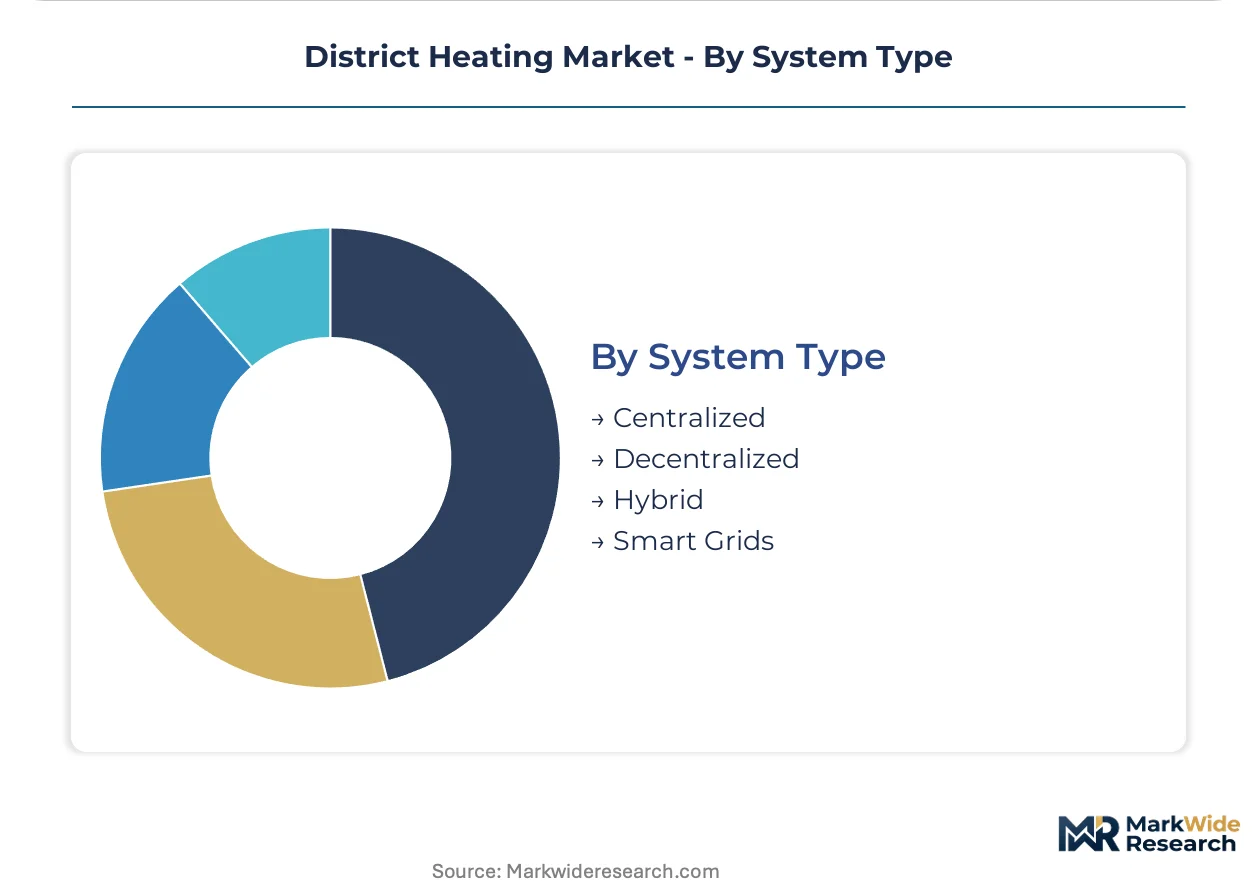
- Centralized:Large-scale CHP and biomass plants with extensive pipe networks deliver economies of scale in dense urban agglomerations. Fortum Oyj operates centralized systems across Finnish cities with integrated fuel logistics and maintenance crews.
- Decentralized:Modular heat pump and boiler clusters serve low-density suburban extensions. Polish utilities are deploying decentralized biomass units in mine closure corridors with limited trunk network access.
- Hybrid:Centralized backbone with decentralized peak shaving and renewable integration is emerging in German retrofit markets.
- Smart Grids:Machine learning demand forecasting and predictive maintenance algorithms are operational in Dutch and Danish pilot networks. Digital twin platforms optimize supply temperature and pump scheduling in real-time.
Centralized systems anchor current capacity. Smart Grids are gaining share fastest as operational margin pools attract software-enabled service providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark's fourth-generation network deployment outpaces Germany's retrofit velocity, while Poland's coal phase-out accelerates municipal utility restructuring. Nordic municipalities anchor waste heat integration, and Baltic states expand biomass-fired capacity.
Germany
Hamburg and Cologne municipal utilities deploy large-scale seawater-source heat pumps to displace coal CHP baseload. The EU Green Deal building renovation targets channel federal funds into low-temperature network extensions. The Ruhr Valley industrial corridor repurposes mine water geothermal for district heating distribution.
Denmark
Aarhus and Copenhagen integrate data center waste heat through long-term purchase agreements with hyperscale operators. The F-Gas Regulation compresses heat pump refrigerant procurement timelines for municipal projects. Danish contractors specify flexible pre-insulated piping beneath dense historic streetscapes.
Poland
Silesian and Łódź agglomerations replan district heating around geothermal wells and biomass plants as mine closures eliminate coal feedstock. National building efficiency codes mandate fossil boiler replacements in multi-family housing. Municipal utilities in Upper Silesia deploy decentralized biomass units in corridor extensions.
Finland
Helsinki commercial districts capture year-round revenue through absorption cooling-heating synergies integrated with seawater loops. Forestry residue supply chains deliver structurally lower thermal input costs under carbon taxation. Finnish energy clusters leverage stumpage price advantages for centralized biomass plant economics.
Sweden
Stockholm housing associations negotiate collective supply contracts with standardized metering frameworks for residential multi-family blocks. The EU Ecodesign framework mandates minimum seasonal performance factors for connected generation equipment. Swedish utilities anchor Nordic district cooling capacity through integrated biomass and seawater infrastructure.
District Heating Market Vendor Landscape
Nordic utility operators anchor one tier; French and Danish engineering specialists hold adjacent positions in equipment and network contracting. The vendor base separates into integrated energy companies, infrastructure fabricators, and technology-integrated service providers. Three archetypes dominate: centralized CHP operators, decentralized heat pump integrators, and digital optimization platform vendors. Competitive moves concentrate on portfolio diversification toward waste heat recovery and strategic partnerships for fourth-generation network engineering.
Among Nordic integrated operators, Fortum Oyj and Vattenfall AB exemplify the centralized generation archetype with extensive CHP footprints across Finland and the Baltic states. ENGIE SA occupies a position within the European retrofit specialist tier, competing in Eastern European markets with decentralized conversion programs. LOGSTOR A/S represents the infrastructure fabrication archetype, supplying pre-insulated flexible piping systems for constrained urban corridors where excavation costs dominate project economics.
| Leading Market Players |
|---|
| Fortum Oyj |
| Vattenfall AB |
| ENGIE SA |
| Danfoss A/S |
| Statkraft AS |
| Veolia Environnement SA |
| Alfa Laval AB |
| Ramboll Group A/S |
| LOGSTOR A/S |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation phase-down mandates are compressing refrigerant procurement timelines for municipal utilities, forcing equipment manufacturers toward CO2 and hydrocarbon alternatives that carry higher upfront engineering costs and elongated certification cycles. This specification-driven demand compression is reshaping supplier pricing power across heat pump couplings and tightening contractor margins in fourth-generation network retrofits.
Pricing Analysis
Contractor markup layers dominate final installed cost structures, with EPC margins compressing as polyurethane foam chemistry and steel input costs fluctuate with petrochemical feedstock markets. Project-based long-term offtake contracts separate premium pre-insulated flexible piping from standard rigid conduit systems, with Danish and German municipal buyers showing highest price sensitivity on pipe network extensions where excavation costs dominate economics. Certification-grade differentiation around REACH-compliant insulation foam and Ecodesign-mandated seasonal performance factors creates tiered pricing separation between qualified European suppliers and non-compliant import alternatives. Pricing pressure stems from F-Gas quota constraints that restrict HFC availability and force accelerated R290 system certification investments.
Supply Chain Analysis
Pre-insulated pipe manufacturing rests on German, Danish, and Polish steel fabrication clusters integrated with Belgian and Dutch polyurethane foam chemistry specialists. Steel coil supply draws from German and Swedish rolling mills, while petrochemical feedstocks for insulation chemistry hinge on Rotterdam and Antwerp refining capacity. Single-source vulnerability concentrates in specialized thermohydraulic engineering talent for low-temperature network design, where legacy district heating workforces lack fourth-generation modeling skills. Distribution runs through municipal utility procurement frameworks and specialized district heating EPC contractors rather than open commodity markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biomass fuel cost arbitrage between Scandinavian forestry residue supply chains and imported natural gas pricing creates geographic-arbitrage value capture for operators with integrated fuel handling infrastructure.
For Market Incumbents: Deploy digital twin network optimization platforms to defend operational margin pools against software-enabled service providers entering thermal optimization. Fortify positions through backward integration into pre-insulated pipe manufacturing or captive waste heat recovery contracts with data center operators, as decentralized heat pump integrators threaten traditional CHP baseload economics. For New Entrants and Emerging Players: Begin with Polish coal phase-out corridors where mine closures eliminate legacy feedstock and municipal utilities replan around geothermal and biomass alternatives. Target Silesian and Łódź agglomerations with modular decentralized biomass units for corridor extensions lacking trunk network access, leveraging energy-as-a-service contracting to bypass capex-heavy utility ownership barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with technology-integrated service providers combining heat pump integration capabilities with digital optimization platforms. Long-term viability favors operators with secured waste heat purchase agreements and fourth-generation network engineering competencies. Watch F-Gas Regulation enforcement intensity as inflection indicator for refrigerant transition cost absorption and equipment manufacturer consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Large-scale seawater-source heat pumps in Hamburg and Aarhus displace coal CHP baseload capacity. |
| Power Purchase Agreement | Long-term heat purchase agreements with hyperscale data center operators convert cooling loads to revenue streams. |
| Technology Licensing | CO2 transcritical cycle heat pump licensing accelerates municipal project deployment under compressed refrigerant timelines. |
| Backward Integration | Upstream control over pre-insulated flexible piping manufacturing secures margin capture in dense urban retrofit corridors. |
| Green Certification Program | Ecodesign and Energy Labelling compliance investments differentiate connected generation equipment in German and Danish procurement. |
Methodological Framework
Coverage spans Germany, Denmark, Poland, Finland, and Sweden, with primary inputs from each market's municipal utility planning officers, district heating EPC contractors, pre-insulated pipe procurement leads, and biomass fuel supply specialists. Secondary validation draws from EU F-Gas Regulation filings, national building renovation wave fund disbursement records, EEA emissions trading data, and municipal heat zoning ordinances. Bottom-up project pipeline assessments triangulate against top-down energy demand modeling across the analysis window.
Segmentation granularity extends to energy source, distribution network architecture, end-user category, and system type, with additional modeling of temperature regime differentiation between conventional and fourth-generation networks. CAGRs derive from installed capacity buildout trajectories and fuel cost evolution assumptions, incorporating carbon taxation schedules and coal phase-out commitments as boundary conditions. Forecast inputs include stumpage price indices for Scandinavian forestry residue and seawater-source heat pump deployment rates in coastal German and Danish networks.
Several conditions sit outside the modeled scope, including unannounced national subsidy program revisions, abrupt refrigerant quota adjustments, and geopolitical disruptions to steel or petrochemical feedstock flows. Forecasts reflect documented assumptions around EU Green Deal implementation velocity and building renovation fund accessibility. A small set of named triggers warrants ongoing watch: F-Gas Regulation enforcement intensity, data center waste heat contract renegotiation cycles, and municipal utility privatization decisions in Polish coal phase-out corridors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Advanced Utility Boilers Market
Boilers
Global Fuel Flexible Boiler Market
Boilers
Marine Boiler Burner Market
Boilers
Asia-Pacific Combined Heat and Power Market
Boilers
Brazil Combined Heat and Power Market
Boilers
Global Boiler Market
Boilers
Boiler Combustion Chamber Market
Boilers
Gas Condensing Boiler Market
Boilers
Middle East and Africa Power Plant Boiler Market
Boilers
Micro Combined Heat and Power (CHP) Market
Boilers
Commercial Boiler Market
Boilers
Combi Boiler Market
Boilers
Europe Power Plant Boiler Market
Boilers
US Combined Heat and Power (CHP) Market
Boilers
Europe Combined Heat and Power Market
Boilers
Boiler Control Market