
 Germany Bunker Fuel Market | 2026-2036
Germany Bunker Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Bunker Fuel Market Foresight
Low-sulfur marine gasoil is restructuring bunker fuel economics as ship operators abandon high-sulfur residual grades post-IMO 2020. Vitol Holding BV leverages its Rotterdam-German coastal supply chain to dominate ARA-delivered volumes into Hamburg and Wilhelmshaven. Royal Dutch Shell Plc anchors its position through integrated LNG bunkering capabilities at German North Sea terminals. Monjasa Holding A/S specializes in niche supply to offshore support fleets operating from Cuxhaven.
Germany bunker fuel denotes marine-grade hydrocarbons and alternative fuels combusted in vessel main and auxiliary engines, with specifications governed by ISO 8217 standards for density, viscosity, and sulfur content below 0.50% m/m for conventional grades. The fuel serves propulsion and power generation for commercial shipping transiting German ports and exclusive economic zones. Heavy fuel oil retains volume leadership among legacy vessel classes despite regulatory pressure, while liquefied natural gas claims the fastest expansion trajectory as dual-fuel engine penetration deepens in container ships and passenger vessels calling at Hamburg and Bremerhaven. Marine diesel oil occupies stable demand among smaller coastal and offshore support fleets where LNG infrastructure remains absent.
The Federal Maritime and Hydrographic Agency enforces MARPOL Annex VI compliance at German ports, while the EU F-Gas Regulation and national implementation of the FuelEU Maritime initiative progressively tighten well-to-wake carbon intensity thresholds for berthed and transiting vessels. KBA oversight of inland waterway fuel quality standards indirectly shapes coastal bunkering specifications through shared supply chain infrastructure. Stakeholders must monitor Berlin's transposition of EU renewable fuel mandates and assess whether biofuel and methanol blending obligations reshape procurement contracts at German port clusters before infrastructure lock-in solidifies.
Market Dynamics
The Germany bunker fuel market is restructuring around fuel-switching mandates from Brussels and Hamburg, as vessel operators abandon residual grades for compliant alternatives and LNG bunkering infrastructure scales along the North Sea coast.
Growth Catalysts
- FuelEU Maritime:The EU regulation progressively tightens well-to-wake carbon intensity thresholds for vessels calling at German ports, forcing procurement of renewable and low-carbon marine fuels.
- LNG bunkering infrastructure:Terminal expansions at Hamburg and Bremerhaven enable dual-fuel container ships to refuel during port calls, accelerating adoption among deep-sea liner operators.
- Container shipping consolidation:Alliance restructuring concentrates procurement power among fewer mega-carriers, streamlining long-term fuel contracts with German suppliers.
Market Restraints
- Crude-linked price volatility:Marine gasoil and low-sulfur fuel oil remain tethered to Rotterdam-refined product differentials, compressing margin predictability for German bunker traders.
- ARA supply concentration:Amsterdam-Rotterdam-Antwerp refining and storage dominance creates single-point vulnerability for Hamburg and Wilhelmshaven deliveries during regional outages.
- Electrification of short-sea routes:Battery-hybrid ferries and coastal feeders operating between German North Sea islands are displacing conventional bunkering volumes in niche segments.
Strategic Opportunities
- Methanol bunkering corridors:The EU Green Deal maritime provisions and national hydrogen strategy position German ports to capture green methanol refueling demand from container lines deploying dual-fuel vessels.
- Offshore wind service vessels:Crew transfer and construction support fleets operating from Cuxhaven and Emden require specialized marine diesel oil and emerging biofuel blends.
- Digital bunkering platforms:Blockchain-verified mass-flow-metering and automated BDN issuance are reducing transaction friction for spot procurement at German terminals.
Industry Challenges
- Dual-fuel engineering talent:Shortages of technicians certified for LNG and methanol engine maintenance are delaying vessel deployment schedules for German-flagged operators.
- ISO 8217 compliance verification:Laboratory testing bottlenecks at Hamburg and Bremerhaven are extending fuel quality certification timelines during peak port calls.
- Legacy HFO infrastructure stranding:Tank farms and pipelines optimized for high-sulfur residual fuel face write-down risk as demand concentrates on cleaner grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Bunker Fuel Market |
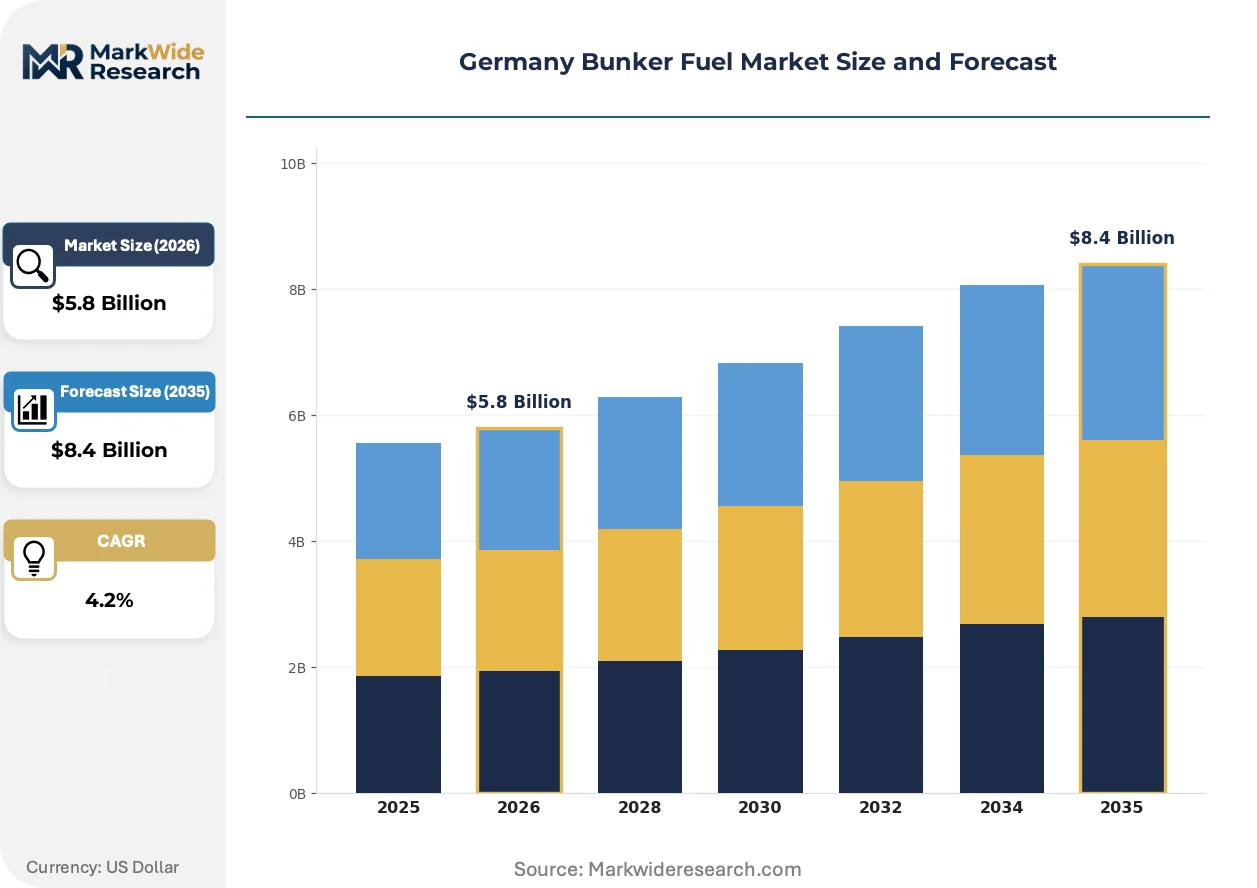
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.4 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Marine Diesel Oil, Heavy Fuel Oil, Liquefied Natural Gas, Biofuel, Methanol Vessel Type: Container Ships, Bulk Carriers, Tankers, Passenger Ships, Offshore Support Vessels Supply Mode: Ship-to-Ship, Barge Delivery, Port Storage, Truck Delivery, Pipeline Transfer End User: Shipping Companies, Port Authorities, Offshore Operators, Bunker Suppliers, Maritime Logistics |
| Companies Covered | Bunker Holding A/S, Vitol Holding BV, Total SA, Royal Dutch Shell Plc, Monjasa Holding A/S, BP Plc, ExxonMobil Corporation, World Fuel Services, Peninsula Petroleum, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Bunker Fuel Market Shifts & Advancements
Marine fuel procurement in Germany is digitizing rapidly while alternative fuel pathways compete for infrastructure investment and regulatory preference.
Ammonia-ready engine designs are rewriting vessel newbuild specifications at German yards and Asian shipbuilders supplying Hamburg-based carriers. Container lines including Hapag-Lloyd are inserting ammonia compatibility clauses into engine orders despite bunkering infrastructure remaining absent. This technology commitment is compressing the window for LNG lock-in before zero-carbon fuels achieve commercial scale.
The EU F-Gas Regulation and national implementation of MARPOL Annex VI through the Federal Maritime and Hydrographic Agency are tightening enforcement at German ports. Ship operators face expanded documentation requirements for fuel sulfur content and eventual carbon intensity reporting. Container shipping alliances are responding by pre-positioning compliant fuels and securing multi-year supply contracts with ARA-German coastal suppliers.
Charterers are consolidating procurement decisions at the fleet level rather than allowing individual vessel masters to negotiate spot bunkers. German container lines and bulk operators are centralizing fuel buying through dedicated trading desks, displacing traditional broker-mediated spot markets. This concentration is most visible among Hamburg-headquartered carriers managing global fleet fuel strategies from their German headquarters.
Germany Bunker Fuel Market Segmentation
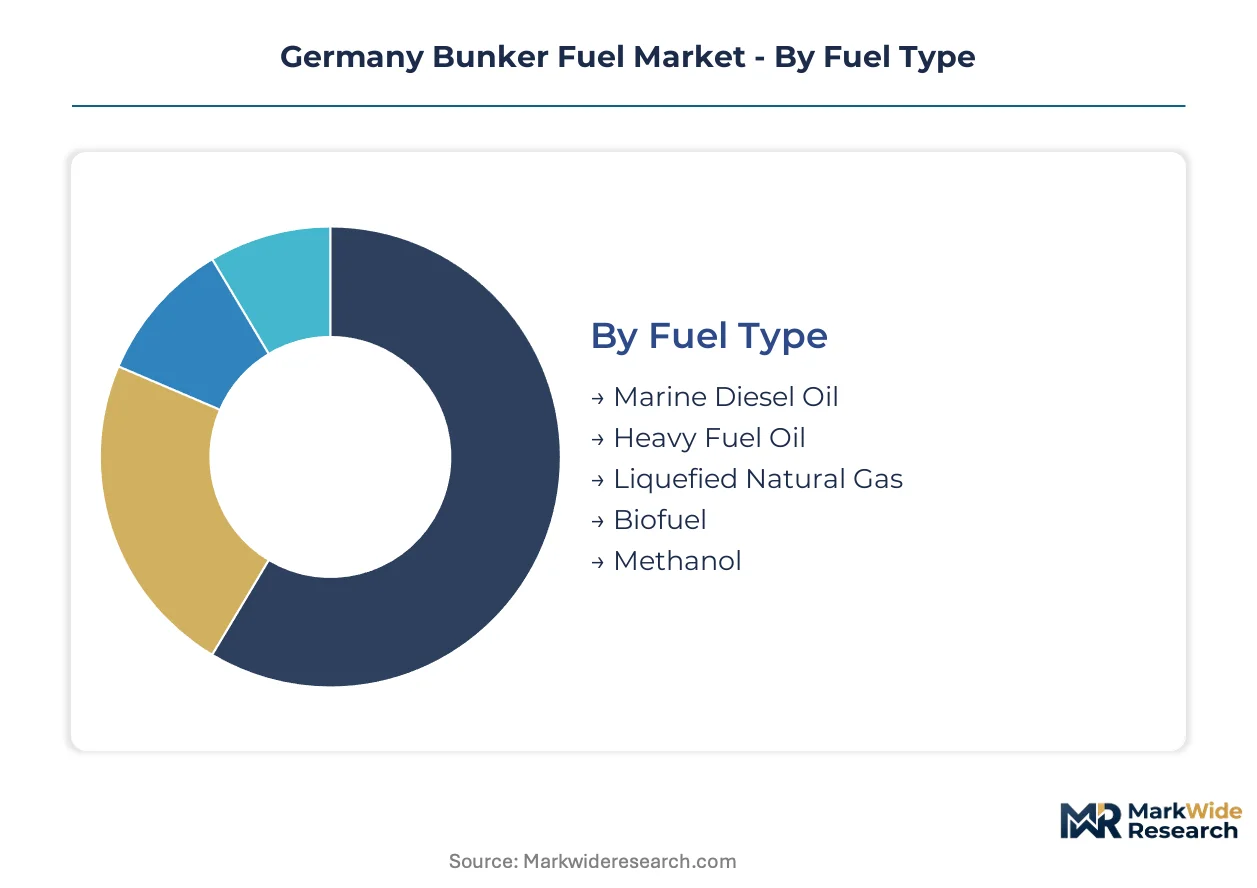
German bunker fuel procurement fragments across fuel specifications, vessel classes, and delivery logistics. Each segmentation axis reveals distinct margin structures and infrastructure requirements that shape supplier positioning along the North Sea coast.
Fuel Type:
Technical specifications and regulatory compliance thresholds define competitive positioning across marine fuel grades.
- Marine Diesel Oil:A distillate fuel meeting ISO 8217 DMA/DMB specifications with sulfur content capped at 0.10% m/m for ECAs. Demand concentrates among coastal feeders and offshore support vessels operating from Cuxhaven and Emden where LNG infrastructure remains absent. KBA enforcement of inland waterway standards indirectly tightens coastal MDO specifications through shared terminal infrastructure.
- Heavy Fuel Oil:Residual-grade fuel oil with maximum 0.50% m/m sulfur content under IMO 2020, though legacy high-sulfur variants persist for scrubber-fitted vessels. Procurement volumes cluster at Hamburg and Wilhelmshaven for capesize bulk carriers and older tanker fleets where capital constraints delay dual-fuel retrofits.
- Liquefied Natural Gas:Cryogenic methane fuel stored at -162°C for dual-fuel engine combustion. Expanding fastest among container ships calling at Bremerhaven and Hamburg as terminal bunkering infrastructure scales.
- Biofuel:FAME and HVO blends dropping into existing marine diesel infrastructure without engine modification. Emerging traction under FuelEU Maritime carbon intensity thresholds.
- Methanol:Low-carbon alcohol fuel requiring dedicated storage and engine systems. Green methanol corridors are forming at German ports under EU Green Deal maritime provisions.
Heavy Fuel Oil leads on scale; Liquefied Natural Gas leads on momentum.
Vessel Type:
Propulsion requirements and voyage patterns segment fuel demand across German port calls.
- Container Ships:Deep-sea liner vessels with 10,000+ TEU capacity dominating Hamburg and Bremerhaven fuel offtake. Alliance procurement centralization concentrates long-term supply contracts with ARA-German coastal suppliers.
- Bulk Carriers:Dry cargo vessels in capesize and panamax classes with high HFO tolerance. Spot procurement flexibility persists as charterer-operators optimize voyage economics around Rotterdam price differentials.
- Tankers:Liquid cargo vessels including product and crude carriers. Demand concentrates at Wilhelmshaven near pipeline terminals and refinery complexes.
- Passenger Ships:Cruise liners and ferries with strict ECA compliance requirements. Dual-fuel LNG penetration is deepest in this segment at German North Sea ports.
- Offshore Support Vessels:Crew transfer and construction support fleets serving North Sea wind farms. Specialized MDO and emerging biofuel demand from Cuxhaven and Emden supply bases.
Container Ships anchor volume concentration; Offshore Support Vessels are expanding most quickly on energy transition mandates.
Supply Mode:
Logistics configuration determines delivery economics and infrastructure lock-in across German terminals.
- Ship-to-Ship:Direct fuel transfer between bunker vessel and receiving ship at anchorage. Dominates Hamburg outer port operations where deep-draft container ships avoid berth congestion.
- Barge Delivery:Flat-bottomed bunker vessels navigating inland port areas. Critical for Bremerhaven container terminals where alongside bunkering integrates with cargo operations.
- Port Storage:Shore-based tank farms feeding vessel connections. Wilhelmshaven leverages pipeline-linked storage for high-volume HFO and MGO distribution.
- Truck Delivery:Road tanker supply for smaller vessels and emergency refueling. Niche role at Emden and minor Lower Saxony ports lacking dedicated bunker barges.
- Pipeline Transfer:Direct refinery-to-terminal product movement. Limited to Wilhelmshaven and Hamburg clusters with integrated petrochemical infrastructure.
Ship-to-Ship commands the largest throughput; Pipeline Transfer offers the steepest expansion trajectory on infrastructure investment cycles.
End User:
Procurement authority and risk allocation patterns segment the German bunker fuel customer base.
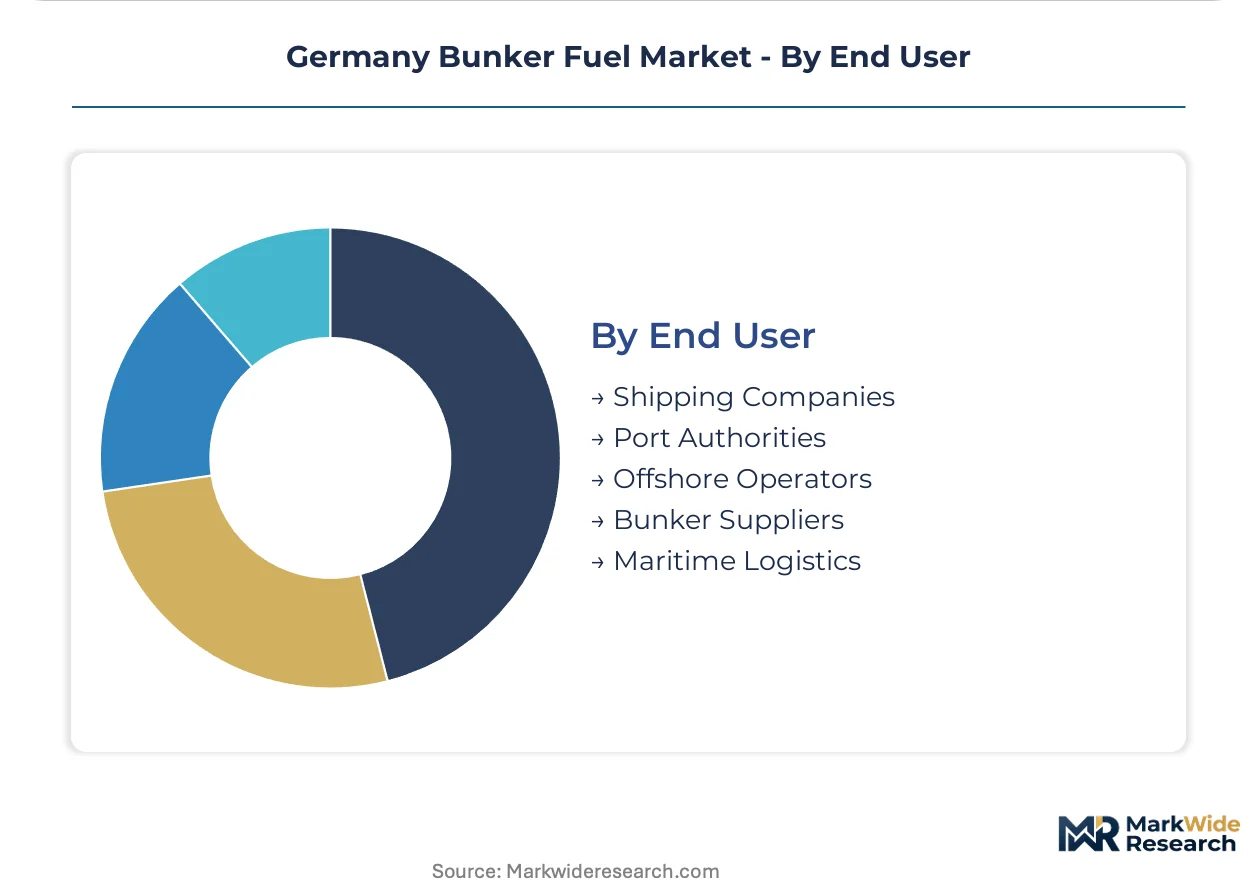
- Shipping Companies:Container lines and bulk operators managing fleet-wide fuel strategies. Hamburg-headquartered carriers centralize global procurement decisions through dedicated trading desks.
- Port Authorities:Terminal operators coordinating bunkering infrastructure and environmental compliance. Federal Maritime and Hydrographic Agency oversight shapes their fuel quality verification protocols.
- Offshore Operators:Wind farm developers and service companies sourcing specialized marine fuels. Concentrated demand from Cuxhaven supply bases serving North Sea renewable installations.
- Bunker Suppliers:Trading houses and physical suppliers managing ARA-German coastal arbitrage. Vitol and Shell dominate delivered volumes through integrated supply chains.
- Maritime Logistics:Charterers and ship managers coordinating voyage fuel requirements. Digital platforms are compressing their spot procurement transaction costs.
Shipping Companies control procurement volume; Offshore Operators are gaining share fastest on energy transition capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Hamburg-Bremerhaven port corridor dominates German bunker fuel procurement, with Lower Saxony and Schleswig-Holstein anchoring North Sea supply infrastructure.
Lower Saxony
Wilhelmshaven's deep-water terminals and pipeline-linked storage facilities attract capesize bulk carriers and tanker fleets seeking high-volume heavy fuel oil refueling. The Federal Maritime and Hydrographic Agency enforces MARPOL Annex VI compliance through expanded documentation requirements for sulfur content verification. Cuxhaven offshore supply bases are scaling marine diesel oil and biofuel blends for crew transfer vessels serving North Sea wind farms.
Schleswig-Holstein
Brunsbüttel at the Kiel Canal entrance captures transit bunkering demand from Baltic-Atlantic container routes and ro-ro operators. KBA oversight of inland waterway fuel standards indirectly tightens coastal specifications through shared terminal infrastructure. LNG bunkering infrastructure is expanding at Brunsbüttel to serve dual-fuel ferries and coastal feeders operating between German North Sea islands.
Hamburg
Hamburg's container terminals generate concentrated marine gasoil demand from 10,000+ TEU vessels operated by alliance-carrier procurement desks. The EU F-Gas Regulation and FuelEU Maritime initiative are tightening well-to-wake carbon intensity thresholds for berthed vessels. Ship-to-ship transfer operations at the outer port enable deep-draft container ships to refuel without berth congestion.
North Rhine-Westphalia
Rhine-Ruhr industrial demand indirectly shapes coastal bunkering through shared refining infrastructure and product pipeline networks. National implementation of the EU Green Deal maritime provisions is pressuring fuel-switching decisions across connected supply chains. Duisburg inland port operators are piloting LNG bunker barge concepts that could extend to coastal applications.
Bremen
Bremerhaven's automotive export terminals drive specialized bunker demand from pure car and truck carriers with strict ECA compliance requirements. Container shipping alliance restructuring concentrates long-term fuel contracts with ARA-German coastal suppliers at this hub. Barge delivery logistics integrate bunkering with cargo operations at dedicated container terminals.
Germany Bunker Fuel Market Competitive Landscape
Global majors compete with regional champions across physical supply infrastructure and alternative fuel capabilities. The vendor base organizes around integrated energy conglomerates, specialized marine fuel traders, and offshore logistics specialists. Three archetypes dominate: Rotterdam-ARA supply chain integrators, LNG bunkering capability builders, and niche offshore support fuel providers. Competitive positioning hardens through terminal infrastructure access and multi-year procurement contracts with alliance carriers.
Among integrated energy conglomerates, Royal Dutch Shell Plc and BP Plc anchor the LNG bunkering capability tier through North Sea terminal investments. Vitol Holding BV exemplifies the ARA-German coastal arbitrage specialist archetype, leveraging Rotterdam supply chain integration to dominate delivered volumes into Hamburg and Wilhelmshaven. Monjasa Holding A/S occupies the offshore support niche, concentrating specialized marine diesel oil supply from Cuxhaven to wind farm service fleets.
| Leading Market Players |
|---|
| Bunker Holding A/S |
| Vitol Holding BV |
| Total SA |
| Royal Dutch Shell Plc |
| Monjasa Holding A/S |
| BP Plc |
| ExxonMobil Corporation |
| World Fuel Services |
| Peninsula Petroleum |
| Others |
Supply & Pricing Matrix
FuelEU Maritime's well-to-wake carbon intensity thresholds gate qualified supply for German bunker fuel procurement, reserving premium-tier pricing access for suppliers with renewable fuel certification and LNG bunkering infrastructure at Hamburg and Bremerhaven terminals.
Pricing Analysis
Rotterdam-refined product differentials pass through directly into German port pricing, with marine gasoil and low-sulfur fuel oil tracking ARA spot benchmarks plus delivery premiums. Price differentiation hinges on sulfur certification grade under ISO 8217 and volume scale from alliance carrier procurement desks. Pricing pressure stems from crude-linked volatility compressing trader margins. Spot-dependent bulk operators show highest price sensitivity; container lines with long-term offtake contracts demonstrate lowest.
Supply Chain Analysis
ARA-delivered channels handle mega-carrier demand through Rotterdam-Amsterdam-Antwerp refining concentration feeding Hamburg and Wilhelmshaven. The supply chain draws from Dutch and Belgian storage terminals, with German coastal infrastructure expanding at Bremerhaven and Brunsbüttel. Single-source vulnerability concentrates in Rotterdam pipeline outages disrupting North Sea deliveries. Distribution runs through integrated trader networks anchored by physical suppliers with terminal access rights.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German bunker fuel procurement has entered a late-cycle quality phase where FuelEU Maritime compliance specifications are concentrating demand on certified low-carbon supply.
For Market Incumbents: To counter LNG infrastructure lock-in by integrated energy majors, specialized traders should secure backward integration into biofuel blending capacity at Cuxhaven and Emden. Terminal access rights at Hamburg outer port anchor retention of deep-sea container ship accounts. For New Entrants and Emerging Players: Enter via green methanol corridor development at Wilhelmshaven, where EU Green Deal maritime provisions are pre-positioning demand ahead of dual-fuel vessel deployment. Offshore wind service fleets offer the most penetrable segment given fragmented MDO procurement and emerging biofuel blend requirements. For Investors and Strategic Acquirers: Roll-up economics work for regional bunker traders with terminal infrastructure because FuelEU Maritime is fragmenting procurement across multiple fuel types. Five-to-ten year viability favors suppliers with LNG and methanol capability buildout. The signal to watch is dual-fuel container ship order intake at German-headquartered carriers.| Strategic Initiative | Industry Significance |
|---|---|
| LNG Bunkering Infrastructure Expansion | Terminal investments at Bremerhaven enable dual-fuel container ship refueling during port calls. |
| Biofuel Blending Capacity Buildout | FAME and HVO infrastructure at Cuxhaven captures FuelEU Maritime carbon intensity compliance demand. |
| Green Methanol Corridor Development | EU Green Deal maritime provisions position Wilhelmshaven for zero-carbon fuel pre-positioning. |
| Digital Bunkering Platform Integration | Blockchain-verified mass-flow-metering reduces transaction friction for spot procurement at Hamburg. |
| Offshore Wind Fuel Specialization | Dedicated MDO and biofuel supply bases at Emden serve North Sea renewable installation fleets. |
Research Methodology
Multiple input streams — physical supplier trading desks, container line procurement officers, terminal operators at Hamburg and Bremerhaven, and Federal Maritime and Hydrographic Agency compliance officials — were reconciled against customs records, EU MRV emissions database filings, and ARA bunker delivery statistics. Secondary validation drew from Lloyd's List intelligence, ISO 8217 certification registries, and port authority throughput disclosures. Bottom-up vessel call analysis and top-down fuel consumption estimates were triangulated to anchor volume projections.
Historical bunker sales trends were cross-referenced against panel input from marine fuel traders and alliance carrier fuel desks to construct the analytical framework across the projection horizon. Segmentation dimensions modeled include fuel specification grade, vessel propulsion architecture, delivery logistics mode, and end-user procurement authority. CAGRs were derived from fuel-switching elasticity assumptions tied to regulatory threshold implementation. Forecast inputs incorporated dual-fuel engine penetration curves and LNG bunkering infrastructure deployment timelines.
Inputs from physical suppliers and container line procurement desks were available through the study window; gaps in real-time spot pricing transparency introduce uncertainty bands around margin estimates. Forecasts reflect documented assumptions regarding IMO regulatory enforcement consistency and EU Green Deal maritime provision implementation timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
South Africa Bunker Fuel Market
Fuels
Aviation Fuel Additives Market
Fuels
Japan Bunker Fuel Market
Fuels
China Coal Market
Fuels
Coal Briquette Box Market
Fuels
Fuel Grinder Market
Fuels
Europe Commercial Aircraft Aviation Fuel Market
Fuels
Smart Gas Market
Fuels
Asia-Pacific Commercial Aircraft Aviation Fuel Market
Fuels
Global Liquid Gas Cylinder (LGC) Market
Fuels
Coal to Liquid Fuel (CTL) Market
Fuels
South America Defense Aircraft Aviation Fuel Market
Fuels
South America Bunker Fuel Market
Fuels
Global Wood Gas Generator Market
Fuels
Palm Methyl Ester Market
Fuels
Saudi Arabia Fuel Station Market