
 Scaffold Materials Market | 2026-2036
Scaffold Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Scaffold Materials Market Analytics
Commercial high-rise construction is decoupling from traditional residential scaffolding intensity as mixed-use towers demand specialized access configurations. PERI Group leverages modular system engineering to dominate European commercial verticals. BrandSafway sustains its North American position through integrated rental and erection services. Layher Holding GmbH differentiates via precision-manufactured steel componentry for complex facade geometries.
Scaffold materials are temporary structural access systems fabricated from steel tube, aluminum extrusion, timber plank, or fiber-reinforced polymer composite, engineered to support workers, tools, and loads at elevation during construction, maintenance, or repair operations. Steel tube assemblies with galvanized zinc coating remain the default for heavy-duty applications exceeding standard load ratings. Aluminum segments are capturing share in light-to-medium duty renovation work where transport efficiency and rapid assembly reduce labor hours. Composite materials occupy emerging niches in corrosive industrial environments where metallic fatigue and chemical degradation accelerate replacement cycles.
OSHA Subpart L scaffolding standards and EN 12811 European access equipment codes dictate load testing protocols, guardrail placement, and plank grading that determine product marketability across jurisdictions. ISO 12811 and national variants in Germany, China, and the United States create layered compliance requirements that favor manufacturers with multi-certification testing capacity. Stakeholders must track evolving carbon-accounting rules for steel and aluminum sourcing as embodied emissions reporting penetrates public infrastructure procurement criteria.
Market Dynamics
Commercial high-rise construction is fragmenting scaffold demand into specialized access configurations, forcing manufacturers to engineer modular systems that accommodate irregular facade geometries and mixed-use load profiles rather than standardized tube-and-coupler assemblies.
Growth Catalysts
- Infrastructure renewal programs:Federal and state capital allocation in the United States, Germany, and China is accelerating public works procurement of engineered access systems for bridge rehabilitation and transit expansion.
- EN 12811 framework updates:Tightened European load testing and guardrail placement mandates are retiring non-compliant inventory, creating replacement demand for certified modular platforms.
- Composite material engineering:Fiber-reinforced polymer formulations are penetrating corrosive industrial environments where galvanized steel degradation previously shortened replacement cycles.
Market Restraints
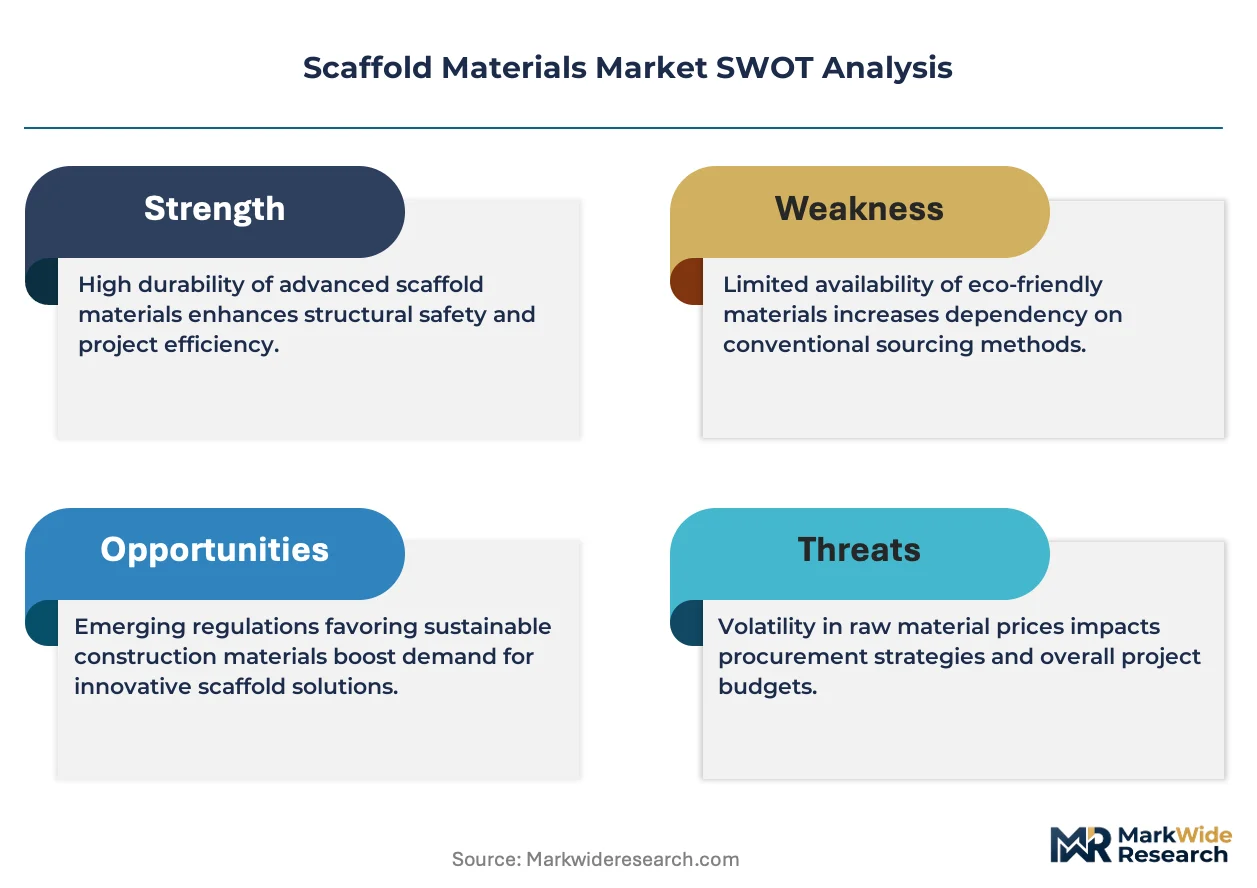
- Steel price volatility:Galvanized zinc coating costs and hot-rolled steel input fluctuations compress margin predictability for tube-and-coupler manufacturers serving heavy-duty segments.
- Supply concentration in China:Primary aluminum extrusion and steel tube sourcing clusters create geographic vulnerability to export tariff adjustments and freight rate spikes.
- Timber plank durability limits:Natural material degradation under cyclic loading restricts plank reuse rates, elevating lifecycle costs versus metallic alternatives in high-rotation rental fleets.
Strategic Opportunities
- Carbon-accounting procurement rules:Embodied emissions reporting requirements in German and US public infrastructure tenders favor manufacturers with verified low-carbon steel and aluminum sourcing.
- Drone-integrated inspection protocols:Convergence of unmanned aerial systems with digital twin modeling is creating subscription-based asset management services for rental fleet operators.
- Light-to-medium renovation segments:Residential retrofit and historic preservation markets in France and Italy remain underpenetrated by aluminum rapid-assembly systems optimized for restricted site access.
Industry Challenges
- Multi-certification testing capacity:ISO 12811, OSHA Subpart L, and national variant compliance requires capital-intensive laboratory infrastructure that strains mid-tier manufacturers.
- Skilled erection labor shortages:Certified scaffold builder training pipelines in the United States and Germany fail to match fleet expansion rates, extending project mobilization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scaffold Materials Market |
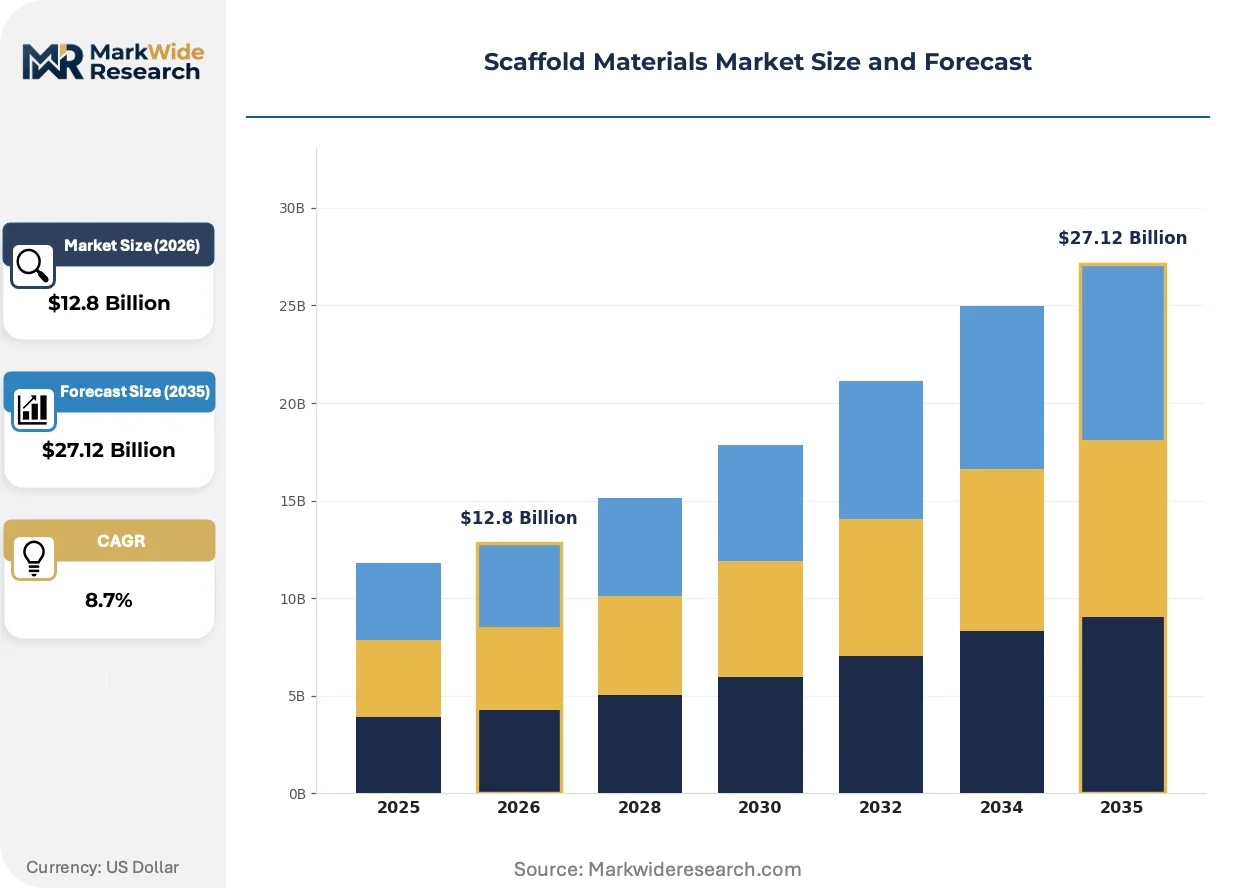
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Steel, Aluminum, Wood, Composite Application: Construction, Industrial, Maintenance, Renovation Load Capacity: Light Duty, Medium Duty, Heavy Duty, Super Heavy Duty Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Altrad Group, Safway Group, Layher Holding GmbH, Waco Kwikform, MJ-Gerüst GmbH, PERI Group, ULMA Construction, ADTO Group, BrandSafway, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scaffold Materials Market Evolving Landscape
Digital fabrication and predictive maintenance protocols are compressing scaffold design-to-deployment cycles while regulatory carbon tracking reconfigures material sourcing hierarchies across construction supply chains.
Modular ringlock and cuplock systems are decentralizing site-level inventory management by enabling component standardization across multiple project types. Regional rental operators in France and Spain are consolidating fleets around interoperable node connections that reduce cross-project reconciliation time. This interoperability is decentralizing procurement authority from central equipment yards to individual site managers who configure assemblies on-demand.
The EU Green Deal's embodied carbon disclosure requirements for construction materials are compelling steel and aluminum suppliers to provide Environmental Product Declarations. German scaffold fabricators are now screening mill certificates for electric arc furnace content to meet public tender thresholds. Aluminum extrusion with verified low-carbon primary metal commands price premiums in Scandinavian infrastructure procurement.
Rental fleet operators are unbundling erection services from equipment hire, creating separate contractual vehicles for labor and asset provision. Large commercial contractors in the United Kingdom are negotiating direct erection partnerships with specialized subcontractors rather than accepting bundled rates from national rental networks. This unbundling is most visible in London's high-rise residential pipeline where developer cost controls favor transparent labor pricing.
Scaffold Materials Market Segmentation
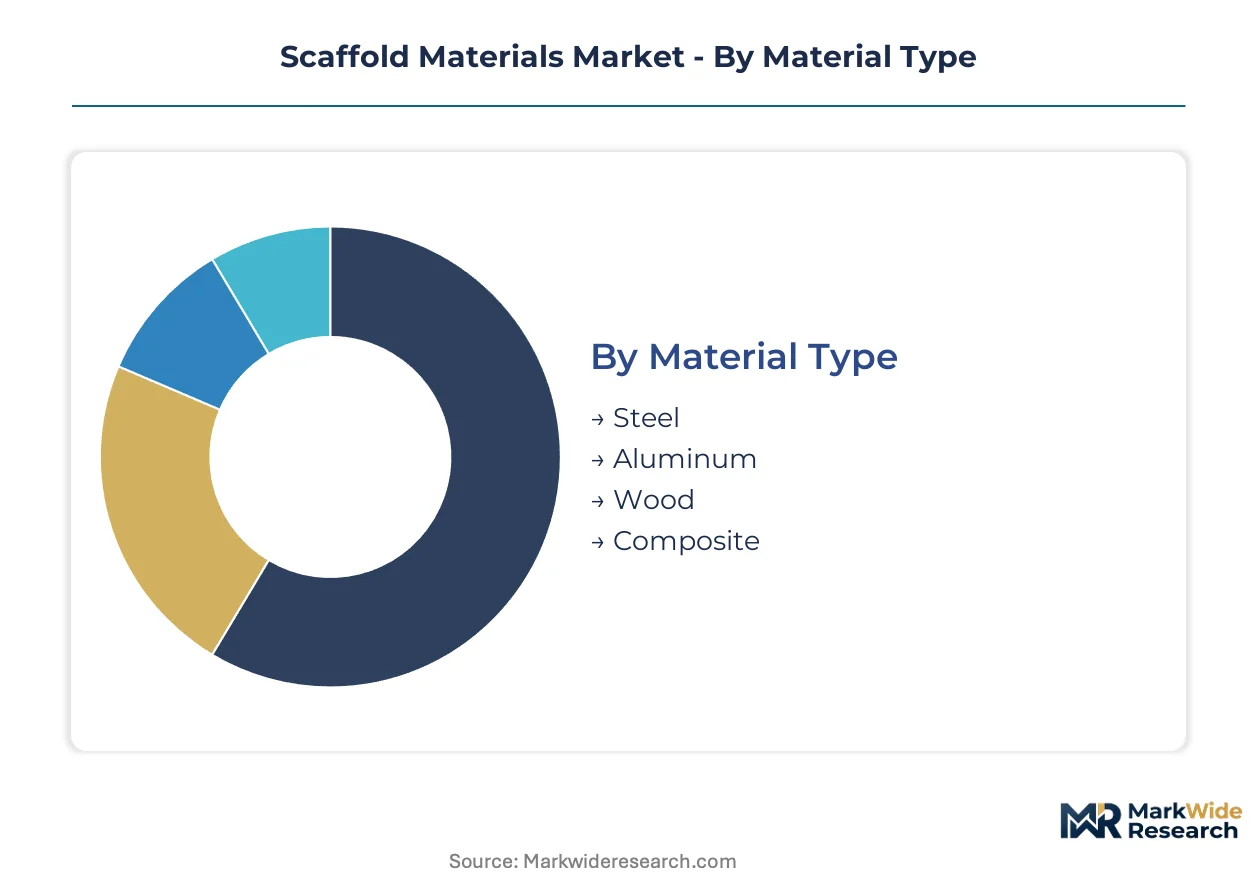
Scaffold material selection directly determines capital deployment intensity across rental fleets and contractor inventories. Load capacity ratings and material composition dictate depreciation schedules, compliance testing investments, and geographic deployment flexibility.
Material Type:
Steel tube assemblies demand the heaviest upfront capital commitment due to galvanizing infrastructure, metallurgical testing laboratories, and high-volume warehousing requirements.
- Steel:Hot-rolled carbon steel with zinc galvanization dominates heavy-duty commercial construction in Germany and the United States. German fabricators screen mill certificates for electric arc furnace content to satisfy public tender carbon thresholds. Steel absorbs the bulk of installed capacity; Composite is expanding most quickly.
- Aluminum:Extruded 6061-T6 alloy sections reduce transport costs and accelerate assembly cycles for light-to-medium renovation work in France and Italy. Aluminum rapid-assembly systems penetrate historic preservation markets where site access restrictions complicate steel erection.
- Wood:Timber plank platforms serve temporary access needs in residential construction segments where load requirements remain modest and material familiarity reduces training overhead.
- Composite:Fiber-reinforced polymer formulations penetrate corrosive industrial environments in coastal China and chemical processing zones where galvanized steel degradation accelerates replacement cycles.
Steel retains the dominant share of rental fleet value; Composite formulations are climbing the fastest as corrosion-resistant specifications proliferate.
Application:
Construction applications generate the highest volume throughput but industrial maintenance commands superior margin structures due to specialized engineering requirements.
- Construction:Commercial high-rise and infrastructure projects in the United States and China drive specification for modular ringlock systems. Mixed-use towers demand irregular facade configurations that strain standardized tube-and-coupler economics.
- Industrial:Petrochemical and power generation facilities in Germany specify corrosion-resistant access systems with extended service intervals. Maintenance turnaround schedules prioritize rapid deployment and certified load documentation.
- Maintenance:Bridge rehabilitation and transit expansion programs across US federal and state capital allocations accelerate procurement of engineered access systems with documented compliance histories.
- Renovation:Residential retrofit markets in France and Italy remain underpenetrated by aluminum rapid-assembly systems optimized for restricted site access and shortened project durations.
Construction commands the greatest absolute equipment deployment; Industrial maintenance is gaining share fastest as facility uptime premiums justify specialized system investment.
Load Capacity:
Heavy-duty ratings concentrate procurement authority with tier-one rental networks capable of underwriting liability for elevated worker concentrations and material staging.
- Heavy Duty:Rated for 75 pounds per square foot, these systems support masonry crews and material hoists on commercial high-rise projects in London and New York. OSHA Subpart L and EN 12811 testing mandates elevate compliance costs that favor scaled operators.
- Super Heavy Duty:Exceeding standard ratings for specialized shoring and structural support applications in German bridge rehabilitation and Chinese infrastructure renewal programs.
- Medium Duty:50 pounds per square foot ratings serve general construction trades where worker density and tool loads remain moderate.
- Light Duty:25 pounds per square foot configurations penetrate residential renovation and interior finishing segments with minimal material staging requirements.
Heavy Duty absorbs the dominant share of rental revenue; Super Heavy Duty is expanding most quickly as infrastructure renewal programs escalate specialized load requirements.
Distribution Channel:
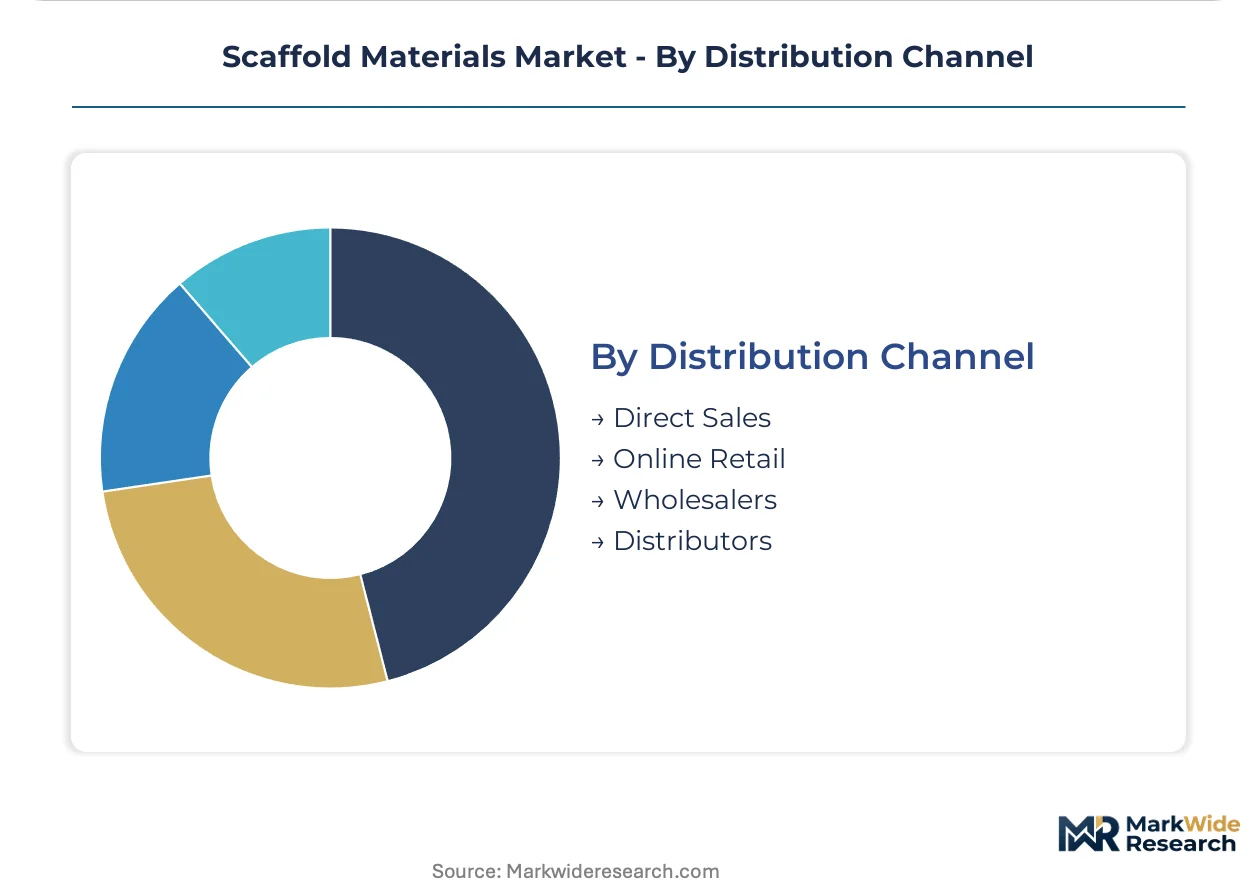
Direct sales relationships capture the largest contract values but require sustained field engineering investment that strains mid-tier manufacturer balance sheets.
- Direct Sales:National rental networks in the United Kingdom and Germany negotiate direct erection partnerships with specialized subcontractors, unbundling labor from equipment hire for transparent pricing.
- Distributors:Regional operators in France and Spain consolidate fleets around interoperable node connections, decentralizing procurement authority to site managers.
- Wholesalers:Volume aggregation serves smaller contractors in fragmented Italian and Spanish construction markets with standardized componentry.
- Online Retail:Digital platforms penetrate light-duty accessory and replacement component sales where specification complexity remains minimal.
Direct Sales commands the preponderance of contract value; Distributor networks are gaining traction fastest as fleet interoperability standards mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the bulk of raw aluminum extrusion and steel tube inputs, while the United States and Germany consume the highest volumes of engineered access systems for commercial vertical construction. This production-consumption divide shapes freight economics and certification arbitrage across procurement networks.
United States
Infrastructure renewal programs and commercial high-rise development in New York and Chicago drive specification for heavy-duty modular systems. OSHA Subpart L mandates rigorous load testing and guardrail placement that elevate compliance costs for rental fleet operators. The Southeast construction corridor from Florida to Georgia concentrates demand for rapid-assembly aluminum platforms in residential retrofit segments.
Germany
Bridge rehabilitation and industrial maintenance schedules in the Ruhr region and Bavaria sustain premium pricing for corrosion-resistant access configurations. EN 12811 framework updates enforce stricter plank grading and node connection standards that retire legacy inventory. Electric arc furnace steel sourcing requirements in public tenders reshape mill certificate screening protocols for domestic fabricators.
China
Coastal chemical processing zones and infrastructure renewal in the Yangtze River Delta generate demand for fiber-reinforced polymer alternatives to galvanized steel. GB standards and evolving carbon neutrality targets from MEE pressure manufacturers to document embodied emissions in export shipments. Shandong Peninsula clusters dominate steel tube galvanizing capacity serving both domestic projects and overseas procurement.
France
Historic preservation mandates in Paris and Lyon restrict site access, favoring lightweight aluminum rapid-assembly systems over conventional tube-and-coupler erection. The country's national construction regulator enforces load documentation requirements that complicate cross-border equipment mobility from Spanish rental networks. Residential retrofit markets in Provence remain underpenetrated by specialized access configurations.
United Kingdom
London's high-rise residential pipeline unbundles erection services from equipment hire, creating separate contractual vehicles for labor and asset provision. The Health and Safety Executive enforces inspection protocols that accelerate drone-integrated asset management adoption among rental operators. Midlands manufacturing clusters supply interoperable node connections to regional fleet consolidators in France and Spain.
Scaffold Materials Market Competitive Landscape
Top-tier vendors anchor the premium modular systems tier, while mid-scale fabricators compete on regional rental density and erection service bundling. The vendor base stratifies across three tiers: integrated multinational rental networks, specialized engineering-led manufacturers, and regional component suppliers. Three strategic archetypes dominate: full-service rental operators with captive erection labor, precision-engineered system designers for complex geometries, and volume-focused tube-and-coupler producers. M&A consolidation and fleet interoperability investments represent the dominant competitive vectors reshaping market structure.
Among German-based engineering specialists, PERI Group and Layher Holding GmbH exemplify the precision-manufactured componentry archetype for irregular facade configurations. BrandSafway represents the integrated North American rental network model combining equipment hire with erection service delivery. These three entities occupy positions across the premium tier where certification depth and multi-jurisdictional compliance capacity determine contract eligibility for heavy-duty commercial projects.
| Leading Market Players |
|---|
| Altrad Group |
| Safway Group |
| Layher Holding GmbH |
| Waco Kwikform |
| MJ-Gerüst GmbH |
| PERI Group |
| ULMA Construction |
| ADTO Group |
| BrandSafway |
| Others |
Value Network & Pricing Analysis
Hot-rolled steel index volatility cascades through scaffold manufacturing tiers, compressing margin predictability for tube-and-coupler producers while amplifying price premiums for certified modular systems with verified low-carbon sourcing.
Pricing Analysis
Margin tightening in heavy-duty steel segments reflects zinc galvanizing cost spikes and electric arc furnace steel premiums demanded by German public tenders. Three-tier pricing structure across premium certified modular, standard compliant, and economy tube-and-coupler levels separates rental fleet operators by liability underwriting capacity. Price differentiation hinges on EN 12811 certification depth and multi-jurisdictional testing documentation. Cost-down pressure on aluminum rapid-assembly systems accelerates as French historic preservation mandates expand addressable demand. Residential renovation contractors exhibit highest price sensitivity, while German industrial maintenance buyers prioritize corrosion resistance over unit economics.
Supply Chain Analysis
Domestic-content mandates in US infrastructure procurement and German public tenders are reshaping mill certificate screening protocols, forcing fabricators to document electric arc furnace content and low-carbon aluminum provenance. Primary supply clusters center on Shandong Peninsula steel tube galvanizing, Yangtze River Delta aluminum extrusion, and Ruhr region precision componentry. Raw material flows draw from Australian iron ore, Chilean copper for electrical grounding systems, and petroleum-based polymer feedstocks for fiber-reinforced composites. Single-source vulnerability concentrates in Chinese zinc refining capacity serving galvanizing operations. Distribution runs through integrated rental networks in the United States and Germany, with regional consolidators in France and Spain gaining share through interoperable fleet standards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scaffold materials markets are consolidating around certification depth and carbon-accounting compliance, with multi-certification testing capacity requirements forcing mid-tier fabricators toward acquisition or exit.
For Market Incumbents: Anticipate margin compression from Chinese export tariff exposure and steel price volatility by deepening backward integration into electric arc furnace steel sourcing and captive galvanizing capacity. Reinforce competitive moats through ISO 12811, OSHA Subpart L, and EN 12811 multi-certification laboratory investments that disqualify smaller rivals from heavy-duty commercial tenders. Prioritize drone-integrated asset management service bundling to capture recurring revenue streams from rental fleet digitization. For New Entrants and Emerging Players: Enter via aluminum rapid-assembly specialization targeting underpenetrated French and Italian residential retrofit segments where site access restrictions disadvantage incumbent steel erection workflows. Target historic preservation mandates in Lyon and Provence with lightweight 6061-T6 systems optimized for restricted urban logistics. Pursue go-to-market partnerships with regional rental consolidators in Spain seeking interoperable node connections to expand fleet utilization rates. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale German fabricators with EN 12811 certification infrastructure and stranded mill certificate screening capabilities as carbon-accounting procurement rules tighten. Long-term viability over the next decade rests on electric arc furnace steel sourcing relationships and multi-jurisdictional compliance capacity rather than pure manufacturing scale. Watch for inflection signals in US federal infrastructure allocation velocity and MEE carbon neutrality enforcement intensity in Chinese export shipments.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Certification Laboratory Investment | OSHA Subpart L, EN 12811, and ISO 12811 testing capacity determines eligibility for heavy-duty commercial tenders in the United States and Germany. |
| Electric Arc Furnace Steel Sourcing | German public tender carbon thresholds and US domestic-content mandates favor fabricators with verified low-carbon mill certificates. |
| Drone-Integrated Asset Management | UK Health and Safety Executive inspection protocols accelerate subscription-based fleet digitization services among rental operators. |
| Aluminum Rapid-Assembly Expansion | French historic preservation mandates in Paris and Lyon create addressable demand for lightweight systems optimized for restricted site access. |
| Regional Fleet Consolidation | Interoperable node connections in France and Spain decentralize procurement authority to site managers, reducing cross-project reconciliation time. |
Research Methodology
Document review covered customs and trade databases, SEC filings from listed construction equipment manufacturers, and EN 12811 framework update records, complemented by interviews with scaffold rental fleet managers, German bridge rehabilitation procurement officers, French historic preservation contractors, and aluminum extrusion procurement leads. Secondary validation drew from OSHA incident reporting databases, EU Green Deal construction material disclosure requirements, and MEE carbon neutrality policy circulars. Bottom-up equipment deployment estimates triangulated against top-down infrastructure spending allocations across the analysis window.
Cross-referencing historical rental fleet utilization patterns with panel input from procurement directors anchored volume and value projections across the modeling period. Segmentation dimensions modeled include material type, load capacity tier, application segment, and distribution channel structure, with additional granularity on certification grade and carbon-accounting compliance status. CAGRs were derived from regression analysis of capital expenditure trajectories and infrastructure renewal program announcements. Industry-specific inputs incorporated GB standards evolution in China and FERC state infrastructure allocation tracking in the United States.
Forecast precision tightens around the base case; tail outcomes carry wider variance under steel price volatility spikes, export tariff adjustments, or accelerated MEE carbon disclosure enforcement. Forecasts reflect documented assumptions regarding infrastructure renewal program continuity and skilled erection labor training pipeline expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Biomimetic Peptides Market
Biomaterials
Self-Healing Hydrogels Market
Biomaterials
Chitosan Oligosaccharides and Glucosamine Market
Biomaterials
US Heparin Market
Biomaterials
Global Biocompatible Materials Market
Biomaterials
Global Hydroxyapatite Market
Biomaterials
Biomimetic Materials Market
Biomaterials
Atelocollagen Market
Biomaterials
Bone Substitutes Market
Biomaterials
Self-Healing Materials Market
Biomaterials
Global Medical Engineered Materials Market
Biomaterials
Brazil Bone Graft and Substitutes Market
Biomaterials
Biomaterial Wound Dressing Market
Biomaterials
Middle East and Africa Orthopedic Biomaterial Market
Biomaterials
Global Biomaterials Market
Biomaterials
Global Implantable Biomaterial Market