
 Flowable Hemostats Market | 2026-2036
Flowable Hemostats Market Size, Share, and Industry Trends Forecast 2026-2036
Flowable Hemostats Market Analysis
Cardiovascular procedures is shifting toward greater reliance on flowable hemostats as catheter-based interventions and open-heart operations demand precise, non-mechanical bleeding control. Baxter International leverages its hospital distribution network to sustain presence across integrated delivery networks. B. Braun Melsungen anchors its competitive stance through specialized surgical portfolios that emphasize absorbable hemostatic technologies. Johnson & Johnson dominates the premium segment with broad R&D intensity across multiple delivery formats.
Flowable hemostats comprise bioresorbable materials—gelatin matrices, oxidized cellulose, or polysaccharide complexes—formulated for viscous or injectable application to irregular wound surfaces where mechanical compression proves impractical. These agents activate platelet aggregation and accelerate clot formation within seconds of contact with blood or tissue, serving primarily to reduce operative time and transfusion requirements in surgical settings. Fibrin sealants command the highest margin pools due to their dual-component mechanism and associated premium pricing, while polysaccharide hemostats represent the fastest-growing chemistry class as manufacturers seek alternatives to animal-derived raw materials. Hospitals remain the dominant end-user channel, though ambulatory surgery centers are gaining procurement influence as outpatient cardiovascular and orthopedic volumes expand.
The FDA regulates flowable hemostats as Class II or III medical devices depending on indication and absorbability profile, requiring substantial equivalence demonstrations or premarket approval that shapes product development timelines and market entry costs. The EU Medical Device Regulation imposes stricter clinical evidence requirements and post-market surveillance obligations through notified bodies, directly affecting how manufacturers structure their European commercialization strategies. Stakeholders must monitor evolving reimbursement thresholds for hemostatic adjuncts in bundled payment models, as these will determine whether premium flowable formats displace conventional mechanical methods in cost-constrained surgical environments.
Market Dynamics
Surging cardiovascular surgical volumes are compressing operative timelines, forcing hospitals to prioritize hemostatic agents that reduce transfusion dependency and accelerate case turnover without mechanical compression.
Growth Catalysts
- Catheter-based cardiovascular interventions:Percutaneous coronary and structural heart procedures demand precise bleeding control at vascular access sites, elevating flowable formats over traditional gauze packing.
- EU Medical Device Regulation (MDR):Stricter post-market surveillance obligations for absorbable hemostats are accelerating documentation investments by manufacturers, filtering out marginal competitors and consolidating quality-certified supply.
- Gelatin-thrombin matrix formulations:These hybrid chemistries activate clotting cascades faster than passive absorbents, driving preference in trauma and orthopedic settings where speed determines outcomes.
Market Restraints
- Bovine-derived raw material dependency:Gelatin sourcing concentrates in specific agricultural regions, exposing manufacturers to zoonotic disease transmission risks and supply interruptions.
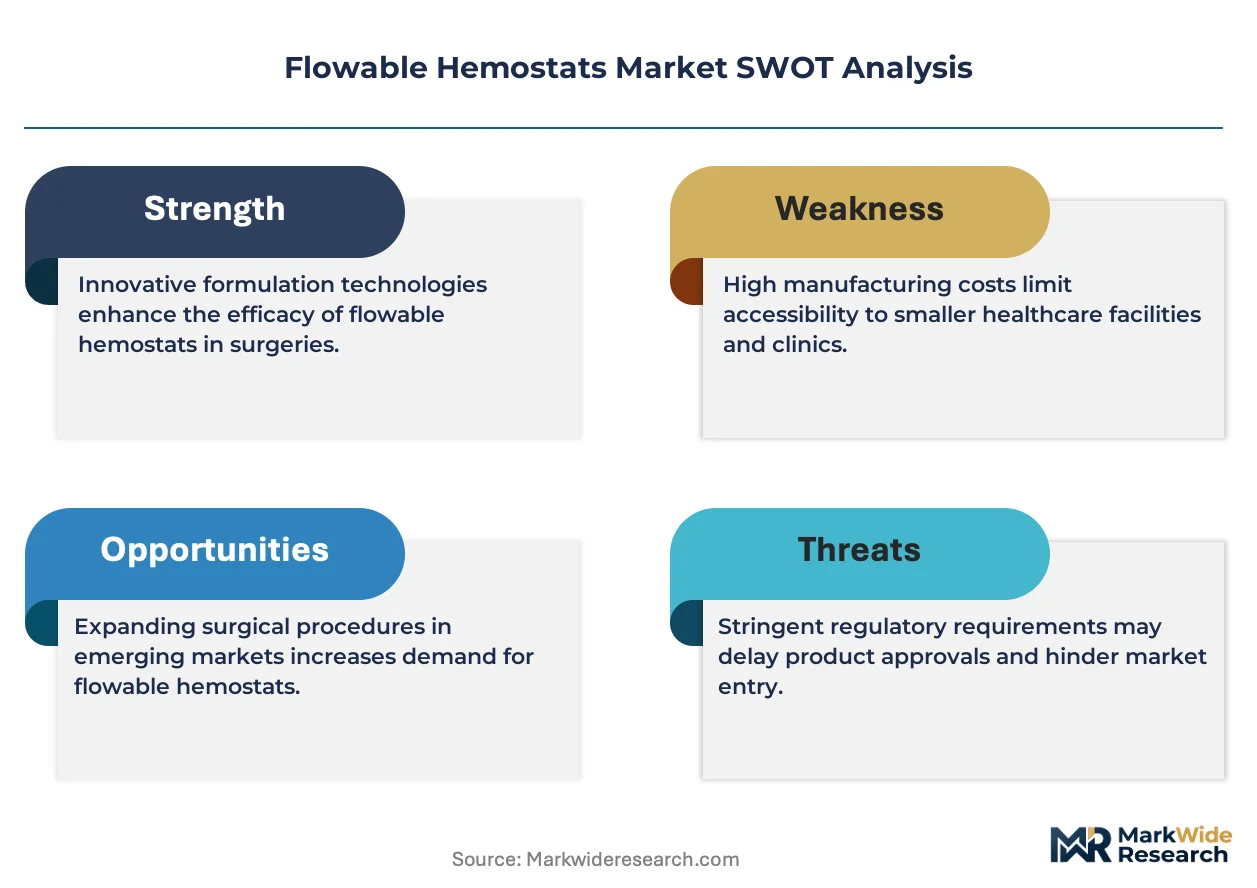
- Premium pricing compression:Fibrin sealant kits cost multiples of oxidized cellulose alternatives, limiting penetration in cash-constrained public hospital systems and emerging markets.
- FDA Class III pathway friction:Premarket approval requirements for novel absorbable hemostats extend development timelines by 18-36 months versus Class II substantial equivalence routes.
Strategic Opportunities
- Ambulatory surgery center expansion:Outpatient cardiovascular and orthopedic volumes in the United States are outpacing inpatient growth, creating demand for compact, single-use flowable formats optimized for lower-acuity settings.
- Polysaccharide chemistry innovation:Plant-derived alternatives to animal-sourced matrices address religious dietary restrictions and prion transmission concerns, opening procurement channels in Middle Eastern and Southeast Asian markets.
- Bundled payment alignment:Medicare's episode-based reimbursement models reward reduced transfusion rates and shorter lengths of stay, incentivizing adoption of premium hemostatic adjuncts that demonstrate total-cost reduction.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization studies face capacity constraints at contract research organizations, delaying regulatory submissions for reformulated products.
- Sterile manufacturing scale-up:Aseptic filling of viscous flowable hemostats requires specialized isolator technology and validated cleanroom infrastructure that commands capital commitments exceeding mid-tier manufacturer thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flowable Hemostats Market |
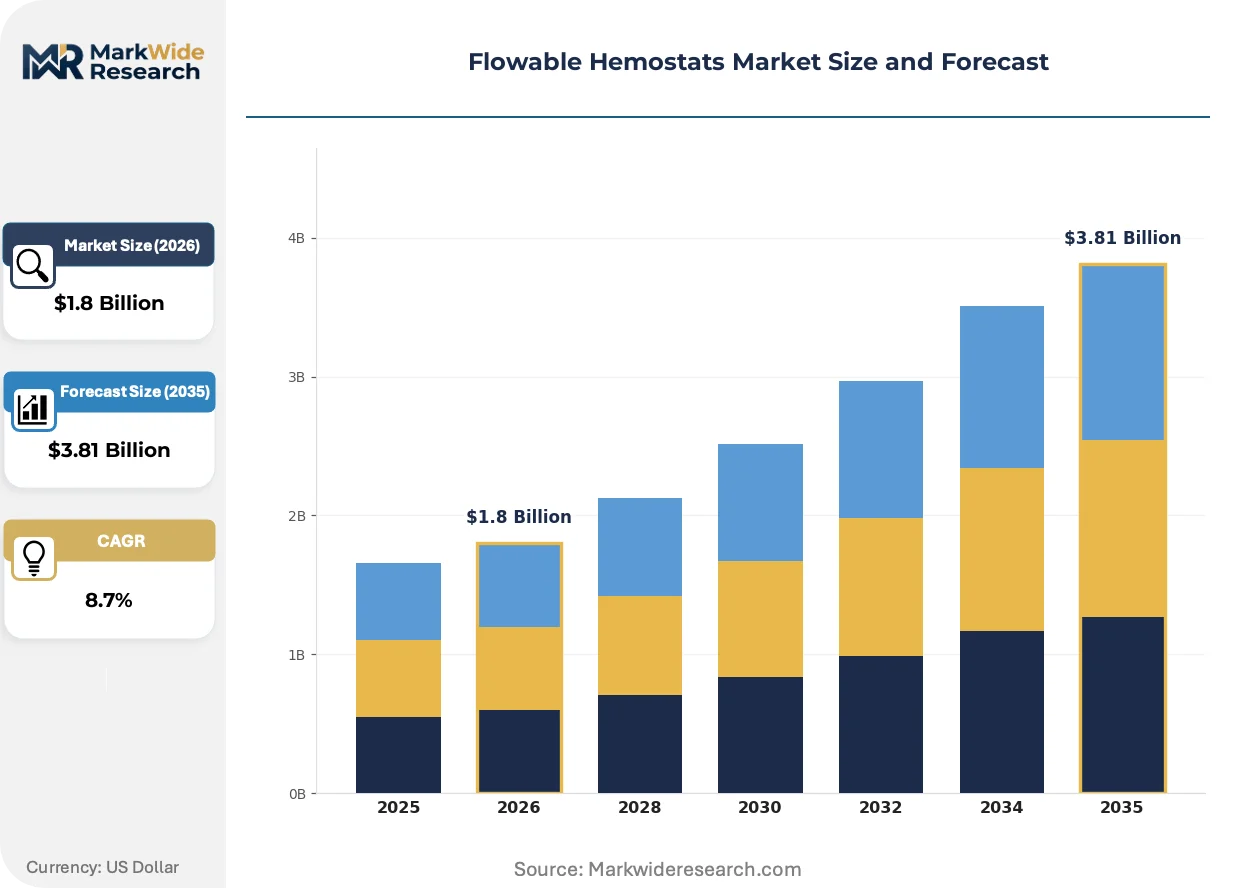
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin-based, Fibrin Sealants, Collagen Products, Polysaccharide Hemostats Application: Orthopedic Surgery, Neuro Surgery, Cardiovascular Procedures, General Surgery End User: Hospitals, Ambulatory Surgery Centers, Trauma Centers, Clinics Delivery Mode: Topical Application, Injectable Solutions, Spray Devices, Adhesive Gels |
| Companies Covered | Johnson & Johnson, Baxter International, Teleflex Incorporated, Ethicon, B. Braun Melsungen, Integra LifeSciences, Pfizer, Gelita Medical, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flowable Hemostats Market Emerging Trajectories
Formulation science and regulatory science are converging to redefine competitive advantage, with chemistry platforms and clinical evidence packages becoming inseparable from market access.
Recombinant thrombin produced through microbial fermentation is electrifying the active hemostat segment by eliminating human and bovine bloodborne pathogen risks. Academic medical centers with high transfusion-free surgery targets are adopting these formats fastest. The technology is electrifying margin structures by decoupling manufacturers from volatile plasma fractionation supply chains.
MDR Article 10 clinical evidence requirements are forcing manufacturers to generate prospective data on absorbable hemostat performance rather than relying on predicate device equivalence. European notified bodies now demand real-world post-market follow-up for Class III absorbables. Surgical societies in Germany and France are responding by developing standardized bleeding severity scales to satisfy these evidentiary burdens.
Hospital value analysis committees have displaced individual surgeon preference as the primary purchasing authority for hemostatic products. Integrated delivery networks in the United States now mandate standardized formularies across affiliated facilities, consolidating vendor relationships. This concentration is most visible in cardiovascular service lines where catheterization laboratory directors negotiate system-wide contracts with manufacturers.
Flowable Hemostats Market Segmentation
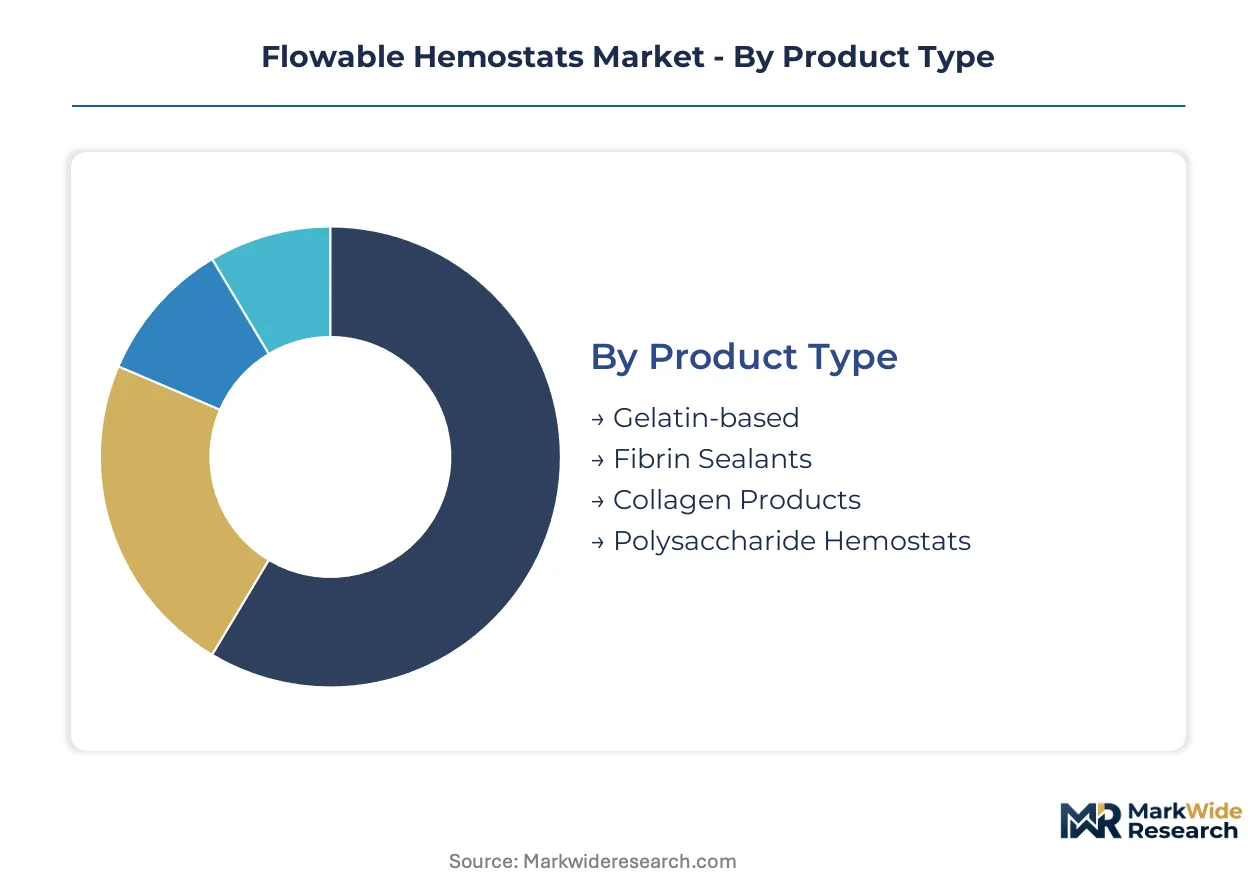
Flowable hemostats fragment across four distinct dimensions that reshape capital allocation and manufacturing footprint. Product chemistry determines raw material sourcing risk, while delivery mode dictates sterile filling infrastructure requirements. Application specialization and end-user channel each impose divergent regulatory and pricing pressures.
Product Type:
Gelatin-based matrices and fibrin sealants demand the heaviest upfront investment in plasma fractionation capacity and recombinant protein fermentation infrastructure. Polysaccharide alternatives require less capital-intensive plant-derived extraction but face steeper biocompatibility validation costs.
- Gelatin-based:Porcine or bovine-derived gelatin matrices combine with thrombin to form viscous flowables that conform to irregular wound surfaces. Demand concentrates in United States trauma centers where speed of hemostasis reduces transfusion dependency. Baxter International and B. Braun Melsungen dominate supply through captive gelatin processing networks.
- Fibrin Sealants:Dual-component systems combining human or recombinant fibrinogen with thrombin command premium pricing through superior clot strength. Cardiovascular procedures in German university hospitals drive procurement, where surgeons prioritize sealant performance over cost in open-heart operations. Recombinant thrombin variants are displacing human plasma-derived alternatives.
- Collagen Products:Bovine or equine collagen matrices provide passive absorption combined with platelet activation.
- Polysaccharide Hemostats:Plant-derived chitosan or starch complexes address religious dietary restrictions and prion transmission concerns.
Most installed capacity flows through gelatin-based formats. Expansion is steepest in polysaccharide alternatives.
Application:
Orthopedic and cardiovascular procedures generate the highest per-case consumption volumes, while neurosurgery imposes the most stringent purity specifications. General surgery spreads demand across lower-acuity settings with compressed pricing tolerance.
- Orthopedic Surgery:Total joint arthroplasty and spine fusion drive substantial flowable hemostat consumption where bone bleeding resists mechanical control. United States ambulatory surgery centers are expanding orthopedic volumes fastest, creating demand for single-use syringe formats.
- Cardiovascular Procedures:Catheter-based interventions and open-heart operations require precise bleeding control at vascular access sites and suture lines. German and French cardiac centers prioritize fibrin sealants in coronary artery bypass grafting.
- Neuro Surgery:Intracranial procedures demand hemostats with minimal swelling potential and rapid absorption.
- General Surgery:Hepatic resection and splenic trauma applications span diverse hospital settings with cost-sensitive procurement.
Cardiovascular applications absorb the highest absolute volume. Orthopedic settings are climbing the fastest as outpatient migration accelerates.
End User:
Hospital consolidation and ambulatory expansion are bifurcating procurement authority. Trauma centers and clinics occupy opposite ends of the acuity spectrum with diverging format preferences.
- Hospitals:Integrated delivery networks in the United States negotiate system-wide formularies that standardize hemostat selection across cardiac, orthopedic, and trauma service lines. Value analysis committees have displaced individual surgeon preference as primary purchasing authority.
- Ambulatory Surgery Centers:Outpatient cardiovascular and orthopedic volumes are outpacing inpatient growth, creating demand for compact single-use formats optimized for lower-acuity settings. Medicare's site-neutral payment policies accelerate this shift.
- Trauma Centers:Level I facilities in United States urban centers prioritize rapid-acting gelatin-thrombin matrices for emergency bleeding control.
- Clinics:Dermatologic and minor surgical applications consume lower volumes with greater price sensitivity.
Hospitals retain the largest installed base. Ambulatory surgery centers are gaining share fastest as procedure migration continues.
Delivery Mode:
Spray devices and adhesive gels require specialized sterile filling infrastructure, while topical and injectable formats accommodate broader contract manufacturing access.
- Topical Application:Direct pouring or manual packing of viscous flowables suits open surgical fields with adequate visualization. General surgery applications in Indian public hospitals favor this lowest-cost delivery approach.
- Injectable Solutions:Syringe-based application enables precise delivery to deep or confined surgical sites. Laparoscopic and robotic procedures in Japanese academic medical centers drive preference for injectable formats.
- Spray Devices:Dual-barrel applicators with gas-powered atomization cover large surface areas in hepatic resection and trauma.
- Adhesive Gels:Cross-linked formulations provide mechanical adhesion combined with hemostatic activity.
Topical formats flow through the most installed capacity. Injectable solutions are expanding most quickly as minimally invasive techniques proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as producers seek jurisdictions with streamlined device approval pathways and favorable reimbursement environments. Cost-of-compliance gaps between the FDA's Class III premarket approval and the EU MDR's clinical evidence requirements are driving strategic facility placement decisions among multinational suppliers.
United States
Hospital consolidation across integrated delivery networks concentrates procurement authority in value analysis committees that negotiate system-wide hemostat formularies. The FDA's evolving guidance on absorbable hemostatic agents shapes product development timelines, with Class II substantial equivalence routes offering faster market entry than Class III pathways. The Minneapolis-St. Paul corridor anchors significant gelatin processing infrastructure serving trauma centers nationwide.
Germany
University hospitals in Bavaria and Baden-Württemberg drive premium fibrin sealant consumption for coronary artery bypass grafting procedures where surgeons prioritize performance metrics. The EU Medical Device Regulation imposes stringent post-market surveillance obligations through notified bodies, filtering marginal competitors from German supply chains. The Frankfurt-Rhine-Main cluster hosts specialized surgical portfolio manufacturers targeting cardiac service lines.
Japan
Academic medical centers in Tokyo and Osaka accelerate adoption of injectable flowable formats for laparoscopic and robotic surgical applications. The Pharmaceuticals and Medical Devices Agency maintains rigorous biocompatibility standards that extend validation timelines but secure premium positioning for approved products. The Kanto region concentrates sterile manufacturing infrastructure serving domestic and Asia-Pacific export markets.
India
Public hospital systems in Maharashtra and Karnataka face pricing compression that limits penetration of premium fibrin sealant kits, favoring oxidized cellulose alternatives. The Central Drugs Standard Control Organization regulates hemostatic devices under medical device rules that are gradually aligning with international standards. The Hyderabad-Chennai corridor attracts contract manufacturing investment for gelatin-based matrices targeting cost-sensitive emerging markets.
United Arab Emirates
Private healthcare networks in Dubai and Abu Dhabi procure advanced flowable hemostats for medical tourism segments serving Gulf Cooperation Council patients. The Ministry of Health and Prevention's medical device registration framework emphasizes quality certification alignment with European notified body standards. The Dubai Healthcare City free zone concentrates distribution infrastructure for Middle Eastern and North African markets.
Flowable Hemostats Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium fibrin sealant categories consolidating around integrated plasma fractionation players while commoditized absorbable formats fragment among regional suppliers. The market structure favors entities with captive gelatin processing networks or recombinant protein fermentation capabilities that insulate margins from raw material volatility. Three archetypes dominate: multinational surgical portfolio conglomerates with hospital distribution scale, mid-tier regional specialists leveraging geographic proximity, and emerging plant-derived chemistry innovators targeting religious dietary restriction markets. Competitive moves concentrate on sterile manufacturing capacity expansion and strategic partnerships with integrated delivery networks for formulary placement.
Within the multinational surgical portfolio tier, Johnson & Johnson and Baxter International occupy positions exemplifying divergent strategic emphases—one anchoring premium R&D intensity across multiple delivery formats, the other sustaining presence through hospital distribution network density. B. Braun Melsungen represents the specialized European archetype with emphasis on absorbable hemostatic technologies. These entities illustrate how competitive positioning increasingly depends on chemistry platform control and regulatory science capabilities rather than product differentiation alone.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Baxter International |
| Teleflex Incorporated |
| Ethicon |
| B. Braun Melsungen |
| Integra LifeSciences |
| Pfizer |
| Gelita Medical |
| Medtronic |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up surgical supply specialists now dominate gelatin-based matrix distribution, concentrating procurement leverage in integrated delivery networks while compressing distributor margins across mid-tier manufacturers. This ownership pattern tightens pricing discipline as portfolio companies cross-sell hemostatic portfolios through captive hospital contracts, forcing standalone suppliers to absorb cost volatility or exit.
Pricing Analysis
Distributor margin compression runs through the United States hospital channel as integrated delivery networks consolidate formulary negotiations. Three-tier pricing structure across premium fibrin sealants, standard gelatin-thrombin matrices, and economy oxidized cellulose alternatives stratifies by clot strength performance and recombinant protein content. Price differentiation hinges on FDA Class III certification tier and captive plasma fractionation capacity. Pricing pressure stems from Medicare's site-neutral payment policies accelerating ambulatory migration. Public hospital systems in emerging markets exhibit highest price sensitivity, while German cardiac centers show lowest sensitivity due to outcome-based procurement criteria.
Supply Chain Analysis
Dual-sourcing requirements from United States integrated delivery networks now mandate qualified backup suppliers for all absorbable hemostat categories, fragmenting volume concentration across multiple gelatin processors. Raw material supply concentrates in the United States Midwest for porcine-derived gelatin, Germany for bovine collagen processing, and Thailand for plant-derived polysaccharide extraction. Manufacturing draws from recombinant thrombin fermentation capacity in Ireland and sterile filling infrastructure in the Kanto region of Japan. Single-source vulnerability concentrates in plasma fractionation networks for fibrinogen supply. Distribution runs through specialized surgical device distributors with temperature-controlled logistics rather than broad-line medical supply wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as hospital value analysis committees displace surgeon preference and demand clinical evidence packages that only premium manufacturers can fund. The demand-shift toward recombinant thrombin formulations eliminates bloodborne pathogen risk and commands sustained pricing power.
For Market Incumbents: Deploy sterile manufacturing capacity expansion in low-cost jurisdictions with FDA and EU MDR dual-certification capability to defend margin position against emerging plant-derived chemistry innovators. Backward integration into recombinant protein fermentation insulates supply from volatile plasma fractionation markets. Deepen hospital system partnership structures through risk-sharing contracts that align transfusion reduction outcomes with formulary placement security.
For New Entrants and Emerging Players: Capture ambulatory surgery center procurement channels in the United States where site-neutral payment policies accelerate outpatient cardiovascular and orthopedic volumes faster than incumbent sales infrastructure can adapt. Polysaccharide chemistry platforms address religious dietary restrictions in Middle Eastern and Southeast Asian markets where animal-derived matrices face procurement barriers. Lead with single-use syringe formats optimized for lower-acuity settings rather than competing for premium hospital contracts.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier regional specialists with captive gelatin processing networks but underdeveloped recombinant protein capabilities. Long-term viability over the coming decade hinges on chemistry platform transition from animal-derived to microbial fermentation inputs. Watch FDA guidance evolution on absorbable hemostatic agent classification as the inflection signal—downward reclassification to Class II pathways would unlock acquisition premiums for late-stage development assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Thrombin Fermentation Scale-Up | Eliminates bovine-derived pathogen risks and decouples supply from volatile plasma fractionation networks. |
| EU MDR Clinical Evidence Package Investment | Satisfies notified body demands for prospective absorbable hemostat performance data under Article 10 requirements. |
| Ambulatory Surgery Center Format Development | Captures outpatient cardiovascular and orthopedic volumes migrating under Medicare site-neutral payment policies. |
| Plant-Derived Polysaccharide Chemistry Pivot | Opens procurement channels in Middle Eastern and Southeast Asian markets with religious dietary restrictions. |
| Integrated Delivery Network Risk-Sharing Contracts | Aligns transfusion reduction outcomes with formulary placement security across hospital consolidation structures. |
Methodological Framework
Bottom-up hospital procurement modeling reconciled against top-down sterile manufacturing capacity tracking forms the analytical core of this study. Primary interviews with cardiovascular surgeons, orthopedic service line directors, hospital value analysis committee members, GPO contracts managers, and biomedical engineers informed demand-side assumptions. Secondary validation drew from FDA 510(k) and PMA filings, EU MDR notified body certificates, CMS Medicare reimbursement databases, and hospital procurement contract disclosures. Top-down supply-side assessment triangulated against bottom-up end-user consumption patterns.
Input-output matrices across chemistry platform, delivery mode, application specialty, and end-user channel dimensions structured volume and value projections over the forecast horizon. Segmentation modeling captured product type differentiation between gelatin-based matrices, fibrin sealants, collagen products, and polysaccharide alternatives; application splits across cardiovascular, orthopedic, neurosurgery, and general surgery; and end-user bifurcation between hospitals and ambulatory surgery centers. CAGRs derived from surgical procedure volume forecasts, hemostat penetration rates by procedure type, and pricing trajectories by chemistry class. Recombinant protein fermentation capacity buildouts and EU MDR transition timelines served as industry-specific forecast inputs.
Regulatory reclassification, raw material supply disruption, and reimbursement policy shifts are the dominant revision risks to the outlook. Deviation in FDA absorbable hemostatic agent guidance would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Biomimetic Materials Market
Biomaterials
Hemostatic Gels Market
Biomaterials
Bioceramics and Hydroxyapatite Market
Biomaterials
Global Biocompatible Materials Market
Biomaterials
Brazil Bone Graft and Substitutes Market
Biomaterials
Global Bone Grafts and Substitutes Market
Biomaterials
Hydrogel Market
Biomaterials
Bone and Joints Ingredients Market
Biomaterials
Spine Surgery Gels Market
Biomaterials
Biodegradable Bone Graft Polymers Market
Biomaterials
Biomaterial Wound Dressing Market
Biomaterials
Global Polymeric Biomaterials Market
Biomaterials
Chitosan Supplements Market
Biomaterials
Global Implantable Biomaterial Market
Biomaterials
Global Extracellular Matrix Patches Market
Biomaterials
Biomimetic Peptides Market